
 Middle East and Africa Orthotic Devices Market | 2026-2036
Middle East and Africa Orthotic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Orthotic Devices Market Outlook
Carbon fiber is rebalancing cost-performance trade-offs across the Middle East and Africa Orthotic Devices Market as it displaces heavier metal alloys in ankle-foot orthoses and spinal braces. Ottobock leverages its German engineering heritage to dominate premium carbon-composite fabrication for neurological patients across Gulf Cooperation Council states. Stryker anchors its regional position through hospital-direct distribution networks that bypass fragmented retail channels in Egypt and Nigeria. DJO Global differentiates via thermoplastic knee bracing systems calibrated for high-temperature climates where material creep degrades conventional polymers.
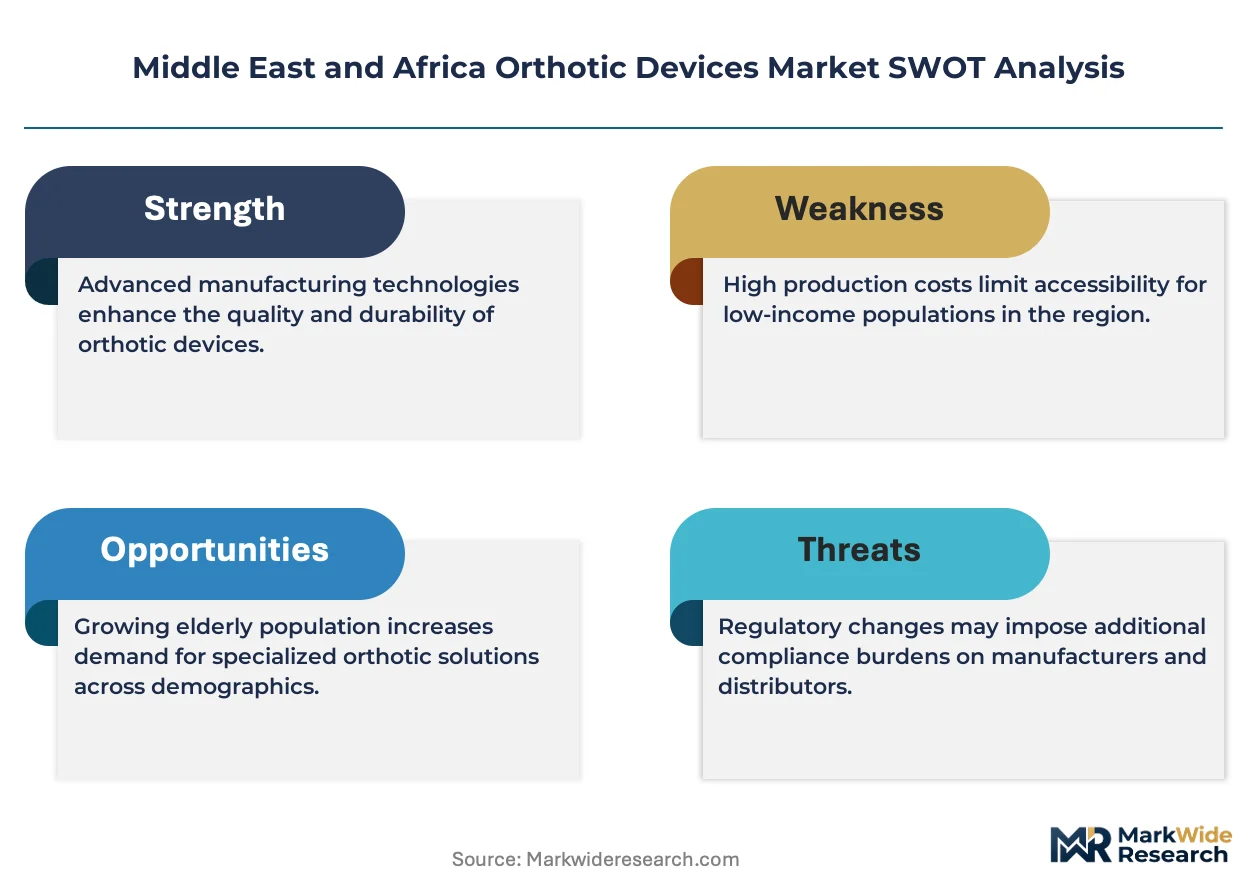
Orthotic devices are externally applied mechanical apparatuses manufactured from thermoplastics, composite laminates, or metal alloys, designed to modify musculoskeletal function through controlled force distribution, joint alignment, or motion restriction. Fabrication employs vacuum-forming over positive molds, CAD-CAM milling, or direct 3D printing from patient scan data to achieve sub-millimeter anatomical conformance for load-path optimization. Braces and supports command the largest revenue share due to chronic disease burden from diabetes-related Charcot foot and post-traumatic osteoarthritis across aging Gulf populations. Rehabilitation applications represent the fastest-expanding segment as Saudi Arabia and the UAE construct dedicated prosthetic and orthotic centers of excellence within their national hospital networks. Home care delivery is maturing slowly given reimbursement gaps and technician shortages that constrain remote fitting protocols outside major South African and Egyptian urban corridors.
Saudi Arabia's SFDA and South Africa's SAHPRA enforce biocompatibility and mechanical testing standards that determine which imported devices gain market access, while the UAE's MOHAP operates a parallel registration pathway with accelerated review for products holding European CE marking or US FDA 510(k) clearance. The Dubai Health Authority's mandatory insurance framework now includes orthotic benefits, directly expanding addressable patient pools beyond previous out-of-pocket constraints. Stakeholders must monitor how Egypt's drug authority expands its nascent medical device regulatory capacity, as Cairo's position as a North African distribution hub hinges on predictable conformity assessment timelines.
Market Dynamics
Carbon fiber composites are compressing the cost-performance frontier for load-bearing orthoses across Gulf rehabilitation networks, forcing recalibration of procurement criteria that previously favored metal alloys for durability.
Growth Catalysts
- Vision 2030 Healthcare Infrastructure:Saudi Arabia's government-backed hospital expansion is constructing dedicated prosthetic and orthotic centers of excellence with mandated device procurement quotas.
- SFDA Biocompatibility Standards:Streamlined registration pathways for CE-marked and FDA-cleared devices are accelerating import velocity for European and American manufacturers.
- Diabetes-Related Charcot Foot Prevalence:Aging Gulf populations are generating sustained demand for ankle-foot orthoses and custom-fabricated braces in tertiary care settings.
Market Restraints
- Carbon Fiber Input Volatility:Aerospace sector competition for prepreg materials creates price instability for orthotic-grade composite laminates.
- Technician Shortage in Remote Fitting:South Africa and Egypt lack sufficient certified orthotists to support home care delivery protocols outside Johannesburg and Cairo corridors.
- Reimbursement Gaps:Egypt's nascent medical device regulatory framework delays predictable conformity assessment timelines, constraining distributor investment.
Strategic Opportunities
- UAE Mandatory Insurance Expansion:Dubai Health Authority's orthotic benefit inclusion is unlocking previously out-of-pocket patient segments for custom-fabricated devices.
- CAD-CAM and 3D Printing Convergence:Direct printing from patient scan data enables same-day fabrication workflows that compress fitting cycles in high-volume Saudi clinics.
- Pediatric Orthopedic Clinic Networks:South Africa's expanding brace procurement programs represent underpenetrated volume for thermoplastic ankle-foot systems.
Industry Challenges
- SAHPRA Certification Timelines:South Africa's pharmaceutical regulator enforces extended mechanical testing protocols that delay product launches for thermoplastic knee bracing systems.
- High-Temperature Material Creep:Conventional polymers degrade in Gulf climates, requiring reformulation investments that strain mid-tier manufacturer R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Orthotic Devices Market |
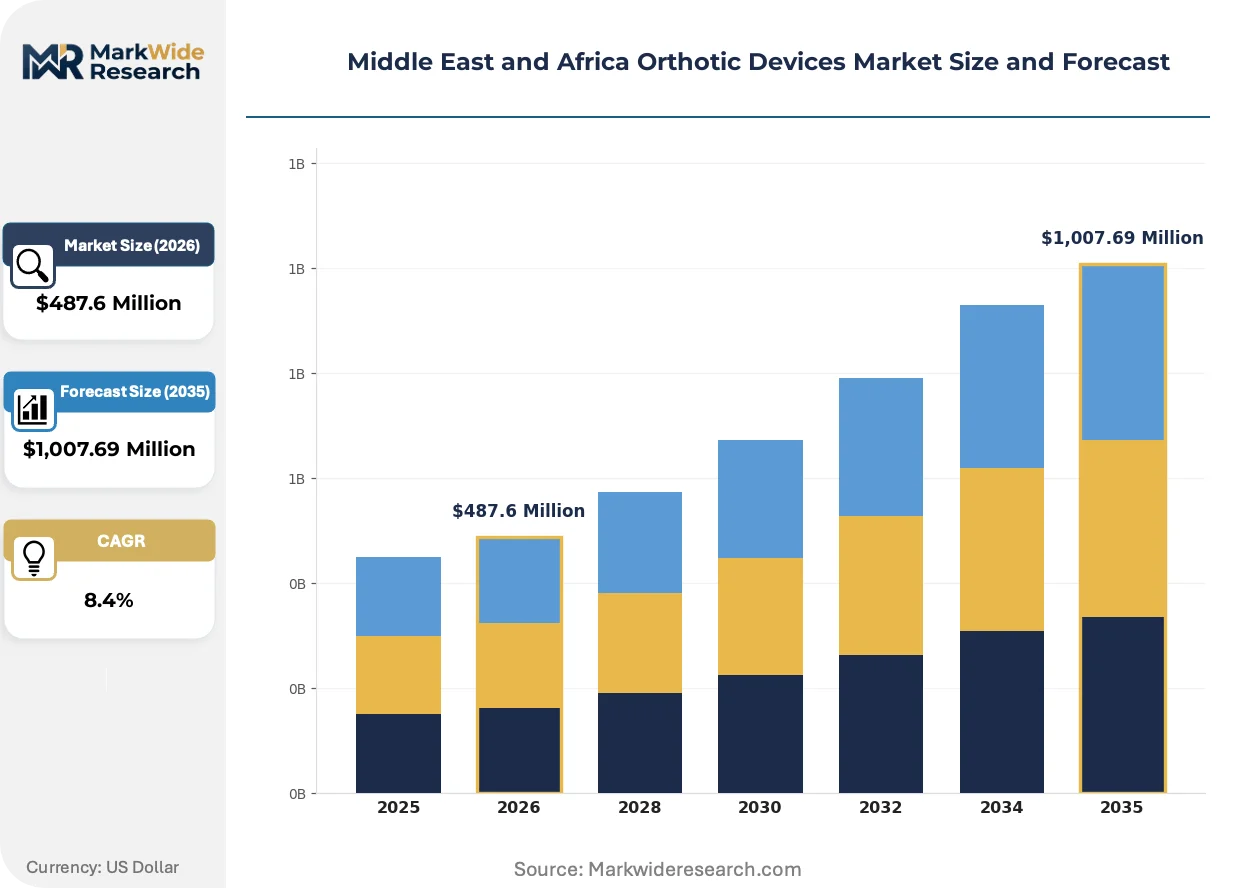
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,007.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Splints, Supports, Insoles Application: Rehabilitation, Sports Injury, Chronic Pain, Post-Surgery End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Material: Thermoplastics, Foam, Metal, Composite |
| Companies Covered | Stryker, Alvimedica, Ottobock, Itamar Medical, Saudi Pharmaceutical Industries & Medical Appliances Corporation, Össur, Smith & Nephew, DJO Global, Medtronic, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Orthotic Devices Market Strategic Shifts
Digital fabrication workflows are collapsing the traditional mold-to-delivery cycle, while regulatory harmonization and climate-adapted materials are redefining competitive differentiation across Middle Eastern and African markets.
Carbon fiber layup automation is unifying structural performance with weight reduction in spinal braces and lower-limb orthoses. Saudi rehabilitation hospitals are adopting these systems at accelerated procurement cycles. This technology is unifying previously separate premium and standard product tiers into single adjustable platforms.
MOHAP's parallel registration pathway for CE-marked devices is compressing market access timelines for European manufacturers. The industrial consequence is accelerated displacement of unregistered Asian suppliers in UAE distribution channels. Thermoplastic knee bracing systems holding European certification are capturing preference share in Dubai's mandatory insurance framework.
Hospital-direct distribution is displacing fragmented retail channels in Egypt and Nigeria. Stryker's anchor position in tertiary care networks demonstrates how manufacturer-controlled logistics compress margin leakage. This pattern is most visible in Saudi Arabia's government hospital procurement, where centralized tendering favors single-source contracts over distributor intermediation.
Middle East and Africa Orthotic Devices Market Segmentation
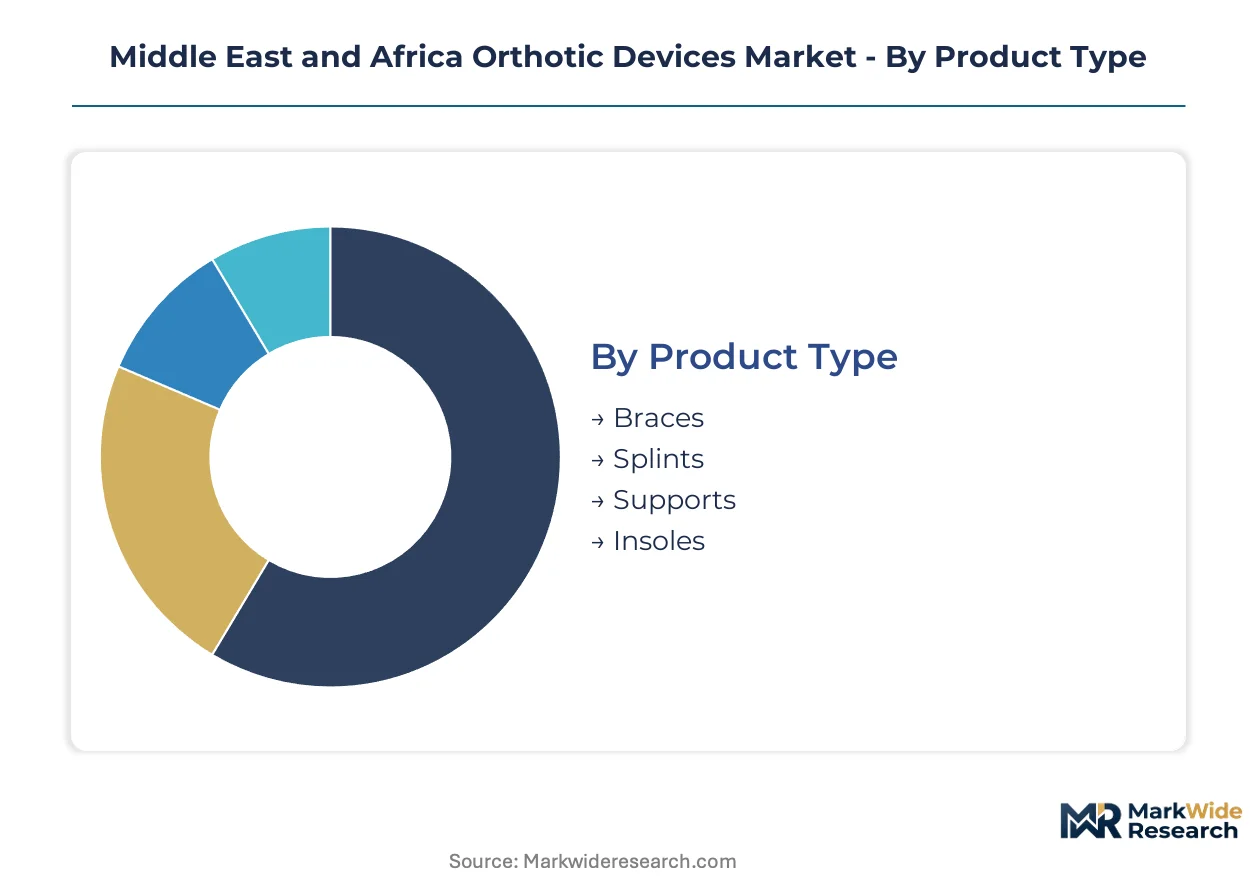
Orthotic device procurement across Middle East and Africa diverges sharply between institutional buyers demanding clinical-grade fabrication and retail channels serving price-sensitive consumers. Understanding where each segment sits on this integration spectrum reveals which manufacturers can capture margin versus volume.
Product Type:
Braces operate as standalone therapeutic systems requiring precise anatomical fitting, while splints and supports embed into broader treatment protocols with lighter customization demands.
- Braces:Rigid and semi-rigid structures fabricated from thermoplastics or composite laminates that redistribute biomechanical loads across joints. Saudi Arabia's Vision 2030 hospital construction is concentrating demand for ankle-foot and spinal braces in tertiary rehabilitation centers where government procurement quotas favor certified European suppliers.
- Supports:Elastic and semi-compressive garments providing proprioceptive feedback without joint immobilization. South Africa's expanding pediatric orthopedic clinic networks are driving volume for knee and wrist supports in Johannesburg and Cape Town corridors where technician availability enables proper fitting protocols.
- Splints:Immobilization devices for acute fracture management and post-surgical protection, typically fabricated from aluminum or fiberglass.
- Insoles:Custom-molded or prefabricated foot orthoses addressing plantar pressure distribution and gait abnormalities.
Braces lead volumes today; supports are gaining share fastest.
Application:
Rehabilitation applications command premium pricing through specialized fitting protocols, while sports injury and chronic pain segments compete on accessibility and repeat purchase frequency.
- Rehabilitation:Long-term therapeutic protocols for neurological conditions, spinal cord injury, and post-amputation care requiring iterative device adjustment. The UAE's MOHAP orthotic benefit inclusion is unlocking patient access to custom-fabricated rehabilitation devices previously constrained by out-of-pocket payment requirements.
- Chronic Pain:Degenerative joint disease and diabetic Charcot foot management through load-redistribution orthoses. Egypt's aging population and diabetes prevalence are concentrating demand for ankle-foot orthoses in Cairo's tertiary hospital network where distributor fragmentation complicates supply reliability.
- Sports Injury:Acute ligament protection and return-to-activity bracing for athletic populations.
- Post-Surgery:Immobilization and protected mobilization following orthopedic procedures.
Rehabilitation commands the highest revenue per patient; chronic pain delivers the steepest expansion trajectory.
End User:
Hospital procurement operates through centralized tendering with stringent technical specifications, whereas home care delivery depends on technician density and reimbursement infrastructure that remains patchy outside major urban corridors.
- Hospitals:Tertiary care institutions with in-house prosthetic and orthotic departments or contracted fabrication partnerships. Saudi Arabia's government-backed hospital expansion is mandating dedicated orthotic centers of excellence with device procurement quotas that favor single-source supplier contracts.
- Rehabilitation Centers:Specialized outpatient facilities focused on neurological and musculoskeletal recovery. Dubai's mandatory insurance framework is accelerating patient flows to private rehabilitation centers equipped for CAD-CAM fabrication workflows.
- Clinics:General orthopedic and podiatric practices providing initial assessment and basic device dispensing.
- Home Care:Remote fitting and delivery protocols for mobility-limited patients.
Hospitals anchor procurement volumes today; rehabilitation centers are expanding most quickly.
Material:
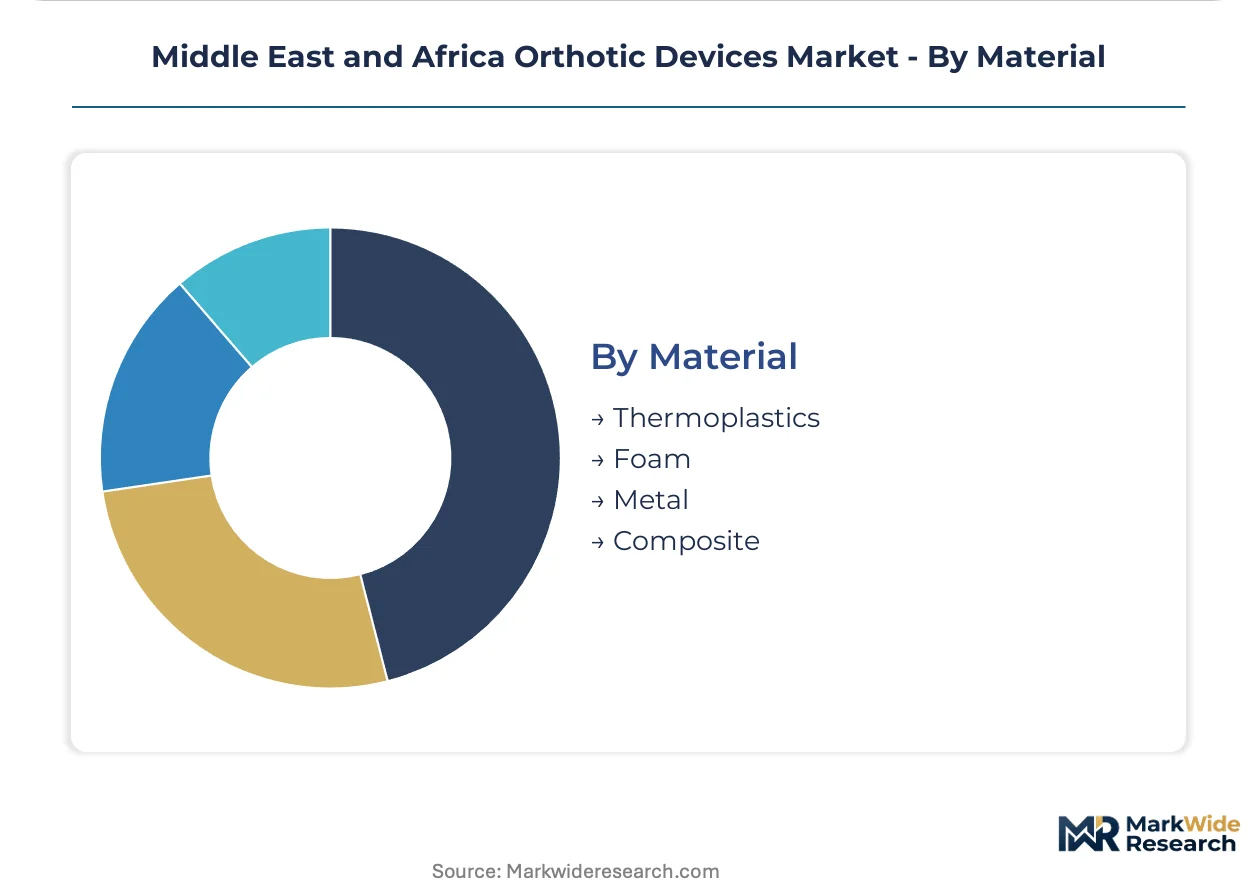
Thermoplastics and composites occupy the performance tier where climate adaptation and weight reduction justify premium positioning, while metal and foam serve cost-constrained applications with shorter replacement cycles.
- Composite:Carbon fiber and glass fiber laminates delivering strength-to-weight ratios critical for load-bearing lower-limb orthoses. Gulf Cooperation Council rehabilitation networks are adopting carbon fiber ankle-foot orthoses at accelerated procurement cycles despite aerospace sector competition for prepreg materials creating input price volatility.
- Thermoplastics:Vacuum-formable polymers enabling rapid custom fabrication over positive molds. DJO Global's climate-calibrated formulations are capturing preference share in high-temperature Gulf environments where conventional polymers exhibit material creep degradation.
- Metal:Aluminum and stainless steel alloys for structural components in heavy-duty orthoses.
- Foam:Cushioning and interface materials for pressure distribution and comfort enhancement.
Thermoplastics dominate unit volumes today; composite materials are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Vision 2030 hospital construction anchors regional demand for orthotic devices, with government procurement quotas concentrating fabrication capacity in Riyadh and Jeddah rehabilitation centers. The UAE's mandatory insurance expansion and South Africa's pediatric clinic networks complete the tripartite demand structure across the region.
Saudi Arabia
Diabetes-related Charcot foot prevalence and aging demographics drive demand for ankle-foot orthoses in tertiary care settings. The Saudi Food and Drug Authority enforces biocompatibility standards that accelerate CE-marked device registrations. Riyadh's government-backed rehabilitation hospitals are constructing dedicated prosthetic and orthotic centers of excellence with mandated procurement quotas.
United Arab Emirates
Dubai's mandatory health insurance framework now includes orthotic benefits, unlocking previously out-of-pocket patient segments for custom-fabricated devices. The Ministry of Health and Prevention operates parallel registration pathways with accelerated review for FDA-cleared products. Dubai's private rehabilitation centers equipped for CAD-CAM fabrication are capturing accelerated patient flows from the insurance expansion.
South Africa
Pediatric orthopedic clinic networks in Johannesburg and Cape Town are expanding brace procurement programs for thermoplastic ankle-foot systems. The South African Health Products Regulatory Authority enforces extended mechanical testing protocols that delay thermoplastic knee bracing launches. Technician shortages constrain home care delivery protocols outside major urban corridors.
Egypt
Aging populations and diabetes prevalence concentrate demand for load-redistribution orthoses in Cairo's tertiary hospital network. The country's nascent medical device regulatory framework delays predictable conformity assessment timelines. Distributor fragmentation complicates supply reliability across North African distribution channels anchored in Cairo.
Nigeria
Post-traumatic osteoarthritis and road injury rehabilitation generate demand for lower-limb orthoses in Lagos and Abuja hospital networks. The national pharmaceutical regulator is expanding medical device oversight capacity. Hospital-direct distribution networks are displacing fragmented retail channels in tertiary care procurement.
Middle East and Africa Orthotic Devices Market Competitive Environment
Hospital-direct distribution dominates the current landscape as manufacturers bypass fragmented retail channels to capture government procurement contracts. The market structures around three tiers: multinational medical device conglomerates with established regulatory registrations, European engineering specialists in carbon-composite fabrication, and regional distributors serving price-sensitive segments. Capacity expansion into climate-calibrated material formulations and strategic partnerships with Saudi hospital networks represent the dominant competitive vectors reshaping positioning.
Among European engineering specialists, Ottobock represents the premium carbon-composite fabrication archetype for neurological applications across Gulf Cooperation Council states. Stryker anchors the multinational conglomerate tier through hospital-direct distribution networks that bypass fragmented retail channels in Egypt and Nigeria. DJO Global occupies the climate-adapted specialization position with thermoplastic formulations calibrated for high-temperature Gulf environments where conventional polymers degrade.
| Leading Market Players |
|---|
| Stryker |
| Alvimedica |
| Ottobock |
| Itamar Medical |
| Saudi Pharmaceutical Industries & Medical Appliances Corporation |
| Össur |
| Smith & Nephew |
| DJO Global |
| Medtronic |
| Others |
Value Chain & Pricing Dynamics
Carbon fiber prepreg costs cascade through three distinct pricing tiers as aerospace sector competition for composite laminates compresses margins for mid-tier orthotic manufacturers serving Gulf rehabilitation networks.
Pricing Analysis
Input-cost pass-through from carbon fiber volatility feeds into a three-tier pricing structure across premium, standard, and economy levels. CE-marked and FDA-cleared devices command 15-25% premiums over unregistered Asian imports due to SFDA and SAHPRA certification requirements. Pricing pressure stems from aerospace sector competition for prepreg materials that elevates raw material costs for orthotic-grade composites. Government hospital procurement in Saudi Arabia exhibits lowest price sensitivity due to mandated Vision 2030 quotas, while Egyptian retail channels face acute margin compression from distributor fragmentation.
Supply Chain Analysis
Certification gating through SFDA, SAHPRA, and MOHAP registration pathways restricts supply base to European and American manufacturers with established biocompatibility documentation. Manufacturing concentrates in Germany, the United States, and Iceland for carbon-composite fabrication, with thermoplastic component sourcing from China and South Korea. Raw material dependencies span carbon fiber from Japan and the United States, medical-grade polymers from Germany and Belgium, and aluminum alloys from domestic Gulf smelters. Single-source vulnerability runs through Japanese Toray carbon fiber supply. Distribution runs through hospital-direct contracts in Saudi Arabia and the UAE, bypassing fragmented retail intermediaries in Egypt and Nigeria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Orthotic Devices Market functions as a geographic-arbitrage opportunity where Dubai's mandatory insurance expansion unlocks patient access at premium pricing points unavailable in Cairo's reimbursement-constrained environment.
For Market Incumbents: Cement dominance in Saudi government procurement by acquiring CE-marking capabilities ahead of SFDA's streamlined registration pathway maturation. Lock in multi-year supply agreements with Toray or Hexcel to hedge carbon fiber input volatility threatening mid-tier margin structures. Defend against climate-calibrated thermoplastic entrants by accelerating in-house R&D for high-temperature polymer formulations. For New Entrants and Emerging Players: Capture volume in South Africa's pediatric orthopedic clinic networks where technician density constraints have slowed incumbent penetration. Exploit reimbursement gaps in Egyptian home care delivery through mobile fitting units equipped for CAD-CAM workflows. Lead with thermoplastic ankle-foot systems priced below Ottobock's carbon-composite premium tier. For Investors and Strategic Acquirers: Consolidation pressure builds where distributor fragmentation in Egypt and Nigeria meets hospital-direct distribution mandates from Saudi Vision 2030 procurement. Target mid-tier European manufacturers with MOHAP registration but limited Gulf hospital contracts. Watch for inflection when Dubai Health Authority expands orthotic benefit caps beyond current custom-fabrication thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | SFDA accelerated review unlocks Saudi government procurement quotas ahead of unregistered competitors. |
| Carbon Fiber Supply Agreement | Long-term Toray or Hexcel contracts hedge aerospace sector competition for orthotic-grade prepreg materials. |
| Hospital System Partnership | Direct contracts with Riyadh and Jeddah rehabilitation centers bypass fragmented Egyptian retail channels. |
| Climate-Calibrated Formulation R&D | Thermoplastic systems resisting Gulf heat degradation capture preference share from conventional polymer failures. |
| CAD-CAM Fabrication Deployment | Same-day molding workflows from patient scan data compress fitting cycles in high-volume Saudi clinics. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with prosthetic and orthotic department heads, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against SFDA registration databases, MOHAP device listings, hospital procurement tenders, and customs import records for carbon fiber and thermoplastic components. Bottom-up demand modeling from patient population estimates and top-down supply verification from manufacturer shipment data were triangulated to constrain forecast variance.
Segment-weighting applied differential growth assumptions across product type, application, end user, material, and country-specific regulatory cluster dimensions. CAGRs were derived from fitted trend extrapolation calibrated to historical import velocity and announced hospital construction timelines. Key inputs included diabetes prevalence projections for Charcot foot demand, Vision 2030 infrastructure spend commitments, and carbon fiber price indices from aerospace composite markets.
Underlying measurement precision varies by segment; Saudi Arabia and UAE hospital procurement data carry tighter precision than Egyptian distributor estimates. Forecasts reflect documented assumptions regarding insurance expansion timing and regulatory pathway maturation. A model refresh is warranted upon material change in Dubai Health Authority benefit caps or SFDA registration fee structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Veterinary Radiography Flat Panel Detectors Market
Medical Devices
North America Ultrasound Probe Disinfection Market
Medical Devices
Global Blood Processing Devices and Consumables Market
Medical Devices
Global Angiography Devices Market
Medical Devices
Cervical Artificial Discs Market
Medical Devices
Global Extremities Market
Medical Devices
Urodynamic Catheter Market
Medical Devices
Global Thrombectomy Devices Market
Medical Devices
Global Medical Drones Market
Medical Devices
Digital Vision Lenses Market
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
Otorhinolaryngology Devices Market
Medical Devices
High Flow Oxygen Therapy Devices Market
Medical Devices
Global Mechanical Ventilators Market
Medical Devices
Supraglottic Device Market
Medical Devices
Global Robotic Endoscopy Devices Market