
 Below-The-Knee Implants Market | 2026-2036
Below-The-Knee Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Below-The-Knee Implants Market Outlook
Hospital procurement consortiums is reconfiguring how below-the-knee implant manufacturers secure volume contracts across integrated delivery networks. Stryker Corporation leverages its trauma and extremities portfolio to anchor long-term supply agreements with major orthopedic service lines. Zimmer Biomet competes through specialized foot and ankle platforms that differentiate its offerings in revision-heavy segments. Johnson & Johnson sustains channel presence via its DePuy Synthes distribution infrastructure, which controls access to ambulatory surgery centers performing tibial and fibular procedures.
Below-the-knee implants encompass prosthetic sockets, pylon systems, and foot-ankle assemblies engineered from carbon fiber composites or titanium alloys, with torsional stiffness calibrated to patient mass and activity level for gait normalization. These devices restore ambulatory function following transtibial amputation or address limb salvage scenarios in diabetic foot and trauma cases. Implantable segments using titanium fixation plates dominate revision volumes where osseointegration failure demands hardware exchange. Permanent usage types command premium positioning against temporary fittings, while orthopedic clinics concentrate the highest-margin custom-fit workflows where silicone liner interfaces and carbon fiber pylons generate recurrent service revenue.
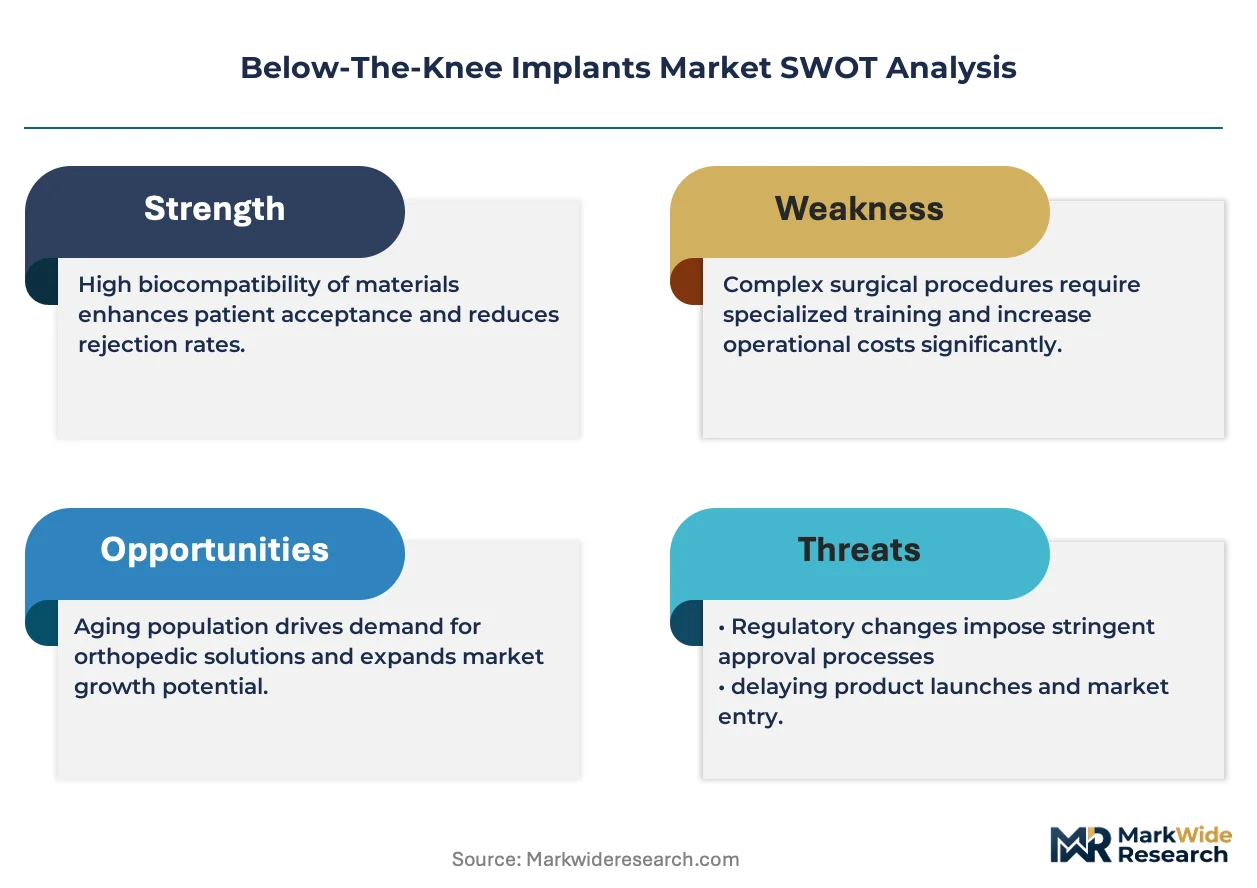
The FDA's 510(k) premarket notification and the EU Medical Device Regulation (MDR) impose divergent clinical evidence requirements that fragment product registration strategies for manufacturers serving both jurisdictions. ISO 10328 structural testing standards govern prosthetic component durability, directly shaping R&D allocation toward fatigue-resistant materials. Stakeholders must monitor how CMS national coverage determinations for osseointegrated prostheses evolve, as this reimbursement signal will dictate whether academic medical centers expand into implantable socket technology or remain anchored to conventional suspension systems.
Market Dynamics
Hospital procurement consortiums are consolidating purchasing power across integrated delivery networks, forcing below-the-knee implant manufacturers to restructure contract terms around volume guarantees and outcome metrics rather than discrete device pricing.
Growth Catalysts
- Statutory health insurance frameworks:Germany's reimbursement protocols for advanced prosthetic components incentivize orthopedic clinics to expand custom-fitting capabilities as core service lines.
- Carbon fiber composite engineering:Torsional stiffness calibration to patient mass and activity level enables gait normalization that permanent fittings deliver over temporary alternatives.
- Osseointegration research pipelines:Academic medical centers in Australia and Sweden are generating clinical evidence packages that support FDA 510(k) pathway expansion for implantable socket technology.
Market Restraints
- Titanium alloy input volatility:Aerospace and medical device competition for premium-grade titanium creates price pressure on pylon and fixation plate manufacturing.
- EU MDR clinical evidence requirements:The divergence from FDA 510(k) standards fragments product registration strategies and extends time-to-market for manufacturers serving both jurisdictions.
- Silicone liner interface limitations:Sweat management and dermatological complications in tropical climates restrict addressable populations for standard suspension systems.
Strategic Opportunities
- Osseointegrated prostheses reimbursement:CMS national coverage determinations signal potential expansion of implantable socket technology into Medicare-covered procedures.
- Ambulatory surgery center channel development:Tibial and fibular procedure migration from hospital inpatient settings creates new distribution nodes for titanium fixation plates.
- Diabetic foot and trauma limb salvage:Rising diabetic population incidence in India and Brazil generates demand for revision-volume hardware exchange protocols.
Industry Challenges
- Prosthetist certification timelines:ISO 10328 structural testing competency requirements extend workforce development cycles for custom-fit workflows.
- Legacy suspension system integration:Orthopedic clinics face capex demands when retrofitting casting and measurement infrastructure for computer-aided design socket fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Below-The-Knee Implants Market |
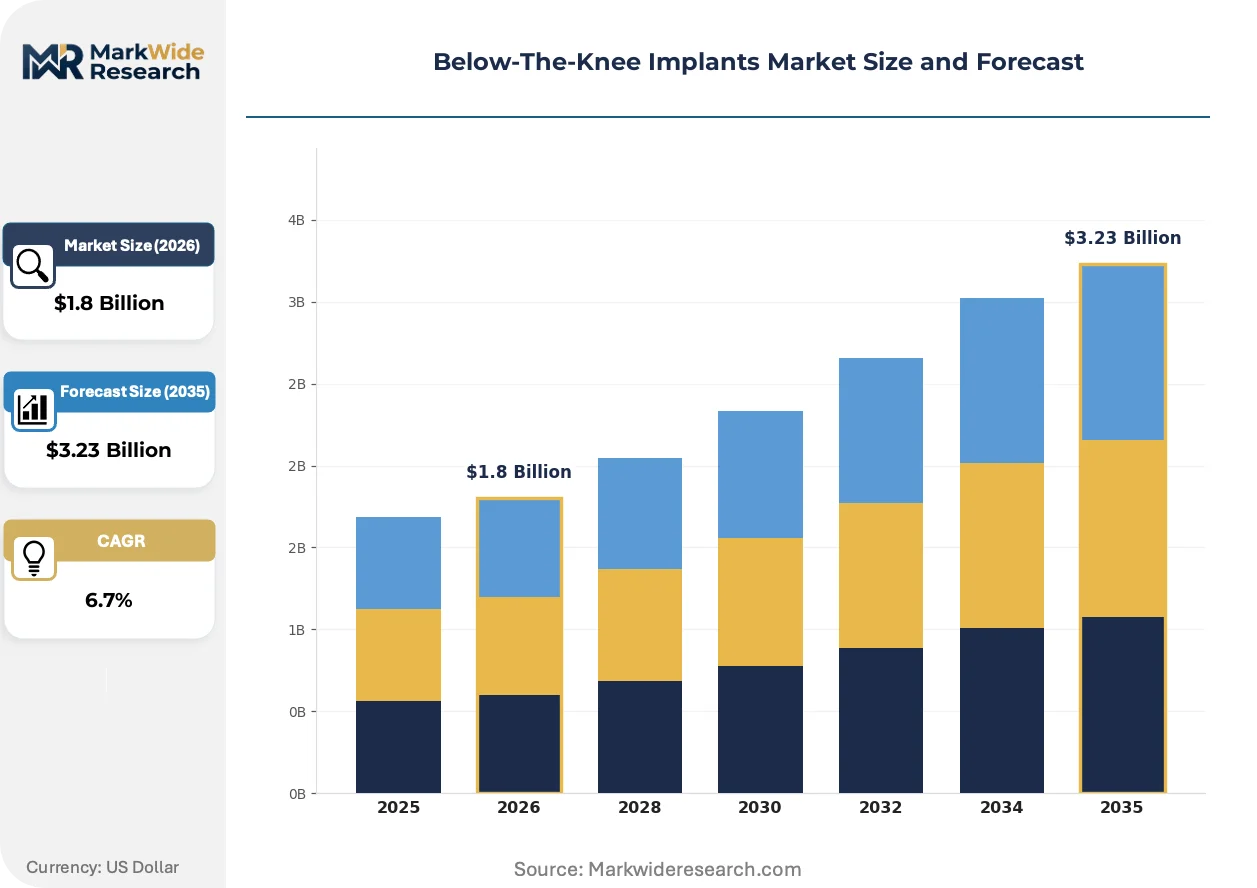
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prosthetic, Orthotic, Implantable, Biomechanical Material: Polyethylene, Titanium, Carbon Fiber, Silicone End User: Orthopedic Clinics, Rehabilitation Centers, Hospitals, Podiatrists Usage Type: Permanent, Temporary, Custom-Fit, Standard-Fit |
| Companies Covered | Stryker Corporation, Zimmer Biomet, Johnson & Johnson, Smith & Nephew, B. Braun, Arthrex, Exactech, Integra LifeSciences, MicroPort Orthopedics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Below-The-Knee Implants Market Strategic Shifts
Digital manufacturing workflows and biomaterial advances are compressing the traditional boundaries between prosthetic fitting, surgical implantation, and long-term rehabilitation monitoring.
Additive manufacturing of titanium lattice structures is collapsing the lead time between patient-specific imaging and definitive socket production. Orthopedic clinics with in-house electron beam melting capacity are reducing fitting appointment sequences from six sessions to two. This compression is eliminating the geographic radius constraints that previously limited patient access to specialized prosthetic centers.
The EU Medical Device Regulation's post-market surveillance requirements are extending clinical follow-up obligations for implantable segments. Manufacturers must now maintain patient registries that track osseointegration failure modes across fifteen-year horizons. Revision-heavy product categories face disproportionate documentation burdens that favor established players with existing quality management systems.
Veterans Affairs healthcare systems are consolidating prosthetic procurement through centralized national contracts rather than facility-level purchasing. This concentration is displacing regional distributors who previously managed silicone liner inventory and carbon fiber pylon logistics. The shift is most visible in the United States, where VA facilities account for a substantial share of high-activity-level patient fittings.
Below-The-Knee Implants Market Segmentation
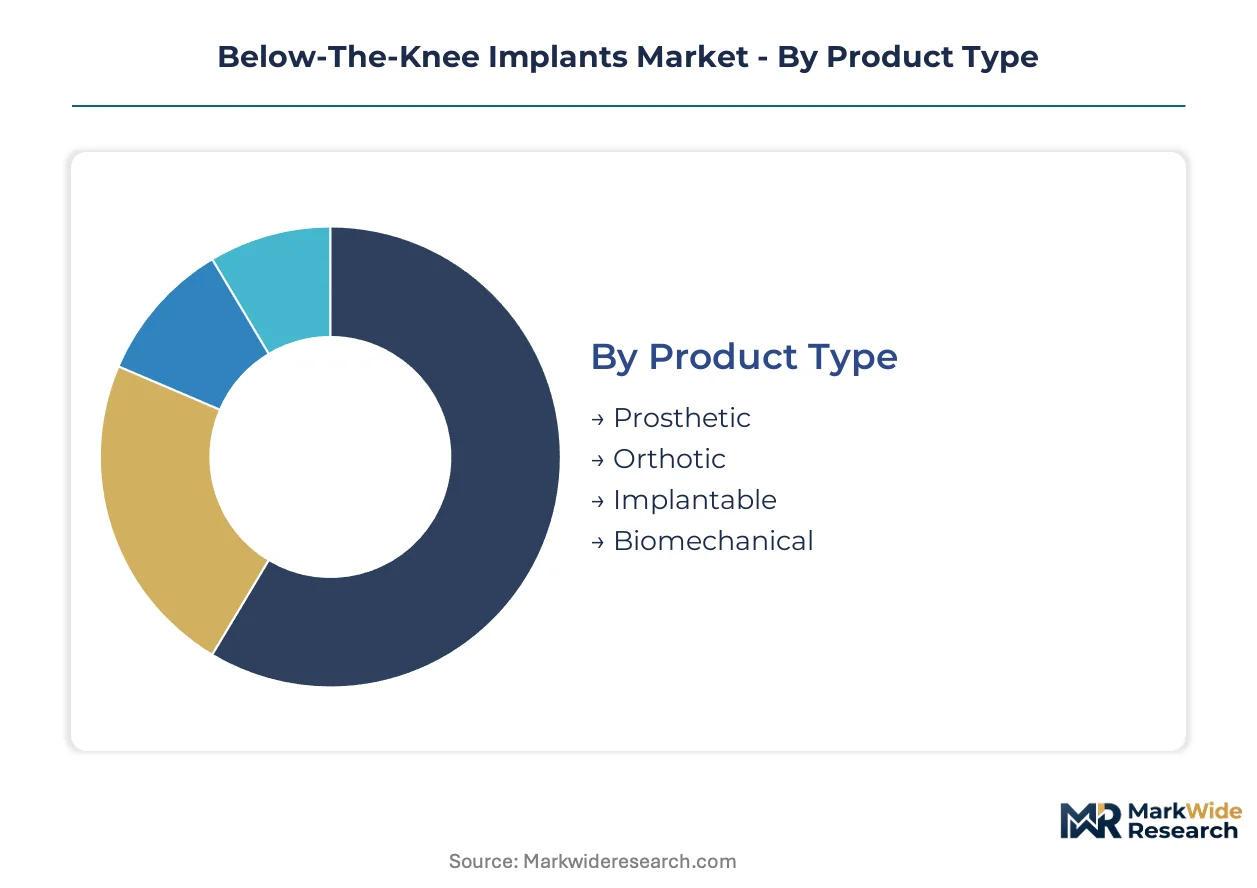
Below-the-knee implant manufacturers structure portfolio decisions around four intersecting dimensions that determine reimbursement pathways and clinical workflows. Product type and material selection dictate regulatory classification and manufacturing investment, while end-user channel and usage type define pricing architecture and service revenue potential.
Product Type:
Application focus separates segments by whether devices restore ambulatory function externally or integrate surgically with skeletal structures.
- Prosthetic:External socket-pylon-foot assemblies replace amputated limb segments. Demand concentrates in German orthopedic clinics where statutory health insurance covers carbon fiber composite pylons calibrated to patient activity levels.
- Implantable:Titanium fixation plates and osseointegrated sockets address revision scenarios where conventional suspension fails. Academic medical centers in Sweden and Australia are building clinical evidence packages for FDA 510(k) pathway expansion.
- Orthotic:External bracing systems stabilize compromised limbs without surgical intervention. Podiatrists in diabetic foot programs prescribe these for limb salvage protocols.
- Biomechanical:Sensor-integrated components enable gait analysis and real-time adjustment. Rehabilitation centers deploy these for high-activity patient monitoring.
Prosthetic holds installed capacity. Implantable is rotating up the share rankings.
Material:
Cost tier and performance specifications segment raw material choices across fatigue resistance, weight, and biocompatibility requirements.
- Carbon Fiber:Torsional stiffness calibration to patient mass enables gait normalization that permanent fittings deliver. Aerospace competition for premium-grade fiber creates input price volatility.
- Titanium:Osseointegration properties dominate implantable socket and fixation plate manufacturing. German and Swedish suppliers control vacuum arc remelting capacity for medical-grade alloy.
- Silicone:Liner interfaces manage suspension and shear forces between residual limb and socket. Tropical climate sweat management limitations restrict addressable populations.
- Polyethylene:Cost-effective pylon and socket components serve temporary fitting protocols. Volume manufacturing in China supplies standard-fit workflows.
Titanium commands margin concentration. Carbon fiber is climbing the fastest.
End User:
Customer type determines service intensity, reimbursement complexity, and distribution infrastructure requirements.
- Orthopedic Clinics:Custom-fit workflows generate recurrent revenue from silicone liner replacement and carbon fiber pylon upgrades. Germany's reimbursement framework incentivizes capability expansion as core service lines.
- Hospitals:Acute trauma and limb salvage procedures concentrate titanium fixation plate demand. Integrated delivery network procurement consortiums are consolidating purchasing power across volume contracts.
- Rehabilitation Centers:Gait training and prosthetic fitting sequences require specialized prosthetist certification. ISO 10328 structural testing competency extends workforce development cycles.
- Podiatrists:Diabetic foot screening and early intervention create upstream referral pathways. Rising diabetic population incidence in India and Brazil expands addressable volume.
Orthopedic clinics anchor premium positioning. Rehabilitation centers are gaining share fastest.
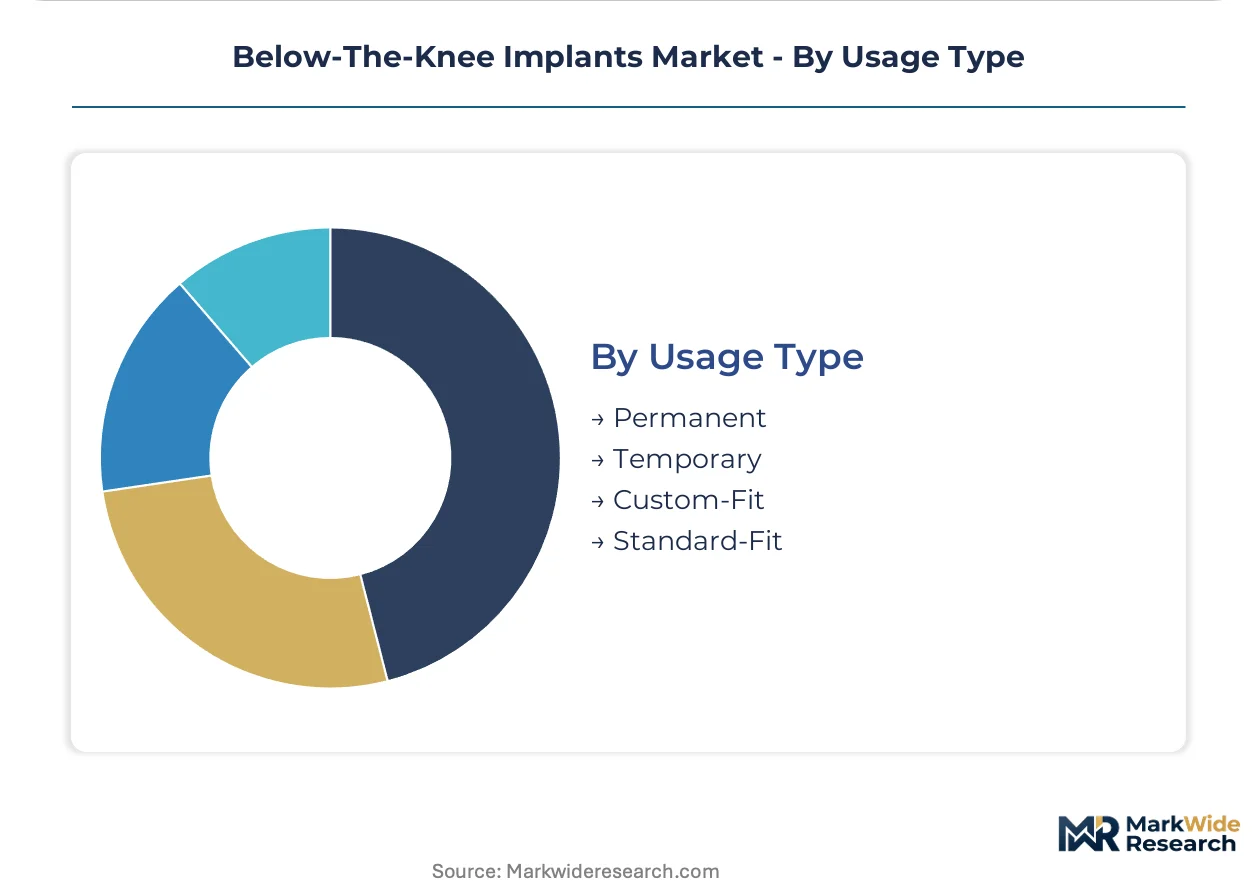
Usage Type:
Volume and margin structure diverge between standardized manufacturing and patient-specific fabrication workflows.
- Custom-Fit:Computer-aided design socket fabrication from patient imaging collapses fitting sequences. Orthopedic clinics face capex demands when retrofitting casting infrastructure for digital workflows.
- Permanent:Definitive prosthetic fittings command premium positioning against temporary alternatives. Veterans Affairs healthcare systems concentrate procurement through centralized national contracts.
- Standard-Fit:Prefabricated components serve cost-sensitive and temporary fitting scenarios. Distribution runs through regional distributors managing silicone liner inventory logistics.
- Temporary:Post-operative and preparatory fittings bridge acute care to definitive prosthesis. Hospital discharge planning drives volume concentration.
Permanent holds installed capacity. Custom-fit is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in carbon fiber composite imports for prosthetic manufacturing, while Rotterdam's medical device distribution hub channels titanium alloys into Dutch orthopedic clinics.
United States
Veterans Affairs healthcare systems drive demand for high-activity-level prosthetic fittings through centralized national procurement contracts. FDA's 510(k) clearance pathway shapes how manufacturers structure clinical evidence packages for lower-limb devices. Academic medical centers in Baltimore and Seattle are expanding osseointegration research pipelines.
Germany
Statutory health insurance reimbursement for advanced prosthetic components incentivizes orthopedic clinics to expand custom-fitting capabilities. EU Medical Device Regulation imposes post-market surveillance requirements extending clinical follow-up obligations to fifteen-year horizons. The Ruhr industrial corridor hosts vacuum arc remelting capacity for medical-grade titanium alloy production.
Sweden
Academic medical centers in Gothenburg and Stockholm generate clinical evidence packages supporting FDA 510(k) pathway expansion for implantable socket technology. The country's national pharmaceutical regulator maintains stringent biocompatibility standards for osseointegrated devices. Sahlgrenska University Hospital anchors limb salvage research clusters.
Australia
Public hospital procurement frameworks concentrate titanium fixation plate demand for trauma and diabetic foot revision scenarios. The Therapeutic Goods Administration aligns clinical evidence requirements with ISO 10328 structural testing standards. Melbourne's prosthetic research institutes collaborate with Swedish counterparts on gait normalization protocols.
India
Rising diabetic population incidence in Maharashtra and Tamil Nadu generates demand for revision-volume hardware exchange protocols. The Central Drugs Standard Control Organization governs import licensing for implantable orthopedic devices. Mumbai's orthopedic service lines are retrofitting casting infrastructure for computer-aided design socket fabrication.
Below-The-Knee Implants Market Competitive Environment
On the supply side, the industry is consolidating around diversified orthopedic conglomerates with trauma and extremities portfolios, while specialized foot-and-ankle platforms carve defensible niches in revision-heavy segments. Three archetypes dominate: integrated delivery network contract anchors, carbon fiber composite specialists, and osseointegration technology developers. M&A activity targets digital manufacturing workflows, and strategic partnerships secure titanium alloy supply chains.
Among US-based diversified conglomerates, Stryker Corporation and Johnson & Johnson occupy positions as integrated delivery network contract anchors, while Zimmer Biomet exemplifies the specialized foot-and-ankle platform archetype. These three companies represent distinct competitive vectors—volume contracting, distribution infrastructure control, and revision-segment differentiation—that structure how procurement consortiums negotiate supply agreements across hospital systems and ambulatory surgery centers.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet |
| Johnson & Johnson |
| Smith & Nephew |
| B. Braun |
| Arthrex |
| Exactech |
| Integra LifeSciences |
| MicroPort Orthopedics |
| Others |
Value Chain & Pricing Dynamics
The Ruhr industrial corridor's vacuum arc remelting capacity for medical-grade titanium alloy anchors upstream pricing power for implantable socket manufacturers, while Rotterdam's carbon fiber distribution hub channels composite inputs into Dutch orthopedic clinics at volume-scaled rates.
Pricing Analysis
Volume-discount tiering structures separate permanent custom-fit prosthetic assemblies from standard-fit temporary alternatives. Three-tier pricing stratifies across premium carbon fiber pylons, mid-grade titanium fixation plates, and economy polyethylene sockets. Cost compression in the polyethylene tier intensifies because Chinese volume manufacturers feed hospital discharge planning workflows. Podiatrists in diabetic foot programs exhibit highest price sensitivity, whereas German orthopedic clinics with statutory health insurance coverage show lowest sensitivity to carbon fiber composite premiums.
Supply Chain Analysis
Export-control regimes on aerospace-grade carbon fiber limit flows from US and Japanese suppliers into prosthetic manufacturing channels. Medical device production draws from German titanium smelters, Chinese polyethylene molders, and Swedish silicone polymer plants. Single-source vulnerability concentrates in vacuum arc remelting capacity for osseointegration-grade alloy. Distribution runs through integrated delivery network procurement consortiums rather than regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story because FDA 510(k) clearance pathways create regulatory entrenchment that extends product development cycles and locks out unapproved competitors.
For Market Incumbents: Insulate titanium alloy supply positions through captive offtake agreements with Ruhr corridor smelters. Deepen backward integration into carbon fiber composite fabrication to offset aerospace competition for premium-grade fiber. Lock in prosthetist certification pipelines to extend workforce development moats against emerging digital manufacturing entrants.
For New Entrants and Emerging Players: Mid-market orthopedic clinics in India's Maharashtra and Tamil Nadu clusters represent the most penetrable entry point for computer-aided design socket fabrication workflows. Ambulatory surgery centers migrating tibial procedures from hospital inpatient settings offer second-mover channel access. Lead with silicone liner interface innovations addressing tropical climate sweat management limitations that incumbent suspension systems fail to solve.
For Investors and Strategic Acquirers: Long-term, this sits as a reimbursement-entrenchment play because CMS national coverage determinations for osseointegrated prostheses will dictate whether academic medical centers expand implantable socket technology or remain anchored to conventional systems. Target acquisition profiles center on digital manufacturing workflow specialists with in-house electron beam melting capacity. Monitor Veterans Affairs centralized procurement contract awards as the inflection signal for distributor displacement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market surveillance requirements extend clinical follow-up obligations to fifteen-year horizons for implantable segments. |
| Hospital System Partnership | Integrated delivery network procurement consortiums consolidate purchasing power across volume contracts with outcome-metric terms. |
| Reimbursement Strategy | CMS national coverage determinations for osseointegrated prostheses signal Medicare expansion into implantable socket technology. |
| Software Companion Development | Sensor-integrated biomechanical components enable real-time gait adjustment for high-activity patient monitoring in rehabilitation centers. |
| Backward Integration | In-house electron beam melting capacity collapses fitting appointment sequences from six sessions to two for orthopedic clinics. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across prosthetists, orthopedic clinic directors, hospital purchasing committee members, GPO contracts managers, and biomedical engineers. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, CMS national coverage determination records, and ISO 10328 structural testing standards. Bottom-up demand modeling across patient procedure volumes triangulated with top-down supply-side capacity assessments.
Calibration against historical reimbursement pathway expansions and prosthetic component adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade, end-user channel, and usage category. CAGRs derived from procedure volume elasticity to reimbursement coverage changes and raw material input cost trajectories. Industry-specific forecast inputs incorporated diabetic population incidence projections and veterans affairs procurement consolidation timelines.
Practitioners should monitor CMS coverage determination timelines and EU MDR post-market surveillance enforcement intensity for early signals of structural shift. Forecasts reflect assumptions on titanium alloy supply stability and statutory health insurance reimbursement continuity. Material shifts in osseointegration clinical evidence acceptance or carbon fiber export-control tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Manometry System Market
Medical Devices
Portable Ultrasonic Skin Scrubber Market
Medical Devices
North America C-Arms Market
Medical Devices
Asia-Pacific Intraoral Scanners Market
Medical Devices
Cyclotron Market
Medical Devices
Wearable Medical Robots Market
Medical Devices
Artificial Implants Market
Medical Devices
Middle East and Africa Non-Surgical Procedures Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Global Anti-Snoring Device Market
Medical Devices
Thoracolumbar Spine Devices Market
Medical Devices
South Africa Anti-Blue Ray Myopia Lenses Market
Medical Devices
Global Tympanostomy Products Market
Medical Devices
Public Access Automated External Defibrillators (Aeds) Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Non-Destructive Medical Technologies Market