
 Spine Positioning Devices Market | 2026-2036
Spine Positioning Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spine Positioning Devices Market Analytics
Hospital group purchasing organizations are rewriting procurement dynamics for capital-intensive positioning equipment. Stryker leverages its integrated surgical technologies portfolio to bundle table systems with navigation platforms. Hill-Rom anchors its position through long-term service contracts and preventive maintenance programs that lock in replacement cycles.
Spine positioning devices encompass mechanical, electromechanical, and robotic systems engineered to immobilize and orient the patient during spinal intervention, typically featuring carbon-fiber radiolucent tabletops with ±15 degree Trendelenburg articulation and integrated pressure-relief surfaces to prevent operative neuropathy. Patient positioning systems and surgical tables command the largest installed base, while robotic-assisted systems represent the fastest-expanding technology segment as hospitals seek workflow integration with intraoperative imaging. Accessories and disposable cushioning generate recurring revenue streams with margin profiles that exceed capital equipment sales.
FDA 510(k) clearance pathways and ISO 13485 quality management standards govern device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa positioning systems marketed in Europe. Stakeholders must monitor how CMS technology add-on payments and parallel European hospital budgeting reforms reshape upgrade timelines across integrated delivery networks.
Market Dynamics
Robotic-assisted positioning platforms are compressing replacement cycles for legacy mechanical tables as ambulatory surgical centers scale outpatient spine capacity under evolving CMS reimbursement frameworks.
Growth Catalysts
- CMS outpatient procedure expansion:Reimbursement parity for select spinal fusions performed in ambulatory settings accelerates capital deployment toward compact, imaging-integrated positioning systems.
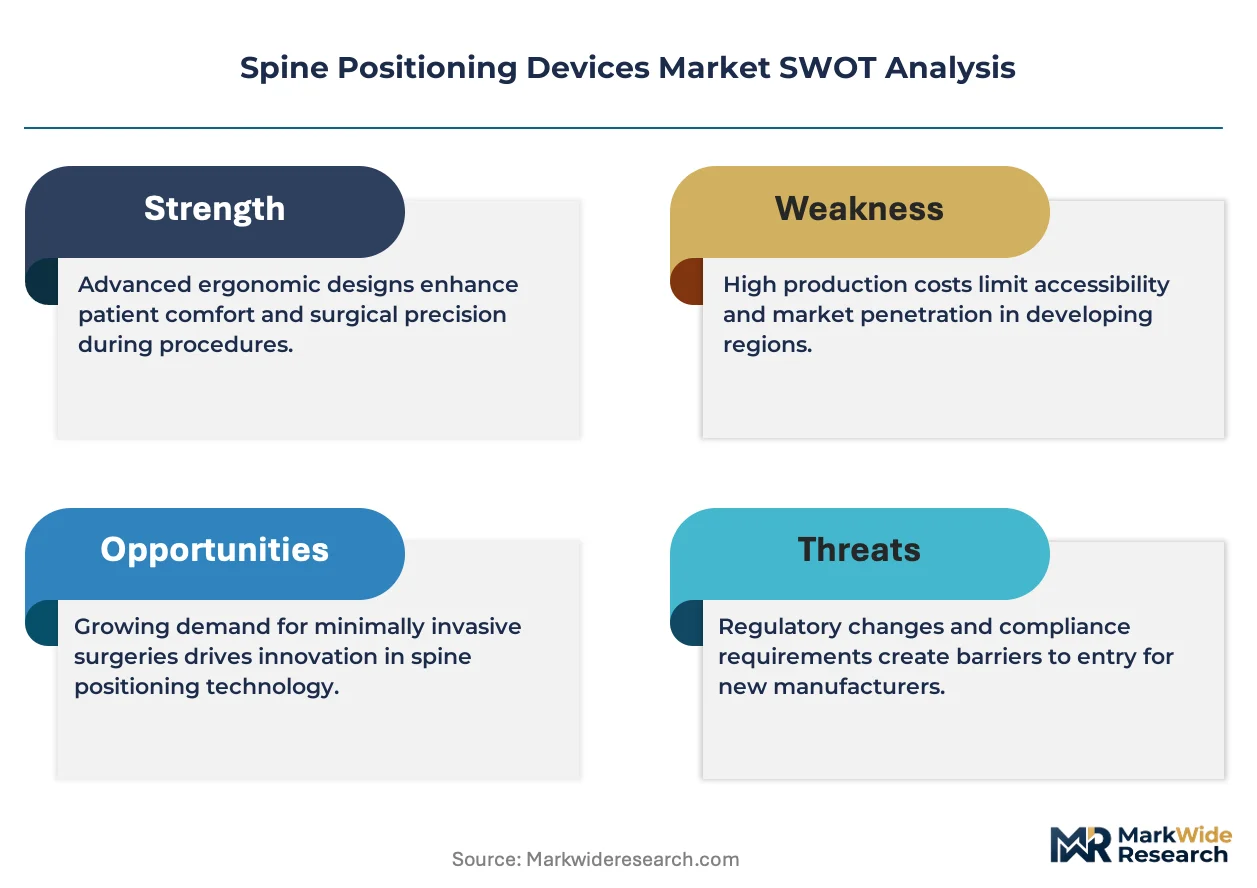
- Carbon-fiber tabletop adoption:Radiolucent materials enabling intraoperative CT and fluoroscopy without patient repositioning drive upgrade demand across integrated delivery networks.
- Integrated delivery network consolidation:Multi-facility health systems standardize on single-vendor table platforms to streamline technician training and service contract management.
Market Restraints
- Capital intensity barriers:Robotic positioning platforms require seven-figure upfront investment that constrains procurement at independent surgical centers and community hospitals.
- Service contract lock-in:Long-term preventive maintenance agreements with incumbent vendors create switching friction and delay competitive replacement cycles.
- Technical interoperability gaps:Proprietary communication protocols between positioning systems and third-party navigation platforms limit mix-and-match purchasing flexibility.
Strategic Opportunities
- EU MDR clinical evidence pathways:Stricter European Medical Device Regulation requirements for Class IIa positioning systems create first-mover advantage for manufacturers with robust clinical data packages.
- Disposable cushioning monetization:Pressure-relief surface replacements and single-use positioning accessories generate recurring revenue streams with margin profiles exceeding capital equipment sales.
- AI-enabled pressure mapping convergence:Integration of real-time neural monitoring with automated table articulation addresses operative neuropathy risk in prolonged spinal procedures.
Industry Challenges
- Biomedical technician specialization:Electromechanical and robotic table maintenance requires skills distinct from traditional surgical equipment repair, creating regional service coverage gaps.
- 510(k) predicate device navigation:FDA clearance pathways for novel articulation mechanisms demand careful predicate selection to avoid de novo review timelines that delay commercialization.
- Legacy OR infrastructure retrofitting:Ceiling-mounted imaging systems and robotic positioning platforms impose conflicting spatial requirements that complicate hybrid operating room design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spine Positioning Devices Market |
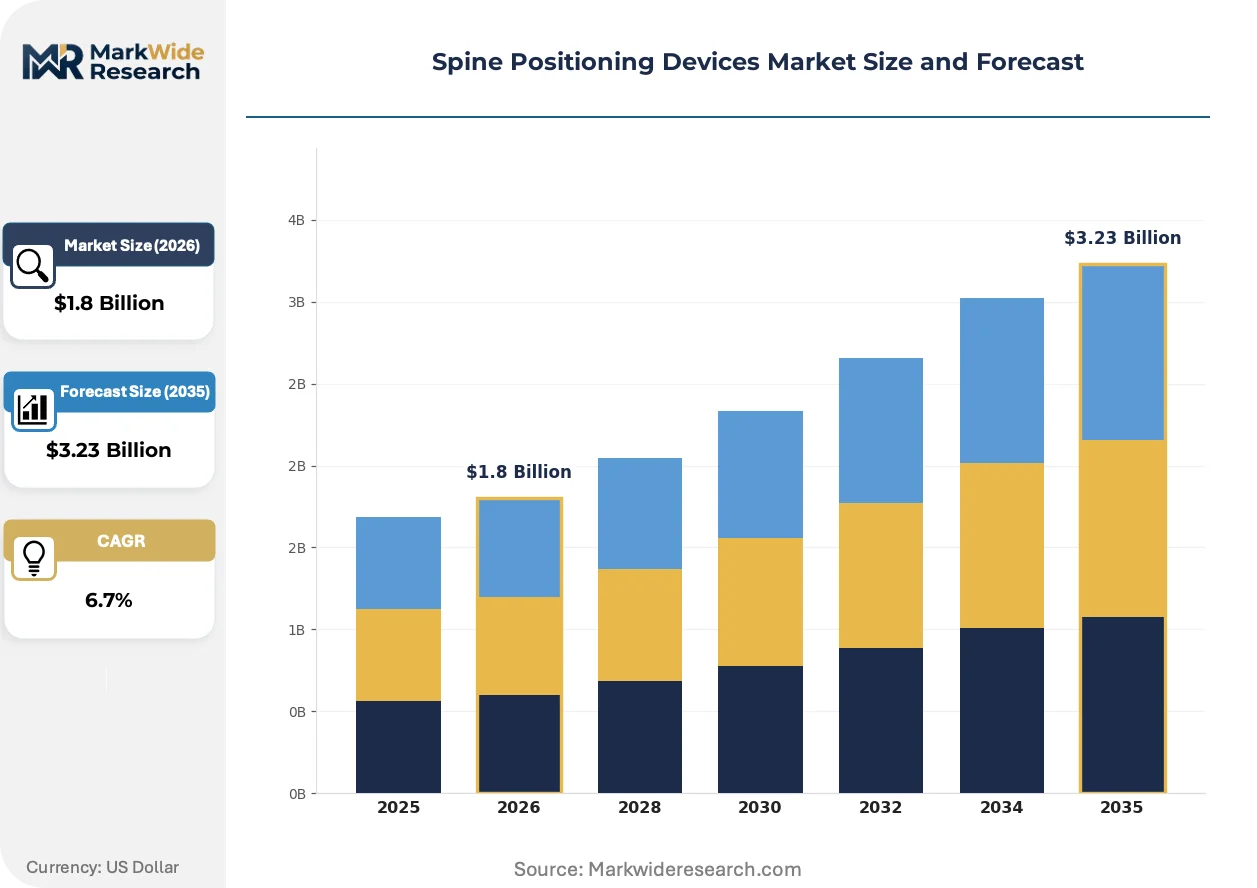
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient Positioning System, Surgical Table, Headrest, Accessories Application: Orthopedic Surgery, Neurosurgery, Postoperative Care, Diagnostic Procedures End User: Hospitals, Surgical Centers, Rehabilitation Facilities, Research Institutes Technology: Robotic-Assisted Systems, Manual Devices, Adjustable Platforms, Imaging Integration |
| Companies Covered | Getinge AB, Hill-Rom, Stryker, Steris Plc, DePuy Synthes, Mizuho OSI, Medline Industries, Smith & Nephew, Span-America Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spine Positioning Devices Market Evolving Landscape
Workflow integration with intraoperative imaging and pressure injury prevention are reshaping positioning device specifications across hospital capital planning cycles.
Robotic table control systems are digitizing surgical workflow coordination by synchronizing patient positioning with preoperative planning software and real-time navigation data. Academic medical centers and high-volume spine centers are deploying these platforms to reduce intraoperative repositioning time. The technology is digitizing the traditional role of circulating nurses in manual table adjustment, compressing procedure duration and standardizing positioning accuracy across surgical teams.
The EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa positioning systems marketed in Europe, including post-market surveillance obligations and notified body involvement in conformity assessment. Manufacturers must now generate clinical performance data beyond bench testing to support 510(k)-equivalent clearances. European hospital procurement committees are extending evaluation timelines to verify MDR compliance documentation before capital commitment.
Subscription-based service models are displacing traditional capital purchase arrangements for high-end positioning platforms, with vendors bundling preventive maintenance, software updates, and replacement part coverage into multi-year operational leases. Integrated delivery networks in the United States are negotiating these contracts to smooth budget volatility and transfer obsolescence risk. This financing restructuring is most visible among nonprofit health systems facing capital expenditure constraints from rising labor and supply costs.
Spine Positioning Devices Market Segmentation
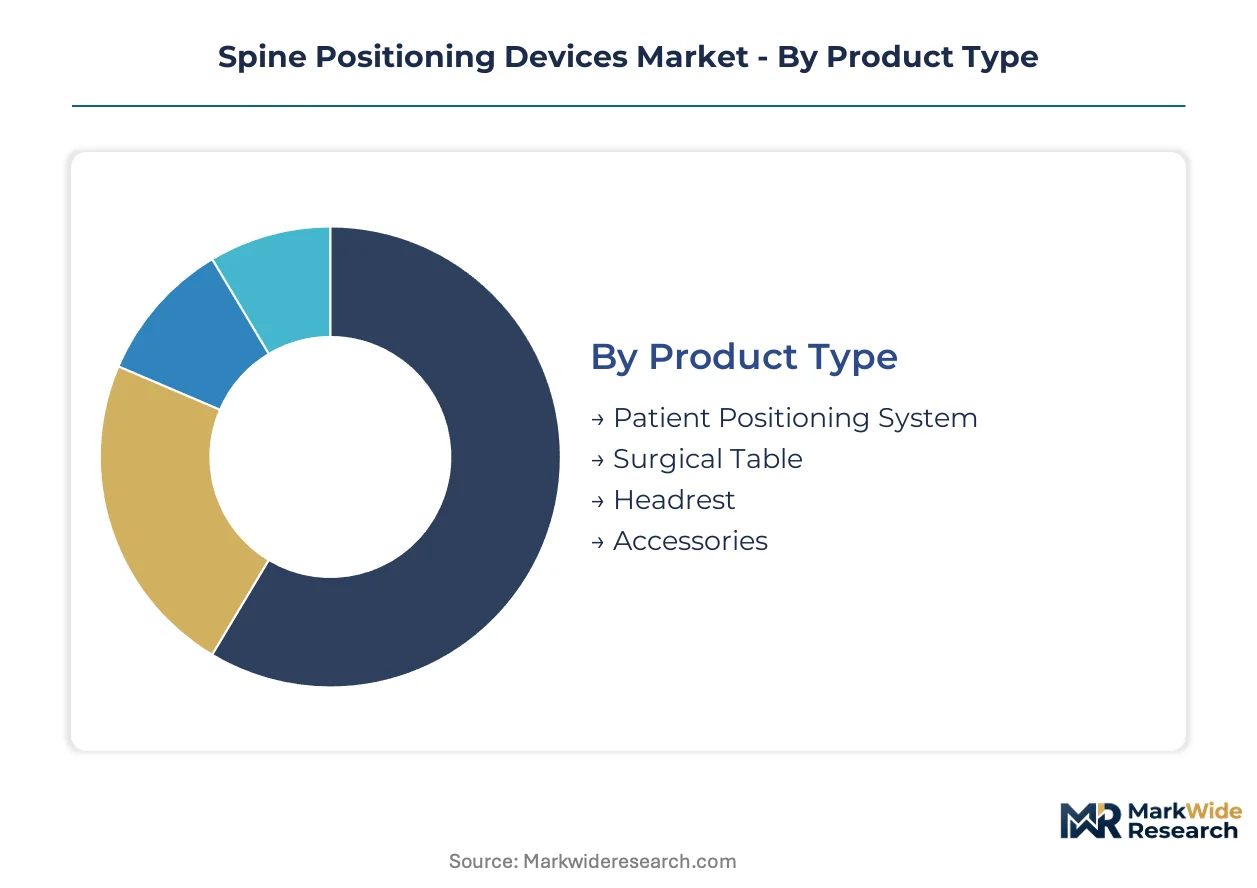
Segmentation in spine positioning devices reveals distinct procurement patterns across product tiers, clinical applications, and facility types. Technical specifications, reimbursement pathways, and capital intensity create divergent growth trajectories that reshape vendor strategies.
Product Type:
Mechanical foundations anchor the installed base while electromechanical and robotic platforms capture upgrade cycles across ambulatory and inpatient settings.
- Patient Positioning System:Carbon-fiber radiolucent tabletops with ±15 degree Trendelenburg articulation and integrated pressure-relief surfaces dominate integrated delivery network standardization programs. United States hospital consolidation drives bulk procurement of compatible systems across multi-facility footprints, with service contract bundling extending replacement timelines.
- Surgical Table:Electromechanical articulation platforms with motorized height adjustment and lateral tilt capabilities command the largest capital expenditure allocation in spine service lines. Ambulatory surgical centers in Texas and Florida prioritize compact footprints with imaging-integrated designs under evolving CMS outpatient reimbursement frameworks.
- Headrest:Disposable and reusable cranial stabilization attachments with three-pin fixation or horseshoe designs address cervical spine access requirements.
- Accessories:Pressure-relief cushioning, lateral supports, and disposable positioning pads generate recurring revenue streams with margin profiles exceeding capital equipment sales.
Established volume favors surgical tables; emerging adoption favors patient positioning systems with robotic articulation.
Application:
Procedure complexity and reimbursement intensity determine positioning device specifications across surgical and non-surgical clinical environments.
- Orthopedic Surgery:Spinal fusion and deformity correction procedures demand radiolucent tabletops compatible with intraoperative CT and fluoroscopy without patient repositioning. Academic medical centers in Germany and the United States deploy integrated navigation-compatible platforms to compress operative time.
- Neurosurgery:Cranial and spinal cord interventions require submillimeter positioning accuracy with real-time neural monitoring integration. Robotic-assisted platforms are expanding most quickly in this segment as surgeons prioritize workflow synchronization with preoperative planning software.
- Postoperative Care:Pressure injury prevention and patient mobilization systems support recovery protocols in step-down units.
- Diagnostic Procedures:MRI-compatible and CT-compatible positioning fixtures enable image-guided interventions outside traditional operating rooms.
Reimbursement concentration favors orthopedic applications; technology upgrade intensity favors neurosurgery.
End User:
Capital availability and procedure volume shape purchasing authority across facility types with divergent equipment lifecycle strategies.
- Hospitals:Integrated delivery networks and academic medical centers deploy seven-figure robotic positioning platforms with multi-year service contracts. United States hospital group purchasing organizations standardize vendor selection across consolidated systems to streamline technician training.
- Surgical Centers:Freestanding ambulatory facilities prioritize compact, imaging-integrated tables under CMS technology add-on payment pathways. Independent centers in Arizona and North Carolina face capital intensity barriers that constrain robotic platform adoption.
- Rehabilitation Facilities:Post-acute settings utilize manual and semi-electric positioning equipment for patient mobilization protocols.
- Research Institutes:Preclinical and biomechanical research centers require specialized fixtures for cadaveric studies and device testing protocols.
Capital deployment scale favors hospitals; volume growth rate favors surgical centers.
Technology:
Automation sophistication separates legacy mechanical installations from next-generation platforms with digital workflow integration.
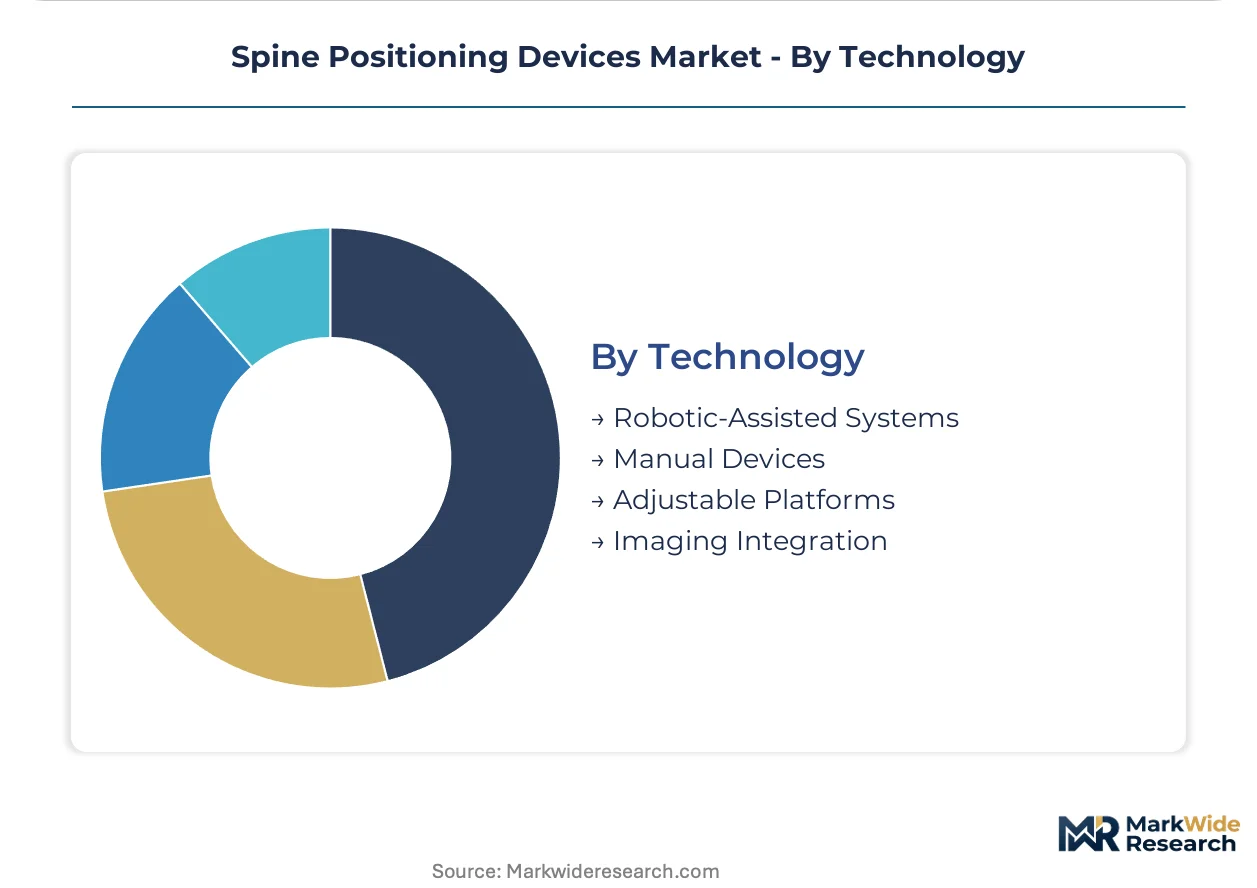
- Robotic-Assisted Systems:Motorized articulation platforms with software-controlled positioning synchronize patient orientation with navigation data and preoperative imaging. FDA 510(k) clearance pathways and proprietary communication protocols create vendor lock-in that limits mix-and-match purchasing flexibility.
- Manual Devices:Hydraulic and mechanical adjustment systems with hand-crank or foot-pedal operation retain substantial installed base in cost-constrained environments. Community hospitals in rural United States markets extend replacement cycles through preventive maintenance programs.
- Adjustable Platforms:Semi-electric systems with powered height adjustment and manual articulation occupy mid-tier price positioning.
- Imaging Integration:Carbon-fiber construction and electromagnetic compatibility specifications enable intraoperative fluoroscopy and CT without patient repositioning.
Installed base concentration favors manual devices; margin expansion favors robotic-assisted systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS reimbursement parity for outpatient spinal fusions is accelerating capital deployment toward imaging-integrated positioning systems in the United States. The EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa positioning systems, extending procurement evaluation timelines across European hospital committees. Japan's aging demographic and universal healthcare framework sustain demand for precision surgical infrastructure.
United States
Integrated delivery networks in Texas and Florida are standardizing on single-vendor table platforms to streamline technician training across multi-facility footprints. FDA 510(k) clearance pathways govern commercialization timelines for novel articulation mechanisms. Academic medical centers in Greater Boston deploy robotic-assisted platforms to compress intraoperative repositioning time during complex deformity corrections.
Germany
University hospitals in Baden-Württemberg and Bavaria prioritize radiolucent carbon-fiber tabletops compatible with intraoperative CT without patient repositioning. The EU MDR requires notified body involvement in conformity assessment for Class IIa positioning systems, elevating documentation burdens for market entry. Industrial clusters around Stuttgart and Munich concentrate electromechanical table manufacturing and precision component supply.
Japan
PMDA regulatory frameworks align with ISO 13485 quality management standards for device commercialization in spinal surgery suites. METI industrial policy supports domestic production of advanced medical equipment including robotic surgical platforms. The Kanto region surrounding Tokyo anchors high-volume spine centers that drive procurement of navigation-compatible positioning systems.
United Kingdom
NHS England procurement frameworks emphasize long-term service contracts and preventive maintenance programs that lock in vendor relationships. MHRA post-Brexit regulatory pathways maintain equivalence with EU MDR clinical evidence requirements for positioning device approvals. The Greater Manchester and London Southeast clusters concentrate academic medical centers pursuing workflow integration with intraoperative imaging.
China
NMPA medical device registration requirements are tightening clinical evidence standards for Class II surgical equipment including positioning systems. Provincial hospital consolidation in Jiangsu and Guangdong provinces is standardizing capital equipment purchasing across municipal health systems. The Yangtze River Delta medical device manufacturing corridor supplies carbon-fiber tabletop components to domestic and export markets.
Spine Positioning Devices Market Competitive Landscape
On the supply side, the industry is consolidating around integrated surgical technologies portfolios that bundle positioning systems with navigation platforms. Tiered competitive dynamics separate multinational conglomerates with full surgical suites from specialized positioning equipment manufacturers. Three archetypes dominate: diversified medtech conglomerates leveraging cross-selling, dedicated surgical table specialists emphasizing service contract lock-in, and emerging robotics players pursuing workflow integration. Dominant competitive moves include strategic partnerships with intraoperative imaging vendors and geographic expansion through hospital group purchasing organization contracts.
Among diversified medtech conglomerates, Stryker and Hill-Rom exemplify the integrated portfolio archetype, bundling table systems with broader surgical infrastructure. Getinge AB represents the specialized surgical equipment tier with concentrated positioning device expertise. These three companies anchor competitive positioning across North American and European procurement channels, with Stryker leveraging its navigation platform integration and Hill-Rom emphasizing long-term service contract structures that extend replacement cycles.
| Leading Market Players |
|---|
| Getinge AB |
| Hill-Rom |
| Stryker |
| Steris Plc |
| DePuy Synthes |
| Mizuho OSI |
| Medline Industries |
| Smith & Nephew |
| Span-America Medical Systems |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta manufacturing corridor anchors carbon-fiber tabletop component production, concentrating supplier leverage among domestic Chinese mills and downstream integrators in Germany and the United States. This geographic concentration shapes pricing power across electromechanical and robotic positioning tiers, with procurement committees absorbing cost volatility through multi-year service contract structures.
Pricing Analysis
Certification level creates the primary spread between FDA 510(k)-cleared platforms and CE-marked alternatives, with ISO 13485 quality management tiering separating premium robotic systems from standard electromechanical tables. Subscription-based service models are displacing capital purchase arrangements as integrated delivery networks seek budget predictability. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize workflow integration over unit cost. Margins are tightening in the manual device tier as community hospitals extend replacement cycles.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for carbon-fiber composite suppliers serving tabletops and radiolucent structures. Component sourcing draws from Germany for precision electromechanical actuators, Japan for robotic control systems, and China for carbon-fiber substrates. Single-source vulnerability concentrates in high-torque motorized articulation modules. Distribution runs through hospital group purchasing organizations in the United States and centralized NHS procurement frameworks in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term service contract lock-in creates a defensive moat for established positioning device vendors, with switching costs embedded in biomedical technician training pathways and preventive maintenance dependencies.
For Market Incumbents: Pre-empt competitive displacement by bundling robotic table platforms with navigation system integration, addressing the interoperability gaps that constrain mix-and-match purchasing. Extend service contract durations to capture replacement cycle timing, while investing in AI-enabled pressure mapping R&D to counter emerging robotics entrants. Anchor position through backward integration into carbon-fiber tabletop manufacturing. For New Entrants and Emerging Players: Freestanding ambulatory surgical centers in Arizona and North Carolina represent the most penetrable end-user segment, with capital intensity barriers delaying robotic adoption among independent facilities. Target these centers with compact, imaging-integrated electromechanical tables offered through operational lease structures rather than capital purchase. Pursue FDA 510(k) clearance with predicate device strategies that accelerate commercialization timelines. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because service contract bundling and disposable accessory monetization generate predictable cash flows detached from capital expenditure cycles. Target acquisition candidates with established GPO contracts and proprietary communication protocols that create vendor lock-in. Monitor CMS technology add-on payment expansion for outpatient spine procedures as the signal indicating accelerated capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Stryker and Hill-Rom leverage integrated delivery network consolidation to standardize multi-facility table platforms. |
| FDA 510(k) Submission | Robotic articulation mechanisms require careful predicate selection to avoid de novo review delays. |
| CE Marking Pathway | EU MDR clinical evidence requirements for Class IIa systems extend procurement evaluation timelines. |
| Software Companion Development | AI-enabled pressure mapping integration addresses operative neuropathy risk in prolonged spinal procedures. |
| Reimbursement Strategy | CMS outpatient procedure expansion accelerates capital deployment toward imaging-integrated positioning systems. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS reimbursement databases, EU MDR notified body documentation, and hospital procurement records. Interviews with biomedical engineers, GPO contracts managers, hospital purchasing committee members, and surgical services directors inform demand-side validation. Bottom-up installed base modeling and top-down capital expenditure triangulation cross-verify segment sizing across mechanical, electromechanical, and robotic technology tiers.
Forecast inputs include procedure volume trajectories, CMS technology add-on payment evolution, EU MDR compliance timeline assumptions, and integrated delivery network consolidation patterns across the projection horizon. Segmentation modeling spans product type, application, end user, and technology automation sophistication. CAGRs derive from replacement cycle compression analysis and ambulatory surgical center capacity expansion rates.
Practitioners should monitor CMS outpatient reimbursement parity decisions, EU MDR notified body capacity constraints, and carbon-fiber composite tariff developments for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Vibrating Mesh Nebulizer Market
Medical Devices
Flow Diverters Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Ocular Trauma Devices Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Global Mobile C-Arm Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Defibrillator Pads Market
Medical Devices
Global Ablation Technologies Market
Medical Devices
Global Scleral Lens Market
Medical Devices
Global Radiofrequency Ablation Devices Market
Medical Devices
Water Flosser Market
Medical Devices
Global Tracheal Tube and Airway Products Market
Medical Devices
Global Subdermal Contraceptive Implants Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Disposable Contact Lenses Market