
 US Nebulizer Market | 2026-2036
US Nebulizer Market Size, Share, and Industry Trends Forecast 2026-2036
US Nebulizer Market Insights
The EPA Clean Air Act enforcement and state-level emissions mandates are broadening demand for home-based respiratory therapy as hospital-acquired infection risks and urban air quality alerts push patients toward self-administered care. OMRON Healthcare leverages its direct-to-consumer channel infrastructure to sustain brand visibility across retail pharmacy networks. Koninklijke Philips N.V. anchors the premium segment through integrated connectivity platforms that link nebulizer use to remote patient monitoring dashboards. PARI Respiratory Equipment, Inc. specializes in pediatric-targeted delivery systems that dominate cystic fibrosis treatment protocols at US children's hospitals.
A nebulizer converts liquid medication into breathable aerosol droplets for direct lung delivery, typically generating particle sizes between one and five micrometers to optimize alveolar deposition. Jet nebulizers rely on compressed gas passing through a venturi nozzle to fragment medication, while mesh nebulizers employ electroformed or laser-drilled apertures to produce finer aerosols with reduced medication waste. Mesh nebulizers command the fastest-expanding product category as patients prioritize portable, battery-operated units for travel and workplace use. Homecare patients represent the deepest end-user margin pool because recurring medication refills and replacement part orders generate sustained revenue streams beyond initial device sales.
FDA 510(k) clearance requirements and ISO 13485 quality management standards govern device manufacturing, while CMS reimbursement codes directly determine patient out-of-pocket costs and physician prescribing behavior. OSHA respiratory protection standards and state-level scope-of-practice regulations for respiratory therapists shape training protocols and device deployment settings across care facilities. Stakeholders must monitor proposed FDA de novo classification pathways for smartphone-connected nebulizers and anticipate how Medicare Advantage plan coverage expansions will redistribute volume across retail and clinical channels.
Market Dynamics
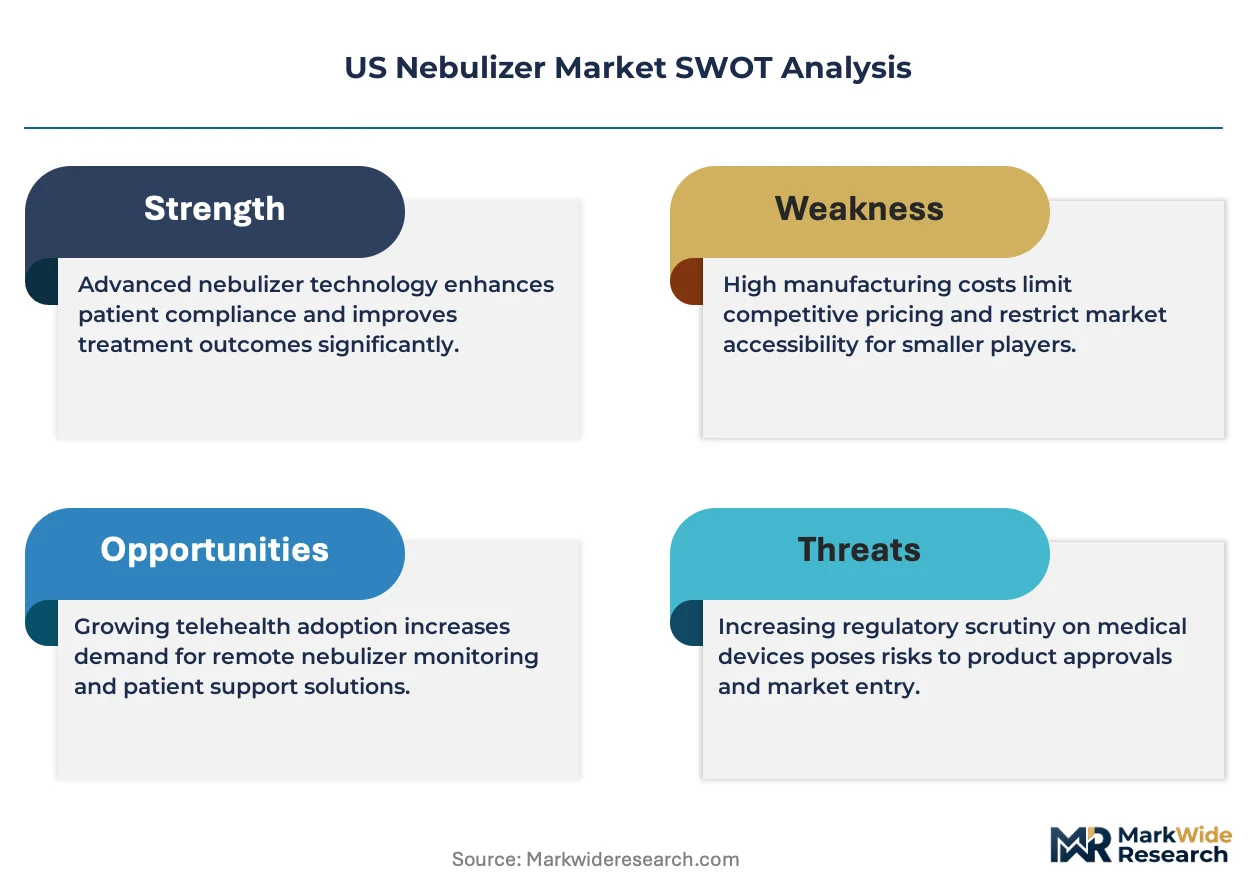
Mesh nebulizer technology is compressing the traditional jet nebulizer installed base as patients and payers prioritize portability, medication efficiency, and reduced treatment times. FDA 510(k) clearance timelines and CMS reimbursement code stability now determine whether manufacturers capture the homecare shift or cede ground to connected inhaler alternatives.
Growth Catalysts
- Medicare Advantage coverage expansion:CMS reimbursement flexibility for home oxygen therapy is pulling chronic respiratory patients out of clinical settings and into Medicare-reimbursed self-administered care models.
- Portable mesh technology:Battery-operated systems with laser-drilled apertures are displacing compressed-gas units among working-age COPD populations who require workplace and travel compatibility.
- Southeastern care facility density:Geriatric care infrastructure concentration across Florida, Georgia, and Alabama is creating localized demand pull that exceeds national prescription averages.
Market Restraints
- Compressed gas supply concentration:Jet nebulizer dependence on medical-grade compressed air systems ties device utility to hospital infrastructure, limiting pure homecare conversion.
- FDA de novo pathway uncertainty:Smartphone-connected nebulizer classification delays are extending product development timelines and freezing capital allocation for digital health integration.
- Connected dry powder inhalers:Propellant-free alternatives with built-in dose tracking are capturing maintenance therapy prescriptions that previously defaulted to nebulized bronchodilators.
Strategic Opportunities
- Remote patient monitoring integration:API-linked nebulizers feeding EHR dashboards are creating subscription revenue streams beyond device sales for integrated health networks.
- Pediatric cystic fibrosis protocols:Specialized delivery systems for children under twelve remain underserved by generic adult-focused mesh platforms at US children's hospitals.
- OSHA respiratory protection alignment:Workplace wellness programs covering occupational asthma are opening employer-sponsored reimbursement channels outside traditional Medicare and commercial insurance.
Industry Challenges
- Respiratory therapist scope-of-practice fragmentation:State-level licensing variations create training protocol inconsistencies that slow device deployment standardization across multi-state health systems.
- ISO 13485 quality management capex:Small manufacturers face facility certification costs that compress R&D budgets and delay product pipeline advancement.
- Replacement part supply chain reconfiguration:Mesh aperture manufacturing concentration in single-source electroforming facilities creates vulnerability to quality variance and delivery disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Nebulizer Market |
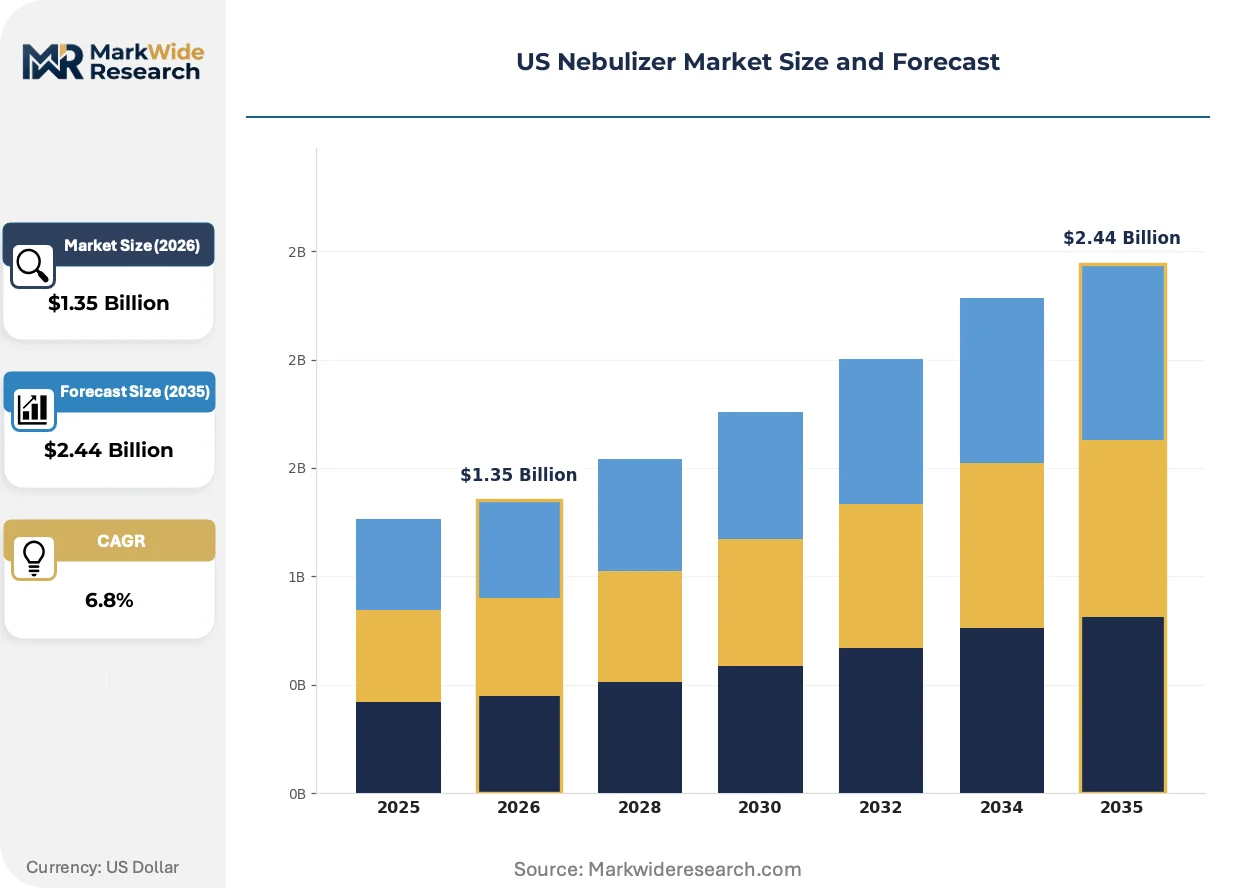
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jet Nebulizers, Ultrasonic Nebulizers, Mesh Nebulizers, Vibrating Mesh, Portable Systems Application: Chronic Obstructive Pulmonary Disorder, Cystic Fibrosis, Asthma Control, Bronchiectasis, Pulmonary Fibrosis End User: Homecare Patients, Respiratory Clinics, Pediatric Centers, Geriatric Care Facilities, Specialized Therapy Centers Distribution Channel: Pharmacies, Online Retailers, Medical Device Distributors, Direct Hospital Supply, Respiratory Equipment Suppliers |
| Companies Covered | OMRON Healthcare, Inc., Allied Healthcare Products, Inc., Koninklijke Philips N.V., Drive DeVilbiss Healthcare, PARI Respiratory Equipment, Inc., GE Healthcare, GF Health Products, Inc., Aerogen, Trudell Medical International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Nebulizer Market Trends and Innovations
Device connectivity and aerosol engineering are converging to transform nebulizers from passive medication delivery tools into data-generating care coordination nodes. Three developments are compressing traditional competitive boundaries and recasting value capture mechanisms.
Smartphone-integrated nebulizer systems are automating adherence tracking and dose verification for payers managing high-cost biologic therapies. Pulmonology practices in Medicare Advantage networks are piloting these platforms to reduce hospitalization rates among severe asthma cohorts. The technology is automating prior authorization workflows by generating timestamped usage data that satisfies step-therapy documentation requirements.
EPA Clean Air Act enforcement is tightening ambient air quality standards in metropolitan corridors, pushing allergists and pulmonologists to prescribe preventive home respiratory therapy earlier in disease progression. State-level emissions mandates in California and Texas are correlating with elevated prescription rates for prophylactic bronchodilator nebulization. Pediatric specialists in urban centers are responding by specifying HEPA-compatible nebulizer systems that maintain treatment integrity during air quality alert periods.
Direct-to-consumer pharmacy channels are compressing the traditional durable medical equipment distribution hierarchy that long dominated nebulizer fulfillment. Retail networks with in-clinic respiratory therapists are capturing prescription-to-device conversion that previously flowed through hospital discharge planning. This channel rotation is most visible in Florida and Arizona, where snowbird populations with established pharmacy relationships drive seasonal demand spikes for portable replacement units.
US Nebulizer Market Segmentation
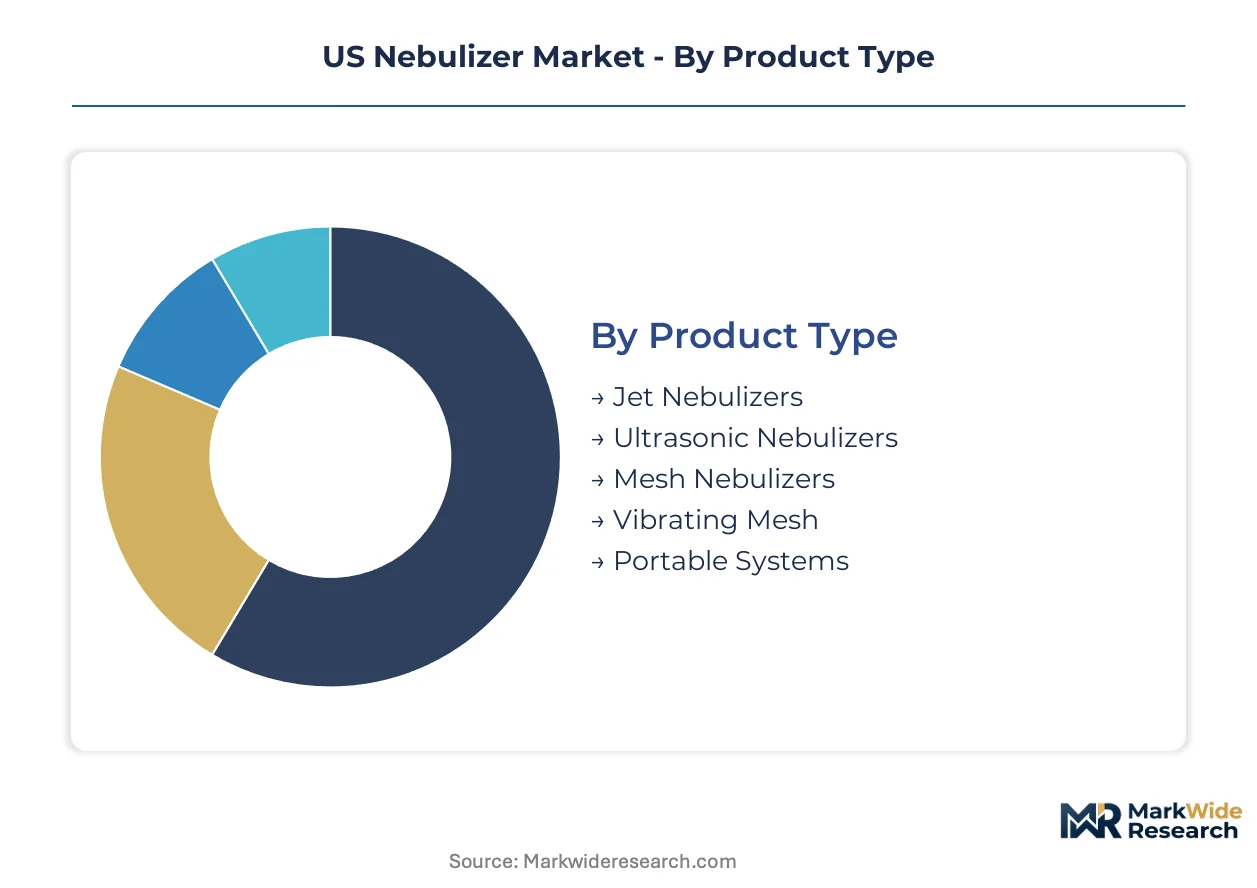
Patient mobility requirements and reimbursement pathways are fragmenting the US nebulizer market into distinct purchasing behaviors. Technology choices, care settings, and distribution access each reshape margin structures and competitive positioning across segments.
Product Type:
Portability and treatment time drive patient willingness to pay premium pricing over compressed-gas alternatives.
- Jet Nebulizers:Compressed-air systems fragment medication through venturi nozzles, producing reliable aerosols at lower equipment cost. Volume concentrates in respiratory clinics and geriatric care facilities where stationary treatment protocols dominate and compressed gas infrastructure is pre-installed.
- Mesh Nebulizers:Electroformed apertures generate finer particle distributions with reduced medication waste. Demand tilts toward homecare patients in Florida and Arizona seeking workplace-compatible, battery-operated units for Medicare-reimbursed chronic COPD management.
- Ultrasonic Nebulizers:Piezoelectric crystal vibration produces aerosols without compressed gas, though heat generation limits thermolabile medication compatibility.
- Vibrating Mesh:Active aperture vibration reduces clogging versus passive mesh designs, commanding price premiums in pediatric cystic fibrosis protocols.
- Portable Systems:Pocket-sized rechargeable units target working-age asthma populations requiring travel-ready prophylactic therapy.
Volume sits with jet systems in institutional settings; growth tilts toward mesh platforms in reimbursed homecare channels.
Application:
Disease severity and biologic therapy eligibility determine device specification requirements and replacement frequency.
- Chronic Obstructive Pulmonary Disorder:Progressive airway obstruction necessitates daily bronchodilator delivery across all severity stages. Medicare Advantage networks in the southeastern United States drive concentrated demand as CMS reimbursement flexibility pulls patients toward self-administered care models.
- Cystic Fibrosis:Thick mucus accumulation requires high-efficiency aerosol deposition for enzymatic and antibiotic therapies. Pediatric specialists at US children's hospitals specify PARI-targeted delivery systems, creating insulated demand with limited price sensitivity.
- Asthma Control:Intermittent symptoms favor rescue inhalers, though severe persistent cases maintain nebulizer prescriptions for acute exacerbation management.
- Bronchiectasis:Irreversible airway dilation requires chronic mucolytic nebulization, with prescription concentration in urban pulmonary practices.
- Pulmonary Fibrosis:Restrictive physiology limits lung compliance, reducing nebulizer efficiency and driving antifibrotic oral therapy substitution.
Prescription volume clusters in COPD maintenance; fastest expansion emerges in cystic fibrosis biologic companion delivery.
End User:
Care setting determines who controls device selection—patient, respiratory therapist, or discharge planner—and thus which distribution channel captures the sale.
- Homecare Patients:Self-directed users prioritize portability, noise reduction, and Medicare coverage eligibility. Florida's snowbird population generates seasonal replacement demand through established pharmacy relationships.
- Respiratory Clinics:Staff-operated settings emphasize treatment throughput and cross-contamination prevention via disposable circuits.
- Pediatric Centers:Face mask compatibility and flow rate adjustability dominate specification requirements for children under twelve.
- Geriatric Care Facilities:Concentrated in Georgia and Alabama, these settings standardize on durable jet systems with simplified patient interfaces.
- Specialized Therapy Centers:Pulmonary rehabilitation programs integrate nebulizers with exercise protocols, requiring rapid medication switching capability.
Recurring revenue concentrates in homecare medication refills; device placement growth accelerates in pediatric specialty centers.
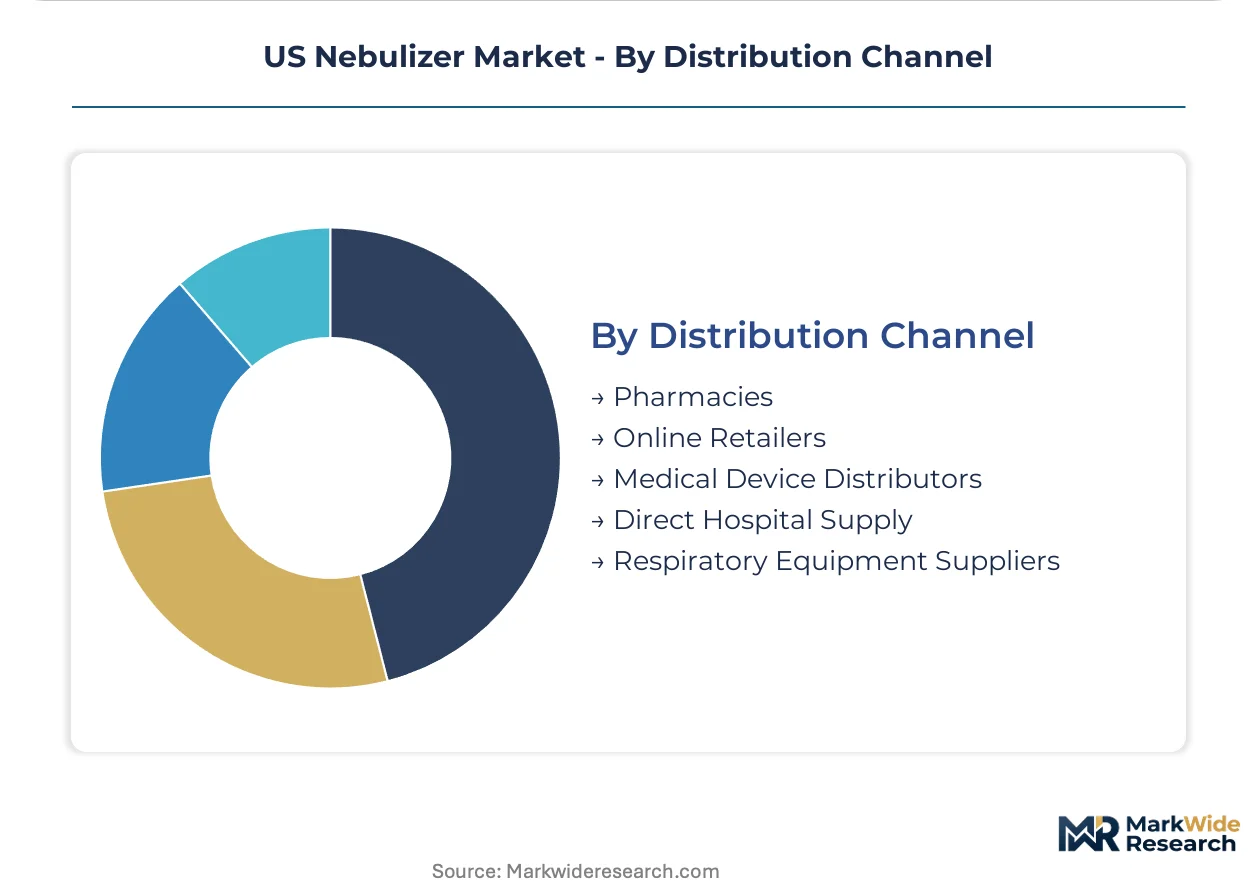
Distribution Channel:
Channel selection determines margin capture—retail pharmacies retain patient relationship data, while distributors handle institutional volume at lower per-unit economics.
- Pharmacies:CVS and Walgreens in-clinic respiratory therapist programs are compressing traditional durable medical equipment hierarchy. Direct-to-consumer conversion in Arizona and Florida pulls prescription fulfillment away from hospital discharge planning.
- Online Retailers:Amazon and specialized respiratory sites capture price-sensitive replacement purchases outside reimbursement networks.
- Medical Device Distributors:McKesson and Cardinal Health dominate institutional procurement with contracted pricing for multi-facility health systems.
- Direct Hospital Supply:Integrated delivery networks source through centralized purchasing, limiting manufacturer pricing autonomy.
- Respiratory Equipment Suppliers:Regional specialists provide training and maintenance services that justify premium positioning in complex pediatric cases.
Institutional volume flows through distributors; patient-direct expansion tilts toward pharmacy and online channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US nebulizer production concentrates in midwestern manufacturing corridors while consumption tilts toward southeastern and southwestern states with elevated chronic respiratory disease prevalence. The mismatch between supply geography and demand density shapes distribution economics and reimbursement policy calibration across state Medicaid programs.
Southeast
Florida, Georgia, and Alabama generate disproportionate prescription volume due to geriatric care facility density and COPD prevalence exceeding national benchmarks. CMS reimbursement flexibility for home oxygen therapy pulls patients toward self-administered mesh nebulizer systems. Atlanta anchors regional distribution networks serving Alabama's rural pulmonary practices.
Southwest
Arizona's snowbird population drives seasonal replacement demand for portable battery-operated units among Medicare Advantage enrollees. EPA Clean Air Act enforcement in Phoenix and Tucson metropolitan corridors elevates preventive nebulizer prescriptions during summer ozone alert periods. Tucson-based respiratory equipment suppliers capture prescription-to-device conversion through established pharmacy relationships.
Midwest
Ohio and Illinois house concentrated durable medical equipment manufacturing operations serving institutional procurement contracts. ISO 13485-certified facilities in Cleveland and Chicago supply jet nebulizer systems to geriatric care networks across the Great Lakes region. Michigan's pulmonary rehabilitation programs integrate nebulizers with exercise protocols requiring rapid medication switching capability.
West Coast
California's state-level emissions mandates correlate with elevated prophylactic bronchodilator nebulization prescriptions in Los Angeles and San Francisco Bay Area pulmonary practices. HEPA-compatible nebulizer specifications dominate pediatric specialist preferences in urban centers facing recurring air quality alerts. San Diego's proximity to Tijuana creates cross-border procurement dynamics for replacement part supply chains.
Northeast
Massachusetts and New York harbor academic medical centers piloting smartphone-connected nebulizer platforms for severe asthma cohorts within integrated delivery networks. FDA 510(k) clearance timelines influence product availability timelines for Boston-based pulmonology practices managing high-cost biologic therapies. Philadelphia's children's hospitals specify specialized delivery systems for cystic fibrosis protocols.
US Nebulizer Market Competitive Landscape
The competitive structure tilts toward diversified health technology conglomerates with established FDA regulatory pathways and Medicare reimbursement expertise. Three archetypes dominate: integrated respiratory care platforms with connectivity capabilities, specialized pediatric delivery system manufacturers, and durable medical equipment suppliers with pharmacy channel access. Consolidation pressure intensifies as CMS reimbursement shifts favor vendors with direct-to-consumer infrastructure and remote patient monitoring integration capacity.
Among diversified health technology conglomerates, Koninklijke Philips N.V. and OMRON Healthcare, Inc. exemplify the integrated platform archetype through their positioning across connectivity-enabled device portfolios. PARI Respiratory Equipment, Inc. occupies a specialized position within pediatric-targeted delivery systems. These three entities represent distinct competitive vectors: premium connectivity integration, direct-to-consumer channel scale, and clinical protocol specialization respectively.
| Leading Market Players |
|---|
| OMRON Healthcare, Inc. |
| Allied Healthcare Products, Inc. |
| Koninklijke Philips N.V. |
| Drive DeVilbiss Healthcare |
| PARI Respiratory Equipment, Inc. |
| GE Healthcare |
| GF Health Products, Inc. |
| Aerogen |
| Trudell Medical International |
| Others |
Pricing and Supply Chain Analysis
Premium-mesh versus commodity-jet bifurcation shapes both margin structures and sourcing footprints across the US nebulizer market, with laser-drilled aperture manufacturing concentrating in ISO-certified midwestern facilities while compressed-gas systems draw from dispersed metal-stamping operations in Mexico and China.
Pricing Analysis
Margin tightening in portable mesh tiers reflects CMS reimbursement code compression and Medicare Advantage formulary restrictions that cap patient out-of-pocket thresholds. Three-tier pricing structure across premium connectivity-enabled, standard battery-operated, and economy jet systems stratifies by FDA 510(k) clearance tier and remote monitoring integration depth. Cost-down pressure on institutional jet units accelerates because GPO contract consolidation favors volume-discounted procurement bundles. Homecare patients exhibit highest price sensitivity, while pediatric cystic fibrosis protocols at US children's hospitals show limited elasticity due to protocol-locked specifications.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific electroforming facilities to midwestern assembly plants is reshaping inventory positioning strategies among mesh aperture suppliers. Component manufacturing draws from China, South Korea, and domestic Ohio-Illinois corridors for piezoelectric crystals, laser-drilled membranes, and molded housings. Single-source vulnerability concentrates in electroformed aperture production, where quality variance at Taiwanese specialist facilities creates downstream FDA submission delays. Distribution runs through McKesson and Cardinal Health for institutional volume, while CVS and Walgreens direct-to-consumer channels capture pharmacy-based replacement sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US nebulizer market sits in a technology-transition phase as battery-operated mesh platforms displace compressed-gas legacy systems across Medicare-reimbursed homecare channels.
For Market Incumbents: Lock in pediatric protocol insulation at US children's hospitals through specialized delivery system R&D that generic mesh competitors cannot replicate without FDA de novo pathways. Secure backward integration into laser-drilled aperture manufacturing to defend margin compression from single-source electroforming bottlenecks. Channel control through in-clinic respiratory therapist programs at retail pharmacy networks protects against durable medical equipment distributor disintermediation.
For New Entrants and Emerging Players: Smartphone-connected nebulizer platforms with API-linked EHR integration offer the most penetrable wedge for Medicare Advantage network penetration, where prior authorization automation commands payer preference. Target southeastern homecare markets in Florida and Georgia where geriatric facility density and COPD prevalence exceed national benchmarks. Pursue OSHA-aligned workplace wellness reimbursement channels outside traditional insurance structures.
For Investors and Strategic Acquirers: Re-rating potential sits with connectivity-enabled device specialists given CMS reimbursement flexibility for remote patient monitoring integration. Long-term viability over a multi-year window favors platforms with FDA regulatory pathway expertise and pharmacy channel infrastructure. Watch FDA de novo classification timelines for smartphone-connected nebulizers as the inflection signal for digital health valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market entry for mesh platforms targeting Medicare Advantage networks. |
| Remote Patient Monitoring Integration | Creates subscription revenue streams beyond device sales for integrated health systems. |
| Hospital System Partnership | Locks in pediatric cystic fibrosis protocol specifications at US children's hospitals. |
| Software Companion Development | Automates adherence tracking for high-cost biologic therapy prior authorization workflows. |
| Reimbursement Strategy | Aligns product positioning with CMS home oxygen therapy coverage expansion trends. |
Research Methodology
Document review covered FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records, complemented by interviews with respiratory therapists, biomedical engineers, GPO contracts managers, and durable medical equipment distributors. Secondary validation drew from EPA Clean Air Act enforcement data, state-level scope-of-practice regulations, and ISO 13485 certification registries. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, end user, and distribution channel dimensions.
Unit shipment and value projections across the analysis window applied patient population epidemiology, Medicare Advantage enrollment trajectories, and technology substitution curves for mesh versus jet platforms. Segmentation modeling incorporated device type, disease indication severity, care setting, and regional reimbursement density. CAGRs derived from fitted adoption curves calibrated to historical CMS code utilization patterns and pulmonary specialist prescribing surveys.
Several conditions sit outside the modeled scope, including FDA de novo classification delays for smartphone-connected devices, sudden compressed gas supply disruptions, and state-level respiratory therapist licensing harmonization. Forecasts reflect documented assumptions about reimbursement stability and technology substitution rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
North America IVD Regulatory Affairs Outsourcing Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
Membrane Oxygenators Market
Medical Devices
Human Anatomical Models Market
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
Photorejuvenation Devices Market
Medical Devices
Mobile Operating Rooms Market
Medical Devices
Interventional Oncology Devices Market
Medical Devices
Urometer Market
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Global Bowel Management System Market
Medical Devices
Water Bath Vaporizer Market
Medical Devices
Connected Drug Delivery Devices Market