
 Home DNA Testing Market | 2026-2036
Home DNA Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Home DNA Testing Market Foresight
Modular test bundling is expanding consumer choice in the Home DNA Testing Market. 23andMe leverages combined ancestry-health packages to sustain premium positioning. Ancestry anchors mass-market penetration through extensive genealogical database scale. MyHeritage competes on international reach with specialized ethnicity reconstruction tools.
Home DNA testing comprises saliva or cheek-swab sample collection for consumer-grade genetic analysis, typically covering single nucleotide polymorphism arrays with coverage of hundreds of thousands to millions of variants; its primary commercial purpose is delivering personalized ancestry, health predisposition, or trait information without clinical intermediation. Ancestry products dominate volume due to lower price points and broader cultural appeal, while health risk segments command higher margins through physician-interpreted reports and recurring wellness subscriptions. Distribution through online retail channels captures the majority of transactions, though pharmacy placement is gaining structural importance for health-focused test categories seeking clinical credibility.
FDA, HIPAA, and state-level laboratory licensing frameworks collectively shape product claims, data handling protocols, and market access requirements for U.S.-based operators. The EU AI Act and GDPR impose additional algorithmic transparency and biometric data restrictions on services reaching European consumers. Stakeholders must monitor evolving regulatory boundaries between wellness information and medical device classification to anticipate compliance costs and product redesign cycles.
Market Dynamics
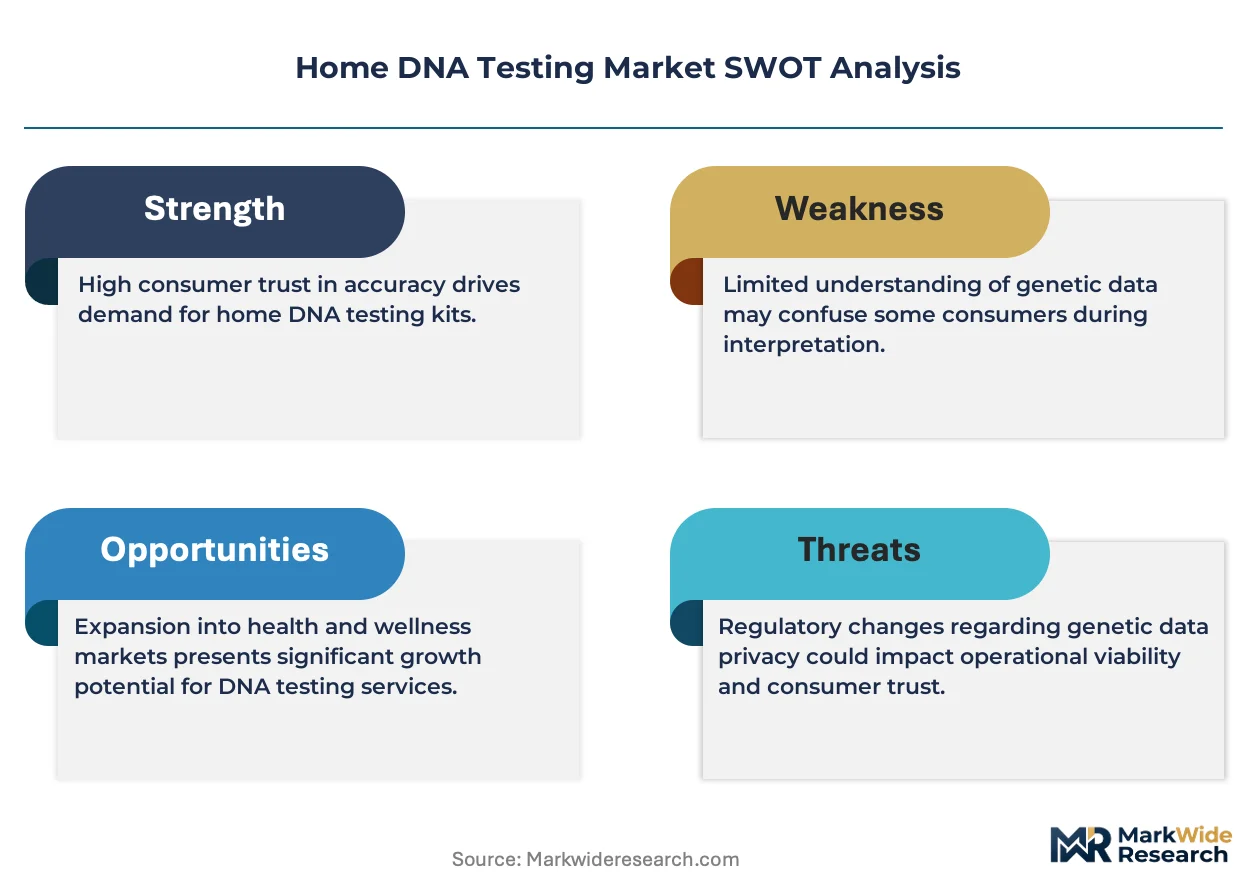
Regulatory reclassification pressure from the FDA is compressing product development cycles as wellness-to-medical device boundaries harden, forcing operators to pre-validate clinical claims before market entry.
Growth Catalysts
- Direct-to-consumer channel expansion:E-commerce infrastructure in the United States enables rapid test kit distribution without clinical intermediation, lowering customer acquisition costs.
- HIPAA-compliant data frameworks:Standardized privacy protocols reduce consumer hesitation around genetic information storage and third-party sharing.
- Polygenic risk score advancement:Algorithmic refinement is expanding health report granularity beyond single-gene variants into multi-factorial condition prediction.
Market Restraints
- Silica membrane supply concentration:Nucleic acid purification consumables depend on a limited supplier base in East Asian manufacturing clusters.
- Clinical validity thresholds:FDA 510(k) clearance requirements for health-risk claims create multi-year validation timelines that freeze product pipelines.
- Saliva substitute emergence:Microbiome and epigenetic testing from blood spot cards offers comparable ancestry resolution with perceived clinical credibility.
Strategic Opportunities
- Pharmacy retail placement:CVS and Walgreens shelf space grants health-focused SKUs immediate clinical adjacency and insurance reimbursement discussions.
- EU AI Act algorithmic transparency:Early compliance with European automated decision-making disclosures creates first-mover positioning for ancestry-ethnicity reconstruction tools.
- Pharmacogenomics integration:Warfarin and clopidogrel metabolism testing bridges consumer wellness into prescriber workflow adoption.
Industry Challenges
- Bioinformatics talent scarcity:Computational genomics and variant interpretation expertise concentrates in academic medical centers, constraining commercial pipeline scaling.
- CAP/CLIA dual accreditation:Laboratory certification timelines extend 18-24 months for multi-site testing networks seeking interstate operational flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home DNA Testing Market |
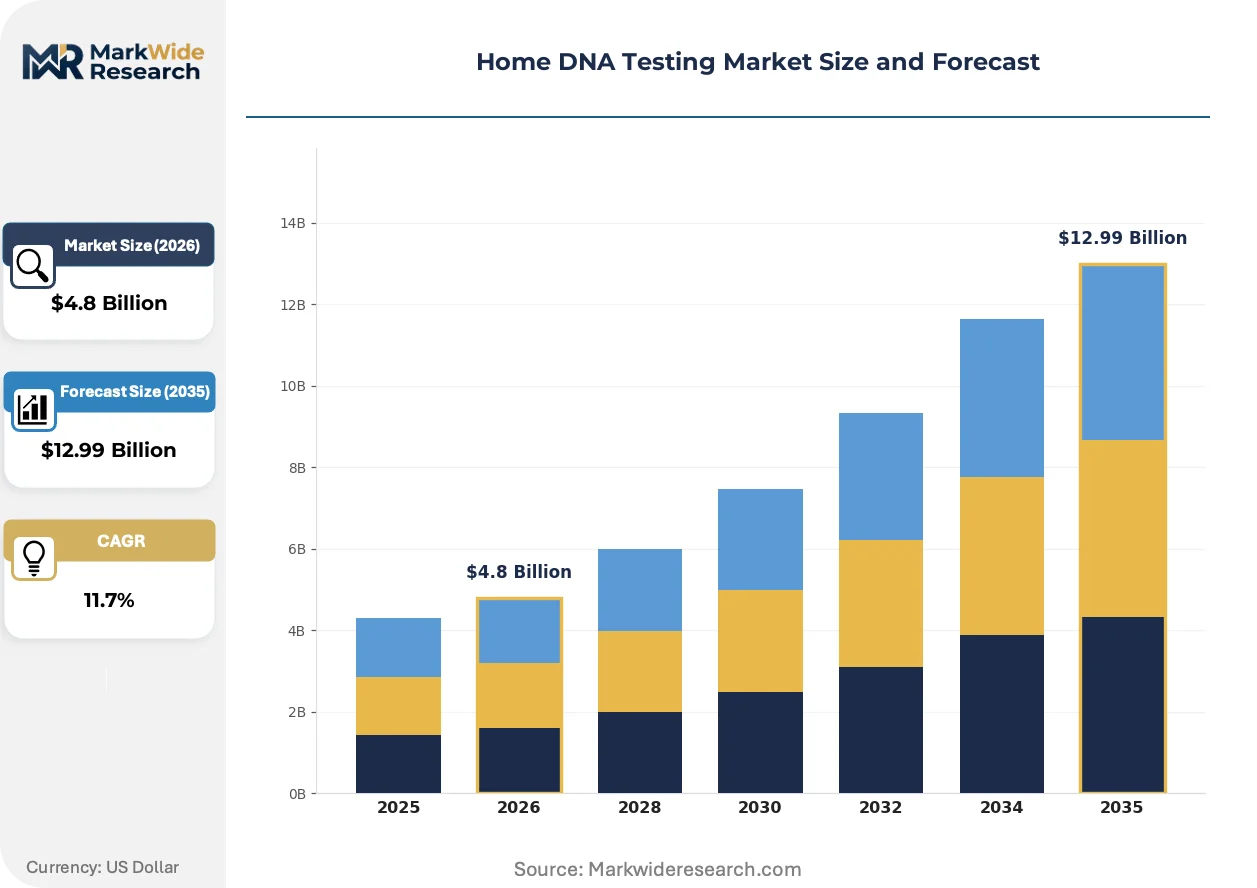
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ancestry, Health Risk, Fitness, Paternity Test Purpose: Genetic Predisposition, Relationship Testing, Nutritional Insights, Ethnicity Estimate Customer Type: Individuals, Families, Researchers, Institutions Distribution Channel: Online Retail, Pharmacies, Genetic Counseling Centers, Direct Sales |
| Companies Covered | 23andMe, Ancestry, MyHeritage, Family Tree DNA, LabCorp, Quest Diagnostics, DNA Diagnostics Center, EasyDNA, Living DNA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home DNA Testing Market Shifts & Advancements
Whole-genome sequencing cost curves and AI-driven variant interpretation are collapsing the price-performance gap between consumer ancestry arrays and clinical-grade diagnostics.
Polygenic risk scoring is absorbing SNP array data into multi-trait predictive models that quantify cumulative genetic liability for cardiovascular and metabolic conditions. Health systems in the United Kingdom are piloting these scores for population stratification. The technology is absorbing wellness-segment consumers into preventive care pathways previously gated by specialist referral.
The EU AI Act's biometric data classification is forcing ancestry platforms to disclose training dataset composition and ethnicity prediction confidence intervals. German and French regulators are interpreting these provisions most strictly. Health-risk report modules face mandatory human oversight requirements that delay automated report generation.
Subscription-based wellness monitoring is displacing one-time ancestry kit purchases as the dominant revenue model. Consumers in California and New York renew for trait updates and carrier screening expansions. Pharmacy chains capture this shift through membership program bundling that locks in recurring sample collection.
Home DNA Testing Market Segmentation
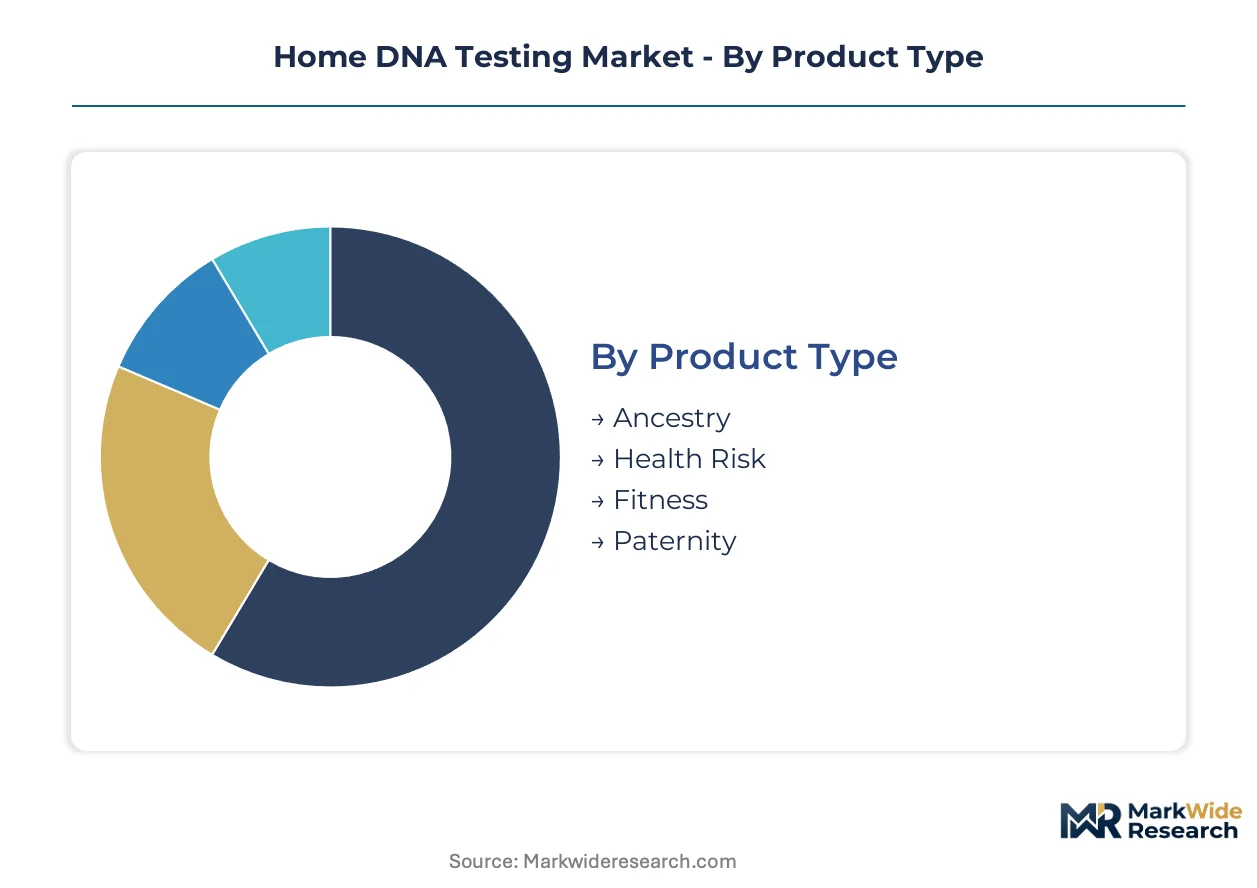
Segmentation in the Home DNA Testing Market determines which regulatory pathways apply and where margin structures diverge. Product type dictates FDA classification intensity, while distribution channel shapes reimbursement eligibility and consumer trust thresholds.
Product Type:
FDA oversight intensity varies sharply across this category, with health-risk claims triggering 510(k) medical device pathways while ancestry products navigate wellness exemptions.
- Ancestry:SNP array analysis reconstructs ethnic origins and genealogical connections from saliva samples. Mass-market penetration concentrates in the United States, driven by consumer curiosity and extensive database network effects that improve match accuracy.
- Health Risk:Polygenic risk scoring and carrier screening for conditions like BRCA variants and APOE Alzheimer's markers. Demand clusters among California and New York consumers seeking preventive health insights, constrained by multi-year FDA validation timelines that freeze new condition additions.
- Fitness:Muscle fiber composition and VO2 max potential assessments from ACTN3 and ACE gene variants. Athletes and biohackers in metropolitan fitness ecosystems drive niche adoption.
- Paternity:STR marker comparison for biological relationship confirmation. Legal-admissible variants require chain-of-custody protocols that elevate pricing above consumer-grade alternatives.
Leading the category by volume: Ancestry. Growing fastest: Health Risk.
Test Purpose:
Cost tier stratification separates one-time curiosity purchases from recurring subscription models across this dimension.
- Genetic Predisposition:Multi-condition risk profiling for cardiovascular, cancer, and neurodegenerative diseases using polygenic algorithms. Health systems in the United Kingdom pilot population stratification applications.
- Relationship Testing:Sibling, avuncular, and grandparent probability calculations for genealogical verification. Genealogy enthusiasts and adoptees seeking biological relatives anchor demand.
- Nutritional Insights:Vitamin metabolism and dietary sensitivity genotyping. Wellness subscribers in California renew for personalized supplement recommendations.
- Ethnicity Estimate:Reference panel matching for continental and sub-regional ancestry percentages. International expansion into Latin America and South Asia depends on expanding population-specific training datasets.
Genetic Predisposition commands premium pricing. Ethnicity Estimate shows steepest expansion trajectory in emerging markets.
Customer Type:
Application maturity divides established consumer segments from emerging institutional procurement patterns.
- Individuals:Direct-to-consumer purchasers seeking personal ancestry or health insights. E-commerce checkout flows and social media advertising efficiency concentrate acquisition spend.
- Families:Multi-kit bundles for household genetic comparison and inheritance pattern tracking. Holiday gifting seasons drive volume spikes in United States retail.
- Researchers:Academic scientists accessing de-identified aggregate datasets for population genetics studies. Data licensing agreements generate recurring revenue for platform operators with sufficient cohort scale.
- Institutions:Corporate wellness programs and insurance pilot studies. HIPAA-compliant infrastructure requirements limit vendor eligibility to CAP/CLIA dual-accredited laboratories.
Individuals dominate transaction count. Researchers deliver highest lifetime value through data licensing.
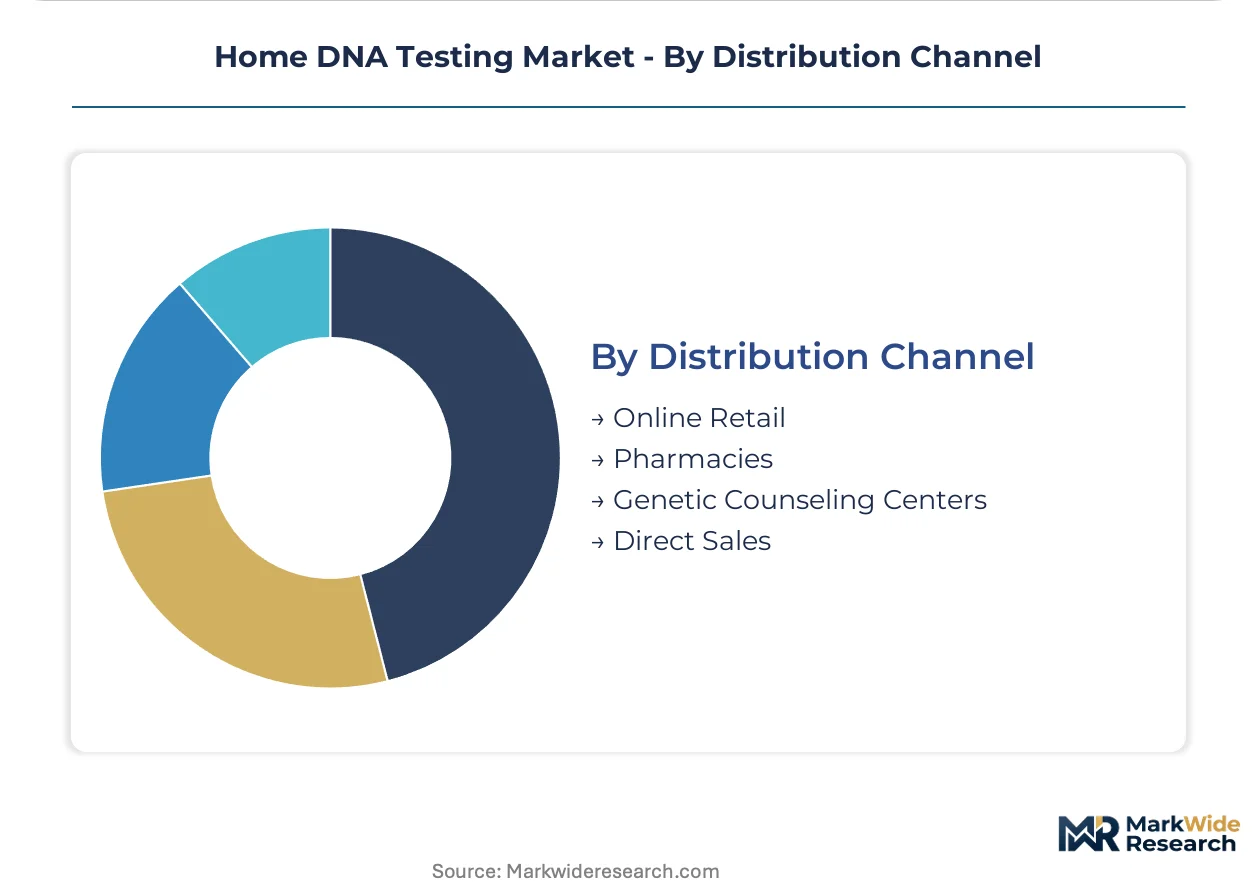
Distribution Channel:
Supply concentration in digital infrastructure shapes fulfillment economics and customer acquisition cost structures.
- Online Retail:Amazon and direct-to-consumer brand sites capture majority transaction volume. United States e-commerce logistics networks enable two-day delivery without clinical intermediation.
- Pharmacies:CVS and Walgreens shelf placement grants health-focused SKUs immediate clinical adjacency. Pharmacist recommendation influence drives conversion for pharmacogenomics products.
- Genetic Counseling Centers:Pre-test consultation and post-test interpretation services. Prevalent in hereditary cancer risk testing where clinical utility requires professional guidance.
- Direct Sales:Employer wellness program enrollment and insurance-sponsored preventive care initiatives. Human resources benefit administrators function as gatekeepers for population-scale deployment.
Online Retail leads by transaction volume. Pharmacies gaining share fastest as health-risk SKUs seek reimbursement credibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of DNA testing consumables clusters in East Asian manufacturing hubs, while consumption concentrates in Western markets with established e-commerce infrastructure and regulatory frameworks for direct-to-consumer genetic services.
United States
FDA oversight of health-risk claims and HIPAA-compliant data frameworks shape product development trajectories for operators serving American consumers. California and New York metro areas generate disproportionate demand for health-focused genetic predisposition testing. The San Francisco Bay Area anchors bioinformatics talent concentration, while Boston's research corridor supports pharmacogenomics integration with clinical workflows.
Germany
BfArM and the EU AI Act impose strict algorithmic transparency requirements on ancestry-ethnicity reconstruction tools reaching German consumers. Munich and Berlin host emerging genetic counseling centers that bridge wellness testing into clinical interpretation services. The country's laboratory accreditation standards create entry barriers for non-EU operators seeking market access.
United Kingdom
NHS pilot programs for polygenic risk score deployment in cardiovascular prevention are absorbing wellness-segment consumers into preventive care pathways. London concentrates headquarters for ancestry platforms targeting Commonwealth genealogical databases. The Medicines and Healthcare products Regulatory Agency monitors boundary conditions between wellness information and medical device classification.
China
NMPA regulatory pathways for genetic testing services remain distinct from wellness product categories, constraining direct-to-consumer health-risk offerings. Shenzhen and Shanghai manufacturing clusters supply silica membrane purification consumables to global testing kit assemblers. Domestic operators focus on relationship testing and nutritional genotyping within narrower regulatory windows.
Australia
TGA oversight of in vitro diagnostic medical devices determines which health-risk modules reach Australian consumers through e-commerce channels. Sydney and Melbourne anchor demand for ancestry testing among immigrant populations seeking ethnic origin reconstruction. The country's biobank infrastructure supports research licensing agreements with international platform operators.
Home DNA Testing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions in the Home DNA Testing Market. Laboratory services conglomerates leverage CAP/CLIA accreditation infrastructure to cross-sell into health-risk segments, while ancestry-focused operators compete on database scale and algorithmic ethnicity reconstruction accuracy. Three archetypes dominate: integrated laboratory-services hybrids, direct-to-consumer ancestry platforms, and pharmacogenomics specialists bridging into prescriber workflows. Competitive moves concentrate on pharmacy retail placement negotiations and subscription-based wellness monitoring transitions.
Among direct-to-consumer ancestry specialists, 23andMe and Ancestry occupy positions exemplifying divergent strategic vectors toward health-risk expansion and genealogical database depth respectively. MyHeritage represents the international reach archetype with specialized ethnicity reconstruction tools targeting European and emerging market consumers. These three operators anchor the competitive structure through which regulatory compliance costs and consumer acquisition economics are collectively negotiated.
| Leading Market Players |
|---|
| 23andMe |
| Ancestry |
| MyHeritage |
| Family Tree DNA |
| LabCorp |
| Quest Diagnostics |
| DNA Diagnostics Center |
| EasyDNA |
| Living DNA |
| Others |
Supply & Pricing Matrix
Bioinformatics talent scarcity in the San Francisco Bay Area and Boston research corridor widens pricing-tier spreads, as CAP/CLIA dual-accredited laboratories command premium positioning while non-certified operators compete on cost. Labor-cost differentials between clinical-grade and consumer-grade testing facilities propagate three-tier pricing stratification across ancestry, health-risk, and pharmacogenomics segments.
Pricing Analysis
Margin tightening in health-risk tiers reflects FDA 510(k) validation timelines that freeze product pipelines and elevate compliance costs. Three-tier pricing structure across premium, standard, and economy levels separates pharmacogenomics with prescriber workflow integration from direct-to-consumer ancestry kits and basic relationship testing. Price differentiation traces to certification grade—CAP/CLIA dual accreditation versus wellness exemptions—and volume scale from database network effects. Cost compression in ancestry segments accelerates because saliva substitute technologies from blood spot cards erode perceived value. Corporate wellness buyers show lowest price sensitivity; individual gift purchasers in holiday windows exhibit highest.
Supply Chain Analysis
Direct-to-consumer brand sites and Amazon marketplace channels handle individual kit demand, while pharmacy retail placement routes health-focused SKUs through CVS and Walgreens distribution networks. Manufacturing concentrates in China for silica membrane purification consumables, the United States for SNP array production, and Germany for precision laboratory instrumentation. Raw material dependencies span nucleic acid purification reagents, plastic consumables for sample collection, and semiconductor components for array scanners. Single-source vulnerability in East Asian silica membrane suppliers exposes kit assemblers to logistics chokepoints. Distribution runs through e-commerce logistics networks for two-day delivery without clinical intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where laboratory certification infrastructure and bioinformatics talent acquisition represent the decisive upstream levers. Players securing CAP/CLIA dual accreditation and computational genomics expertise gain sustainable positioning against wellness-to-medical device boundary hardening.
For Market Incumbents: Deploy pharmacy retail placement negotiations to secure shelf space at CVS and Walgreens, converting health-risk SKUs into insurance reimbursement discussions. Deepen backward integration into silica membrane purification consumables to offset East Asian supply concentration. Blood spot card alternatives from microbiome testing entrants threaten saliva-based kit volumes; preemptive pharmacogenomics integration with prescriber workflows defends margin position. For New Entrants and Emerging Players: EU AI Act algorithmic transparency requirements in Germany and France open a window for ancestry-ethnicity reconstruction tools with disclosed training dataset composition. White-space targets include Latin American and South Asian ethnicity estimate expansion where population-specific reference panels remain underdeveloped. Corporate wellness programs seeking HIPAA-compliant infrastructure offer the most penetrable institutional entry point. Direct sales through human resources benefit administrators provides a defensible go-to-market angle against established e-commerce dominance. For Investors and Strategic Acquirers: Re-rating potential sits with pharmacogenomics specialists bridging into prescriber workflows given FDA clearance for warfarin and clopidogrel metabolism testing. Long-term viability across the analysis window favors operators with CAP/CLIA dual accreditation and recurring subscription revenue models displacing one-time ancestry purchases. Acquisition target archetype: mid-cap laboratories with interstate operational flexibility and existing health system relationships. Signal to watch: NHS polygenic risk score pilot program expansion in the United Kingdom as indicator of preventive care pathway absorption.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy Retail Placement | CVS and Walgreens shelf space grants health-focused SKUs immediate clinical adjacency and insurance reimbursement credibility. |
| EU AI Act Compliance | Early algorithmic transparency disclosure creates first-mover positioning for ancestry-ethnicity reconstruction tools in German and French markets. |
| Pharmacogenomics Integration | Warfarin and clopidogrel metabolism testing bridges consumer wellness into prescriber workflow adoption with FDA-cleared clinical utility. |
| Subscription Model Transition | Recurring wellness monitoring displaces one-time ancestry kit purchases, locking in California and New York consumer renewals. |
| CAP/CLIA Dual Accreditation | Laboratory certification enables interstate operational flexibility and eligibility for institutional procurement requiring HIPAA-compliant infrastructure. |
Research Methodology
Document review covered FDA 510(k) filings, HIPAA compliance frameworks, EU AI Act regulatory texts, and CAP/CLIA accreditation databases, complemented by interviews with laboratory services executives, genetic counseling center directors, bioinformatics R&D leads, and pharmacy chain category buyers. Secondary validation drew from CMS Medicare data, hospital procurement databases, and e-commerce platform transaction analytics. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Cross-referencing historical adoption curves with expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, test purpose, customer archetype, and distribution channel complexity. CAGRs derived from algorithmic trend extrapolation weighted by regulatory pathway velocity and consumer acquisition cost trajectories. Forecast inputs incorporated polygenic risk score advancement rates and pharmacy retail placement penetration assumptions.
The model assumes a particular technology adoption path; alternative pathways for whole-genome sequencing cost collapse would alter the outlook. Forecasts reflect base-case assumptions regarding FDA wellness-to-medical device boundary stability and silica membrane supply continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
D-Dimer Testing Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Global Drug Abuse Testing Market
Testing Services
Mask Bacterial Filtration Efficiency Tester Market
Testing Services
Anderson Cascade Impactor Market
Testing Services
Chromatin Immunoprecipitation Testing Market
Testing Services
Warfarin Sensitivity Testing Market
Testing Services
Tablet Hardness Testers Market
Testing Services
Global Coagulation Testing Market
Testing Services
At-Home Testing Market
Testing Services
Global Multiplex Assays Market
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
Global Diagnostic Testing Market
Testing Services
Rapid Sterility Testing Market
Testing Services
ATP Assays Market
Testing Services
Calprotectin Testing Market