
 Europe Ablation Technologies Market | 2026-2036
Europe Ablation Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ablation Technologies Market Foresight
Hospital procurement consolidation across France and Germany is rebalancing vendor relationships toward integrated supply contracts. Medtronic plc leverages its broad electrophysiology portfolio to sustain long-term service agreements with centralized purchasing bodies. Boston Scientific Corporation anchors its European position through specialized cryoablation platforms for pulmonary vein isolation. Johnson & Johnson competes on surgical navigation integration across hybrid operating rooms.
Europe ablation technologies encompass energy-based systems that destroy pathological tissue through controlled thermal, cryogenic, or electromagnetic delivery, typically operating at frequencies between 460 and 500 kHz for radiofrequency modalities with tip temperatures monitored at 50 to 90 degrees Celsius. These systems serve primarily to treat cardiac arrhythmias, solid tumors, and gynecological conditions through minimally invasive access. Radiofrequency ablation occupies the largest installed base across European hospitals due to reimbursement familiarity and established clinical guidelines, while cryoablation represents the fastest-expanding segment in cardiology applications driven by reduced procedure complexity. Microwave ablation systems command premium positioning in oncology settings where larger ablation zones reduce repeat interventions.
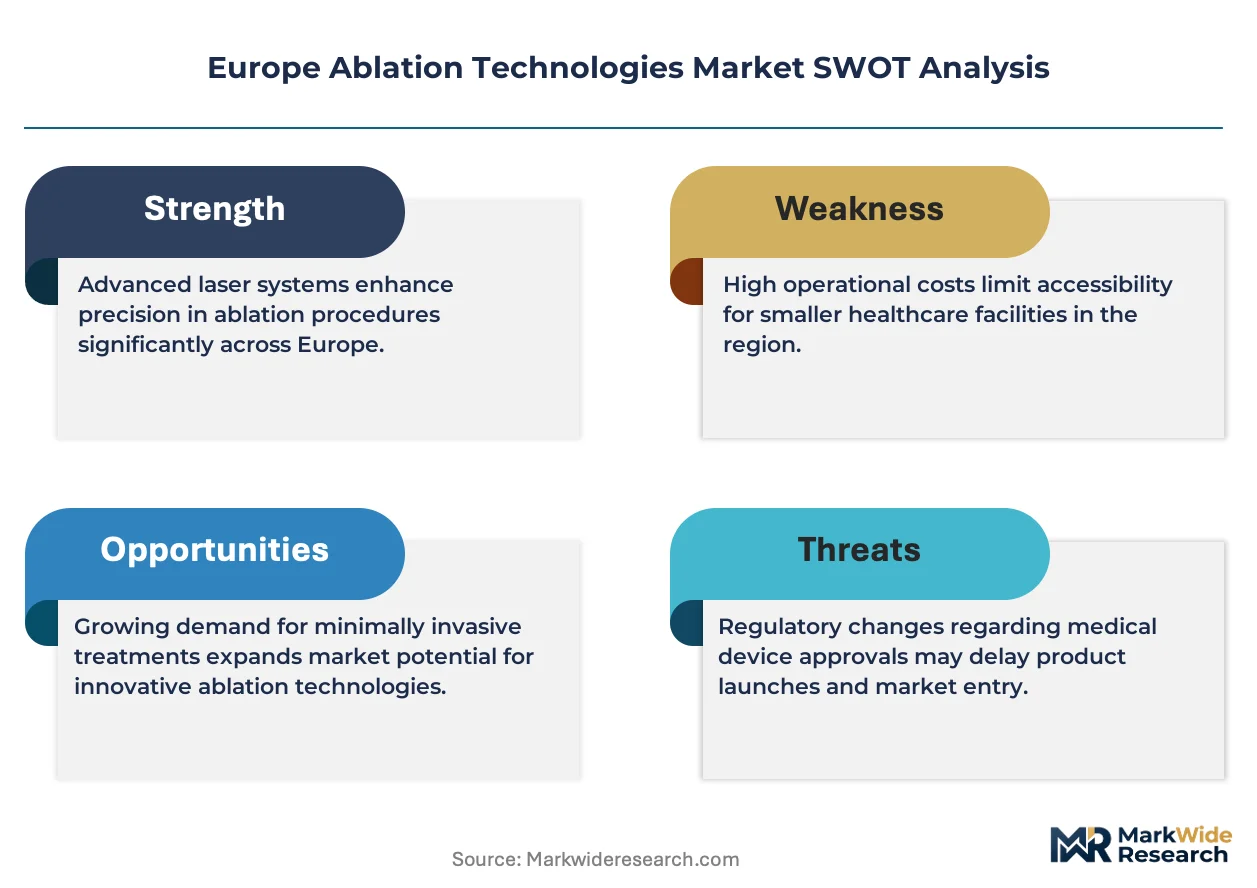
The EU Medical Device Regulation (MDR) and CE marking requirements under Notified Body oversight are extending product recertification timelines and elevating clinical data burdens for ablation catheter manufacturers. The European Medicines Agency (EMA) coordinates vigilance reporting for adverse events, while national health technology assessment bodies in Germany and France condition reimbursement on demonstrated cost-effectiveness. Stakeholders must monitor evolving MDR implementation consistency across member states to anticipate market access delays and recalibrate European launch sequencing accordingly.
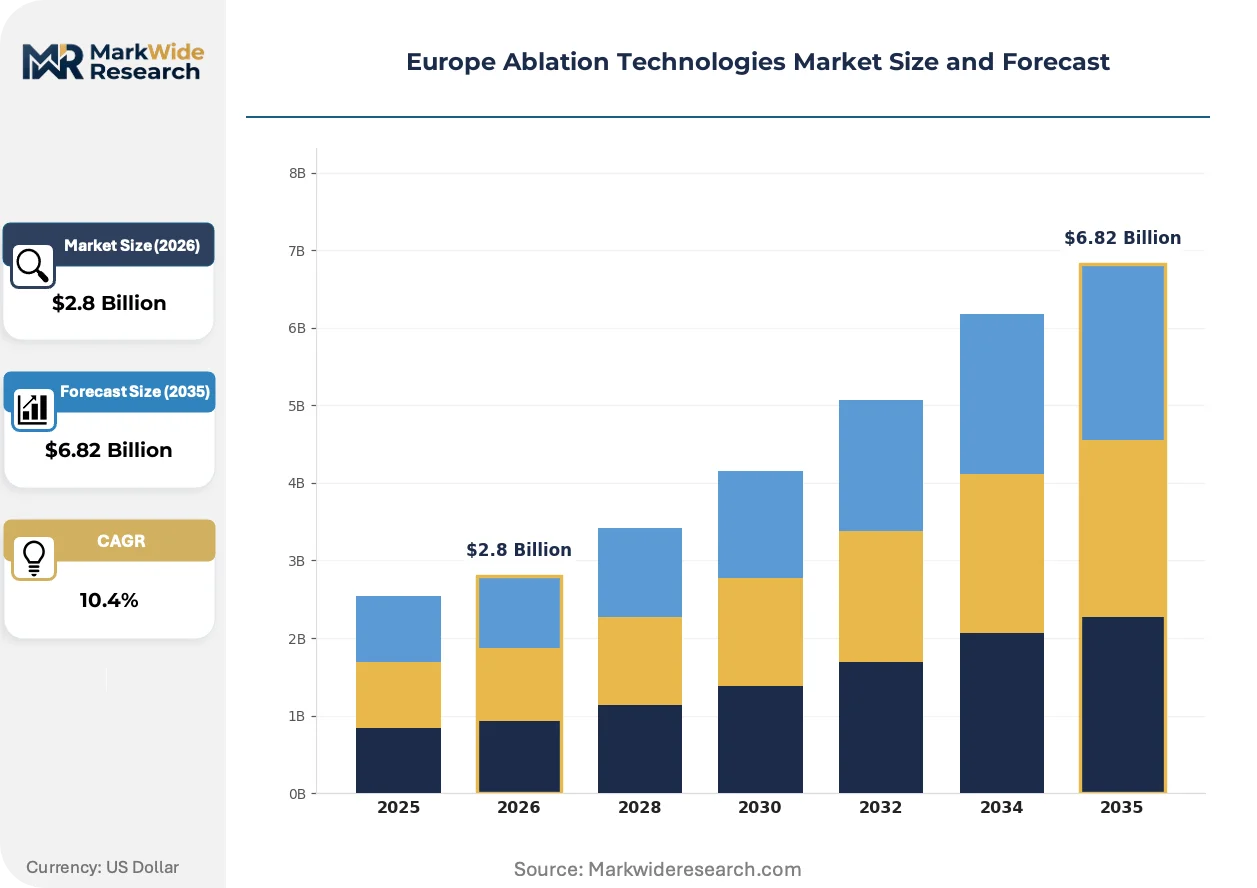
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing product lifecycles and forcing manufacturers to rebuild clinical evidence portfolios for legacy catheter systems already deployed across European electrophysiology labs.
Growth Catalysts
- CE marking under Notified Body oversight:Streamlined conformity assessment pathways for cryoablation platforms are accelerating market entry for next-generation cardiac devices in France and Germany.
- Tertiary cardiac center expansion:Hospital infrastructure investment across Western Europe is creating dedicated electrophysiology suites with integrated imaging and mapping capabilities.
- Radiofrequency catheter standardization:Established reimbursement codes for thermal ablation procedures in oncology and cardiology are reducing payer friction for repeat interventions.
Market Restraints
- MDR clinical data requirements:Extended recertification timelines for reusable ablation catheters are freezing product iterations and extending capital recovery periods.
- Notified Body capacity constraints:Bottlenecks in European conformity assessment infrastructure are delaying CE marking approvals and compressing launch windows.
- Pulsed field ablation substitution:Emerging electroporation technologies threaten to displace thermal modalities in pulmonary vein isolation procedures.
Strategic Opportunities
- Poland and Czech Republic hospital networks:Underpenetrated Eastern European markets present first-mover advantages for integrated ablation system vendors establishing training partnerships.
- Hybrid operating room convergence:Surgical navigation integration with electrophysiology mapping systems is opening procedure expansion into complex arrhythmia cases.
- EU Green Deal procurement incentives:Sustainability-linked tender criteria are favoring manufacturers with circular economy programs for catheter reprocessing.
Industry Challenges
- Electrophysiologist training pipelines:Specialist physician shortages in Italy and Spain are constraining procedure volume expansion despite installed base growth.
- Legacy system integration:Mapping software incompatibilities between generations of ablation platforms are fragmenting data workflows in multi-vendor labs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ablation Technologies Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.82 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency Ablation, Laser Ablation, Microwave Ablation, Cryoablation End User: Hospitals, Outpatient Clinics, Surgical Centers, Academic Institutions Technology: Electrophysiology, Surgical Navigation, Imaging Systems, Advanced Energy Devices Application: Cardiology, Oncology, Gynecology, Urology |
| Companies Covered | Boston Scientific Corporation, Medtronic plc, Olympus Corporation, CONMED Corporation, Johnson & Johnson, Smith & Nephew PLC, AngioDynamics, AtriCure, Inc, Elekta AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ablation Technologies Market Shifts & Advancements
Technology convergence between cardiac imaging and energy delivery systems is compressing procedure times and enabling same-day discharge protocols across European tertiary centers.
Cryoablation balloon catheters are overtaking point-source radiofrequency systems in pulmonary vein isolation procedures due to simplified lesion creation and reduced operator learning curves. German and French electrophysiology labs are adopting cryogenic platforms at accelerated replacement cycles. This modality shift is compressing training requirements and expanding treatable patient populations beyond specialized academic centers.
MDR vigilance reporting mandates are elevating post-market surveillance burdens for ablation catheter manufacturers. The European Medicines Agency coordinates adverse event databases that feed national health technology assessments. Cardiology device segments face the steepest compliance cost escalation as electrophysiology procedures generate higher incident report volumes than surgical specialties.
Hospital purchasing consortia in France and Germany are consolidating vendor relationships around multi-year service agreements. Integrated supply contracts now bundle catheter procurement with mapping system maintenance and software updates. This concentration is most visible in Rhône-Alpes and Bavaria, where regional purchasing bodies command pricing leverage exceeding single-site negotiations.
Europe Ablation Technologies Market Segmentation
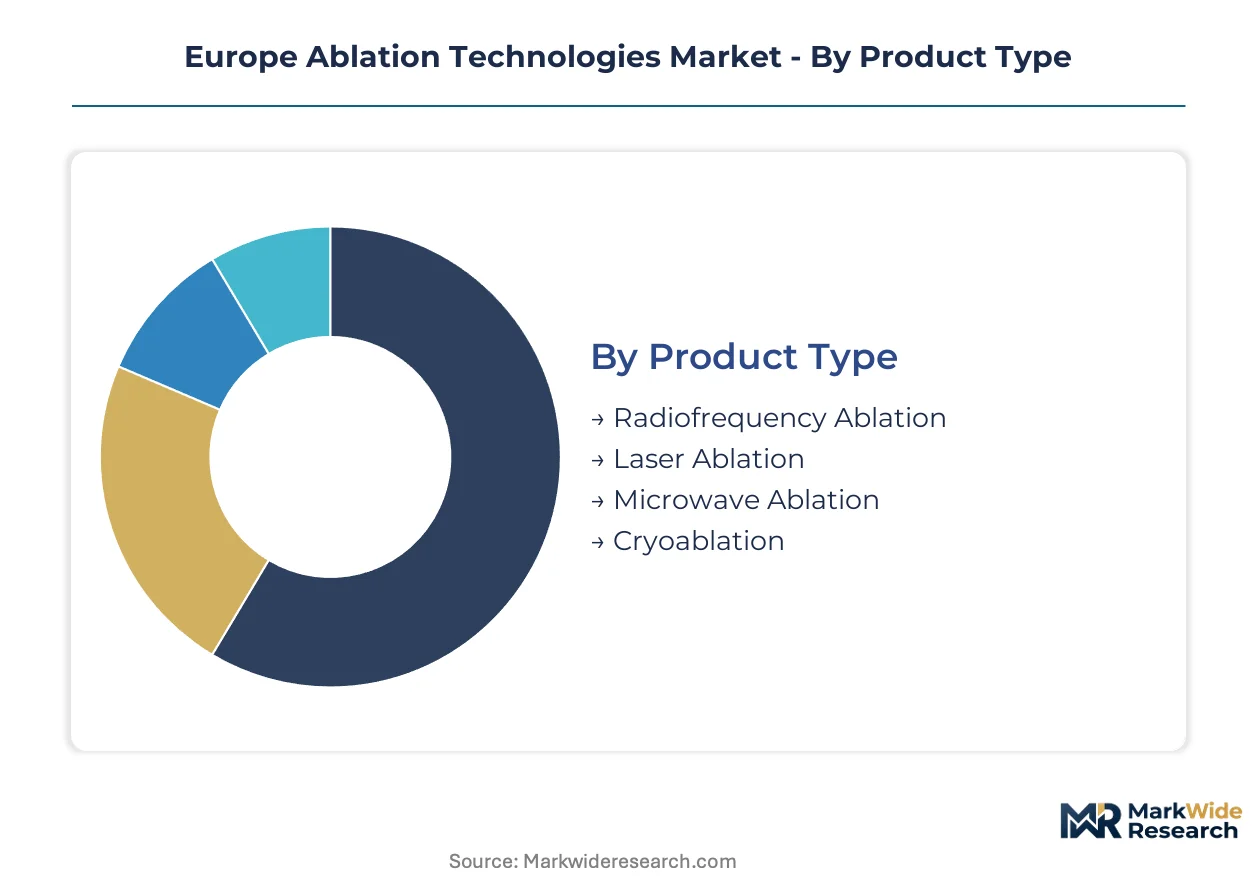
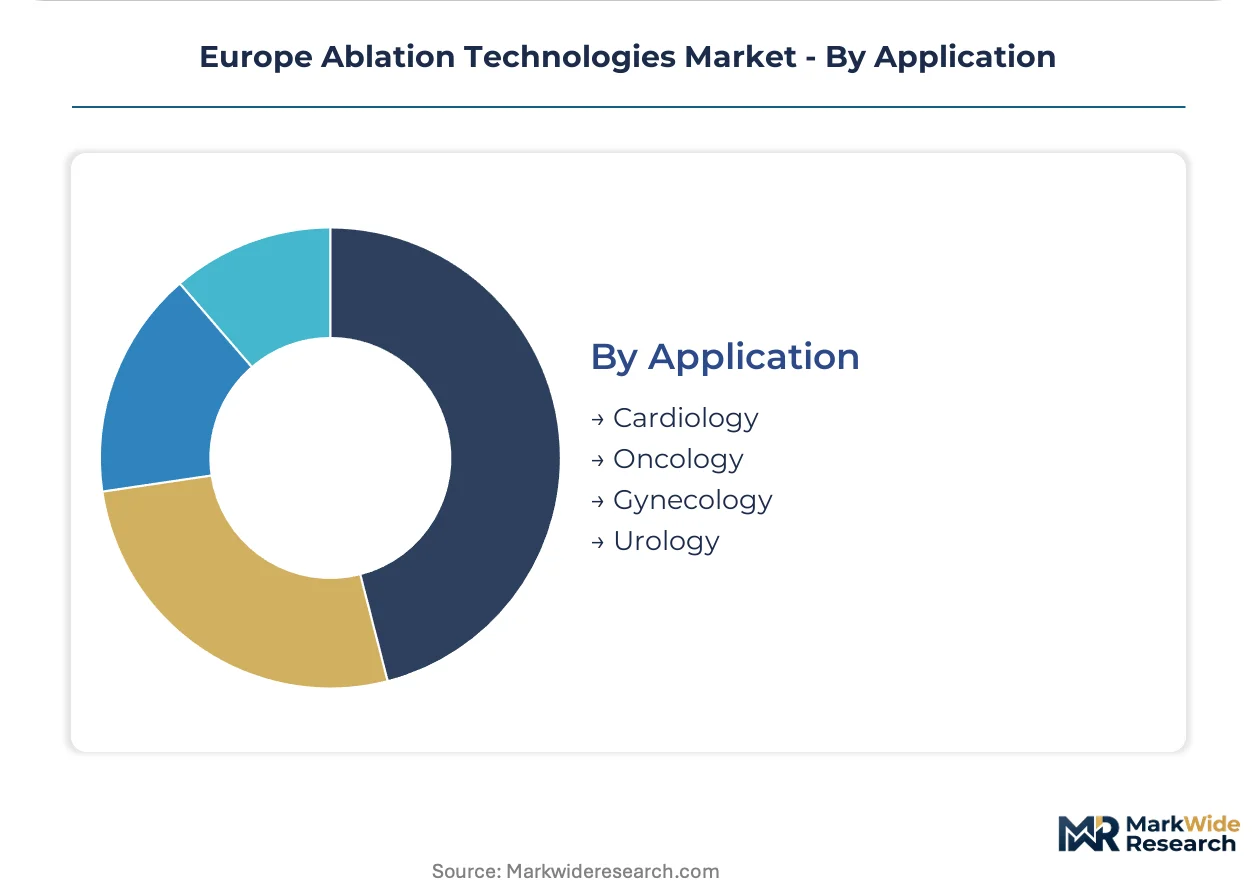
Segmentation in Europe ablation technologies reveals divergent procurement patterns across cardiac and oncology settings. Hospital purchasing consortia weight technology integration differently than outpatient operators, while regulatory pathways under MDR vary sharply by energy modality.
Product Type:
Procurement committees prioritize reimbursement familiarity and training infrastructure when selecting energy platforms.
- Radiofrequency Ablation:Thermal delivery systems operating at 460–500 kHz with tip temperatures monitored between 50°C and 90°C. German and French tertiary centers concentrate demand here due to established catheter lab workflows and deep electrophysiologist training pipelines.
- Cryoablation:Balloon-based cryogenic platforms achieving pulmonary vein isolation through controlled tissue freezing. French electrophysiology labs are expanding treatable patient populations fastest as simplified lesion creation compresses operator learning curves.
- Laser Ablation:Coherent light energy delivery for precise tissue destruction with minimal thermal spread.
- Microwave Ablation:Electromagnetic heating systems generating larger ablation zones for oncology interventions.
Volume sits with radiofrequency platforms; growth tilts toward cryoablation.
End User:
Facility infrastructure determines technology access and procedure complexity thresholds.
- Hospitals:Integrated electrophysiology suites with 3D mapping and imaging capabilities. Western European tertiary cardiac centers in Germany and France drive capital equipment procurement through centralized purchasing bodies.
- Outpatient Clinics:Limited-service facilities performing straightforward thermal ablations under local anesthesia. Italian and Spanish markets show constrained expansion due to electrophysiologist shortages.
- Surgical Centers:Specialized facilities combining laparoscopic access with energy delivery systems.
- Academic Institutions:Research-focused centers validating next-generation modalities and training protocols.
Procedure concentration favors hospital settings; outpatient penetration faces specialist bottlenecks.
Technology:
System integration requirements reshape vendor selection criteria across European purchasing frameworks.
- Electrophysiology:Cardiac mapping and energy delivery convergence enabling real-time lesion assessment. Bavarian and Rhône-Alpes hospital networks are consolidating around multi-year service agreements bundling catheter procurement with software maintenance.
- Imaging Systems:Intra-procedural visualization through fluoroscopy, ICE, or contact-force sensing. Hybrid operating room installations in Germany are climbing fastest as surgical navigation integration opens complex arrhythmia cases.
- Surgical Navigation:Spatial tracking for precise probe positioning in solid tumor interventions.
- Advanced Energy Devices:Next-generation platforms including pulsed field ablation systems.
Installed base concentrates in electrophysiology; imaging integration commands premium positioning.
Application:
Clinical indication shapes regulatory evidence requirements and reimbursement negotiation leverage.
- Cardiology:Atrial fibrillation ablation through pulmonary vein isolation and substrate modification. German hospital procurement is expanding catheter-based programs as first-line therapy, though EMA vigilance reporting elevates post-market surveillance burdens.
- Oncology:Percutaneous tumor destruction in liver, lung, and kidney malignancies. Microwave systems gain traction here where larger ablation zones reduce repeat interventions.
- Gynecology:Endometrial ablation and fibroid treatment through hysteroscopic or laparoscopic access.
- Urology:Renal mass and prostate tissue destruction via minimally invasive approaches.
Revenue weight rests with cardiology; oncology applications show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity ceramic substrates and platinum-iridium electrode alloys anchor European ablation device manufacturing, with specialized foundries concentrated in Germany's industrial heartland and Switzerland's precision engineering corridor.
Germany
Hospital procurement consolidation across Bavaria and North Rhine-Westphalia is accelerating integrated electrophysiology suite investments. The Federal Institute for Drugs and Medical Devices (BfArM) enforces MDR conformity assessments that extend recertification timelines for reusable catheters. The Munich-Stuttgart corridor hosts the densest concentration of catheter manufacturing facilities serving Western European tertiary cardiac centers.
France
Rhône-Alpes and Île-de-France hospital networks are expanding cryoablation programs as first-line atrial fibrillation therapy. The National Agency for Food, Environmental and Occupational Health Safety (ANSES) coordinates vigilance reporting with EMA databases for cardiac device adverse events. The Lyon-Grenoble cluster commands pricing leverage through regional purchasing bodies bundling catheter procurement with mapping system maintenance.
United Kingdom
NHS England's specialized commissioning frameworks are concentrating complex arrhythmia procedures into designated cardiac centers across London and the Midlands. The Medicines and Healthcare products Regulatory Agency (MHRA) operates parallel MDR implementation pathways post-Brexit, creating dual conformity assessment requirements for manufacturers. The Cambridge-Oxford corridor attracts next-generation ablation technology R&D investments from US and European vendors.
Italy
Lombardy and Emilia-Romagna electrophysiology labs face procedure volume constraints despite installed base expansion due to specialist physician shortages. The Italian Medicines Agency (AIFA) conditions reimbursement on demonstrated cost-effectiveness through regional health technology assessments. The Milan-Bologna axis maintains strong cardiac surgery traditions that slow catheter-based ablation substitution in hybrid operating rooms.
Poland
Warsaw and Kraków hospital networks present first-mover opportunities for integrated ablation system vendors establishing training partnerships in underpenetrated Eastern European markets. The Office for Registration of Medicinal Products, Medical Devices and Biocidal Products (URPL) processes CE marking applications through Notified Body referrals. The Silesian metropolitan area is emerging as a distribution hub for cardiac devices serving Central European expansion strategies.
Europe Ablation Technologies Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pulsed field ablation and electroporation modalities outside thermal energy paradigms. The vendor landscape concentrates around diversified medical technology conglomerates with electrophysiology portfolios and specialized cardiac surgery device manufacturers. Three archetypes dominate: integrated platform vendors bundling mapping systems with catheter supply, pure-play energy delivery specialists, and surgical navigation integrators targeting hybrid operating room convergence. Competitive moves center on multi-year service agreements with hospital purchasing consortia and MDR compliance infrastructure investments extending product lifecycles.
Among US-based diversified medical technology groups, Boston Scientific Corporation and Medtronic plc exemplify integrated platform strategies anchoring European market presence through broad electrophysiology portfolios. Johnson & Johnson occupies a position within surgical navigation integration, targeting hybrid operating room configurations. These three entities represent distinct competitive vectors: catheter-based cardiac ablation expansion, cryogenic platform specialization, and surgical-electrophysiology convergence.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic plc |
| Olympus Corporation |
| CONMED Corporation |
| Johnson & Johnson |
| Smith & Nephew PLC |
| AngioDynamics |
| AtriCure, Inc |
| Elekta AB |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up catheter specialists anchor European supply networks, compressing procurement cycles while enforcing disciplined pricing tiers across German and French hospital purchasing consortia. Their consolidated ownership structures synchronize inventory pooling with multi-year service agreements, translating supply concentration into premium capture for integrated electrophysiology platforms.
Pricing Analysis
Volume concentrates in standard-tier radiofrequency catheters while margins concentrate in cryoablation balloon systems and advanced energy devices. Pricing stratifies across premium, standard, and economy tiers based on CE marking tier under MDR and bundled mapping software integration. Cost compression in standard thermal catheters is intensifying because Notified Body recertification delays extend capital recovery periods. Outpatient clinics in Italy and Spain exhibit highest price sensitivity due to constrained reimbursement, while German tertiary centers prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
CE marking and MDR vigilance reporting requirements gate supplier qualification, extending onboarding timelines for component vendors serving European electrophysiology manufacturers. Manufacturing concentrates in Germany, Switzerland, and Ireland, drawing from high-purity ceramic substrate and platinum-iridium electrode supply chains. Single-source vulnerability persists for specialized cryogenic balloon materials sourced from Swiss precision engineering corridors. Distribution runs through regional hospital purchasing bodies in Bavaria and Rhône-Alpes bundling catheter procurement with mapping system maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European ablation technologies constitute a consolidation play where MDR compliance costs and extended recertification timelines force subscale manufacturers toward strategic exits or acquisition.
For Market Incumbents: Cement service agreement dominance by embedding mapping software subscriptions into multi-year catheter supply contracts with Rhône-Alpes and Bavarian purchasing consortia. Deepen backward integration into high-purity ceramic substrate production to insulate margin structures from raw material volatility. Pulsed field ablation substitution threats demand accelerated R&D investment in electroporation platforms before thermal modality displacement accelerates. For New Entrants and Emerging Players: Enter via training partnership models in Warsaw and Kraków hospital networks, where electrophysiology lab expansion outpaces specialist physician supply. Poland and Czech Republic markets present lowest competitive density for cryoablation platform introduction. Target first-mover positioning through distributor relationships with Silesian distribution hubs serving Central European expansion strategies. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap catheter manufacturers with dormant CE marking portfolios in Germany facing Notified Body capacity constraints. Long-term viability hinges on MDR compliance infrastructure and installed base migration capability. Watch EMA vigilance reporting volume trends as inflection indicator for cardiac device segment consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR recertification acceleration unlocks launch windows before pulsed field ablation matures. |
| Hospital System Partnership | Multi-year service agreements with Bavarian purchasing bodies bundle catheter supply with software maintenance. |
| Backward Integration | In-house ceramic substrate production reduces dependency on Swiss precision engineering corridors. |
| Software Companion Development | Mapping system integration commands premium positioning in German hybrid operating room installations. |
| Reimbursement Strategy | Cost-effectiveness demonstration through German IQWiG assessments conditions national coverage expansion. |
Research Methodology
EMA vigilance databases, BfArM medical device registrations, and hospital procurement records formed the secondary backbone, cross-referenced with primary interviews involving electrophysiologists, biomedical engineers, GPO contracts managers, and catheter manufacturing executives. Bottom-up unit economics triangulated against top-down spending flows from national health technology assessment bodies validated market sizing across energy modalities and application segments.
Historical trendline analysis of catheter lab installation rates and procedure volume trajectories informed projection frameworks across the modeling period. Segmentation dimensions modeled include energy modality, facility infrastructure tier, and regulatory approval pathway complexity. CAGRs derived from fitted growth curves incorporating MDR implementation pace and cryoablation substitution elasticity.
Revisions become necessary when Notified Body capacity constraints intensify, EMA vigilance reporting thresholds shift, or pulsed field ablation clinical trial readouts accelerate thermal modality displacement timelines. A model refresh is warranted upon material change in MDR implementation consistency across member states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Implantable Drug Eluting Devices Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Global Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Syndesmosis Repair System Market
Medical Devices
Global Gynecology Devices Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
Medical Manifolds Market
Medical Devices
Global Electroceuticals Market
Medical Devices
Germany Respiratory Devices Market
Medical Devices
Bone Conduction Hearing Aids Market
Medical Devices
Global Dermatoscope Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
North America and Europe Group 2 Powered Mobility Devices Market
Medical Devices
Radiotherapy Patient Positioning Accessories Market