
 Pharmaceutical Filtration Devices Market | 2026-2036
Pharmaceutical Filtration Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Filtration Devices Market Outlook
Single-source membrane supply is shifting toward dual-qualified vendor strategies across biopharma filtration procurement. Danaher Corporation leverages its Pall life sciences platform to anchor North American sterile filtration demand. Sartorius AG specializes in single-use filtration assemblies for cell-culture applications. Thermo Fisher Scientific competes through integrated analytical and filtration workflow bundles.
Pharmaceutical filtration devices employ polymeric membranes with defined pore-size distributions, typically rated at 0.1 to 0.22 microns for sterilizing-grade applications, to remove particulates, bacteria, and endotoxins from drug substances and parenteral solutions. Membrane filters command premium positioning due to their critical role in final sterile filtration, while depth filters sustain volume demand in upstream clarification steps where particle-loading capacity determines operational economics. Ultrafiltration technology leads in protein concentration and diafiltration workflows, whereas nanofiltration occupies specialized viral clearance and endotoxin removal applications with higher margin profiles.
FDA sterilization validation requirements under 21 CFR Part 211 and EMA's Good Manufacturing Practice Annex 1 revisions mandate documented filter integrity testing and single-use system validation, directly shaping equipment specification and vendor qualification cycles. The EPA monitors wastewater discharge from pharmaceutical manufacturing, influencing filtration selection for process-effluent treatment. ISO 13485 quality management standards govern device design controls, creating compliance barriers for new entrants. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on continuous manufacturing guidelines, as real-time release testing will redefine filtration performance validation protocols.
Market Dynamics
Single-use filtration systems are compressing validation timelines and displacing reusable stainless-steel infrastructure across biopharmaceutical manufacturing, restructuring capital allocation and vendor relationships throughout the supply chain.
Growth Catalysts
- EMA Annex 1 Revisions:The updated sterile manufacturing guidelines mandate continuous viable monitoring and enhanced barrier technology, compelling filtration system upgrades across European parenteral drug facilities.
- mRNA Platform Expansion:Lipid nanoparticle manufacturing for nucleic acid therapeutics requires specialized sterile filtration at multiple process stages, creating dedicated membrane demand from CDMOs and integrated biopharma producers.
- India PLI Scheme:The Production Linked Incentive program for active pharmaceutical ingredients and medical devices is attracting filtration equipment investment into domestic manufacturing clusters around Hyderabad and Ahmedabad.
Market Restraints
- PVDF Membrane Supply Concentration:Polyvinylidene fluoride resin production clusters in Northeast Asia, exposing filter manufacturers to feedstock disruption and freight cost volatility.
- Integrity Test Validation Burden:FDA 21 CFR Part 211 requirements for bubble point and diffusion testing documentation extend qualification cycles, delaying facility startup and revenue recognition.
- Depth Filter Saturation:Mature cellulose and diatomaceous earth media face substitution pressure from charged nanofiber layers in clarification applications, constraining pricing power in upstream processing.
Strategic Opportunities
- Continuous Manufacturing Integration:FDA and EMA convergence on real-time release testing frameworks creates specification demand for in-line filtration sensors and automated integrity verification systems.
- Cell and Gene Therapy:Viral vector production for CAR-T and gene editing therapies requires specialized nanofiltration for adventitious agent clearance, opening premium product categories with limited incumbent presence.
- Digital Twin Deployment:Process analytical technology integration enables predictive filter replacement scheduling, creating software-enabled service revenue streams alongside hardware sales.
Industry Challenges
- Filter Extractables Qualification:Compendial testing under USP 1664 and ISO 10993-18 demands toxicological assessment of polymeric leachables, extending product development timelines and requiring specialized analytical chemistry capabilities.
- Legacy System Interoperability:Brownfield biologics facilities with established stainless-steel infrastructure face mechanical and control-system integration barriers when retrofitting single-use filtration skids.
- Single-Use Component Standardization:Proprietary connector geometries and bag dimensions across vendors create inventory complexity and limit second-source flexibility for manufacturing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Filtration Devices Market |
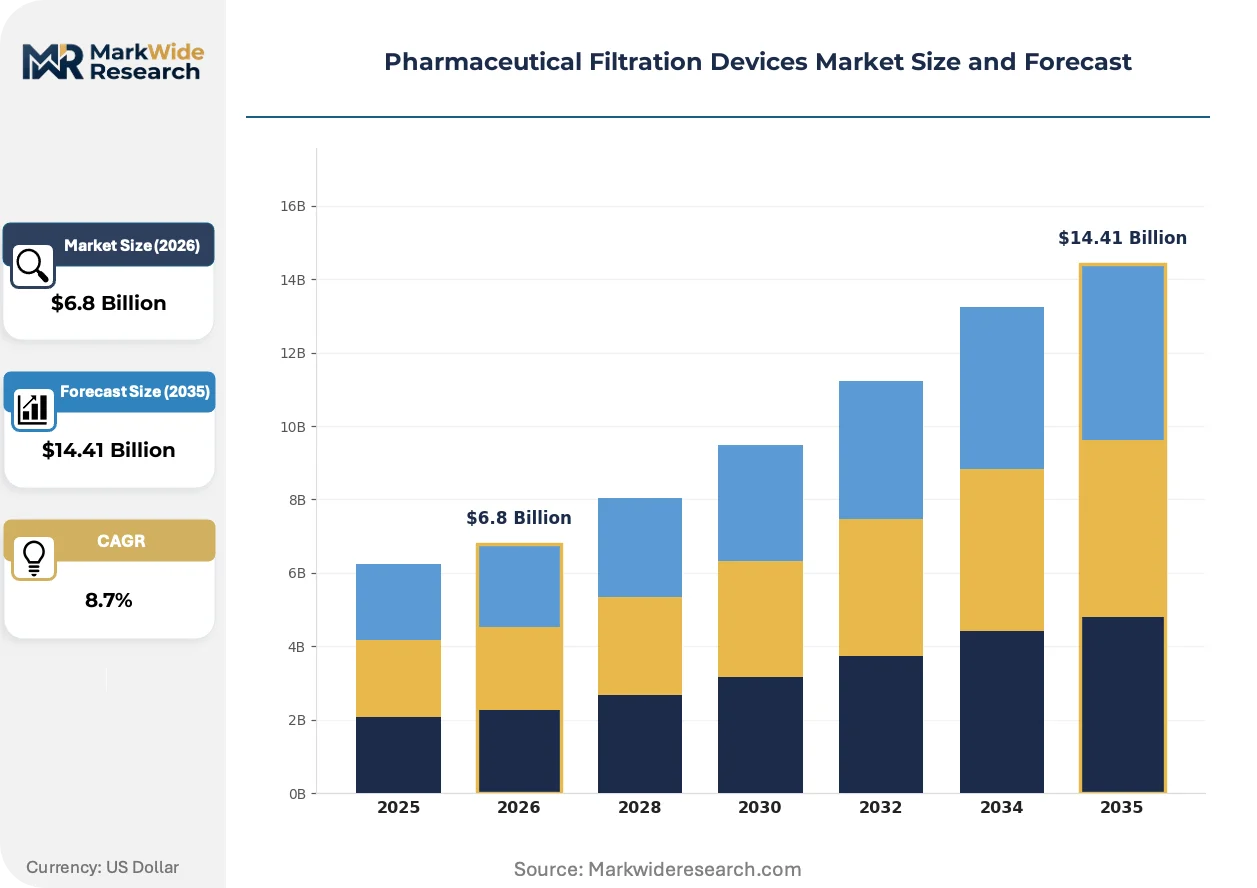
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filter Cartridges, Membrane Filters, Filter Capsules, Depth Filters Application: Biopharmaceutical Production, Sterilization, Final Filtration, Liquid Filtration End User: Pharmaceutical Manufacturers, Contract Manufacturing Organizations, Research Laboratories, Hospitals Technology: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis |
| Companies Covered | Merck KGaA, Danaher Corporation, Sartorius AG, Thermo Fisher Scientific, 3M Company, Parker Hannifin Corporation, Eaton Corporation, Meissner Filtration Products, Pall Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Filtration Devices Market Strategic Shifts
Membrane chemistry advances and process analytical integration are compressing batch release timelines while regulatory pressure on contamination control intensifies specification requirements across sterile manufacturing.
Multi-layer asymmetric membranes are unifying sterilizing-grade and pre-filtration functions into single-use capsules, reducing hold-up volume and flushing requirements. Contract development and manufacturing organizations are standardizing on these integrated formats to minimize process changeover time between campaigns. The technology is unifying what were previously separate procurement categories, consolidating vendor relationships and simplifying supply chain management for multi-product facilities.
EMA's revised Annex 1 on sterile manufacturing entered force in August 2023, mandating barrier isolation and continuous environmental monitoring for Grade A operations. The regulation compels filtration system redesigns to eliminate human intervention during sterile connection and disconnection. Aseptic processing facilities across Germany, Ireland, and Switzerland are retrofitting isolator-integrated filtration skids to achieve compliance before enforcement deadlines.
Consolidated vendor contracting is displacing point-solution procurement as biopharma manufacturers seek single-source accountability for filtration, chromatography, and fluid management. Large-cap biologics producers are negotiating enterprise agreements with preferred suppliers covering multi-site, multi-year membrane and hardware supply. This pattern is most pronounced among North American and Western European headquarters operations managing global manufacturing networks.
Pharmaceutical Filtration Devices Market Segmentation
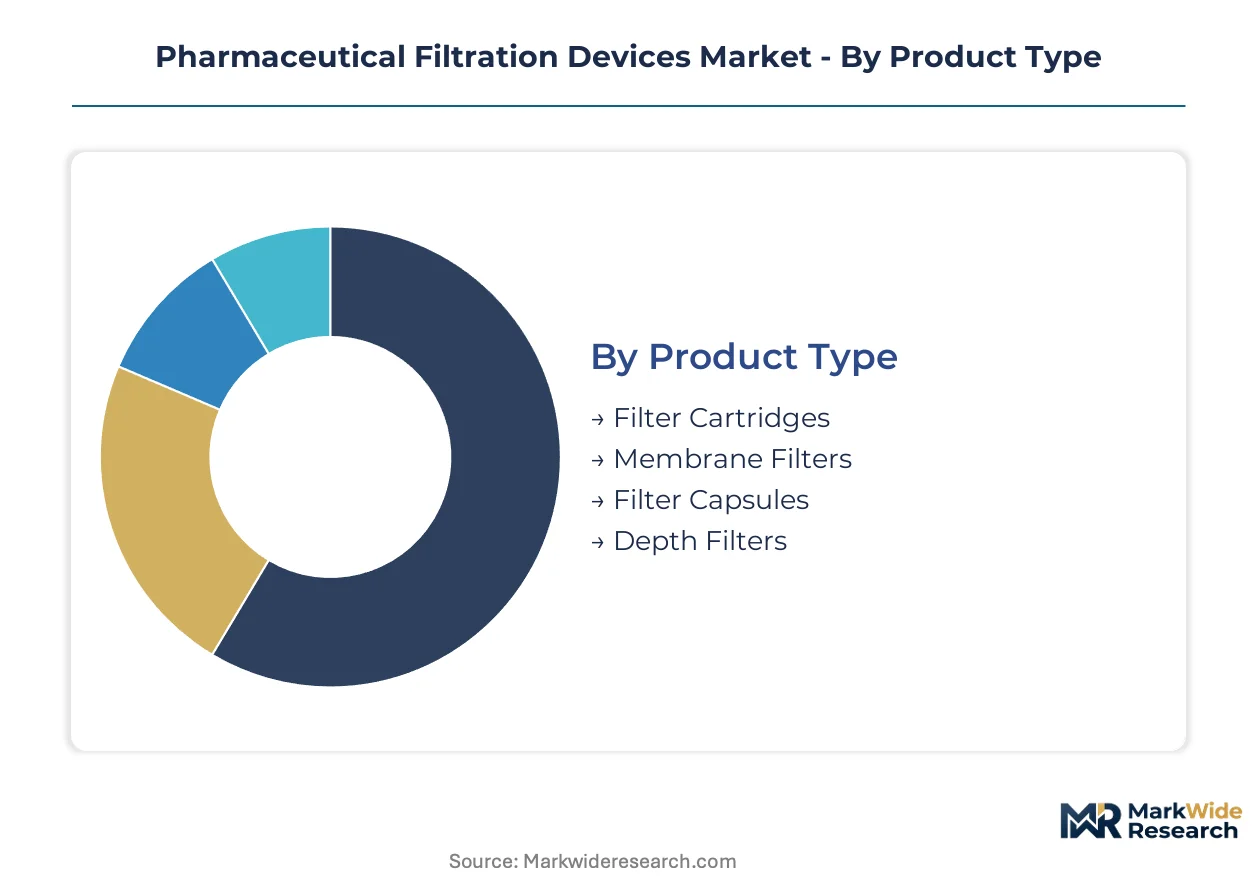
Pharmaceutical filtration devices fragment across multiple technical and commercial dimensions, each carrying distinct margin profiles and qualification barriers. Procurement patterns diverge sharply between high-volume upstream clarification and premium sterile-grade final filtration, creating tiered vendor strategies across product categories.
Product Type:
Membrane filters command premium positioning through sterilizing-grade pore precision, while depth filters sustain volume economics in particle-heavy clarification steps.
- Membrane Filters:Polymeric sheets with defined 0.1–0.22 micron pore ratings deliver bacterial and endotoxin retention for parenteral drug final filtration. Demand concentrates in fill-finish suites across Switzerland and Germany as EMA Annex 1 mandates intensify barrier isolation requirements.
- Filter Cartridges:Cylindrical pleated configurations maximize surface area for high-flow sterile processing in bioreactor harvest lines. Pharmaceutical manufacturers in Ireland and Belgium deploy these for mRNA lipid nanoparticle clarification where batch volumes scale rapidly.
- Filter Capsules:Self-contained single-use units eliminate assembly validation for multi-product CDMO facilities.
- Depth Filters:Cellulose and diatomaceous earth matrices handle high particle loads in upstream cell culture clarification.
Today's leader: Membrane Filters. Tomorrow's challenger: Filter Capsules.
Application:
Final filtration absorbs the highest specification burden, while biopharmaceutical production generates the largest absolute membrane consumption.
- Final Filtration:Terminal sterile processing of parenteral solutions demands validated bacterial retention per FDA 21 CFR Part 211. Facilities in the United States and Germany allocate disproportionate procurement budgets here due to zero-failure tolerance for injectable therapeutics.
- Biopharmaceutical Production:Cell culture harvest and purification workflows consume filtration media at scale. India's Hyderabad and Ahmedabad clusters are expanding membrane demand through PLI scheme-driven API and biologics investment.
- Sterilization:Bioburden reduction for process intermediates and equipment rinse cycles.
- Liquid Filtration:Buffer and media preparation steps upstream of sterile boundaries.
Final Filtration captures margin concentration. Biopharmaceutical Production drives volume expansion fastest.
End User:
Contract manufacturing organizations compress validation timelines through single-use standardization, while integrated pharmaceutical manufacturers retain complex multi-step filtration workflows.
- Contract Manufacturing Organizations:Multi-product facilities prioritize rapid changeover and disposable supply security. CDMOs in Switzerland and Singapore are consolidating vendor relationships to secure membrane allocation for viral vector and mRNA campaigns.
- Pharmaceutical Manufacturers:Integrated biologics producers with captive capacity run dedicated filtration trains optimized to specific molecule characteristics. Large-scale facilities in Germany and the United States negotiate enterprise supply agreements spanning multiple sites.
- Research Laboratories:Preclinical and process development groups drive small-lot membrane consumption for early-stage molecule characterization.
- Hospitals:Compounding pharmacies and centralized sterile preparation units require point-of-use filtration for patient-specific parenteral formulations.
CDMOs are pulling single-use adoption forward. Integrated manufacturers anchor long-term supply contracts.
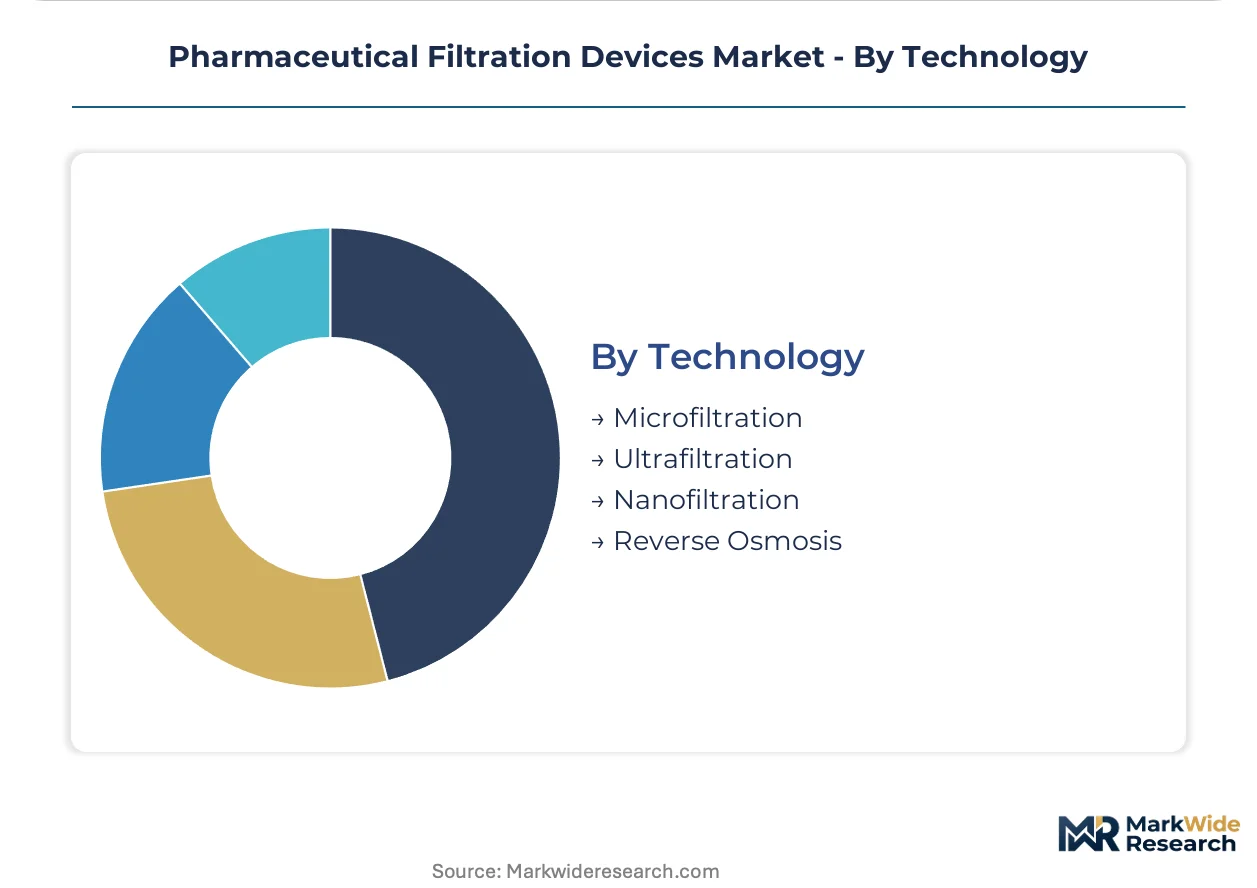
Technology:
Ultrafiltration dominates protein concentration workflows, while nanofiltration occupies specialized viral clearance niches with limited supplier competition.
- Ultrafiltration:Tangential-flow systems concentrate and diafilter therapeutic proteins using molecular weight cut-off membranes. Demand clusters in Massachusetts and California biologics corridors where monoclonal antibody titers continue climbing.
- Nanofiltration:Tight pore structures below 0.001 microns clear adventitious viruses and endotoxins from high-value drug substances. Cell and gene therapy producers in Pennsylvania and North Carolina are expanding membrane area for viral vector safety testing.
- Microfiltration:0.1–0.22 micron rated membranes handle standard bacterial retention across sterilizing-grade applications.
- Reverse Osmosis:Water-for-injection and process water purification systems rely on these membranes for ionic and organic contaminant removal.
Ultrafiltration holds installed base dominance. Nanofiltration is climbing the fastest as gene therapy manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biologics corridor anchors filtration device procurement through concentrated monoclonal antibody and cell therapy manufacturing. Switzerland and Germany sustain premium membrane demand through parenteral drug fill-finish investments. India's pharmaceutical clusters are expanding membrane consumption through government production incentives.
United States
Massachusetts and California biologics producers drive ultrafiltration membrane consumption for protein concentration workflows. FDA 21 CFR Part 211 sterilization validation requirements compel documented filter integrity testing across parenteral drug facilities. The Philadelphia-Camden viral vector manufacturing corridor is expanding nanofiltration deployment for gene therapy safety testing.
Germany
EMA Annex 1 barrier isolation mandates are accelerating isolator-integrated filtration skid retrofits across sterile processing facilities. The country's national pharmaceutical regulator enforces continuous viable monitoring standards for Grade A operations. The Rhine-Main biopharma cluster around Frankfurt is consolidating single-use filtration procurement through multi-site enterprise agreements.
Switzerland
Contract manufacturing organizations in Basel and Zurich prioritize rapid-changeover filter capsules for multi-product viral vector campaigns. Swissmedic sterile manufacturing guidelines align with EMA Annex 1 enforcement timelines. The Lake Geneva biotech corridor is retrofitting filtration infrastructure to eliminate human intervention during sterile connections.
India
The CDSCO Production Linked Incentive scheme for active pharmaceutical ingredients is attracting membrane filtration investment into domestic manufacturing. Hyderabad and Ahmedabad clusters are expanding sterile filtration capacity for export-oriented parenteral drug production. Domestic biologics producers are qualifying dual-source membrane vendors to reduce supply concentration risk.
China
NMPA tightening of biologics manufacturing standards is driving substitution of reusable stainless-steel systems with validated single-use filtration. The Yangtze River Delta biopharma corridor around Shanghai is expanding membrane area for monoclonal antibody contract manufacturing. Local producers are qualifying indigenous membrane suppliers to reduce dependence on imported polymeric media.
Pharmaceutical Filtration Devices Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized viral clearance and gene therapy applications. The vendor base stratifies across integrated life sciences conglomerates, dedicated filtration specialists, and diversified industrial suppliers. Three archetypes dominate: platform-anchored multinationals with chromatography-filtration bundles, membrane chemistry specialists with single-use assemblies, and diversified industrial players leveraging materials science capabilities. Competitive moves concentrate on strategic partnerships for continuous manufacturing integration and capacity expansion in high-growth Asian markets.
Among Germany-based filtration specialists, Sartorius AG exemplifies the membrane chemistry archetype through its single-use assembly focus. Danaher Corporation anchors the platform-integrated tier, leveraging life sciences infrastructure across North American sterile filtration demand. Thermo Fisher Scientific occupies the workflow-bundled position, competing through integrated analytical and filtration combinations. These three represent distinct strategic vectors without implying specific market share claims.
| Leading Market Players |
|---|
| Merck KGaA |
| Danaher Corporation |
| Sartorius AG |
| Thermo Fisher Scientific |
| 3M Company |
| Parker Hannifin Corporation |
| Eaton Corporation |
| Meissner Filtration Products |
| Pall Corporation |
| Others |
Value Chain & Pricing Dynamics
PVDF resin price indices from Northeast Asian petrochemical benchmarks cascade through membrane manufacturing into three-tier pricing structures across sterilizing-grade, pre-filtration, and depth filter categories. Polymeric feedstock volatility compresses margins at the standard tier while premium membrane grades retain pricing power through FDA 21 CFR Part 211 validation requirements.
Pricing Analysis
Input-cost pass-through from polyvinylidene fluoride resin markets governs membrane filter pricing, with feedstock fluctuations absorbed differentially across certification tiers. Price differentiation rests on FDA sterilization validation documentation and ISO 13485 quality management certification, with validated single-use assemblies commanding premiums over unvalidated alternatives. Pricing pressure stems from Indian and Chinese domestic membrane qualification programs that reduce import dependence. Contract manufacturing organizations exhibit highest price sensitivity due to campaign-based procurement, while integrated biologics producers prioritize supply security over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with PVDF resin production concentrated in China, Japan, and South Korea, exposing filter manufacturers to regional feedstock disruption. Membrane manufacturing draws from polymeric resin, non-woven support substrates, and precision pleating equipment. Tariff exposure on imported filtration media into India and China compounds logistics chokepoint risks at major port hubs. Distribution runs through authorized distributor networks serving biopharmaceutical clusters, with direct enterprise contracting displacing spot procurement among large-volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharmaceutical filtration devices market functions as a stable compounder anchored by irreversible regulatory mandates for sterile manufacturing that perpetually refresh equipment replacement cycles.
For Market Incumbents: Hedge against PVDF supply concentration through backward integration into resin qualification partnerships with secondary feedstock sources. Prioritize EMA Annex 1 compliance engineering services to capture retrofit demand from European barrier isolation mandates. Defensive patent positioning around nanofiltration viral clearance architectures limits emerging entrant encroachment into gene therapy applications.
For New Entrants and Emerging Players: Begin with specialized nanofiltration membranes for cell and gene therapy viral vector production, where incumbent presence remains limited and qualification timelines favor nimble suppliers. Target the Philadelphia-Camden viral vector manufacturing corridor for initial reference site development. A regulatory-first go-to-market emphasizing expedited USP 1664 extractables documentation accelerates customer qualification.
For Investors and Strategic Acquirers: Asymmetric upside sits with membrane chemistry specialists possessing validated single-use assembly platforms and established CDMO relationships. Long-term viability across the analysis window favors vendors with demonstrated EMA and FDA dual-qualification track records. Monitor NMPA biologics manufacturing standard enforcement in China as an inflection indicator for indigenous supplier substitution rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Membrane Qualification | Reduces supply concentration risk for CDMOs facing EMA Annex 1 compliance deadlines. |
| Isolator-Integrated Filtration Skid Development | Captures European retrofit demand from barrier isolation mandates entering enforcement. |
| Digital Twin Deployment for Predictive Maintenance | Creates software-enabled recurring revenue alongside hardware sales to biologics producers. |
| India PLI Scheme Manufacturing Localization | Positions suppliers for government-incentivized API and biologics cluster expansion. |
| USP 1664 Extractables Acceleration Program | Compresses toxicological assessment timelines to win gene therapy qualification races. |
Study Parameters
Direct dialogue with bioprocess engineers, regulatory affairs directors, filtration procurement managers, and CDMO manufacturing heads grounded qualitative findings in operational reality. Secondary validation drew from FDA 21 CFR guidance documents, EMA Annex 1 revision texts, CDSCO PLI scheme notifications, and ISO 13485 certification databases. Bottom-up membrane consumption modeling triangulated against top-down biopharmaceutical capacity expansion announcements.
Bottom-up volume projections aggregated individual filtration train configurations across monoclonal antibody, mRNA, and viral vector manufacturing platforms. Top-down demand estimates calibrated against regional biologics capacity investments and regulatory enforcement timelines. Segmentation modeling spanned product type, application, technology, and end-user archetype dimensions across the projection horizon. CAGRs derived from facility startup schedules, replacement cycle assumptions, and single-use adoption curve penetration rates.
Caveats apply where NMPA enforcement intensity, EMA Annex 1 inspection backlog resolution, or PVDF supply disruption could materially shift the outlook. Forecasts embed assumptions regarding regulatory convergence timelines and membrane chemistry substitution elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cardiac Implants Market
Medical Devices
Temporary Cardiac Pacing Wires and Leads Market
Medical Devices
Wearable Medical Technology Market
Medical Devices
Ear Tube Devices Market
Medical Devices
North America Pen Needles Market
Medical Devices
Vitrectomy Devices Market
Medical Devices
Global Ligation Devices Market
Medical Devices
LAMEA External Defibrillators Market
Medical Devices
South Africa Anesthesia Devices Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Global Ileostomy Market
Medical Devices
Global Positive Airway Pressure Devices Market
Medical Devices
Global Venous Stents Market
Medical Devices
Artificial Corneal Implants Market
Medical Devices
Table-Top Autorefractor Market
Medical Devices
Interspinous Process Decompression Devices Market