
 US Prefilled Syringes Market | 2026-2036
US Prefilled Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
US Prefilled Syringes Market Insights
Hospital pharmacy procurement is rewriting distribution economics for injectable drug delivery in the United States. Becton, Dickinson and Company leverages its vertically integrated needle-syringe platform to control cost positions across acute care networks. Gerresheimer AG anchors glass barrel supply through dedicated US manufacturing, while West Pharmaceutical Services, Inc. competes on elastomer-plunger engineering for high-value biologics.
Prefilled syringes are single-dose injection systems preloaded with pharmaceutical product, typically constructed from borosilicate glass or cyclic olefin polymer with bonded stainless steel needles and elastomeric closures, designed to eliminate dose preparation error and reduce contamination risk in clinical and self-administration settings. Glass prefilled syringes dominate oncology and vaccination segments where inert barrier properties protect protein stability, while plastic prefilled syringes extend into mass immunization campaigns where breakage tolerance and lighter logistics outweigh premium material costs. Safety prefilled syringes command attention in home healthcare channels as needlestick prevention regulations harden across state Medicaid programs.
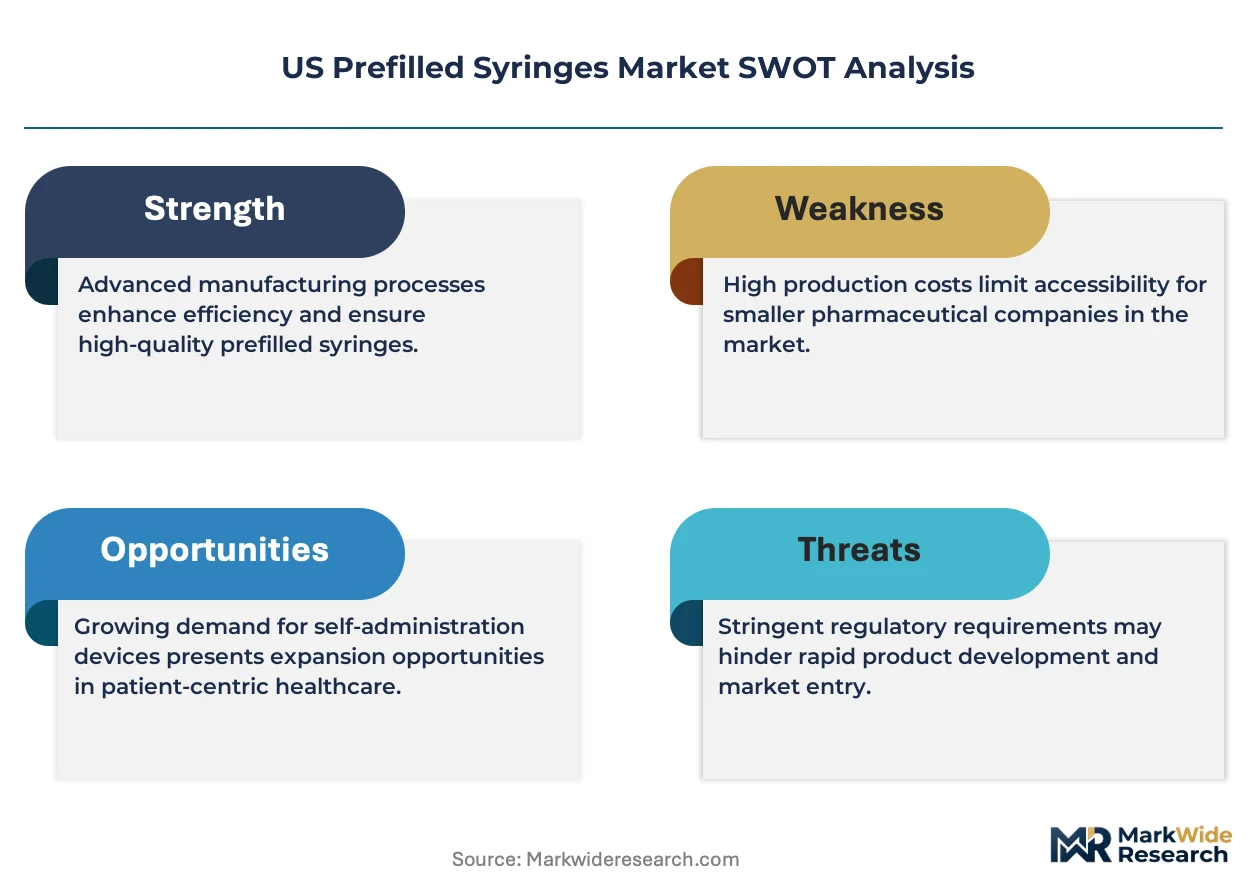
FDA oversight of combination products, USP Chapter 788 particulate standards, and OSHA bloodborne pathogen requirements collectively elevate manufacturing compliance costs while accelerating safety-engineered format adoption. The Drug Supply Chain Security Act serialization mandates now extend to prefilled units, forcing upstream integration of track-and-trace infrastructure. Stakeholders must monitor how CMS reimbursement shifts for hospital outpatient biologics reshape purchasing consolidation patterns.
Market Dynamics
Hospital outpatient consolidation is compressing procurement cycles for injectable drug delivery systems, as integrated delivery networks in Massachusetts and New York standardize on prefilled formats to reduce pharmacy labor costs and medication error liability.
Growth Catalysts
- OSHA Bloodborne Pathogen Standard:Needlestick prevention mandates across state Medicaid programs accelerate safety-engineered syringe adoption in home healthcare channels.
- Biologics administration:Oncology and autoimmune therapy expansion in Northeast corridor hospitals concentrates demand for ready-to-administer formats.
- Borosilicate glass barrier properties:Protein stability requirements in temperature-sensitive formulations protect glass prefilled syringe demand against polymer substitution.
Market Restraints
- Specialty elastomer supply concentration:Bromobutyl and chlorobutyl plunger formulations depend on limited North American polymer compounders, creating input cost volatility.
- FDA combination product guidance:Container closure integrity validation requirements extend development timelines and elevate sterility testing expenditures for new entrants.
- Glass breakage logistics:Cold chain distribution of glass-barrel units generates higher freight insurance and replacement costs versus polymer alternatives in mass immunization settings.
Strategic Opportunities
- Southeast ambulatory surgery center expansion:Florida and Texas outpatient facility construction creates underpenetrated demand for single-dose injectables outside traditional hospital pharmacy networks.
- Drug Supply Chain Security Act serialization:Track-and-trace infrastructure mandates force upstream integration partnerships between manufacturers and 3PL providers.
- Cyclic olefin polymer safety syringes:Breakage-tolerant materials converge with needlestick prevention engineering to displace glass in mass vaccination campaigns.
Industry Challenges
- Extractables and leachables validation:USP Chapter 1664 testing protocols require specialized analytical chemistry talent scarce in domestic contract manufacturing organizations.
- Legacy ERP integration:DSCSA serialization requirements force compatibility rebuilds with warehouse management systems at mid-tier distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Prefilled Syringes Market |
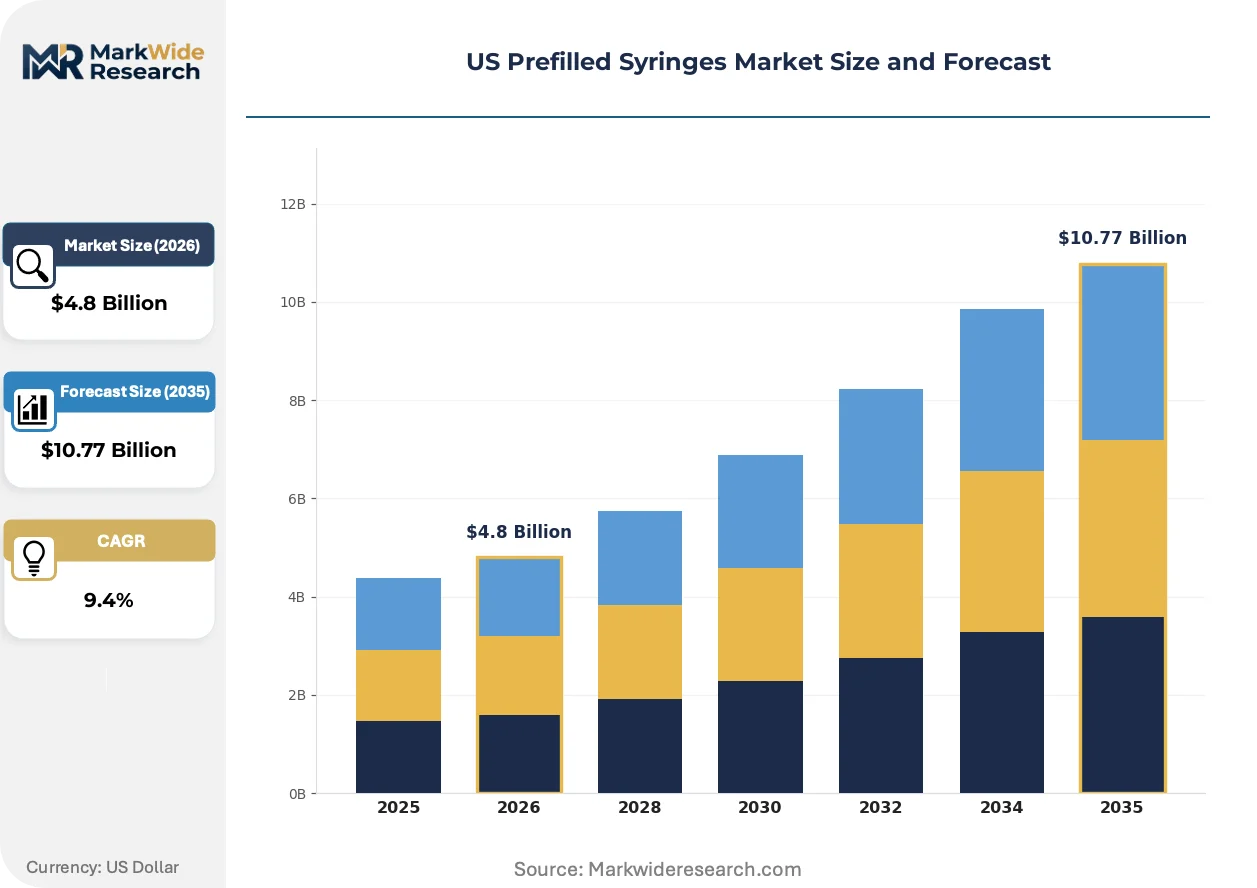
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Prefilled Syringes, Plastic Prefilled Syringes, Safety Prefilled Syringes, Biodegradable Prefilled Syringes, Disposable Syringes Therapy Area: Oncology, Diabetes, Immunology, Vaccination, Dermatology End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Laboratories, Home Healthcare Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Medical Supply Distributors, Direct Sales |
| Companies Covered | Becton, Dickinson and Company (BD), Gerresheimer AG, SCHOTT AG, West Pharmaceutical Services, Inc., Nipro Corporation, Terumo Corporation, Stevanato Group, Catalent, Inc., AptarGroup, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Prefilled Syringes Market Trends and Innovations
Material science advances and regulatory serialization mandates are restructuring manufacturing economics and supply chain architecture for prefilled injectable systems.
Connected syringe platforms embedding temperature loggers and dose-verification sensors are digitizing custody documentation for biologics. Cold chain distributors in the Northeast corridor deploy these units for high-value oncology therapies. Real-time data transmission is digitizing compliance evidence for FDA inspection readiness.
FDA's updated container closure guidance for combination products tightens sterility validation thresholds for elastomeric closures. Manufacturers now invest in barrier coating technologies and accelerated aging protocols. Glass prefilled syringe suppliers face the steepest compliance burden due to adhesive-delamination risk in protein formulations.
Integrated delivery network procurement committees now mandate safety-engineered formats with needlestick prevention features as a condition of formulary inclusion. Group purchasing organizations consolidate contracts around dual-chamber and pre-assembled safety syringes. This specification tightening is most visible in Massachusetts and New York hospital systems standardizing on ready-to-administer biologic delivery.
US Prefilled Syringes Market Segmentation
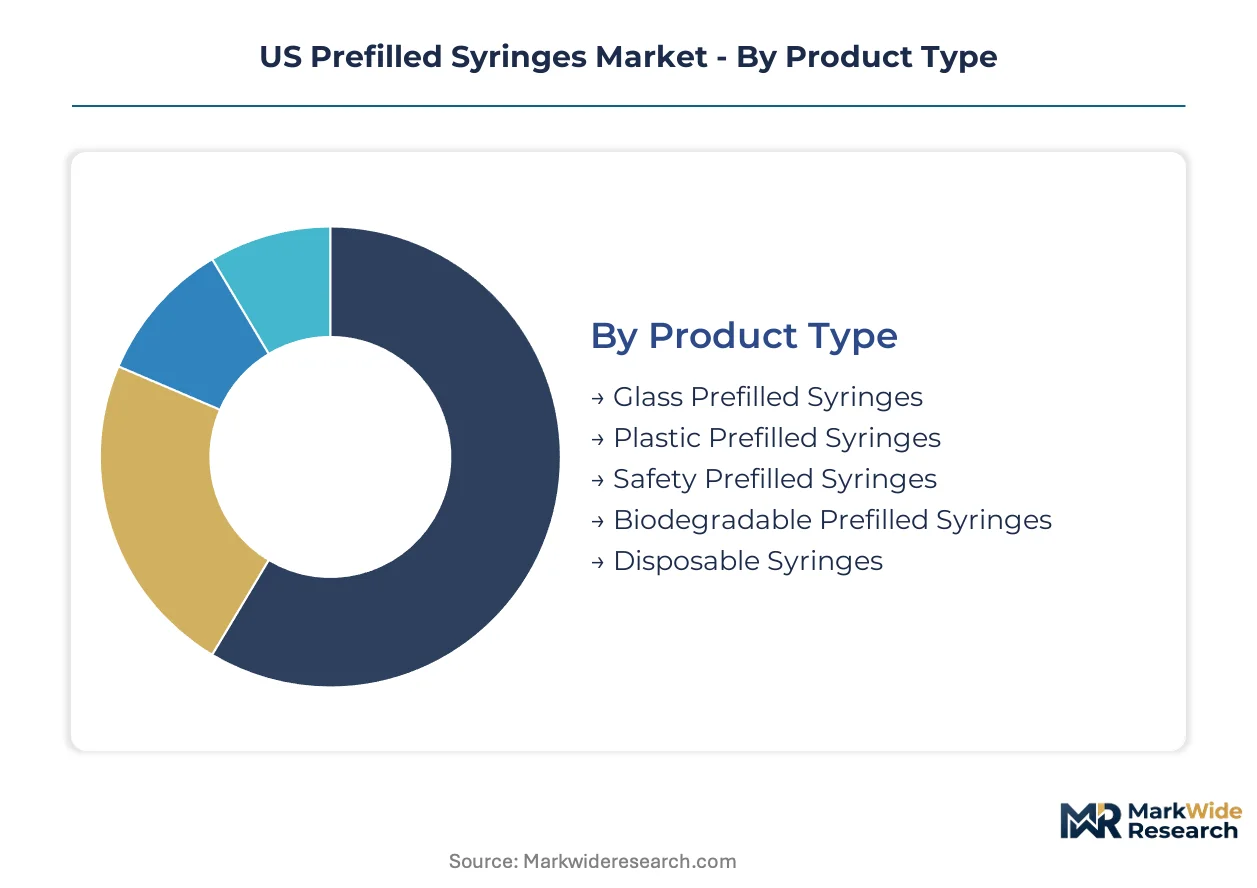
Prefilled syringe procurement patterns diverge sharply across material specifications, therapeutic applications, and care delivery settings. Manufacturers configure production lines around these dimensional splits to align barrier properties with biologic stability requirements and administration workflows.
Product Type:
Material composition defines barrier performance, breakage tolerance, and regulatory validation burden across the installed base.
- Glass Prefilled Syringes:Borosilicate construction delivers inert surface chemistry for protein-based biologics. Northeast corridor oncology centers specify these for temperature-sensitive monoclonal antibodies where delamination risk demands accelerated aging protocols.
- Plastic Prefilled Syringes:Cyclic olefin polymer barrels withstand drop impacts and thermal cycling without fracture. Mass immunization programs in Florida and Texas outpatient networks favor these for logistics efficiency where freight insurance premiums outweigh material cost differentials.
- Safety Prefilled Syringes:Needlestick prevention engineering integrates retractable or shielded mechanisms. State Medicaid programs in Massachusetts and New York mandate these for home healthcare channels.
- Biodegradable Prefilled Syringes:Polylactic acid and polyhydroxyalkanoate formulations target sustainability procurement criteria. Limited commercial penetration reflects unresolved USP Chapter 661 plastic certification timelines.
- Disposable Syringes:Single-use designs without preloaded drug product occupy lowest cost tier. Ambulatory surgery centers stock these for emergency backup against prefilled stockouts.
Glass prefilled syringes command the established base. The steepest expansion runs through safety-engineered plastic formats.
Therapy Area:
Clinical application determines volume scale, dosing frequency, and self-administration feasibility.
- Oncology:Cytotoxic and biologic agents require highest barrier protection. Northeast integrated delivery networks standardize on glass prefilled formats for chemotherapy suites to minimize compounding error liability.
- Diabetes:Insulin delivery concentrates in disposable pen systems rather than prefilled syringes. Limited segment relevance reflects device format substitution.
- Immunology:Autoimmune biologics demand temperature-controlled distribution with real-time monitoring. Connected syringe platforms with embedded loggers penetrate this segment fastest.
- Vaccination:Mass immunization campaigns drive highest unit volumes. Cyclic olefin polymer safety syringes displace glass in federal stockpile procurement.
- Dermatology:Intralesional and subcutaneous biologics for psoriasis and atopic conditions. Specialty clinics in Texas and Florida ambulatory networks represent concentrated demand pockets.
Oncology anchors revenue concentration. Vaccination delivers steepest unit volume expansion.
End User:
Care setting dictates labor cost structure, error tolerance, and regulatory oversight intensity.
- Hospitals:Pharmacy labor reduction drives formulary standardization on ready-to-administer formats. Massachusetts and New York systems consolidate procurement through integrated delivery network committees.
- Specialty Clinics:Rheumatology and gastroenterology practices administer biologics in outpatient suites. These facilities prioritize safety-engineered formats to reduce needlestick incident reporting.
- Ambulatory Surgical Centers:Fastest-growing site of service for injectable procedures. Southeast construction boom in Florida and Texas creates underpenetrated demand for single-dose units.
- Research Laboratories:Clinical trial supply requires serialization compliance under FDA Drug Supply Chain Security Act mandates. Track-and-trace infrastructure investments concentrate here.
- Home Healthcare:Self-administration channels face OSHA bloodborne pathogen enforcement across state Medicaid programs. Needlestick prevention features are non-negotiable procurement criteria.
Hospitals retain volume leadership. Ambulatory surgical centers are gaining share fastest.
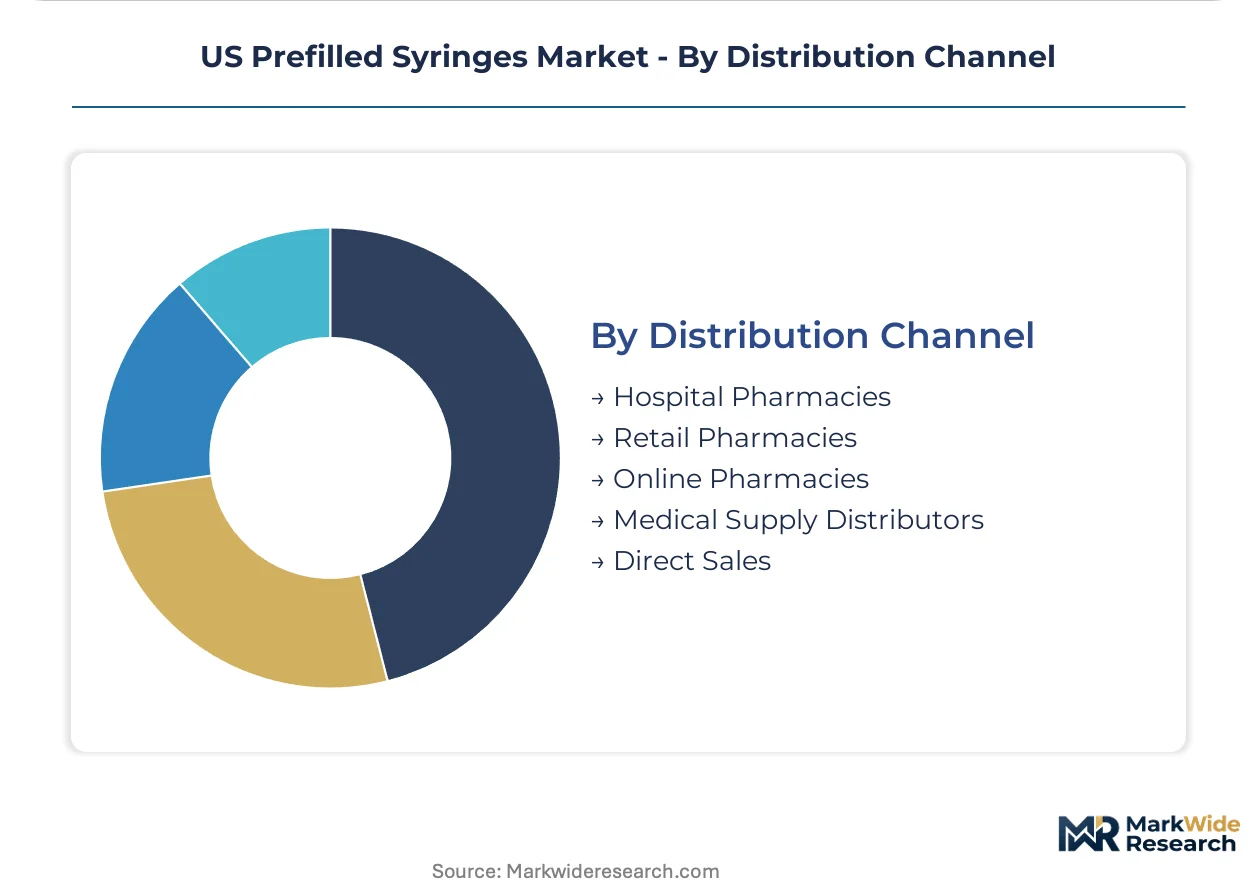
Distribution Channel:
Channel structure shapes serialization compliance burden and margin capture for manufacturers.
- Hospital Pharmacies:Integrated delivery network purchasing committees negotiate consolidated contracts. Group purchasing organization aggregation concentrates procurement power in Northeast corridor systems.
- Retail Pharmacies:Limited prefilled syringe penetration reflects reimbursement complexity for self-administered biologics. CVS and Walgreens specialty pharmacy divisions handle exceptions.
- Online Pharmacies:Direct-to-patient shipment requires cold chain validation and DSCSA track-and-trace integration. Regulatory uncertainty around interstate compounding limits segment development.
- Medical Supply Distributors:McKesson and Cardinal Health warehouse networks manage inventory for mid-tier hospitals. These intermediaries face ERP rebuild costs for serialization compliance.
- Direct Sales:Manufacturer-to-provider contracts for high-value biologics bypass distribution markup. Becton Dickinson and West Pharmaceutical Services deploy dedicated account teams for integrated delivery networks.
Hospital pharmacies dominate procurement volume. Direct sales channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts and New York integrated delivery networks command pricing leverage through consolidated procurement committees, while Southeast ambulatory surgery centers pay distribution premiums for single-dose injectables outside established hospital pharmacy networks.
Northeast Corridor
Oncology biologics and monoclonal antibody administration concentrate demand for borosilicate glass prefilled syringes in Boston and New York City hospital systems. FDA container closure guidance for combination products tightens sterility validation requirements for elastomeric closures used in protein formulations. Massachusetts General Hospital and Memorial Sloan Kettering standardize on ready-to-administer formats to reduce pharmacy compounding labor costs.
Southeast
Florida and Texas ambulatory surgery center construction generates underpenetrated demand for cyclic olefin polymer safety syringes in outpatient injectable procedures. OSHA bloodborne pathogen enforcement across state Medicaid programs mandates needlestick prevention features for home healthcare channels. Tampa and Houston specialty clinics prioritize retractable-needle formats to minimize incident reporting liability.
Midwest
Chicago and Detroit hospital networks consolidate injectable drug procurement through group purchasing organization contracts. USP Chapter 788 particulate standards elevate quality testing expenditures for glass-barrel suppliers serving rheumatology and gastroenterology practices. Cleveland Clinic anchors regional demand for high-barrier prefilled formats in autoimmune biologic administration.
Pacific Coast
Seattle and San Francisco biotech clusters drive clinical trial supply demand for serialized prefilled syringes under Drug Supply Chain Security Act mandates. Cold chain distributors deploy connected syringe platforms with embedded temperature loggers for high-value immunology therapies. Stanford and UCSF medical centers specify track-and-trace infrastructure for investigational drug products.
US Prefilled Syringes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on materials and closure engineering. The vendor base separates into three functional layers: needle-syringe assemblers, glass barrel fabricators, and elastomer-plunger compounders. Consolidation pressure runs through integrated delivery network procurement committees demanding single-source accountability. Capacity expansion and backward integration into polymer compounding represent the dominant competitive vectors as input cost volatility reshapes margin structures.
Within the platform integrator tier, Becton, Dickinson and Company and Terumo Corporation exemplify vertically integrated manufacturers controlling needle bonding and safety-engineering capabilities. Among European-based component specialists, Gerresheimer AG and SCHOTT AG occupy positions anchoring borosilicate glass supply for biologic barrier applications. West Pharmaceutical Services, Inc. represents the elastomer-plunger engineering archetype serving high-value oncology and immunology formulations. These named entities illustrate how competitive positioning stratifies across system integration, primary packaging materials, and specialized closure technologies.
| Leading Market Players |
|---|
| Becton, Dickinson and Company (BD) |
| Gerresheimer AG |
| SCHOTT AG |
| West Pharmaceutical Services, Inc. |
| Nipro Corporation |
| Terumo Corporation |
| Stevanato Group |
| Catalent, Inc. |
| AptarGroup, Inc. |
| Others |
Pricing and Supply Chain Analysis
Specialty elastomer compounding capacity in North America anchors margin capture for downstream safety-engineered syringe assemblers. Bromobutyl and chlorobutyl plunger formulations concentrate among limited domestic polymer compounders, translating input scarcity into pricing leverage for integrated manufacturers with captive supply agreements.
Pricing Analysis
Configured-to-order glass prefilled syringes for oncology biologics command substantial premiums over standard cyclic olefin polymer formats for mass vaccination. Pricing stratifies across premium, standard, and economy tiers based on barrier certification grade and volume commitment scale. Cost compression in plastic safety syringes is intensifying as Southeast ambulatory surgery centers consolidate procurement. Retail pharmacy channels exhibit highest price sensitivity due to reimbursement complexity for self-administered biologics.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk planning for borosilicate glass barrel suppliers. Germany, the United States, and Japan anchor global pharmaceutical glass fabrication. Production draws from bromobutyl elastomer, stainless steel needle stock, and cyclic olefin polymer resin. Single-source vulnerability concentrates in specialty plunger compounding. Distribution runs through integrated delivery network procurement committees and group purchasing organization contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic extractables and leachables testing capacity sits far below FDA combination product submission volume, creating a binding constraint on new entrant speed to market. Analytical chemistry talent scarcity in contract manufacturing organizations extends development timelines for container closure validation.
For Market Incumbents:Entrench safety-engineered format dominance through backward integration into elastomer compounding and accelerated aging protocol investment. Cyclic olefin polymer substitution threatens glass oncology share; defend through barrier coating technology differentiation. Hospital pharmacy consolidation demands single-source accountability contracts.
For New Entrants and Emerging Players:Pursue Southeast ambulatory surgery center networks in Florida and Texas where established hospital pharmacy relationships remain underdeveloped. Biodegradable prefilled syringes offer white-space positioning pending USP Chapter 661 plastic certification resolution. Lead with breakage-tolerant safety formats and direct sales account teams bypassing distributor markup.
For Investors and Strategic Acquirers:Capital is best deployed toward mid-tier elastomer-plunger engineering specialists with FDA master file portfolios and Northeast corridor GPO contract access. Long-term viability hinges on serialization infrastructure readiness and track-and-trace integration capability. Watch for DSCSA compliance deadline acceleration as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Captive bromobutyl supply secures margin stability against polymer cost volatility. |
| Connected Syringe Platform Development | Temperature logger integration addresses FDA inspection readiness for biologics distributors. |
| USP Chapter 1664 Testing Capacity Expansion | Domestic extractables validation accelerates combination product approval timelines. |
| Ambulatory Surgery Center Direct Sales Force | Florida and Texas outpatient construction creates underpenetrated channel access. |
| DSCSA Serialization Infrastructure Partnership | Track-and-trace integration with 3PL providers satisfies Drug Supply Chain Security Act mandates. |
Research Methodology
Initial hypotheses were tested against primary input from hospital pharmacy directors, GPO contracts managers, regulatory affairs leads at combination product manufacturers, and biomedical engineers at integrated delivery networks and refined through secondary validation against FDA 483 inspection observations, USP Chapter revision notices, CMS Medicare cost report data, and OSHA enforcement action records. Bottom-up demand modeling across material type, therapy area, and end-use setting was triangulated against top-down market sizing.
Demand-supply balance dynamics across the analysis window were modeled through segmentation across material composition, therapeutic application, care delivery setting, and regional regulatory cluster. CAGRs were derived from installed base attrition rates and new format adoption curves. Forecast inputs incorporated DSCSA serialization mandate phasing, state Medicaid needlestick prevention enforcement patterns, and biologics pipeline administration route specifications.
The forecast holds incumbent behavior within observed patterns; aggressive moves by European glass barrel specialists with US manufacturing footprints would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wireless Surgical Cameras Market
Medical Devices
Toe Fixation System Market
Medical Devices
Lyophilized Injectable Market
Medical Devices
Video Dermatoscope Market
Medical Devices
Airway Clearance Systems Market
Medical Devices
Abdominal Closure Systems Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Dialysis Catheters Market
Medical Devices
Digital Blood Pressure Monitors Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
PET-CT Scanner Device Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
Foot and Ankle Devices Market
Medical Devices
Tubal Obstruction Devices Market