
 Global Transcranial Magnetic Stimulators Market | 2026-2036
Global Transcranial Magnetic Stimulators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transcranial Magnetic Stimulators Market Foresight
The transcranial magnetic stimulator market is decoupling into premium deep TMS systems and commodity repetitive TMS devices. MagVenture leverages its coil technology leadership to command positions in European psychiatric facilities. Neurosoft competes through portable device specialization that extends access to private practices with limited capital budgets. BrainsWay anchors the premium tier with H-coil systems that target treatment-resistant depression segments.
Transcranial magnetic stimulators are non-invasive neurostimulation devices that generate magnetic pulses through copper coils to induce electrical currents in targeted cortical regions, with field strengths typically ranging from 1.5 to 4 Tesla depending on coil configuration and indication. These systems serve primary commercial purposes in treating major depressive disorder, obsessive-compulsive disorder, and facilitating post-stroke motor recovery through cortical reorganization protocols. Repetitive TMS devices occupy the largest installed base across neurology clinics, while deep TMS systems capture disproportionate margin pools due to specialized H-coil engineering and expanded indication portfolios. Portable devices represent the fastest-growing deployment type as reimbursement shifts enable outpatient and home-based treatment models.
FDA 510(k) premarket notifications and EU MDR conformity assessments shape device commercialization timelines and clinical evidence requirements for manufacturers seeking multi-regional presence. The WHO's inclusion of non-invasive brain stimulation in mental health care guidelines reinforces institutional purchasing frameworks across public health systems. Stakeholders must monitor evolving NMPA registration pathways in China and Health Canada priority review designations as these regulators expand neurostimulation coverage decisions.
Market Dynamics
Deep TMS coil engineering is bifurcating the installed base, with psychiatric facilities consolidating purchasing power around H-coil systems while private neurology clinics prioritize portable repetitive TMS platforms to extend outpatient reach.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's premarket notification framework accelerates commercial entry for repetitive TMS devices targeting major depressive disorder, compressing time-to-revenue for manufacturers with predicate device strategies.
- WHO mental health guideline integration:Non-invasive brain stimulation inclusion in WHO care protocols reinforces institutional purchasing frameworks across public health systems in Germany, Japan, and Australia.
- Neurology clinic density expansion:Concentrated facility growth in the United States and Japan supports installed base multiplication for high-throughput deep TMS systems.
Market Restraints
- Copper coil supply concentration:Precision-wound coil manufacturing concentrates among specialized Japanese and German component suppliers, exposing device assemblers to input bottlenecks.
- EU MDR conformity assessment delays:Expanded clinical evidence requirements for CE marking under the Medical Device Regulation extend commercialization timelines for novel coil configurations.
- Electroconvulsive therapy substitution:Established ECT protocols in severe treatment-resistant depression segments limit TMS penetration where anesthesia infrastructure exists.
Strategic Opportunities
- Home-based treatment models:Portable device specialization enables reimbursement-driven expansion into outpatient settings beyond traditional clinic infrastructure.
- Post-stroke motor recovery protocols:Cortical reorganization applications represent underpenetrated therapeutic verticals with expanding clinical trial evidence.
- Health Canada priority review designations:Accelerated regulatory pathways for neurostimulation coverage decisions create first-mover advantages in the Canadian psychiatric facility segment.
Industry Challenges
- Clinical technician certification gaps:Specialized training requirements for coil positioning and motor threshold determination constrain deployment velocity in emerging markets.
- Legacy EMR integration complexity:Treatment session data capture and outcome tracking systems require custom interoperability development with hospital information architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transcranial Magnetic Stimulators Market |
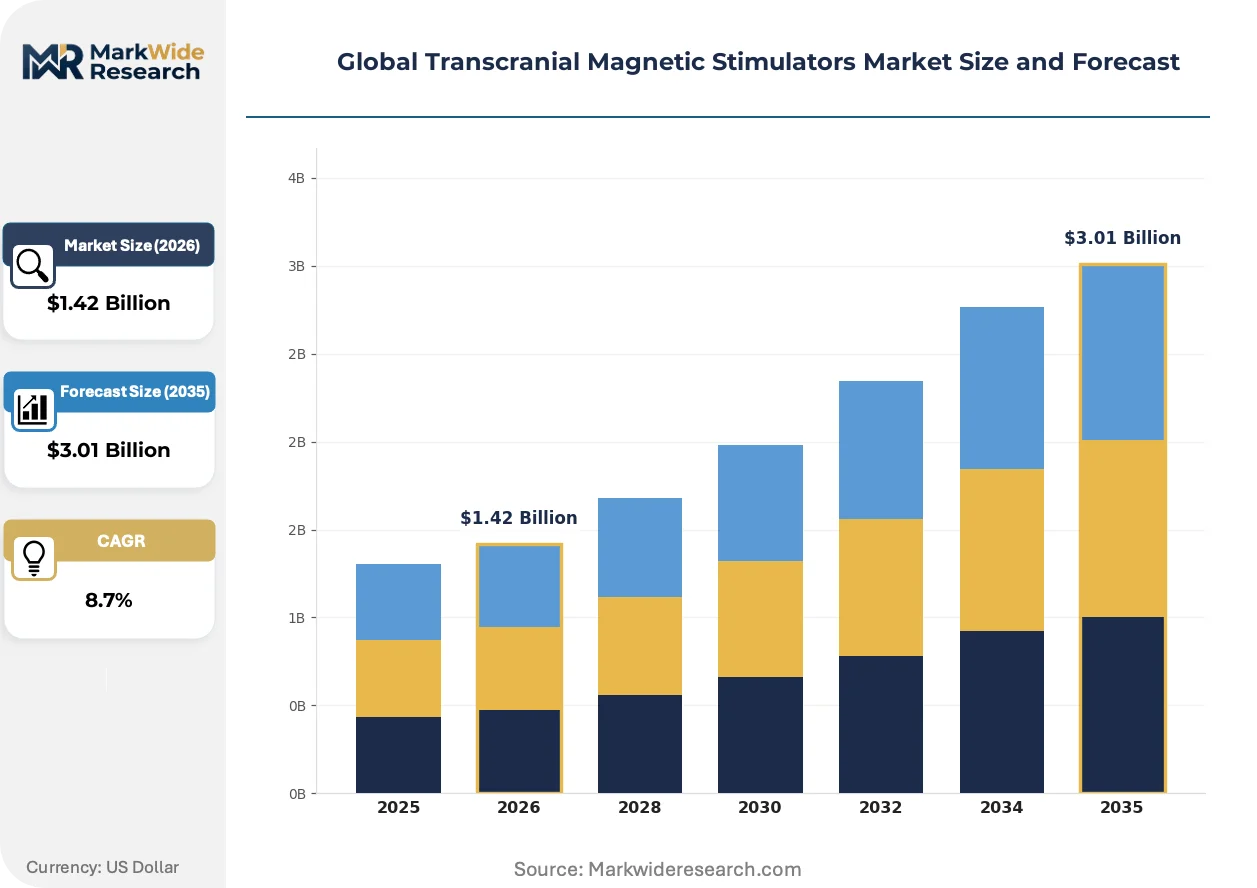
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Pulse Stimulators, Repetitive TMS Devices, Deep TMS, H-Coil Systems, Figure-8 Coil Systems Therapy Area: Depression, Anxiety Disorders, Post-Traumatic Stress, Schizophrenia, Stroke Rehabilitation End User: Neurology Clinics, Psychiatric Facilities, Rehabilitation Centers, Research Institutes, Private Practices Deployment Type: In-Clinic Systems, Portable Devices, Hospital-Based Units, Research Laboratory Equipment |
| Companies Covered | MagVenture, Neurosoft, BrainsWay, Neuronetics, Cool Tech, Remed, Guideline Geo, Blackrock Neurotech, CCD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transcranial Magnetic Stimulators Market Shifts & Advancements
Neurostimulation hardware is converging with digital therapeutics platforms, creating integrated treatment ecosystems that extend device value capture beyond the capital equipment sale into recurring software and protocol subscriptions.
H-coil deep TMS systems are electrifying competitive positioning in the premium psychiatric facility segment. These engineered coil arrays generate broader magnetic field penetration for anterior cingulate modulation. Major academic medical centers in the United States and Germany are standardizing procurement specifications around H-coil platforms. The technology is electrifying margin pools as manufacturers bundle proprietary treatment protocols with hardware leases.
EU MDR conformity assessments are restructuring commercialization economics for multi-regional manufacturers. Expanded post-market surveillance obligations and clinical evidence requirements for novel indications extend regulatory timelines. Deep TMS systems with obsessive-compulsive disorder clearances face disproportionate compliance burdens. European psychiatric facilities are consolidating purchasing around established CE-marked platforms to mitigate supply uncertainty.
Outcome-based reimbursement contracts are restructuring buyer-seller relationships in the United States. Commercial payers and hospital systems are shifting from capital purchase models toward per-treatment fee structures tied to response rate metrics. This reconfiguration favors manufacturers with robust real-world evidence platforms and remote monitoring capabilities. The shift concentrates procurement authority among integrated delivery networks with actuarial infrastructure to manage utilization risk.
Global Transcranial Magnetic Stimulators Market Segmentation
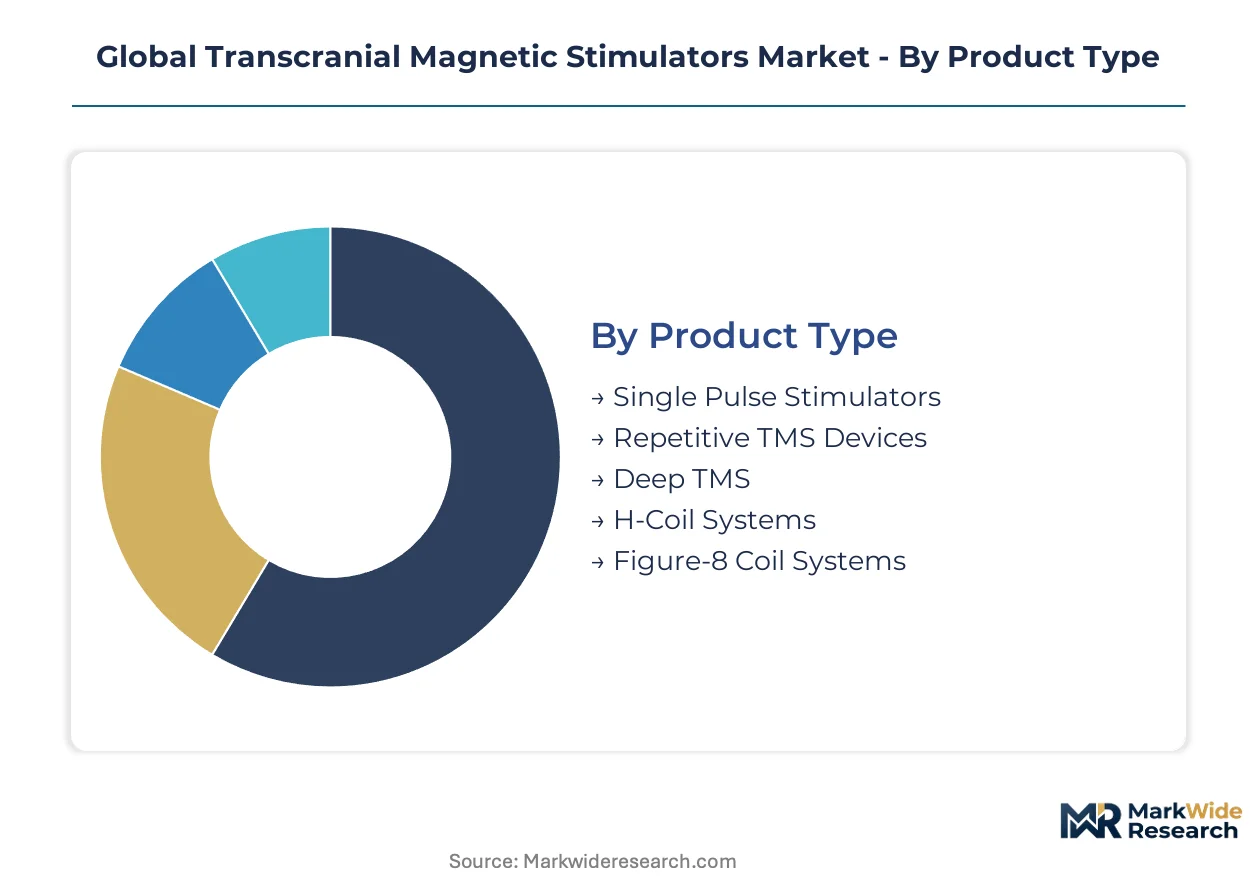
Segmentation in the transcranial magnetic stimulator market reveals distinct procurement patterns across psychiatric and neurological care settings. Coil engineering sophistication and reimbursement eligibility create tiered purchasing behaviors that manufacturers must navigate to optimize commercial positioning.
Product Type:
Capital allocation decisions hinge on treatment indication breadth and coil configuration complexity.
- Deep TMS:H-coil arrays generate penetrating magnetic fields reaching deeper cortical structures for anterior cingulate modulation. Psychiatric facilities in Germany and the United States prioritize these systems for obsessive-compulsive disorder protocols where shallower coils prove insufficient.
- Repetitive TMS Devices:Standard figure-8 and circular coil configurations dominate installed bases through established major depressive disorder clearances. Private neurology clinics in Japan favor these platforms for outpatient throughput efficiency where capital constraints limit premium system acquisition.
- Single Pulse Stimulators:Diagnostic motor threshold mapping applications concentrate in research laboratories and academic medical centers.
- H-Coil Systems:Specialized deep field arrays command premium positioning in treatment-resistant depression segments with dedicated reimbursement codes.
- Figure-8 Coil Systems:Focal stimulation precision suits motor cortex applications in post-stroke rehabilitation protocols.
Repetitive TMS devices lead on scale; Deep TMS leads on momentum.
Therapy Area:
Reimbursement pathway maturity determines addressable market expansion sequencing.
- Depression:FDA 510(k) clearances and established CPT codes create predictable revenue streams for device manufacturers across United States psychiatric facilities. Major depressive disorder protocols represent the foundational commercial indication with the broadest payer coverage.
- Stroke Rehabilitation:Cortical reorganization applications for motor recovery are gaining clinical trial evidence in Japanese and German rehabilitation centers. Post-stroke protocols are expanding most quickly as neuroplasticity research validates repetitive stimulation efficacy.
- Anxiety Disorders:Generalized anxiety and panic disorder applications remain investigational with limited commercial reimbursement.
- Post-Traumatic Stress:Veterans Affairs systems in the United States pilot dedicated protocols with emerging outcome data.
- Schizophrenia:Negative symptom targeting occupies early-stage clinical development with specialized research institute deployments.
Depression commands current revenue concentration; Stroke Rehabilitation shows steepest expansion trajectory.
End User:
Facility infrastructure and patient volume economics shape system configuration preferences.
- Psychiatric Facilities:Academic medical centers and dedicated mental health hospitals in the United States and Germany standardize on deep TMS platforms with bundled protocol subscriptions. These institutions command procurement authority through integrated delivery network structures.
- Neurology Clinics:Outpatient practices in Japan prioritize portable repetitive TMS systems to extend treatment access beyond hospital infrastructure. Capital efficiency requirements favor leasing models over outright purchase.
- Rehabilitation Centers:Post-stroke motor recovery applications concentrate in German and Japanese physical medicine facilities with specialized neurorehabilitation focus.
- Research Institutes:Investigational protocol development drives demand for configurable single-pulse and paired-pulse systems.
- Private Practices:Solo and small-group psychiatric practices in the United States adopt portable devices as reimbursement shifts enable outpatient service expansion.
Psychiatric Facilities anchor premium system deployment; Private Practices are gaining share fastest.
Deployment Type:
Care delivery model evolution is restructuring physical system requirements across treatment settings.
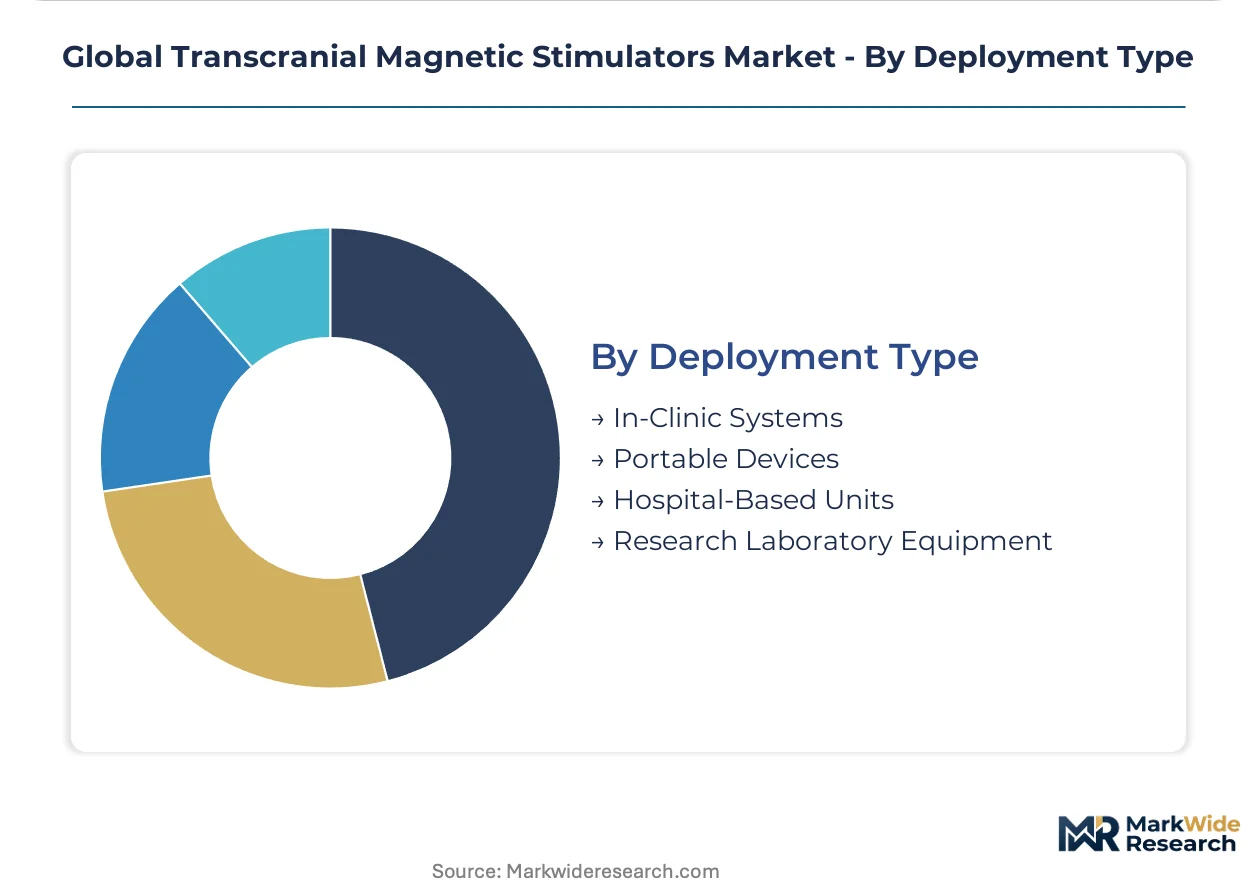
- Portable Devices:Compact coil-integrated systems enable reimbursement-driven expansion into outpatient and home-based treatment models. United States private practices deploy these platforms to capture per-treatment fee structures without dedicated facility infrastructure.
- In-Clinic Systems:Fixed-installation deep TMS platforms with shielded coil arrays serve high-throughput psychiatric facilities in Germany and Japan. These configurations optimize treatment room utilization for established major depressive disorder protocols.
- Hospital-Based Units:Integrated neurostimulation suites in academic medical centers combine TMS with imaging and electrophysiology monitoring.
- Research Laboratory Equipment:Configurable stimulation parameters and data acquisition capabilities serve investigational protocols in university-affiliated facilities.
In-Clinic Systems maintain current installed base dominance; Portable Devices demonstrate the strongest growth acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized neurostimulation technicians cluster in academic medical centers across the United States, Germany, and Japan, anchoring device deployment density and training infrastructure for advanced coil protocols.
United States
Veterans Affairs health systems drive institutional procurement for post-traumatic stress protocols, while FDA 510(k) clearances for obsessive-compulsive disorder indications expand reimbursable indications. The Boston-Cambridge corridor concentrates research institute demand for configurable single-pulse systems investigating cortical plasticity mechanisms.
Germany
Psychiatric facility networks in Bavaria and North Rhine-Westphalia standardize on deep TMS platforms with bundled protocol subscriptions, reflecting EU MDR conformity assessments that favor established CE-marked systems. METI-coordinated reimbursement frameworks for outpatient neurostimulation accelerate private clinic adoption in the Munich-Stuttgart medical corridor.
Japan
PMDA regulatory pathways for repetitive TMS devices compress commercialization timelines for manufacturers targeting major depressive disorder segments. The Tokyo-Osaka metropolitan axis hosts concentrated neurology clinic density supporting portable device deployment for aging-related stroke rehabilitation protocols.
Australia
TGA priority review designations for neurostimulation coverage create procurement momentum in public mental health systems across New South Wales and Victoria. WHO guideline integration reinforces institutional purchasing frameworks in Melbourne and Sydney academic medical centers expanding non-invasive brain stimulation service lines.
Canada
Health Canada priority review pathways for deep TMS systems with expanded indication portfolios attract manufacturer pre-market submission activity. Toronto and Montreal psychiatric facilities pilot outcome-based reimbursement contracts tied to treatment-resistant depression response metrics.
Global Transcranial Magnetic Stimulators Market Competitive Landscape
Top-tier vendors anchor the premium deep TMS segment with specialized H-coil engineering, while mid-scale competitors occupy portable repetitive TMS niches through capital-efficient device architectures. The vendor base stratifies across three functional tiers: coil technology specialists, portable platform fabricators, and integrated neurostimulation suite providers. Dominant competitive moves include strategic partnerships with academic medical centers for clinical evidence generation and geographic licensing agreements to bypass direct regulatory submission burdens.
Within the coil technology specialist tier, MagVenture and BrainsWay occupy positions reflecting European and Israeli engineering heritage respectively. Neurosoft represents the portable platform archetype, with company nomenclature suggesting Italian operational origins. These three named entities exemplify how competitive positioning fragments across technical specialization rather than consolidating around full-stack capabilities.
| Leading Market Players |
|---|
| MagVenture |
| Neurosoft |
| BrainsWay |
| Neuronetics |
| Cool Tech |
| Remed |
| Guideline Geo |
| Blackrock Neurotech |
| CCD |
| Others |
Supply & Pricing Matrix
Captive coil manufacturing in Germany and Japan anchors both supply security and pricing power for deep TMS system vendors, insulating premium tiers from copper volatility while commodity repetitive TMS assemblers absorb spot-market exposure. This integration choice concentrates margin capture among H-coil specialists and fragments pricing discipline across portable device fabricators sourcing from distributed component markets.
Pricing Analysis
Bundled protocol subscriptions versus unbundled hardware leases split the pricing architecture across psychiatric facility procurement. Three-tier pricing structure across premium H-coil systems, standard repetitive TMS platforms, and economy-grade portable devices reflects FDA 510(k) clearance tiering and coil engineering complexity. Pricing pressure stems from outcome-based reimbursement contracts in United States integrated delivery networks compressing per-treatment yields. Private practices exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize clinical evidence depth over acquisition cost.
Supply Chain Analysis
Domestic-content mandates in China's NMPA registration pathway and India's phased manufacturing program are reshaping sourcing strategies for coil winding and magnetic core components. Precision-wound copper coil production concentrates in Japan, Germany, and South Korea, with rare-earth magnetic materials drawing from Chinese processing facilities. Single-source vulnerability in specialized ferrite core supply exposes device assemblers to export restriction risk. Distribution runs through authorized dealer networks serving hospital systems and direct-to-clinic channels for private practice segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by psychiatric facility procurement consolidation around H-coil systems with bundled evidence protocols. The demand shift toward premium specifications with expanded indication portfolios rewards manufacturers with vertical integration into coil engineering.
For Market Incumbents: Anticipate electroconvulsive therapy substitution pressure in severe depression segments by deepening clinical evidence platforms for treatment-resistant populations. Prioritize EU MDR conformity assessment completion to defend CE-marked positioning against novel coil configuration entrants. Coil technology specialization remains the priority lever for margin defense. For New Entrants and Emerging Players: Private practice channel partners offer the most penetrable entry vector for portable repetitive TMS platforms capitalizing on reimbursement-driven outpatient expansion. Target post-stroke motor recovery protocols in Japanese and German rehabilitation centers where clinical trial evidence is accelerating adoption. Pursue software companion development as the primary go-to-market angle to differentiate beyond hardware commoditization. For Investors and Strategic Acquirers: Roll-up economics work for portable platform specialists because reimbursement fragmentation across United States state Medicaid programs prevents national-scale organic growth. The five-to-ten year viability window favors acquisition targets with Health Canada priority review submissions in progress. Watch FDA 510(k) clearance velocity for obsessive-compulsive disorder indications as the inflection signal for deep TMS premium-tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Expansion | Accelerates commercial entry for novel coil configurations targeting major depressive disorder segments. |
| CE Marking Pathway Investment | Secures EU MDR conformity for H-coil systems amid extended assessment timelines for psychiatric facilities. |
| Hospital System Partnership | Locks in integrated delivery network procurement authority through outcome-based reimbursement contracting. |
| Software Companion Development | Captures recurring revenue streams via treatment protocol subscriptions beyond capital equipment sales. |
| Reimbursement Strategy Execution | Aligns CPT code expansion with Veterans Affairs pilot programs for post-traumatic stress protocols. |
Research Methodology
Coverage spans the United States, Germany, Japan, Australia, and Canada, with primary inputs from each market cluster combining executive interviews with psychiatric facility procurement directors, biomedical engineers specializing in neurostimulation, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary validation draws from FDA 510(k) premarket notification databases, EU MDR conformity assessment records, PMDA submission filings, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up installed base modeling triangulates against top-down market sizing across coil configuration and deployment type segments.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. The analytical framework models coil engineering tier, therapy area reimbursement maturity, end-user facility type, and deployment portability as core segmentation dimensions. CAGRs derive from clinician adoption curve analysis and payer coverage decision timelines. Forecast inputs incorporate PMDA regulatory pathway velocity and METI-coordinated reimbursement framework evolution in Japan.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR assessment backlog resolution and copper coil supply concentration risk. The analysis reflects assumptions around WHO guideline integration sustaining institutional purchasing frameworks and FDA 510(k) pathway stability for predicate device strategies. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
Mandibular Advancement Devices Market
Medical Devices
United States Ultrasound Devices Market
Medical Devices
Diode Laser Hair Removal Equipment Market
Medical Devices
Global Angiographic Catheters Market
Medical Devices
Neurovascular Catheters Market
Medical Devices
Needle-Free Injectors Market
Medical Devices
Pulmonary Function Testing System Market
Medical Devices
Medical Device Validation and Verification Market
Medical Devices
Dosage Unit Sampling Apparatus Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
Tissue Sectioning Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Cyberknife Market
Medical Devices
Clot Management Devices Market