
 General Surgery Devices Market | 2026-2036
General Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
General Surgery Devices Market Intelligence
Modular instrument bundles is pivoting how procurement teams evaluate capital expenditures against per-procedure costs. Medtronic Plc leverages integrated energy platforms to anchor its position in advanced vessel sealing. Johnson & Johnson Service, Inc. differentiates through broad suture portfolios spanning absorbable and non-absorbable materials. Stryker Corporation competes on visualization ecosystems that link cameras to integrated operating room infrastructure.
General surgery devices encompass instruments, energy systems, closure materials, and fixation tools manufactured from medical-grade stainless steel, polymers, or biologic matrices, designed to enable tissue manipulation, hemostasis, and wound closure across operative interventions. Electrosurgical devices typically operate at frequencies between 300 kHz and 3 MHz, delivering controlled thermal energy for cutting and coagulation with precision measured in millimeters. Surgical instruments and sutures occupy mature margin pools where scale manufacturing and established brand loyalty protect incumbent positions, while robotic-assisted technology captures premium pricing through system-and-consumable attachment models. Minimally invasive platforms across abdominal and cardiothoracic applications represent the fastest-expanding procedural volume segment as patient recovery metrics and reimbursement incentives align.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements impose divergent compliance burdens that stretch engineering resources and delay commercial timelines for multi-market launches. The EPA regulates sterilization emissions from ethylene oxide facilities, constraining device reprocessing capacity and pushing hospitals toward single-use alternatives. Stakeholders must monitor how FDA digital health guidance and EU AI Act risk classifications intersect with emerging surgical navigation algorithms to determine whether software-enabled devices trigger additional premarket scrutiny or streamlined review.
Market Dynamics
Robotic-assisted surgical platforms are compressing procedure times while expanding addressable case volumes, forcing capital equipment vendors to restructure pricing around disposable instrument attach rates rather than upfront system sales.
Growth Catalysts
- EU MDR compliance deadlines:Manufacturers accelerating technical documentation for legacy device recertification are simultaneously upgrading product architectures, creating a forced modernization cycle across electrosurgical and laparoscopic portfolios.
- University hospital networks in Germany:These institutions anchor European demand for advanced vessel sealing and integrated energy platforms, with procurement committees prioritizing systems that reduce operating room turnover.
- Single-use instrument migration:EPA ethylene oxide emission constraints on sterilization facilities are pushing ambulatory surgery centers toward disposable alternatives, expanding addressable volume for polymer-based instrument manufacturers.
Market Restraints
- Titanium and medical-grade stainless steel input costs:Volatility in specialty metal pricing compresses margin pools for instrument manufacturers locked into multi-year hospital supply agreements.
- Robotic system supply concentration:Proprietary instrument ecosystems tie hospitals to single-vendor consumable streams, limiting competitive pressure on per-procedure pricing.
- FDA 510(k) substantial equivalence requirements:Predicate device dependencies slow iterative innovation for electrosurgical generators and bipolar forceps, extending development timelines for novel energy delivery modalities.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives attract contract manufacturers seeking to serve Southeast Asian markets with localized production of sutures and basic laparoscopic instruments.
- AI-enabled surgical navigation:Convergence of computer vision algorithms with laparoscopic camera feeds creates white space for software-integrated visualization platforms that reduce reliance on tactile feedback.
- Direct-to-hospital digital procurement channels:Specialized distributors are building e-commerce infrastructure that bypasses traditional medical-surgical wholesalers, capturing margin from high-velocity consumable categories.
Industry Challenges
- Robotic surgery technician certification:Hospital systems face scarcity of trained staff capable of troubleshooting integrated operating room platforms, extending equipment downtime and compressing case throughput.
- EU MDR notified body capacity: Bottlenecks in technical documentation review extend time-to-market for Class IIa and IIb surgical devices, straining cash conversion cycles for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | General Surgery Devices Market |
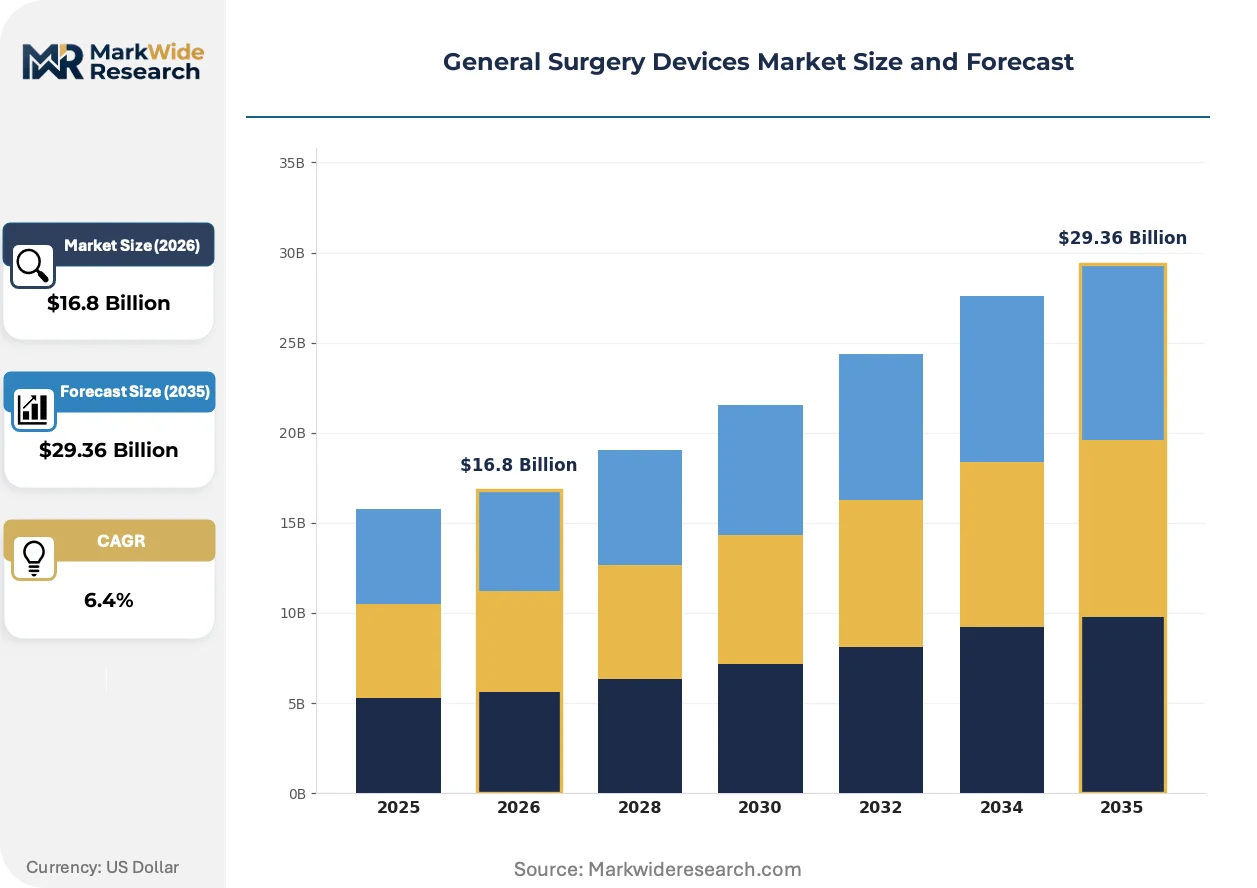
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $29.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Sutures, Electro-surgical Devices, Anchors Technology: Minimally Invasive, Robotic-assisted, Laparoscopic, Open Surgery End User: Hospitals, Surgical Centers, Clinics, Ambulatory Surgery Centers Application: Abdominal Surgery, Cardiothoracic Surgery, Neurosurgery, Orthopedic Surgery |
| Companies Covered | Medtronic Plc, Johnson & Johnson Service, Inc., Stryker Corporation, B. Braun Melsungen Ag, Becton, Dickinson and Company, Conmed Corporation, Olympus Corporation, Smith & Nephew, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
General Surgery Devices Market Strategic Shifts & Innovations
Energy delivery systems and visualization hardware are merging into unified platforms that reduce surgical team cognitive load while capturing procedure data for quality analytics.
Advanced bipolar vessel sealing technology is converging with ultrasonic dissection platforms, enabling simultaneous hemostasis and tissue transection without instrument exchange. Academic medical centers in the United States are piloting these hybrid energy systems for complex hepatobiliary procedures. The convergence is compressing operative time metrics and forcing standalone electrosurgical manufacturers to integrate or exit premium abdominal surgery segments.
FDA digital health guidance on software as a medical device is reshaping premarket submission requirements for surgical navigation algorithms that overlay anatomical mapping onto live video feeds. Manufacturers must now demonstrate clinical validation for machine learning models trained on proprietary image databases. Laparoscopic camera vendors with embedded AI capabilities face extended review timelines compared to conventional hardware-only systems.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, negotiating third-party maintenance for robotic platforms and visualization towers. This behavior disrupts traditional vendor lock-in strategies and shifts margin toward independent service organizations with specialized technical expertise. The pattern is most visible in United States health systems with centralized supply chain governance and multi-hospital service networks.
General Surgery Devices Market Segmentation
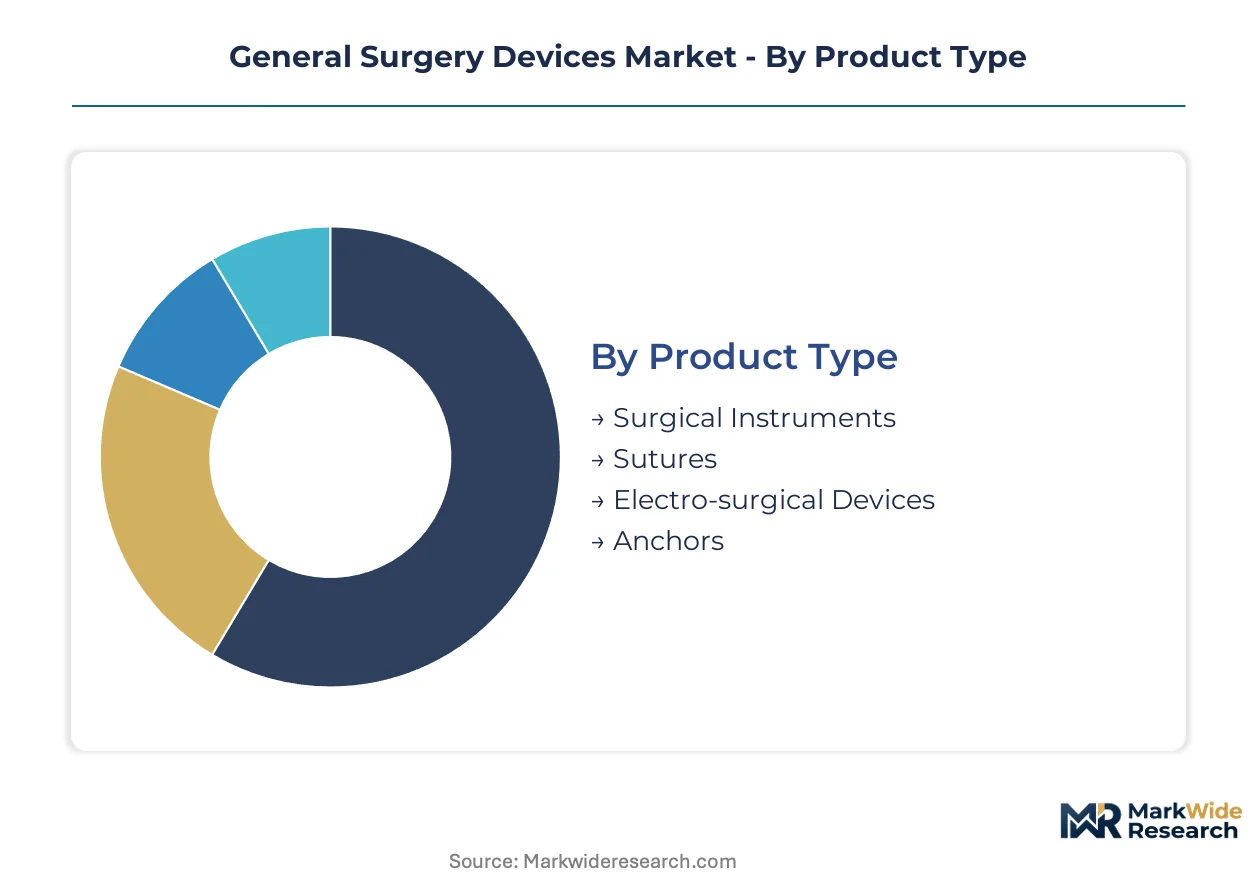
Procurement committees evaluate general surgery devices through multiple lenses simultaneously. Product specifications, procedural fit, and total cost of ownership each dominate at different decision stages. Understanding these segment boundaries clarifies where manufacturers can defend premium positioning versus where commoditization pressures concentrate.
Product Type:
Capital allocation decisions separate commodity consumables from platforms requiring technical validation and training infrastructure.
- Surgical Instruments:Manufactured from medical-grade stainless steel and titanium alloys, these graspers, retractors, and dissectors face margin compression from multi-year supply agreements. German university hospital networks prioritize instrument durability metrics and standardized tray configurations to reduce operating room turnover delays.
- Sutures:Absorbable and non-absorbable closure materials span synthetic polymers and natural collagen matrices. Demand concentrates in ambulatory surgery centers migrating toward pre-sterilized, procedure-matched packs that eliminate reprocessing bottlenecks under EPA ethylene oxide emission constraints.
- Electro-surgical Devices:Generators and active electrodes operating at 300 kHz to 3 MHz deliver thermal cutting and coagulation. FDA 510(k) predicate dependencies slow iterative innovation for novel energy delivery modalities.
- Anchors:Fixation devices for soft tissue reattachment deploy screw-in, push-in, or knotless designs across polymer and metallic constructions. Sports medicine applications in United States hospital systems drive specification requirements.
Volume sits with surgical instruments and sutures; growth tilts toward electro-surgical platforms integrating vessel sealing with ultrasonic dissection.
Technology:
Procedure selection and reimbursement incentives determine which technical platforms hospitals prioritize for capital investment cycles.
- Minimally Invasive:Laparoscopic and thoracoscopic approaches through small incisions reduce recovery metrics and length-of-stay costs. United States health systems with bundled payment contracts favor these platforms for their impact on episode-of-care economics.
- Robotic-assisted:Computer-controlled surgical systems with articulated instrument arms enable precision in confined anatomical spaces. Academic medical centers in Germany anchor European demand despite proprietary consumable ecosystems that limit vendor switching.
- Laparoscopic:Camera-guided abdominal procedures using rigid endoscopes and specialized instrumentation. Visualization ecosystem vendors compete on integrated operating room infrastructure linkages.
- Open Surgery:Traditional incision-based approaches persist for trauma, emergency, and complex oncological resections where tactile feedback and rapid access override minimally invasive constraints.
Installed base concentrates in open and laparoscopic platforms; expansion concentrates in robotic-assisted systems capturing premium per-procedure economics.
End User:
Site-of-care economics and case complexity stratify purchasing authority and technical support requirements.
- Hospitals:Integrated health systems with centralized supply chain governance negotiate capital equipment and high-volume consumable contracts. United States hospital networks unbundle after-sales service from equipment purchases, shifting margin toward independent service organizations.
- Surgical Centers:Focused facilities performing scheduled procedures prioritize instrument turnover efficiency and disposable alternatives to minimize reprocessing infrastructure. EPA sterilization emission regulations accelerate single-use migration.
- Clinics:Office-based settings handle minor procedures with basic instrumentation and local anesthesia. Procurement emphasizes cost containment over advanced platform capabilities.
- Ambulatory Surgery Centers:Medicare-certified facilities performing same-day discharge procedures. These centers drive demand for pre-packaged, sterilized instrument sets that eliminate on-site reprocessing entirely.
Revenue concentrates in hospital procurement committees; volume expansion tilts toward ambulatory surgery centers capturing outpatient migration.
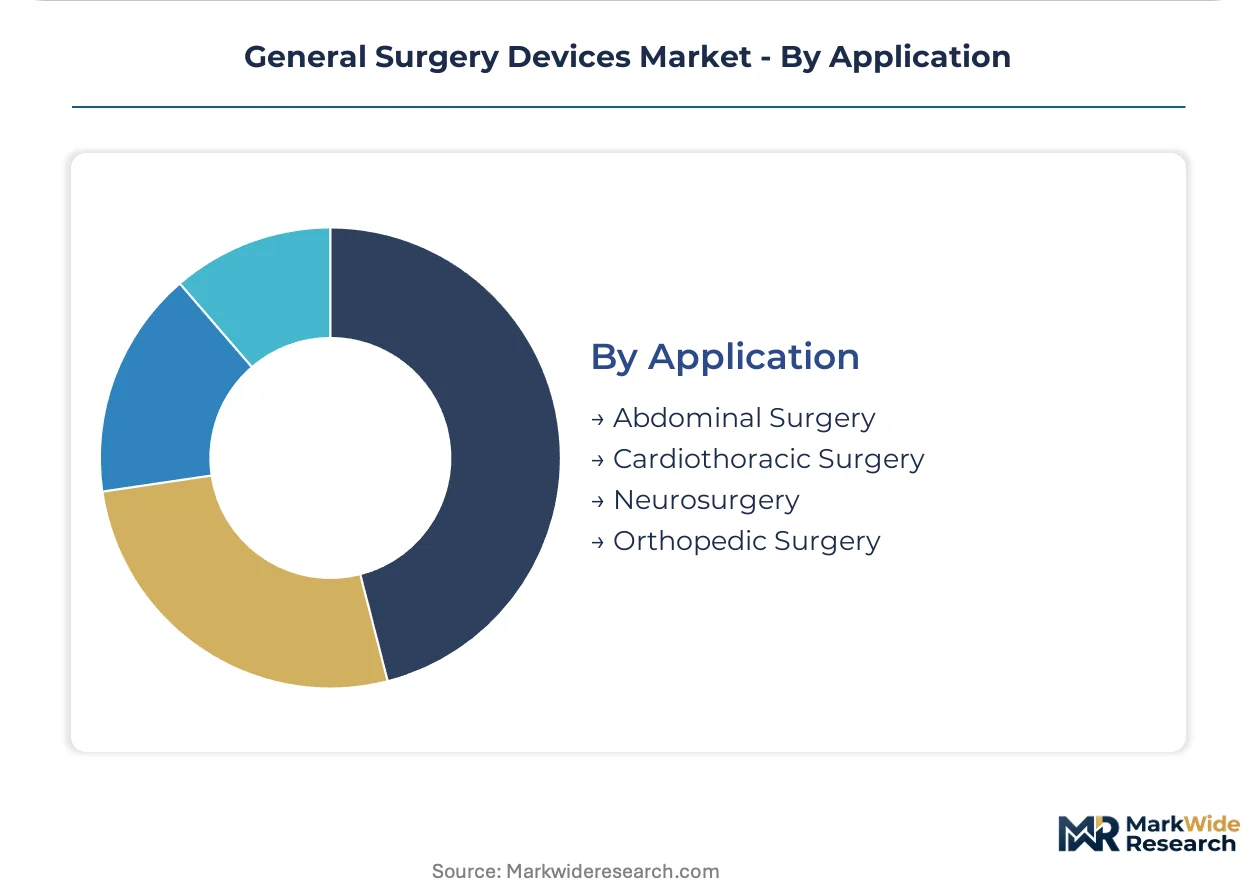
Application:
Anatomical specialization determines energy platform specifications and visualization requirements.
- Abdominal Surgery:Hepatobiliary, colorectal, and gastric procedures demand hybrid energy systems combining vessel sealing with ultrasonic dissection. Academic medical centers pilot advanced bipolar platforms for complex resections.
- Cardiothoracic Surgery:Cardiac and pulmonary interventions require precise hemostasis in vascular tissue. Sternotomy and thoracotomy approaches persist alongside minimally invasive alternatives.
- Neurosurgery:Cranial and spinal procedures prioritize visualization clarity and micro-instrument precision. Navigation systems with anatomical mapping overlays face extended FDA review timelines under digital health guidance.
- Orthopedic Surgery:Joint reconstruction and trauma fixation utilize power tools, implants, and soft tissue anchors. Sports medicine volumes concentrate in United States ambulatory settings.
Procedure volume concentrates in abdominal and orthopedic applications; technology intensity climbs fastest in cardiothoracic and neurosurgical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters concentrate in Germany and the United States while consumption tilts toward hospital networks in Western Europe and North American health systems. Regulatory divergence between FDA 510(k) pathways and EU MDR compliance timelines stretches commercial timelines for multi-market launches.
United States
Hospital networks in the United States are expanding procurement of robotic-assisted surgical platforms as bundled payment contracts reward reduced length-of-stay metrics. FDA premarket notification pathways impose predicate device dependencies that slow iterative innovation for electrosurgical generators. Academic medical centers in Boston and the Bay Area pilot hybrid energy systems for complex hepatobiliary procedures.
Germany
University hospital networks in Germany anchor European demand for advanced vessel sealing and integrated energy platforms. EU MDR technical documentation requirements impose compliance burdens that strain engineering resources for mid-scale manufacturers. The Baden-Württemberg cluster around Tübingen and Stuttgart concentrates visualization ecosystem development linking cameras to integrated operating room infrastructure.
India
Domestic manufacturing incentives under the PLI scheme attract contract manufacturers seeking to serve Southeast Asian markets with localized production of sutures and basic laparoscopic instruments. CDSCO regulatory frameworks govern medical device registration timelines for imported capital equipment. The Maharashtra-Gujarat corridor hosts emerging production facilities targeting cost-competitive polymer-based instrument manufacturing.
Japan
PMDA review timelines for software-enabled surgical navigation systems extend commercialization cycles for AI-integrated visualization platforms. METI industrial policy supports precision manufacturing capabilities in medical-grade stainless steel instrumentation. The Kansai region around Osaka maintains concentration in electrosurgical device component fabrication.
United Kingdom
NHS procurement frameworks prioritize total cost-of-ownership metrics in capital equipment decisions, unbundling after-sales service from system purchases. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines, creating parallel compliance requirements. The Cambridge-Oxford-London triangle anchors surgical robotics research programs with ties to National Health Service hospital networks.
General Surgery Devices Market Key Industry Players
The competitive structure tilts toward diversified conglomerates with cross-portfolio energy platforms and visualization ecosystems. Three archetypes dominate: integrated system vendors capturing premium through disposable attach rates, scale manufacturers defending margin pools in sutures and basic instrumentation, and specialized visualization firms competing on operating room infrastructure integration. Consolidation pressures concentrate in electrosurgical segments where hybrid energy convergence favors platform breadth over standalone innovation.
Among the diversified conglomerates, Medtronic Plc and Johnson & Johnson Service, Inc. exemplify the integrated system archetype, while Stryker Corporation occupies a position emphasizing visualization ecosystem linkages. These three entities represent distinct strategic postures within a market where proprietary instrument ecosystems tie hospitals to single-vendor consumable streams and limit competitive pressure on per-procedure pricing.
| Leading Market Players |
|---|
| Medtronic Plc |
| Johnson & Johnson Service, Inc. |
| Stryker Corporation |
| B. Braun Melsungen Ag |
| Becton, Dickinson and Company |
| Conmed Corporation |
| Olympus Corporation |
| Smith & Nephew |
| Boston Scientific Corporation |
| Others |
Cost & Logistics Intelligence
Titanium alloy feedstock and medical-grade stainless steel sheet move from German and Japanese specialty mills through three pricing tiers before reaching hospital procurement committees. EPA ethylene oxide emission constraints on sterilization facilities amplify cost-down pressure on reprocessable instrument bundles. Contract manufacturers in India's Maharashtra-Gujarat corridor capture economy-tier volume with polymer-based alternatives.
Pricing Analysis
Margin tightening in consumable tiers reflects multi-year supply agreement lock-ins that prevent pass-through of specialty metal volatility. Three-tier pricing structure across premium robotic ecosystems, standard laparoscopic platforms, and economy single-use instruments dominates procurement evaluations. Pricing pressure intensifies in basic instrumentation as ambulatory surgery centers migrate toward disposable alternatives. Surgical centers exhibit highest price sensitivity; academic medical centers anchor premium tier demand through integrated energy platform specifications.
Supply Chain Analysis
Freight cost escalation from Asia-Pacific manufacturing hubs compresses landed margins for polymer-based instrument manufacturers serving European hospital networks. Supply concentrates in Germany for precision electrosurgical components, the United States for visualization ecosystem assembly, and India for suture and basic laparoscopic production. Raw material dependencies span medical-grade stainless steel from Japanese mills, titanium alloys from Russian and Chinese sources, and biologic collagen matrices from Australian and New Zealand processors. Single-source vulnerability in robotic instrument consumables creates vendor lock-in exposure. Distribution runs through specialized medical-surgical wholesalers and emerging direct-to-hospital digital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance deadlines and hybrid energy platform convergence are forcing mid-scale manufacturers toward exit or acquisition, consolidating competitive structure around diversified system vendors.
For Market Incumbents: Deepen backward integration into medical-grade stainless steel processing to offset commodity volatility in instrument manufacturing. Anchor hospital relationships through captive service organizations that capture unbundled maintenance contracts from robotic platform sales. FDA 510(k) predicate dependencies protect positions in electrosurgical generators but require accelerated R&D investment to defend against ultrasonic-bipolar hybrid convergence.
For New Entrants and Emerging Players: Ambulatory surgery centers facing EPA sterilization constraints represent the most penetrable buyer archetype for polymer-based single-use instrument bundles. India's PLI scheme enables cost-competitive manufacturing for Southeast Asian market entry. Direct-to-hospital digital procurement channels bypass entrenched wholesaler relationships and capture margin from high-velocity consumable categories.
For Investors and Strategic Acquirers: Notified body capacity bottlenecks extending EU MDR recertification timelines are the leading indicator that mid-scale manufacturers with strong technical documentation will command acquisition premiums. Long-term viability centers on platform breadth across energy delivery and visualization ecosystems rather than standalone innovation. Watch for hospital procurement committee unbundling of after-sales service contracts as signal of margin migration toward independent technical service providers.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device dependencies in electrosurgical segments protect incumbent positions while slowing iterative innovation cycles. |
| CE Marking Pathway | EU MDR technical documentation requirements strain engineering resources and extend time-to-market for Class IIb surgical devices. |
| Hospital System Partnership | Academic medical centers in Germany and the United States anchor demand for integrated energy platforms and robotic ecosystems. |
| Software Companion Development | FDA digital health guidance on surgical navigation algorithms triggers extended review timelines for AI-integrated visualization systems. |
| Reimbursement Strategy | United States bundled payment contracts reward reduced length-of-stay metrics that favor minimally invasive platform adoption. |
Research Approach
FDA 510(k) clearance databases, EU MDR notified body technical documentation filings, and hospital procurement contract registries formed the secondary backbone for market sizing and competitive positioning. Primary interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and electrosurgical device R&D leads validated demand assumptions and pricing dynamics. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored value estimates across the analysis window.
Historical trendline analysis of robotic-assisted surgical platform installations, laparoscopic procedure migration rates, and single-use instrument adoption patterns informed projection frameworks. Segmentation dimensions spanned product type, technology platform, end-user site of care, and anatomical application. CAGRs derived from weighted average of procedure volume growth and per-procedure pricing trajectories. Industry-specific inputs included EPA sterilization facility capacity constraints and EU MDR recertification completion rates.
Revisions become necessary when FDA digital health guidance expands premarket scrutiny of AI-enabled surgical navigation, or when EU notified body capacity constraints extend beyond current backlog projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Clear Aligners Market
Medical Devices
Orthodontic Retainers Market
Medical Devices
3D-Printed Maxillofacial Implants Market
Medical Devices
Allografts Market
Medical Devices
Global Thoracic Drainage Devices Market
Medical Devices
Global Automated Suturing Devices Market
Medical Devices
Intraosseous Infusion Device Market
Medical Devices
China Anesthesia Devices Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
Ocular Trauma Devices Market
Medical Devices
Medical Device Manufacturing Outsourcing Market
Medical Devices
Global Large Volume Wearable Injectors Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
Intravenous Access Devices Market
Medical Devices
Multi Dose Drug Vial Adapters Market
Medical Devices
Italy Contraceptive Devices Market