
 South Africa Neurology Devices Market | 2026-2036
South Africa Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Neurology Devices Market Analytics
South Africa's National Health Insurance policy framework is pivoting procurement priorities toward domestically registered neurology devices. Medtronic PLC leverages its established regulatory dossiers to sustain hospital channel access across Gauteng and Western Cape provinces. Stryker Corporation anchors its competitive position through specialized surgical instrument portfolios designed for neurotrauma procedures. Abbott Laboratories differentiates via diagnostic monitoring platforms that integrate with public-sector electronic health record systems.
Neurology devices encompass instruments and equipment engineered for the diagnosis, surgical intervention, and therapeutic management of central and peripheral nervous system disorders, typically requiring biocompatible materials, precision-machined components, and signal fidelity thresholds measured in microvolts for electrophysiological applications. Diagnostic imaging equipment leads segment value contribution, reflecting capital-intensive MRI and CT installations at tertiary hospitals, while neurostimulation devices represent the fastest-expanding category as spinal cord and deep brain stimulation protocols gain reimbursement traction for chronic pain and movement disorders. Monitoring devices occupy a mature, replacement-driven position with margin pools concentrated in long-term service contracts and consumable electrode streams.
The South African Health Products Regulatory Authority enforces device registration aligned with ISO 13485 quality management and IEC 60601 electrical safety standards, creating compliance barriers that favor established multinationals with dedicated local regulatory affairs teams. BIS certification requirements for imported electromedical equipment further shape market access timelines and distributor selection criteria. Stakeholders must monitor National Health Insurance procurement rule changes and provincial health department budget allocations to anticipate demand shifts between public tenders and private hospital capital cycles.
Market Dynamics
The South African Health Products Regulatory Authority's tightening of ISO 13485 and IEC 60601 compliance requirements for implantable neurostimulators is restructuring competitive access, favoring multinationals with dedicated local regulatory affairs teams and dedicated quality management infrastructure.
Growth Catalysts
- Neurodiagnostic procurement expansion:Public hospital networks in Gauteng Province are accelerating capital expenditure on MRI and CT installations to address diagnostic backlogs for stroke and epilepsy cases.
- National Health Insurance framework:The policy pivot toward domestically registered devices is creating procurement preference pathways for suppliers with established South African Health Products Regulatory Authority dossiers.
- Deep brain stimulation protocols:Reimbursement traction for movement disorder interventions is driving demand for programmable neurostimulator systems in academic medical centers.
Market Restraints
- BIS certification timelines:Imported electromedical equipment faces extended clearance periods, compressing distributor working capital cycles and delaying hospital commissioning schedules.
- Biocompatible material concentration:Precision-machined components and signal-grade electrodes rely on concentrated Asian supply bases, exposing procurement to shipping cost volatility.
- Microvolt signal fidelity thresholds:Electrophysiological monitoring devices require specialized calibration infrastructure unavailable in most secondary hospitals, limiting addressable market depth.
Strategic Opportunities
- Western Cape province penetration:Cape Town's academic hospital cluster remains underweight in neurointerventional surgical suites relative to Gauteng, presenting greenfield installation potential.
- Electronic health record integration:Diagnostic monitoring platforms that interface directly with public-sector hospital information systems can capture long-term service contract streams.
- Consumable electrode aftermarket:Replacement-driven monitoring device segments offer recurring revenue pools through disposable component supply agreements with provincial health departments.
Industry Challenges
- Neurophysiology technician scarcity:Specialized training programs for intraoperative monitoring and evoked potential interpretation remain limited at South African technical institutions.
- Capital equipment depreciation cycles:Tertiary hospitals face compressed replacement timelines for magnetic resonance imaging systems due to helium supply constraints and coil upgrade requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Neurology Devices Market |
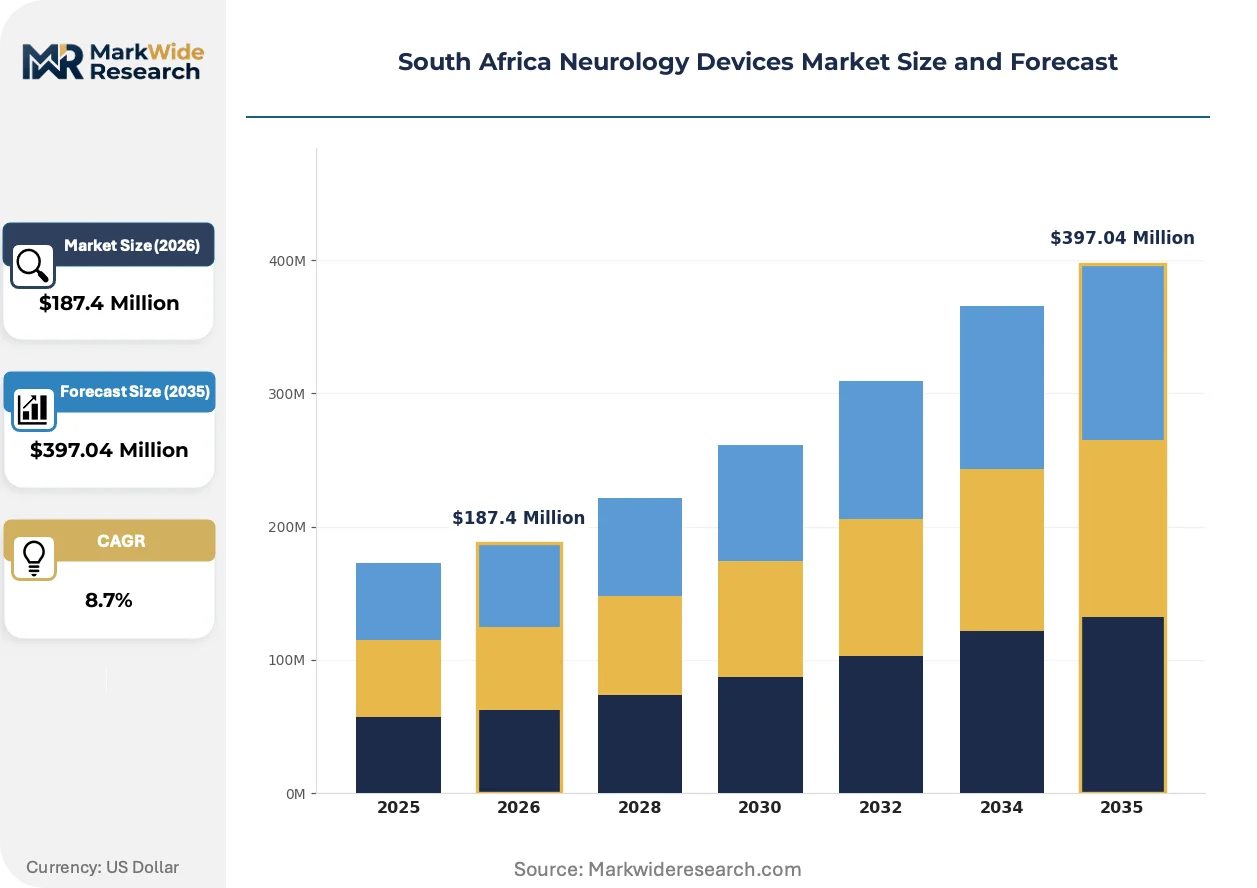
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurostimulation Devices, Diagnostic Imaging Equipment, Surgical Instruments, Monitoring Devices Technology: MRI, CT, EEG, Ultrasound Application: Epilepsy, Chronic Pain Management, Stroke Rehabilitation, Neurodegenerative Disorders End User: Hospitals, Neurology Clinics, Research Institutes, Outpatient Centers |
| Companies Covered | B Braun Melsungen AG, Stryker Corporation, Medtronic PLC, Abbott Laboratories, Johnson and Johnson, Nihon Kohden Corporation, Smith & Nephew, Integra LifeSciences Corporation, GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Neurology Devices Market Evolving Landscape
Neurology device architectures in South Africa are pivoting toward interoperability mandates and signal processing miniaturization, with procurement criteria increasingly weighting integration capabilities alongside standalone performance specifications.
Implantable pulse generators with closed-loop sensing capabilities are converging with cloud-based patient monitoring platforms, enabling remote parameter adjustment for chronic pain management. Private hospital groups in Johannesburg are piloting these systems to reduce specialist consultation frequency. The convergence is compressing service delivery costs while extending device lifecycle value capture for manufacturers through subscription telemetry models.
The South African Health Products Regulatory Authority's alignment with ISO 13485 quality management standards is elevating documentation requirements for neurostimulator registration dossiers. Local distributors now face extended technical file preparation periods before market authorization. Neurodiagnostic imaging equipment imports encounter the most significant procedural friction, with electrical safety testing protocols adding three to six months to typical clearance timelines.
Provincial health departments are consolidating neurology device procurement through centralized tender frameworks, displacing hospital-level purchasing autonomy. The Western Cape and Gauteng health departments have established dedicated neurosurgical capital committees. This concentration is most visible in Pretoria's academic hospital cluster, where multi-year framework agreements now govern magnetic resonance imaging coil and neurosurgical instrument replenishment cycles.
South Africa Neurology Devices Market Segmentation
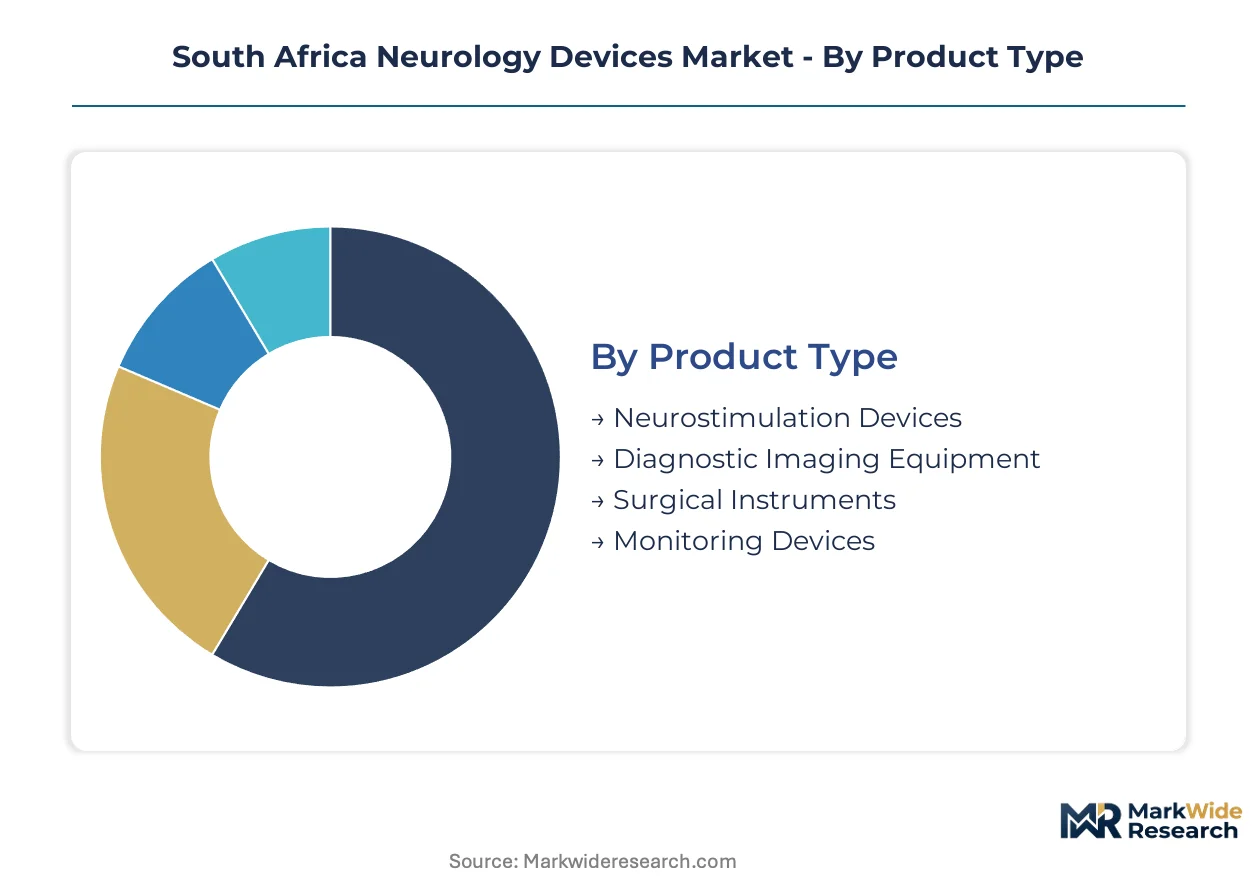
Neurology device procurement in South Africa follows distinct technical and clinical pathways. Hospital capital committees evaluate segments against reimbursement schedules, regulatory registration status, and provincial budget cycles.
Product Type:
Capital allocation decisions hinge on procedure volume thresholds and replacement cycles at tertiary facilities.
- Neurostimulation Devices:Implantable pulse generators with closed-loop sensing capabilities enable remote parameter adjustment for chronic pain and movement disorders. Academic medical centers in Johannesburg and Pretoria are expanding deep brain stimulation programs as reimbursement protocols solidify for Parkinson's disease interventions.
- Diagnostic Imaging Equipment:MRI and CT systems require helium infrastructure and specialized coil arrays for neurovascular and functional brain imaging. Gauteng Province's public hospital networks are prioritizing these installations to address diagnostic backlogs for stroke and epilepsy cases.
- Surgical Instruments:Precision-machined tools for neurotrauma and microvascular procedures.
- Monitoring Devices:Electrophysiological systems with microvolt signal fidelity for intraoperative and intensive care settings.
Volume sits with Diagnostic Imaging Equipment; growth tilts toward Neurostimulation Devices.
Technology:
Procurement specifications vary by clinical setting and signal processing requirements.
- MRI:High-field systems with neurovascular coils dominate tertiary hospital procurement. Western Cape academic hospitals remain underweight in neurointerventional MRI suites relative to Gauteng, creating installation gaps.
- CT:Rapid acquisition systems for emergency stroke protocol imaging.
- EEG:Electroencephalography platforms with long-term monitoring capabilities for epilepsy surgical evaluation.
- Ultrasound:Transcranial Doppler systems for cerebrovascular hemodynamic assessment.
Capital concentration favors MRI; EEG gains share fastest through ambulatory monitoring expansion.
Application:
Reimbursement traction and disease prevalence patterns shape demand distribution across clinical indications.
- Epilepsy:Surgical evaluation protocols require integrated EEG, MRI, and neurostimulation device coordination. Academic centers in Pretoria are consolidating multi-modal diagnostic pathways for refractory case management.
- Chronic Pain Management:Spinal cord stimulation systems with rechargeable pulse generators.
- Stroke Rehabilitation:Neuroplasticity-focused interventions combining diagnostic imaging with functional electrical stimulation.
- Neurodegenerative Disorders:Deep brain stimulation targeting Parkinson's and essential tremor patient populations.
Procedure volume clusters in Epilepsy; Chronic Pain Management shows the steepest expansion trajectory.
End User:
Facility type determines procurement channel access and service contract structures.
- Hospitals:Tertiary public hospitals in Gauteng and Western Cape provinces anchor capital equipment procurement through centralized tender frameworks. Multi-year agreements now govern coil replenishment and neurosurgical instrument cycles.
- Neurology Clinics:Specialized outpatient facilities concentrated in Johannesburg and Cape Town.
- Research Institutes:Academic medical centers with clinical trial infrastructure for neurostimulator protocol development.
- Outpatient Centers:Ambulatory settings for diagnostic monitoring and post-implant follow-up.
Equipment value concentrates in Hospitals; service contract growth tilts toward Outpatient Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johannesburg and Pretoria anchor South Africa's neurology device demand through Gauteng Province's dense concentration of academic medical centers and tertiary public hospitals.
Gauteng Province
Diagnostic imaging procurement dominates capital expenditure as public hospital networks address stroke and epilepsy backlogs. The South African Health Products Regulatory Authority's ISO 13485 alignment creates registration barriers that favor established multinationals with local regulatory affairs teams. Pretoria's academic hospital cluster now operates under multi-year framework agreements governing MRI coil replenishment and neurosurgical instrument cycles.
Western Cape Province
Cape Town's academic hospital cluster remains underweight in neurointerventional surgical suites relative to Gauteng, presenting greenfield installation potential for specialized equipment. Provincial health department centralized tender frameworks are displacing hospital-level purchasing autonomy. The province's neurosurgical capital committees are consolidating neurology device procurement through dedicated procurement pathways.
KwaZulu-Natal Province
Durban's tertiary facilities are expanding electrophysiological monitoring capabilities for intraoperative applications. BIS certification requirements for imported electromedical equipment extend clearance timelines, compressing distributor working capital cycles. The province's secondary hospitals face limited addressable market depth due to scarce specialized calibration infrastructure for microvolt signal fidelity thresholds.
Eastern Cape Province
Port Elizabeth and East London hospital networks are prioritizing neurotrauma surgical instrument portfolios as road injury caseloads drive emergency intervention demand. National Health Insurance procurement rule changes are shifting demand between public tenders and private hospital capital cycles. The province's neurology clinic density remains concentrated in metropolitan corridors with limited rural penetration.
South Africa Neurology Devices Market Competitive Landscape
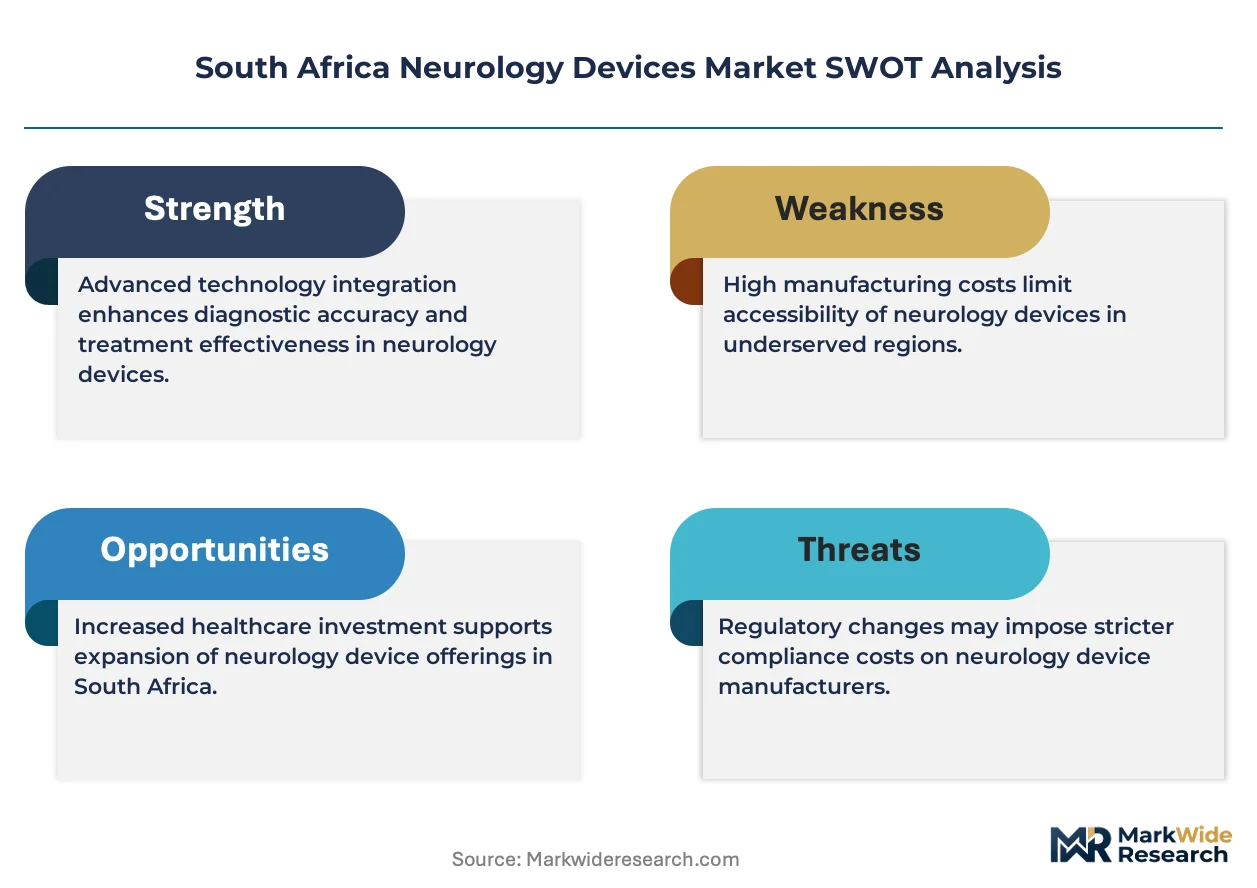
The competitive structure tilts toward multinational conglomerates with dedicated regulatory infrastructure. Established players with ISO 13485 quality management systems and local regulatory affairs teams capture preference pathways under National Health Insurance frameworks. Three archetypes dominate: diversified medical technology conglomerates with broad surgical portfolios, specialized neurodiagnostic equipment manufacturers with imaging system expertise, and implantable device specialists with neurostimulation programming capabilities. Competitive moves concentrate on strategic partnerships with provincial health departments and portfolio diversification into closed-loop sensing systems.
Among diversified medical technology conglomerates, Medtronic PLC and Stryker Corporation exemplify archetypes with established South African Health Products Regulatory Authority dossiers. Abbott Laboratories occupies a position representing diagnostic monitoring platform specialists with public-sector electronic health record integration capabilities. These three anchors demonstrate how regulatory registration depth and hospital channel access determine competitive positioning under tightening compliance requirements.
| Leading Market Players |
|---|
| B Braun Melsungen AG |
| Stryker Corporation |
| Medtronic PLC |
| Abbott Laboratories |
| Johnson and Johnson |
| Nihon Kohden Corporation |
| Smith & Nephew |
| Integra LifeSciences Corporation |
| GE Healthcare |
| Others |
Value Network & Pricing Analysis
Multinational conglomerates with dedicated South African regulatory affairs teams anchor procurement pricing through long-term service contracts that bundle capital equipment with consumable replenishment cycles, compressing margin pools for distributors lacking ISO 13485 quality management infrastructure. The South African Health Products Regulatory Authority's IEC 60601 electrical safety requirements create compliance cost tiers that stratify vendor access to provincial health department tenders.
Pricing Analysis
Value-based pricing anchored to diagnostic throughput and device uptime governs MRI and CT procurement at tertiary hospitals. Pricing stratifies across premium-tier multinationals with established dossiers, mid-tier regional suppliers with partial registration coverage, and economy-tier distributors dependent on gray-market import channels. Cost compression in the economy tier intensifies because BIS certification timelines extend working capital cycles. Public hospital procurement committees exhibit highest price sensitivity, while private academic medical centers prioritize integration capabilities over unit cost.
Supply Chain Analysis
Regional distribution centers in Johannesburg and Cape Town operate hub-and-spoke patterns feeding provincial hospital networks. Precision-machined neurosurgical components and signal-grade electrodes draw from concentrated manufacturing bases in Germany, Japan, and Switzerland. Single-source vulnerability pervades the helium supply chain for MRI magnet cooling. Distribution runs through authorized dealer networks with exclusive territory agreements rather than open-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Africa neurology devices market functions as a cost-of-compliance story where ISO 13485 certification creates a barrier-to-entry moat favoring established multinationals with dedicated local quality management infrastructure.
For Market Incumbents: Deploy regulatory dossier depth as the primary defensive lever. Extend multi-year framework agreements with Gauteng and Western Cape provincial health departments to lock out emerging competitors. Counter margin pressure from centralized tender consolidation by deepening software companion development for diagnostic monitoring platforms that interface with public-sector electronic health record systems. For New Entrants and Emerging Players: The premium-economy price gap in electrophysiological monitoring devices opens viable entry pathways. Target KwaZulu-Natal and Eastern Cape secondary hospitals underserved by specialized calibration infrastructure. Capture initial share through consumable electrode supply agreements rather than capital equipment sales, building service relationships that mature into diagnostic platform installations. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap distributors with established South African Health Products Regulatory Authority relationships in the Western Cape. Long-term viability hinges on National Health Insurance procurement rule implementation accelerating domestic registration requirements. Monitor provincial health department budget allocation signals as the critical inflection indicator for demand shifts between public tender and private hospital capital cycles.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | SAHPRA registration pathways open preferential procurement access under National Health Insurance frameworks. |
| Electronic Health Record Integration | Diagnostic monitoring platforms capturing long-term service contracts with public hospital information systems. |
| Consumable Electrode Supply Agreements | Recurring revenue streams from disposable component replenishment cycles with provincial health departments. |
| Western Cape Neurointerventional Suite Expansion | Greenfield installation potential in Cape Town's academic hospital cluster relative to Gauteng saturation. |
| Closed-Loop Sensing Platform Development | Remote parameter adjustment capabilities enabling subscription telemetry models for chronic pain management. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contracts, and CMS-equivalent South African health expenditure records underwrites the qualitative findings. Primary interviews with biomedical engineers, hospital purchasing committee members, and provincial health department procurement officers combined with secondary validation from SAHPRA registration filings, customs import records, and academic medical center capital budget disclosures. Bottom-up equipment installation tracking and top-down provincial health expenditure analysis provided cross-verification.
Rate-of-change decomposition across neurostimulation device adoption curves, diagnostic imaging replacement cycles, and monitoring device upgrade patterns structured the analytical framework. Segmentation dimensions modeled include product type, technology platform, clinical application, and end-user facility tier. CAGRs were derived from procedure volume trajectories, reimbursement schedule adjustments, and capital equipment depreciation schedules. Forecast inputs incorporated neurophysiology technician training pipeline constraints and helium supply availability for MRI infrastructure.
Inputs from hospital procurement databases and provincial tender announcements were available through the study window; gaps in private hospital capital cycle timing introduce uncertainty bands around private-sector demand projections. Forecasts reflect documented assumptions regarding National Health Insurance implementation pace and SAHPRA registration backlog resolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United States Ultrasound Devices Market
Medical Devices
US Clear Aligners Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
US Anti-Blue Ray Myopia Lenses Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Digital Sphygmomanometer Market
Medical Devices
Injectable Drug Delivery Market
Medical Devices
Retinal Implant Market
Medical Devices
Auto-Transfusion Systems Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
United Kingdom Minimally Invasive Surgery Devices Market
Medical Devices
Breast Biopsy Localization Wire Market
Medical Devices
Global Defibrillators Market
Medical Devices
Global Tympanostomy Products Market
Medical Devices
Europe Breast Implant Market
Medical Devices
Artificial Spine Discs Market