
 Corneal Surgery Devices Market | 2026-2036
Corneal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Corneal Surgery Devices Market Analysis
Femtosecond laser platforms is rebalancing cost structures across corneal surgery workflows by displacing mechanical microkeratomes in premium refractive procedures. Alcon leverages its integrated diagnostic-to-surgical platform to sustain pricing power in LASIK and cataract suites. Ziemer Ophthalmic Systems specializes in compact femtosecond architectures that anchor its position in high-throughput eye clinics across Europe and Asia.
Corneal surgery devices encompass precision instruments and energy-delivery systems engineered to reshape, replace, or diagnose corneal tissue with micron-level accuracy, typically operating at ultraviolet excimer wavelengths of 193 nm for photoablative procedures. These devices serve ophthalmic surgeons performing vision correction, transplantation, and diagnostic assessments where tissue preservation and optical outcomes determine clinical value. Laser systems command the dominant revenue share due to capital intensity and recurring consumable attach rates, while diagnostic instruments represent the fastest-expanding margin pool as preoperative topography and tomography become standard of care. Surgical blades retain volume significance in emerging markets where laser adoption remains constrained by reimbursement structures and capital budgets.
FDA 510(k) clearances and CE marking under the EU MDR shape product development timelines and commercial access trajectories for manufacturers serving the United States and European markets. ISO 13485 quality management certification operates as a baseline threshold for supplier qualification by hospital procurement committees and group purchasing organizations. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled diagnostic overlays and the EU AI Act's risk classification for autonomous surgical planning algorithms.
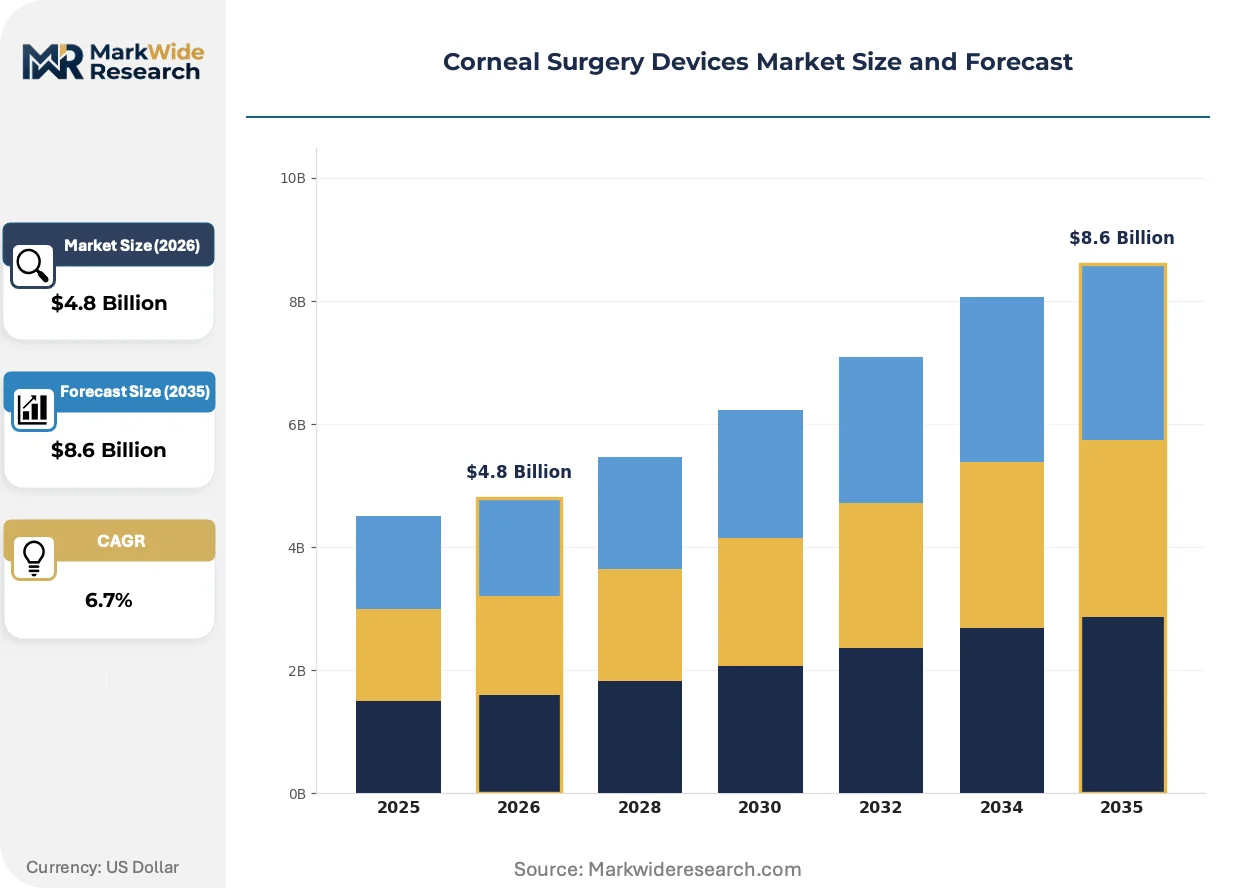
Market Dynamics
Femtosecond laser platforms are consolidating surgical workflows by displacing mechanical microkeratomes, compressing capital deployment timelines for ambulatory surgical centers and redistributing margin pools toward integrated diagnostic-surgical ecosystems.
Growth Catalysts
- Outpatient volume surge:Ambulatory surgical centers in the United States and Germany are expanding refractive procedure capacity as same-day discharge protocols reduce hospital bed dependency.
- EU MDR compliance pathways:Streamlined CE marking under the Medical Device Regulation is accelerating commercial access for next-generation excimer laser systems across European markets.
- Topography-guided ablation:Wavefront-optimized treatment planning is expanding addressable patient pools beyond conventional myopia correction into higher-order aberration management.
Market Restraints
- Capital intensity barrier:Femtosecond laser platforms require $500,000-$800,000 upfront investment, constraining adoption in Indian and Brazilian clinics with limited equipment financing access.
- Consumable supply concentration:Single-use patient interfaces and suction rings for laser systems depend on a narrow supplier base concentrated in German and Swiss precision manufacturing clusters.
- Reimbursement compression:CMS coding revisions in the United States are narrowing coverage differentials between premium femtosecond-assisted and conventional blade-based procedures.
Strategic Opportunities
- Indian tier-2 city expansion:Underpenetrated markets in Hyderabad, Chennai, and Pune present whitespace for compact laser platforms targeting medical tourism and domestic middle-class demand.
- AI-enabled surgical planning:Convergence of corneal topography with machine learning algorithms is creating autonomous treatment parameter optimization under emerging FDA guidance frameworks.
- Direct-to-consumer diagnostic channels:Refractive surgery chains in Brazil are deploying in-mall topography screening to compress patient acquisition funnels and bypass traditional ophthalmology referral networks.
Industry Challenges
- Femtosecond engineer scarcity:Laser physicist and biomedical engineer talent pools are insufficient to support maintenance and calibration demands across rapidly expanding clinic networks.
- ISO 13485 certification timelines:Quality management system audits for new device variants are extending 14-18 months, delaying product launches and freezing R&D amortization schedules.
- Interoperability fragmentation:Diagnostic data formats from competing topographers and tomographers lack standardization, forcing clinics to maintain redundant software ecosystems or manual data translation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corneal Surgery Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Systems, Surgical Blades, Sutures, Diagnostic Instruments Technique: LASIK, PRK, Cataract Surgery, Keratoplasty End User: Hospitals, Eye Clinics, Ambulatory Surgical Centers, Private Practices Application: Vision Correction, Corneal Transplantation, Refractive Surgery, Diagnostic Procedures |
| Companies Covered | Carl Zeiss, Rayner, Alcon, Ziemer Ophthalmic Systems, Hoya Corporation, Johnson & Johnson, Abbott, Topcon Corporation, Bausch + Lomb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corneal Surgery Devices Market Emerging Trajectories
Corneal surgery workflows are converging around closed-loop diagnostic-surgical ecosystems that compress preoperative planning cycles and reduce manual intervention points. Three interconnected developments are restructuring competitive positioning.
Smile (Small Incision Lenticule Extraction) technology is integrating femtosecond lenticule creation with single-step extraction, eliminating excimer laser dependency entirely. High-volume refractive chains in Japan and South Korea are adopting Smile platforms to reduce per-procedure capital depreciation and consumable costs. This integration is compressing the addressable market for standalone excimer systems while expanding margin capture for all-in-one femtosecond vendors.
The EU AI Act's risk classification framework is mandating clinical validation protocols for autonomous surgical planning algorithms before CE marking. Manufacturers must now submit algorithmic transparency documentation and real-world performance datasets to notified bodies. Diagnostic platform vendors with integrated AI modules face 12-24 month timeline extensions, favoring established players with regulatory affairs infrastructure over venture-stage entrants.
Japanese ophthalmology groups are unbundling after-sales service contracts from capital equipment purchases, shifting toward third-party maintenance providers and independent biomedical engineering networks. This disintermediation is pressuring OEM service revenue streams while creating aftermarket opportunities for specialized calibration and laser chamber refurbishment firms concentrated in Osaka and Nagoya manufacturing corridors.
Corneal Surgery Devices Market Segmentation
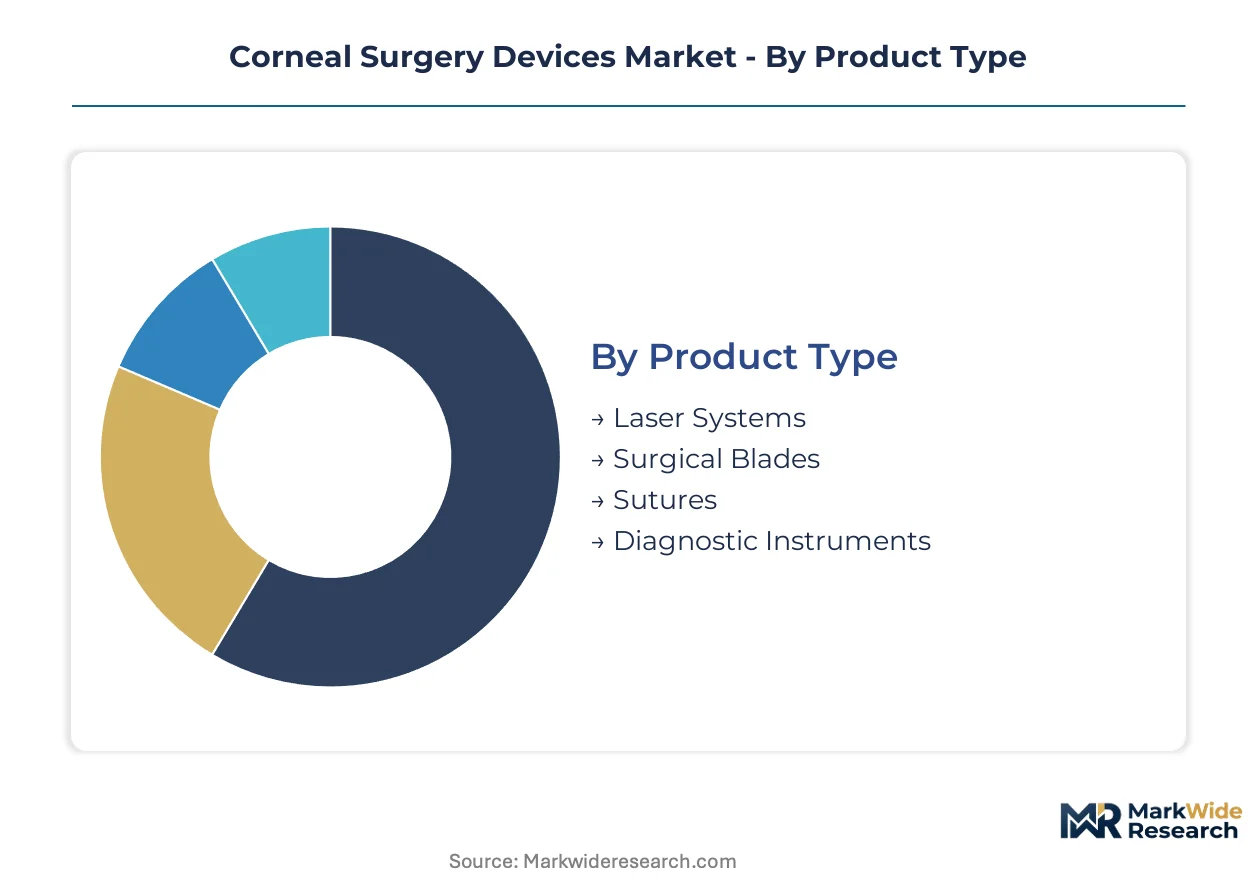
Segmentation in corneal surgery devices reveals how capital deployment, reimbursement pathways, and clinical workflow integration determine purchasing decisions across provider types. Understanding these divisions exposes where margin pools concentrate and which technology transitions will reshape competitive positioning.
Product Type:
Capital intensity varies dramatically across this category, with femtosecond and excimer laser platforms demanding $500,000-$800,000 upfront investment while consumable-heavy segments operate on radically different cash flow profiles.
- Laser Systems:Femtosecond and excimer platforms deliver tissue modification through photoablation at 193 nm ultraviolet wavelengths with micron-level precision. Demand clusters in ambulatory surgical centers across the United States and Germany where same-day discharge protocols maximize equipment utilization rates. These systems generate recurring revenue through single-use patient interfaces and suction rings.
- Diagnostic Instruments:Corneal topographers and tomographers map anterior segment architecture through Scheimpflug imaging and Placido disc reflection analysis. Japanese and South Korean eye chains are deploying these systems in direct-to-consumer screening locations to compress patient acquisition funnels. Preoperative measurement standardization is driving replacement cycles.
- Surgical Blades:Diamond and stainless steel microkeratomes maintain volume significance in Indian and Brazilian markets where laser capital constraints persist.
- Sutures:Nylon and polyester monofilament configurations serve penetrating keratoplasty and lamellar transplantation procedures with limited technology differentiation.
Laser Systems absorb the bulk of installed capacity; Diagnostic Instruments are expanding most quickly.
Technique:
Procedure selection tracks directly to corneal thickness profiles, refractive error magnitude, and surgeon training pathways established during residency.
- LASIK:Femtosecond laser-created flaps combined with excimer stromal ablation remain the dominant volume procedure in premium refractive markets. German and Japanese high-throughput clinics favor this technique for rapid visual recovery and established reimbursement coding.
- PRK:Surface ablation without flap creation serves thin cornea patients and military aviation candidates where flap trauma risk is unacceptable. Demand persists in United States military treatment facilities and correctional vision programs.
- Cataract Surgery:Femtosecond laser-assisted capsulotomy and lens fragmentation integrates with premium intraocular lens implantation workflows.
- Keratoplasty:Penetrating and deep anterior lamellar techniques address corneal dystrophy and post-infectious scarring through full or partial thickness replacement.
LASIK captures the majority of refractive procedure volume; PRK maintains defensive positioning in specialized indications.
End User:
Procurement authority and equipment financing access diverge sharply between consolidated hospital systems and fragmented private practice structures.
- Ambulatory Surgical Centers:Dedicated ophthalmology facilities in the United States concentrate refractive volume through streamlined same-day protocols and direct consumer marketing. These centers achieve femtosecond laser depreciation through high procedure throughput.
- Eye Clinics:Multispecialty ophthalmology groups in Japan and South Korea are unbundling service contracts from capital purchases, shifting maintenance to third-party biomedical engineering networks.
- Hospitals:Academic medical centers maintain keratoplasty programs and complex corneal pathology referral bases with lower equipment utilization rates.
- Private Practices:Solo and small group ophthalmologists in Indian tier-2 cities represent whitespace for compact laser platforms targeting medical tourism flows.
Ambulatory Surgical Centers deploy capital most aggressively; Eye Clinics are diversifying service arrangements fastest.
Application:
Clinical indication segmentation separates elective cash-pay procedures from reimbursed medical necessity treatments with fundamentally different pricing power.
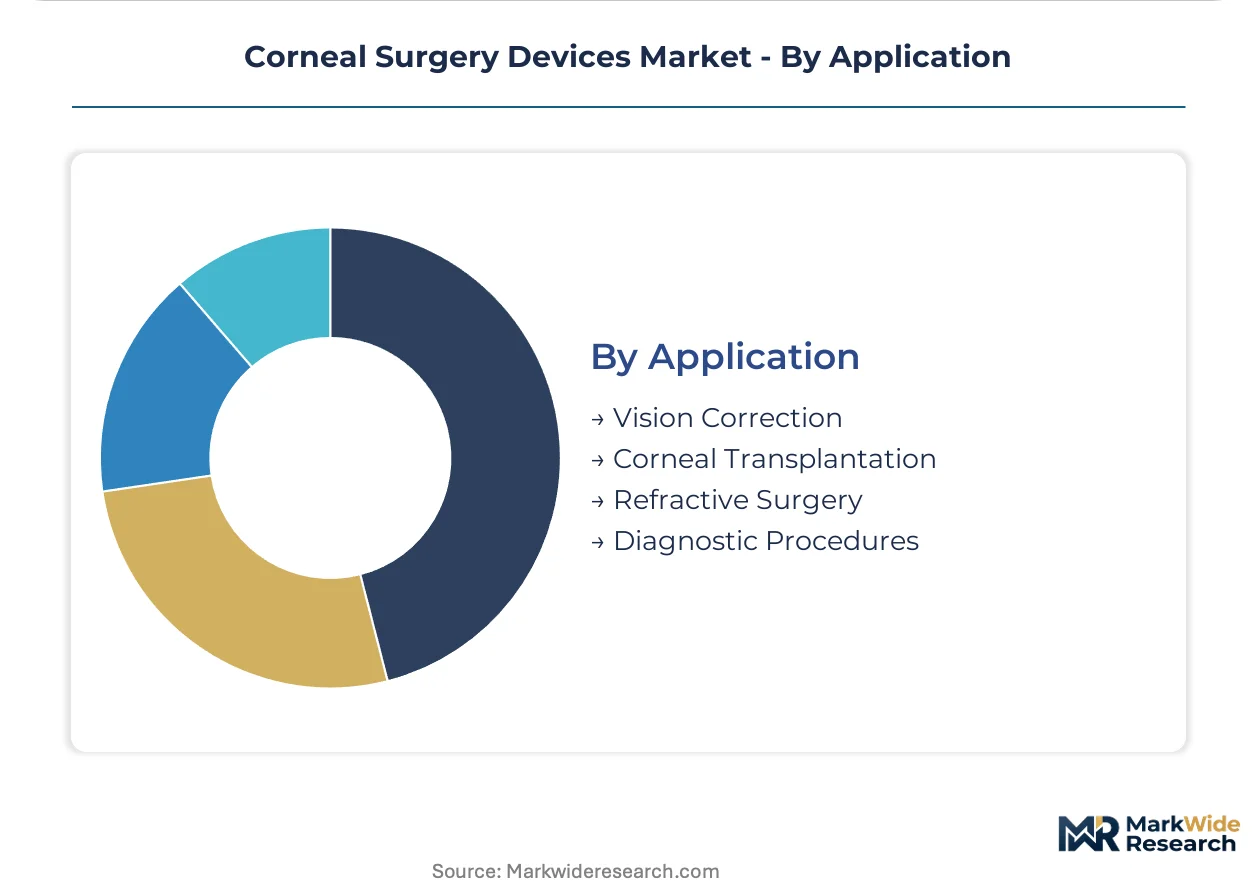
- Vision Correction:Myopia, hyperopia, and astigmatism modification through laser ablation constitutes the largest addressable patient pool. Brazilian refractive chains are deploying in-mall topography screening to bypass traditional ophthalmology referral networks.
- Refractive Surgery:Presbyopia correction and higher-order aberration management expand beyond conventional spherical equivalent targets. Wavefront-optimized treatment planning is penetrating Japanese and South Korean markets.
- Corneal Transplantation:Endothelial keratoplasty and penetrating procedures address Fuchs dystrophy and pseudophakic bullous keratopathy with tissue availability constraints.
- Diagnostic Procedures:Preoperative screening and postoperative monitoring generate recurring instrument utilization with lower per-procedure revenue but higher margin attach rates.
Vision Correction commands the largest patient flow; Refractive Surgery is climbing the fastest as presbyopia-correcting platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Hyderabad and Shenzhen concentrate femtosecond laser assembly operations through tax-advantaged manufacturing corridors. These zones attract precision optics suppliers and biomedical engineering talent pools.
United States
Ambulatory surgical centers in Florida and Texas drive femtosecond laser depreciation through high-volume refractive throughput. FDA 510(k) clearance pathways for excimer laser upgrades compress product launch timelines. Dallas-Fort Worth and Miami metropolitan clusters host consolidated ophthalmology chains unbundling service contracts from capital purchases.
Germany
Baden-Württemberg precision manufacturing clusters supply single-use patient interfaces and suction rings to global laser system vendors. EU MDR streamlined CE marking accelerates next-generation excimer platform commercial access. Stuttgart and Karlsruhe industrial corridors concentrate femtosecond laser physicist talent pools for maintenance networks.
Japan
Kanto region eye chains deploy Smile platforms to reduce per-procedure capital costs and eliminate excimer dependency. METI medical device reimbursement frameworks favor same-day discharge protocols. Tokyo and Osaka metropolitan areas unbundle after-sales service contracts toward third-party biomedical engineering networks.
India
Hyderabad and Chennai medical tourism corridors present whitespace for compact laser platforms targeting domestic middle-class demand. CDSCO medical device registration timelines shape import substitution strategies for diagnostic instruments. Telangana and Tamil Nadu special economic zones concentrate femtosecond laser assembly through precision optics supplier ecosystems.
Brazil
São Paulo and Rio de Janeiro refractive chains deploy in-mall topography screening to bypass traditional ophthalmology referral networks. ANVISA regulatory pathways for imported laser systems constrain capital deployment timelines. Southeast metropolitan clusters anchor direct-to-consumer diagnostic channel expansion for patient acquisition compression.
Corneal Surgery Devices Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated diagnostic-surgical platform vendors capturing premium pricing in developed markets while component suppliers serve emerging market cost constraints. The vendor base concentrates around three strategic archetypes: capital equipment OEMs with recurring consumable revenue streams, precision optics component specialists, and refractive surgery chain operators with captive equipment demand. M&A activity targets diagnostic software capabilities and femtosecond laser maintenance networks. Geographic expansion into Indian tier-2 cities and Brazilian medical tourism corridors dominates strategic planning cycles.
Within the integrated platform tier, Alcon and Ziemer Ophthalmic Systems exemplify divergent scale strategies. Alcon anchors the premium capital equipment segment through diagnostic-to-surgical workflow integration. Ziemer Ophthalmic Systems occupies a compact architecture specialist position targeting high-throughput European and Asian eye clinics. Carl Zeiss represents the precision optics heritage archetype with embedded femtosecond laser expertise.
| Leading Market Players |
|---|
| Carl Zeiss |
| Rayner |
| Alcon |
| Ziemer Ophthalmic Systems |
| Hoya Corporation |
| Johnson & Johnson |
| Abbott |
| Topcon Corporation |
| Bausch + Lomb |
| Others |
Supply Flow & Price Mechanics
Procurement committee consolidation across United States ambulatory surgical centers is compressing vendor margins and forcing laser OEMs to unbundle service contracts from capital sales, which fragments revenue recognition and elevates financing risk for precision optics suppliers.
Pricing Analysis
Short lead-time premiums for femtosecond laser patient interfaces and suction rings command 15-25% markups over standard delivery schedules, while spot inventory of excimer laser consumables trades at discounts in European secondary markets. Pricing stratifies across FDA-cleared premium tiers, CE-marked standard configurations, and Indian market economy variants lacking full diagnostic integration. Cost compression in economy-tier surgical blades intensifies as domestic Indian manufacturers scale diamond microkeratome production. Ambulatory surgical centers exhibit acute price sensitivity to per-procedure consumable costs, whereas academic medical centers prioritize capital equipment reliability over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss precision manufacturing clusters for femtosecond laser optical components and ultra-fast pulse generation modules. Supply concentrates in Baden-Württemberg for patient interface polymers, Basel for suction ring elastomers, and Osaka for laser chamber ceramics. Raw material dependencies span synthetic sapphire for optical windows, medical-grade titanium for applanation lenses, and fluoropolymer coatings for biocompatibility. Tariff exposure on imported excimer laser gas mixtures threatens margin stability for Asian clinic operators. Distribution runs through authorized dealer networks in developed markets and direct OEM relationships in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Femtosecond laser physicist scarcity props pricing power for maintenance-capable vendors, creating a supply-constrained environment where service contract unbundling remains incomplete.
For Market Incumbents: Deepen backward integration into precision optics manufacturing to capture margin pools currently flowing to German and Swiss component suppliers. Lock in exclusive service contracts with high-throughput Japanese eye chains before third-party biomedical engineering networks mature. Alcon and Ziemer must defend against Smile platform commoditization by embedding AI-enabled treatment planning into diagnostic-surgical workflows. For New Entrants and Emerging Players: The price-point gap between premium integrated platforms and economy-tier surgical blades creates entry space for compact femtosecond architectures targeting Indian tier-2 cities. Hyderabad and Chennai medical tourism corridors offer the most penetrable whitespace. Brazilian refractive chains' direct-to-consumer diagnostic channels provide a proven go-to-market template for bypassing traditional ophthalmology referral networks. For Investors and Strategic Acquirers: The window for entry favors diagnostic software specialists with FDA 510(k) clearance pathways and CE marking experience under EU MDR. Long-term viability hinges on regulatory affairs infrastructure capable of navigating autonomous surgical planning algorithm validation. Watch for ISO 13485 certification timeline extensions as the inflection signal for distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR streamlined procedures accelerate excimer laser platform commercial access across Stuttgart and Karlsruhe corridors. |
| Hospital System Partnership | United States ambulatory surgical center consolidation demands integrated diagnostic-surgical procurement contracts with GPOs. |
| Software Companion Development | AI-enabled topography-guided ablation modules require FDA guidance compliance for autonomous treatment parameter optimization. |
| Reimbursement Strategy | CMS coding revisions narrow coverage differentials between femtosecond-assisted and blade-based procedures in Florida and Texas markets. |
| Geographic Expansion | Compact laser platform deployment in Telangana and Tamil Nadu special economic zones targets domestic Indian middle-class demand. |
Methodological Framework
Multi-period observation of femtosecond laser installed base depreciation rates and excimer system replacement cycles anchored the trend analysis, supplemented by interviews with ophthalmic surgeons, ambulatory surgical center procurement managers, biomedical engineers, and GPO contracts specialists. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement schedules, and hospital procurement committee records. Bottom-up equipment shipment tracking and top-down refractive procedure volume estimates were triangulated against capital expenditure disclosures.
Input-output matrices mapped laser system sales to consumable attach rates across product type, technique, end user, and application dimensions throughout the forecast period. CAGRs were derived from equipment utilization modeling and procedure volume elasticity to capital deployment. Industry-specific forecast inputs incorporated femtosecond physicist labor pool constraints and ISO 13485 certification pipeline backlogs.
Underlying measurement precision varies by segment; laser systems and diagnostic instruments carry tighter precision than surgical blades and sutures due to concentrated vendor reporting. Forecasts reflect assumptions on EU AI Act implementation timelines and CDSCO registration pathway efficiency. Deviation in FDA guidance on autonomous surgical planning algorithms would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spectacle Lens Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market
Medical Devices
Portable OT Light Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Global Blood Processing Devices and Consumables Market
Medical Devices
Ultrasound Stimulator Market
Medical Devices
Bioresorbable Coronary Scaffolds Market
Medical Devices
US Stethoscope Market
Medical Devices
Global Cosmetic Contact Lens Market
Medical Devices
Global Artificial Skin Market
Medical Devices
Global Vitreoretinal Surgery Devices Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Global Embolic Protection Device Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
Sensor Based Smart Catheters Market