
 Korea Continuous Glucose Monitoring Devices Market | 2026-2036
Korea Continuous Glucose Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Korea Continuous Glucose Monitoring Devices Market Foresight
Domestic manufacturing capacity for biosensor substrates in Korea is hardening as local suppliers scale cleanroom production for medical-grade electrochemical components. Dexcom, Inc. anchors its Korea position through deep distributor partnerships with major hospital procurement consortia. Abbott Laboratories differentiates via integrated software ecosystems that connect glucose data directly to electronic health records at leading medical centers. Medtronic competes on algorithm sophistication, leveraging predictive hypoglycemia alerts that reduce clinical intervention rates in tertiary care settings.
Continuous glucose monitoring devices are wearable electrochemical systems that measure interstitial glucose concentrations through enzymatic reactions at the sensor-tissue interface, typically sampling every one to five minutes and transmitting data to receivers or smartphones for real-time glycemic management. The primary purpose is to replace or supplement fingerstick blood glucose testing with automated, longitudinal glucose profiles that enable precise insulin dosing and metabolic trend analysis. Real-time monitoring systems dominate hospital procurement budgets due to reimbursement alignment with intensive insulin therapy protocols, while flash glucose monitoring captures expanding homecare share through patient-pay models that bypass prior authorization requirements. Wearable sensors incorporating intradermal platforms represent the fastest-growing technology segment as manufacturers reduce insertion trauma and extend sensor wear duration beyond fourteen days.
MFDS regulates CGM devices as Class III or IV medical products under the Medical Device Act, requiring clinical validation of accuracy against laboratory reference methods before market authorization. The Ministry of Health and Welfare's National Health Insurance Service determines reimbursement tiers, directly shaping patient access economics and manufacturer pricing strategies. MFDS alignment with international standards from ISO and IEC facilitates parallel regulatory submissions for Korean manufacturers seeking export markets. Stakeholders must monitor evolving reimbursement criteria for non-intensive Type 2 diabetes populations, as coverage expansion decisions will reshape addressable volume and competitive positioning across homecare and clinic channels.
Market Dynamics
MFDS reimbursement tier revisions for non-intensive Type 2 diabetes populations are compressing manufacturer pricing power while expanding addressable patient volume across Seoul's hospital networks. This regulatory pivot forces competitors to recalibrate channel economics between institutional procurement and direct-to-patient models.
Growth Catalysts
- MFDS Streamlined Approval Pathways:The regulator's accelerated review framework for wearable sensor platforms reduces time-to-market for next-generation electrochemical biosensors. Korean manufacturers leverage this to fast-track fourteen-day wear duration devices.
- Hospital Procurement Consortium Expansion:Seoul and Busan hospital systems are embedding CGM protocols into routine diabetes management. This institutional pull creates predictable demand volumes for real-time monitoring systems.
- Intradermal Platform Miniaturization:Advanced micro-needle array fabrication is reducing insertion trauma and extending sensor longevity. Cleanroom-scale domestic production of medical-grade substrates supports cost-competitive manufacturing.
Market Restraints
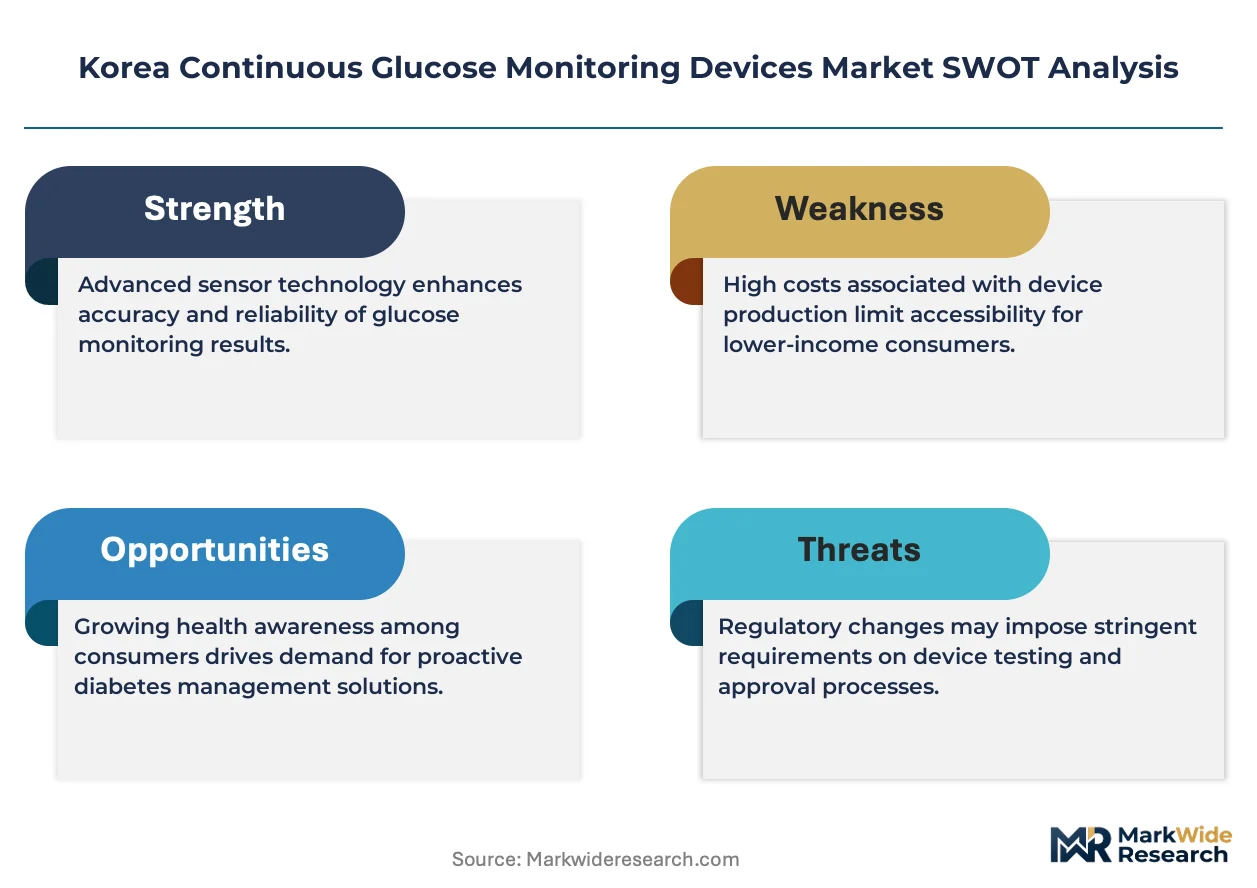
- Reimbursement Coverage Gaps:National Health Insurance Service restrictions on homecare CGM for non-insulin-dependent patients limit patient-pay market penetration. Out-of-pocket costs deter price-sensitive demographics in secondary cities.
- Biosensor Substrate Supply Concentration:Domestic cleanroom capacity for medical-grade electrochemical components remains concentrated among three Seoul-based suppliers. Input bottlenecks constrain rapid scaling of sensor production.
- Accuracy Validation Burden:MFDS Class III/IV clinical validation requirements against laboratory reference methods impose lengthy pre-market timelines. Small domestic manufacturers lack resources for parallel international submissions.
Strategic Opportunities
- Daegu-Gwangju Corridor Penetration:Secondary metropolitan hospital networks outside Greater Seoul Area remain underpenetrated for CGM integration. Regional diabetes clinics present whitespace for flash glucose monitoring adoption.
- Software-EHR Convergence:Direct glucose data integration with electronic health records at leading medical centers creates platform stickiness. Vendors bundling analytics dashboards capture multi-year procurement contracts.
- PLI Scheme Alignment:Korean government production-linked incentives for medical device manufacturing reduce capital intensity for domestic sensor fabrication. Local players expand backward integration into enzymatic reagent production.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Specialized expertise in enzymatic sensor design and signal processing algorithms remains concentrated among senior researchers at KAIST and Seoul National University. Manufacturers compete aggressively for this limited talent pool.
- Legacy Glucometer Infrastructure Lock-in:Existing hospital investments in point-of-care blood glucose testing systems create switching friction. CGM vendors must demonstrate total cost-of-care reduction to displace incumbent fingerstick protocols.
- Multi-Site Clinical Trial Coordination:MFDS mandates for accuracy validation across diverse patient populations require coordination across tertiary care centers. Trial management complexity extends regulatory timelines unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Korea Continuous Glucose Monitoring Devices Market |
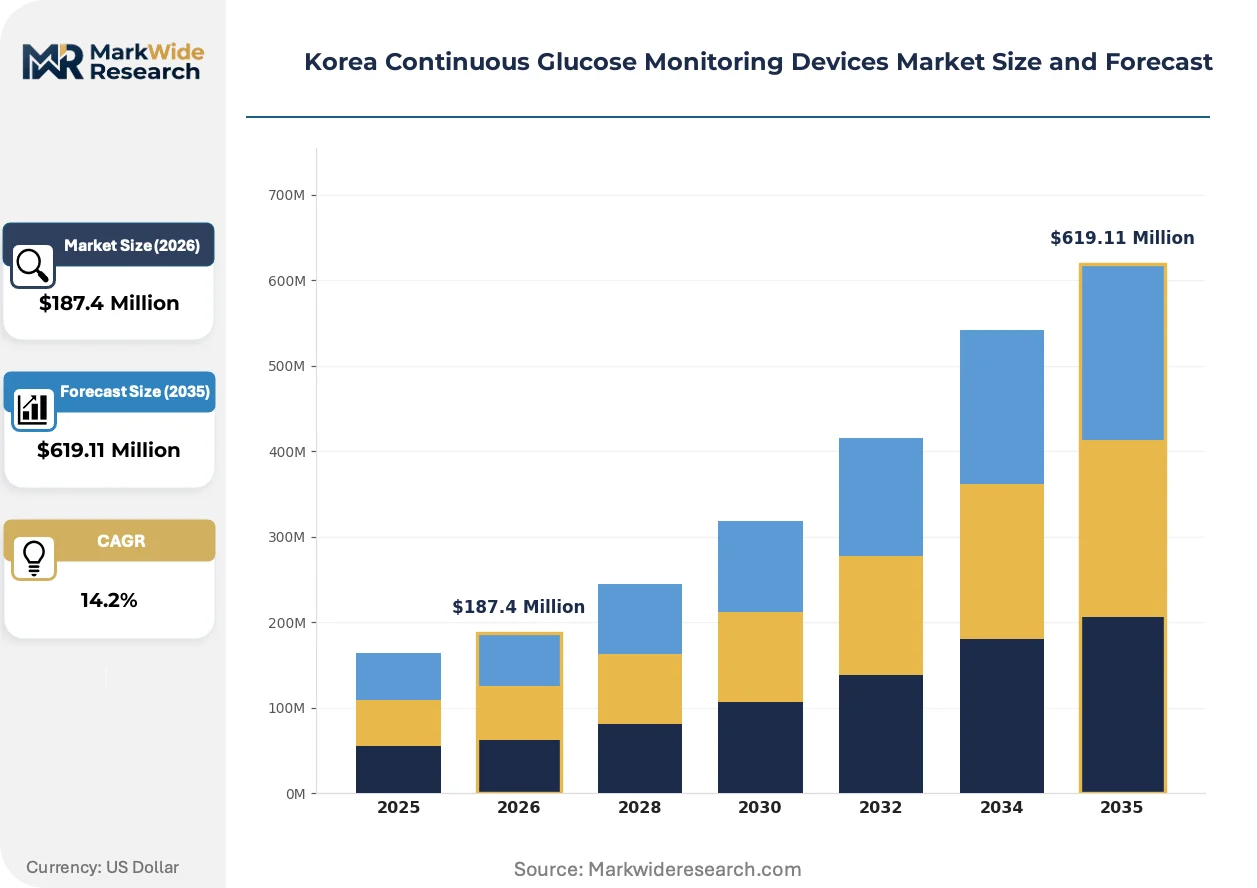
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Real-time Monitoring, Flash Glucose Monitoring, Continuous Glucose Monitoring, Wearable Sensors Technology: Intradermal Sensors, Enzymatic Sensors, Optical Sensors, Non-invasive Sensors End User: Homecare, Hospitals, Diabetes Clinics, Research Institutes Application: Type 1 Diabetes, Type 2 Diabetes, Prediabetes Management, Insulin Resistance |
| Companies Covered | Abbott Laboratories, Dexcom, Inc., Medtronic, F. Hoffmann-La Roche Ltd, i-SENS, Inc., Senseonics Holdings, Inc., Ascensia Diabetes Care Holdings AG, Companion Medical, Becton, Dickinson and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Korea Continuous Glucose Monitoring Devices Market Shifts & Advancements
Wearable sensor architectures are undergoing fundamental redesign as manufacturers compete on wear duration and insertion comfort. Three interconnected developments are compressing product lifecycles and reshaping competitive positioning.
Intradermal micro-needle electrochemical sensors are rewriting performance benchmarks for glucose monitoring devices. These platforms sample interstitial fluid through enzymatic reactions at reduced tissue penetration depth. Seoul-based diabetes clinics are piloting twenty-one-day wear systems for insulin-dependent patients. The technology is compressing replacement cycle frequency and reducing total cost of ownership for hospital procurement budgets.
MFDS alignment with ISO 15197 and IEC 62304 standards is facilitating parallel regulatory submissions for Korean manufacturers targeting export markets. This harmonization reduces redundant clinical validation burdens across jurisdictions. Domestic sensor producers are leveraging streamlined documentation to access Southeast Asian medical device markets simultaneously with domestic launches. Tertiary care settings benefit from accelerated access to next-generation accuracy algorithms.
Patient data ownership preferences are fragmenting traditional hospital-centric distribution models. Individuals with Type 2 diabetes increasingly demand smartphone-native glucose analytics independent of institutional EHR integration. Direct-to-consumer channels are capturing growing share of flash glucose monitoring volume in Busan and Incheon metropolitan areas. This behavioral shift pressures manufacturers to unbundle software subscriptions from hardware procurement contracts.
Korea Continuous Glucose Monitoring Devices Market Segmentation
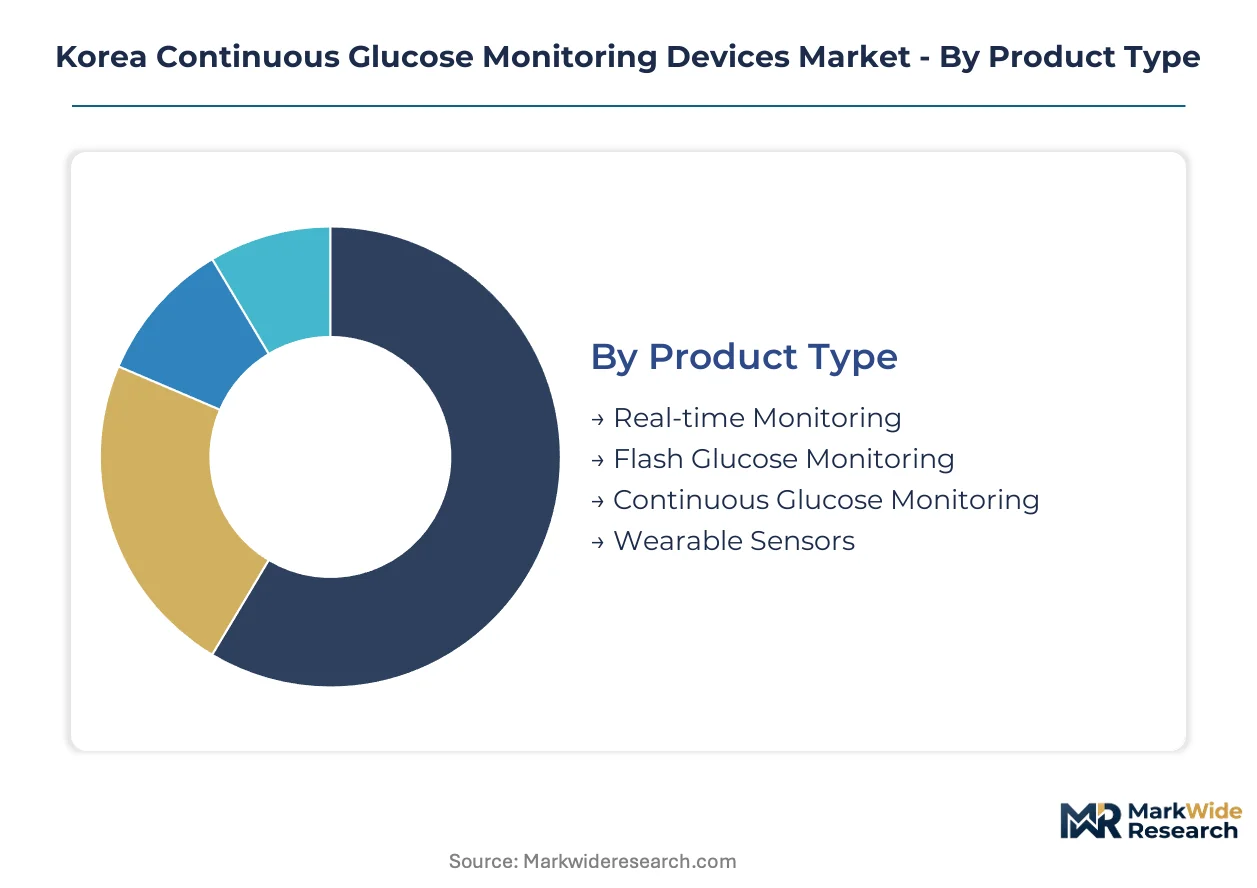
CGM device segmentation in Korea reflects divergent reimbursement economics and patient acuity profiles. Product architecture choices directly determine whether manufacturers compete for institutional procurement contracts or direct-to-consumer channels.
Product Type:
Replacement cycles and upgrade incentives vary sharply across device architectures, with hospital procurement favoring integrated systems while homecare gravitates toward modular platforms.
- Real-time Monitoring:Electrochemical sensor-receiver pairs transmit glucose readings every one to five minutes to dedicated displays or smartphones. Seoul's tertiary hospital networks concentrate demand for these systems where intensive insulin protocols mandate continuous data streams.
- Flash Glucose Monitoring:Factory-calibrated sensors store retrospective glucose profiles for on-demand scanning via handheld readers. Busan and Incheon metropolitan areas show expanding patient-pay adoption where National Health Insurance Service coverage gaps persist.
- Continuous Glucose Monitoring:Integrated pump-sensor systems automate insulin delivery based on algorithmic glucose predictions. Demand clusters among academic medical centers with established closed-loop protocol expertise.
- Wearable Sensors:Discrete patch-form factors prioritize aesthetic concealment and extended wear duration. Secondary city diabetes clinics increasingly specify these for adolescent and working-age patient populations.
Volume placements concentrate in Real-time Monitoring; the faster expansion belongs to Flash Glucose Monitoring.
Technology:
Sensor fabrication methods determine manufacturing capital intensity and regulatory validation burden, with enzymatic platforms dominating current output while intradermal architectures attract development investment.
- Intradermal Sensors:Micro-needle arrays sample interstitial fluid at reduced penetration depth, minimizing insertion trauma. Daegu-Gwangju corridor clinics pilot twenty-one-day wear systems for insulin-dependent patients seeking reduced replacement frequency.
- Enzymatic Sensors:Glucose oxidase-mediated electrochemical reactions generate current proportional to interstitial glucose concentration. Domestic cleanroom production in Seoul supplies medical-grade substrates for these established platforms.
- Optical Sensors:Near-infrared spectroscopy or Raman scattering estimates glucose through skin without enzymatic consumption. Accuracy validation against laboratory reference methods remains pending MFDS clearance.
- Non-invasive Sensors:Transdermal or interstitial fluid extraction without needle penetration. Technology readiness lags clinical acceptance thresholds for reimbursement eligibility.
Manufacturing output clusters around Enzymatic Sensors; Intradermal Sensors are climbing the fastest toward commercial scale.
End User:
Channel economics diverge between institutional procurement with multi-year contracts and patient-direct purchases bypassing prior authorization requirements.
- Homecare:Individual patients or caregivers manage glucose monitoring outside clinical settings. Out-of-pocket payment models dominate where National Health Insurance Service restrictions apply to non-insulin-dependent Type 2 populations.
- Hospitals:Inpatient and outpatient departments integrate CGM into standardized diabetes protocols. Seoul and Busan hospital systems embed these devices into intensive insulin therapy order sets.
- Diabetes Clinics:Specialized outpatient facilities focus on metabolic disease management. Greater Seoul Area clinics drive adoption of analytics-integrated platforms connecting glucose data to electronic health records.
- Research Institutes:Academic and clinical trial organizations utilize CGM for pharmacokinetic studies and algorithm development. KAIST and Seoul National University partnerships concentrate validation research in this channel.
Procurement volume tilts toward Hospitals; Diabetes Clinics are gaining share fastest as regional network expansion accelerates.
Application:
Patient population characteristics determine reimbursement tier eligibility and device specification requirements, with insulin dependency status serving as the primary coverage determinant.
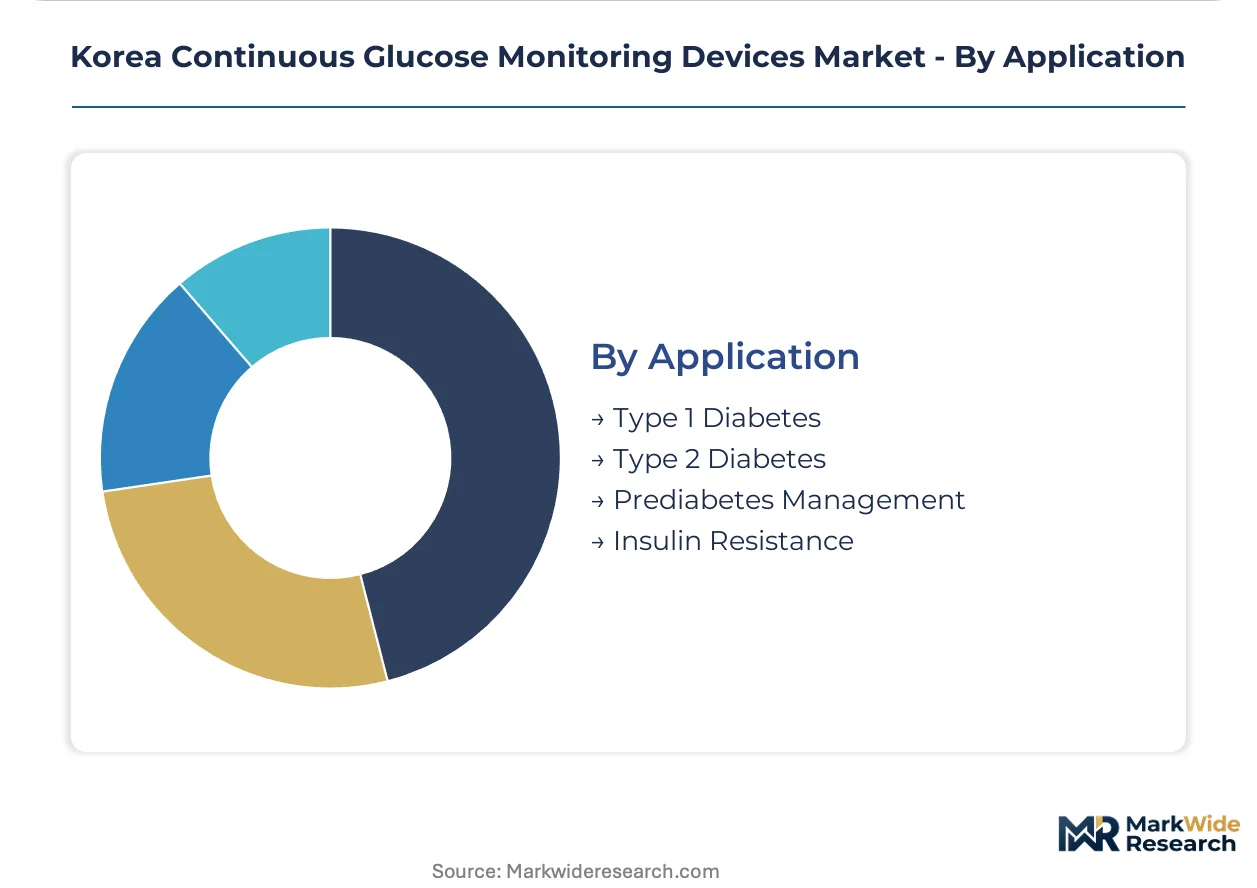
- Type 1 Diabetes:Absolute insulin deficiency mandates continuous glucose awareness for dosing safety. MFDS reimbursement alignment with intensive therapy protocols ensures predictable demand from pediatric and adult endocrinology services.
- Type 2 Diabetes:Progressive insulin resistance spans oral medication to injectable therapy transitions. Coverage expansion debates for non-intensive patients reshape addressable volume calculations across manufacturer commercial teams.
- Prediabetes Management:Elevated glucose below diabetes thresholds motivates lifestyle intervention monitoring. Wellness-oriented direct-to-consumer channels capture this emerging demand outside reimbursement frameworks.
- Insulin Resistance:Metabolic syndrome and polycystic ovary syndrome populations seek glucose pattern awareness. Specialist referral networks in Seoul's women's health centers pilot prescription access for these indications.
Device deployment concentrates in Type 1 Diabetes; Type 2 Diabetes shows the steepest expansion trajectory pending reimbursement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade electrochemical substrate production anchors Korea's CGM manufacturing base in Seoul's cleanroom clusters. Metropolitan hospital procurement consortia in the capital region concentrate demand for real-time monitoring systems. MFDS regulatory alignment with ISO standards positions Korean manufacturers for simultaneous export launches across Asia-Pacific.
Seoul Capital Area
Tertiary hospital networks in Seoul and Incheon drive institutional procurement volume for intensive insulin therapy protocols. MFDS streamlined approval pathways accelerate market entry for next-generation wearable sensor platforms. Cleanroom fabrication facilities in Guro-dong and Pangyo supply medical-grade enzymatic substrates to domestic device manufacturers.
Busan-Ulsan
Flash glucose monitoring adoption accelerates through patient-pay models in Busan's metropolitan diabetes clinics. National Health Insurance Service coverage gaps for non-intensive Type 2 patients expand direct-to-consumer channel penetration. Ulsan's biomedical industrial complex hosts electrochemical sensor assembly operations serving southeastern hospital networks.
Daegu-Gyeongbuk
Regional diabetes clinics in Daegu pilot twenty-one-day intradermal sensor systems for insulin-dependent populations. MFDS reimbursement tier revisions compress manufacturer pricing power while expanding addressable patient volume. Gyeongsan city's medical device cluster attracts production-linked incentive schemes for domestic sensor fabrication.
Daejeon-Sejong
Research institutes at KAIST and Korea Research Institute of Bioscience and Biotechnology concentrate electrochemical engineering talent for algorithm development. Government R&D funding for non-invasive glucose sensing technologies flows through Sejong's science belt. Daejeon-based startups leverage MFDS accelerated review frameworks for wearable platform commercialization.
Gwangju-Honam
Secondary metropolitan hospital networks in Gwangju remain underpenetrated for CGM protocol integration compared to Greater Seoul. Regional endocrinology specialists advocate for expanded National Health Insurance Service coverage for Type 2 diabetes populations. Honam's diabetes clinics represent whitespace for software-EHR converged analytics platforms.
Korea Continuous Glucose Monitoring Devices Market Competitive Landscape
Global majors compete with regional champions across technology licensing and hospital procurement contracting. The vendor base stratifies into three tiers: multinational device conglomerates with integrated software ecosystems, mid-scale Korean manufacturers with domestic cleanroom advantages, and specialized algorithm developers licensing predictive analytics to institutional buyers. Dominant competitive moves include strategic partnerships with Seoul hospital procurement consortia and backward integration into enzymatic reagent production.
Among U.S.-based multinationals, Abbott Laboratories, Dexcom, Inc., and Medtronic exemplify divergent archetypes within the premium tier. Abbott Laboratories occupies a position emphasizing software-EHR convergence for hospital system stickiness. Dexcom, Inc. anchors its presence through distributor partnerships with major procurement consortia. Medtronic represents algorithm sophistication focused on predictive hypoglycemia alerts in tertiary care settings. Korean manufacturers including i-SENS, Inc. leverage domestic cleanroom capacity and MFDS regulatory alignment to compete on cost-competitive substrate production.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom, Inc. |
| Medtronic |
| F. Hoffmann-La Roche Ltd |
| i-SENS, Inc. |
| Senseonics Holdings, Inc. |
| Ascensia Diabetes Care Holdings AG |
| Companion Medical |
| Becton, Dickinson and Company |
| Others |
Supply & Pricing Matrix
Hospital procurement consortium consolidation in Seoul and Busan is forcing manufacturers to absorb sensor substrate cost volatility while maintaining fixed contract pricing for multi-year agreements. This buyer-side concentration compels suppliers to secure captive enzymatic reagent production and compress logistics overhead to preserve margin structures.
Pricing Analysis
Warranty and calibration service bundling separates premium-tier real-time monitoring contracts from unbundled flash glucose monitoring hardware sold through patient-pay channels. Three-tier pricing structure across premium, standard, and economy levels aligns with MFDS reimbursement tiers and software-EHR integration depth. Cost compression in the standard tier is intensifying because domestic manufacturers leverage production-linked incentives to undercut multinational sensor pricing. Homecare patients outside intensive insulin protocols exhibit highest price sensitivity, while tertiary hospital networks prioritize accuracy validation over unit cost.
Supply Chain Analysis
Direct-to-hospital procurement channels handle institutional demand from Seoul and Busan metropolitan networks, while distributor partnerships serve secondary city diabetes clinics. Medical-grade electrochemical substrate fabrication concentrates in South Korea, Japan, and Germany, with enzymatic glucose oxidase reagents drawing from Swiss and Danish specialty chemical suppliers. Single-source vulnerability persists for fourteen-day wear intradermal sensor membranes, where domestic cleanroom capacity expansion lags demand growth. Distribution runs through GPO-authorized medical device consortia and direct manufacturer contracts with leading academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around manufacturers with backward integration into biosensor substrates and MFDS regulatory expertise, as reimbursement tier revisions squeeze pricing power for undifferentiated hardware vendors.
For Market Incumbents: Anticipate margin compression from domestic cleanroom-scale competitors by securing exclusive enzymatic reagent supply agreements and embedding predictive analytics into multi-year hospital procurement contracts. MFDS reimbursement expansion debates for non-intensive Type 2 populations represent the critical regulatory threat to current volume projections. Priority investment in intradermal platform miniaturization extends replacement cycle differentiation against flash glucose monitoring commoditization. For New Entrants and Emerging Players: Regional diabetes clinic partnerships in the Daegu-Gwangju corridor offer whitespace penetration before incumbent distributor lock-in solidifies. Software-EHR convergence capabilities at Gwangju metropolitan hospitals remain underdeveloped relative to Seoul, creating entry latitude for analytics-native platforms. Direct-to-patient subscription models bypassing National Health Insurance Service authorization requirements capture expanding homecare share in Busan and Incheon. For Investors and Strategic Acquirers: The window for entry favors domestic manufacturers with captive cleanroom substrate production and MFDS streamlined approval track records. Long-term viability rests on algorithm sophistication and reimbursement strategy execution rather than hardware scale alone. Watch for MFDS coverage expansion decisions for non-insulin-dependent Type 2 diabetes as the volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Streamlined Approval Pathway | Accelerated market entry for intradermal sensor platforms reduces competitive lag for Korean manufacturers. |
| Hospital System Partnership | Multi-year procurement contracts with Seoul tertiary networks lock in predictable real-time monitoring volumes. |
| Backward Integration into Enzymatic Reagents | Captive substrate production insulates margin structures from imported glucose oxidase price volatility. |
| Software-EHR Companion Development | Direct glucose data integration at leading medical centers creates platform stickiness against modular competitors. |
| Reimbursement Strategy Alignment | Early positioning for non-intensive Type 2 coverage expansion captures addressable volume growth ahead of rivals. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews conducted with hospital procurement committee members, biomedical engineering directors at tertiary care centers, GPO contracts managers, and diabetes clinic operations leads. MFDS device registration databases, National Health Insurance Service reimbursement bulletins, Korean Medical Device Industry Association member directories, and Seoul metropolitan hospital procurement disclosures supplied quantitative grounding. Bottom-up sensor shipment estimates triangulated against top-down addressable patient population calculations.
Segment-level modeling addressed product type, technology platform, end-user channel, and application across the analysis window, with regional granularity at metropolitan cluster level. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns and adjusted for reimbursement policy scenario weighting. Forecast inputs incorporated MFDS approval pipeline velocity, cleanroom capacity expansion schedules, and hospital procurement consortium contract renewal cycles.
Caveats apply where MFDS reimbursement tier revisions or biosensor substrate supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding regulatory harmonization progress and domestic manufacturing scale-up timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Canada Continuous Glucose Monitoring Market
Diabetes Care
India Self-Monitoring Blood Glucose Devices Market
Diabetes Care
United States Blood Glucose Monitoring Market
Diabetes Care
Philippines Diabetes Care Devices Market
Diabetes Care
Asia-Pacific Insulin Delivery Devices Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
Brazil Oral Anti-Diabetic Drug Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
Vietnam Insulin Drug and Delivery Device Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
Artificial Intelligence in Diabetes Management Market
Diabetes Care
US Continuous Glucose Monitoring Market
Diabetes Care
Continuous Glucose Monitoring Device Market
Diabetes Care
Russia Diabetes Care Devices Market