
 North America C-Arms Market | 2026-2036
North America C-Arms Market Size, Share, and Industry Trends Forecast 2026-2036
North America C-Arms Market Analytics
Subscription-based software upgrades for image processing and AI-assisted positioning is consolidating vendor-customer relationships beyond hardware transactions. Siemens Healthineers leverages its digital service architecture to sustain recurring revenue from installed base modernization. GE Healthcare anchors its North American position through dense field-service networks that reduce equipment downtime for hospital buyers. Philips Healthcare differentiates via integrated software ecosystems that connect C-Arm workflows to enterprise imaging platforms.
C-Arms are mobile fluoroscopy systems built around an X-ray source and detector mounted on a C-shaped gantry, typically operating at 70-120 kVp with variable mA settings for real-time intraoperative imaging during surgical procedures. Digital C-Arms with flat-panel detectors now dominate new procurement decisions due to superior dose efficiency and image resolution compared to legacy image-intensifier systems. Among applications, orthopedic surgery occupies the largest installed base, while cardiovascular procedures represent the fastest-growing segment as electrophysiology and structural heart interventions expand in outpatient settings. Hospitals remain the primary end-user channel, though surgical centers are capturing disproportionate growth as site-of-care migration accelerates.
FDA 510(k) premarket notification requirements govern device clearance timelines, while Joint Commission accreditation standards shape capital equipment purchasing protocols for hospital systems. State-level certificate-of-need regulations in Texas, Florida, and New York directly control C-Arm deployment density by restricting imaging equipment expansion without demonstrated community need. Stakeholders must monitor ambulatory surgery center reimbursement parity legislation across state Medicaid programs, as payment rate convergence will determine whether capital migrates toward outpatient sites or remains concentrated in hospital-based procedure suites.
Market Dynamics
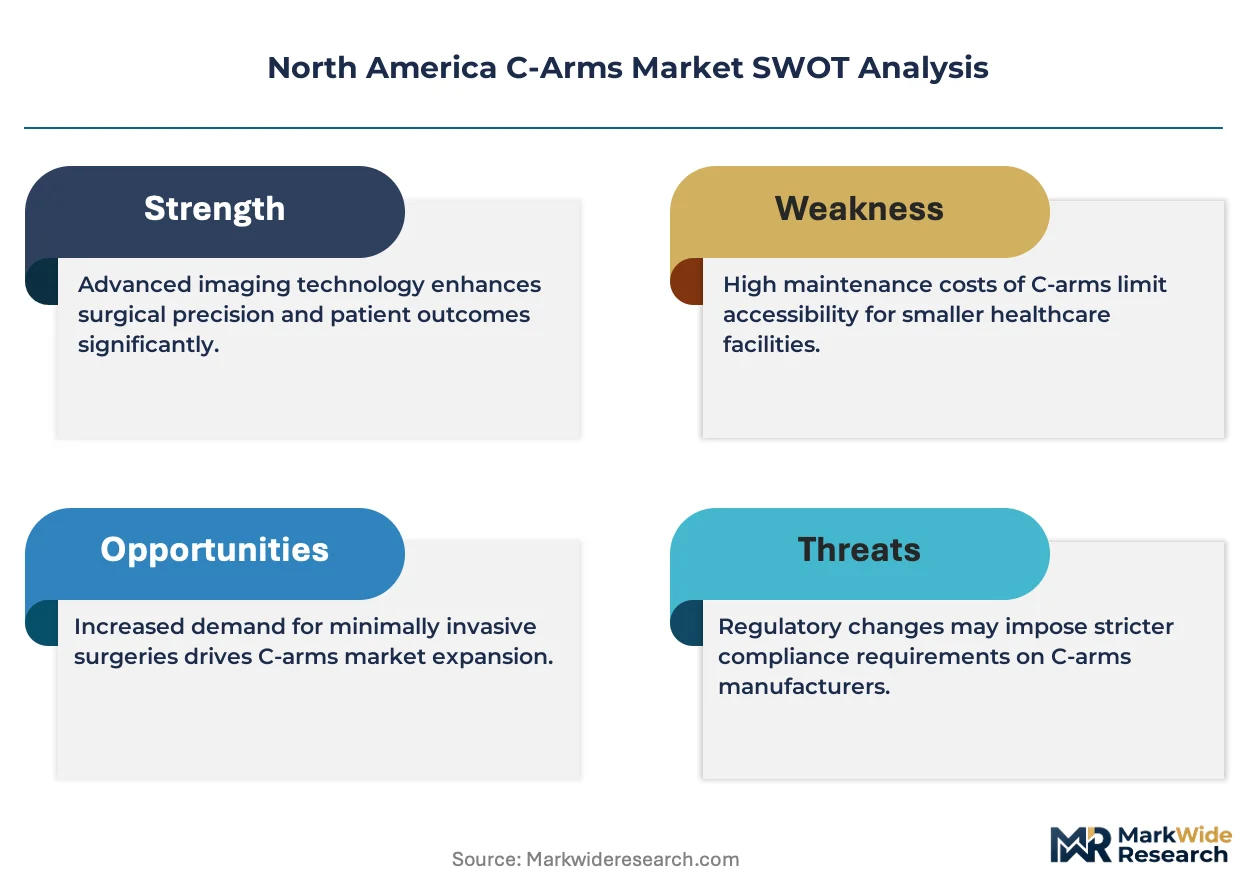
Site-of-care migration from hospitals to ambulatory surgical centers is compressing capital deployment cycles and forcing vendors to reconfigure service delivery models around distributed, lower-volume facilities.
Growth Catalysts
- FDA 510(k) Clearance Streamlining:Accelerated pathways for digital flat-panel detector upgrades reduce regulatory friction for equipment refreshes. Hospital systems exploit this to modernize installed bases without full system replacement.
- Orthopedic Procedure Volume Concentration:Southeastern United States hospital construction and specialty expansion drive concentrated demand for intraoperative imaging. Florida and Texas certificate-of-need approvals favor imaging equipment deployment in high-growth metropolitan corridors.
- AI-Assisted Positioning Software:Subscription-based image processing modules extend vendor-customer relationships beyond hardware transactions. Recurring revenue models align vendor incentives with customer uptime requirements.
Market Restraints
- Certificate-of-Need Density Caps:State-level CON regulations in New York, Texas, and Florida restrict imaging equipment expansion without demonstrated community need. These frameworks artificially constrain addressable market size regardless of clinical demand.
- Flat-Panel Detector Supply Concentration:Critical detector components concentrate among a limited supplier base in East Asian manufacturing clusters. Disruption risk elevates procurement uncertainty for North American OEMs.
- Legacy Image-Intensifier Stranded Assets:Hospitals with depreciated analog systems face capital inefficiency when upgrade paths require full gantry replacement rather than modular retrofit.
Strategic Opportunities
- Outpatient Cardiovascular Expansion:Electrophysiology and structural heart interventions migrating to ambulatory settings create demand for compact, dose-optimized C-Arm configurations. Procedure volume growth in catheterization-capable surgical centers outpaces hospital-based expansion.
- Medicaid Reimbursement Parity Legislation:State-level payment rate convergence between ASCs and hospital outpatient departments determines capital migration patterns. Stakeholders monitoring Texas and Florida Medicaid program evolution gain positioning advantage.
- Enterprise Imaging Platform Integration:C-Arm workflow connectivity to PACS and VNA architectures differentiates vendor offerings. Philips Healthcare and GE Healthcare compete on software ecosystem depth rather than hardware specifications alone.
Industry Challenges
- Field Service Network Optimization:Distributed ASC deployments require denser technician coverage with lower revenue per site. Siemens Healthineers and GE Healthcare must rebalance service cost structures against equipment utilization rates.
- Joint Commission Accreditation Compliance:Capital equipment purchasing protocols for hospital systems impose documentation and validation burdens that extend sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America C-Arms Market |
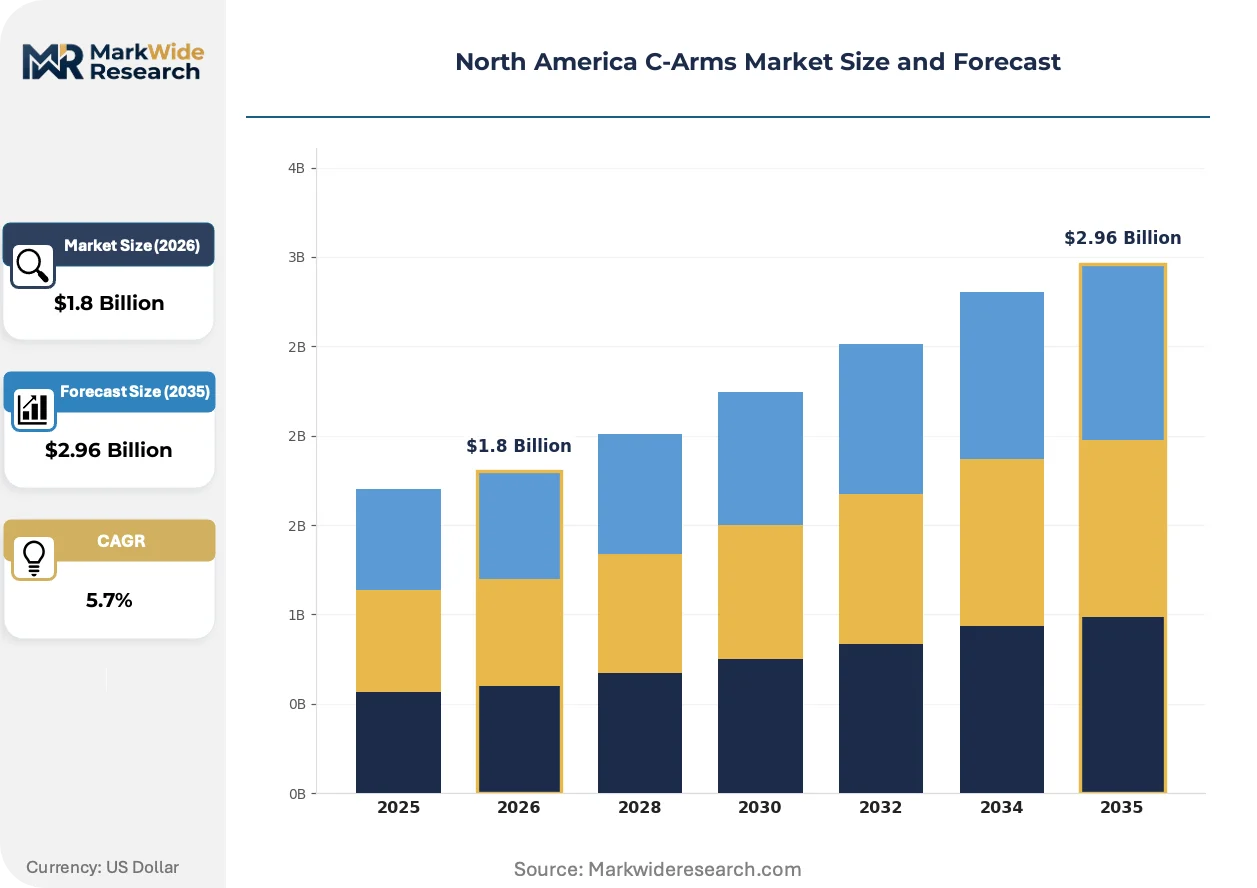
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog C-Arms, Digital C-Arms, Mini C-Arms, Full-Size C-Arms End User: Hospitals, Surgical Centers, Ambulatory Care Centers, Diagnostic Imaging Centers Technology: Image Intensifier, Flat Panel Detector, Wireless, Integrated Software Application: Orthopedic Surgery, Cardiovascular Procedures, Pain Management, Trauma Surgery |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems, Hologic Corporation, Ziehm Imaging, Fujifilm Holdings Corporation, Shimadzu Corporation, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America C-Arms Market Evolving Landscape
Digital detector technology and software-defined imaging architectures are redefining competitive differentiation, while regulatory and procurement frameworks force adaptation in go-to-market models.
Flat-panel detectors with cesium iodide scintillator layers are absorbing the functional role of legacy image-intensifier chains in new system procurement. Ambulatory surgical centers prioritize these configurations for dose efficiency and spatial resolution advantages in orthopedic and vascular applications. The technology is absorbing service contract value as detector reliability becomes the dominant uptime determinant.
FDA 510(k) premarket notification requirements for hardware and software modifications create compliance velocity pressures for manufacturers. Shorter clearance timelines for incremental upgrades compress product lifecycle management and force continuous regulatory engagement. Digital C-Arm vendors with established FDA submission trackbooks exploit this friction to accelerate refresh cycles against competitors with thinner regulatory infrastructure.
Subscription pricing for image processing and AI-assisted positioning modules is displacing perpetual license structures in vendor-customer negotiations. Hospital procurement functions resist capital-intensive hardware purchases while accepting operational expenditure models for software capabilities. This pattern concentrates in health system IDNs with centralized technology assessment committees, particularly in the southeastern United States where construction-driven expansion strains capital allocation frameworks.
North America C-Arms Market Segmentation
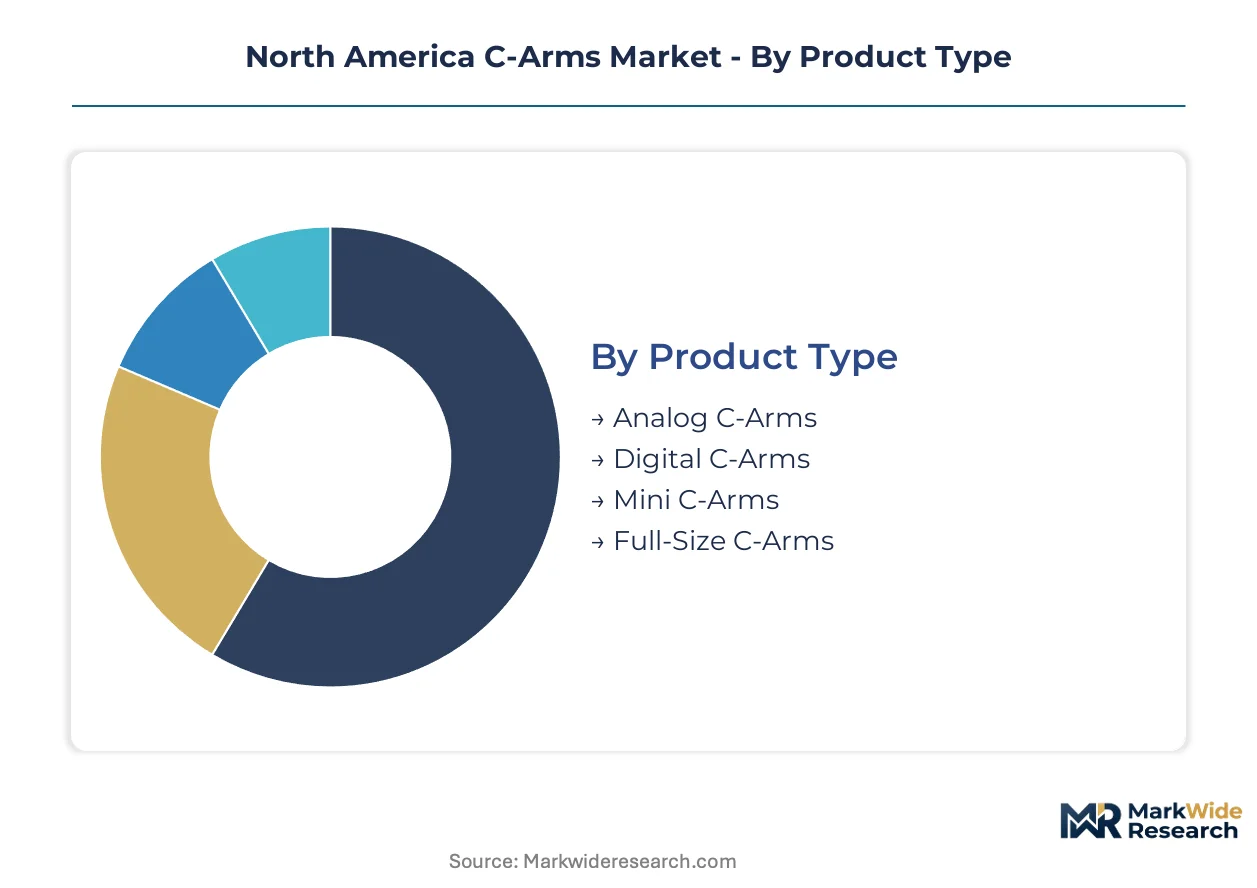
Segmentation reveals how capital allocation priorities diverge across clinical settings and technological generations in North American C-Arm procurement. Understanding these divisions exposes where vendor margins concentrate and where installed base modernization creates replacement demand.
Product Type:
Capital-intensity varies dramatically across product categories, with full-size digital systems commanding the largest upfront commitments while mini configurations serve constrained budgets.
- Digital C-Arms:Flat-panel detector architectures operating at 70-120 kVp with superior dose efficiency and spatial resolution. Southeastern United States hospital construction drives concentrated procurement as health systems modernize surgical suites. FDA 510(k) clearance streamlining accelerates refresh cycles for legacy analog replacements.
- Full-Size C-Arms:Standard gantry configurations with extended C-arc travel for complex multi-planar imaging during spine and cardiac procedures. Texas and Florida certificate-of-need approvals favor deployment in high-volume metropolitan corridors where orthopedic specialty expansion is most active.
- Analog C-Arms:Image-intensifier based systems with depreciated installed bases facing stranded asset risk. Hospitals confront capital inefficiency when upgrade paths require complete gantry replacement.
- Mini C-Arms:Compact configurations optimized for extremity imaging with reduced footprint requirements. Ambulatory surgical centers prioritize these for distributed site deployment with lower procedure volumes.
Full-size systems absorb the bulk of installed capacity; mini C-Arms are expanding most quickly in outpatient settings.
End User:
Procurement authority and volume concentration shape vendor engagement models, with centralized health system IDNs negotiating differently than distributed surgical center networks.
- Hospitals:Primary procurement channel with capital equipment committees governing technology assessment and Joint Commission compliance documentation. Southeastern construction activity concentrates demand in Florida, Texas, and Georgia surgical suite expansions.
- Surgical Centers:Fastest-growing deployment channel as site-of-care migration accelerates fluoroscopy-based interventions. Medicaid reimbursement parity legislation in Texas and Florida determines capital migration toward these distributed facilities.
- Ambulatory Care Centers:Intermediate settings with hybrid diagnostic and minor procedure capabilities. Certificate-of-need density caps in New York restrict equipment expansion regardless of clinical demand.
- Diagnostic Imaging Centers:Specialized facilities with dedicated radiology operations and distinct reimbursement pathways. Lower C-Arm penetration due to preference for fixed-room fluoroscopy systems.
Hospitals retain the dominant installed base; surgical centers are gaining share fastest as procedure volume migrates outpatient.
Technology:
Component architecture determines service contract value and uptime reliability, with detector technology now the critical margin driver.
- Flat Panel Detector:Cesium iodide scintillator layers absorbing the functional role of legacy image-intensifier chains. Ambulatory surgical centers prioritize dose efficiency advantages in orthopedic and vascular applications.
- Integrated Software:Subscription-based image processing and AI-assisted positioning modules extending vendor-customer relationships. Health system IDNs with centralized technology assessment committees drive operational expenditure adoption.
- Image Intensifier:Legacy vacuum-tube technology with deteriorating supply chains and limited upgrade pathways. Stranded asset risk elevates replacement urgency for hospitals with depreciated analog systems.
- Wireless:Cable-free detector communication reducing OR tripping hazards and enabling positioning flexibility. Integration complexity with enterprise imaging platforms varies by vendor ecosystem depth.
Flat panel detector systems command the dominant technology share; integrated software is climbing the fastest as recurring revenue models consolidate.
Application:
Procedure volume growth rates and reimbursement dynamics create divergent equipment utilization profiles across clinical specialties.
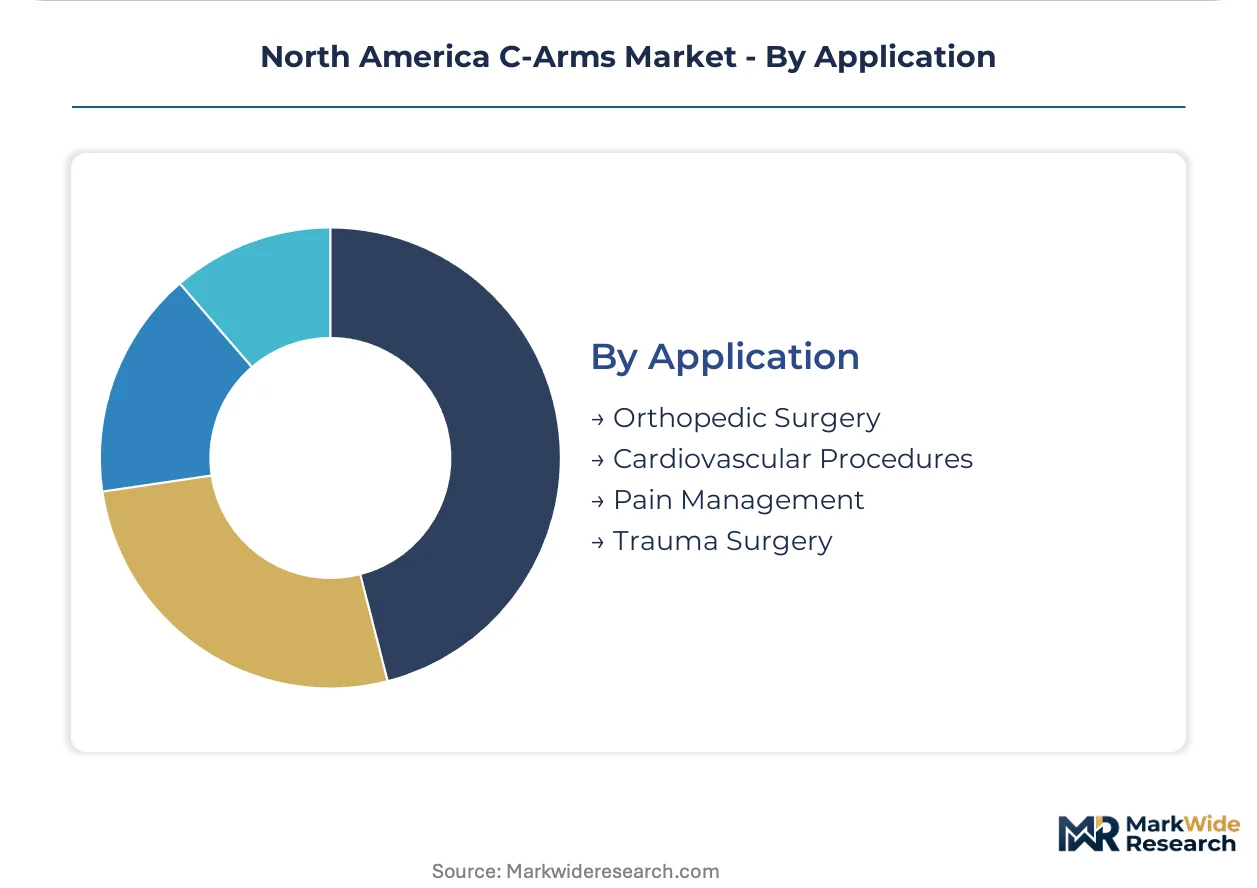
- Orthopedic Surgery:Largest installed base segment with spine, trauma, and joint reconstruction procedures driving intraoperative imaging demand. Southeastern United States specialty expansion concentrates procurement in high-growth metropolitan corridors.
- Cardiovascular Procedures:Electrophysiology and structural heart interventions migrating to ambulatory settings. Catheterization-capable surgical centers in Texas and Florida outpace hospital-based expansion for compact, dose-optimized configurations.
- Pain Management:Fluoroscopy-guided injections and vertebral augmentation with lower equipment utilization rates. Smaller gantry footprints suit office-based procedure suites.
- Trauma Surgery:Emergency department and hybrid OR deployments requiring rapid availability and mobile positioning. Joint Commission accreditation standards shape purchasing protocols for hospital systems.
Orthopedic surgery holds the largest procedure volume; cardiovascular applications show the steepest expansion trajectory as interventions migrate outpatient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American C-Arm consumption concentrates in the United States, while Canadian and Mexican markets absorb secondary tier systems with distinct procurement patterns. Regional demand splits between hospital construction corridors and ambulatory surgical center expansion zones.
United States
Southeastern hospital construction in Florida, Texas, and Georgia drives concentrated demand for full-size digital systems. FDA 510(k) clearance streamlining accelerates equipment refresh cycles for legacy analog replacements. Dallas-Fort Worth and Miami metropolitan corridors absorb disproportionate procurement volumes as orthopedic specialty expansion strains surgical suite capacity.
Southeastern United States
Certificate-of-need approvals in Florida and Texas favor imaging equipment deployment in high-growth metropolitan zones. State Medicaid reimbursement parity legislation determines capital migration toward ambulatory surgical centers versus hospital outpatient departments. Atlanta and Houston surgical center networks expand fluoroscopy-based intervention volumes faster than national averages.
Canada
Provincial health authority procurement governs C-Arm deployment through centralized capital equipment committees. Health Canada regulatory pathways align with FDA premarket notification structures but impose distinct documentation requirements for software-defined imaging upgrades. Ontario and Quebec health systems prioritize enterprise imaging platform integration in hospital modernization programs.
Mexico
Private hospital chains in Mexico City and Monterrey drive premium system procurement while public sector facilities absorb refurbished analog equipment. COFEPRIS regulatory frameworks create compliance velocity pressures distinct from FDA pathways. Guadalajara medical device distribution clusters serve as regional logistics hubs for Central American secondary markets.
North America C-Arms Market Competitive Landscape
Top-tier vendors anchor the premium digital segment, while mid-tier specialists and regional fabricators compete on price-sensitive configurations. The vendor base stratifies across three tiers: integrated imaging conglomerates with software ecosystem depth, detector technology specialists with component supply advantages, and regional service organizations with dense field coverage. Dominant competitive moves include subscription-based software monetization and field service network densification for distributed ambulatory deployments.
Within the integrated imaging tier, GE Healthcare, Siemens Healthineers, and Philips Healthcare exemplify archetypes competing on software ecosystem depth rather than hardware specifications alone. GE Healthcare occupies a position anchored by dense North American field-service infrastructure. Siemens Healthineers represents the digital service architecture approach to recurring revenue generation. Philips Healthcare sits within the enterprise imaging platform integration vector connecting C-Arm workflows to hospital IT architectures.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Canon Medical Systems |
| Hologic Corporation |
| Ziehm Imaging |
| Fujifilm Holdings Corporation |
| Shimadzu Corporation |
| Medtronic |
| Others |
Value Network & Pricing Analysis
EU RoHS hazardous substance restrictions gate qualified supply and premium-tier pricing access for C-Arm manufacturers sourcing flat-panel detectors from East Asian fabrication facilities. Compliance with lead-free soldering mandates and restricted material declarations separates vendors eligible for health system procurement from those relegated to refurbished equipment channels.
Pricing Analysis
Margin tightening in mid-tier configurations reflects detector component cost escalation and freight surcharges on East Asian imports. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA clearance tier and field service bundling intensity. Hospital IDNs with centralized technology assessment committees extract volume discounts exceeding ambulatory surgical center procurement. Surgical centers exhibit highest price sensitivity due to lower equipment utilization rates and capital constraint.
Supply Chain Analysis
Freight cost volatility on transpacific routes elevates landed cost uncertainty for North American OEMs sourcing cesium iodide scintillator substrates and amorphous silicon backplanes. Critical detector components concentrate in South Korea, Japan, and Taiwan manufacturing clusters. Supply chain risk centers on single-source vulnerability for high-resolution flat-panel arrays. Distribution runs through authorized dealer networks with regional service depot requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America C-Arms market is a vertical-integration race where detector fabrication capability determines margin retention against East Asian component suppliers.
For Market Incumbents: Deploy backward integration into scintillator material processing to reduce detector cost exposure. Anchor field service density in Texas and Florida certificate-of-need corridors where construction-driven demand concentrates. Consolidate subscription software revenue streams to offset hardware margin compression from ambulatory surgical center price sensitivity. For New Entrants and Emerging Players: Launch via mini C-Arm configurations targeting extremity imaging in distributed surgical center networks. Penetrate pain management and orthopedic subspecialties where full-size system incumbents maintain less entrenched positions. Pursue FDA 510(k) clearance for wireless detector retrofit kits as a lower-capital entry vector. For Investors and Strategic Acquirers: Texas Medicaid reimbursement parity legislation is the leading indicator that capital migration toward ambulatory surgical centers will accelerate. Target detector technology specialists with established FDA submission trackbooks and cesium iodide scintillator supply relationships. Monitor certificate-of-need approval velocity in Florida and New York as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortened clearance timelines compress competitor refresh cycles in digital detector upgrades. |
| Flat-Panel Detector Backward Integration | In-house scintillator processing reduces component cost exposure against East Asian suppliers. |
| Ambulatory Surgical Center Service Network Densification | Distributed technician coverage captures site-of-care migration volume in Texas and Florida. |
| Enterprise Imaging Platform Integration | PACS connectivity differentiates vendor offerings for hospital IDN procurement committees. |
| Subscription Software Monetization | Recurring revenue from AI-assisted positioning modules extends customer lifetime value. |
Research Methodology
Document review covered FDA 510(k) clearance databases, hospital procurement records, and state certificate-of-need filings, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and ambulatory surgical center administrators. Secondary sources included CMS Medicare reimbursement data, Joint Commission accreditation standards, and state Medicaid program documentation. Bottom-up equipment shipment analysis triangulated against top-down health system capital expenditure surveys.
Installed base projections and revenue estimates across the analysis window reflect procedure volume modeling by orthopedic and cardiovascular specialty. Segmentation dimensions encompassed product type, end-user channel, detector technology generation, and application category. CAGRs derived from equipment replacement cycle analysis and site-of-care migration velocity. Forecast inputs incorporated certificate-of-need approval trajectories and Medicaid reimbursement parity legislative tracking.
Certificate-of-need regulatory shifts, flat-panel detector supply disruption, and ambulatory surgery center reimbursement rate divergence are the dominant revision risks to baseline projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Mexico Artificial Organs and Bionic Implants Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
Global Aneurysm Clips Market
Medical Devices
Neuromodulation Market
Medical Devices
Global Organs-On-Chips Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
Veterinary Equipment and Disposables Market
Medical Devices
Portable Ultrasonic Skin Scrubber Market
Medical Devices
Home Dialysis Systems Market
Medical Devices
Soft Tissue Markers Market
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Non-Rebreathing Oxygen Mask Market
Medical Devices
Low Vision Aids Market
Medical Devices
Invisible Orthodontics Market
Medical Devices
Interphalangeal Fusion Market