
 Latin America General Surgical Devices Market | 2026-2036
Latin America General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America General Surgical Devices Market Foresight
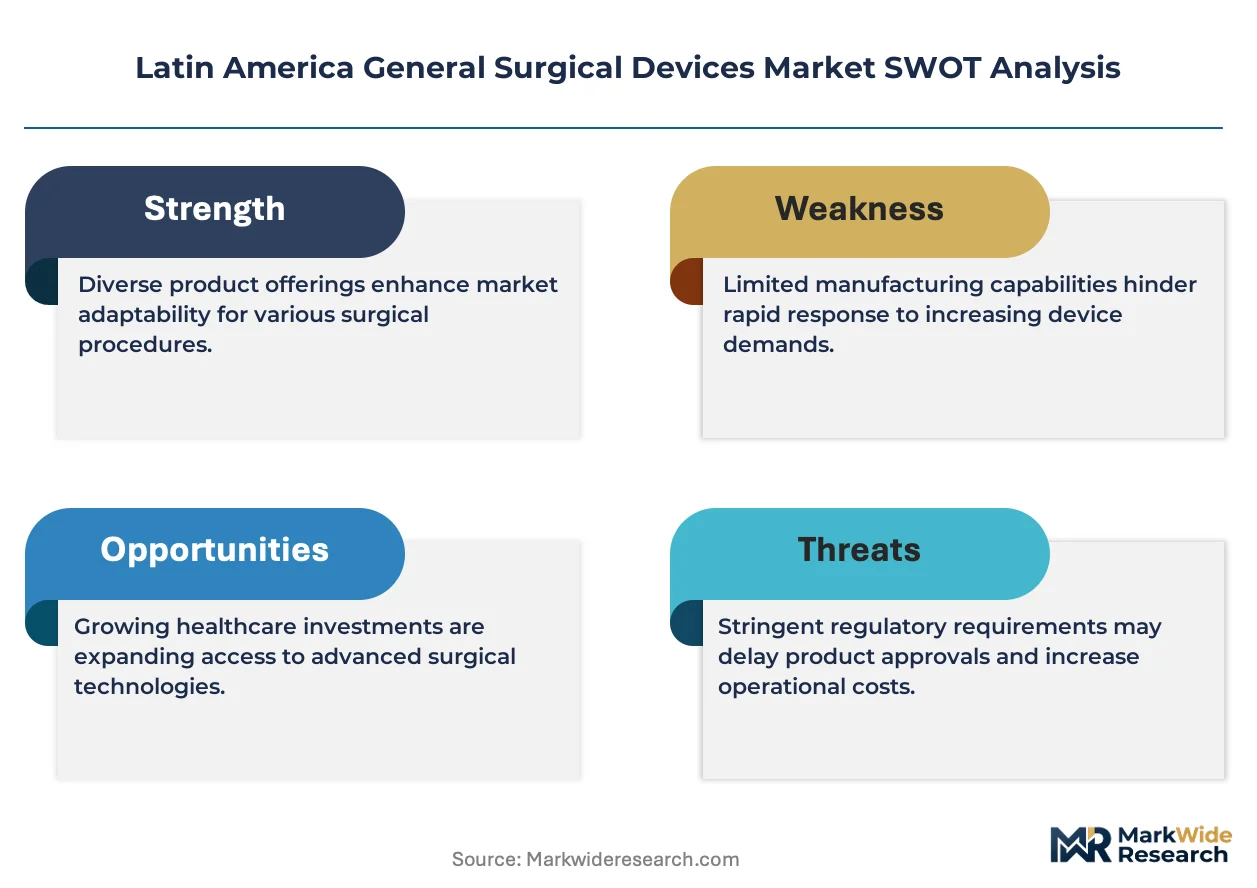
Specialized surgical instrument technicians is redrawing competitive boundaries across Latin America as training pipeline gaps constrain operating room throughput. Medtronic leverages its broad electrosurgical portfolio to anchor presence in Brazilian teaching hospitals. B. Braun Melsungen AG sustains manufacturing scale through its regional production hub in the Dominican Republic. Johnson & Johnson differentiates via suture and stapler bundles that integrate with its surgical ecosystem strategy.
General surgical devices encompass precision-engineered instruments manufactured from medical-grade stainless steel, titanium alloys, and polymer composites, sterilized for single or multi-use applications in operative procedures. These instruments enable tissue manipulation, hemostasis, and wound closure across open and minimally invasive surgical workflows. Electrosurgical devices command premium positioning due to energy-delivery precision requirements and recurring electrode consumption. Minimally invasive surgery delivery modes are expanding fastest as laparoscopic training programs proliferate in Colombian and Chilean medical schools. Sutures retain stable volume pools across public hospital procurement networks where cost sensitivity dominates purchasing criteria.
ANVISA in Brazil and COFEPRIS in Mexico enforce medical device registration and post-market surveillance protocols that shape product entry timelines and clinical evidence requirements. CE marking alignment and ISO 13485 certification increasingly filter supplier eligibility for regional tender processes. Stakeholders must monitor regulatory convergence between Mercosur technical standards and evolving national pharmacovigilance frameworks to anticipate compliance cost trajectories.
Market Dynamics
Electrosurgical energy platforms are fragmenting procedural workflows across Brazilian metropolitan hospital networks as laparoscopic training programs expand surgical throughput capacity. This technology diffusion is compressing equipment replacement cycles and reshaping procurement criteria toward integrated energy systems.
Growth Catalysts
- ANVISA Registration Pathway Modernization:Brazil's updated Class III medical device approval timelines are accelerating market entry for precision electrosurgical instruments.
- Metropolitan Hospital Expansion:Brazilian teaching hospital networks are adding surgical capacity to address backlogged elective procedures accumulated during pandemic restrictions.
- Polymer Composite Adoption:Advanced polymer-based instrument coatings are reducing sterilization degradation and extending multi-use device lifecycles in high-volume Mexican border-state surgical corridors.
Market Restraints
- Medical-Grade Stainless Steel Price Volatility:Input cost fluctuations for surgical-grade alloys are compressing margin structures for instrument manufacturers serving public procurement networks.
- Dominican Republic Production Concentration:Regional manufacturing gravity around a single Caribbean hub creates exposure to logistics disruptions and currency fluctuation risk.
- COFEPRIS Documentation Burden:Mexico's medical device registration requirements impose extended clinical evidence timelines that delay product commercialization for foreign suppliers.
Strategic Opportunities
- Chilean Medical School Integration:Minimally invasive surgery training program proliferation is creating captive demand channels for simulation-compatible instrument platforms.
- Mercosur Technical Standard Alignment:Convergence between Brazilian ANVISA protocols and Argentine national pharmacovigilance frameworks is reducing multi-country compliance overhead.
- Direct Hospital Contracting Models:Bypassing traditional distributor layers through dedicated service agreements with Colombian tertiary care networks captures margin previously allocated to intermediaries.
Industry Challenges
- Specialized Surgical Instrument Technician Scarcity:Training pipeline gaps in Brazil constrain operating room throughput despite available equipment capacity.
- ISO 13485 Certification Timeline Compression:Accelerated supplier qualification requirements for regional tender processes strain quality management system implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America General Surgical Devices Market |
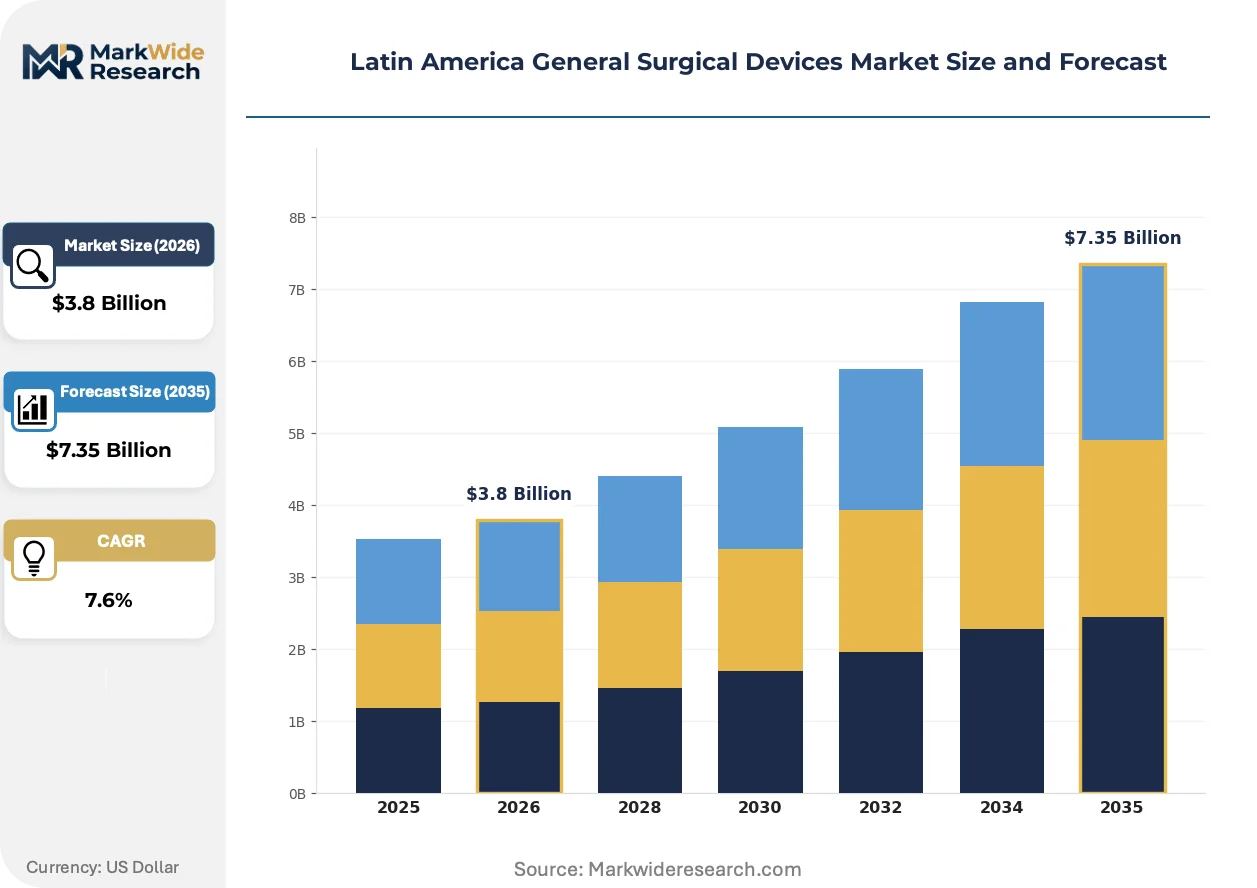
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrosurgical Devices, Sutures, Staplers, Surgical Scissors End User: Hospitals, Ambulatory Surgical Centers, Clinics, Surgical Centers Delivery Mode: Open Surgery, Minimally Invasive Surgery, Robotic Surgery, Laparoscopic Surgery Application: Cardiothoracic Surgery, Orthopedic Surgery, General Surgery, Neurosurgery |
| Companies Covered | Boston Scientific Corporation, Johnson & Johnson, Medtronic, Stryker Corporation, Getinge AB, Olympus Corporation, B. Braun Melsungen AG, Conmed Corporation, Smith and Nephew plc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America General Surgical Devices Market Shifts & Advancements
Energy-delivery precision requirements are reshaping competitive positioning across Latin American surgical device markets. Three convergent developments are redefining product architecture, regulatory compliance, and procurement behavior.
Radiofrequency ablation platforms are fragmenting traditional electrosurgical market segments by enabling tissue-specific energy modulation. Colombian university hospitals are adopting these systems at accelerated pace for hepatobiliary procedures. This capability expansion is fragmenting vendor lock-in patterns as surgeons demand instrument interchangeability across energy modalities.
COFEPRIS in Mexico is tightening post-market surveillance protocols for Class IIb and Class III surgical instruments through enhanced adverse event reporting mandates. Manufacturers must now maintain localized clinical safety databases as a condition of registration renewal. Mexican border-state surgical corridors are responding by consolidating supplier relationships toward entities with established pharmacovigilance infrastructure.
Public hospital networks in Brazil are unbundling after-sales service from capital equipment contracts to reduce total cost of ownership. Independent technical service providers are displacing manufacturer-captive service organizations in São Paulo and Rio de Janeiro metropolitan procurement. This unbundling is most visible in suture and stapler categories where standardized maintenance protocols reduce dependency on original equipment manufacturer expertise.
Latin America General Surgical Devices Market Segmentation
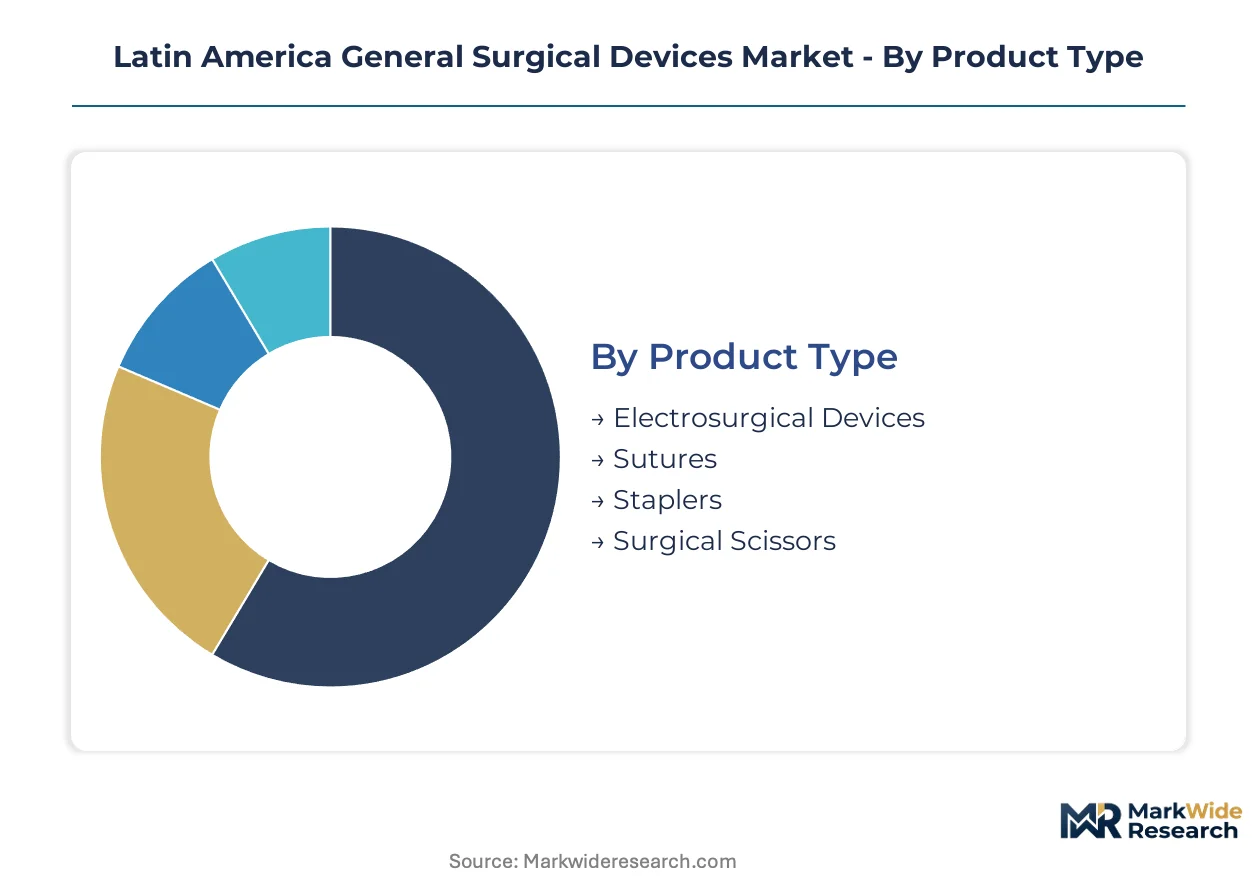
Channel configuration across Latin America varies sharply by product complexity and regulatory classification. Electrosurgical platforms flow through manufacturer-direct hospital contracts, while commoditized consumables navigate layered distributor networks. Understanding these pathway distinctions shapes procurement strategy and margin capture potential.
Product Type:
Channel economics diverge substantially across instrument categories, with capital-intensive platforms commanding direct sales relationships while consumables tolerate intermediary markups.
- Electrosurgical Devices:Energy-delivery systems incorporating radiofrequency generators and specialized electrodes require intensive clinical training support. Brazilian teaching hospital networks concentrate demand for integrated platforms that combine cutting, coagulation, and vessel sealing modalities.
- Sutures:Absorbable and non-absorbable wound closure materials manufactured from synthetic polymers or natural collagen derivatives. Mexican border-state surgical corridors generate high-volume procurement through centralized public health tenders where cost-per-unit dominates selection criteria.
- Staplers:Mechanical wound closure devices deployed across gastrointestinal and thoracic procedures.
- Surgical Scissors:Precision cutting instruments fabricated from medical-grade stainless steel or tungsten carbide alloys.
By volume, Sutures leads procurement tonnage across public hospital networks. By growth pace, Electrosurgical Devices is ahead as metropolitan centers upgrade energy platforms.
End User:
Facility scale determines instrument sophistication requirements and service contract complexity, with tertiary institutions demanding integrated solutions while smaller sites prioritize capital efficiency.
- Hospitals:Multi-specialty institutions performing complex operative procedures across cardiothoracic, orthopedic, and neurosurgical disciplines. São Paulo and Rio de Janeiro metropolitan networks are expanding surgical capacity to clear pandemic-era procedure backlogs.
- Ambulatory Surgical Centers:Same-day procedure facilities optimized for efficiency and rapid patient throughput. Colombian outpatient networks are adopting disposable instrument kits to minimize sterilization infrastructure investment.
- Clinics:Limited-procedure settings focused on minor surgical interventions and wound management.
- Surgical Centers:Dedicated operative facilities concentrating on high-volume, standardized procedures.
Procurement concentration tilts toward Hospitals for capital equipment. Ambulatory Surgical Centers is climbing the fastest as same-day procedure migration accelerates.
Delivery Mode:
Technological trajectory across surgical approaches is reshaping training requirements and instrument design specifications throughout the region.
- Open Surgery:Traditional operative approach with direct tissue visualization through large incisions. Public hospital networks in Brazil's northern states retain substantial volume due to infrastructure constraints limiting minimally invasive adoption.
- Minimally Invasive Surgery:Laparoscopic and endoscopic techniques reducing tissue trauma and recovery intervals. Chilean medical schools are embedding simulation-based training programs that create captive demand for compatible instrument platforms.
- Robotic Surgery:Computer-assisted operative systems enabling precision manipulation through telemanipulation interfaces.
- Laparoscopic Surgery:Abdominal and pelvic procedures performed through small port incisions using specialized elongated instruments.
Procedure volume still favors Open Surgery across resource-constrained settings. Minimally Invasive Surgery is gaining share fastest as training infrastructure proliferates.
Application:
Specialty-specific instrument requirements create distinct procurement patterns tied to reimbursement structures and procedure reimbursement rates.
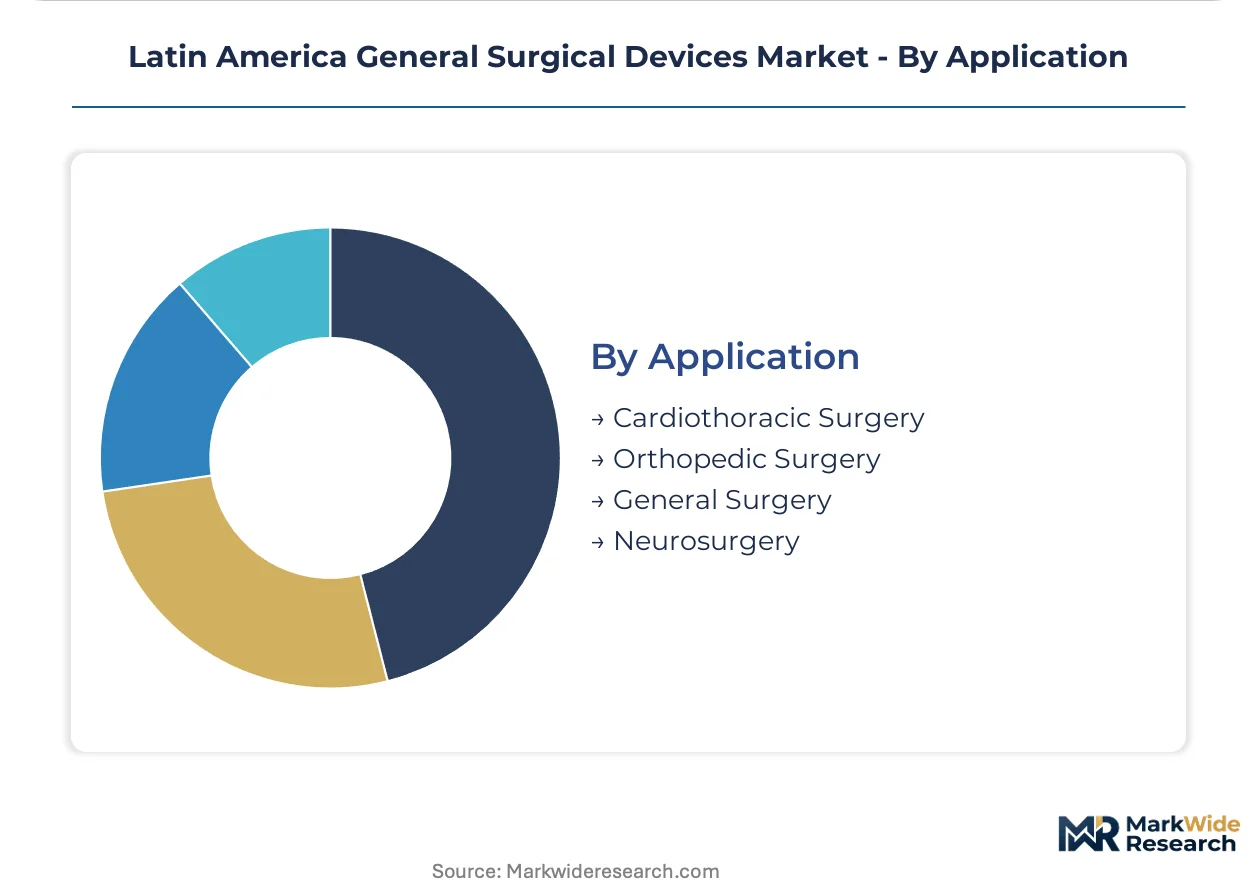
- Cardiothoracic Surgery:Procedures involving heart, lung, and mediastinal structures requiring precision suturing and sternal fixation systems. Argentine cardiac centers are consolidating supplier relationships toward vendors with established regional technical service presence.
- Orthopedic Surgery:Bone and joint procedures utilizing powered instrumentation and specialized implant delivery systems. Brazilian private hospital networks are expanding arthroscopy capacity to capture sports medicine demand.
- General Surgery:Abdominal, gastrointestinal, and soft tissue procedures spanning open and minimally invasive approaches.
- Neurosurgery:Central and peripheral nervous system interventions demanding microsurgical precision instruments.
General Surgery captures the broadest procedure volume across mixed-specialty institutions. Cardiothoracic Surgery shows the steepest expansion trajectory as regional cardiac referral networks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates capital equipment procurement for electrosurgical platforms while Mexican border-state surgical corridors drive high-volume suture consumption through centralized public health tenders.
Brazil
São Paulo and Rio de Janeiro metropolitan hospital networks are expanding surgical capacity to clear pandemic-era procedure backlogs. ANVISA updated Class III medical device registration pathways are compressing approval timelines for precision electrosurgical instruments. Teaching hospitals across these metropolitan clusters are anchoring demand for integrated energy platforms that combine cutting, coagulation, and vessel sealing modalities.
Mexico
Border-state surgical corridors generate concentrated procurement volume for wound closure materials through federal health system tenders. COFEPRIS post-market surveillance protocols for Class IIb and III instruments now require localized clinical safety databases for registration renewal. Tijuana and Ciudad Juárez surgical hubs are consolidating supplier relationships toward entities with established pharmacovigilance infrastructure.
Argentina
Cardiac centers in Buenos Aires and Córdoba are consolidating supplier relationships toward vendors with regional technical service presence. The national pharmacovigilance framework is converging with Mercosur technical standards to reduce multi-country compliance overhead. Argentine tertiary care networks are expanding cardiothoracic procedure capacity as regional cardiac referral networks mature.
Chile
Medical schools in Santiago and Valparaíso are embedding simulation-based training programs that create captive demand for compatible instrument platforms. University hospitals are adopting radiofrequency ablation systems at accelerated pace for hepatobiliary procedures. This capability expansion is fragmenting vendor lock-in patterns as surgeons demand instrument interchangeability across energy modalities.
Colombia
Outpatient surgical networks in Bogotá and Medellín are adopting disposable instrument kits to minimize sterilization infrastructure investment. Direct hospital contracting models are bypassing traditional distributor layers through dedicated service agreements with tertiary care networks. Colombian ambulatory surgical centers are capturing margin previously allocated to intermediaries through unbundled procurement structures.
Latin America General Surgical Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on procedure-specific instrumentation and regional service density. The integrated tier commands direct hospital contracts for capital-intensive electrosurgical platforms, while specialists capture consumables volume through layered distributor networks. Three archetypes define competitive positioning: diversified medical technology conglomerates with broad surgical portfolios, precision instrument specialists with concentrated manufacturing scale, and regional service-anchored suppliers with localized technical support infrastructure. Capacity expansion and portfolio diversification represent the dominant competitive moves as players address backlogged procedure demand.
Within the diversified conglomerate tier, Medtronic plc and Johnson & Johnson occupy positions that exemplify integrated portfolio breadth, while B. Braun Melsungen AG represents manufacturing-scale specialists with regional production infrastructure. Boston Scientific Corporation and Stryker Corporation anchor the precision technology segment with positions in advanced surgical platforms. These entities collectively illustrate the competitive tension between global scale and regional service density that shapes procurement outcomes across Latin American hospital networks.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Johnson & Johnson |
| Medtronic |
| Stryker Corporation |
| Getinge AB |
| Olympus Corporation |
| B. Braun Melsungen AG |
| Conmed Corporation |
| Smith and Nephew plc |
| Others |
Supply & Pricing Matrix
Regional manufacturing scale in the Dominican Republic shapes both supply concentration and price floors for electrosurgical platforms across Latin America. Brazilian metropolitan hospital networks leverage volume procurement to compress margins on commoditized sutures while premium energy systems retain pricing power through clinical training bundling.
Pricing Analysis
Long-term service contracts anchor capital equipment procurement in Brazilian teaching hospitals, while spot purchasing dominates consumable replenishment in Mexican public health tenders. Price differentiation rests on ISO 13485 certification tier and after-sales service bundling, with premium electrosurgical systems commanding substantial markups over standard instrument sets. Cost compression in suture categories is intensifying because public procurement networks unbundle maintenance from capital contracts. Ambulatory surgical centers exhibit highest price sensitivity due to sterilization infrastructure constraints, while tertiary cardiac centers prioritize performance over unit cost.
Supply Chain Analysis
The Dominican Republic anchors regional production for precision surgical instruments, while Germany and the United States supply specialized electrosurgical generators and energy platforms. Raw material dependencies center on medical-grade stainless steel from European mills, titanium alloys from aerospace supply chains, and polymer composites from North American chemical producers. Single-source vulnerability concentrates around Caribbean manufacturing hubs exposed to hurricane disruption and currency fluctuation. Distribution runs through manufacturer-direct hospital contracts for capital platforms and layered distributor networks for high-volume consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates substantial switching costs for hospital procurement committees. ANVISA and COFEPRIS registration pathways lock in approved suppliers and extend replacement timelines for foreign entrants.
For Market Incumbents: Shield market position by deepening technical service infrastructure in São Paulo and Rio de Janeiro metropolitan clusters where independent service providers threaten manufacturer-captive organizations. Expand backward integration into polymer composite instrument coatings to capture margin from sterilization degradation solutions and offset stainless steel price volatility.
For New Entrants and Emerging Players: Differentiate on simulation-compatible instrument platforms for Chilean medical school training programs where captive demand channels remain underdeveloped. Target Colombian ambulatory surgical centers with disposable kit solutions that minimize sterilization capital requirements and bypass entrenched distributor relationships through direct contracting models.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision instrument specialists with established regional pharmacovigilance infrastructure over diversified conglomerates facing margin compression in commoditized categories. Acquisition candidates should demonstrate localized clinical safety databases for COFEPRIS compliance and technical service density in Brazilian metropolitan networks. The signal to watch is consolidation of supplier relationships in Mexican border-state surgical corridors toward entities with adverse event reporting capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Pathway Investment | Accelerated Class III approval timelines compress competitive entry windows for precision electrosurgical instruments in Brazilian teaching hospitals. |
| Hospital System Partnership | Dedicated service agreements with Colombian tertiary care networks capture margin previously allocated to traditional distributor intermediaries. |
| Software Companion Development | Simulation-based training integration with Chilean medical school curricula creates captive demand channels for compatible laparoscopic platforms. |
| CE Marking Pathway Alignment | European certification convergence with Mercosur technical standards reduces multi-country compliance overhead for regional expansion. |
| Reimbursement Strategy | Public hospital network unbundling of after-sales service from capital contracts reshapes total cost of ownership calculations in São Paulo procurement. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and ANVISA regulatory consultants; and secondary validation through hospital procurement databases, ANVISA registration filings, COFEPRIS adverse event reports, and GPO contract disclosure records. Bottom-up instrument shipment analysis triangulated against top-down healthcare expenditure modeling.
The projection horizon spans the full analysis window with segmentation across product type, end user facility scale, delivery mode, and application specialty. CAGRs derived from procedure volume elasticity models incorporating surgical capacity expansion timelines, training program proliferation rates, and regulatory approval velocity. Forecast inputs include pandemic backlog clearance trajectories in Brazilian metropolitan networks and polymer composite adoption curves in Mexican border-state corridors.
The analysis sits within stated boundaries; outcomes outside sustained ANVISA modernization pace or COFEPRIS documentation burden stability would require recalibration. Forecasts reflect assumptions around surgical technician training pipeline expansion and medical-grade alloy price normalization. Recalibration cycles align with material shifts in Mercosur technical standard convergence and independent service provider displacement rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cervical Spine System Market
Medical Devices
3D Printed Brain Model Market
Medical Devices
Global Cardiopulmonary Bypass Accessory Equipment Market
Medical Devices
Implant Handpiece Market
Medical Devices
Global Advanced Drug Delivery Systems Market
Medical Devices
Peri-Implantitis Market
Medical Devices
Cervical Disc Prosthesis Market
Medical Devices
Intravenous Access Devices Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
Lumbar Disc Replacement Device Market
Medical Devices
Infusion Pump Market
Medical Devices
Oxygen Conserving Devices Market
Medical Devices
Germany Respiratory Devices Market
Medical Devices
Surgical Incision Closure Devices Market
Medical Devices
Germany Anesthesia Devices Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market