
 Magnetic Plastics Market | 2026-2036
Magnetic Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Plastics Market Intelligence
Automotive OEM buyers are gaining share as consumer electronics procurement plateaus, and demand is bifurcating between high-performance rare-earth polymer magnets for EV powertrain sensors and cost-optimized ferrite-filled compounds for auxiliary motors. TDK Corporation leverages its materials science heritage to dominate rare-earth polymer formulations for precision automotive applications. Arnold Magnetic Technologies sustains competitive position through vertical integration into bonded magnet powder sourcing and tight tolerance manufacturing. Hitachi Metals Ltd. anchors Asian supply chains with advanced compression-molded neodymium polymer magnets for industrial servo systems.
Magnetic plastics are polymer-matrix composites embedding hard ferrite, neodymium-iron-boron, or samarium-cobalt particles in thermoplastic or thermoset binders, typically achieving remanence values of 0.2–0.5 Tesla and coercivity sufficient for operating temperatures up to 150°C depending on filler loading and binder selection. These materials serve industrial and commercial purposes where complex geometries, corrosion resistance, or electrical insulation preclude sintered metal magnets. Flexible magnets in sheet and strip form occupy mature, high-volume segments with thin margin pools, while rigid composite magnets in custom-molded shapes capture premium pricing due to tighter dimensional tolerances and higher energy products. Medical device applications represent the fastest-growing demand channel, driven by miniaturized diagnostic equipment and drug delivery mechanisms requiring biocompatible, magnetically actuated components.
EPA regulations in the United States restrict volatile organic compound emissions during magnet compounding and molding processes, while REACH and RoHS in Europe impose substance restrictions on cadmium, lead, and certain phthalate plasticizers used in flexible magnet formulations. FDA device classification rules further shape medical-grade magnetic plastic specifications, requiring extractables and biocompatibility testing for implantable or patient-contact applications. Stakeholders must monitor evolving rare-earth export controls and substitution incentives across multiple jurisdictions, as supply security for neodymium and dysprosium feedstocks increasingly determines formulation strategy and geographic sourcing decisions.
Market Dynamics
Automotive electrification is compressing magnet procurement cycles as OEMs demand bonded ferrite and rare-earth polymer magnets for integrated motor-sensor assemblies, forcing compounders to compress development timelines from 18 months to under 9 months.
Growth Catalysts
- EV Powertrain Integration:Electric vehicle manufacturers in Germany, Japan, and the United States are embedding magnetic plastics directly into motor housings and position sensors, eliminating separate magnet assembly steps.
- REACH Substance Restrictions:European halogen-free mandates are redirecting formulation R&D toward low-cobalt samarium-cobalt alternatives and bio-based polymer binders that maintain magnetic performance at elevated temperatures.
- Medical Device Miniaturization:Diagnostic equipment manufacturers require biocompatible, magnetically actuated drug delivery mechanisms and implantable sensors that sintered metal magnets cannot achieve due to corrosion and geometry constraints.
Market Restraints
- Rare-Earth Supply Concentration:Neodymium and dysprosium feedstock dependency on Chinese processing infrastructure creates price volatility and export control exposure that disrupts long-term compounder contracting.
- High-Performance Ferrite Cost Floor:Strontium and barium ferrite raw material costs have established a pricing basement that prevents bonded magnet producers from competing with sintered ferrite on purely cost-driven auxiliary motor applications.
- RoHS Heavy-Metal Limits:Cadmium and lead restrictions in European flexible magnet formulations force reformulation of legacy calendar-sheet products, eroding margin pools in mature high-volume segments.
Strategic Opportunities
- India Industrial Automation:PLI scheme incentives for domestic manufacturing equipment are creating first-mover advantages for magnet compounders establishing local bonded ferrite production near Pune and Chennai automotive clusters.
- FDA Breakthrough Device Pathway:Expedited review timelines for magnetically actuated implantable drug delivery systems are compressing commercialization cycles for medical-grade magnetic plastic suppliers with established biocompatibility testing protocols.
- Halogen-Free Thermoplastic Vulcanizate Convergence:Crosslinking advances in TPV binders are enabling injection-molded magnets with flexible magnet sheet conformability and rigid composite dimensional stability in a single material platform.
Industry Challenges
- Magnetician Talent Scarcity:Formulation chemistry expertise combining rare-earth powder metallurgy with polymer rheology resides in a shrinking cohort of specialists nearing retirement, constraining R&D throughput at mid-scale compounders.
- ISO 13485 Medical Certification Timelines:Eighteen to twenty-four month quality management system audits for implantable magnet applications delay revenue recognition and tie up working capital in pre-commercial inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Plastics Market |
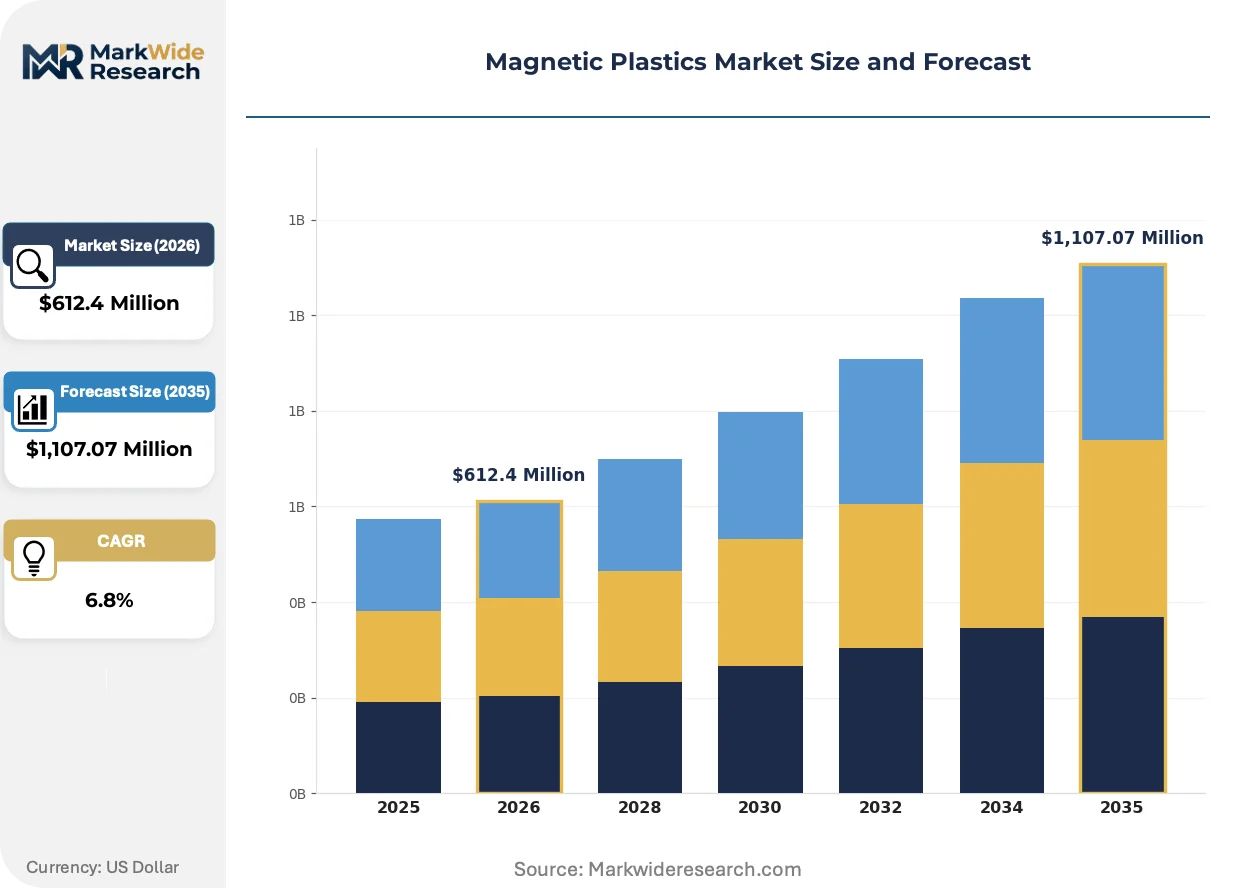
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Magnets, Composite Magnets, Flexible Magnets, Rigid Magnets Application: Consumer Electronics, Automotive Components, Medical Devices, Industrial Equipment End User: OEMs, Aftermarket Suppliers, Distributors, Retailers Form: Sheets, Rods, Disks, Custom Shapes |
| Companies Covered | 3M Company, Arnold Magnetic Technologies, TDK Corporation, Hitachi Metals Ltd., Daido Steel Co. Ltd., Kolektor Magnet Technology GmbH, ALL Magnetics Inc., Eclipse Magnetics Ltd., Sura Magnets AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Plastics Market Strategic Shifts & Innovations
Magnetic plastics are undergoing functional specialization as end-users trade commodity flexible sheet for application-specific molded compounds with integrated thermal management and electromagnetic shielding properties.
Multi-pole magnetization technology is miniaturizing. Advanced impulse magnetization equipment achieves 100+ poles per inch in thin-wall injection-molded rings, enabling compact encoder resolutions previously requiring bulkier sintered magnet assemblies. Medical device manufacturers in Switzerland and Germany are adopting these micro-pole configurations for surgical navigation sensors and miniature pump actuators. The technology is miniaturizing diagnostic equipment form factors while maintaining magnetic field uniformity across complex curved geometries.
EPA volatile organic compound emission rules under the Clean Air Act are tightening compounding facility permitting requirements. Magnet producers in Ohio and Michigan face capital expenditures for thermal oxidizers and solvent recovery systems that smaller compounders cannot absorb. The regulatory pressure is consolidating North American bonded magnet production toward integrated chemical companies with existing emissions control infrastructure.
Automotive Tier-1 suppliers are unbundling magnet procurement from motor assembly contracts. Previously captive magnet operations at Bosch, Continental, and Denso are spinning out to specialized compounders as OEMs demand transparent rare-earth provenance and carbon footprint documentation. This disintermediation is most advanced in Germany, where Stuttgart-based automotive clusters now source bonded neodymium polymer magnets through independent compounders with certified conflict-mineral supply chains.
Magnetic Plastics Market Segmentation
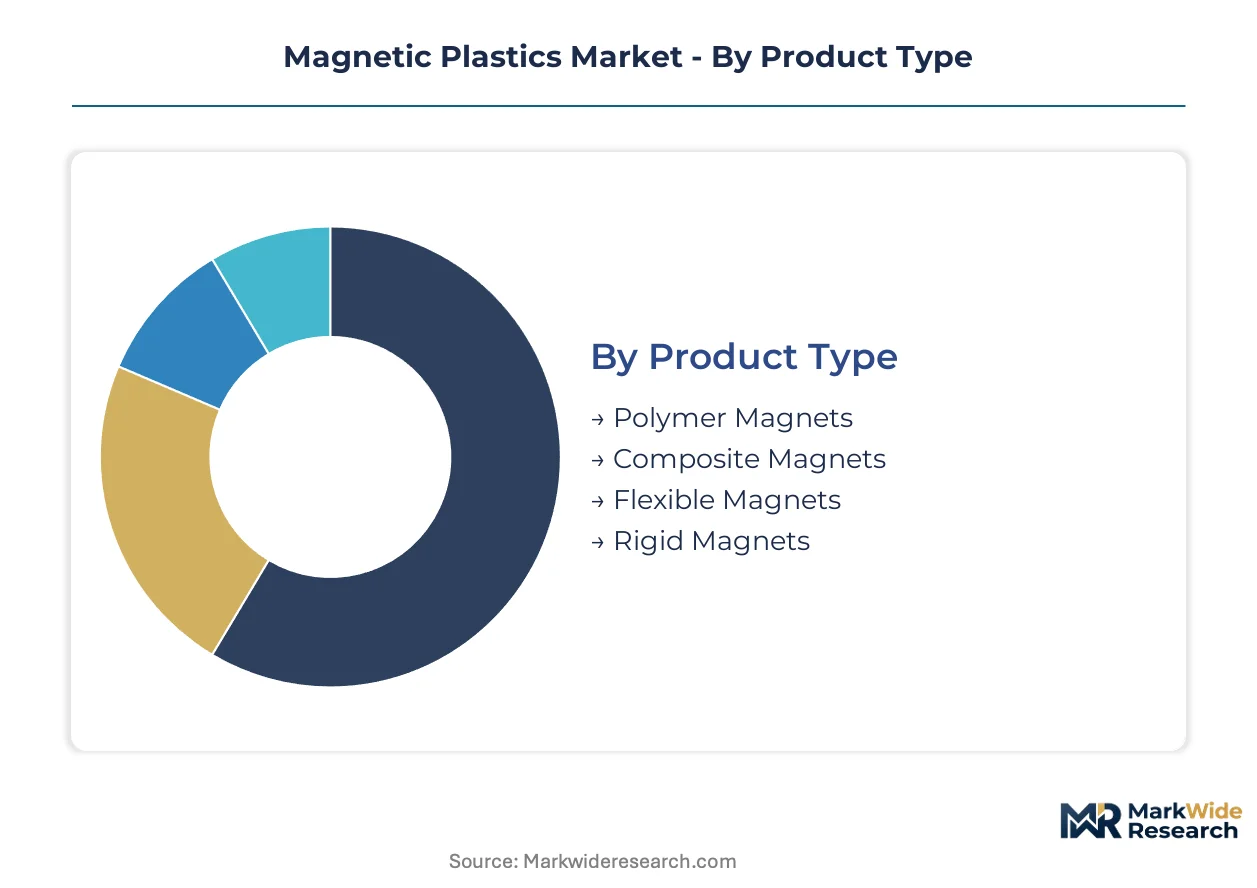
Magnetic plastics serve heterogeneous demand profiles that strain uniform manufacturing approaches. Product form, application requirements, and channel economics create distinct margin pools that compounders must navigate through specialized equipment and formulation expertise.
Product Type:
Channel economics diverge sharply: flexible sheet products flow through distribution networks serving sign-making and packaging industries, while rigid composite magnets move through direct OEM contracting with automotive and medical device manufacturers.
- Polymer Magnets:Thermoplastic matrices loaded with ferrite or rare-earth powders achieve remanence values up to 0.4 Tesla through injection molding. Demand concentrates in Germany's automotive sensor clusters around Stuttgart, where Bosch and Continental source bonded neodymium formulations for integrated motor-sensor assemblies. REACH substance restrictions on heavy-metal content are redirecting formulation R&D toward halogen-free polymer binders that maintain magnetic performance at 150°C operating temperatures.
- Composite Magnets:Compression-molded compounds with thermoset binders deliver higher dimensional stability and energy products for precision industrial servo systems. Japanese industrial automation OEMs in the Nagoya manufacturing belt specify these materials for robotic joint actuators requiring tight tolerance repeatability. EPA volatile organic compound emission rules under the Clean Air Act are tightening compounding facility permitting requirements for North American producers of thermoset-based formulations.
- Flexible Magnets:Calendar-extruded ferrite-filled elastomers in sheet and strip configurations serve mature, high-volume segments with thin margin pools. The refrigerator gasket and point-of-purchase display industries in the United States and Western Europe represent core demand channels.
- Rigid Magnets:Injection-molded or compression-molded shapes with fixed geometries capture premium pricing through tighter dimensional tolerances and custom magnetization patterns. Swiss and German medical device manufacturers specify these for surgical navigation sensors requiring micro-pole configurations.
By volume, flexible magnets lead. By growth pace, rigid magnets are expanding most quickly.
Application:
Cost tiers stratify across applications: medical devices command formulation premiums for biocompatibility certification, while industrial equipment operates on cost-optimized ferrite specifications with minimal regulatory overhead.
- Consumer Electronics:Miniature speakers, vibration motors, and sensor housings in smartphones and wearables. Procurement from Chinese and Vietnamese contract manufacturers has plateaued as device form factors stabilize.
- Automotive Components:Electric motor position sensors, actuator housings, and integrated powertrain assemblies. German OEM supply chains around Munich and Stuttgart are embedding magnetic plastics directly into motor housings, eliminating separate magnet assembly steps.
- Medical Devices:Biocompatible, magnetically actuated drug delivery mechanisms and implantable sensors. FDA device classification rules require extractables and biocompatibility testing that sintered metal magnets cannot satisfy due to corrosion constraints.
- Industrial Equipment:Conveyor systems, separation equipment, and automation machinery. India's PLI scheme incentives for domestic manufacturing equipment are creating first-mover advantages for bonded ferrite production near Pune and Chennai automotive clusters.
Medical devices command the steepest pricing tiers. Automotive components are climbing the fastest.
End User:
Customer type determines contracting structure: OEMs demand transparent rare-earth provenance and carbon footprint documentation, while aftermarket channels prioritize inventory availability and price competitiveness.
- OEMs:Direct procurement from compounders with certified conflict-mineral supply chains and ISO 13485 quality management systems. Automotive electrification is compressing magnet procurement cycles from 18 months to under 9 months.
- Aftermarket Suppliers:Replacement magnet components for industrial equipment maintenance and repair. Price sensitivity dominates purchasing decisions with minimal technical specification negotiation.
- Distributors:Stocking flexible magnet sheet products for sign-making, packaging, and point-of-purchase display industries. Inventory turnover velocity determines supplier relationships.
- Retailers:Consumer-facing sales of magnetic craft products, educational materials, and hobbyist supplies. Seasonal demand patterns and private-label sourcing characterize this channel.
OEMs concentrate the highest value contracts. Distributors move the largest unit volumes.
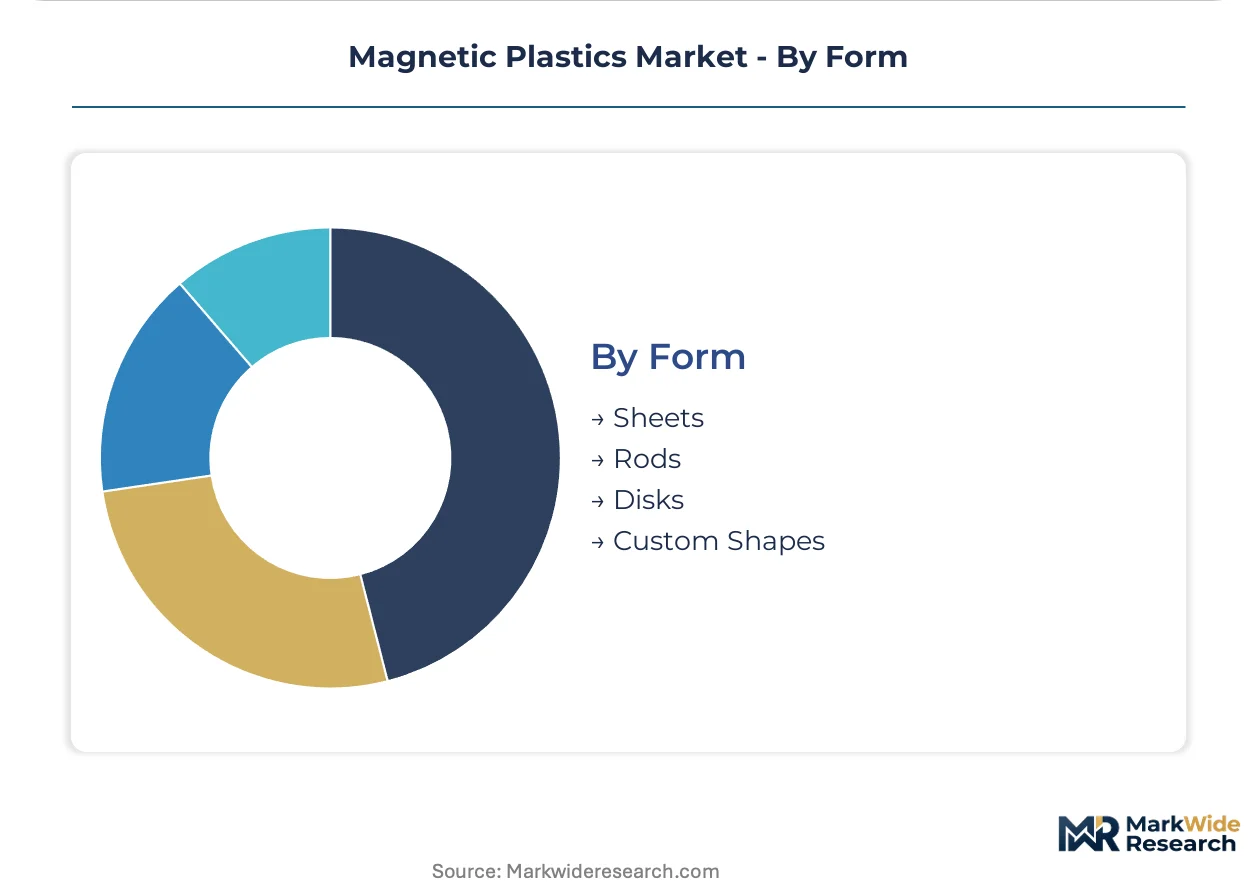
Form:
Manufacturing scale and tooling investment separate form categories: sheets and rods amortize capital across high-volume runs, while custom shapes require program-specific mold investments with dedicated capacity commitments.
- Sheets:Flexible magnet material in continuous rolls or cut-to-length formats for advertising displays, vehicle signage, and gasket applications. Calendar-extrusion equipment in Ohio and Michigan faces EPA thermal oxidizer capital expenditure requirements.
- Rods:Cylindrical extrusions for sensor housings, actuator cores, and industrial separation equipment. Diameter tolerances and straightness specifications determine grade classification.
- Disks:Punch-pressed or molded circular geometries for speaker assemblies, magnetic couplings, and holding applications. Multi-pole magnetization patterns enable compact encoder resolutions.
- Custom Shapes:Application-specific geometries with integrated mounting features, thermal management structures, or electromagnetic shielding properties. FDA breakthrough device pathway expedited reviews are compressing commercialization cycles for implantable configurations.
Sheets dominate unit volume. Custom shapes are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Magnet compounders cluster near automotive OEM supply chains and rare-earth processing infrastructure. Germany, Japan, China, the United States, and India concentrate distinct competitive advantages across formulation expertise, feedstock access, and end-user proximity.
Germany
Automotive electrification drives procurement of bonded neodymium formulations for integrated motor-sensor assemblies. REACH and RoHS substance restrictions redirect R&D toward halogen-free polymer binders and low-cobalt alternatives. Stuttgart and Munich host dense clusters of magnet compounders serving Bosch and Continental supply chains.
Japan
Industrial automation OEMs specify compression-molded compounds for robotic joint actuators requiring tight tolerance repeatability. METI rare-earth stockpiling programs mitigate supply disruption risks from Chinese processing concentration. Nagoya manufacturing belt anchors domestic compounder capacity for precision servo systems.
China
Neodymium and dysprosium processing infrastructure supplies global feedstock for rare-earth polymer formulations. MEE environmental compliance tightening forces compounding facility upgrades in magnet production zones. Shenzhen and Dongguan electronics clusters consume flexible magnet sheet for consumer device assemblies.
United States
EPA Clean Air Act volatile organic compound rules tighten permitting for thermoset-based compounding operations in Ohio and Michigan. FDA breakthrough device pathway expedites commercialization for implantable magnet applications. Medical device manufacturers in Massachusetts and Minnesota drive biocompatible formulation demand.
India
PLI scheme incentives for domestic manufacturing equipment create first-mover opportunities for bonded ferrite production. BIS quality standards harmonization accelerates supplier qualification for automotive Tier-1 procurement. Pune and Chennai automotive clusters attract compounder investments for auxiliary motor applications.
Magnetic Plastics Market Key Industry Players
Concentration sits with integrated materials specialists and captive powder producers. The vendor base spans three tiers: multinational chemical conglomerates with emissions control infrastructure, mid-scale compounders with automotive certification, and regional flexible magnet converters. Strategic moves center on backward integration into rare-earth powder sourcing and geographic expansion toward Indian automotive clusters.
Among Japanese and European materials conglomerates, TDK Corporation, Arnold Magnetic Technologies, and Hitachi Metals Ltd. exemplify distinct archetypes. TDK anchors rare-earth polymer formulation heritage for precision applications. Arnold Magnetic Technologies represents vertical integration into bonded magnet powder sourcing. Hitachi Metals Ltd. occupies a position in advanced compression-molded compounds for industrial servo systems. These three entities illustrate the competitive spectrum from materials science depth to manufacturing tolerance control.
| Leading Market Players |
|---|
| 3M Company |
| Arnold Magnetic Technologies |
| TDK Corporation |
| Hitachi Metals Ltd. |
| Daido Steel Co. Ltd. |
| Kolektor Magnet Technology GmbH |
| ALL Magnetics Inc. |
| Eclipse Magnetics Ltd. |
| Sura Magnets AB |
| Others |
Cost & Logistics Intelligence
Eighteen-month magnet procurement cycles collapsing to nine months concentrates pricing power with compounders holding certified rare-earth provenance and ISO 13485 quality systems, while automotive OEMs absorb premium markups for bonded neodymium formulations with transparent supply chains.
Pricing Analysis
REACH and RoHS substance restrictions dictate the pricing tier structure across the Magnetic Plastics Market, separating halogen-free certified grades for automotive sensors from legacy ferrite compounds facing cadmium reformulation costs. Price differentiation rests on biocompatibility certification level and rare-earth loading density, with medical-grade formulations commanding substantial premiums over industrial ferrite specifications. Cost compression in flexible magnet sheet segments is intensifying because RoHS heavy-metal limits force calendar-extrusion line conversions. Aftermarket distributors exhibit the highest price sensitivity, while German automotive OEMs prioritize supply security over unit cost.
Supply Chain Analysis
Rare-earth oxide processing infrastructure in China, Japan, and Germany constitutes the critical chokepoint anchoring global bonded magnet production, with neodymium and dysprosium feedstock concentration creating single-source vulnerability for Western compounders. Raw material dependencies span strontium ferrite powders, thermoplastic binder resins, and samarium-cobalt alloys. Tariff exposure on Chinese-processed rare-earth oxides disrupts long-term contracting stability. Distribution runs through direct OEM contracting for rigid composite magnets and wholesale distribution networks for flexible sheet products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic plastics occupy an early-cycle expansion phase as automotive electrification penetrates powertrain sensor architectures and FDA breakthrough pathways accelerate implantable device commercialization timelines.
For Market Incumbents: Consolidate backward integration into bonded magnet powder sourcing to secure rare-earth feedstock independence from Chinese processing concentration. Expand halogen-free formulation capacity near Stuttgart and Munich automotive clusters before REACH substance restrictions tighten further. Captive supply of neodymium-iron-boron powders defends margin position against price volatility from export control exposure.
For New Entrants and Emerging Players: Differentiate on medical-grade biocompatibility certification by establishing ISO 13485 quality systems ahead of FDA breakthrough device pathway submissions. India's PLI scheme incentives for domestic manufacturing equipment represent the most penetrable geography, with Pune and Chennai automotive clusters underserved by local bonded ferrite production. Pursue joint development agreements with Swiss and German surgical navigation sensor manufacturers requiring micro-pole magnetization capabilities.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across halogen-free thermoplastic vulcanizate compounding lines as EPA thermal oxidizer requirements consolidate North American production toward integrated chemical companies. Five-to-ten year viability favors compounders with dual automotive and medical certification portfolios. Acquisition targets should display established biocompatibility testing protocols and conflict-mineral supply chain documentation. Monitor METI rare-earth stockpiling program expansions as an inflection signal for Japanese supply security investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Powder Sourcing | Captive neodymium-iron-boron supply insulates compounders from Chinese export control volatility. |
| Halogen-Free Polymer Binder Development | REACH-compliant formulations unlock German automotive OEM procurement with 150°C thermal stability. |
| ISO 13485 Quality System Certification | Medical device manufacturer qualification enables FDA breakthrough pathway participation for implantable magnets. |
| Geographic Expansion to Indian Automotive Clusters | PLI scheme incentives near Pune and Chennai capture first-mover advantages in auxiliary motor applications. |
| Multi-Pole Magnetization Equipment Investment | Advanced impulse magnetization achieves 100+ poles per inch for Swiss surgical navigation sensor specifications. |
Research Approach
Cross-validation between primary interviews with magnet compounder technical directors, automotive Tier-1 procurement managers, and medical device biomedical engineers anchors the qualitative findings against secondary validation from customs trade data, SEC filings of listed materials companies, and EPA Clean Air Act permitting records. Bottom-up modeling of injection-molding capacity and top-down triangulation of end-use demand from vehicle production databases and hospital procurement systems converged on segment-level estimates.
Sensitivity analysis across rare-earth price volatility bands, REACH substance restriction implementation timelines, and automotive electrification penetration curves tested forecast robustness throughout the projection horizon. Segmentation dimensions modeled include product form, application vertical, end-user contracting structure, and geographic production cluster. CAGRs were derived from fitted growth curves against historical bonded magnet shipment data and forward-looking OEM platform engineering specifications.
Material uncertainties — rare-earth export control escalations, REACH heavy-metal limit revisions, and FDA biocompatibility testing protocol updates — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as regulatory enforcement intensity and automotive platform standardization decisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Magnetic Filter Market
Magnetic Materials
Japan Neodymium Iron Boron Magnet Market
Magnetic Materials
Europe Copper Magnetic Wire Market
Magnetic Materials
North America Samarium Cobalt Magnets Market
Magnetic Materials
High Purity Carbonyl Iron Powder (CIP) Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Magnetorheological Fluid Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
Magnetostrictive Materials Market
Magnetic Materials
Global Bonded Magnet Market
Magnetic Materials
Copper Magnet Wire Market
Magnetic Materials
Superconducting Magnets Market
Magnetic Materials
Europe Ferrite Magnet Market
Magnetic Materials
Ferrofluid Market
Magnetic Materials
Asia-Pacific Magnet Wire Market