
 Ferromanganese Market | 2026-2036
Ferromanganese Market Size, Share, and Industry Trends Forecast 2026-2036
Ferromanganese Market Intelligence
Long-term supply agreements between alloy producers and integrated steel mills are reshaping procurement patterns across the ferromanganese value chain. Ferroglobe plc leverages its European smelting footprint to sustain premium positioning in specialty grades. Tata Steel Limited anchors Indian demand through captive consumption at its Jamshedpur complex. Eramet Group competes on African ore access, while Vale SA dominates Brazilian manganese ore supply to Asian converters.
Ferromanganese is an iron-manganese alloy typically containing 65-80% manganese by weight, produced through carbothermic reduction of manganese ore in submerged arc furnaces for steel deoxidation and sulfur fixation. High carbon ferromanganese retains the largest volume share due to its cost efficiency in basic oxygen steelmaking, though silicomanganese gains traction as a dual-purpose alloying agent. Medium and low carbon variants command margin premiums from specialty steel mills and foundry alloy applications where carbon control determines final product specifications.
China's MEE enforces GB emission standards on ferroalloy smelters, while India's CEA mandates energy efficiency benchmarks for designated consumers under the PAT scheme. The EU Green Deal and REACH frameworks increasingly restrict carbon-intensive alloy imports, redirecting trade flows toward certified lower-carbon supply sources. Stakeholders must monitor evolving border carbon adjustments and ore traceability requirements that will redefine competitive access to European and North American steel mill customers.
Market Dynamics
China's dual carbon goals and stricter GB emission standards on alloy smelters are compressing the cost-competitive advantage of conventional high-carbon production, forcing converters toward low-carbon process retrofits and captive renewable energy integration.
Growth Catalysts
- Steel mill electrification:Electric arc furnace expansion across Asia-Pacific drives specification-grade ferromanganese demand for deoxidation and sulfur control in scrap-based steelmaking.
- EU Green Deal border adjustments:Carbon-intensive alloy imports face mounting compliance costs, redirecting procurement toward certified lower-carbon supply sources with traceable ore provenance.
- India's PAT scheme energy benchmarks:Designated consumers under CEA mandates must improve specific energy consumption, accelerating adoption of submerged arc furnace efficiency retrofits.
Market Restraints
- Manganese ore supply concentration:African and Brazilian ore deposits dominate feedstock availability, exposing converters to geopolitical disruption and port logistics bottlenecks.
- Power cost volatility:Ferroalloy smelting requires 3,500-4,500 kWh per tonne; grid electricity price spikes in energy-importing regions erode margin sustainability.
- Silicomanganese substitution:Dual-purpose alloying agents displace pure ferromanganese in certain carbon steel grades, compressing volume in standardized applications.
Strategic Opportunities
- Low-carbon certification premiums:Renewable-powered smelting in hydroelectric-rich geographies commands price premiums from European specialty steel mills under CSRD supply chain disclosure rules.
- Scrap-based manganese recovery:Urban mining and battery recycling streams offer emerging secondary feedstock channels as primary ore grades decline.
- Digital furnace optimization:AI-driven electrode positioning and raw material blending algorithms reduce specific energy consumption below legacy operational benchmarks.
Industry Challenges
- Smelter engineering talent scarcity:Experienced furnace operators and process metallurgists with carbothermic reduction expertise are aging out of the workforce faster than training programs replenish capacity.
- GB standard compliance timelines:Chinese smelters face compressed retrofit deadlines for particulate and SO2 emissions, requiring capital deployment amid margin pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferromanganese Market |
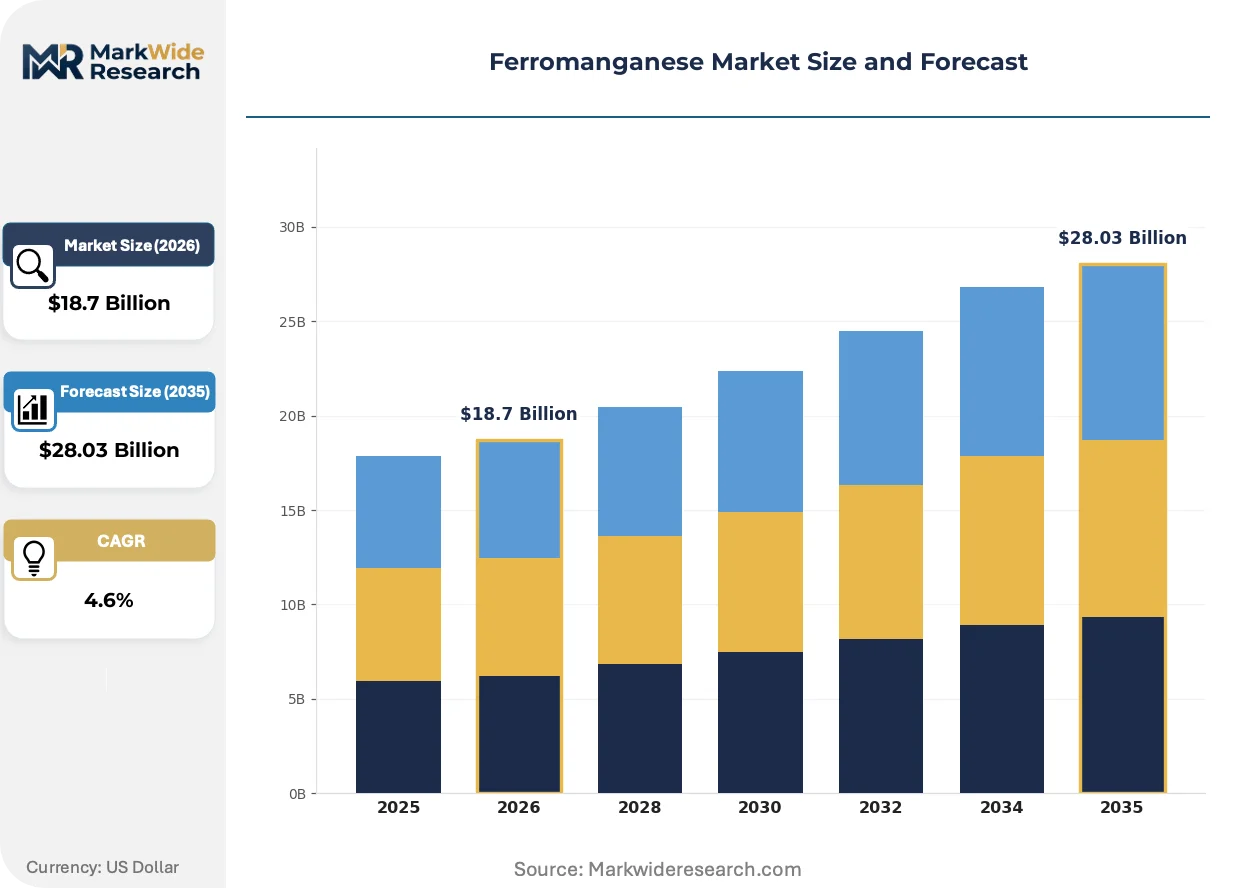
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Carbon Ferromanganese, Medium Carbon Ferromanganese, Low Carbon Ferromanganese, Silicomanganese Application: Steel Production, Foundry Alloys, Welding Electrodes, Chemical Industry End User Industry: Steel Mills, Foundries, Welding Manufacturers, Chemical Processors Packaging Type: Bags, Bulk, Sacks, Drums |
| Companies Covered | Ferroglobe plc, Anglo American plc, Tata Steel Limited, Monnet Group, Eurasian Resources Group Sàrl, Vale SA, Glencore plc, Maithan Alloys Limited, Eramet Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferromanganese Market Strategic Shifts & Innovations
Process intensification and regulatory carbon accounting are converging to redefine competitive advantage in ferromanganese production, with technology adoption now inseparable from market access permissions.
Pre-reduced manganese ore technologies are collapsing the energy intensity of submerged arc furnace operations by completing partial metallization outside the electric smelting unit. European converters with access to natural gas or hydrogen reduction circuits are piloting this shift to secure EU Green Deal compliance. The structural consequence is collapsing the cost gap between conventional high-carbon production and certified low-carbon variants.
China's MEE enforcement of GB emission standards on ferroalloy smelters is tightening particulate and sulfur dioxide discharge limits with real-time monitoring mandates. Smaller converters without flue gas treatment infrastructure face operational suspension or forced consolidation. Medium-carbon ferromanganese producers serving automotive steel specifications are most affected, accelerating relocation to industrial parks with centralized waste handling.
Steel mill procurement departments are consolidating supplier panels and demanding cradle-to-gate carbon declarations with third-party verification. Long-term offtake agreements now embed emissions performance clauses that adjust pricing bands based on certified carbon intensity. This behavioral shift is most visible in Germany and the Netherlands, where automaker supply chain mandates cascade into alloy purchasing specifications.
Ferromanganese Market Segmentation
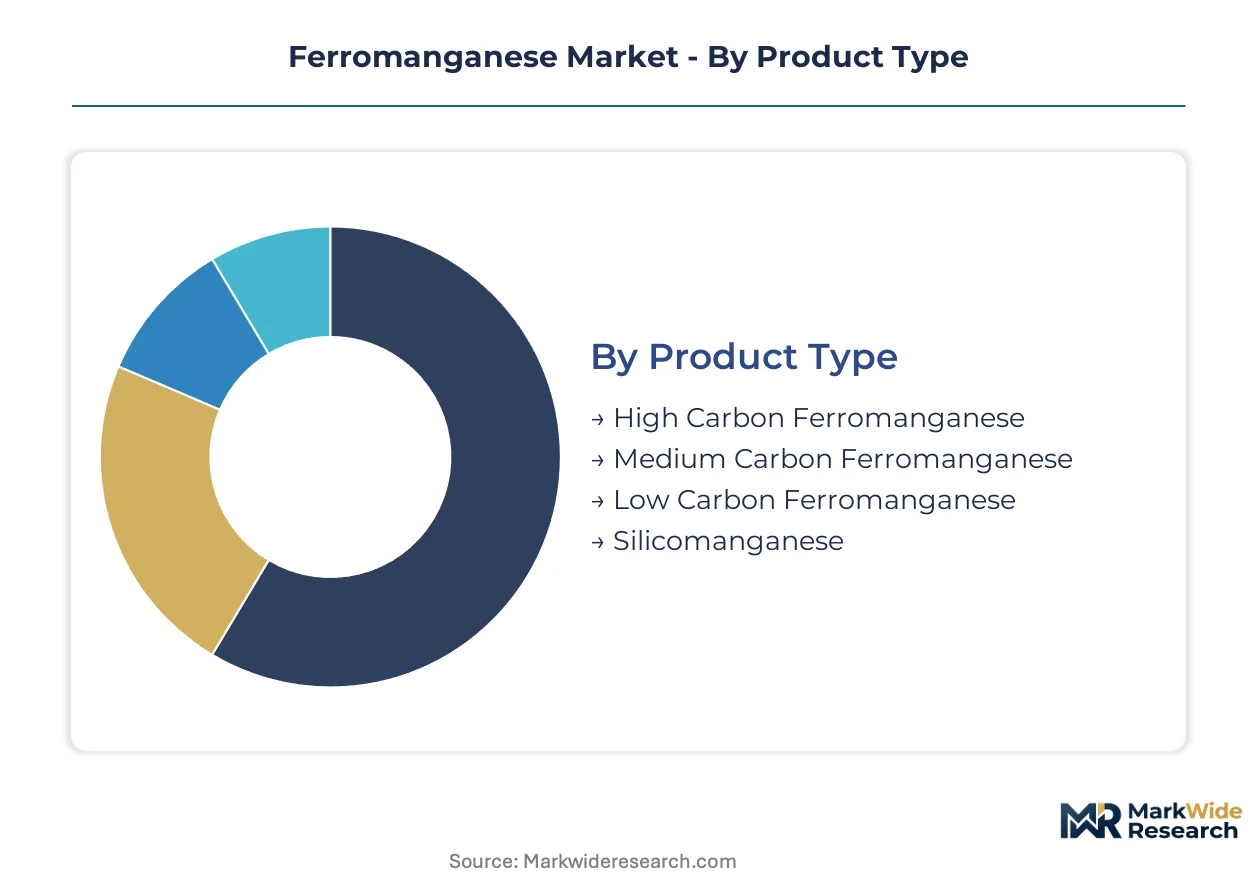
Ferromanganese segmentation reflects divergent technical specifications across steelmaking chemistry requirements, foundry precision demands, and chemical processing purity standards. Product carbon content, application metallurgy, and end-user operational scale each create distinct procurement patterns and margin structures.
Product Type:
Carbon control requirements span from basic oxygen furnace bulk additions to ultra-low carbon stainless steel specifications, creating a four-tier alloy hierarchy.
- High Carbon Ferromanganese:Contains 65-80% manganese with 6-8% carbon content, produced through conventional submerged arc furnace carbothermic reduction. Steel mills in India's eastern industrial corridor—JSPL and Tata Steel's Jamshedpur complex—consume this grade for cost-efficient deoxidation in carbon steel production, though China's GB emission standards are compressing margin sustainability for conventional smelters.
- Silicomanganese:Dual-purpose alloy with 65-68% manganese and 18-22% silicon enables simultaneous deoxidation and alloying in electric arc furnace operations. Asia-Pacific steel mill electrification is accelerating specification-grade procurement of this variant for scrap-based steelmaking, displacing pure ferromanganese in standardized carbon steel grades.
- Medium Carbon Ferromanganese:1-2% carbon content serves automotive and specialty steel specifications where controlled carbon pickup is critical. Chinese smelters face MEE enforcement pressures on particulate emissions, forcing relocation to industrial parks with centralized waste handling.
- Low Carbon Ferromanganese:Below 0.5% carbon content commands premium positioning from European specialty steel mills under CSRD supply chain disclosure rules. Renewable-powered smelting in hydroelectric-rich geographies captures certification premiums.
The dominant share belongs to High Carbon Ferromanganese, while Silicomanganese is closing the gap fastest.
Application:
End-use metallurgy determines alloy specification, with steel chemistry control representing the volume anchor against specialized foundry and chemical niches.
- Steel Production:Deoxidation and sulfur fixation in basic oxygen and electric arc furnace operations consume the majority of ferromanganese volume. India's CEA PAT scheme mandates energy efficiency benchmarks for designated steel consumers, accelerating submerged arc furnace retrofits across integrated complexes.
- Foundry Alloys:Precision manganese additions for gray iron and ductile iron casting require tightly controlled carbon and silicon specifications. Medium and low carbon variants penetrate this segment where final product mechanical properties are sensitive to residual chemistry.
- Welding Electrodes:Flux-cored wire and coated electrode formulations utilize ferromanganese for arc stability and deposit metal alloying. Specification-grade procurement from welding manufacturers follows distinct certification protocols separate from bulk steel mill purchasing.
- Chemical Industry:Battery-grade manganese sulfate precursors and specialty chemical applications demand high-purity manganese units with trace element controls below steelmaking tolerances.
Steel Production retains the volume majority, yet Foundry Alloys generates the steepest margin expansion trajectory.
End User Industry:
Customer operational scale and technical sophistication stratify procurement behavior from bulk commodity offtake to specification-certified supply agreements.
- Steel Mills:Integrated producers and electric arc furnace operators dominate consumption through long-term supply agreements with embedded emissions performance clauses. German and Dutch procurement departments now mandate cradle-to-gate carbon declarations with third-party verification.
- Foundries:Smaller batch requirements and alloy precision needs create fragmented supplier relationships distinct from steel mill panel consolidation. Energy efficiency retrofits are less capital-intensive given smaller furnace footprints.
- Welding Manufacturers:Flux and wire producers source specification-grade material with certification protocols tied to electrode performance standards. Procurement volumes scale with infrastructure construction cycles.
- Chemical Processors:Battery precursor and specialty chemical applications drive purity requirements exceeding conventional ferromanganese specifications, often requiring secondary refining or alternative manganese units.
Steel Mills command procurement gravity, while Chemical Processors are expanding most quickly.
Packaging Type:
Logistics economics and material handling infrastructure determine packaging selection across ocean freight, inland distribution, and plant-level consumption patterns.
- Bulk:Vessel and railcar shipments serve integrated steel complexes with dedicated unloading infrastructure. Port logistics bottlenecks in African and Brazilian ore supply chains extend to finished alloy distribution.
- Bags:50kg woven polypropylene units facilitate manual handling at foundries and smaller welding electrode producers lacking bulk handling equipment.
- Sacks:Multi-layer paper or polymer sacks offer moisture protection for coastal storage conditions and extended inventory holding.
- Drums:Sealed steel containers serve chemical industry applications requiring contamination prevention and precise batch traceability.
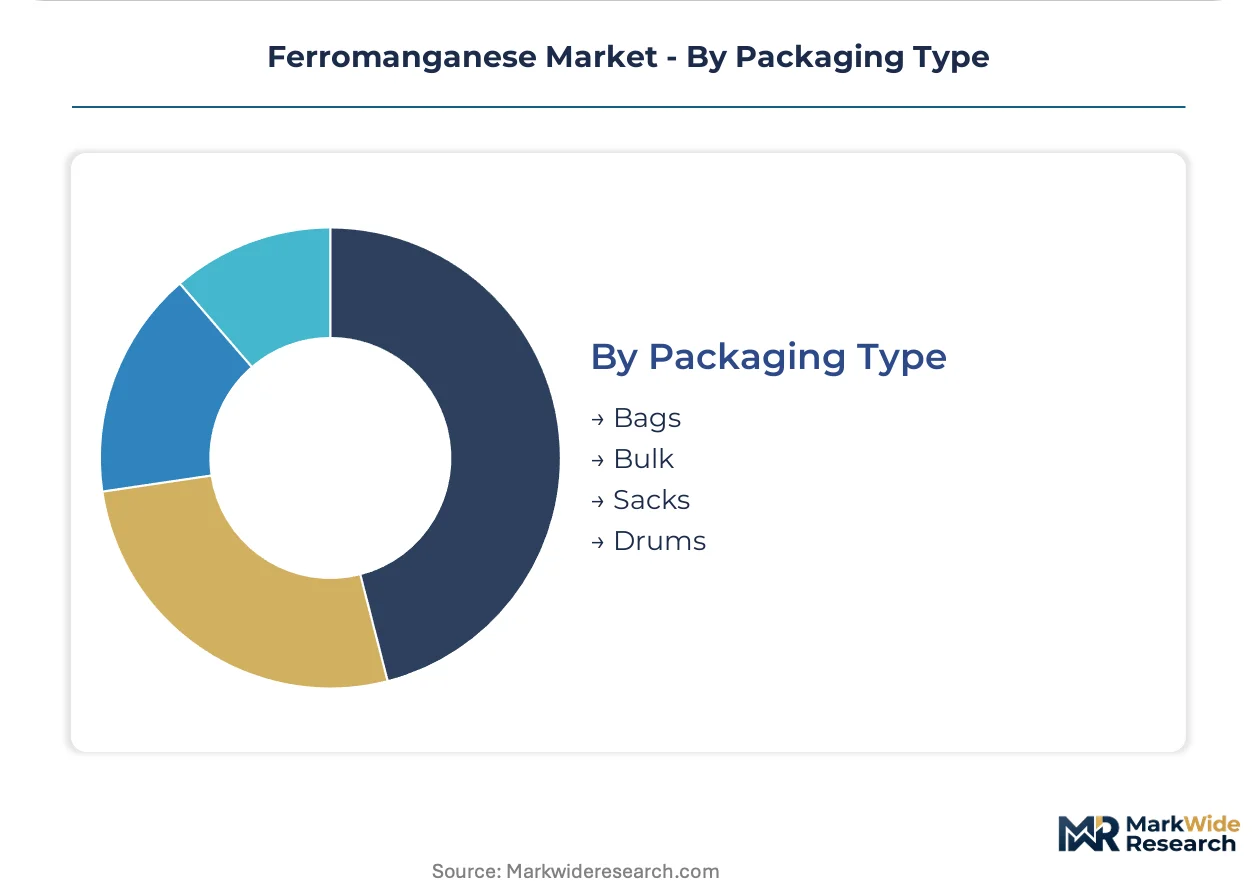
Bulk shipments dominate tonnage, though Bags capture the fastest share gain among smaller end users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan Port complex underwrites China's dominance in ferromanganese trade flows, handling ore imports from South Africa and Australia while dispatching finished alloys to Southeast Asian steel mills.
China
Submerged arc furnace clusters in Guangxi and Guizhou provinces process manganese ore from South African bulk carriers. The MEE enforces GB emission standards with real-time monitoring mandates, forcing smaller smelters toward consolidation or industrial park relocation. Ningbo-Zhoushan's deepwater berths enable direct ore-to-alloy logistics that compress inland transport costs.
India
JSPL and Tata Steel operate integrated ferromanganese complexes along the eastern industrial corridor from Jamshedpur to Raipur. The CEA mandates energy efficiency benchmarks under the PAT scheme for designated consumers, accelerating furnace retrofits. Visakhapatnam port serves as the primary import gateway for Gabonese and Australian ore feedstock.
South Africa
The Kalahari Manganese Field supplies high-grade ore to domestic smelters in the Northern Cape and Mpumalanga provinces. Eskom's grid instability forces converters toward captive solar installations and diesel backup systems. Port Elizabeth and Richards Bay handle bulk ore exports to Asian alloy producers.
Brazil
Vale SA dominates manganese ore extraction in the Carajás mineral province, shipping through São Luís port to Chinese and Indian converters. The National Mining Agency enforces tailings dam safety protocols that extend to manganese operations. Integrated logistics corridors link mine sites to Atlantic shipping terminals.
Norway
Hydroelectric-powered smelters in Mo i Rana and Sauda produce low-carbon ferromanganese for European specialty steel mills. The EU Green Deal border adjustment mechanism rewards renewable-powered production with preferential market access. Fjord-side locations enable direct bulk shipping to Rotterdam and Hamburg steel clusters.
Ferromanganese Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream. The ferromanganese sector exhibits tiered consolidation around ore-accessible geographies and energy-advantaged smelting locations. Three archetypes dominate: diversified mining conglomerates with captive ore reserves, integrated steel producers with captive alloy consumption, and independent smelters competing on power cost positioning. Capacity expansion into hydroelectric-rich jurisdictions and strategic ore offtake agreements represent the dominant competitive vectors.
Among diversified mining conglomerates, Vale SA and Anglo American plc exemplify ore-accessible positioning through Brazilian and South African deposit control. Ferroglobe plc occupies a position within the European specialty tier, leveraging Nordic hydroelectric infrastructure for low-carbon production certification. Tata Steel Limited anchors the integrated steel producer archetype through captive consumption at its Jamshedpur complex, representing backward integration into alloy supply security.
| Leading Market Players |
|---|
| Ferroglobe plc |
| Anglo American plc |
| Tata Steel Limited |
| Monnet Group |
| Eurasian Resources Group Sàrl |
| Vale SA |
| Glencore plc |
| Maithan Alloys Limited |
| Eramet Group |
| Others |
Cost & Logistics Intelligence
The Ningbo-Zhoushan Port complex compresses freight economics for manganese ore imports while amplifying price differentiation between carbon-intensive and certified low-carbon ferromanganese grades destined for European specialty steel mills.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates renewable-powered low-carbon certification grades from conventional high-carbon production and silicomanganese substitutes. Price differentiation rests on carbon intensity certification and volume scale in long-term offtake agreements. Pricing pressure stems from China's GB emission compliance costs compressing margin sustainability for conventional smelters. Integrated steel mills with captive consumption exhibit lowest price sensitivity; independent foundries purchasing bagged quantities face highest cost pass-through vulnerability.
Supply Chain Analysis
Export-control regimes on critical mineral processing technologies limit equipment flows to certain smelter modernization programs. Geographic supply concentrates in South Africa's Kalahari Manganese Field, Brazil's Carajás province, and Australia's Groote Eylandt deposits. Raw material dependencies span high-grade manganese ore, metallurgical coke, and grid or captive power infrastructure. Supply chain risk centers on Eskom grid instability forcing South African converters toward diesel backup systems. Distribution runs through long-term supply agreements with embedded emissions performance clauses rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ferromanganese sits in early-cycle expansion as electric arc furnace electrification across Asia-Pacific steel mills accelerates specification-grade procurement for scrap-based steelmaking chemistry control.
For Market Incumbents: Insulate margin position through backward integration into African ore offtake agreements and captive renewable energy installations in hydroelectric-rich geographies. Threats from silicomanganese substitution in standardized carbon steel grades demand defensive certification investment for automotive-grade medium-carbon specifications. Priority levers include submerged arc furnace efficiency retrofits and centralized industrial park relocation to satisfy MEE particulate enforcement timelines.
For New Entrants and Emerging Players: Pursue white-space opportunities in battery-grade manganese sulfate precursor supply to chemical processors, where purity requirements exceed conventional ferromanganese specifications. India's eastern industrial corridor around Raipur offers penetrable geography with fragmented foundry alloy demand. Go-to-market positioning should emphasize urban mining and scrap-based manganese recovery streams as secondary feedstock channels.
For Investors and Strategic Acquirers: Hydroelectric-powered Nordic smelters with EU Green Deal compliance certification represent the most defensible acquisition archetype for long-term viability across the projection horizon. Signal to watch: German and Dutch steel mill procurement departments mandating cradle-to-gate carbon declarations with third-party verification, which will bifurcate valuation multiples between certified and conventional supply sources.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Embeds emissions performance clauses that adjust pricing bands based on certified carbon intensity. |
| Backward Integration | Captures African ore deposit access through offtake agreements with South African and Brazilian miners. |
| Green Manufacturing Transition | Secures EU Green Deal border adjustment preferential access via renewable-powered smelting in Norway. |
| Capacity Expansion | Adds submerged arc furnace capacity in industrial parks with centralized flue gas treatment infrastructure. |
| Joint Venture | Combines ore reserve control with power cost positioning through partnerships in hydroelectric-rich geographies. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews with submerged arc furnace operators, steel mill procurement directors, foundry metallurgists, and ferroalloy distribution channel partners. Secondary validation drew from customs and trade flow databases, SEC filings of diversified mining conglomerates, CEA PAT scheme energy consumption disclosures, and EU ETS carbon accounting registries. Bottom-up alloy production estimates and top-down steel consumption models were triangulated to cross-verify volume assumptions.
Calibration against historical price differentials between carbon grades and documented furnace efficiency benchmarks anchored the analytical framework across the analysis window. Segmentation dimensions modeled include carbon content tier, end-use application metallurgy, and regional regulatory compliance cluster. CAGRs were derived from steel production forecasts and electric arc furnace penetration assumptions, with specific inputs for India's PAT scheme energy efficiency trajectories and China's MEE emission standard compliance timelines.
Macroeconomic conditions sit as an overlay; deviation in grid electricity pricing volatility or manganese ore freight rates would shift the trajectory. Forecasts reflect assumptions on regulatory enforcement continuity and technology adoption curves for pre-reduced ore processing. Material shifts in EU border carbon adjustment implementation scope or Chinese smelter consolidation pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Neodymium [Nd-Fe-B] Magnet Market
Magnetic Materials
Sintered Magnet Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
Samarium Cobalt Magnets Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
North America Magnet Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Nanocrystalline Soft Magnetic Material Market
Magnetic Materials
Cobalt Oxide Market
Magnetic Materials
Magnetic Filter Market
Magnetic Materials
Sintered Soft Magnetic Material Market
Magnetic Materials
High Purity Carbonyl Iron Powder (CIP) Market
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
Neodymium-Iron-Boron Magnet Market