

High Performance Permanent Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Permanent Magnet Market Insights
Modular magnet assemblies is decoupling from monolithic rotor designs, letting buyers swap magnetic blocks rather than replace entire motor cores. Proterial leverages integrated powder-to-magnet manufacturing to control neodymium supply from mine to finished arc segment. TDK Corporation anchors its position through sintering scale in Japan and bonded magnet specialization for miniature electronics. Shin-Etsu Chemical dominates rare-earth alloy production, sustaining pricing power through captive intermediate processing.
High performance permanent magnets are intermetallic compounds—chiefly NdFeB and SmCo—engineered to deliver maximum energy product exceeding 30 MGOe with high coercivity against demagnetization. Sintering produces the densest grades for traction motors and wind generators where flux density and thermal resilience matter most. Neodymium Iron Boron occupies the dominant volume position across electric vehicle platforms and direct-drive wind turbines. Samarium Cobalt competes in aerospace and defense applications where operational temperatures exceed NdFeB thresholds. Bonding technology is carving faster growth in robotics and medical devices requiring complex geometries that sintering cannot economically achieve.
China's Ministry of Industry and Information Technology governs rare-earth extraction quotas and downstream magnet export licensing, directly constraining non-Chinese manufacturers' feedstock access. The EU REACH regulation and F-Gas framework are pressing OEMs to document supply chain provenance and phase out fluorinated process gases in magnet coating operations. The US Department of Defense and Department of Energy are separately funding domestic rare-earth separation and magnet manufacturing through defense production authorities and clean energy loan programs. Stakeholders must weigh concentrated supply risk against the capital intensity of building alternative rare-earth processing corridors before committing to long-term offtake agreements.
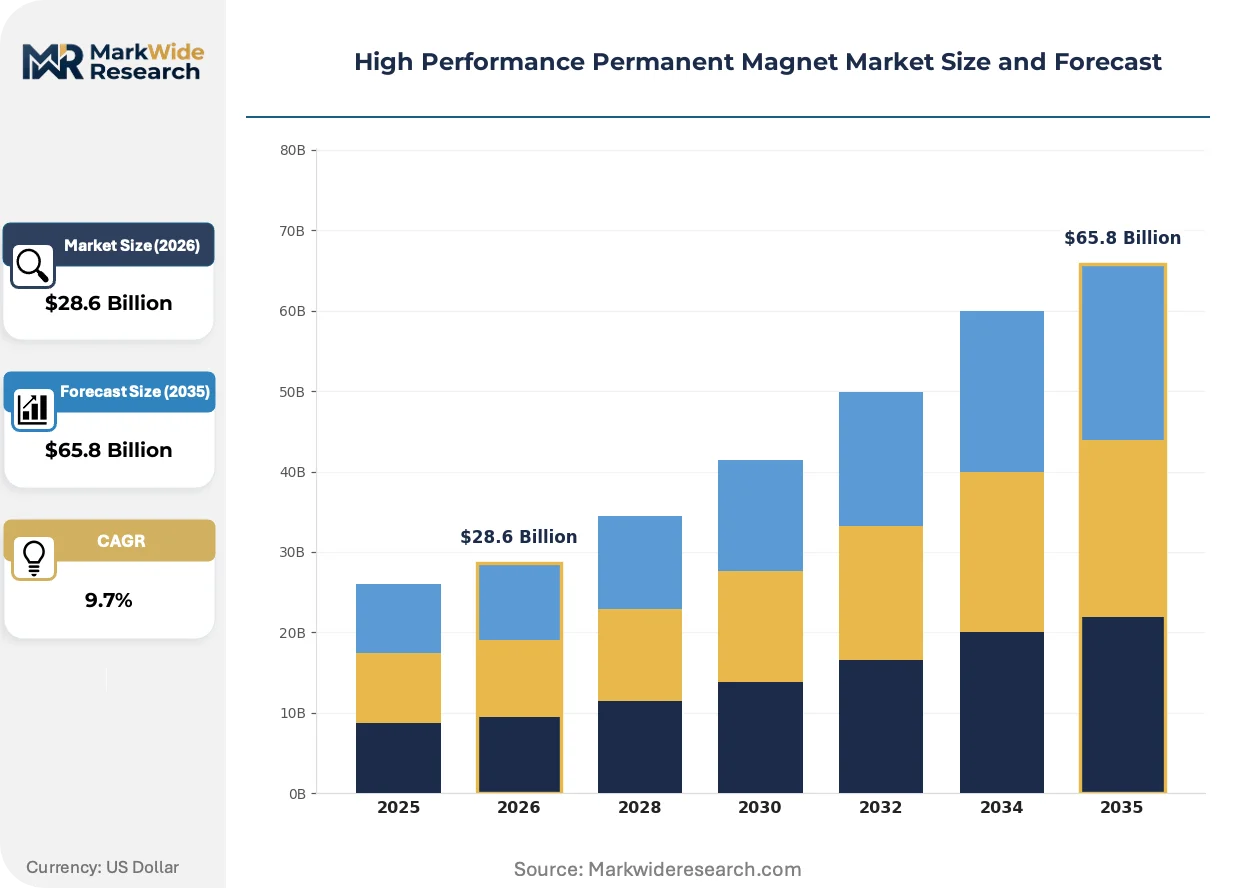
Market Dynamics
China's export licensing regime for processed rare earths has concentrated feedstock control within its borders, forcing non-Chinese magnet fabricators to restructure procurement corridors and accelerate alternative separation investments.
Growth Catalysts
- Electric vehicle traction motor mandates:Automotive OEMs in Germany and South Korea are locking in multi-year offtake agreements for sintered NdFeB arc segments to meet fleet electrification targets under national carbon neutrality frameworks.
- REACH and F-Gas regulatory pressure:The EU's phased restrictions on fluorinated process gases in magnet coating operations are accelerating adoption of aqueous-based surface treatment technologies across European fabrication clusters.
- Direct-drive wind turbine scaling:Offshore wind developers in Denmark and the United Kingdom are specifying high-temperature-grade NdFeB for 15+ MW generators, pulling volume through specialized magnet supply chains.
Market Restraints
- Rare-earth oxide price volatility:Neodymium and dysprosium oxide spot markets swing 40-60% annually, compressing magnet fabricator margins and destabilizing long-term contract pricing.
- Intermediate processing concentration:Separation and refining capacity for heavy rare earths concentrates in southern China provinces, creating single-point-of-failure exposure for non-domestic magnet manufacturers.
- Samarium Cobalt thermal ceiling:SmCo magnets face substitution pressure from high-temperature-stabilized NdFeB grades above 180°C operating thresholds in aerospace generator applications.
Strategic Opportunities
- Domestic rare-earth corridors:The US Department of Energy loan programs and Defense Production Act funding are de-risking magnet manufacturing investments in Texas and California to reduce import dependency.
- Medical device miniaturization:Bonded NdFeB injection molding is penetrating surgical robotics and implantable drug delivery systems requiring sub-millimeter dimensional tolerances.
- Dual carbon policy alignment:China's MIIT rare-earth extraction quotas tied to carbon intensity benchmarks are creating preferential feedstock access for magnet producers with verified low-carbon separation partnerships.
Industry Challenges
- Rare-earth metallurgy expertise scarcity:Magnet alloy formulation and hydrogen decrepitation process engineering talent concentrates within legacy Japanese and Chinese facilities, constraining new entrant scale-up.
- Multi-site certification timelines:IATF 16949 automotive quality system audits and customer-specific production part approval processes extend new supplier qualification to 18-24 months.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Permanent Magnet Market Trends and Innovations
Magnet fabrication is bifurcating between massive sintered blocks for traction motors and precision-bonded geometries for robotics, with process innovation racing to bridge the performance gap between the two pathways.
Grain boundary diffusion technology is overtaking conventional single-alloy sintering as the dominant method for achieving high coercivity in reduced-heavy-rare-earth NdFeB formulations. Tier-1 automotive suppliers in Japan and Germany are qualifying diffusion-treated arc segments for 800V inverter-driven traction motors. This metallurgical advance is compressing dysprosium and terbium intensity per kilogram of finished magnet by 30-50%, reshaping rare-earth procurement hedging strategies.
The EU F-Gas Regulation's progressive ban on sulfur hexafluoride and perfluorocarbon process gases is compelling magnet coaters to retrofit physical vapor deposition and plasma electrolytic oxidation lines. Surface treatment houses in Slovakia and Poland are absorbing capital costs for aqueous conversion coating systems to retain wind energy OEM contracts. This environmental compliance wave is fragmenting coating service availability and extending lead times for corrosion-protected magnet deliveries to northern European markets.
Magnet buyers are consolidating supplier panels from 8-12 qualified vendors to 3-4 strategic partners with captive rare-earth sourcing. Wind turbine OEMs in Spain and Italy are embedding magnet fabricators within blade and nacelle assembly joint ventures to secure volume allocation during feedstock shortages. This relational contracting model is displacing spot-market purchasing and locking in multi-year price-volume agreements with indexed rare-earth pass-through mechanisms.
High Performance Permanent Magnet Market Segmentation
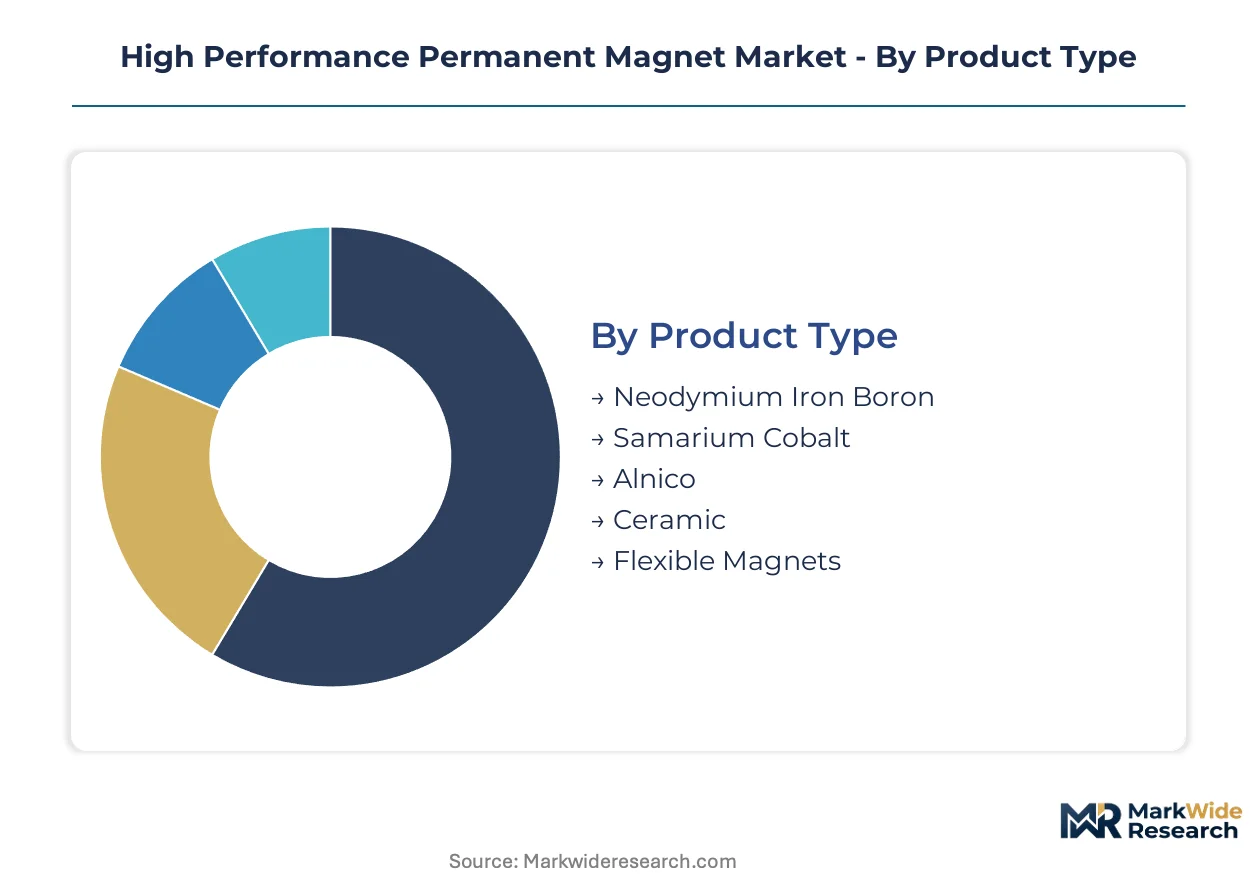
Magnet specification and fabrication method determine integration depth across end-use systems. Standalone magnetic subassemblies serve discrete replacement markets, while embedded grades bond permanently into motor laminates and sensor housings.
Product Type:
Integration depth varies sharply: NdFeB and SmCo embed irreplaceably into traction motor rotors and aerospace generators, while Alnico and ceramic magnets often slot into field-serviceable subassemblies.
- Neodymium Iron Boron:Intermetallic Nd2Fe14B compound delivers energy products exceeding 50 MGOe with coercivity stabilized through dysprosium grain boundary diffusion. Demand concentrates in German and South Korean automotive OEM supply chains for 800V traction motor programs, where magnetic arc segments bond permanently into rotor laminates during motor assembly. Procurement contracts now span 5-7 year horizons with rare-earth oxide price pass-through clauses.
- Samarium Cobalt:SmCo5 and Sm2Co17 alloys sustain magnetic performance above 300°C operating temperatures where NdFeB demagnetizes. Aerospace generator manufacturers in France and the United States specify SmCo for integrated drive generators and auxiliary power units, embedding magnets into hermetically sealed rotor assemblies that resist thermal cycling across flight profiles.
- Alnico:Aluminum-nickel-cobalt-iron alloys offer temperature stability up to 540°C with moderate coercivity, serving sensor applications and vintage audio equipment where magnet replacement remains feasible without full system disassembly.
- Ceramic:Ferrite-based magnets provide lowest-cost magnetic solutions for refrigerator seals, loudspeaker drivers, and automotive sensors where performance specifications tolerate lower remanence.
- Flexible Magnets:Ferrite or NdFeB powders embedded in polymer matrices enable roll-forming and die-cutting for signage, sealing gaskets, and lightweight motor applications requiring conformable magnetic surfaces.
Volume placements concentrate in Neodymium Iron Boron; the faster expansion belongs to Samarium Cobalt as aerospace electrification accelerates.
Technology:
Process selection governs whether magnets ship as finished embedded components or enter secondary assembly operations, with capital intensity and geometric precision as the decisive variables.
- Sintering:Powder metallurgy compaction and high-temperature densification produces maximum magnetic energy product for traction motors and wind generators. Japanese fabricators in Aichi and Osaka prefectures dominate high-volume sintering lines serving Toyota and Honda electrification platforms, embedding magnets directly into rotor stack assemblies.
- Injection Molding:NdFeB or SmCo powders compounded with thermoplastic binders enable complex geometries with dimensional tolerances below 50 micrometers. Swiss and German medical device manufacturers specify injection-molded magnets for surgical robotics and implantable drug delivery systems where miniaturization demands integrated magnetic positioning elements.
- Bonding:Compression bonding of magnetic powders with epoxy resins yields isotropic or anisotropic blocks for sensors and small motors, permitting secondary machining and field replacement without full motor disassembly.
- Hot Pressing:Simultaneous compaction and heat treatment of rapidly solidified ribbons produces nanocrystalline microstructures with enhanced coercivity for high-temperature automotive sensors.
- Die Casting:Molten metal injection into permanent molds fabricates Alnico shapes with oriented columnar grain structures for specialized instrumentation applications.
Capital deployment clusters in Sintering; the steepest expansion trajectory belongs to Injection Molding as medical robotics penetrates surgical suites.
Application:
Application context determines whether magnets function as standalone field-replaceable units or permanent embedded elements within larger electromechanical systems.
- Electric Motors:Traction motors for battery electric vehicles and industrial drives embed sintered NdFeB arc segments into laminated rotor cores during motor assembly, rendering magnets inaccessible for replacement without full motor disassembly. German automotive OEMs specify these embedded magnet configurations for 150kW+ drive units.
- Wind Turbines:Direct-drive generators for offshore wind platforms integrate massive NdFeB blocks into permanent magnet synchronous generators, with Danish and United Kingdom developers specifying 15+ MW units where magnet replacement requires nacelle crane operations.
- Medical Devices:Magnetic resonance imaging gradient coils and surgical robotics employ precision-bonded or injection-molded magnets as embedded positioning elements within sterile instrument housings.
- Robotics:Collaborative robot joints and linear actuators integrate compact NdFeB ring magnets into frameless torque motors, with Japanese and German automation OEMs specifying embedded configurations for cleanroom-compatible designs.
- Audio Equipment:High-fidelity loudspeaker drivers and professional microphones retain field-serviceable magnet structures, permitting aftermarket replacement and voice coil repair.
Procurement volume aggregates in Electric Motors; medical device applications are gaining share fastest as surgical robotics scales.
End User Industry:
Industry verticals impose distinct integration protocols, with aerospace and power generation demanding permanent embedding while consumer electronics retains modular architectures.
- Power Generation:Wind turbine OEMs and gas turbine generator manufacturers embed SmCo and high-temperature NdFeB grades into rotor forgings, with United Kingdom and Danish developers specifying 25-year operational lifecycles without magnet service access.
- Aerospace:Integrated drive generators and flight control actuators specify SmCo magnets hermetically sealed within titanium housings, embedding magnetic components irreplaceably across aircraft service intervals exceeding 30 years.
- Consumer Electronics:Smartphone haptic actuators and laptop fan motors employ bonded NdFeB rings in snap-fit assemblies, permitting magnetic component replacement during device refurbishment cycles.
- Automation:Factory robot servo motors and linear motion systems integrate sintered NdFeB into sealed motor housings, though modular actuator designs permit field replacement of magnetic subassemblies in some collaborative robot platforms.
- Telecommunications:Base station filters and satellite communication systems employ temperature-stable Alnico and SmCo elements, with some legacy ground station equipment retaining field-adjustable magnetic tuners.
Contract volume concentrates in Power Generation; Aerospace procurement is climbing the fastest as commercial aviation electrifies auxiliary systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's rare-earth processing special economic zones concentrate upstream magnet feedstock, redirecting procurement corridors for fabricators in Germany, Japan, and the United States.
China
MIIT extraction quotas and export licensing for processed rare earths dominate feedstock allocation. The Jiangxi and Inner Mongolia processing corridors supply sintered NdFeB manufacturers in Ningbo and Shenzhen, where magnet fabricators serve domestic EV and wind energy OEMs.
Germany
Automotive electrification mandates from Berlin drive sintered NdFeB offtake for 800V traction motors. The EU F-Gas Regulation pressures coating houses in Saxony to abandon fluorinated process gases. Magnet fabricators in Bavaria qualify diffusion-treated arc segments for Porsche and BMW electrification platforms.
Japan
Legacy hydrogen decrepitation expertise concentrates in Aichi and Osaka prefectures serving Toyota and Honda. METI funding secures dysprosium stockpiles against Chinese export constraints. Shin-Etsu Chemical anchors rare-earth alloy production in Gunma, sustaining captive intermediate processing for domestic magnet fabricators.
United States
Defense Production Act and DOE loan programs de-risk magnet manufacturing investments in Texas and California. The Department of Defense funds domestic rare-earth separation to reduce import dependency. Magnet fabricators in the Mountain West region prototype grain boundary diffusion lines for aerospace generator applications.
South Korea
Carbon neutrality frameworks lock in multi-year NdFeB contracts for Hyundai and Kia electrification programs. The Ministry of Trade, Industry and Energy subsidizes magnet recycling infrastructure in Gyeonggi Province. Fabricators in Incheon specialize in bonded magnet injection molding for medical robotics exports.
High Performance Permanent Magnet Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across magnet fabrication tiers. The market structure concentrates around Japanese and Chinese incumbents with captive rare-earth processing, while Western entrants rely on strategic partnerships for feedstock security. Three archetypes dominate: integrated powder-to-magnet operators controlling mine-to-finished supply chains, sintering-scale specialists serving automotive qualification pipelines, and bonded-magnet precision houses targeting medical miniaturization. Competitive moves center on backward integration into rare-earth separation and multi-year offtake contracting with indexed oxide pass-through mechanisms.
Among Japanese fabricators, Shin-Etsu Chemical, TDK Corporation, and Daido Steel occupy positions defined by metallurgical expertise concentration. Shin-Etsu Chemical exemplifies the integrated archetype through captive rare-earth alloy production. TDK Corporation represents sintering-scale specialization with automotive qualification depth. Daido Steel sits within the precision-bonded tier serving miniature electronics and medical device geometries. These three anchors demonstrate how geographic clustering of hydrogen decrepitation talent creates defensive moats against new entrant scale-up.
| Leading Market Players |
|---|
| Proterial |
| TDK Corporation |
| Shin-Etsu Chemical |
| Daido Steel |
| Arnold Magnetic Technologies |
| Vacuumschmelze |
| Electron Energy Corporation |
| Earth-Panda Advance Magnetic Material |
| Ningbo Yunsheng |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between automotive-qualified sintered NdFeB and commodity-bonded grades manifests in dual pricing regimes and fragmented procurement corridors. IATF 16949-qualified arc segments command rare-earth oxide pass-through premiums through multi-year offtake contracts, while non-certified bonded magnets trade on spot neodymium pricing with compressed margins.
Pricing Analysis
Short-lead-time premiums for corrosion-protected sintered blocks separate automotive procurement from wind energy spot purchasing. Contract-based long-term offtake with indexed oxide pass-through clauses dominates Tier 1 automotive supply chains, while spot-market volatility compresses margins for fabricators serving industrial replacement demand. Price differentiation hinges on IATF certification tier and captive rare-earth sourcing depth. Pricing pressure stems from dysprosium spot volatility, with wind turbine OEMs most price-sensitive due to magnet mass per megawatt.
Supply Chain Analysis
Magnet refurbishment flows from end-of-life wind turbines and traction motors are emerging as secondary feedstock corridors. Upstream concentration rests in China's Jiangxi and Inner Mongolia rare-earth processing zones, with Japanese hydrogen decrepitation expertise and German automotive fabrication completing the tripartite structure. Raw material dependencies center on neodymium oxide, dysprosium, and terbium from ion-adsorption clay deposits. Single-source vulnerability concentrates in southern Chinese heavy rare-earth separation. Distribution runs through magnet fabricator-OEM direct contracts, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into rare-earth separation and alloy production is accelerating as the decisive competitive lever, with defense funding and carbon-border mechanisms reshaping capital allocation across fabrication tiers.
For Market Incumbents: Anchor metallurgical expertise concentration through captive hydrogen decrepitation capacity in legacy Japanese and Chinese facilities. Lock in multi-year offtake with rare-earth oxide pass-through clauses before alternative separation corridors mature. Defend against grain boundary diffusion technology commoditization by qualifying next-generation reduced-heavy-rare-earth formulations with automotive OEMs. For New Entrants and Emerging Players: Enter via bonded magnet injection molding for surgical robotics and implantable drug delivery systems where dimensional precision requirements exceed sintering capabilities. Target Swiss and German medical device manufacturers with sub-50-micrometer tolerance offerings. Pursue aqueous coating technology partnerships to bypass EU F-Gas regulatory barriers. For Investors and Strategic Acquirers: Re-rating potential sits with domestic rare-earth corridor developers given Defense Production Act funding inflection and clean energy loan program de-risking. Long-term viability hinges on verified low-carbon separation partnerships aligned with China's MIIT carbon intensity benchmarks. Monitor Texas and California magnet manufacturing prototype qualification timelines as early signals of supply chain diversification traction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Separation | Captive oxide supply insulates margin compression from Chinese export licensing volatility. |
| Grain Boundary Diffusion Scale-Up | Reduced dysprosium intensity per kilogram reshapes procurement hedging for 800V traction motors. |
| Aqueous Coating Technology Transition | EU F-Gas compliance secures wind energy OEM contracts in northern European markets. |
| Medical Device Miniaturization Partnerships | Swiss surgical robotics OEMs specify injection-molded magnets for sterile instrument integration. |
| Domestic Corridor Joint Ventures | DOE loan programs de-risk Texas and California magnet manufacturing investments against import dependency. |
Research Methodology
Trade statistics from customs authorities, SEC filings from listed magnet fabricators, and MIIT extraction quota disclosures formed the secondary backbone for supply-side calibration. Primary interviews with rare-earth separation plant managers, automotive Tier 1 procurement leads, wind turbine generator engineers, and coating technology R&D directors validated demand assumptions. Bottom-up magnet consumption estimates by end-use application triangulated against top-down rare-earth oxide allocation data.
Historical trendline analysis of neodymium oxide spot pricing and sintered NdFeB contract premiums anchored the projection framework across the analysis window. Segmentation modeling incorporated magnet grade tier, fabrication technology, end-use application, and regional regulatory cluster dimensions. CAGRs derived from elasticity-adjusted demand curves for electric vehicle traction motors and direct-drive wind turbines, with aerospace generator electrification as a secondary growth input.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Chinese export licensing escalation or breakthrough high-temperature-stabilized NdFeB formulations. Practitioners should monitor MIIT carbon intensity benchmark enforcement and grain boundary diffusion automotive qualification timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.