
 Global Copper Cathode Market | 2026-2036
Global Copper Cathode Market Size, Share, and Industry Trends Forecast 2026-2036
Global Copper Cathode Market Foresight
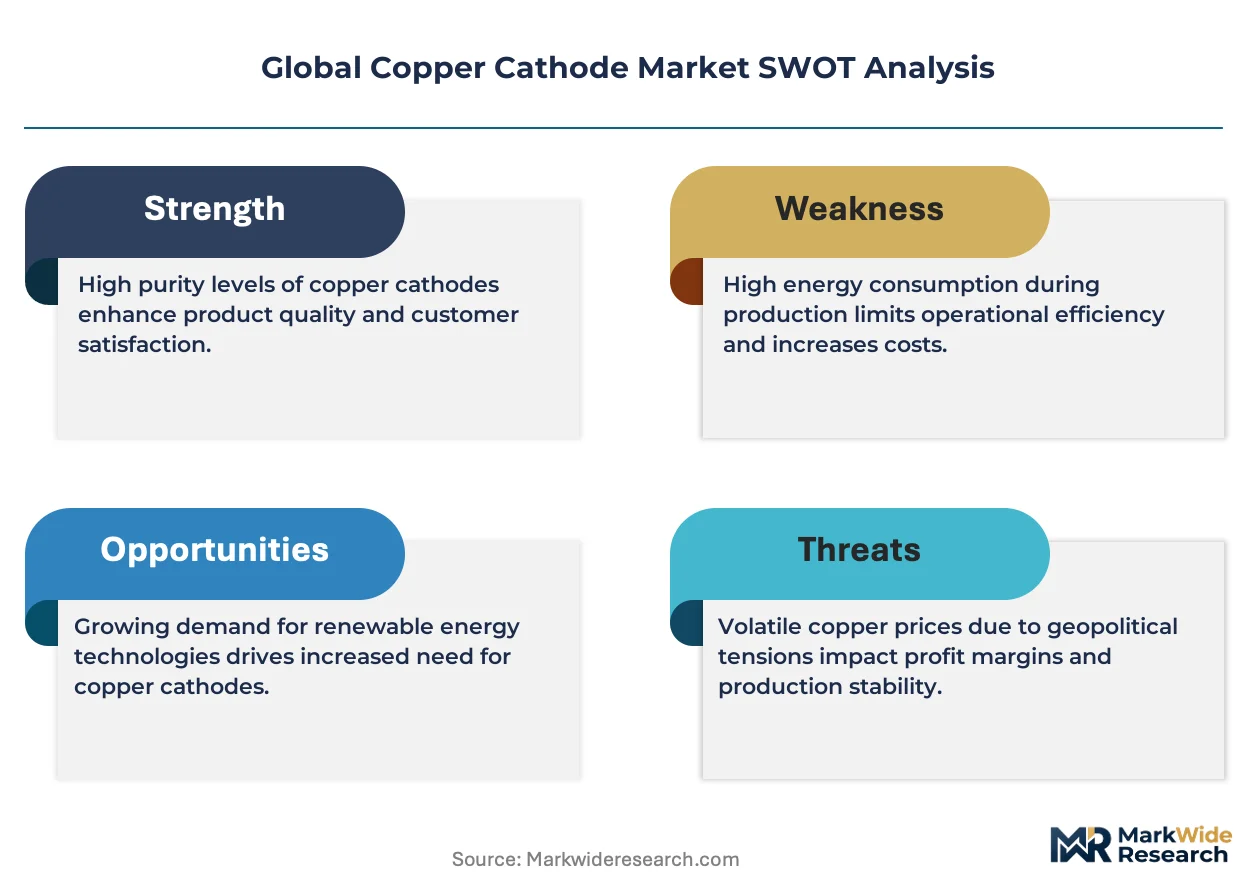
Aluminum is broadening its competitive threat in power transmission cabling, yet copper cathode retains irreplaceable conductivity advantages in precision electronics and EV architectures. Codelco leverages its state-owned vertical integration to anchor Chilean supply security against resource nationalism risks. Freeport-McMoRan sustains Indonesian and Peruvian operational scale despite escalating ore-grade decline. Glencore navigates complex DRC geopolitics while controlling substantial Central African concentrate flows.
Copper cathode denotes refined metallic copper of minimum 99.99% purity, produced via electrolytic refining of blister copper in tank houses operating at current densities of 200-350 A/m² with sulfuric acid electrolyte; its primary purpose is serving as feedstock for wire rod, alloy production, and direct electrical component fabrication. Electrolytic grade cathodes dominate institutional procurement for grid infrastructure and automotive harnesses due to trace-element consistency, while oxygen-free variants command premium positioning in semiconductor lead frames and vacuum applications where hydrogen embrittlement resistance determines performance. Continuous cast cathodes occupy growing share among OEMs seeking reduced remelt energy costs, though sulfur-free specifications remain niche for specialized chemical process equipment.
Chile's Ministry of Mining enforces escalating royalty frameworks that reshape project economics, while China's MIIT implements GB standards on recycled copper content that alter import specifications. The EU F-Gas Regulation indirectly pressures copper demand through heat pump deployment mandates, and EPA tailings standards in the United States constrain permitted extraction methods. Stakeholders must monitor ore-grade trajectory, smelter capacity bottlenecks, and substitution elasticity in medium-voltage cable applications to calibrate long-term offtake commitments.
Market Dynamics
Electrolytic refining capacity is tightening as Chilean state royalty frameworks and Indonesian concentrate export bans simultaneously constrain feedstock availability and smelter economics. This dual squeeze is forcing cathode buyers into longer-term offtake negotiations with fewer qualified suppliers.
Growth Catalysts
- EV Battery Procurement:Electric vehicle manufacturers are locking in multi-year cathode supply contracts to secure high-conductivity feedstock for motor windings and battery busbars.
- EU F-Gas Regulation:Heat pump deployment mandates across member states are accelerating copper-intensive HVAC system manufacturing and installation.
- Chilean Mining Belt Concentration:State-backed vertical integration in Atacama operations is stabilizing electrolytic-grade output despite ore-grade decline pressures.
Market Restraints
- Sulfuric Acid Electrolyte Costs:Tank house chemical input volatility is compressing refining margins for independent smelters without captive acid production.
- DRC Geopolitical Concentration:Central African copper-cobalt corridor instability concentrates concentrate supply risk in a single high-risk jurisdiction.
- Aluminum Substitution in MV Cabling:Medium-voltage power transmission applications are partially displacing copper cathode with lower-cost aluminum conductors.
Strategic Opportunities
- US IRA Clean Energy Credits:Domestic content incentives for grid infrastructure are creating localized cathode demand for transformer and switchgear manufacturing.
- Semiconductor Lead Frame Applications:Oxygen-free high-conductivity grades command premium positioning in advanced packaging for AI chip substrates.
- Recycled Copper GB Standards:China's MIIT import specification shifts are opening secondary feedstock channels for certified cathode producers.
Industry Challenges
- Tank House Electrochemical Engineering Talent:Current density optimization expertise is aging out of the workforce faster than technical training programs can replenish.
- EPA Tailings Permitting Timelines:US greenfield extraction projects face multi-year environmental review cycles that delay cathode supply diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Copper Cathode Market |
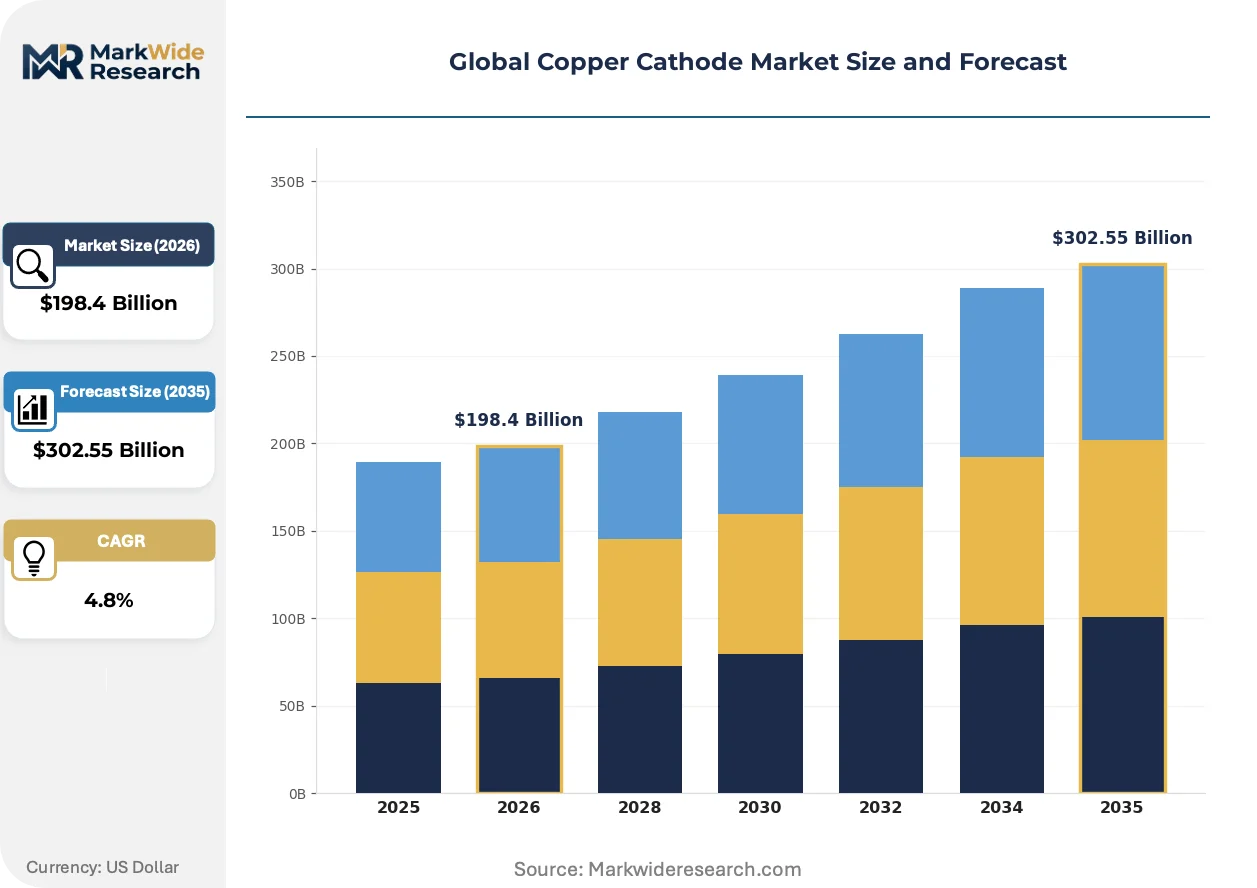
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $302.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolytic Grade, Continuous Cast, Oxygen-Free, High Conductivity, Sulfur-Free Application: Electrical Wiring, Electronics Manufacturing, Renewable Energy, Construction, Transportation End User: OEMs, Electrical Equipment Manufacturers, Infrastructure Developers, Electrical Contractors Distribution Channel: Direct Sales, Distributors, Online Marketplaces, Wholesale Traders |
| Companies Covered | Glencore, KGHM Polska Miedz, BHP, Antofagasta, CMOC Group, Codelco, Southern Copper, Lundin Mining, Freeport-McMoRan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Copper Cathode Market Shifts & Advancements
Continuous casting technologies and digital tank house monitoring systems are compressing the traditional electrolytic refining paradigm. These shifts are reducing energy intensity while tightening trace-element consistency specifications for premium applications.
Continuous cast cathode production is decentralizing cathode supply chains by enabling regional smelters to bypass traditional electrolytic tank house infrastructure. OEMs in automotive harness manufacturing are adopting these formats to reduce remelt energy costs at their wire rod facilities. The technology is decentralizing procurement patterns away from established electrolytic-grade suppliers toward integrated semi-fabricators with captive casting capacity.
REACH heavy metal content restrictions are tightening trace-element specifications for cathodes entering EU electrical component supply chains. ECHA enforcement is forcing importers to certify arsenic, antimony, and bismuth levels below 10 ppm thresholds. Semiconductor and medical device manufacturers are responding by qualifying oxygen-free grades from Chilean and Japanese suppliers with demonstrated impurity control.
Long-term offtake contracting is displacing spot market purchasing among grid infrastructure developers and EV battery manufacturers. Buyers are accepting price premiums for 3-5 year supply security rather than managing quarterly procurement volatility. This pattern is most visible in German and South Korean automotive supplier networks where cathode inventory carrying costs exceed contract premium spreads.
Global Copper Cathode Market Segmentation
Copper cathode procurement patterns diverge sharply between volume-driven commodity buyers and specification-sensitive precision manufacturers. Understanding these fault lines reveals where margin compression concentrates and where premium positioning endures.
Product Type:
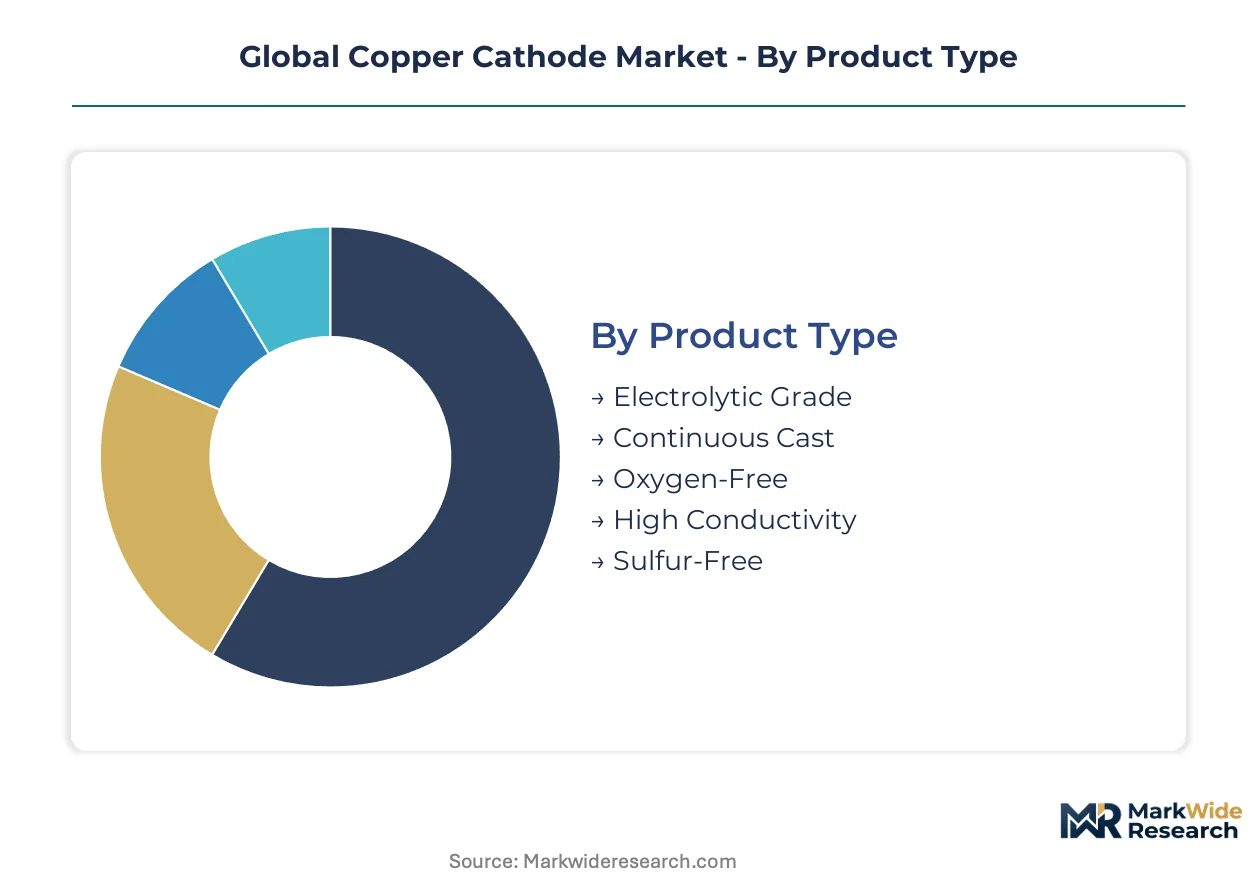
Volume buyers dominate electrolytic grade procurement while premium applications fragment across specialized purity tiers.
- Electrolytic Grade:Standard 99.99% purity cathodes produced via tank house electrolysis at 200-350 A/m² current density. Grid infrastructure developers in Germany and automotive harness manufacturers in South Korea anchor demand through multi-year offtake contracts. Ore-grade decline at Chilean state operations is tightening availability for spot purchasers.
- Continuous Cast:Direct casting bypasses traditional electrolytic refining, cutting remelt energy costs for wire rod producers. Regional smelters in the US Midwest and Poland's Legnica-Glogów copper district are expanding captive casting capacity to serve OEMs seeking supply chain compression.
- Oxygen-Free:Vacuum-processed cathodes with hydrogen embrittlement resistance command semiconductor lead frame applications. Japanese METI-certified producers and Codelco's El Teniente operations supply AI chip packaging manufacturers with sub-5 ppm oxygen specifications.
- High Conductivity:Trace-element controlled grades for EV motor windings and battery busbars. Chinese MIIT GB standards and US IRA domestic content rules are bifurcating procurement pools between qualified and non-qualified suppliers.
- Sulfur-Free:Niche specification for chemical process equipment and medical device applications. Swiss and German pharmaceutical equipment fabricators maintain qualified supplier lists shorter than ten approved sources.
Today's leader: Electrolytic Grade. Tomorrow's challenger: Continuous Cast.
Application:
End-use concentration tracks electrification intensity, with transportation and renewable energy climbing fastest against mature construction demand.
- Electrical Wiring:Grid infrastructure and building harnesses consume standard electrolytic grades through long-term utility procurement cycles. US FERC interconnection queue backlogs and EU F-Gas heat pump mandates are accelerating conductor demand faster than transmission buildout can match.
- Electronics Manufacturing:Semiconductor packaging and PCB fabrication require oxygen-free and high-conductivity specifications. Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek semiconductor cluster concentrate premium cathode consumption for advanced node production.
- Renewable Energy:Solar inverters, wind turbine generators, and battery storage systems specify high-conductivity grades for efficiency-critical connections. India's CEA renewable purchase obligations and Brazil's ANEEL distributed generation rules are expanding addressable demand.
- Construction:Building wire and plumbing applications face aluminum substitution pressure in cost-sensitive segments. China's property sector adjustments and US multifamily construction cycles create demand volatility independent of copper fundamentals.
- Transportation:EV motor windings, battery busbars, and charging infrastructure represent the steepest expansion trajectory. German KBA vehicle type approvals and South Korea's KATRI certification requirements are locking in cathode specifications for platform generations.
Transportation applications are climbing the fastest; construction holds the largest installed base.
End User:
Procurement sophistication separates integrated manufacturers with captive metallurgy expertise from project-dependent contractors exposed to spot volatility.
- OEMs:Automotive and appliance manufacturers with internal wire rod facilities negotiate direct cathode supply. Tesla's Nevada operations and BYD's Shenzhen campus exemplify backward integration into semi-fabrication that compresses intermediate margins.
- Electrical Equipment Manufacturers:Transformer, switchgear, and motor producers balance inventory carrying costs against contract premiums. ABB's Swiss headquarters and Siemens' German operations maintain 90-180 day cathode cover through qualified smelter relationships.
- Infrastructure Developers:Grid utilities and renewable project sponsors face long lead times between procurement commitment and conductor installation. India's Power Grid Corporation and Italy's Terna manage price exposure through indexed supply agreements.
- Electrical Contractors:Installation and maintenance operations purchase through distributor networks with limited price hedging capability. US NECA-affiliated contractors and Germany's ZVEH member firms pass material cost fluctuations through project change orders.
OEMs command the tightest supplier relationships; electrical contractors absorb the greatest price volatility.
Distribution Channel:
Channel selection reflects buyer scale and specification complexity, with direct relationships consolidating among volume consumers.
- Direct Sales:Smelter-to-manufacturer relationships dominate electrolytic grade procurement above 10,000 tonne annual volumes. Codelco's Santiago trading desk and Glencore's Baar headquarters transact directly with qualified wire rod producers.
- Distributors:Regional metal service centers stock standard grades for mid-tier fabricators with intermittent demand. Kloeckner & Co's German network and Reliance Steel's US branches maintain 30-60 day inventory positions.
- Online Marketplaces:Digital platforms are penetrating spot purchasing for non-critical applications. China's 1688.com and India's IndiaMART list certified cathode lots with laboratory documentation for small-batch buyers.
- Wholesale Traders:Merchants arbitrage geographic price differentials and timing spreads. Geneva-based traders and Singapore commodity houses finance inventory positions against LME futures curves.
Direct sales capture the premium contract volume; online marketplaces are gaining share fastest in spot procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's Atacama mining belt concentrates the world's electrolytic refining capacity, anchoring cathode supply security for precision electronics and EV battery manufacturers across three continents.
Chile
State-backed vertical integration through Codelco stabilizes electrolytic-grade output despite ore-grade pressures from aging porphyry deposits. Chile's Ministry of Mining enforces escalating royalty frameworks that reshape project economics for greenfield expansions. The Chuquicamata and El Teniente complexes concentrate tank house capacity near Antofagasta, supplying oxygen-free specifications to semiconductor packaging manufacturers in Asia.
China
MIIT implements GB standards on recycled copper content that alter import specifications for cathode feedstock. The country's dual carbon goals accelerate procurement of high-conductivity grades for EV motor windings and grid-scale battery storage. Yangtze River Delta smelters around Shanghai and Jiangsu province process concentrate from Central Africa while expanding captive casting capacity for wire rod producers.
United States
EPA tailings permitting timelines constrain greenfield extraction projects, delaying cathode supply diversification beyond legacy Southwest operations. FERC interconnection queue backlogs and IRA clean energy credits create localized demand for transformer and switchgear manufacturing feedstock. Arizona's Morenci district and Utah's Bingham Canyon anchor remaining electrolytic refining capacity serving domestic automotive harness producers.
Democratic Republic of Congo
Copper-cobalt corridor instability concentrates concentrate supply risk in a single high-risk jurisdiction despite substantial geological endowment. Artisanal mining governance frameworks and export certification requirements from the country's mining ministry complicate logistics for integrated traders. Kolwezi and Lubumbashi processing hubs feed Asian smelters while facing persistent infrastructure and security challenges.
Germany
KBA vehicle type approvals lock in cathode specifications for EV platform generations across automotive supplier networks. EU F-Gas Regulation heat pump deployment mandates accelerate copper-intensive HVAC system manufacturing from Ruhr Valley fabricators. Hamburg and Düsseldorf trading desks structure long-term offtake contracts that displace spot purchasing among grid infrastructure developers.
Global Copper Cathode Market Competitive Landscape
Long-term offtake contracting dominates the current landscape as buyers accept price premiums for supply security. The vendor base stratifies between state-integrated mining houses, diversified natural resource traders, and independent smelter operators. Three archetypes anchor competitive positioning: sovereign wealth-backed vertical integrators, merchant traders with concentrate arbitrage expertise, and regional smelters with captive casting capacity. Geographic expansion and portfolio diversification represent the dominant competitive moves as players secure feedstock access across politically divergent jurisdictions.
Within the state-integrated tier, Codelco and KGHM Polska Miedz exemplify sovereign-backed producers with captive tank house infrastructure and domestic offtake prioritization. Glencore occupies a merchant-trader position, leveraging logistics networks across the Central African copper-cobalt corridor. Freeport-McMoRan represents the diversified mining house archetype, maintaining operational scale across Indonesian and Peruvian assets despite ore-grade decline pressures.
| Leading Market Players |
|---|
| Glencore |
| KGHM Polska Miedz |
| BHP |
| Antofagasta |
| CMOC Group |
| Codelco |
| Southern Copper |
| Lundin Mining |
| Freeport-McMoRan |
| Others |
Supply & Pricing Matrix
Continuous casting adoption is compressing traditional electrolytic refining economics while redistributing pricing power toward regional smelters with captive wire rod partnerships. Chilean royalty escalations and Indonesian concentrate export restrictions simultaneously inflate feedstock costs and concentrate supply leverage among integrated producers.
Pricing Analysis
Input-cost pass-through from sulfuric acid electrolyte volatility and declining ore grades is intensifying margin pressure at independent tank houses without captive acid production. Contract-based long-term offtake dominates procurement above 10,000 tonne annual volumes, with price differentiation anchored in trace-element certification and oxygen-free specifications. Cost compression runs through standard electrolytic grades as aluminum substitution accelerates in medium-voltage cabling. Electrical contractors purchasing through distributor networks exhibit highest price sensitivity, while semiconductor manufacturers qualifying oxygen-free grades accept substantial premiums for supply security.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from automotive harness manufacturers and grid infrastructure developers, while regional metal service centers serve mid-tier fabricators with intermittent requirements. Supply concentrates in Chile, the Democratic Republic of Congo, and China, with concentrate flows from Central Africa feeding Yangtze River Delta smelters. The chain draws from copper concentrate, sulfuric acid, and electrolytic refining infrastructure as critical inputs. Single-source vulnerability from DRC geopolitical concentration poses structural risk, with logistics chokepoints at Kolwezi and Lubumbashi processing hubs. Distribution runs through direct smelter relationships for qualified volumes, supplemented by wholesale traders arbitraging LME futures curves.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Copper Cathode Market functions as a stable compounder under electrification tailwinds, with EV battery procurement and grid infrastructure buildout providing durable demand foundations across the projection horizon.
For Market Incumbents: Deploy long-term offtake contracting as the primary defensive lever to lock in buyer relationships before continuous cast technologies disintermediate traditional electrolytic suppliers. Deepen backward integration into concentrate sourcing across politically divergent jurisdictions to mitigate DRC concentration risk. Invest in oxygen-free certification capacity to capture premium positioning in semiconductor lead frame applications as AI chip packaging demand accelerates.
For New Entrants and Emerging Players: Enter via regional continuous cast capacity serving wire rod OEMs seeking remelt energy cost reduction, bypassing capital-intensive tank house infrastructure. Target US Midwest automotive harness manufacturers and Poland's Legnica-Glogów copper district fabricators as underpenetrated geographies with qualified supplier shortages. Pursue secondary feedstock channels under China's MIIT GB standards as a go-to-market angle for certified recycled cathode production.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional smelters with captive casting technology and qualified supplier status under EU REACH specifications. Long-term viability rests on electrification intensity across transportation and renewable energy applications, with 5-10 year demand visibility supported by platform standardization in EV architectures. Target acquisition archetypes include integrated semi-fabricators with captive wire rod capacity and demonstrated impurity control for semiconductor applications. Monitor EPA tailings permitting timelines as the critical signal for US supply diversification inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Concentrate Sourcing | Secures feedstock autonomy against Indonesian export bans and Chilean royalty escalations. |
| Oxygen-Free Grade Certification Investment | Qualifies supply for Taiwan Hsinchu and South Korea Pyeongtaek semiconductor packaging clusters. |
| Continuous Cast Capacity Expansion | Captures OEM demand for remelt energy cost reduction in automotive harness manufacturing. |
| Long-Term Offtake Contracting | Locks in German automotive and South Korean battery manufacturer procurement commitments. |
| Secondary Feedstock Channel Development | Opens certified recycled copper flows under China MIIT GB import specifications. |
Research Methodology
Multiple input streams — tank house operations data, customs trade flows, and smelter capacity disclosures — were reconciled across primary interviews with cathode procurement managers, wire rod plant engineers, and semiconductor packaging specialists. Secondary validation drew from LME warehouse stock reports, Chilean Ministry of Mining production statistics, EPA tailings permit filings, and EU ECHA REACH enforcement documentation. Bottom-up cathode consumption estimates by application were triangulated against top-down mine production and refining capacity aggregates.
Data-stream reconciliation anchored volume and value outputs across the analysis window, with segmentation modeling across product type, application, end user, and distribution channel dimensions. CAGRs were derived from electrolytic refining capacity trajectories, ore-grade decline curves, and substitution elasticity parameters in medium-voltage cable applications. Forecast inputs incorporated EV motor winding specifications from German KBA type approvals and US IRA domestic content rules for grid infrastructure.
Inputs from Chilean state mining disclosures and Central African export certification records were available through the study window; gaps in artisanal mining governance data from the DRC introduce uncertainty bands around concentrate supply assumptions. Forecasts reflect documented assumptions on smelter ramp schedules and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Steel Market
Metals
Global Flat Carbon Steel Market
Metals
India Special Steel Market
Metals
Shipbuilding Steel Plate Market
Metals
Tinplate Market
Metals
Stainless Steel Market
Metals
Europe Welding Consumables Market
Metals
Aluminum Scrap Recycling Market
Metals
Liquid Metal Thermal Pad Market
Metals
Global Copper Market
Metals
Global Tool Steel Market
Metals
Osmium Market
Metals
Ferro Aluminum Market
Metals
US Copper Scrap Market
Metals
Aluminum Wire Market
Metals
United States Metal Casting Market