
 Global Bonded Magnet Market | 2026-2036
Global Bonded Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bonded Magnet Market Foresight
Market Context
Magnet materials engineering talent is bifurcating between rare earth metallurgists and polymer-composite specialists, creating two non-interchangeable labor pools that constrain capacity scaling. Arnold Magnetic Technologies leverages its integrated powder-to-magnet pipeline to sustain North American defense and medical sensor contracts. TDK Corporation anchors Asian supply chains through captive ferrite and NdFeB bonding operations in Japan and China. VACUUMSCHMELZE GmbH & Co. KG competes on precision tolerance capabilities for aerospace actuator segments where magnetic stability under thermal cycling commands premium positioning.
Technical Definition and Structural Segments
Bonded magnets consist of magnetic powders—typically NdFeB, SmCo, or ferrite—dispersed in thermoplastic or thermoset binders and formed through injection molding, compression, or extrusion to net-shape tolerances of ±0.05 mm, serving applications where sintered magnets fracture or where complex geometries eliminate secondary machining. The product type dimension shows NdFeB bonded grades capturing the dominant value share due to energy density requirements in brushless DC motors, while flexible bonded variants grow fastest from wearable electronics and thin-profile sensor arrays where mechanical compliance outweighs remanence. Application segmentation concentrates margin pools in magnetic resonance imaging gradient coil assemblies and precision motor subsystems, with loudspeaker magnet assemblies representing a mature, price-commoditized tier where Chinese ceramic bonded suppliers dominate volume.
Regulatory Frame and Outlook
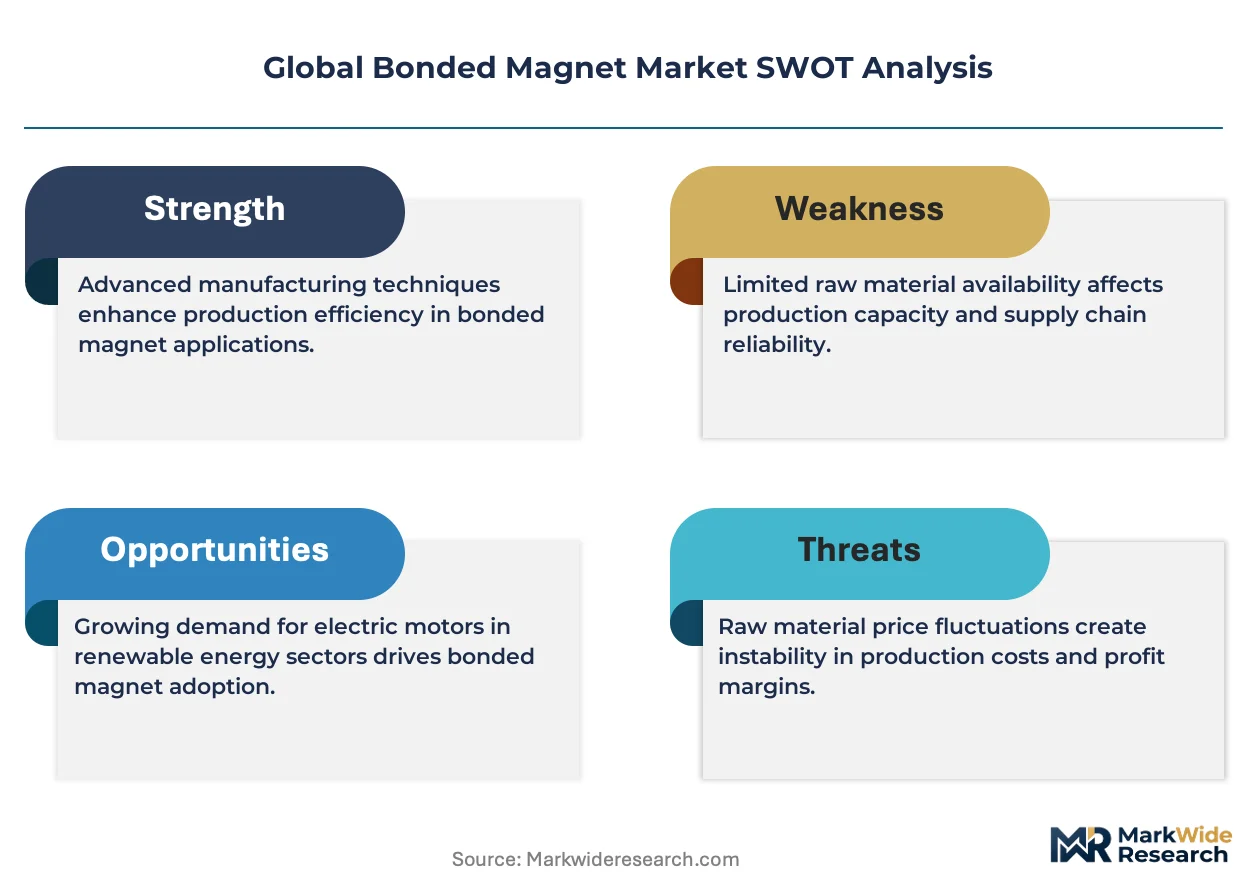
REACH and RoHS frameworks in Europe restrict heavy metal content in polymer binders and mandate recyclability disclosures for bonded magnet assemblies entering automotive and consumer electronics channels. China's GB standards and MEE directives on rare earth mining tailings and smelter emissions are elevating compliance costs for powder feedstock, indirectly advantaging bonded architectures that use 30-40% less rare earth mass per unit of magnetic output. Japan's METI supply security policies and JIS material specifications further shape qualification protocols for bonded SmCo in satellite and defense applications. Stakeholders must monitor how dual carbon goals across East Asian manufacturing bases redirect binder chemistry toward bio-based epoxies and whether powder recyclability mandates in the EU cascade into design-for-disassembly requirements for bonded magnet assemblies.
Market Dynamics
China's NMPA and MIIT rare earth processing standards are forcing motor manufacturers to redesign magnetic assemblies around lower-dysprosium bonded architectures, compressing qualification timelines and reshaping supplier tiers.
Growth Catalysts
- EV Powertrain Miniaturization:OEMs in Germany's Stuttgart-Munich corridor are qualifying compact bonded NdFeB motor assemblies that deliver thermal stability without sintered magnet brittleness.
- REACH Recyclability Mandates:European automotive and electronics channels now require bonded magnet assemblies with disclosed end-of-life recovery pathways, favoring thermoplastic-binder designs over thermosets.
- GB Standards Compliance Arbitrage:China's tightened smelter emissions rules under MEE directives are elevating costs for sintered powder feedstock, indirectly pulling demand toward bonded alternatives using 30-40% less rare earth mass.
Market Restraints
- Rare Earth Price Volatility:Neodymium and dysprosium spot markets exhibit 40-60% annual swings that compress bonded magnet margins when OEMs lock multi-year automotive supply contracts.
- Polymer-Composite Talent Scarcity:The labor pool for magnetic powder dispersion and injection molding process control remains concentrated in Japan and Germany, constraining capacity scaling in emerging production zones.
- RoHS Heavy Metal Restrictions:European ECHA enforcement against lead and cadmium traces in polymer binders forces reformulation cycles that delay new product qualification by 12-18 months.
Strategic Opportunities
- India PLI Scheme Alignment:India's production-linked incentive schemes for automotive component manufacturing create qualification pathways for bonded ferrite suppliers serving domestic two-wheeler electrification.
- Bio-Based Epoxy Binder Development:EU Green Deal procurement preferences and CSRD disclosure requirements are opening specification windows for magnet assemblies using plant-derived thermoset matrices.
- Wearable Electronics Flex Magnet Demand:Thin-profile bonded ferrite arrays with mechanical compliance are displacing rigid sintered alternatives in fitness tracker haptic motors and hearable device speaker assemblies.
Industry Challenges
- Dual Metallurgy-Polymer Expertise Gap:Magnet materials engineering talent splits between rare earth metallurgists and polymer-composite specialists, with minimal crossover extending R&D team buildout timelines.
- JIS-METI Satellite Qualification Burden:Japan's METI supply security policies mandate lot-traceability and thermal cycling documentation that adds 8-12 months to bonded SmCo qualification for defense and space actuator programs.
- ISO 19443 Nuclear Certification Complexity:Medical imaging OEMs require bonded magnet suppliers to implement quality management systems for safety-class components, imposing audit costs that filter out mid-tier competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bonded Magnet Market |
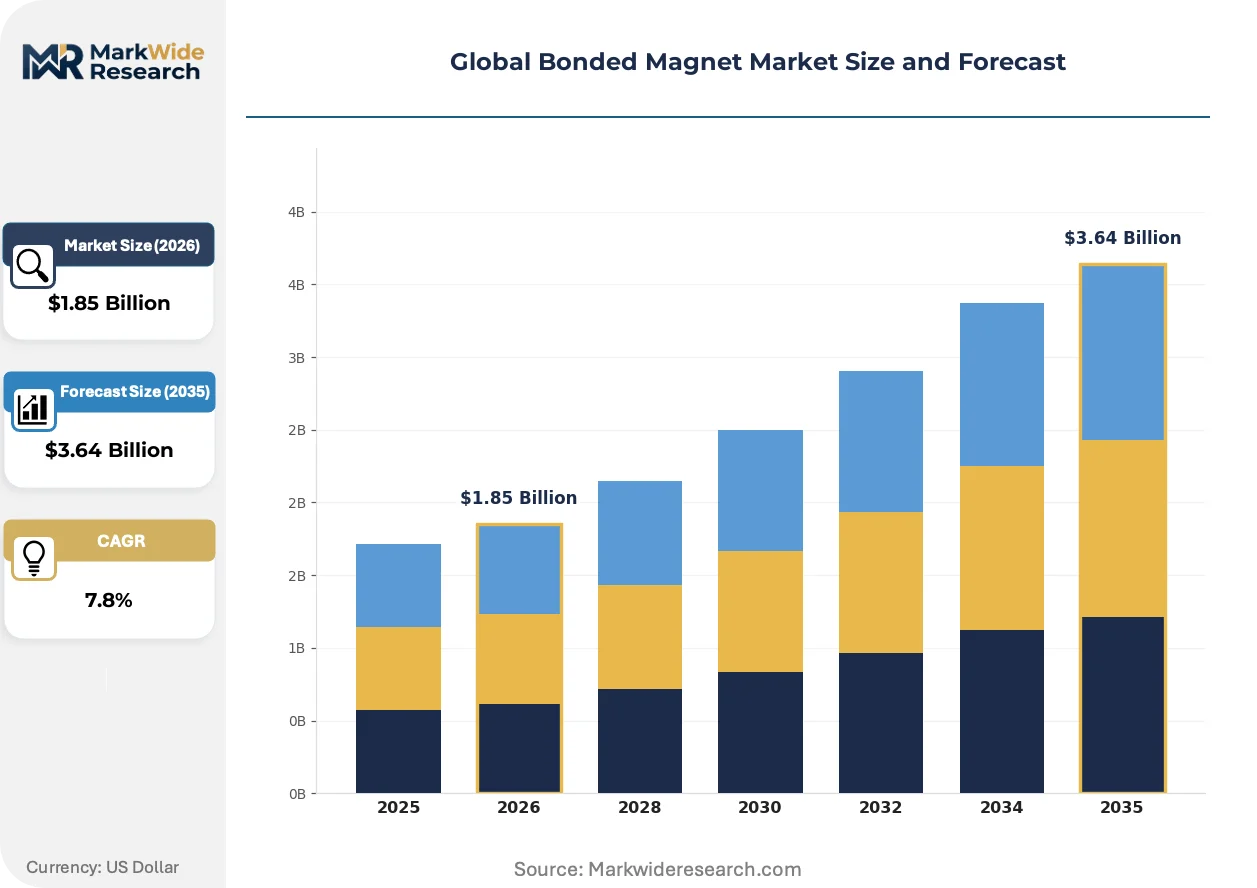
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NdFeB, SmCo, Alnico, Ceramic, Flexible Application: Motors, Sensors, Magnetic Resonance Imaging, Loudspeakers, Magnetic Separation End User Industry: Consumer Electronics, Aerospace, Renewable Energy, Construction, Telecommunications Manufacturing Technology: Injection Molding, Compression Bonding, Extrusion, Calendering, 3D Printing |
| Companies Covered | Arnold Magnetic Technologies, Alliance LLC, TDK Corporation, Ningbo Yunsheng Co. Ltd., VACUUMSCHMELZE GmbH & Co. KG, Advanced Technology & Materials Co. Ltd., Magnequench International LLC, Stanford Magnets, Proterial Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bonded Magnet Market Shifts & Advancements
Magnet manufacturing is splitting between precision-tolerance aerospace-medical tiers and high-volume automotive-consumer tiers, with binder chemistry and forming process choices hardening into incompatible capability sets.
Hot-deformed NdFeB powder processing is bifurcating the bonded magnet technology landscape. This approach delivers anisotropic magnetic properties without sintering furnace capital intensity. German tier-one motor suppliers in Baden-Württemberg are adopting it for next-generation e-axle programs. The technology is bifurcating supplier tiers into hot-deformation licensees versus conventional melt-spun powder incumbents.
EU F-Gas Regulation phase-down schedules are pressuring manufacturers to eliminate fluorinated polymer binders used in high-temperature motor applications. Industrial consequence includes accelerated R&D into silicone and polyimide alternatives for under-hood automotive segments. German KBA type-approval timelines for traction motors now explicitly screen for F-Gas-compliant magnet encapsulation materials.
Buyer consolidation among European automotive OEMs has compressed supplier qualification from 24-month cycles to 14-16 month gates, with bonded magnet vendors absorbing upfront tooling costs to secure platform awards. Tier-one motor suppliers now demand concurrent engineering partnerships rather than arm's-length component procurement. This pattern is most visible in France's Renault-Nissan supply base and Volkswagen Group's consolidated e-mobility purchasing organization.
Global Bonded Magnet Market Segmentation
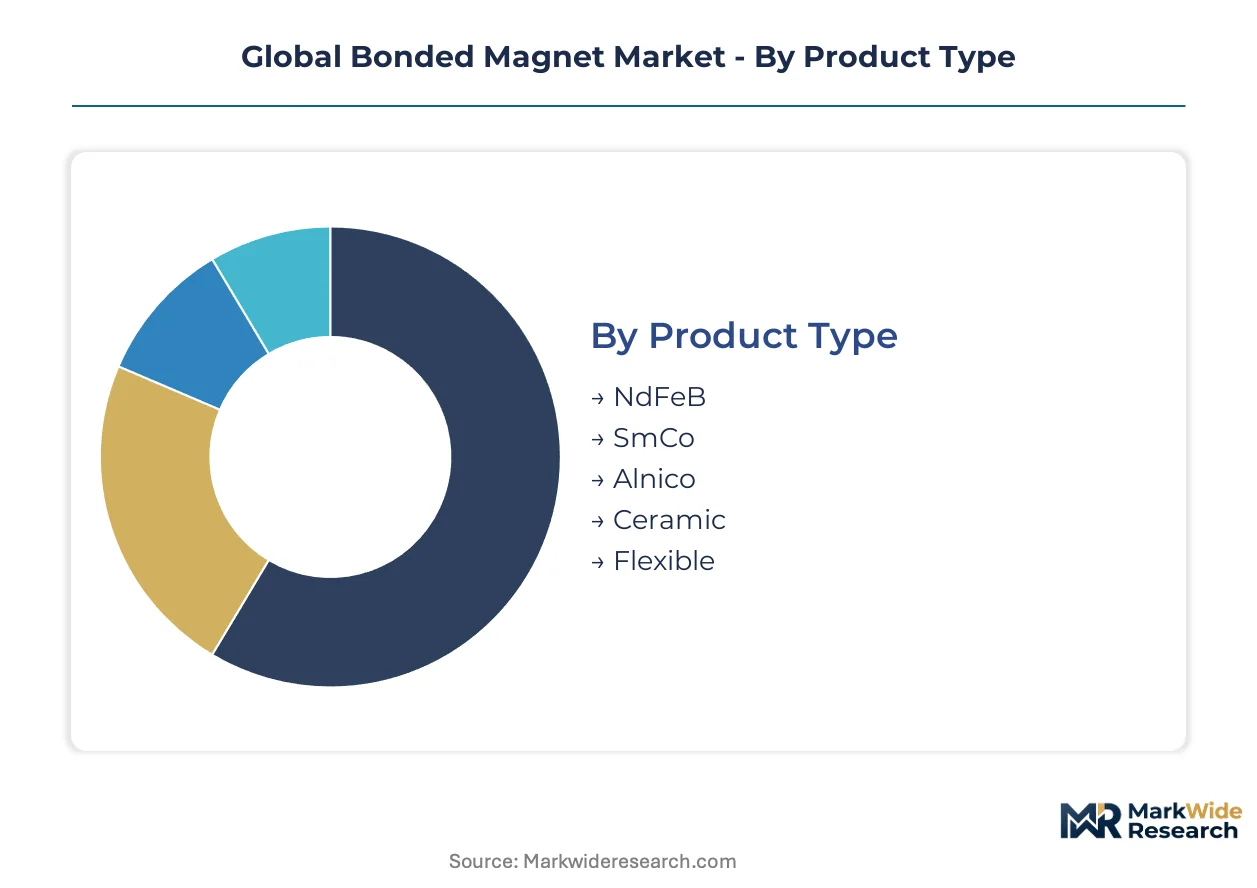
Segmentation in bonded magnets reveals how binder chemistry and forming methods partition the market into incompatible capability tiers. Each dimension—powder composition, end-use application, industry vertical, and manufacturing route—carries distinct qualification barriers and margin structures that reshape supplier positioning.
Product Type:
Substitution pressure runs strongest against sintered alternatives in high-energy-density grades, where bonded architectures must prove thermal stability and mechanical resilience to displace conventional magnets.
- NdFeB:Rare earth-iron-boron powders dispersed in thermoplastic matrices deliver remanence values approaching 0.8 T with isotropic alignment. German automotive suppliers around Stuttgart are qualifying these for e-axle traction motors where thermal cycling resistance outweighs absolute energy density.
- Flexible:Ferrite or NdFeB particles in elastomeric binders enable bending radii below 5 mm for conformal sensor arrays. Wearable electronics manufacturers in Japan and South Korea are adopting thin-profile flexible magnets for fitness tracker haptic feedback modules.
- SmCo:Samarium-cobalt grades retain magnetic output above 250°C, serving satellite actuator programs under METI supply security protocols with lot-traceability mandates.
- Alnico:Aluminum-nickel-cobalt bonded variants occupy legacy instrumentation niches where temperature coefficient stability matters more than energy density.
- Ceramic:Strontium ferrite bonded magnets dominate loudspeaker assemblies through Chinese volume production, competing primarily on unit cost rather than performance metrics.
NdFeB retains volume leadership; Flexible holds the steepest expansion curve.
Application:
Application segmentation tracks how magnetic assembly requirements diverge between precision-tolerance aerospace-medical tiers and high-volume automotive-consumer tiers with incompatible qualification timelines.
- Motors:Brushless DC motor subsystems consume the largest bonded magnet volume, with injection-molded NdFeB rotors displacing sintered alternatives in power steering and HVAC blower applications. Volkswagen Group's consolidated e-mobility purchasing organization has compressed supplier qualification gates to 14-16 months.
- Magnetic Resonance Imaging:Gradient coil assemblies demand ±0.05 mm tolerance bonded arcs with isotropic field uniformity. ISO 19443 nuclear certification requirements filter out mid-tier suppliers from medical imaging OEM procurement pools.
- Sensors:Position and speed sensing applications favor small, complex geometries achievable through injection molding without secondary machining operations.
- Loudspeakers:Commoditized ferrite bonded magnets serve consumer audio with minimal differentiation beyond unit pricing.
- Magnetic Separation:Food and pharmaceutical processing equipment uses corrosion-resistant bonded ferrite drum assemblies with epoxy encapsulation.
Motors command the dominant revenue share; Magnetic Resonance Imaging generates the highest margin pools per kilogram.
End User Industry:
End-use concentration reflects how dual carbon goals and supply security policies redirect procurement toward bonded architectures with lower rare earth intensity and disclosed recyclability pathways.
- Consumer Electronics:Smartphones, laptops, and hearables drive demand for micro-scale bonded magnets in speaker, vibration motor, and hinge applications. Apple's supply chain mandates on recycled content are pushing contract manufacturers toward thermoplastic-binder designs with end-of-life recovery documentation.
- Aerospace:Satellite and defense actuator programs require bonded SmCo with thermal cycling documentation spanning -55°C to 200°C. Japan's METI supply security policies add 8-12 months to qualification timelines.
- Renewable Energy:Wind turbine generator field systems and solar tracking motors adopt bonded ferrite for cost-sensitive auxiliary functions.
- Telecommunications:Base station antenna positioning motors and optical switch components use precision-tolerance bonded NdFeB.
- Construction:Elevator motors and building automation sensors represent a mature, specification-driven segment with stable but low-growth demand.
Consumer Electronics anchors volume demand; Aerospace sustains the premium pricing tier.
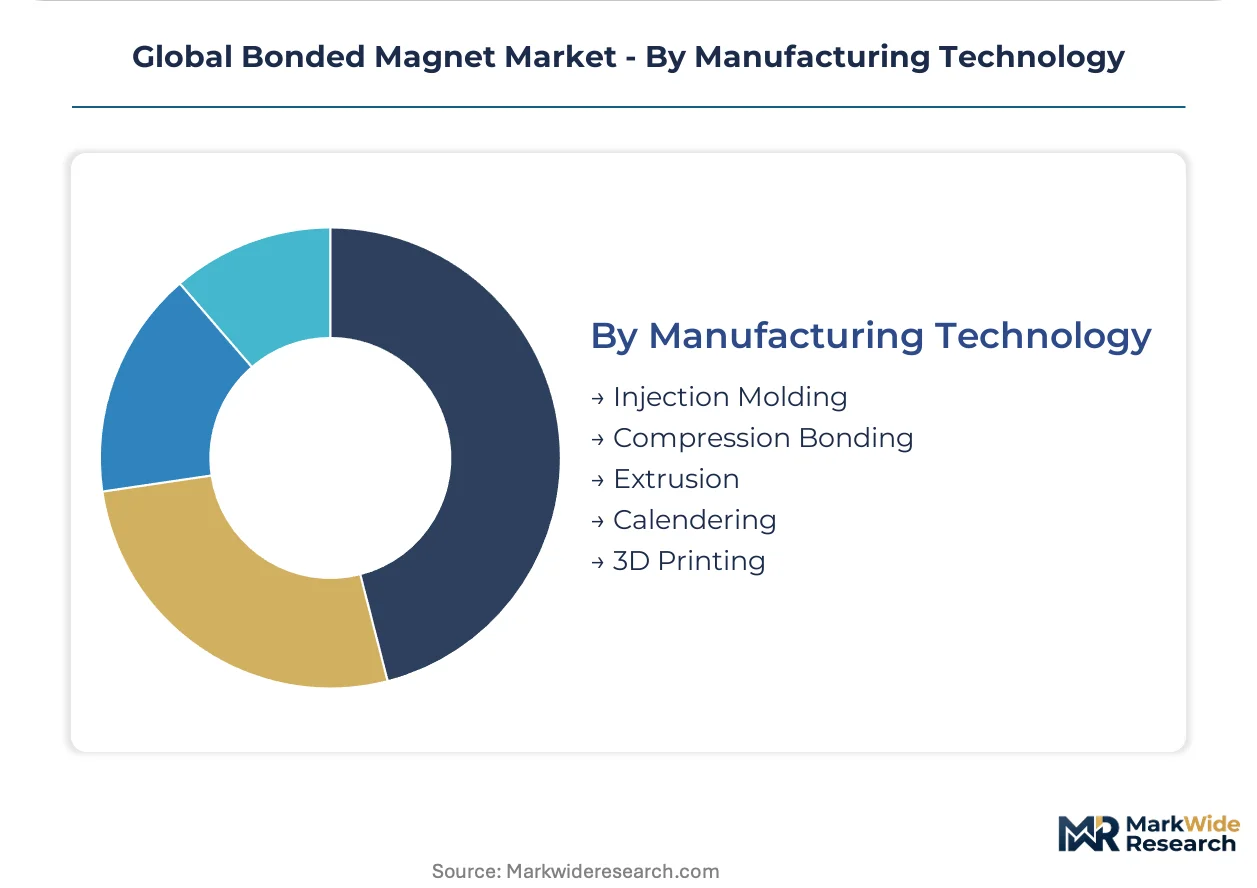
Manufacturing Technology:
Process selection hardens into strategic capability moats, with equipment specialization and polymer-composite talent scarcity constraining migration between forming methods.
- Injection Molding:Thermoplastic-bonded magnets achieve net-shape tolerances with cycle times under 60 seconds, enabling high-volume automotive motor production. German tier-one suppliers in Baden-Württemberg are qualifying hot-deformed NdFeB feedstock through this route for next-generation e-axle programs.
- Compression Bonding:Thermoset epoxy-bonded magnets deliver higher magnetic loading fractions up to 85% by volume, serving aerospace and medical applications where mechanical strength outweighs geometric complexity.
- Extrusion:Continuous profile forming produces bonded magnet strips for linear motor and sensor applications with consistent cross-sectional properties.
- Calendering:Roll-forming of flexible magnet sheets serves refrigerator gasket and signage applications with thickness control below 0.1 mm.
- 3D Printing:Binder jet and material extrusion approaches enable topology-optimized magnet geometries for prototype and low-volume production, though magnetic alignment remains technically challenging.
Injection Molding captures the volume leadership position; 3D Printing is climbing the fastest as design-for-additive workflows mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT and NMPA processing standards have restructured rare earth supply chains, forcing motor manufacturers across Germany, Japan, and the United States to redesign magnetic assemblies around lower-dysprosium bonded architectures.
China
GB standards and MEE directives on smelter emissions have elevated compliance costs for sintered powder feedstock. The Yangtze River Delta concentrates bonded magnet production, with Ningbo-based suppliers scaling thermoplastic-bonded NdFeB output for export markets.
Germany
Automotive OEMs in the Stuttgart-Munich corridor are qualifying compact bonded NdFeB motor assemblies for e-axle traction systems. KBA type-approval timelines now screen for F-Gas-compliant magnet encapsulation materials under EU phase-down schedules.
Japan
METI supply security policies mandate lot-traceability documentation that extends bonded SmCo qualification timelines by 8-12 months for satellite actuator programs. The Kanto region around Tokyo anchors precision-tolerance manufacturing for aerospace and defense applications.
United States
Defense and medical sensor contracts sustain demand for integrated powder-to-magnet pipelines. Arnold Magnetic Technologies leverages captive North American operations to serve FDA-regulated imaging equipment and FAA-certified aerospace actuator segments.
India
PLI schemes for automotive component manufacturing create qualification pathways for bonded ferrite suppliers. Maharashtra and Gujarat host emerging motor manufacturing clusters where domestic two-wheeler electrification drives specification development.
Global Bonded Magnet Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market bifurcating between precision-tolerance aerospace-medical suppliers and high-volume automotive-consumer producers. Three archetypes dominate: captive rare earth processors with downstream magnet fabrication, polymer-composite specialists with injection molding scale, and regional defense-aerospace contractors with qualification depth. Competitive moves center on hot-deformation technology licensing and backward integration into powder feedstock supply.
Within the integrated processing tier, Arnold Magnetic Technologies and TDK Corporation exemplify vertically structured operations spanning powder production to finished magnet assemblies. VACUUMSCHMELZE GmbH & Co. KG occupies a position among European precision-tolerance specialists serving thermally cycled aerospace applications. Among Asia-Pacific fabricators, Ningbo Yunsheng Co. Ltd. and Advanced Technology & Materials Co. Ltd. represent scale-driven production anchored to China's rare earth processing corridor.
| Leading Market Players |
|---|
| Arnold Magnetic Technologies |
| Alliance LLC |
| TDK Corporation |
| Ningbo Yunsheng Co. Ltd. |
| VACUUMSCHMELZE GmbH & Co. KG |
| Advanced Technology & Materials Co. Ltd. |
| Magnequench International LLC |
| Stanford Magnets |
| Proterial Ltd. |
| Others |
Supply & Pricing Matrix
Sixty-day powder inventory cycles at German tier-one motor suppliers signal supply-chain concentration in China's Yangtze River Delta and translate directly into pricing leverage for NdFeB feedstock converters. This lead-time compression shapes how automotive procurement teams negotiate multi-year bonded magnet contracts.
Pricing Analysis
Geographic price spreads between Ningbo-exported bonded NdFeB and European-qualified compression-bonded grades exceed threefold, reflecting certification-tier differentiation. Three-tier pricing structure across aerospace-medical, automotive-industrial, and consumer-commodity levels tracks ISO 19443 nuclear certification and REACH recyclability documentation. Pricing pressure stems from rare earth spot volatility compressing margins on locked automotive supply agreements. Consumer electronics buyers exhibit highest price sensitivity, while satellite actuator programs tolerate premium positioning for lot-traceable SmCo.
Supply Chain Analysis
Strategic stockpiling of rare earth oxide inventories dominates procurement behavior among Japanese SmCo suppliers, contrasting with just-in-time thermoplastic pellet flows at German injection molders. Supply concentrates in China, Japan, and Germany, drawing from neodymium-dysprosium alloy, thermoplastic binder resin, and magnetizing fixture inputs. Single-source vulnerability runs through China's Ningbo processing corridor under tightening GB standards and MEE emissions directives. Distribution runs through captive powder-to-magnet pipelines for defense-medical tiers and merchant-market distributors for consumer audio applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent bonded magnet suppliers face substitution pressure from hot-deformed NdFeB architectures that bypass sintering capital intensity. Defense of market position requires strategic repositioning around qualification depth and powder supply security.
For Market Incumbents: Compound qualification advantages by deepening captive control over rare earth powder feedstock and accelerating hot-deformation technology licensing to tier-one automotive suppliers. METI supply security protocols and ISO 19443 nuclear certification create defensible moats against commodity entrants. For New Entrants and Emerging Players: Anchor in India's PLI-supported automotive component corridors, where bonded ferrite demand from two-wheeler electrification outpaces established supplier presence. Target Maharashtra and Gujarat motor manufacturing clusters with thermoplastic-bonded NdFeB qualification programs for domestic OEMs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized magnet fabrication assets and dormant powder supply relationships. Five-to-ten-year viability hinges on rare earth processing consolidation under Chinese environmental compliance. Watch for NMPA processing standard revisions as inflection signals for bonded architecture substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Deformation Technology Licensing | Enables anisotropic bonded NdFeB without sintering furnace capital, reshaping German e-axle supplier tiers. |
| Bio-Based Epoxy Binder Development | Aligns magnet assemblies with EU Green Deal procurement preferences and CSRD disclosure requirements. |
| Backward Integration into Rare Earth Powder | Secures feedstock supply under China's tightening MEE smelter emissions standards and NMPA processing rules. |
| ISO 19443 Nuclear Certification Investment | Filters mid-tier competitors from medical imaging OEM procurement pools for gradient coil assemblies. |
| Concurrent Engineering Partnerships | Compresses Volkswagen Group and Renault-Nissan qualification gates from twenty-four to fourteen-month cycles. |
Research Methodology
Desk research of customs trade flows, SEC filings from magnet material suppliers, and GB standards documentation preceded structured interviews with powder metallurgy R&D directors, tier-one motor supplier procurement leads, and medical imaging OEM component engineers. Primary fieldwork across Germany's Stuttgart-Munich corridor, Japan's Kanto precision manufacturing zone, and China's Yangtze River Delta bonded magnet clusters was validated against secondary data from ECHA REACH compliance databases and METI supply security policy filings. Bottom-up volume modeling triangulated against top-down rare earth consumption estimates.
Variance decomposition across powder composition, manufacturing technology, end-use application, and geographic regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level demand elasticity modeling and input cost trajectory assumptions. Forecast inputs included automotive platform electrification timelines, F-Gas Regulation phase-down schedules, and PLI scheme disbursement patterns.
Material uncertainties — rare earth price volatility swings, NMPA standard revision timing, and polymer-composite talent pool expansion rates — sit outside the modeled envelope. Forecasts reflect assumptions about sustained automotive electrification CAPEX and stable REACH-RoHS regulatory enforcement. Revision becomes warranted when dysprosium spot price volatility exceeds historical bands or Chinese environmental compliance triggers feedstock supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Samarium Cobalt Magnets Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
Sintered Soft Magnetic Material Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
Neodymium-Iron-Boron Magnet Market
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Magnetic Material Magnetization and Testing Equipment Market
Magnetic Materials
Europe Copper Magnetic Wire Market
Magnetic Materials
Magnetic Filter Market
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
Magnet Buffer Market