
 Conductive Polymer Coatings Market | 2026-2036
Conductive Polymer Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Conductive Polymer Coatings Market Analysis
Asian specialty chemical producers is consolidating around captive monomer supply and toll coating capacity. Heraeus Holding leverages its precious metals heritage to dominate silver-flake conductive formulations for high-frequency electronics. PPG Industries sustains broad automotive OEM qualification across North American and European assembly plants. Akzo Nobel N.V. competes through waterborne dispersion R&D aligned with tightening solvent-emission rules.
Conductive polymer coatings are thin functional layers comprising intrinsically conductive polymers or polymer matrices loaded with conductive fillers such as carbon nanotubes, silver flakes, or PEDOT:PSS, applied to substrates via spraying, printing, or casting to impart electrical conductivity, static dissipation, or electromagnetic interference shielding. Films command premium positioning in flexible display and wearable sensor architectures where optical transparency paired with sheet resistance below 100 ohms/sq remains mandatory. Dispersions represent the fastest-growing product form as inkjet and screen-printable formats displace sputtered metal in antenna and RFID trace fabrication. Electronics application leads volume absorption, though aerospace qualification cycles create sticky, high-margin aftermarket positions.
EPA VOC regulations and REACH SVHC restrictions in Europe are forcing solvent-borne formulation phaseouts and accelerating waterborne emulsion development timelines. FDA device biocompatibility requirements and FCC EMI compliance standards in the United States shape product testing protocols for medical electronics and telecommunications equipment. Stakeholders must monitor polymer feedstock cost volatility and regional carbon-border adjustment mechanisms to preserve margin structures and supply chain optionality.
Market Dynamics
Waterborne emulsion formulations are displacing solvent-borne systems as REACH SVHC restrictions and EPA VOC regulations harden compliance baselines, forcing R&D timelines to compress and reshaping competitive positioning around dispersion chemistry capabilities.
Growth Catalysts
- Flexible Circuit Board Expansion:Electronics manufacturers in South Korea and Taiwan are scaling inkjet-printable conductive traces for foldable display architectures, pulling volume through dispersion-grade PEDOT:PSS formulations.
- EMI Shielding Mandates:FCC compliance standards for telecommunications equipment are tightening emission thresholds, compelling antenna and base-station fabricators to adopt silver-flake loaded coatings over metal housings.
- REACH Phase-Out Deadlines:ECHA restrictions on solvent-based coating constituents are accelerating waterborne emulsion qualification cycles among European automotive electronics suppliers.
Market Restraints
- Silver Price Volatility:Precious metal feedstock swings compress margin predictability for flake-loaded formulations, forcing hedging costs onto smaller compounders lacking captive metal supply.
- Monomer Supply Concentration:EDOT monomer production clusters in Chinese coastal provinces create geographic single-point vulnerability for PEDOT:PSS manufacturers elsewhere.
- Optical Transparency Limits:Sheet resistance below 50 ohms/sq remains incompatible with 90%+ visible light transmission in current carbon nanotube loadings, capping wearable sensor design freedom.
Strategic Opportunities
- Aerospace Aftermarket Qualification:FAA certification cycles for de-icing and static-dissipation coatings create decade-long incumbent positions with minimal substitution threat once approved.
- Medical Electronics Biocompatibility:FDA device-grade coating demand is outpacing qualified supply, opening margin expansion for compounders achieving ISO 10993 compliance.
- Printed Antenna Convergence:Screen-printable conductive inks are automating RFID trace fabrication, displacing etched copper in logistics and retail tagging applications.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Waterborne dispersion expertise resides in a narrow pool of polymer scientists, inflating compensation and extending hiring cycles for mid-cap producers.
- Multi-Regulatory Testing Burden:Simultaneous REACH, FDA, and FCC qualification protocols stretch validation timelines to 18-24 months for cross-vertical product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conductive Polymer Coatings Market |
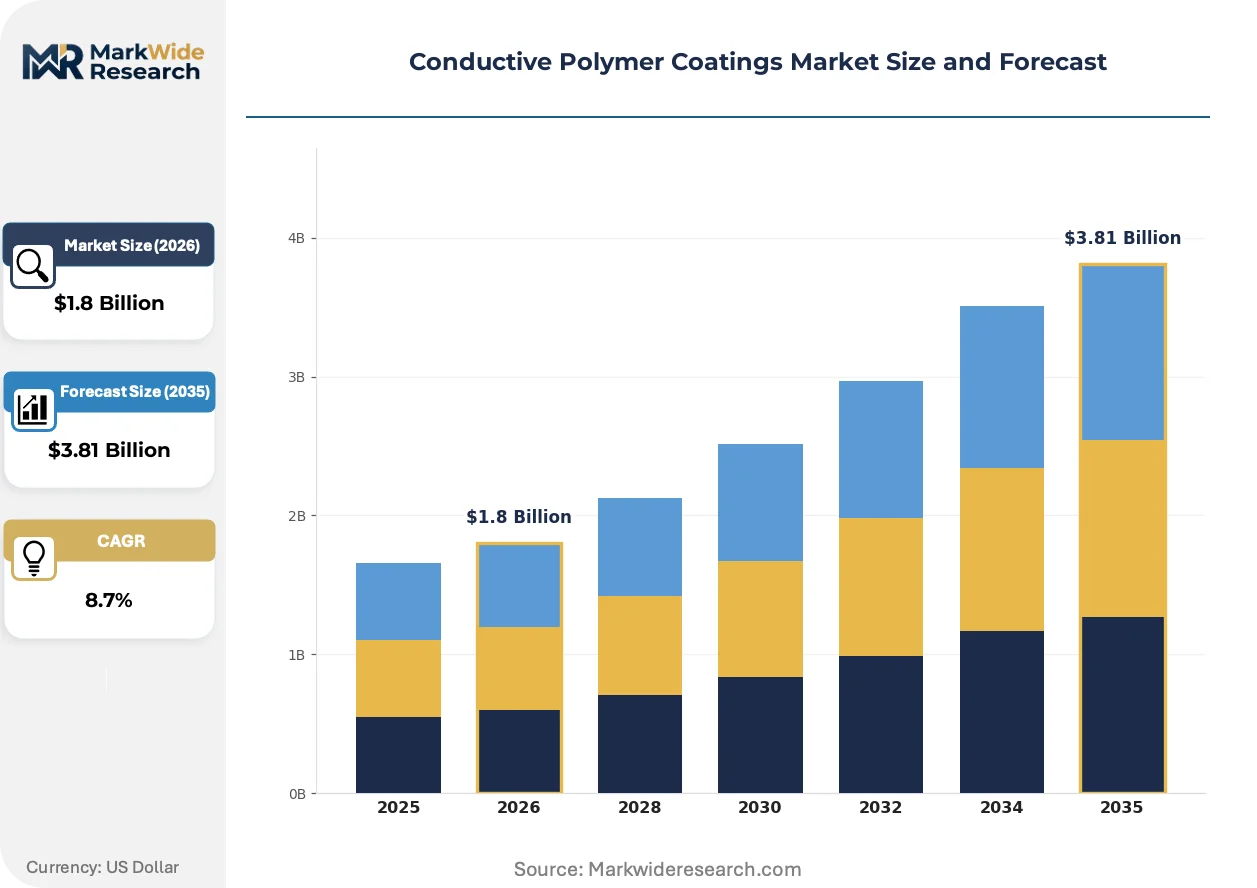
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsions, Solutions, Dispersions, Films Application: Electronics, Automotive, Aerospace, Solar Energy End User: Manufacturers, Research Institutions, Defense, Electronics Companies Installation: Spraying, Coating, Printing, Casting |
| Companies Covered | Heraeus Holding, PPG Industries, Inc., Akzo Nobel N.V., The Sherwin-Williams Company, AnCatt Inc., Henkel Electronics, The Lubrizol Corporation, The Dow Chemical Company, Agfa-Gevaert Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conductive Polymer Coatings Market Emerging Trajectories
Digital printing integration and regulatory chemistry shifts are compressing traditional coating application methods while opening new substrate-conformal possibilities previously unreachable through sputtering or lamination.
Roll-to-roll inkjet deposition systems are automating antenna trace fabrication onto curved automotive glass and textile substrates. Tier-one electronics manufacturers in Germany and Japan are qualifying these lines for 5G mm-wave antenna modules. This automation is compressing prototyping cycles from weeks to hours and reducing tooling capital versus photolithographic masks.
ECHA REACH SVHC candidate list expansion is forcing reformulation of legacy solvent-borne conductive primers used in industrial control enclosures. Coatings suppliers serving European automation OEMs are accelerating waterborne acrylic-urethane hybrid development. Medical electronics manufacturers face parallel pressure as MDR biocompatibility assessments now explicitly query coating leachables.
Direct procurement relationships between automotive OEMs and specialty chemical compounders are displacing traditional distributor networks for qualified coating supply. Tier-one EV battery pack manufacturers in Michigan and Bavaria now negotiate annual volume agreements directly with dispersion producers. This channel compression is most visible in North American electric powertrain assembly plants where traceability requirements exceed distributor technical capabilities.
Conductive Polymer Coatings Market Segmentation
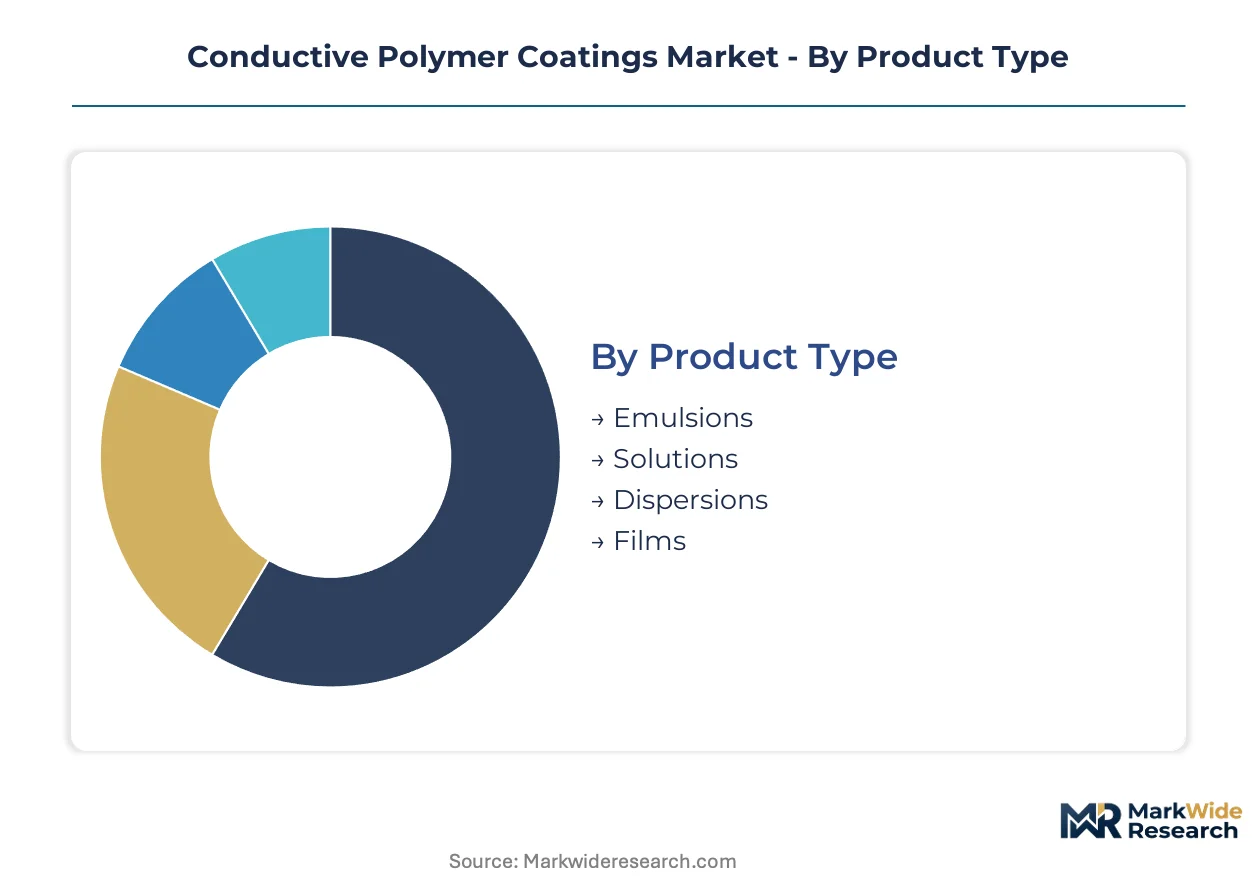
Conductive polymer coatings demand fragments across product chemistries, application verticals, and installation methods, each carrying distinct regulatory burdens and margin profiles. Understanding these segment boundaries reveals where formulation R&D investments concentrate and which qualification pathways govern market entry.
Product Type:
REACH SVHC restrictions and FDA device-grade approvals impose divergent testing timelines across these four chemistries, with waterborne systems facing compressed development cycles while solvent-borne legacy formulations require full reformulation.
- Emulsions:Waterborne acrylic-urethane hybrids carrying PEDOT:PSS or carbon nanotube loads. European automotive electronics suppliers in Stuttgart and Wolfsburg are accelerating qualification cycles as ECHA phase-out deadlines approach for solvent-based alternatives.
- Solutions:Solvent-borne conductive primers with legacy industrial control enclosure penetration. Reformulation costs are rising as ECHA REACH SVHC candidate list expansion forces substitution of aromatic hydrocarbon carriers.
- Dispersions:Inkjet and screen-printable formats displacing sputtered metal in antenna fabrication. South Korean foldable display manufacturers are scaling PEDOT:PSS dispersion volumes for flexible circuit traces.
- Films:Cast or extruded conductive layers demanding optical transparency below 100 ohms/sq sheet resistance. Wearable sensor architects in Japan and Germany specify these for biometric monitoring applications.
Leading the category by volume: Dispersions. Growing fastest: Emulsions.
Application:
End-use verticals stratify by certification intensity, with aerospace and medical electronics demanding multi-year qualification protocols while consumer electronics cycles compress to quarters.
- Electronics:Flexible circuit boards, EMI shielding, and antenna traces absorbing the majority of PEDOT:PSS and silver-flake formulation output. Taiwan and South Korean manufacturing clusters are scaling inkjet-printable conductive trace capacity for foldable smartphones and 5G mm-wave modules.
- Automotive:EV battery pack thermal management and powertrain EMI shielding. Direct procurement relationships between Michigan and Bavarian OEMs and specialty compounders are displacing traditional distributor networks for qualified supply.
- Aerospace:De-icing and static-dissipation coatings requiring FAA certification cycles that create decade-long incumbent positions once approved. Aftermarket demand concentrates in North American and European MRO facilities.
- Solar Energy:Transparent conductive oxide alternatives for photovoltaic cell front electrodes. German and Japanese module manufacturers are testing roll-to-roll compatible formulations.
Electronics commands volume leadership. Aerospace delivers margin premium through qualification stickiness.
End User:
Customer types diverge by technical capability, with research institutions driving early-stage formulation validation while defense buyers impose ITAR and security-cleared manufacturing constraints.
- Manufacturers:Tier-one electronics and automotive producers with in-house coating application lines. These buyers negotiate annual volume agreements directly with dispersion producers, bypassing distributor networks where traceability requirements exceed channel technical capabilities.
- Research Institutions:Universities and national laboratories piloting next-generation carbon nanotube loadings and biocompatible PEDOT:PSS variants. Publication-driven demand pulls small-batch specialty formulations.
- Defense:Security-cleared suppliers serving military electronics and aircraft platforms. ITAR compliance and domestic sourcing mandates restrict qualified vendor pools.
- Electronics Companies:Consumer device OEMs and contract manufacturers in Shenzhen, Seoul, and Tokyo. FCC EMI compliance standards shape product testing protocols for telecommunications equipment shipments.
Manufacturers dominate procurement volume. Research institutions generate disproportionate formulation innovation spillover.
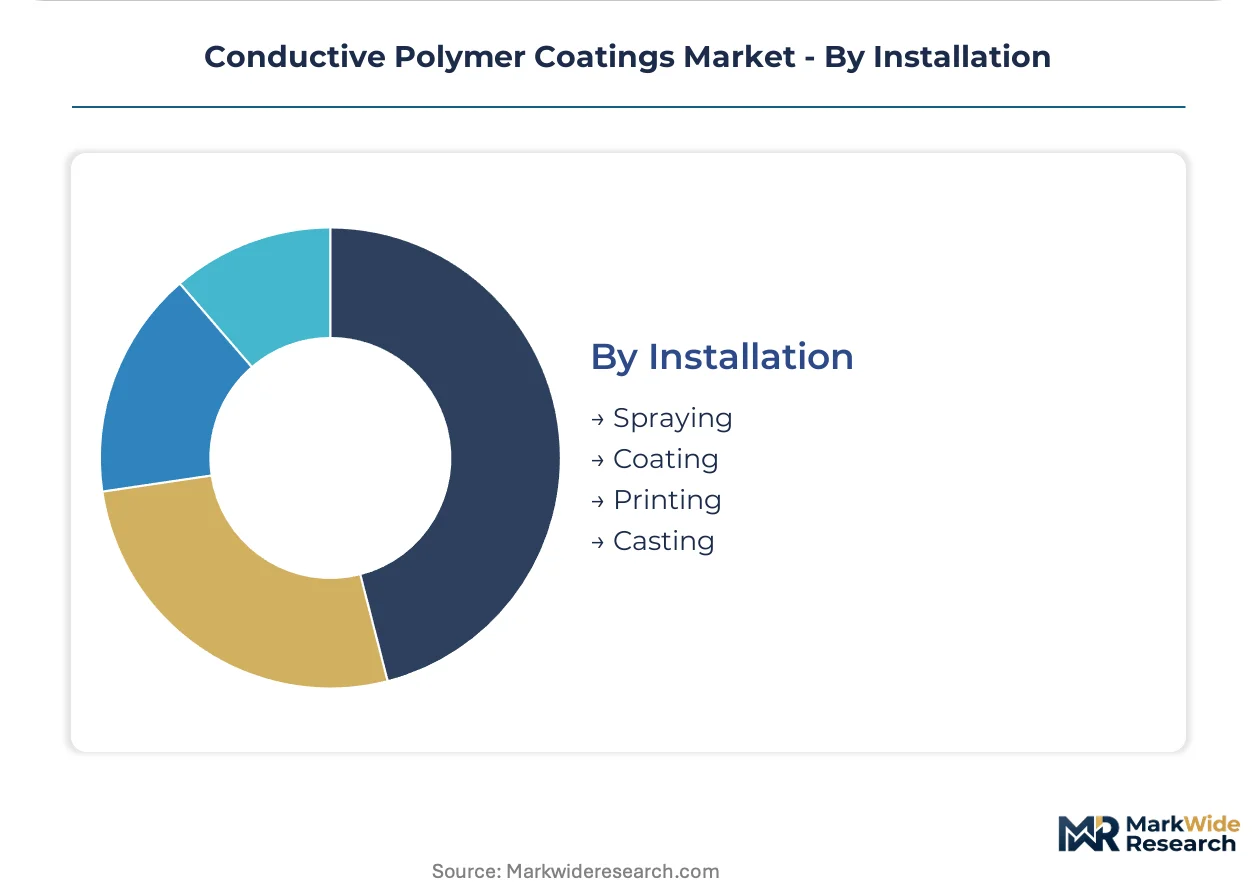
Installation:
Application method selection determines capital intensity and substrate versatility, with digital printing integration compressing prototyping cycles while traditional spraying retains scale advantages.
- Spraying:Conventional airless and electrostatic systems for large-area EMI shielding on industrial enclosures and automotive components. EPA VOC regulations are forcing equipment upgrades to capture solvent emissions.
- Coating:Dip and flow coating for uniform thickness on complex geometries. Medical device manufacturers in Massachusetts and Minnesota specify these methods for ISO 10993-compliant catheter and implant coatings.
- Printing:Screen, inkjet, and gravure deposition for antenna traces and flexible circuit patterns. Roll-to-roll inkjet systems are automating 5G mm-wave antenna fabrication onto curved automotive glass.
- Casting:Doctor blade and slot-die methods for free-standing conductive films. Wearable sensor producers in Japan and Germany use casting for optical transparency-critical biometric patches.
Printing gains share fastest through digital integration. Spraying retains volume leadership in industrial-scale applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EDOT monomer production clusters in Chinese coastal provinces anchor supply-side geography for PEDOT:PSS formulations, while electronics manufacturing demand concentrates in East Asian fabrication hubs and German automotive corridors.
China
Coastal province chemical parks in Jiangsu and Zhejiang host concentrated EDOT monomer synthesis capacity serving global PEDOT:PSS dispersion output. The Ministry of Ecology and Environment enforces dual carbon goals that tighten emissions standards for solvent-borne coating facilities. Shenzhen and Dongguan electronics contract manufacturers scale inkjet-printable conductive trace capacity for foldable smartphone exports.
South Korea
Seoul Capital Area display panel producers drive dispersion-grade PEDOT:PSS volumes for flexible OLED circuit architectures. The Ministry of Trade, Industry and Energy administers K-REACH chemical registration parallel to EU standards. Suwon and Gumi manufacturing clusters qualify roll-to-roll inkjet deposition lines for 5G mm-wave antenna modules.
Germany
Baden-Württemberg and Bavarian automotive electronics suppliers accelerate waterborne emulsion qualification for EV battery pack thermal management. ECHA REACH SVHC restrictions force phase-out timelines for legacy solvent-borne conductive primers. Stuttgart and Wolfsburg OEMs negotiate direct procurement agreements with specialty compounders bypassing distributor networks.
United States
Michigan and California EV powertrain manufacturers absorb silver-flake loaded coatings for EMI shielding in high-voltage battery assemblies. EPA VOC regulations and FCC emission compliance standards shape product testing protocols for telecommunications equipment. Boston and Minneapolis medical device clusters demand ISO 10993-compliant catheter coatings with biocompatibility certification.
Japan
Kanto and Kansai wearable sensor architects specify cast conductive films combining optical transparency with sub-100 ohm/sq sheet resistance. METI oversees JIS standards alignment for electronics-grade coating performance specifications. Nagoya and Osaka precision equipment manufacturers pilot carbon nanotube loadings for biometric monitoring patches.
Conductive Polymer Coatings Market Vendor Landscape
Global majors compete with regional champions across formulation chemistry capabilities and qualification breadth. Market structure tilts toward consolidated leadership in precious metals-based formulations alongside fragmented dispersion specialists. Three archetypes dominate: diversified coatings conglomerates with automotive OEM qualification, precious metals heritage players anchoring high-frequency electronics, and waterborne emulsion specialists aligned with REACH compliance timelines. Competitive moves concentrate on direct procurement relationship cultivation with tier-one manufacturers and waterborne R&D capacity expansion.
Among diversified coatings conglomerates, PPG Industries and Akzo Nobel N.V. occupy positions spanning automotive and industrial qualification networks. Heraeus Holding exemplifies the precious metals heritage archetype, leveraging upstream metal supply control for conductive flake formulations. These three anchors illustrate how competitive positioning splits between scale-driven broad qualification and captive feedstock specialization.
| Leading Market Players |
|---|
| Heraeus Holding |
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| The Sherwin-Williams Company |
| AnCatt Inc. |
| Henkel Electronics |
| The Lubrizol Corporation |
| The Dow Chemical Company |
| Agfa-Gevaert Group |
| Others |
Supply Flow & Price Mechanics
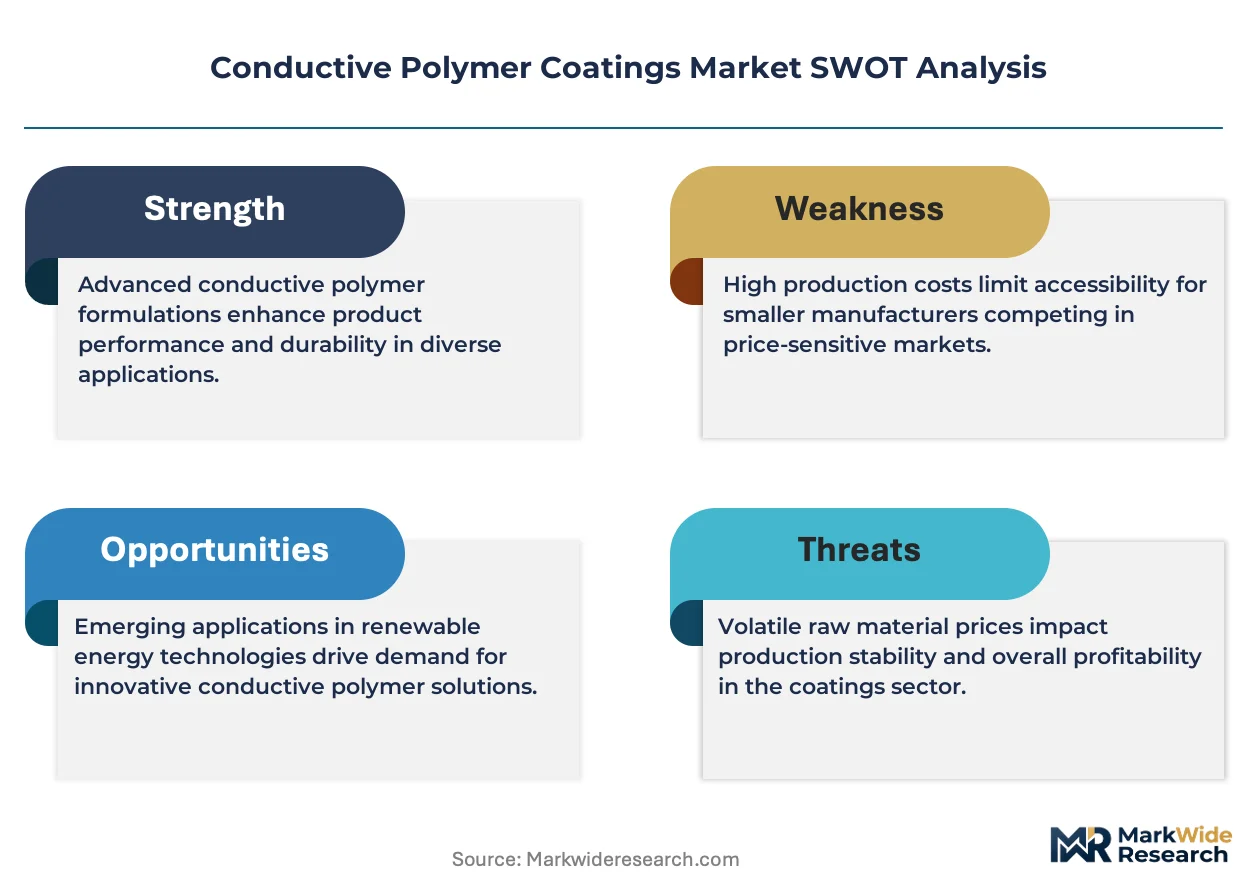
Silver flake feedstock costs cascade through three distinct pricing tiers before reaching automotive EMI shielding buyers, with precious metal volatility compressing margins most severely at mid-scale compounders lacking captive metal supply or long-term offtake hedging instruments.
Pricing Analysis
Warranty-backed qualification certificates bundle with premium-grade PEDOT:PSS dispersions for medical electronics, while standard industrial EMI coatings ship unbundled. Three-tier pricing structure across premium, standard, and economy levels separates FDA device-grade formulations from automotive qualified and generic industrial grades. Cost compression in the standard tier is intensifying because South Korean display manufacturers are consolidating procurement volumes and demanding annual price step-downs. Contract manufacturers in Shenzhen exhibit highest price sensitivity; aerospace aftermarket buyers show least sensitivity due to decade-long qualification lock-in.
Supply Chain Analysis
Domestic-content mandates under ITAR compliance and K-REACH parallel registration requirements are reshaping sourcing patterns for defense and South Korean electronics suppliers. EDOT monomer synthesis clusters in China's Jiangsu and Zhejiang provinces, with secondary capacity in South Korea and Japan. Conductive polymer coatings draw from silver flake, carbon nanotube, and acrylic-urethane resin inputs. Single-source vulnerability concentrates around Chinese coastal chemical parks for EDOT supply. Distribution runs through direct procurement relationships between automotive OEMs and specialty compounders, bypassing traditional distributor networks where traceability requirements exceed channel technical capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The conductive polymer coatings sector sits in a waterborne-emulsion transition phase, with inkjet-printable PEDOT:PSS dispacements displacing legacy solvent-borne primers under REACH SVHC and EPA VOC regulatory compression.
For Market Incumbents: Hedge precious metal exposure through backward integration into silver flake supply or long-term offtake agreements with mining consortiums. Accelerate waterborne emulsion R&D capacity in Baden-Württemberg and Michigan to defend automotive OEM qualification positions against emerging Asian dispersion specialists. Certification investment in ISO 10993 biocompatibility pathways opens medical electronics margin expansion. For New Entrants and Emerging Players: Capture white-space in FDA device-grade coating supply where qualified compounders lag demand growth from Boston and Minneapolis medical device clusters. Target aerospace aftermarket qualification cycles for de-icing and static-dissipation coatings to build decade-long incumbent positions with minimal substitution threat. Lead with toll coating partnerships offering REACH-compliant waterborne formulations to European automotive electronics suppliers facing ECHA phase-out deadlines. For Investors and Strategic Acquirers: Distressed-cycle entries favor waterborne emulsion specialists with captive monomer supply in Chinese coastal provinces or toll coating capacity in Germany. Long-term viability hinges on regulatory chemistry capabilities aligned with tightening solvent-emission rules across multiple geographies. Watch for inflection signals in roll-to-roll inkjet deposition line qualification counts at Tier-one electronics manufacturers in Seoul and Tokyo.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Flake Supply | Heraeus Holding leverages precious metals heritage to secure flake formulation margins against COMEX volatility. |
| Waterborne Emulsion Capacity Expansion | PPG Industries sustains broad automotive OEM qualification across North American and European assembly plants. |
| Medical Electronics Biocompatibility Certification | Akzo Nobel N.V. competes through ISO 10993-aligned waterborne dispersion R&D for catheter coating demand. |
| Roll-to-Roll Inkjet Deposition Partnership | South Korean display manufacturers scale PEDOT:PSS dispersion volumes for foldable smartphone circuit architectures. |
| Aerospace Aftermarket Qualification | FAA certification cycles for de-icing coatings create sticky, high-margin positions with minimal substitution threat. |
Methodological Framework
Document review covered SEC 10-K filings from coatings conglomerates, ECHA REACH registration databases, and FCC EMI compliance filings, complemented by interviews with technical R&D directors at specialty chemical compounders, procurement leads at Tier-one electronics manufacturers, plant managers at EDOT monomer synthesis facilities, and distribution channel partners serving automotive OEMs. Secondary validation drew from customs/trade data, ACC and Cefic industry reports, and hospital procurement databases for medical electronics applications. Bottom-up volume builds and top-down market sizing were triangulated to ensure consistency.
Segmentation-level outputs across the analysis window reflect modeled assumptions for product chemistry, application vertical, installation method, and regional regulatory cluster. CAGRs were derived from regression analysis against electronics manufacturing output indices, automotive production forecasts, and aerospace MRO spending patterns. Industry-specific inputs included inkjet deposition line qualification timelines, REACH SVHC candidate list expansion schedules, and silver price volatility bands.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EDOT monomer supply disruptions in Chinese coastal provinces, abrupt REACH restriction expansions, and foldable display adoption rates in consumer electronics. Forecasts reflect documented assumptions about regulatory enforcement intensity and waterborne formulation technical maturation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Canada Industrial Wood Coatings Market
Coatings
United Arab Emirates Floor Coatings Market
Coatings
Anti-Microbial Coatings Market
Coatings
E-Coat Market
Coatings
Tablet Coatings Market
Coatings
Leisure Boat Marine Coatings Market
Coatings
Europe Coil Coatings Market
Coatings
Silicone Coating Market
Coatings
Asia-Pacific Epoxy Powder Coatings Market
Coatings
Graphene Coatings Market
Coatings
Silicate Coatings Market
Coatings
Coatings and Fillings Market
Coatings
Global Hydrophobic Coating Market
Coatings
Polyvinylidene Fluoride (PVDF) Coatings Market
Coatings
Coating Auxiliaries Market
Coatings
Asia-Pacific Radiation Curable Coatings Market