
 North America Magnet Market | 2026-2036
North America Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
North America Magnet Market Intelligence
Defense and aerospace procurement is collapsing toward commercial EV and wind turbine OEMs as the dominant buyer archetype in the North America magnet space. Arnold Magnetic Technologies leverages its rare-earth processing capabilities to serve high-performance motor applications. MP Materials anchors domestic upstream supply through its Mountain Pass, California, rare earth mining and separation operations. Electron Energy Corporation specializes in samarium-cobalt magnets for extreme-temperature defense and space systems.
A magnet is a material or object that produces a magnetic field, typically composed of iron, nickel, cobalt, or rare-earth elements such as neodymium and dysprosium, with remanence and coercivity values determining field strength and thermal stability. Its primary industrial purpose is to convert electrical energy to mechanical motion in motors, generators, and actuators, or to enable sensing, separation, and confinement functions across manufacturing and healthcare systems. Permanent magnets command the largest share of value given their irreplaceable role in EV traction motors, though superconducting magnets capture premium margins in medical imaging equipment. Soft magnets serve high-frequency electronics and transformer applications where rapid magnetization reversal is essential.
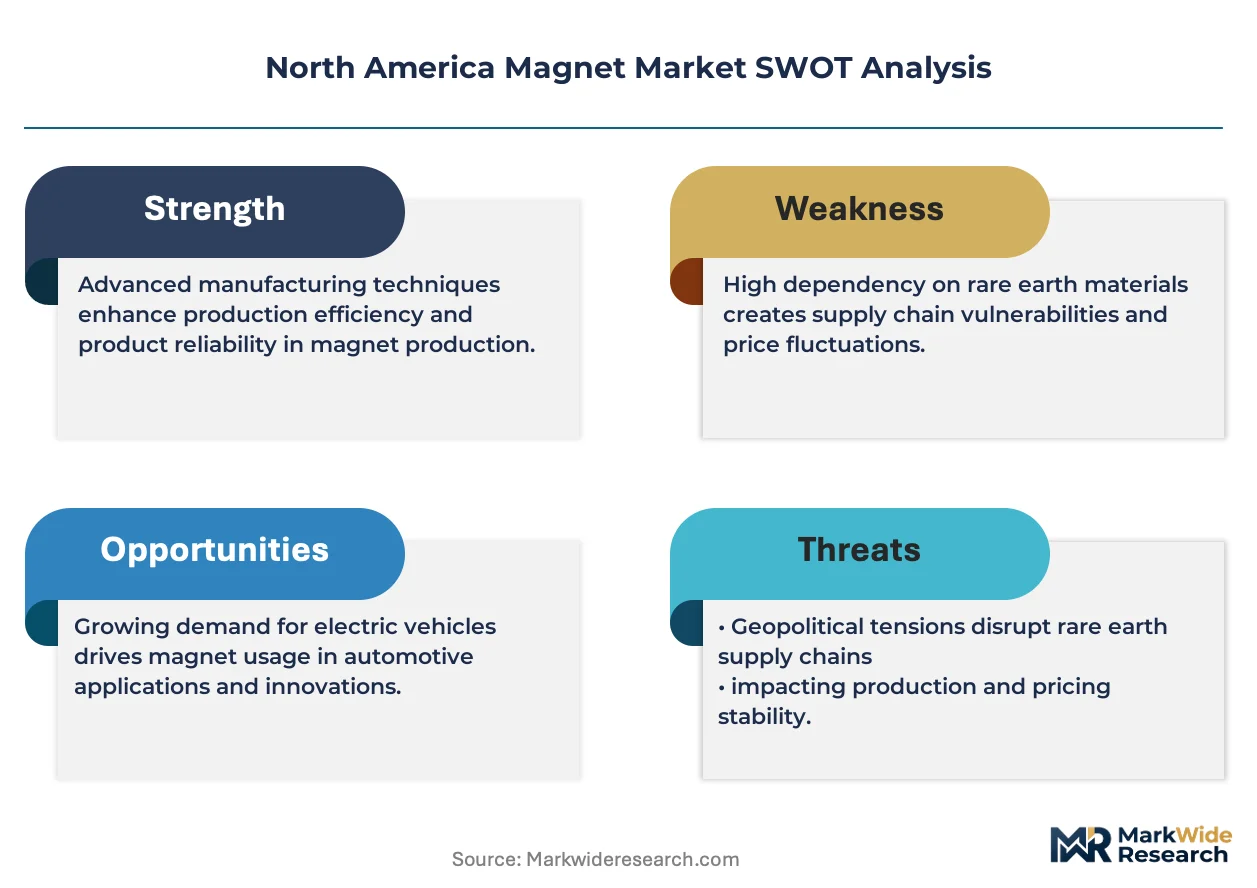
The US Department of Energy enforces rare-earth supply chain resilience mandates that direct federal procurement toward domestically processed magnet materials. EPA hazardous waste rules govern the environmental compliance burden of rare-earth extraction and refining operations. NHTSA fuel economy standards indirectly amplify magnet demand by pushing automakers toward lighter, more efficient permanent magnet motor designs. Stakeholders must monitor how quickly US-based separation and alloying capacity scales to match the IRA's domestic content thresholds without disrupting cost structures.
Market Dynamics
The Inflation Reduction Act's domestic content thresholds are compressing magnet supply chains toward US-based rare-earth separation and alloying capacity, forcing powertrain manufacturers to requalify vendors against origin-certification requirements rather than pure performance metrics.
Growth Catalysts
- IRA Domestic Content Incentives:Federal tax credits for EVs and clean energy equipment now require North American-sourced critical minerals, redirecting procurement teams toward domestic magnet processors.
- Powertrain Electrification:Traction motor architectures in battery electric vehicles permanently embed rare-earth permanent magnets, locking in material demand regardless of motor topology variations.
- Defense Stockpiling Mandates:The US Department of Defense's rare-earth reserve directives create a parallel demand stream independent of commercial pricing cycles.
Market Restraints
- Upstream Concentration Risk:Heavy rare-earth separation capacity remains concentrated in Asian processing corridors, exposing US magnet fabricators to export restriction vulnerabilities.
- Dysprosium-Terbium Cost Volatility:Thermal-grade magnet formulations depend on these heavy rare-earth inputs, with spot pricing subject to geopolitical disruption rather than pure supply-demand mechanics.
- Sintered NdFeB Technical Ceiling:Grain boundary diffusion techniques are approaching theoretical coercivity limits, constraining temperature performance gains for next-generation traction motors.
Strategic Opportunities
- Recycling Infrastructure Gap:End-of-life magnet recovery from discarded electronics and industrial equipment remains underdeveloped across the US Midwest manufacturing belt.
- Wind Turbine Direct-Drive Conversion:Offshore wind installations above 10MW capacity are shifting from doubly-fed induction to permanent magnet generators, opening new volume channels.
- Medical Imaging Magnet Refurbishment:Superconducting MRI system lifecycle extension programs create aftermarket demand for magnetic field stability verification and cryostat reconditioning services.
Industry Challenges
- Rare-Earth Metallurgy Talent Scarcity:Separation chemistry and magnet alloy formulation expertise has atrophied in North American universities over three decades of offshoring.
- Dual-Use Export Control Complexity:ITAR and EAR classification rules for high-performance samarium-cobalt grades create compliance friction for defense-aerospace suppliers serving commercial EV crossover demand.
- Legacy Motor Retrofit Integration:Industrial equipment OEMs face mechanical redesign costs when substituting ferrite or induction architectures with rare-earth permanent magnet solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Magnet Market |
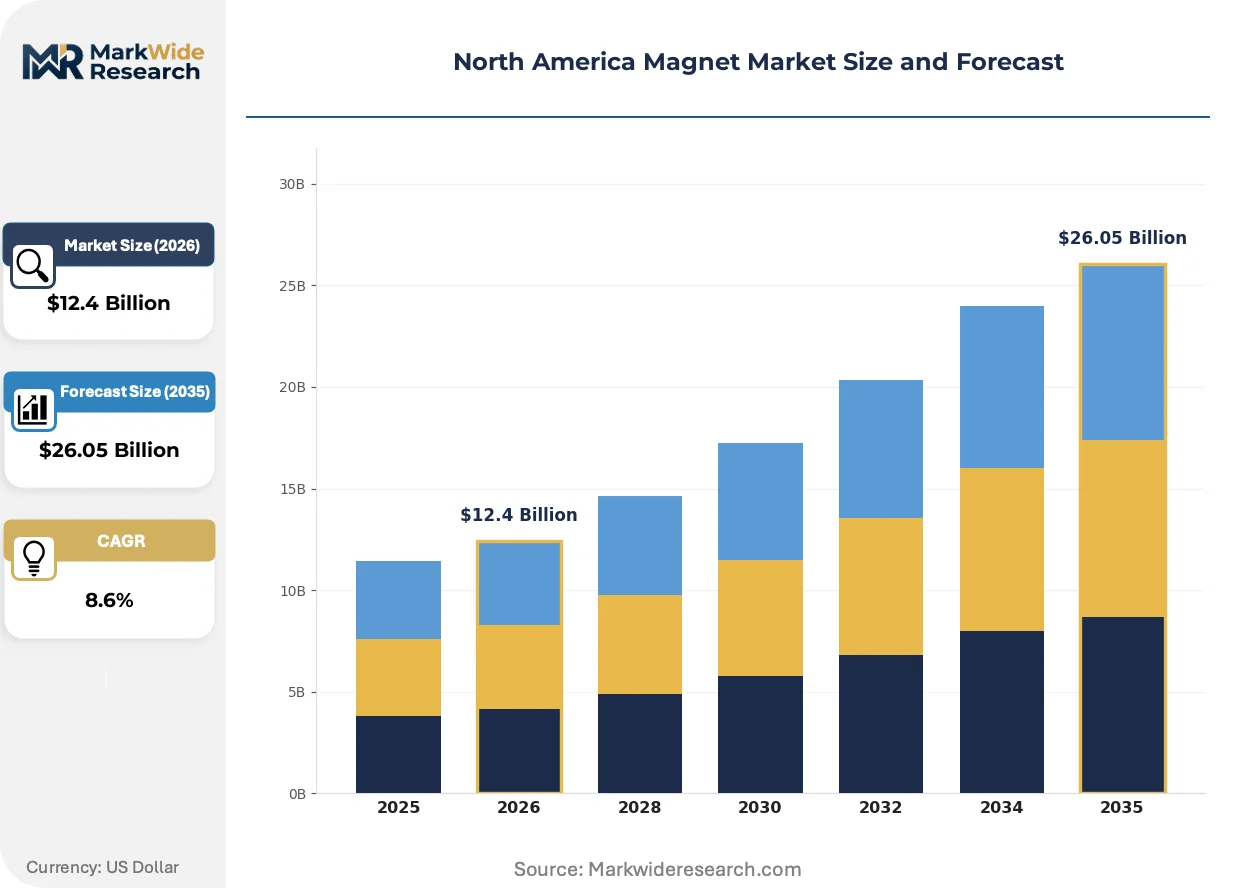
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Magnets, Electromagnets, Soft Magnets, Superconducting Magnets End User: Automotive, Electronics, Medical Devices, Industrial Equipment Technology: 3D Printing, Injection Molding, Magnetic Separation, Thin-Film Application: Magnetic Sensors, Motors, Magnetic Bearings, Magnetic Resonance Imaging |
| Companies Covered | Electron Energy Corporation, Rochester Magnet, Arnold Magnetic Technologies, Adams Magnetic Products, Integrated Magnetics, Master Magnetics, Dura Magnetics, MP Materials, Magnum Magnetics, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Magnet Market Strategic Shifts & Innovations
Magnet technology trajectories are diverging between cost-optimized ferrite solutions for auxiliary automotive loads and performance-differentiated rare-earth formulations for traction and aerospace applications.
Grain boundary diffusion processing for neodymium-iron-boron magnets is fragmenting the supplier landscape between integrated miners with captive separation capacity and independent alloy fabricators dependent on spot oxide markets. Tier-1 EV motor manufacturers are dual-sourcing between these supplier archetypes to hedge against concentration risk. The technical consequence is a bifurcation in coercivity-grade availability, with premium thermal ratings commanding extended lead times.
The EPA's hazardous waste classification for rare-earth extraction tailings is tightening discharge permitting for Mountain Pass and any planned domestic separation expansions. This regulatory friction is extending project development timelines by 18-24 months for greenfield refining capacity. Magnet processors are responding by investing in closed-loop water recovery systems to preempt enforcement actions and secure operating licenses.
Long-term magnet supply agreements are displacing spot purchasing for EV powertrain programs as OEMs seek origin certification traceability for IRA compliance. Procurement teams are embedding metallurgical auditors at supplier facilities to verify rare-earth provenance. This behavioral shift is most pronounced among Detroit Three automakers with battery assembly commitments in Tennessee, Kentucky, and Michigan.
North America Magnet Market Segmentation
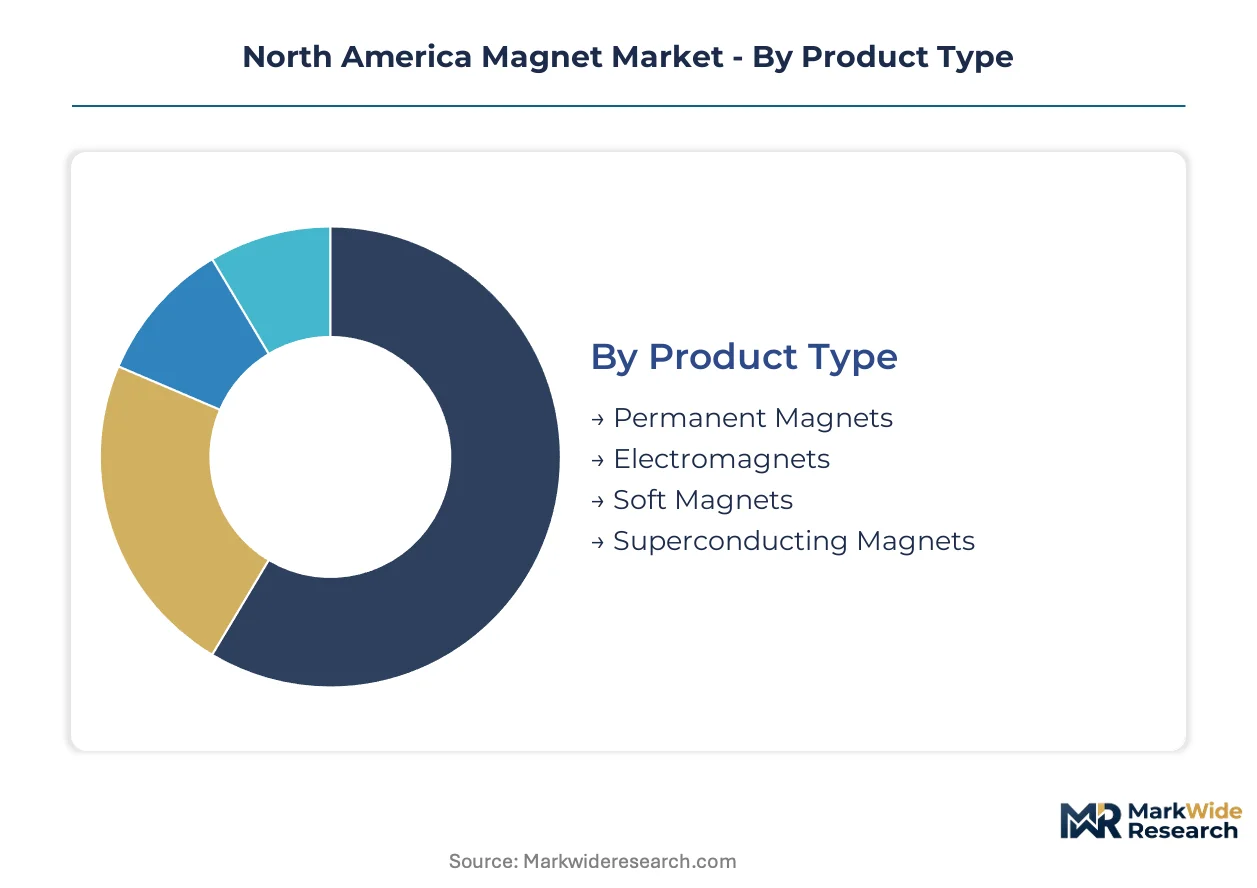
Magnet procurement patterns diverge sharply between volume-driven automotive programs and specification-critical defense-medical channels. Understanding these segment-specific demand profiles enables suppliers to align metallurgical investments with the correct customer archetype.
Product Type:
Permanent magnets flow predominantly through direct OEM supply agreements, while superconducting and soft magnet categories concentrate in specialized distributor networks serving fragmented equipment markets.
- Permanent Magnets:Neodymium-iron-boron and samarium-cobalt alloys dominate traction motor specifications, with sintered NdFeB formulations capturing the bulk of EV powertrain procurement from Michigan and Tennessee assembly plants. Heavy rare-earth content determines thermal grade eligibility for aerospace applications.
- Electromagnets:Copper-wound cores with adjustable field strength serve industrial lifting and sorting equipment across the US Midwest manufacturing belt. Demand concentrates in scrap metal processing and automated material handling installations where field modulation outweighs energy efficiency priorities.
- Soft Magnets:Silicon-iron laminations and ferrite cores enable high-frequency transformer and inductor applications. Motor laminations from Ohio and Pennsylvania steel mills feed into appliance and HVAC compressor motor production.
- Superconducting Magnets:Niobium-titanium and rare-earth barium-copper-oxide configurations generate the intense, stable fields required for MRI diagnostic imaging. Installation and refurbishment services generate recurring revenue streams independent of unit sales cycles.
By volume, permanent magnets lead. By growth pace, superconducting magnet services are expanding most quickly.
End User:
Cost tiers separate the market: automotive and industrial buyers prioritize unit economics at scale, while medical and electronics segments absorb premium pricing for traceability and precision.
- Automotive:Traction motor magnets constitute the largest single demand pool, with Detroit Three OEMs and Tesla anchoring procurement volumes. IRA domestic content rules are forcing requalification of magnet suppliers against origin-certification standards rather than pure performance metrics.
- Electronics:Miniaturized NdFeB grades power smartphone haptics, acoustic transducers, and hard disk drive spindle motors. California and Texas design centers drive specification-setting for consumer electronics magnet vendors.
- Medical Devices:MRI system manufacturers and implantable device producers demand samarium-cobalt stability for surgical instruments and diagnostic equipment. FDA device regulations impose material traceability requirements that favor established magnet fabricators with quality system certifications.
- Industrial Equipment:Conveyor separators, lifting magnets, and magnetic couplings serve mining, recycling, and chemical processing operations. Price sensitivity here favors ferrite alternatives unless operational temperatures mandate rare-earth performance.
Automotive commands the revenue base. Medical devices generate the steepest margin expansion trajectory.
Technology:
Maturity curves separate established processes from emerging fabrication methods still seeking production-scale validation.
- 3D Printing:Additive manufacturing of complex magnet geometries remains confined to prototyping and low-volume aerospace components. Binder jet and directed energy deposition techniques struggle to match the magnetic properties of conventionally sintered materials.
- Injection Molding:Polymer-bonded NdFeB and ferrite compounds enable intricate shapes for automotive sensors and consumer electronics. Kentucky and Indiana molding houses serve tier-1 automotive suppliers with integrated magnet-assembly capabilities.
- Magnetic Separation:Eddy current and drum separator systems recover ferrous and non-ferrous materials from waste streams. Equipment OEMs in Ohio and Illinois dominate this aftermarket-driven segment.
- Thin-Film:Sputtered and plated magnetic layers enable read/write heads, MEMS devices, and magnetic recording media. Deposition expertise concentrates in California and Arizona semiconductor fabrication corridors.
Injection molding scales fastest. Thin-film commands the highest process complexity premiums.
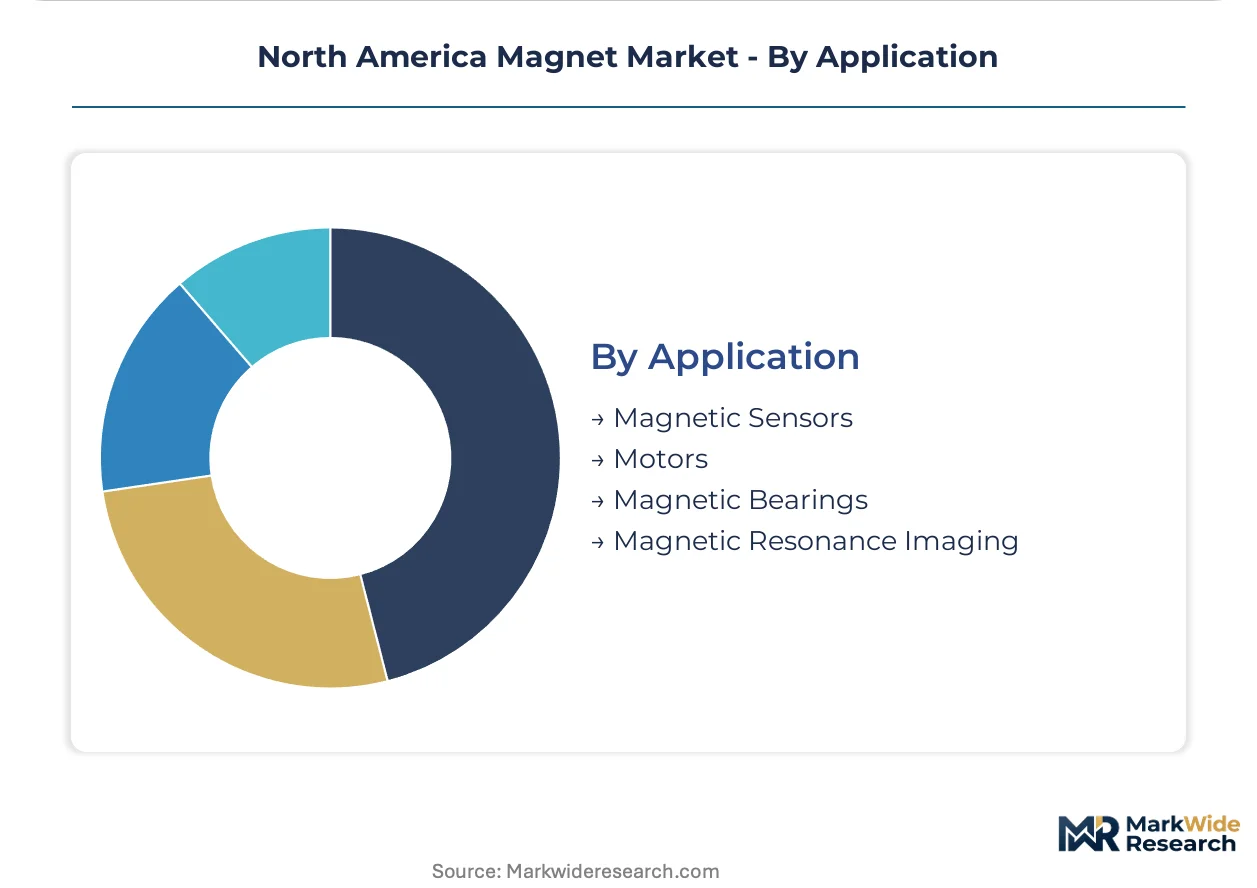
Application:
Geographic clustering shapes demand: motors concentrate in the US Southeast, sensors in the Midwest, and imaging equipment on the coasts.
- Magnetic Sensors:Hall-effect and magnetoresistive devices enable position, speed, and current sensing across automotive and industrial automation. Tennessee and Kentucky sensor module plants source bonded magnet assemblies from regional processors.
- Motors:Traction, servo, and spindle motor architectures embed permanent magnets as the irreplaceable torque generation mechanism. Georgia, South Carolina, and Michigan motor assembly plants are driving regional magnet processing investment.
- Magnetic Bearings:Contact-free suspension systems serve turbo machinery, vacuum pumps, and flywheel energy storage. Oil-free compressor applications in Texas and Louisiana chemical plants sustain niche demand.
- Magnetic Resonance Imaging:Superconducting magnet systems require cryogenic stability and field homogeneity specifications that only a handful of global suppliers can meet. Refurbishment and field service operations extend system lifecycles beyond original equipment sales.
Motors dominate volume throughput. Magnetic bearings are gaining share fastest in emerging energy storage applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense and aerospace procurement is collapsing toward commercial EV and wind turbine OEMs as the dominant buyer archetype in the North America magnet space. Electric vehicle powertrain manufacturers are accelerating orders for rare-earth permanent magnets. Demand is concentrating in the US Southeast, where battery and motor assembly plants are clustering near magnet processing facilities.
United States
Traction motor magnets constitute the largest single demand pool, with Detroit Three OEMs and Tesla anchoring procurement volumes. The Inflation Reduction Act's domestic content incentives are reshaping supply chain localization decisions. Georgia, South Carolina, and Michigan motor assembly plants are driving regional magnet processing investment.
Canada
Soft magnet laminations from Ontario steel mills feed into appliance and HVAC compressor motor production. Health Canada regulations govern medical device magnet traceability for implantable products. Quebec's rare-earth exploration projects are advancing toward feasibility studies for upstream supply diversification.
Mexico
Automotive sensor module assembly in Nuevo León and Baja California sources bonded magnet components from regional processors. USMCA origin rules create compliance pathways for magnet content qualification in North American vehicle production. Mexico City Metro area houses electronics manufacturing services integrating miniaturized magnet assemblies.
North America Magnet Market Key Industry Players
Player mix skews toward vertically integrated miners with captive separation capacity and independent alloy fabricators dependent on spot oxide markets. Tier-1 EV motor manufacturers are dual-sourcing between these supplier archetypes to hedge against concentration risk. Strategic archetypes include domestic upstream integrators, specialty defense-aerospace fabricators, and volume-driven automotive suppliers. Competitive moves center on capacity expansion for rare-earth separation and strategic partnerships for origin-certification traceability.
Among domestic upstream integrators, MP Materials anchors domestic supply through its Mountain Pass, California, rare-earth mining and separation operations. Arnold Magnetic Technologies leverages its rare-earth processing capabilities to serve high-performance motor applications. Electron Energy Corporation exemplifies the specialty defense-aerospace fabricator archetype, occupying a position focused on extreme-temperature systems.
| Leading Market Players |
|---|
| Electron Energy Corporation |
| Rochester Magnet |
| Arnold Magnetic Technologies |
| Adams Magnetic Products |
| Integrated Magnetics |
| Master Magnetics |
| Dura Magnetics |
| MP Materials |
| Magnum Magnetics |
| Others |
Cost & Logistics Intelligence
Ferrite magnet substitution in auxiliary automotive motors simultaneously shifts procurement geography toward domestic Ohio and Pennsylvania steel mills and compresses rare-earth pricing premiums for traction-grade NdFeB formulations. This displacement dynamic rewards suppliers with captive ferrite powder production while exposing independent rare-earth alloy fabricators to margin erosion in non-critical motor applications.
Pricing Analysis
Cost-plus contracts indexed to Shanghai Metal Market rare-earth oxide quotations dominate long-term EV powertrain procurement, with thermal-grade premiums widening based on dysprosium-terbium content thresholds. Price differentiation separates IRA-certified domestic origin magnets from uncertified imports, with Detroit Three automakers absorbing standard-grade premiums while aerospace buyers pay steep markups for ITAR-traceable samarium-cobalt. Pricing pressure stems from heavy rare-earth spot volatility rather than demand softness, with industrial equipment OEMs exhibiting highest price sensitivity and medical device manufacturers showing lowest elasticity due to FDA-mandated supplier lock-in.
Supply Chain Analysis
China and Myanmar anchor heavy rare-earth mining and separation, with the United States and Australia expanding light rare-earth extraction capacity at Mountain Pass and Mount Weld respectively. Magnet alloy fabrication draws from separated oxide feedstock, copper winding materials, and specialty coating chemistries. Single-source vulnerability concentrates in heavy rare-earth separation corridors subject to export licensing disruptions. Distribution runs through direct OEM supply agreements for permanent magnets and specialized distributor networks for soft magnet laminations serving fragmented industrial equipment markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America magnet market is recovering from a cyclical trough driven by EV production ramp schedules and IRA incentive activation timelines. Powertrain electrification commitments by Detroit Three OEMs provide demand visibility through the mid-decade capacity buildout phase.
For Market Incumbents: Compound metallurgical expertise advantages by securing captive heavy rare-earth offtake agreements before separation capacity constraints tighten. Expand grain boundary diffusion processing lines in Tennessee and Kentucky to capture IRA-compliant demand from regional motor assembly plants. Defend against Chinese integrated miners entering US magnet fabrication through accelerated origin-certification investments.
For New Entrants and Emerging Players: ITAR fast-track certification for samarium-cobalt grades opens defense-aerospace procurement channels insulated from automotive pricing cycles. Target medical device magnet refurbishment services in California and Massachusetts, where FDA quality system requirements create incumbent switching costs. Pursue bonded ferrite injection molding partnerships with Kentucky automotive sensor suppliers as the lowest-capital entry vector.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rare-earth separation ventures in Mountain Pass and Texas that require downstream integration to capture full margin stacks. Five-to-ten-year viability hinges on sustained IRA domestic content enforcement and defense stockpiling mandate continuity. Watch EPA hazardous waste permitting velocity for greenfield refining projects as the inflection signal for supply-constraint duration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Separation | Captures margin upstream from oxide feedstock through magnet alloy production under IRA origin rules. |
| Grain Boundary Diffusion Capacity Expansion | Enables thermal-grade NdFeB supply for next-generation traction motors at Tennessee assembly plants. |
| ITAR Certification Investment | Unlocks defense-aerospace procurement insulated from automotive spot pricing volatility. |
| Magnet Recycling Infrastructure Buildout | Addresses end-of-life recovery gap across Midwest manufacturing belt for secondary rare-earth supply. |
| Closed-Loop Water Recovery Systems | Preempts EPA enforcement actions and secures operating licenses for domestic refining expansion. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with magnet procurement directors at Detroit Three OEMs, rare-earth separation plant managers, and EPA regulatory compliance officers; and secondary validation against USGS mineral commodity summaries, SEC 10-K filings from listed miners, and NHTSA fuel economy rulemaking dockets. Bottom-up triangulation across powertrain magnet content per vehicle and top-down reconciliation against EV production forecasts anchored volume estimates.
Across the analysis window, the forecasting framework modeled demand trajectories by magnet alloy type, end-use sector concentration, and thermal grade specification tier. CAGRs were derived from installed capacity buildout schedules and IRA domestic content threshold phase-in mechanics. Key inputs included motor architecture adoption curves, rare-earth separation capacity expansion timelines, and defense stockpiling mandate funding authorization patterns.
Underlying assumptions cover sustained IRA incentive eligibility, EPA permitting continuity, and absence of export restriction shocks, with deviation risk concentrated in heavy rare-earth supply disruption and EV adoption rate deceleration. Recalibration cycles align with quarterly mineral commodity price releases and federal procurement policy updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Magnetic Carbon Nanofoam Market
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
North America Magnet Wire Market
Magnetic Materials
North America Ferrite Magnet Market
Magnetic Materials
Neodymium [Nd-Fe-B] Magnet Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Magnet Wire Market
Magnetic Materials
High Purity Carbonyl Iron Powder (CIP) Market
Magnetic Materials
Ferrite Magnet Market
Magnetic Materials
Cobalt Oxide Market
Magnetic Materials
Global Permanent Magnet Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market