
 Gadolinium Market | 2026-2036
Gadolinium Market Size, Share, and Industry Trends Forecast 2026-2036
Gadolinium Market Analysis
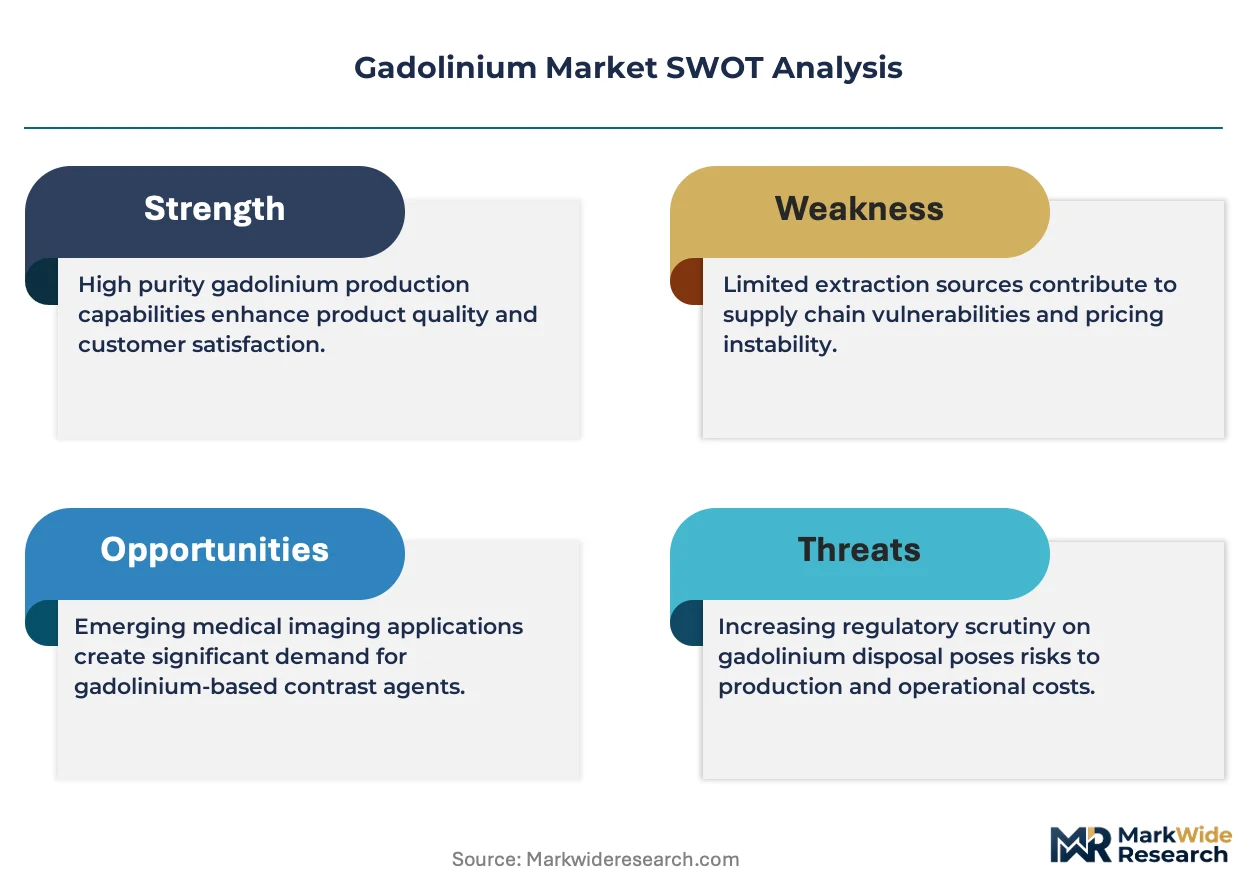
Asset-light leasing models for MRI contrast agents are narrowing the competitive field. Bayer AG leverages captive pharmaceutical distribution to sustain margin capture across hospital networks. Lynas Rare Earths anchors Western supply security through its Mount Weld concentration and Malaysian separation infrastructure. GE Healthcare competes on integrated imaging system-contrast bundling that locks in procurement cycles.
Gadolinium is a lanthanide rare earth element with atomic number 64, characterized by exceptionally high neutron absorption cross-section and strong paramagnetic properties at room temperature; it is produced through solvent extraction of bastnäsite or monazite concentrates, followed by ion exchange purification to meet pharmaceutical-grade specifications for injectable contrast media. Gadolinium oxide dominates product-type value pools due to its role as the precursor for all chelated contrast agents, while medical imaging commands the largest application share despite emerging competition from gadolinium-free MRI protocols. Magnetic refrigeration represents the fastest-growing application segment, though from a negligible base, as research institutions prototype solid-state cooling systems that exploit its giant magnetocaloric effect near room temperature.
The FDA maintains strict pharmacovigilance requirements for gadolinium-based contrast agents through boxed warnings on retention in renal-impaired patients, while the EPA monitors rare earth mining waste streams under the Resource Conservation and Recovery Act. China's MIIT enforces export licensing and environmental quotas on heavy rare earth separation that directly constrain gadolinium oxide availability. REACH registration obligations in Europe impose full toxicological dossier requirements on importers, elevating compliance costs for non-EU refiners. Stakeholders must monitor the trajectory of macrocyclic versus linear chelate formulations as regulatory risk stratification reshapes product liability and reimbursement positioning.
Market Dynamics
China's ion-adsorption clay belt processing restrictions and Japan's downstream separation chokepoints are tightening gadolinium oxide availability faster than diagnostic imaging protocols can adapt procurement cycles.
Growth Catalysts
- Contrast-enhanced MRI protocol expansion:Diagnostic imaging centers in Germany and South Korea are scaling T1-weighted sequences for neurological and oncological screening, multiplying vial throughput per scanner.
- MIIT environmental quotas:China's Ministry of Industry and Information Technology enforcement on heavy rare earth separation is forcing inventory builds among Japanese pharmaceutical formulators, sustaining spot demand premiums.
- Magnetic refrigeration prototyping:Research institutions in Switzerland and the Netherlands are validating solid-state cooling systems exploiting gadolinium's giant magnetocaloric effect near room temperature.
Market Restraints
- Feedstock concentration:Bastnäsite and monazite concentrate supply concentrates in China's Jiangxi and Fujian provinces, exposing separation facilities to export licensing volatility.
- Substitution pressure from gadolinium-free protocols:Ferumoxytol-enhanced MRI and synthetic contrast agents are capturing renal-impaired patient segments previously dependent on macrocyclic chelates.
- REACH registration burden:ECHA toxicological dossier requirements impose six-figure compliance costs on non-EU refiners seeking European pharmaceutical-grade market access.
Strategic Opportunities
- Malaysian separation corridor expansion:Mount Weld concentrate flows through Kuantan refining infrastructure offer Western supply security alternatives to Chinese clay belt dependence.
- Macrocyclic chelate regulatory tailwind:FDA boxed warning differentiation between linear and macrocyclic retention profiles is elevating formulation premiums for the latter category.
- Leasing model penetration in India:Asset-light contrast agent procurement is displacing capital-intensive vial purchasing among tier-two hospital networks in Maharashtra and Karnataka.
Industry Challenges
- Solvent extraction technician scarcity:Rare earth hydrometallurgy expertise concentrates in Chinese state-owned enterprises, constraining Western separation facility staffing.
- Pharmaceutical-grade ion exchange certification timelines:FDA validation protocols for injectable gadolinium oxide purity extend facility qualification periods beyond typical capital deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gadolinium Market |
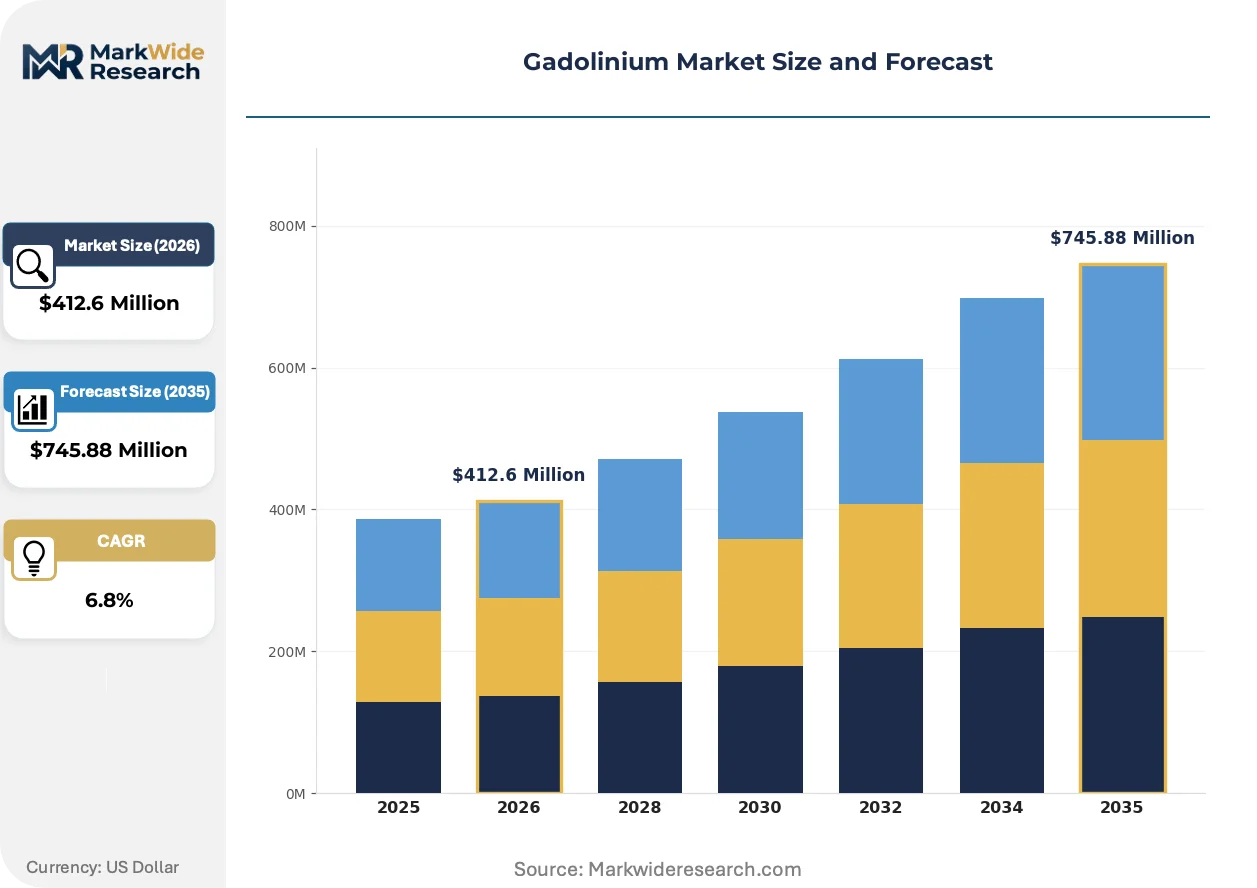
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gadolinium Oxide, Gadolinium Chloride, Gadolinium Sulfate, Gadolinium Nitrate Application: Medical Imaging, Neutron Capture Therapy, Nuclear Reactors, Magnetic Refrigeration End User: Hospitals, Diagnostic Centers, Research Institutions, Industrial Manufacturers Form: Powder, Solution, Pellet, Granule |
| Companies Covered | Bayer AG, GE Healthcare, Bracco Imaging, Guerbet, Lynas Rare Earths, Shin-Etsu Chemical, Lantheus Medical Imaging, MP Materials, Goodfellow Cambridge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gadolinium Market Emerging Trajectories
Formulation chemistry, regulatory risk stratification, and procurement model restructuring are compressing competitive timelines across the gadolinium value chain.
Macrocyclic chelate architecture is migrating from linear DTPA-based formulations to DOTA-derived structures with superior kinetic stability. Academic medical centers in the United States and university hospitals in France are accelerating this transition ahead of reimbursement policy adjustments. The shift is compressing liability exposure for contrast agent manufacturers while elevating raw material purity specifications for oxide precursors.
REACH authorization requirements under ECHA oversight are extending toxicological dossier obligations to gadolinium compound importers. European formulators are consolidating supplier qualification programs to reduce registration duplication costs. The regulation most directly affects mid-scale refiners in Southeast Asia seeking direct European market access without Malaysian or Japanese intermediate processing.
Consignment inventory arrangements are displacing traditional purchase-order procurement among German and Japanese hospital networks. Imaging equipment vendors are bundling contrast supply contracts with MRI system leases, locking multi-year procurement cycles. This restructuring is most visible in North Rhine-Westphalia and Tokyo metropolitan clusters where equipment refresh cycles coincide with contrast agent contract renegotiations.
Gadolinium Market Segmentation
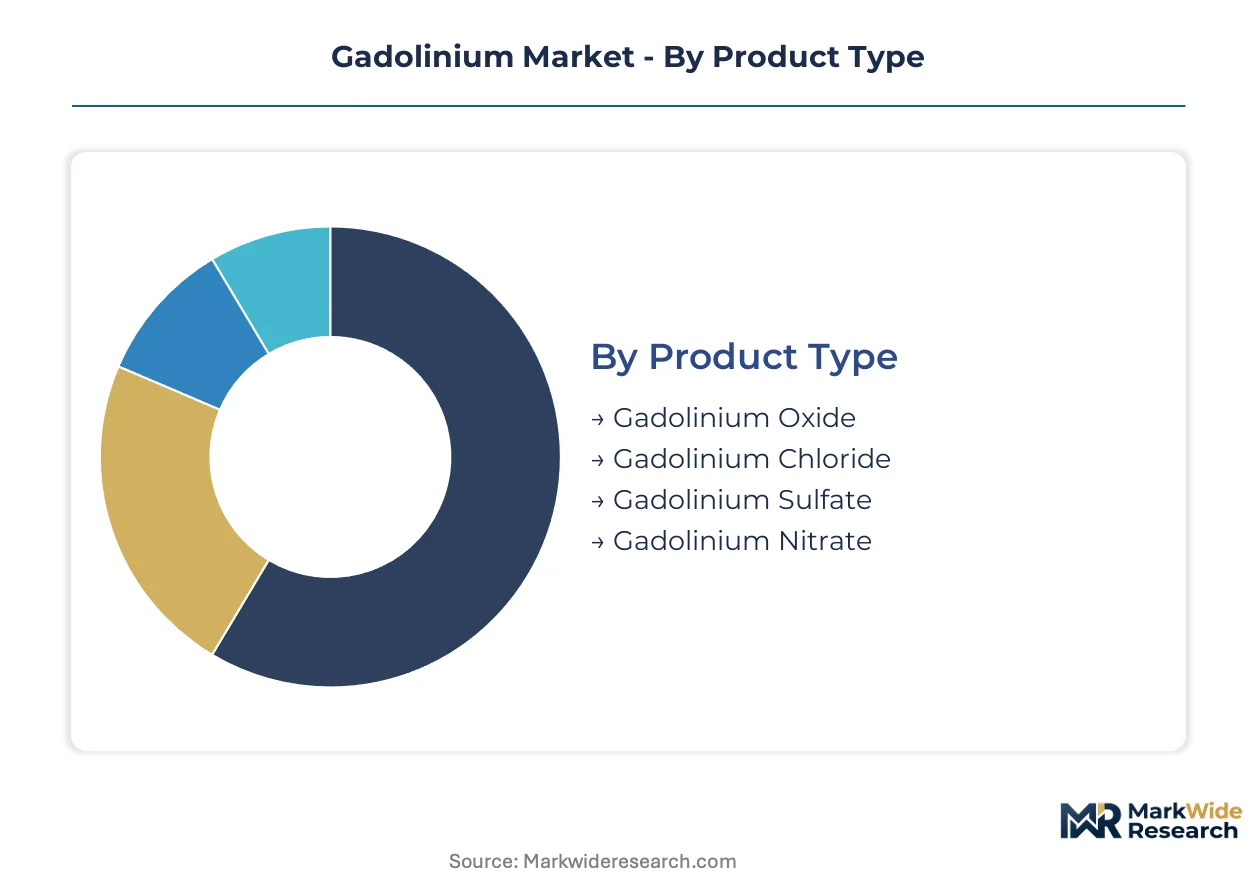
Gadolinium procurement patterns diverge sharply across chemical forms, clinical applications, and end-user sophistication tiers. Formulation requirements and regulatory compliance burdens reshape competitive positioning within each segment boundary.
Product Type:
Cost tiers separate pharmaceutical-grade oxides from industrial-grade salts, with purity specifications determining market access and margin capture.
- Gadolinium Oxide:Serves as the universal precursor for all chelated contrast agents, requiring ion exchange purification to meet FDA injectable specifications. Demand concentrates in Japanese and European pharmaceutical formulators facing REACH registration burdens.
- Gadolinium Chloride:Intermediate feedstock for laboratory-scale chelation research and specialized ceramic doping applications. German and Swiss research institutions drive spot demand for high-purity chloride precursors in neutron scattering experiments.
- Gadolinium Sulfate:Water treatment and glass manufacturing applications in China's Fujian province absorb volume in industrial-grade specifications.
- Gadolinium Nitrate:Nuclear reactor control rod fabrication and specialized pyrotechnic formulations in South Korea.
Established volume favors Gadolinium Oxide; emerging adoption favors Gadolinium Nitrate.
Application:
Application maturity spans decades-old clinical protocols to experimental solid-state cooling systems with divergent regulatory pathways.
- Medical Imaging:Contrast-enhanced MRI protocols consume the majority of pharmaceutical-grade oxide output, with macrocyclic chelate formulations displacing linear DTPA structures in US and French hospital networks.
- Magnetic Refrigeration:Research institutions in Switzerland and the Netherlands prototype solid-state cooling systems exploiting the giant magnetocaloric effect near room temperature.
- Neutron Capture Therapy:Boron neutron capture therapy adjunct applications in Japanese and Taiwanese oncology centers.
- Nuclear Reactors:Control rod and burnable poison applications in South Korean and French pressurized water reactor fleets.
Medical Imaging commands dominant revenue share; Magnetic Refrigeration exhibits the steepest expansion trajectory.
End User:
Customer sophistication tiers separate capital-intensive hospital networks from asset-light diagnostic operators and research grant-funded institutions.
- Hospitals:Integrated health systems in Germany's North Rhine-Westphalia and Tokyo metropolitan clusters bundle contrast procurement with MRI equipment leases, locking multi-year supply contracts.
- Diagnostic Centers:India's tier-two networks in Maharashtra and Karnataka adopt consignment inventory models, displacing traditional vial purchasing.
- Research Institutions:Academic medical centers in the United States and university hospitals in France accelerate macrocyclic chelate transitions ahead of reimbursement adjustments.
- Industrial Manufacturers:Ceramic, glass, and electronics producers in China's Jiangxi province absorb non-pharmaceutical grade output.
Hospitals anchor procurement volume; Diagnostic Centers drive model innovation fastest.
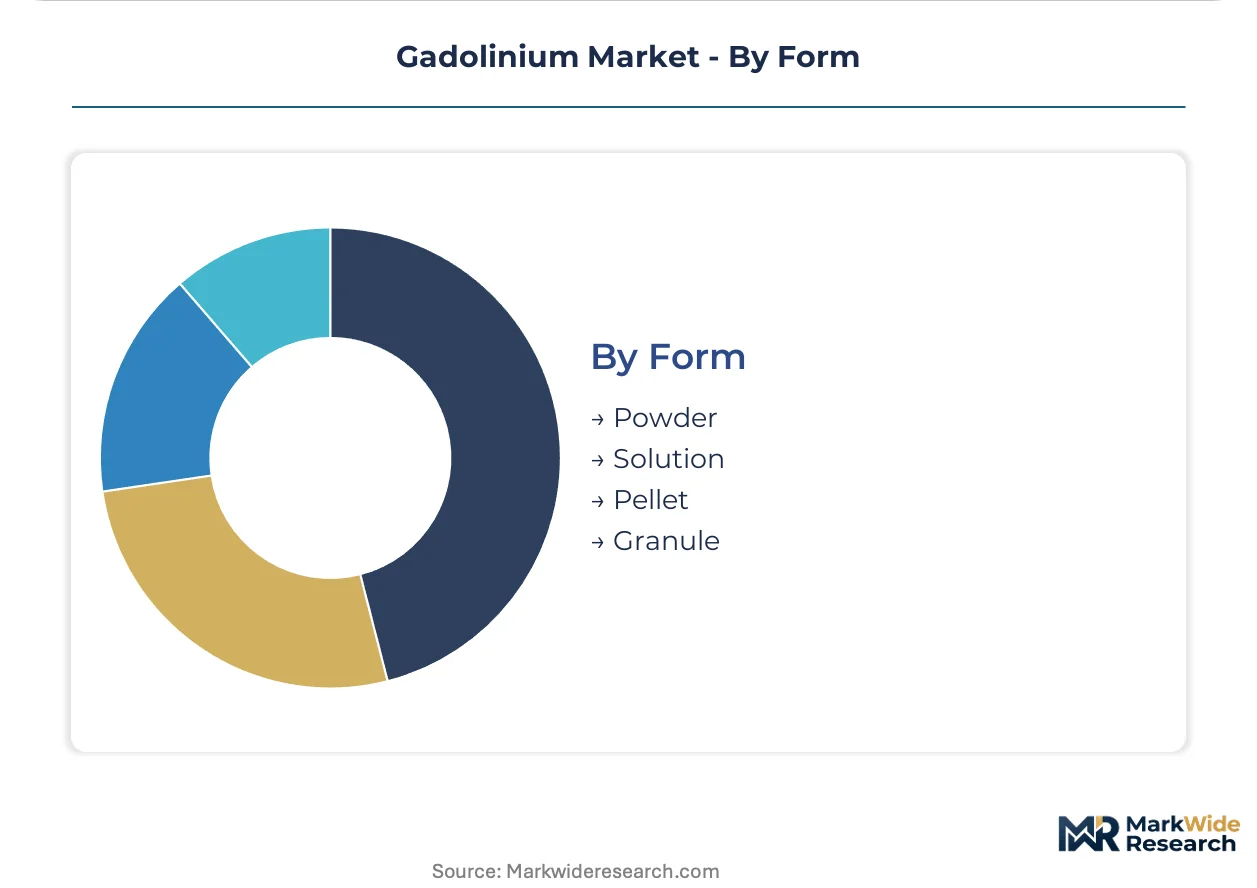
Form:
Physical form selection aligns with downstream processing economics and regulatory handling requirements across the value chain.
- Powder:Standard precursor form for oxide and salt production, requiring controlled atmosphere handling in pharmaceutical-grade facilities.
- Solution:Pre-dissolved formats reduce formulator processing steps in high-throughput diagnostic environments.
- Pellet:Nuclear reactor control rod fabrication favors pressed pellet geometries for precise neutron absorption profiling.
- Granule:Intermediate form for ceramic and glass manufacturing in industrial applications.
Powder dominates upstream supply; Solution formats gain share in formulator efficiency programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are redrawing gadolinium oxide flows as Chinese processing restrictions collide with pharmaceutical formulator inventory builds in Japan and Europe. The analysis tracks five countries where diagnostic imaging demand, rare earth policy, and refining infrastructure intersect.
China
Jiangxi and Fujian provinces host the ion-adsorption clay belt that supplies the majority of global gadolinium concentrate. MIIT environmental quotas on heavy rare earth separation are constraining oxide availability and forcing Japanese pharmaceutical formulators to accelerate inventory builds. The Ganzhou rare earth industrial cluster faces tightening wastewater discharge standards under MEE enforcement.
Japan
Downstream separation facilities in Kanto and Kansai regions process Chinese concentrate into pharmaceutical-grade oxide for domestic MRI contrast manufacturers. METI industrial security policies are incentivizing strategic stockpiling of separated rare earths. The Tokyo metropolitan cluster anchors formulation capacity for macrocyclic chelate production.
Germany
North Rhine-Westphalia hospital networks are bundling contrast procurement with MRI equipment leases, locking multi-year supply contracts. ECHA REACH registration obligations impose full toxicological dossier requirements on gadolinium compound importers. The Bavarian research corridor hosts neutron scattering facilities driving spot demand for high-purity chloride precursors.
United States
FDA pharmacovigilance requirements through boxed warnings on gadolinium retention are accelerating macrocyclic chelate transitions at academic medical centers. The Department of Energy is monitoring rare earth supply chain vulnerabilities under defense production authorities. California and Massachusetts research institutions are prototyping magnetic refrigeration systems exploiting the giant magnetocaloric effect.
South Korea
Pressurized water reactor fleets in Gyeonggi and Busan regions absorb gadolinium nitrate for control rod fabrication. MFDS pharmaceutical regulations are aligning with FDA guidance on contrast agent safety profiles. The Seoul Capital Area diagnostic imaging market is scaling T1-weighted MRI protocols for oncological screening.
Gadolinium Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in rare earth separation and oxide refining. The vendor base organizes around three strata: pharmaceutical formulators with captive distribution, rare earth miners with integrated separation assets, and research-grade chemical suppliers serving niche applications. Two strategic archetypes dominate—vertically integrated rare earth processors and imaging equipment vendors with contrast bundling capabilities. Competitive moves concentrate on Malaysian separation corridor expansion and macrocyclic chelate formulation differentiation.
Among pharmaceutical formulators, Bayer AG and GE Healthcare exemplify platform integrators leveraging hospital network relationships, while Lynas Rare Earths anchors the upstream separation tier through Australian concentrate and Malaysian refining infrastructure. These three occupy positions across the value chain that reflect divergent margin capture strategies—captive distribution versus feedstock security versus equipment-contrast bundling.
| Leading Market Players |
|---|
| Bayer AG |
| GE Healthcare |
| Bracco Imaging |
| Guerbet |
| Lynas Rare Earths |
| Shin-Etsu Chemical |
| Lantheus Medical Imaging |
| MP Materials |
| Goodfellow Cambridge |
| Others |
Supply Flow & Price Mechanics
China's ion-adsorption clay belt concentration in Jiangxi and Fujian provinces funnels margin capture toward Japanese pharmaceutical formulators and German hospital networks with locked procurement cycles. The downstream separation chokepoints in Kanto and Kansai regions amplify pricing power for pharmaceutical-grade oxide precursors while industrial-grade salts compete on spot-market volatility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for nuclear reactor control rod fabricators in South Korea, while diagnostic imaging centers in Germany and Japan operate on consignment inventory arrangements bundled with MRI equipment leases. Price differentiation rests on pharmaceutical-grade ion exchange certification versus industrial-grade purity specifications, with FDA-validated oxide commanding substantial premiums over ceramic doping grades. Cost compression in industrial sulfate and nitrate tiers is intensifying because Chinese environmental quotas are constraining feedstock availability. Hospital networks with integrated equipment-contrast bundling exhibit the least price sensitivity, whereas India's tier-two diagnostic centers in Maharashtra and Karnataka demonstrate acute responsiveness to per-vial economics.
Supply Chain Analysis
Rare earth hydrometallurgy specialists in Chinese state-owned enterprises hold captive solvent extraction capacity, constraining Western separation facility expansion. Geographic supply concentration centers on China's Jiangxi province for ion-adsorption clay concentrate, Malaysia's Kuantan corridor for Mount Weld-derived oxide, and Japan's Kanto region for downstream pharmaceutical-grade refining. Raw material dependencies draw from bastnäsite and monazite concentrates, specialized ion exchange resins, and high-purity acid reagents. Single-source vulnerability pervades the heavy rare earth separation tier where MIIT licensing restricts export flows. Distribution runs through pharmaceutical formulators with captive hospital network contracts, research-grade chemical suppliers serving neutron scattering facilities, and industrial ceramic producers in Fujian province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic refrigeration commercialization represents a high-growth disruption as solid-state cooling prototypes exploit gadolinium's giant magnetocaloric effect near room temperature. FDA pharmacovigilance requirements on gadolinium retention are simultaneously accelerating macrocyclic chelate transitions and compressing competitive timelines for formulation differentiation.
For Market Incumbents: Pre-empt substitution pressure from ferumoxytol-enhanced MRI and synthetic contrast agents by accelerating macrocyclic DOTA-derived formulation transitions ahead of reimbursement policy adjustments. Deepen backward integration into Malaysian separation infrastructure to reduce dependence on Chinese clay belt export licensing volatility. Channel control through asset-light leasing models in India's tier-two hospital networks locks procurement cycles against spot-market competitors.
For New Entrants and Emerging Players: Build out research-grade chloride and nitrate supply capabilities for neutron scattering facilities in Switzerland and the Netherlands, where academic demand outstrips specialized chemical supplier capacity. The magnetic refrigeration prototyping segment offers the most penetrable white-space target, with solid-state cooling system developers seeking validated gadolinium alloy sources. A go-to-market angle anchored in giant magnetocaloric effect material certification bypasses entrenched pharmaceutical formulator competition.
For Investors and Strategic Acquirers: Capital is best deployed toward Western-aligned rare earth separation assets with pharmaceutical-grade ion exchange certification and Malaysian or Australian geographic positioning. Long-term viability hinges on supply security premiums as Chinese environmental quotas tighten and Japanese strategic stockpiling sustains demand. The signal to watch is MIIT export licensing velocity for heavy rare earth oxides, which directly constrains Japanese pharmaceutical formulator inventory economics and spot-market premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Malaysian Separation Corridor Expansion | Mount Weld concentrate flows through Kuantan refining reduce Chinese clay belt dependence for Western pharmaceutical formulators. |
| Macrocyclic Chelate Formulation Transition | DOTA-derived structures with superior kinetic stability capture FDA boxed warning differentiation premiums in US hospital networks. |
| Magnetic Refrigeration Material Certification | Giant magnetocaloric effect alloy validation opens research institution procurement channels in Switzerland and the Netherlands. |
| Asset-Light Leasing Model Penetration | Consignment inventory arrangements displace capital-intensive vial purchasing among India's tier-two diagnostic networks. |
| Strategic Rare Earth Stockpiling | METI industrial security policies in Japan sustain inventory builds that amplify spot demand premiums for separated oxides. |
Methodological Framework
Initial hypotheses were tested against primary input from pharmaceutical formulators, rare earth separation facility managers, hospital procurement committees, and diagnostic imaging center operators and refined through secondary validation against customs trade data, SEC filings from listed rare earth miners, FDA pharmacovigilance databases, and ECHA REACH registration records. Bottom-up modeling of vial throughput per MRI scanner across German and South Korean diagnostic networks was triangulated with top-down oxide demand estimates derived from Japanese pharmaceutical formulator inventory disclosures.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation across chemical form, application maturity, and end-user sophistication tier, with specific incorporation of pharmaceutical-grade versus industrial-grade purity specifications and macrocyclic versus linear chelate formulation transitions. CAGRs were derived from iterative reconciliation of scanner installation rates, protocol expansion assumptions, and rare earth separation capacity constraints. Industry-specific forecast inputs included MIIT environmental quota enforcement timelines and magnetic refrigeration prototype development milestones.
Stress conditions across Chinese export licensing volatility, FDA pharmacovigilance escalation, and magnetic refrigeration commercialization acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of MIIT heavy rare earth separation quotas, EMA macrocyclic chelate reimbursement positioning, and Swiss magnetic refrigeration prototype validation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Magnet Wire Market
Magnetic Materials
Samarium Cobalt Magnets Market
Magnetic Materials
Global Bonded Magnet Market
Magnetic Materials
Superconducting Magnets Market
Magnetic Materials
Ferromanganese Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
Japan Neodymium Iron Boron Magnet Market
Magnetic Materials
Neodymium-Iron-Boron Magnet Market
Magnetic Materials
Cobalt Oxide Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Nanocrystalline Soft Magnetic Material Market
Magnetic Materials
Ferroboron Market
Magnetic Materials
North America Ferrite Magnet Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Magnet Buffer Market