
 Iron Oxide Market | 2026-2036
Iron Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Iron Oxide Market Outlook
Project finance for synthetic iron oxide facilities is tilting competitive dynamics toward asset-light operators with off-take agreements. LANXESS AG leverages its backward integration into nitrobenzene intermediates to sustain margin stability across pigment cycles. BASF SE anchors European supply through dedicated production complexes in Ludwigshafen. Cathay Industries dominates Asian volume with manufacturing positions in mainland China.
Iron oxide comprises synthetic and naturally occurring ferric oxide compounds (Fe₂O₃, Fe₃O₄, FeO(OH)) valued for tinting strength, UV stability, and chemical inertness, produced via precipitation, calcination, or Penniman processes primarily for coloring construction materials, coatings, and plastics. Red iron oxide leads construction applications due to superior alkali resistance in cement matrices. Cosmetic grade commands premium positioning as formulation purity requirements tighten under FDA and EU frameworks. Industrial grade occupies volume leadership across coatings and plastics segments where cost efficiency governs procurement.
EPA oversight under the Toxic Substances Control Act shapes synthetic pigment manufacturing standards in the United States, while REACH registration mandates in Europe constrain raw material sourcing and impurity thresholds. China's Ministry of Ecology and Environment enforces dual carbon goals that tighten energy intensity benchmarks for calcination-based production. Stakeholders must monitor regulatory divergence between jurisdictions to align certification investments with destination market requirements.
Market Dynamics
Calcination energy intensity regulations are forcing producers to reconfigure thermal processing routes, splitting capital allocation between retrofitting legacy assets and greenfield precipitation plants in lower-carbon jurisdictions.
Growth Catalysts
- Construction-grade pigment demand:Colored concrete specifications for infrastructure resilience are expanding procurement volumes from highway and municipal building agencies across India and Germany.
- REACH purity thresholds:Tightened impurity benchmarks for heavy metals are accelerating qualification of synthetic grades over natural ores in European architectural coatings.
- Dual carbon compliance:China's Ministry of Ecology and Environment enforcement is concentrating calcination capacity among producers with captive renewable energy or carbon capture integration.
Market Restraints
- Nitrobenzene feedstock volatility:Synthetic pigment economics remain tethered to benzene derivative pricing, compressing margins during upstream petrochemical cycles.
- Natural ore substitution ceiling:High-iron-content specular hematite deposits in select geographies limit synthetic grade pricing power in cost-sensitive industrial coatings.
- EPA TSCA notification burdens:New chemical substance reviews for modified pigment surface treatments extend commercialization timelines by 18-24 months for US-focused formulations.
Strategic Opportunities
- Cosmetic-grade certification gap:FDA and EU cosmetic pigment purity standards are creating entry barriers that favor producers with dedicated GMP-compliant production lines.
- Coatings distribution disintermediation:Direct procurement platforms are compressing distributor margins and enabling pigment suppliers to capture formulation advisory value.
- Magnetic iron oxide convergence:Ferrite precursor applications in electric motor laminations are opening parallel demand channels beyond traditional colorant markets.
Industry Challenges
- Process engineer scarcity:Precipitation chemistry expertise is concentrating at legacy production clusters, constrating talent availability for new facility commissioning.
- Multi-jurisdiction certification timelines:Parallel REACH, TSCA, and GB standard registrations are fragmenting product development resources and delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iron Oxide Market |
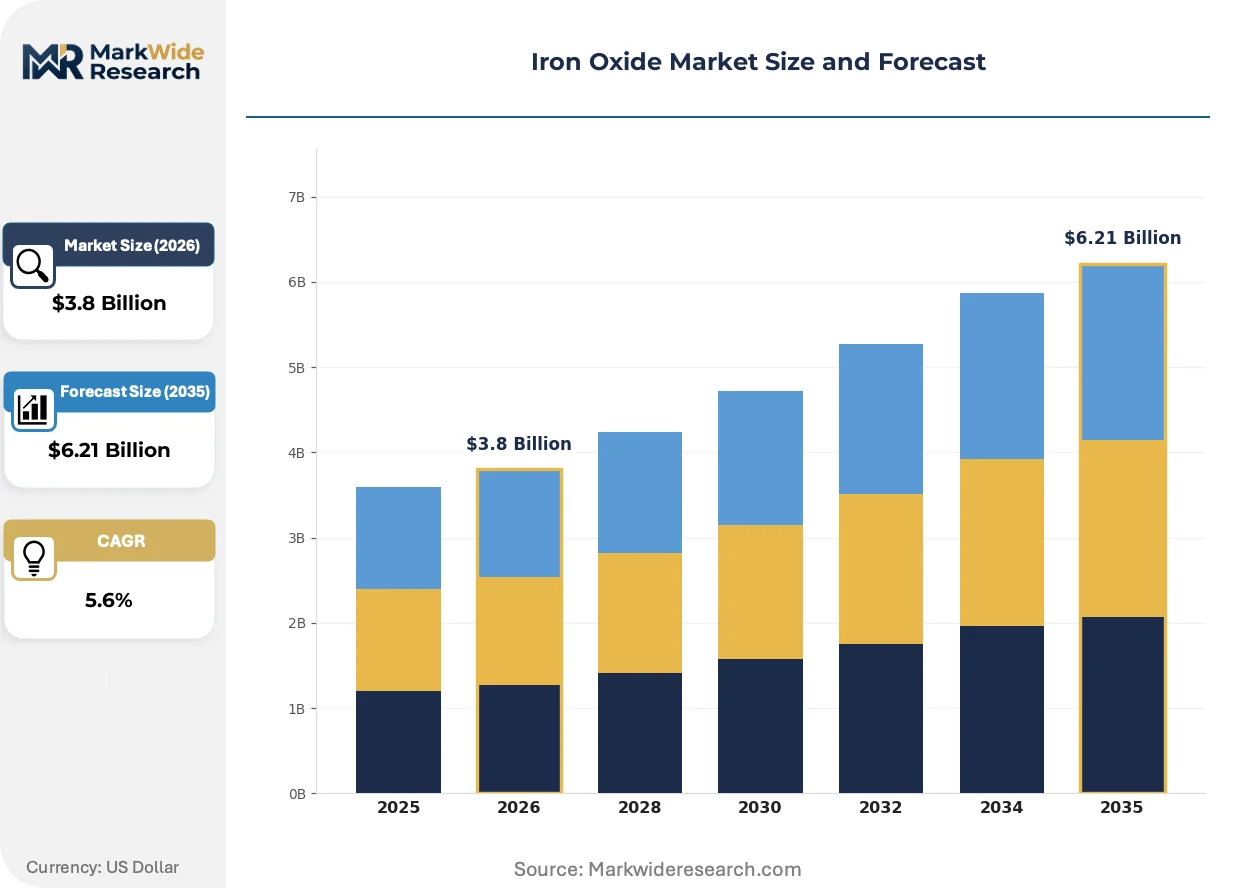
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Iron Oxide, Yellow Iron Oxide, Black Iron Oxide, Brown Iron Oxide Grade: Industrial Grade, Cosmetic Grade, Food Grade, Pharmaceutical Grade Application: Coatings, Plastics, Construction, Paper End User: Aerospace, Automotive, Electronics, Textiles |
| Companies Covered | Clariant AG, Cathay Industries, LANXESS AG, Tata Pigments Limited, Heubach GmbH, BASF SE, Huntsman International LLC, Sudarshan Chemical Industries Limited, Venator Materials PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iron Oxide Market Strategic Shifts
Process chemistry and regulatory compliance are converging to reshape how pigment producers configure manufacturing assets and qualify products for destination markets.
Precipitation-based synthetic production is migrating from batch tank operations toward continuous flow reactor systems. Coating formulators in automotive and industrial segments are qualifying these grades for improved batch-to-batch consistency. The technology shift is compressing working capital cycles and enabling just-in-time pigment delivery contracts that displace traditional bulk inventory models.
EU F-Gas Regulation phase-down schedules are indirectly pressuring thermal processing economics by raising energy cost baselines for calcination-dependent producers. Pigment manufacturers with Ludwigshafen and Antwerp cluster positions are accelerating heat recovery investments to maintain cost parity. The regulatory pressure is most acute for red iron oxide grades where calcination remains technically necessary for hue stability.
Specification-driven procurement is consolidating buyer power among multinational coatings and construction material firms. Tier-one suppliers are responding with embedded technical service teams that co-develop formulations rather than transact commodity volumes. This behavioral shift is most visible in German and US markets where architectural specification chains concentrate purchasing decisions among fewer technical decision-makers.
Iron Oxide Market Segmentation
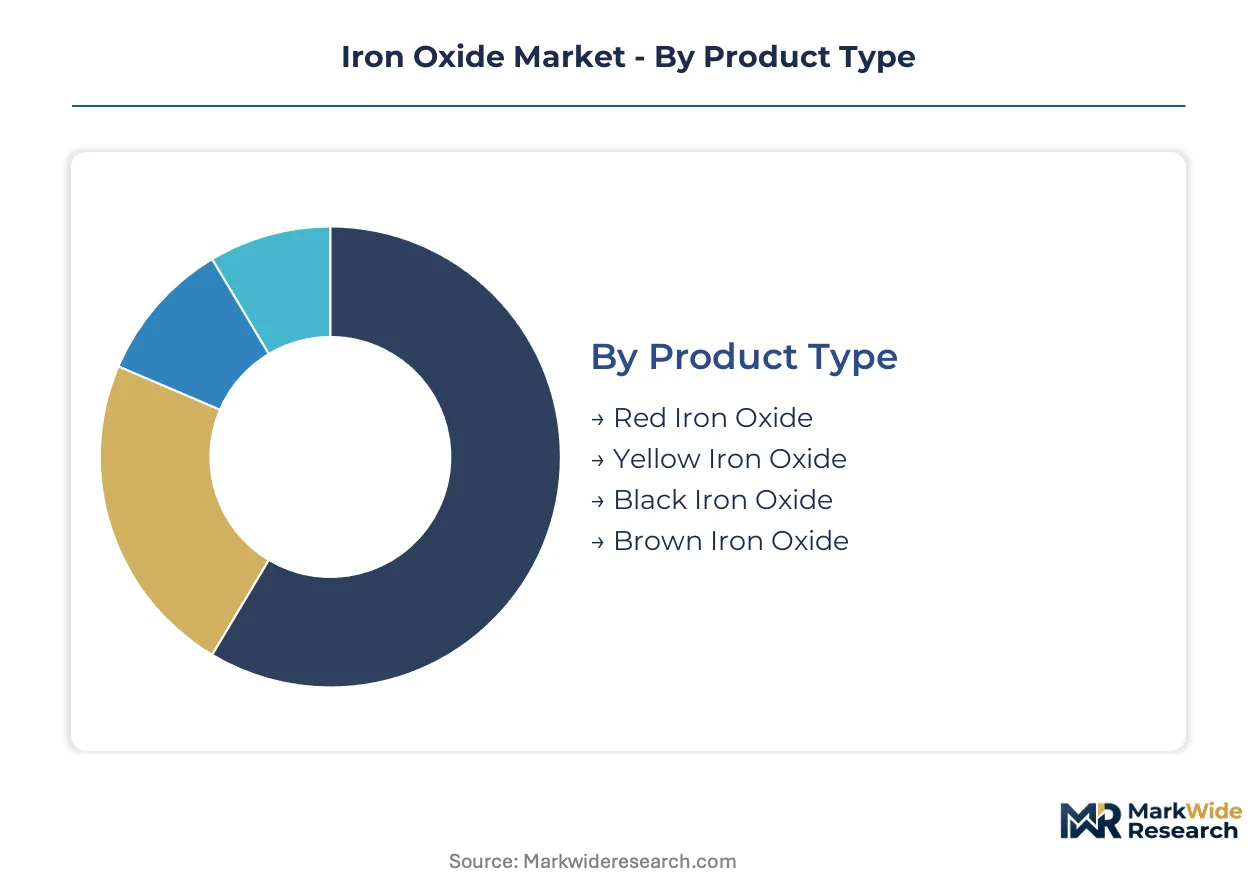
Iron oxide market segmentation reflects divergent purity requirements and thermal processing economics across colorant applications. Procurement patterns split between specification-driven architectural coatings and volume-driven construction materials, with regulatory thresholds determining grade premiums.
Product Type:
Use-case spectrum spans construction tinting, corrosion protection, and specialty magnetics, with hue stability and alkali resistance governing grade selection.
- Red Iron Oxide:Predominantly alpha-Fe₂O₃ produced via calcination or Penniman processes, delivering superior alkali resistance in cement matrices. Demand concentrates in German and Indian highway infrastructure specifications where colorfastness under UV exposure is mandatory.
- Yellow Iron Oxide:Goethite-based FeO(OH) requiring controlled precipitation chemistry for consistent particle size distribution. Coatings formulators in automotive refinish segments are qualifying synthetic grades to replace natural ore variability.
- Black Iron Oxide:Fe₃O₄ magnetite grades serving both colorant and ferrite precursor applications.
- Brown Iron Oxide:Blended or co-precipitated grades targeting wood stain and furniture coating segments.
The dominant share belongs to Red Iron Oxide, while Black Iron Oxide is closing the gap fastest on magnetic material demand.
Grade:
Cost tiers separate commodity volume from certified purity, with regulatory compliance investments determining facility configuration and margin capture.
- Industrial Grade:Standard synthetic pigments for coatings and plastics where heavy metal thresholds align with REACH industrial use exemptions. Procurement volumes from multinational construction material firms dominate, with price sensitivity governing supplier selection.
- Cosmetic Grade:GMP-compliant production with FDA and EU cosmetic pigment purity certification. Formulation houses in France and Germany are consolidating supplier lists to pre-qualified producers with dedicated cosmetic lines.
- Food Grade:E172 additive compliance with EFSA purity benchmarks for confectionery and supplement applications.
- Pharmaceutical Grade:USP-NF and EP monograph adherence for tablet coloring and excipient use.
Industrial Grade commands volume leadership, though Cosmetic Grade exhibits the steepest expansion trajectory on premium personal care positioning.
Application:
Customer type differentiation separates specification-driven architectural procurement from cost-optimized industrial volume buying.
- Coatings:Automotive OEM, refinish, and industrial protective segments demanding batch-to-batch consistency. Direct procurement platforms are compressing distributor roles as formulators seek embedded technical service.
- Construction:Colored concrete for infrastructure resilience, with municipal agencies in India and Germany expanding pigment volumes for highway and public building specifications.
- Plastics:Masterbatch integration requiring thermal stability during polymer processing.
- Paper:Specialty printing and packaging applications with moderate volume contribution.
Construction anchors volume demand, while Coatings is gaining share fastest on specification consolidation among fewer technical decision-makers.
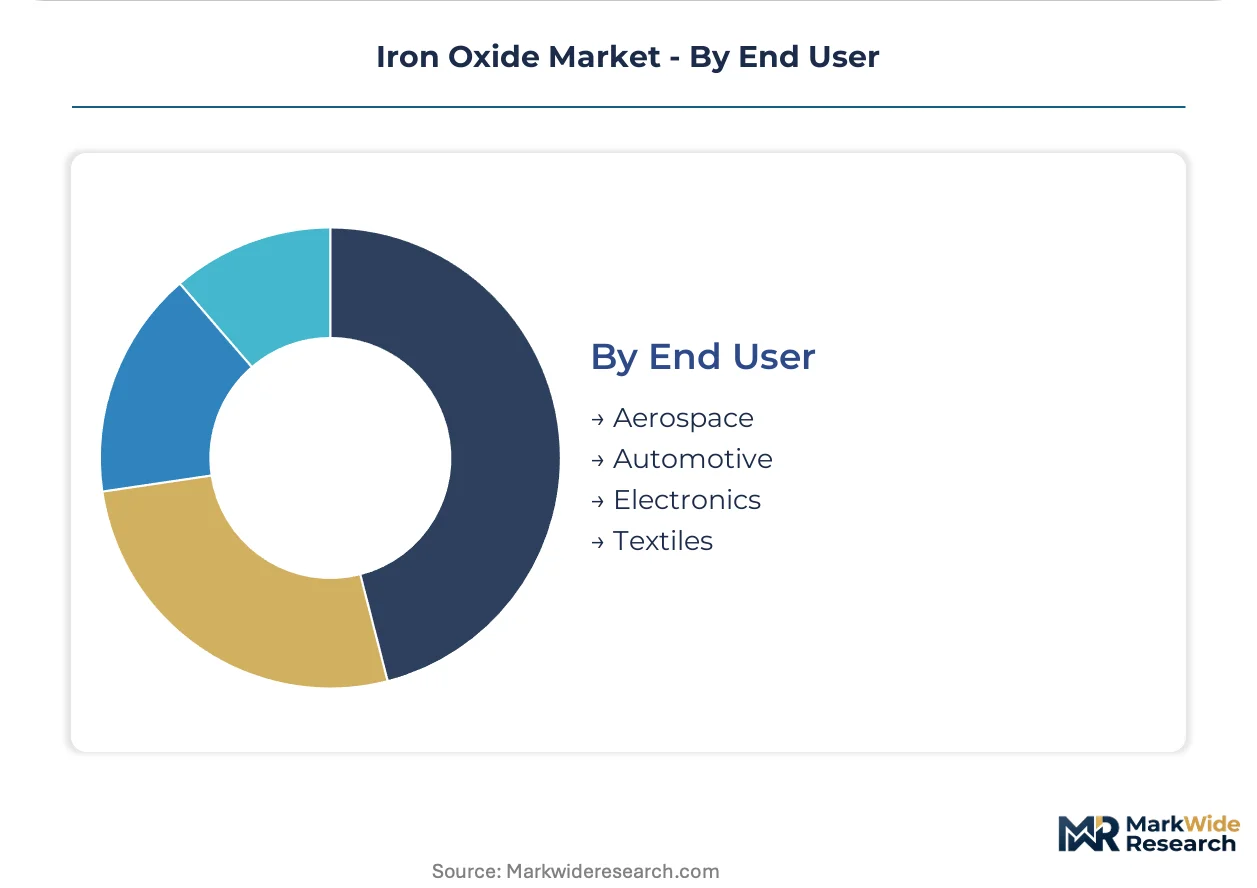
End User:
Supply concentration varies by sector maturity, with aerospace and electronics demanding certified supply chains distinct from automotive commodity procurement.
- Automotive:OEM and refinish coatings specifying synthetic grades for color matching consistency. Tier-one suppliers with Ludwigshafen and Antwerp cluster positions are embedding technical teams for co-development relationships.
- Electronics:Ferrite precursors for electric motor laminations and magnetic tape applications. China's dual carbon enforcement is concentrating calcination capacity among producers with captive renewable energy.
- Aerospace:Mil-spec coatings with extended qualification timelines and limited supplier pools.
- Textiles:Dyeing and printing applications with declining synthetic pigment share on alternative chemistry substitution.
Automotive retains the largest end-user position, while Electronics is expanding most quickly on magnetic iron oxide convergence beyond traditional colorant markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are redirecting capital flows toward regional manufacturing hubs as freight costs and carbon border adjustments reshape procurement geography. Major consuming markets are reconfiguring supply relationships to reduce transit exposure and align with local regulatory regimes.
China
Dual carbon enforcement from the Ministry of Ecology and Environment is consolidating calcination capacity among producers with captive renewable energy or carbon capture integration. GB standards for industrial pigment purity are tightening faster than REACH alignment timelines, forcing export-oriented facilities to maintain parallel certification tracks. The Yangtze River Delta concentration around Shanghai anchors both precipitation chemistry expertise and ferrite precursor supply for electronics applications.
Germany
REACH registration mandates and F-Gas Regulation phase-down schedules are raising thermal processing cost baselines for calcination-dependent red iron oxide grades. The Ludwigshafen chemical cluster sustains backward-integrated nitrobenzene-to-pigment production chains that buffer margin volatility. Specification-driven procurement from municipal building agencies is expanding volumes for highway infrastructure colorfastness requirements.
United States
EPA Toxic Substances Control Act notification burdens for modified pigment surface treatments are extending commercialization timelines by 18-24 months for domestic-focused formulations. The Gulf Coast petrochemical corridor supplies benzene derivative feedstocks for synthetic pigment economics. Construction-grade demand from federal infrastructure programs is expanding procurement volumes for colored concrete resilience specifications.
India
Bureau of Indian Standards certification requirements for construction materials are accelerating synthetic grade qualification over natural ore variability. The Gujarat chemical belt is attracting precipitation-based greenfield investments to serve both domestic coatings demand and Middle East export markets. Municipal building agencies in Maharashtra and Karnataka are expanding pigment volumes for public building color specifications.
Japan
METI energy intensity benchmarks are pressuring legacy calcination assets toward heat recovery retrofits or precipitation technology migration. JIS standards for automotive coatings are consolidating supplier lists to pre-qualified producers with batch-to-batch consistency protocols. The Kansai industrial corridor around Osaka maintains ferrite precursor supply relationships with electric motor laminations manufacturers.
Iron Oxide Market Competitive Environment
On the supply side, the industry is consolidating around backward-integrated chemical conglomerates and specialized pigment houses with dedicated production assets. Three archetypes dominate: diversified chemical majors with nitrobenzene integration, standalone pigment specialists with precipitation chemistry expertise, and natural ore processors pivoting toward synthetic grade qualification. Competitive moves center on heat recovery investments for calcination assets and direct procurement platform development to capture formulation advisory value.
Within the diversified chemical tier, LANXESS AG and BASF SE exemplify the backward-integrated model that sustains margin stability across pigment cycles. Cathay Industries occupies a position as the volume anchor for Asian precipitation capacity. Among European specialists, Heubach GmbH and Clariant AG represent the technical service-intensive archetype that co-develops formulations with specification-driven buyers rather than transacting commodity volumes.
| Leading Market Players |
|---|
| Clariant AG |
| Cathay Industries |
| LANXESS AG |
| Tata Pigments Limited |
| Heubach GmbH |
| BASF SE |
| Huntsman International LLC |
| Sudarshan Chemical Industries Limited |
| Venator Materials PLC |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta concentration around Shanghai anchors global precipitation capacity, concentrating pricing power among producers with captive nitrobenzene integration while forcing asset-light operators toward toll manufacturing arrangements. This geographic clustering creates divergent margin structures between backward-integrated majors and specialized pigment houses.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across cosmetic, industrial, and construction tiers based on certification grade and volume scale. Cost compression in industrial grades intensifies as natural ore substitution limits synthetic pricing power, while cosmetic-grade buyers exhibit lowest price sensitivity due to FDA and EU purity mandates.
Supply Chain Analysis
Cathay Industries, LANXESS AG, and BASF SE hold concentrated synthetic capacity across China, Germany, and the United States. Production draws from benzene derivative feedstocks, iron scrap, and energy-intensive calcination inputs, with single-source vulnerability in nitrobenzene supply creating margin volatility. Distribution runs through direct procurement platforms and embedded technical service relationships with multinational coatings formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized precipitation chemistry expertise has become the binding constraint for facility commissioning, with legacy production clusters hoarding process engineers and forcing capital deployment toward talent acquisition rather than equipment alone.
For Market Incumbents: Build certification moats around dedicated GMP-compliant cosmetic lines to defend against natural ore processors pivoting toward synthetic qualification. Anchor backward integration into nitrobenzene intermediates to buffer petrochemical cycle volatility. Prioritize heat recovery investments at Ludwigshafen and Antwerp cluster positions to maintain cost parity under EU F-Gas Regulation pressure. For New Entrants and Emerging Players: India's Gujarat chemical belt offers underpenetrated precipitation capacity with Bureau of Indian Standards certification requirements accelerating synthetic grade adoption over natural ore variability. Target municipal building agencies in Maharashtra and Karnataka expanding public building color specifications. Enter through direct procurement platforms that capture formulation advisory value currently held by distributors. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because parallel REACH, TSCA, and GB standard registrations fragment product development resources and delay market entry for non-compliant operators. Acquire standalone pigment specialists with precipitation chemistry expertise and existing multi-jurisdiction certifications. Monitor EPA TSCA notification timeline extensions as inflection indicator for US-focused formulation commercialization delays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrobenzene | LANXESS AG sustains margin stability across pigment cycles through captive intermediate supply. |
| Heat Recovery Retrofit Investment | Ludwigshafen cluster producers maintain calcination cost parity under tightening EU F-Gas Regulation. |
| GMP-Compliant Cosmetic Line Certification | FDA and EU purity standards create entry barriers favoring dedicated production asset operators. |
| Direct Procurement Platform Development | Pigment suppliers capture formulation advisory value from compressed distributor margins in coatings. |
| Continuous Flow Reactor Migration | Precipitation-based synthetic production enables just-in-time delivery contracts displacing bulk inventory models. |
Study Parameters
The analysis maps synthetic precipitation, calcination, and natural ore processing sub-sectors, each validated through plant managers, procurement leads at downstream coatings OEMs, distribution channel partners, and technical R&D directors. Primary interview data triangulates against customs and trade records, ACC and Cefic industry reports, SEC 10-K filings, and regulatory registration databases. Bottom-up facility capacity assessments reconcile with top-down end-use demand modeling across construction, coatings, and plastics segments.
Assumptions hold regulatory enforcement timelines and dual carbon compliance trajectories within observed patterns while varying feedstock cost scenarios and substitution elasticity parameters. Segmentation dimensions include product type, grade tier, application, and regional production hub. CAGRs derive from installed capacity utilization trends, specification-driven procurement consolidation patterns, and magnetic iron oxide convergence beyond traditional colorant markets.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by state-backed Chinese producers or accelerated natural ore qualification in cost-sensitive industrial coatings would shift outcomes. Quarterly review of EPA TSCA notification timelines, REACH registration renewal schedules, and Ministry of Ecology and Environment enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Cobalt Oxide Market
Magnetic Materials
Neodymium-Iron-Boron Magnet Market
Magnetic Materials
Japan Neodymium Iron Boron Magnet Market
Magnetic Materials
High Purity Carbonyl Iron Powder (CIP) Market
Magnetic Materials
Europe Ferrite Magnet Market
Magnetic Materials
Global Bonded Magnet Market
Magnetic Materials
Rare Earth Magnet Market
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
Global Non-Oriented Electrical Steel Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Ferroboron Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
Reduced Iron Powder Market
Magnetic Materials
Magnet Market
Magnetic Materials
Carbonyl Iron Powder Market
Magnetic Materials
Global Permanent Magnet Market