
 Global Magnetic Beads Market | 2026-2036
Global Magnetic Beads Market Size, Share, and Industry Trends Forecast 2026-2036
Global Magnetic Beads Market Foresight
Modular kit configurations is broadening buyer choice in the magnetic beads space as vendors unbundle reagents from instruments and offer application-specific formulations. Thermo Fisher Scientific leverages its deep catalog of surface chemistries to sustain pull-through in proteomics workflows. Merck KGaA anchors European supply through GMP-grade bead production for cell therapy manufacturing. Bio-Rad Laboratories differentiates with instrument-agnostic bead chemistries that compete across multiple automation platforms.
Magnetic beads are spherical particles, typically 0.5–5 micrometers in diameter, composed of iron oxide cores encased in polymer shells and functionalized with silanol, carboxyl, or streptavidin surface groups for biomolecule capture. Superparamagnetic behavior enables rapid separation under applied magnetic fields without residual magnetization, supporting automated washing and elution in diagnostic and research workflows. The cell separation and nucleic acid isolation applications dominate current volume, while protein purification commands higher per-unit margins due to customized affinity ligand requirements. Surface functionalization technology leads R&D investment as vendors develop mixed-mode chemistries that reduce protocol steps and improve binding specificity for complex sample matrices.
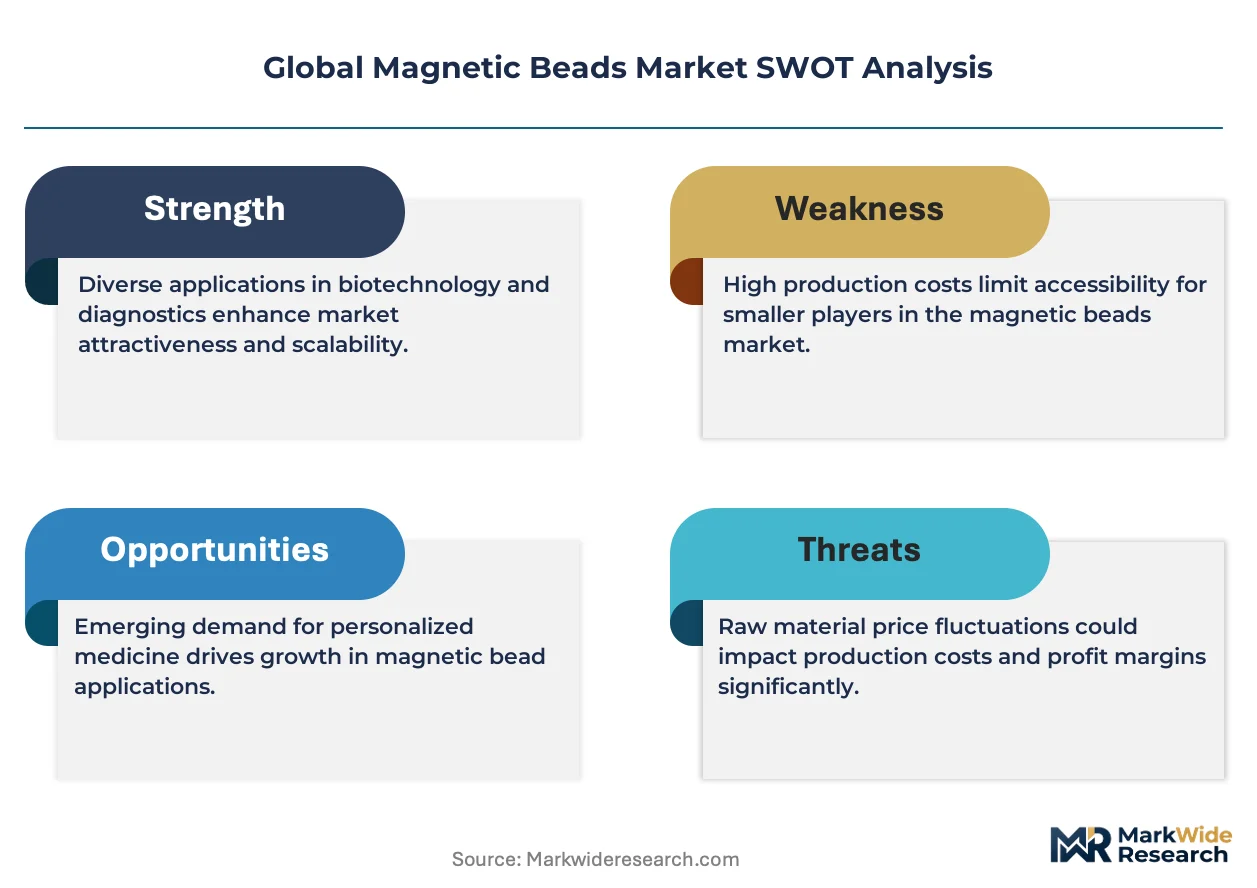
The FDA regulates magnetic beads incorporated into IVD devices under 21 CFR Part 820 quality system requirements, while the EU IVDR mandates notified body involvement for class C and D devices employing bead-based detection. China's NMPA has accelerated review pathways for domestically manufactured magnetic bead reagents used in infectious disease diagnostics. REACH compliance in Europe and state-level chemical reporting in California add layer costs for iron oxide nanoparticle formulations. Stakeholders must monitor evolving harmonization between FDA and EMA performance criteria for companion diagnostic bead assays to anticipate registration burden shifts.
Market Dynamics
Automation in clinical diagnostics is compressing protocol steps and forcing bead vendors to standardize surface chemistries around high-throughput liquid handlers. Thermo Fisher Scientific and Merck KGaA now engineer beads specifically for Tecan, Hamilton, and Beckman Coulter platforms, locking in instrument-agnostic compatibility as the baseline purchase criterion.
Growth Catalysts
- EU IVDR compliance deadlines:Diagnostic manufacturers must validate bead-based assays under stricter performance criteria, accelerating replacement of legacy reagent kits with certified alternatives.
- Cell therapy manufacturing scale-up:GMP-grade magnetic beads enable closed-system T-cell isolation, with demand concentrating at CDMO facilities in Germany and the United States.
- Silanol surface chemistry advances:Mixed-mode functionalization reduces nucleic acid extraction from four steps to two, cutting per-sample processing time for high-volume reference laboratories.
Market Restraints
- Iron oxide supply concentration:Over 70% of pharmaceutical-grade ferrofluid precursors originate from Chinese refiners, exposing bead producers to export licensing volatility.
- Streptavidin cost structure:Recombinant protein production requires fermentation capacity that mid-tier vendors lack, squeezing margins on affinity-capture product lines.
- Residual magnetization limitations:Sub-micron beads exhibit incomplete superparamagnetic recovery, forcing manual intervention in automated workflows and limiting adoption in point-of-care devices.
Strategic Opportunities
- India's CDSCO fast-track pathway:Domestic manufacturing incentives for infectious disease diagnostics create first-mover advantage for localized bead production.
- Protein purification convergence:Immobilized metal affinity chromatography beads integrated with continuous bioprocessing systems displace resin-based batch methods in monoclonal antibody production.
- Direct-to-researcher distribution:E-commerce platforms bypass distributor markups for academic core facilities, capturing price-sensitive volume in the United States and United Kingdom.
Industry Challenges
- Surface chemistry PhD scarcity:Polymer functionalization expertise concentrates at ten to fifteen specialist labs globally, constraining R&D velocity for mid-cap entrants.
- FDA 510(k) timeline compression:Parallel validation of bead lots across multiple instrument platforms extends regulatory submission preparation by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Magnetic Beads Market |
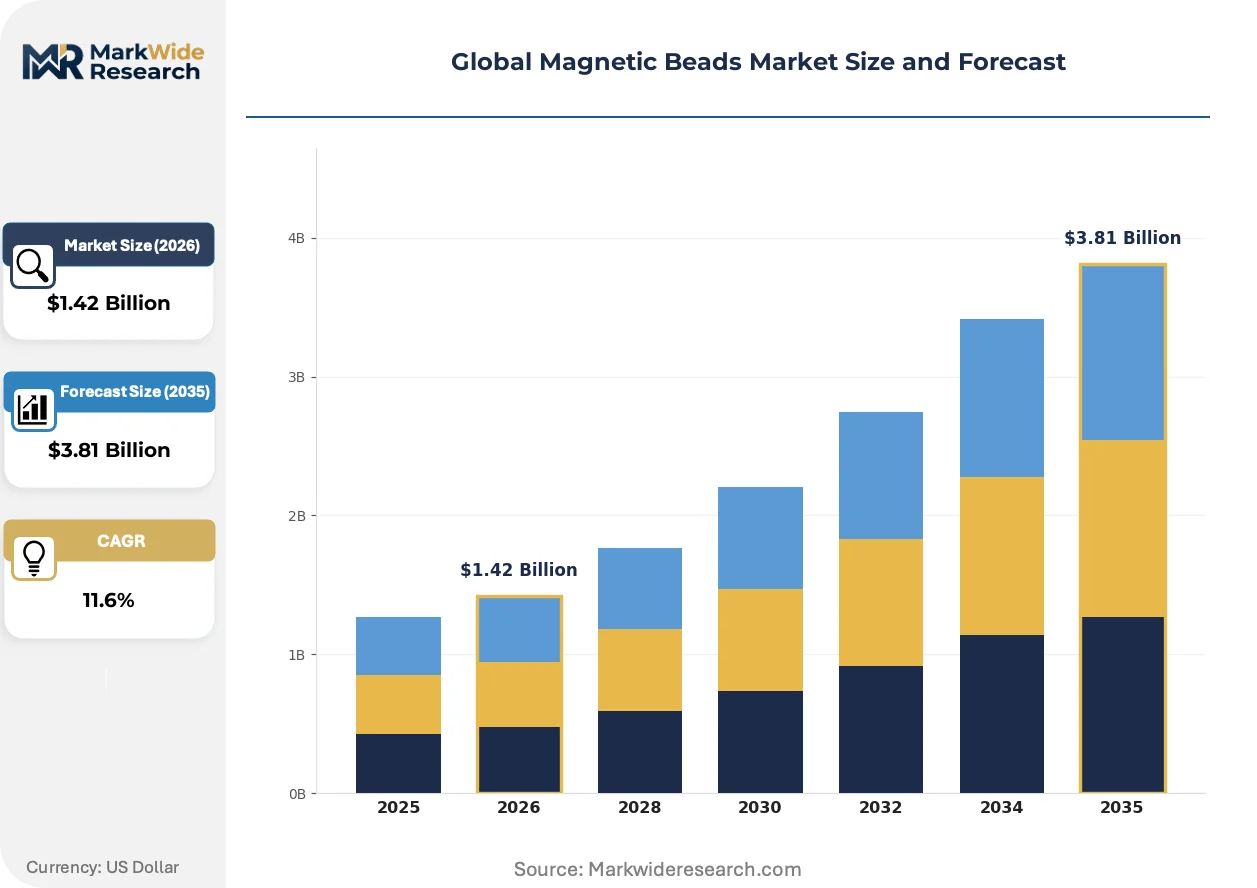
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Superparamagnetic Beads, Paramagnetic Beads, Microparticles, Nanoparticles, Ferrofluids Application: Cell Separation, Protein Purification, Nucleic Acid Isolation, Immunoassays, Drug Discovery End User: Biotechnology Firms, Diagnostic Laboratories, Pharmaceutical Companies, Research Institutes, Contract Research Organizations Technology: Surface Functionalization, Magnetic Separation, Covalent Binding, Electrostatic Binding, Affinity Binding |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Bio-Rad Laboratories, Inc., Miltenyi Biotec, GenScript Biotech Corporation, Promega Corporation, QIAGEN, Bangs Laboratories, Inc., New England Biolabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Magnetic Beads Market Shifts & Advancements
Surface engineering and workflow integration dominate vendor roadmaps as buyers demand beads that ship pre-validated on specific automation platforms. Standardization pressure from diagnostic OEMs is compressing the viable chemistry set and rewarding scale over specialization.
Multiplexed bead arrays are consolidating detection workflows in clinical microbiology. Luminex-style color-coded beads enable simultaneous pathogen identification from single samples. Reference laboratories in the United States and Germany have adopted these systems for respiratory panel testing. The technology is consolidating what previously required three sequential PCR runs into one 90-minute assay, eroding demand for single-analyte magnetic bead kits.
REACH authorization requirements for iron oxide nanoparticles are tightening traceability obligations across European supply chains. ECHA's 2023 update to annex substance listings mandates toxicity dossiers for particles below 100 nanometers. Bead producers serving diagnostic OEMs must now document full manufacturing history from ore to functionalized surface. German and Swiss suppliers have absorbed compliance costs into premium pricing tiers, while smaller Italian and Spanish vendors have exited the market entirely.
Consolidated procurement at hospital network level is displacing decentralized reagent purchasing. United States health systems with over 500 beds now mandate single-source contracts for nucleic acid extraction platforms, bundling instrument, beads, and service. This concentration forces bead vendors to compete on total cost of ownership rather than per-kit pricing. The shift is most visible in Texas and California, where IDN consolidation has reduced qualified suppliers from six to three in major metropolitan markets.
Global Magnetic Beads Market Segmentation
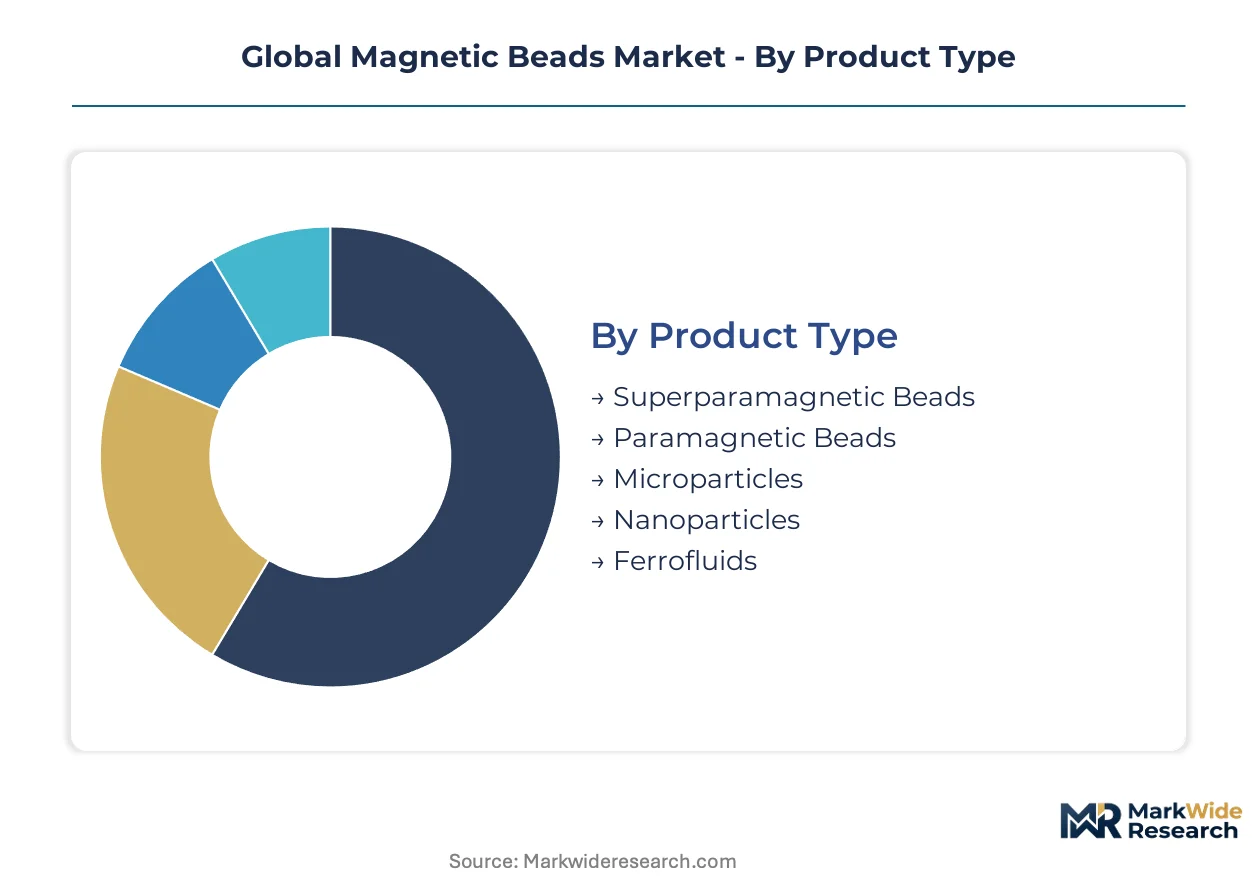
Magnetic bead segmentation reflects divergent paths between standardized bulk formulations and application-specific surface engineering. Buyers now select across five distinct dimensions where technical specifications, regulatory requirements, and automation compatibility create non-overlapping purchase criteria.
Product Type:
Customization intensity varies sharply across this category, from commodity ferrofluids to precision-engineered superparamagnetic architectures.
- Superparamagnetic Beads:Iron oxide cores below 30 nanometers exhibit zero residual magnetization after field removal, enabling automated wash cycles without clumping. Demand concentrates in United States reference laboratories running high-throughput nucleic acid extraction on Tecan and Hamilton platforms, where FDA-validated bead lots command premium positioning.
- Paramagnetic Beads:Larger ferrite particles retain weak magnetization, requiring stronger separation fields but offering lower cost per milligram. German cell therapy CDMOs favor these for GMP-grade T-cell isolation where magnetic recovery time matters less than sterility assurance and batch documentation.
- Microparticles:1-5 micrometer polystyrene-iron composites serve lateral flow immunoassays and point-of-care devices.
- Nanoparticles:Sub-100 nanometer formulations enable intracellular delivery and MRI contrast applications.
- Ferrofluids:Colloidal suspensions of surfactant-coated magnetite provide thermal and sealing applications beyond biomedicine.
Leading the category by volume: Paramagnetic Beads. Expanding most quickly: Superparamagnetic Beads.
Application:
Margin structures separate this category, with protein workflows capturing value from customized affinity ligands while nucleic acid extraction competes on throughput economics.
- Protein Purification:Immobilized metal affinity and streptavidin surface chemistries enable single-step capture of recombinant proteins and antibodies. Chinese biopharma manufacturers expanding monoclonal antibody capacity drive demand for cobalt and nickel-charged beads compatible with continuous chromatography systems.
- Cell Separation:CD3, CD4, and CD19 antibody-coated beads enable closed-system immunomagnetic selection for CAR-T manufacturing. United States and German facilities require GMP-grade materials with full donor-to-patient traceability, tightening supplier qualification to three dominant vendors.
- Nucleic Acid Isolation:Silanol and carboxyl functionalized beads automate DNA/RNA extraction across infectious disease diagnostics.
- Immunoassays:Chemiluminescent and fluorescent bead formats serve automated analyzers in clinical chemistry.
- Drug Discovery:Magnetic bead-based screening platforms accelerate target validation and lead optimization.
Highest margin capture: Protein Purification. Steepest volume climb: Nucleic Acid Isolation.
End User:
Procurement sophistication divides this category, from centralized health system tenders to fragmented academic purchasing.
- Diagnostic Laboratories:United States hospital networks with 500+ beds now mandate single-source extraction platform contracts bundling instruments, beads, and service. This concentration forces vendors to compete on total cost of ownership rather than per-kit pricing, reducing qualified suppliers in Texas and California metropolitan markets from six to three.
- Biotechnology Firms:Cell therapy developers in Germany and the United States require GMP-grade beads with validated supply chains for regulatory submission support.
- Pharmaceutical Companies:Large-scale bioprocessing operations integrate magnetic beads into continuous manufacturing workflows.
- Research Institutes:Academic core facilities prioritize instrument-agnostic formulations and e-commerce procurement channels.
- Contract Research Organizations:CDMOs serving multiple clients demand flexible bead configurations with rapid lot-to-lot qualification.
Dominant volume position: Diagnostic Laboratories. Fastest procurement transformation: Biotechnology Firms.
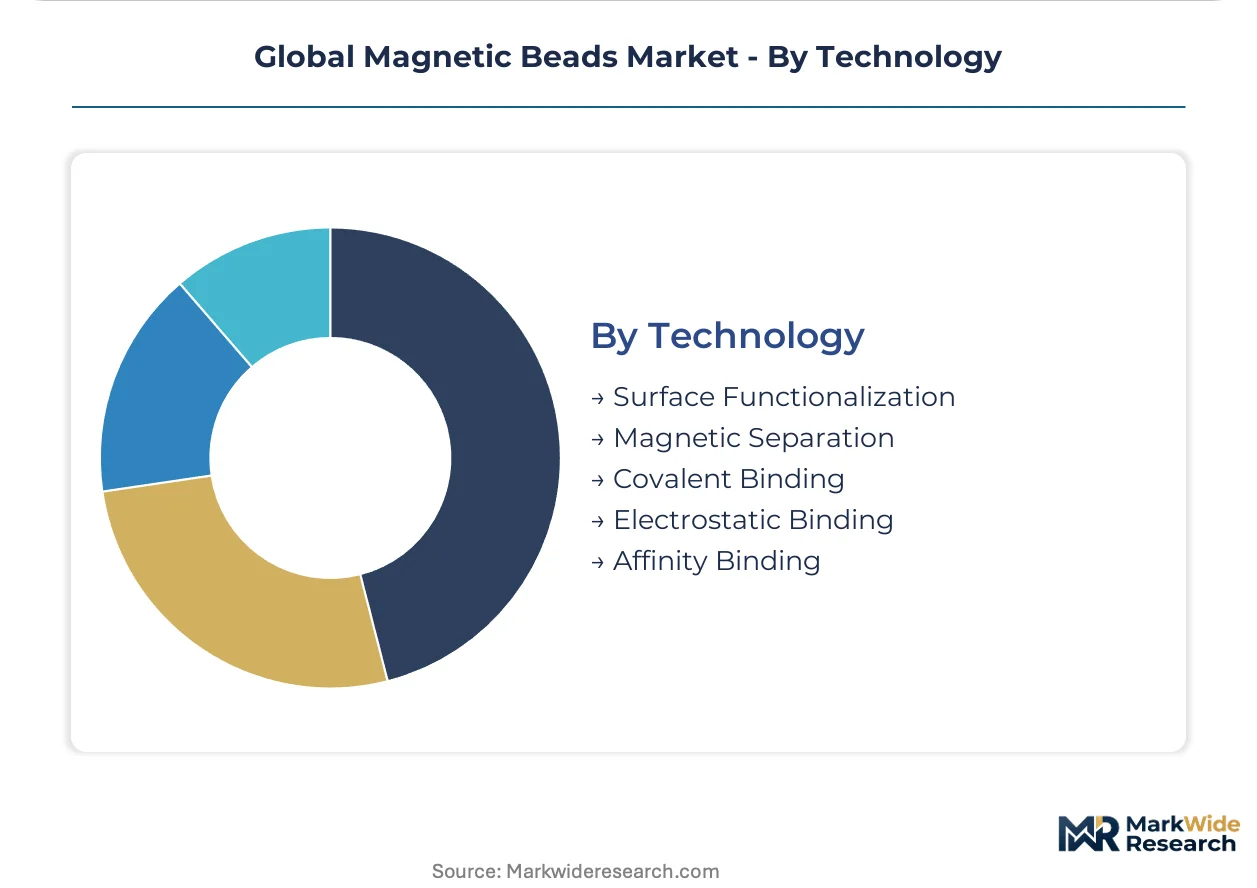
Technology:
Patent density and R&D concentration shape competitive moats across binding chemistries.
- Surface Functionalization:Silanol, carboxyl, amine, and streptavidin coatings determine binding specificity and elution efficiency. Mixed-mode chemistries reducing nucleic acid extraction from four steps to two command development priority at Thermo Fisher Scientific and Merck KGaA, with polymer functionalization expertise concentrated at ten to fifteen specialist labs globally.
- Affinity Binding:Antibody and ligand immobilization enables target-specific capture for cell therapy and protein purification applications.
- Magnetic Separation:Permanent magnet and electromagnet configurations determine field strength and separation kinetics.
- Covalent Binding:Carbodiimide and click chemistry approaches provide stable ligand attachment for harsh processing conditions.
- Electrostatic Binding:Charge-based capture offers reversible interactions for gentle elution protocols.
Most commercially critical: Surface Functionalization. Gaining R&D investment fastest: Affinity Binding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of pharmaceutical-grade iron oxide precursors, while the United States and Germany consume the highest volumes of finished magnetic beads for clinical diagnostics and cell therapy manufacturing.
United States
Hospital networks exceeding 500 beds now mandate single-source contracts for nucleic acid extraction platforms, bundling instruments, beads, and service. The FDA enforces 21 CFR Part 820 quality system requirements for IVD devices incorporating bead-based detection. Reference laboratories in Texas and California have reduced qualified suppliers from six to three through consolidated procurement at the integrated delivery network level.
Germany
CDMO facilities specializing in CAR-T manufacturing require GMP-grade magnetic beads with full donor-to-patient traceability. The EU IVDR mandates notified body involvement for class C and D devices employing bead-based assays. Cell therapy production clusters in Baden-Württemberg and Bavaria concentrate demand among three dominant qualified vendors.
China
Domestic biopharma manufacturers expanding monoclonal antibody capacity drive consumption of cobalt and nickel-charged beads for protein purification. The NMPA has accelerated review pathways for locally manufactured magnetic bead reagents used in infectious disease diagnostics. Yangtze River Delta production facilities supply over 70% of pharmaceutical-grade ferrofluid precursors to global bead producers.
India
Domestic manufacturing incentives for infectious disease diagnostics create first-mover advantage for localized bead production. The CDSCO fast-track pathway prioritizes review of domestically manufactured diagnostic reagents. Maharashtra and Karnataka host emerging contract manufacturing facilities targeting regional supply chain independence.
Switzerland
Precision surface functionalization expertise concentrates in specialist polymer chemistry laboratories serving European diagnostic OEMs. Swissmedic regulates bead-based IVD devices under harmonized EU IVDR criteria with additional national documentation requirements. Basel and Zurich anchor premium-tier bead production for pharmaceutical-grade applications.
Global Magnetic Beads Market Competitive Landscape
The competitive structure tilts toward diversified life science conglomerates with deep surface chemistry catalogs and GMP manufacturing infrastructure. Three archetypes dominate: instrument-integrated platform vendors, standalone reagent specialists with validated supply chains, and contract manufacturers serving diagnostic OEMs. Capacity expansion and strategic partnerships represent the primary competitive moves, with vendors engineering beads specifically for Tecan, Hamilton, and Beckman Coulter automation platforms to lock in compatibility.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA exemplify the platform-integrated archetype, while Bio-Rad Laboratories, Inc. occupies a position emphasizing instrument-agnostic formulations. These three entities anchor the premium tier through established regulatory dossiers and automation platform validation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Bio-Rad Laboratories, Inc. |
| Miltenyi Biotec |
| GenScript Biotech Corporation |
| Promega Corporation |
| QIAGEN |
| Bangs Laboratories, Inc. |
| New England Biolabs |
| Others |
Supply & Pricing Matrix
REACH authorization requirements for iron oxide nanoparticles gate qualified supply and premium-tier pricing access for European diagnostic OEMs, forcing bead producers to absorb toxicity dossier costs into tiered certification grades or exit the market entirely.
Pricing Analysis
Cost-down pressure on GMP-grade formulations accelerates as United States hospital networks consolidate procurement around single-source platform contracts bundling instruments, beads, and service. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated superparamagnetic beads for high-throughput reference laboratories from instrument-agnostic mid-tier chemistries and commodity paramagnetic alternatives. Certification tier and volume scale drive price differentiation, with biotechnology firms least price-sensitive due to regulatory submission requirements and academic core facilities most sensitive through e-commerce procurement channels.
Supply Chain Analysis
Freight cost volatility from Chinese refiners to German and United States manufacturing facilities amplifies working capital requirements for ferrofluid precursor inventory. Supply concentrates in China for pharmaceutical-grade iron oxide, Germany for GMP-grade surface functionalization, and Switzerland for precision polymer chemistry. Raw material dependencies span magnetite ore, recombinant streptavidin fermentation capacity, and silanol coupling agents. Single-source vulnerability from Yangtze River Delta ferrofluid production creates tariff exposure and export licensing risk. Distribution runs through diagnostic OEM direct contracts, CDMO supply agreements, and academic e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU IVDR's stricter performance validation requirements for class C and D devices create a cost-of-compliance moat that favors incumbent vendors with established notified body relationships and GMP manufacturing infrastructure.
For Market Incumbents: Lock in automation platform compatibility through validated bead lots engineered specifically for Tecan, Hamilton, and Beckman Coulter liquid handlers. Expand backward integration into iron oxide precursor supply through partnerships with Yangtze River Delta refiners to mitigate export licensing volatility. Prioritize mixed-mode surface chemistry R&D to reduce protocol steps and defend margin position against instrument-agnostic competitors.
For New Entrants and Emerging Players: Begin with India's CDSCO fast-track pathway for domestically manufactured infectious disease diagnostic reagents, where localized production incentives create first-mover advantage before supply chain independence consolidates. Target Maharashtra and Karnataka contract manufacturing facilities seeking regional bead supply alternatives. Pursue direct-to-researcher e-commerce distribution to bypass established distributor markups in price-sensitive academic segments.
For Investors and Strategic Acquirers: CDSCO approval acceleration for domestic Indian manufacturers is the leading indicator that regional supply chain independence will reshape competitive positioning in Asia-Pacific diagnostics. Surface functionalization expertise concentrated at ten to fifteen specialist labs globally represents scarce capability with long-term consolidation potential. Monitor REACH authorization timelines for sub-100 nanometer iron oxide particles as the signal for European market exit acceleration among sub-scale vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | Enables closed-system T-cell isolation supply to CAR-T CDMOs in Germany and the United States. |
| Automation Platform Partnership | Locks in instrument-specific bead validation with Tecan, Hamilton, and Beckman Coulter liquid handlers. |
| Backward Integration into Precursors | Captures supply security for pharmaceutical-grade ferrofluid from Yangtze River Delta refiners. |
| Surface Chemistry Acquisition | Consolidates scarce polymer functionalization expertise from specialist European laboratories. |
| Regional Manufacturing Localization | Exploits CDSCO fast-track pathways in Maharashtra and Karnataka for Indian diagnostic supply. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with diagnostic laboratory directors, cell therapy manufacturing executives, bead vendor R&D leads, and hospital procurement managers. FDA 510(k) databases, EU IVDR notified body submissions, ECHA REACH authorization records, and NMPA accelerated review pathway disclosures provided regulatory trajectory validation. Bottom-up bead volume estimates by application and end-user segment triangulated against top-down market sizing from ferrofluid precursor trade flows.
Reconciliation of production capacity disclosures from Chinese refiners, German CDMO facility expansions, and United States reference laboratory automation deployments shaped the analytical framework. Segmentation modeling spanned product type, surface functionalization technology, application workflow, and end-user procurement sophistication across the projection horizon. CAGRs derived from instrument installation base growth, cell therapy clinical trial expansion, and nucleic acid extraction test volume trends in infectious disease diagnostics.
Underlying measurement precision varies by segment; superparamagnetic beads for FDA-validated IVD workflows carry tighter precision than commodity paramagnetic alternatives for research use. Forecasts reflect assumptions about IVDR compliance timeline adherence, ferrofluid export licensing stability, and cell therapy manufacturing scale-up rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Global Non-Oriented Electrical Steel Market
Magnetic Materials
Sintered Magnet Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Global Iron Powder Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
High Performance Magnet Market
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Nanocrystalline Soft Magnetic Material Market
Magnetic Materials
High Purity Carbonyl Iron Powder (CIP) Market
Magnetic Materials
North America Samarium Cobalt Magnets Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Neodymium [Nd-Fe-B] Magnet Market
Magnetic Materials
Japan Neodymium Iron Boron Magnet Market
Magnetic Materials
Global Permanent Magnet Market
Magnetic Materials
Rare Earth Magnet Market