
 Europe Copper Magnetic Wire Market | 2026-2036
Europe Copper Magnetic Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Copper Magnetic Wire Market Insights
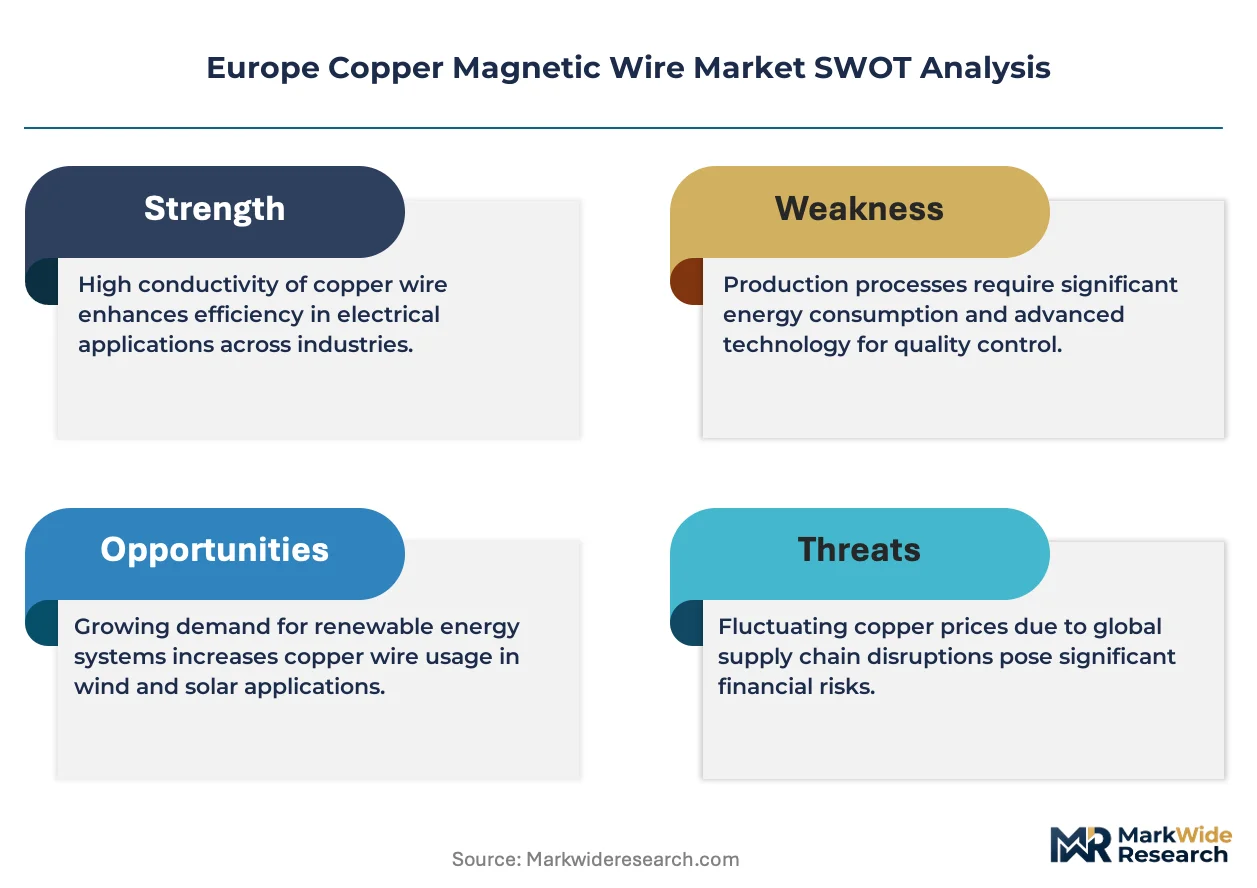
The split between premium enameled wire and commodity bare copper conductors is shifting as EV power density requirements harden. Schwering & Hasse Elektrodraht GmbH leverages its vertical integration into enamel coating chemistry to command premium positioning. Elektrisola Dr. Gerd Schildbach GmbH & Co. KG anchors its competitiveness through extreme fine-wire specialization for precision winding applications. IRCE S.p.A. competes on geographic proximity to Southern European motor manufacturers.
Copper magnetic wire consists of high-conductivity copper conductors, typically 99.9% pure, insulated with synthetic resin enamels or polymer films to enable electromagnetic energy conversion in rotating machines and static apparatus. The conductor diameter ranges from sub-millimeter fine wire to heavy-gauge rectangular strip, with insulation build classified by thermal index from 105°C to 240°C under IEC 60172 test protocols. Enameled wire carries the dominant value share due to its irreplaceability in high-slot-fill motor designs, while Litz wire captures accelerating demand from high-frequency power electronics in automotive inverters where skin effect losses demand stranded conductor architectures. The Automotive end-user segment concentrates margin pools as OEMs specify thermal class 200+ insulations for under-hood durability.
REACH compliance and the EU F-Gas Regulation constrain insulation resin formulations, pushing manufacturers toward bio-based polyesters and reduced-VOC curing processes. EMA and national regulators in Germany, Italy, and France enforce IEC 60317 dimensional standards that govern cross-border component interoperability. CE marking requirements under the EU Low Voltage Directive shape product liability exposure for wire supplied into safety-critical applications. Stakeholders must track how the EU AI Act and emerging digital product passport rules will mandate supply chain traceability for copper sourcing and insulation chemistry disclosure.
Market Dynamics
EV power density requirements are compressing insulation thickness tolerances while expanding thermal class specifications, forcing wire manufacturers to reconcile slot-fill optimization with REACH-compliant resin chemistry across Germany's automotive corridor.
Growth Catalysts
- EU Green Deal decarbonization mandates:Binding emission targets for transport electrification are pulling thermal class 200+ wire specifications into mass-market EV traction motor contracts.
- High-frequency inverter architectures:Silicon carbide switching frequencies above 20 kHz are demanding Litz wire configurations to suppress skin effect losses in automotive power electronics.
- France's battery gigafactory cluster:Cell manufacturing expansion around Dunkirk and Douai is creating localized demand for precision winding wire in battery management system inductors.
Market Restraints
- Copper cathode price volatility:LME price swings above 15% annually are compressing margin visibility for wire drawers without captive smelter arrangements.
- Insulation resin supply concentration:Specialty polyimide precursor manufacturing clusters in Germany's chemical belt create single-source vulnerability for thermal class 220+ formulations.
- Aluminum conductor substitution:Mass-sensitive applications in aviation and select automotive auxiliary motors are adopting aluminum magnet wire to reduce winding weight.
Strategic Opportunities
- Poland's emerging motor manufacturing corridor:Underdeveloped local enamel coating capacity creates import substitution potential for wire suppliers establishing regional slitting and insulating operations.
- EU AI Act supply chain traceability:Mandatory digital product passports for critical raw materials will reward early adopters of blockchain-verified copper sourcing documentation.
- Direct-to-tiers distribution platforms:B2B marketplaces connecting wire mills with tier-two stator winders are disintermediating traditional national distributor networks in Southern Europe.
Industry Challenges
- Enamel chemist talent scarcity:Formulation expertise for bio-based polyester development is concentrating among retiring specialists at German and Italian research institutes.
- IEC 60317 certification timelines:Thermal index requalification for modified resin systems requires 18-month accelerated aging protocols that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Copper Magnetic Wire Market |
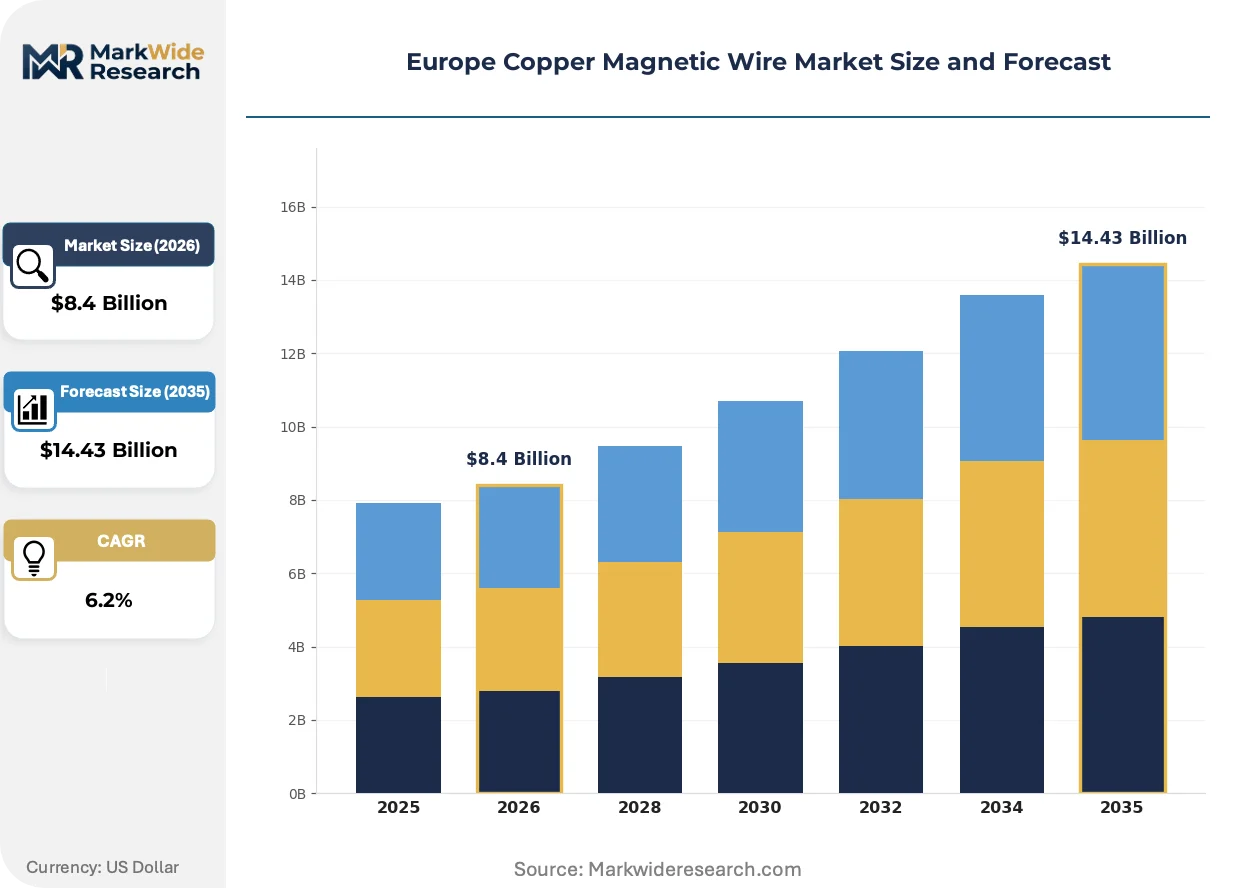
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enameled Wire, Bare Wire, Litz Wire, Magnet Wire Insulation Type: Polyester, Polyamide, Polyesterimide, Glass Application: Transformers, Electric Motors, Inductors, Generators End User: Automotive, Aerospace, Home Appliances, Industrial Equipment |
| Companies Covered | Schwering & Hasse Elektrodraht GmbH, HPW Metallwerk GmbH, Elektrisola Dr. Gerd Schildbach GmbH & Co. KG, IRCE S.p.A., Dahrén Group, Altana AG, Superior Essex Inc., TE Connectivity, SYNFL eX Elektro GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Copper Magnetic Wire Market Trends and Innovations
Rectangular profile wire with corner radius optimization is displacing traditional round conductors in high-slot-fill EV motor designs, while regulatory chemistry constraints are accelerating bio-based insulation development.
Self-bonding enamel formulations with thermoplastic overcoats are electrifying precision winding applications by eliminating bobbin requirements and enabling compact coil geometries. Medical device motor manufacturers in Switzerland and laboratory equipment OEMs in Germany are specifying these constructions for miniature actuator assemblies. The technology is compressing winding cycle times and reducing assembly part counts in sub-50W motor categories.
REACH Annex XIV authorization requirements for certain phthalate-based plasticizers are forcing reformulation of flexible insulation systems used in appliance motor lead wire. ECHA's sunset date scheduling is compressing supplier transition timelines, with Italian wire manufacturers accelerating polyesterimide alternatives to maintain CE marking continuity. The regulatory pressure falls heaviest on mid-tier suppliers serving white goods manufacturers in Poland and Turkey.
Consolidated procurement desks at European automotive OEMs are compressing supplier qualification cycles and demanding integrated copper-enameled wire-Litz wire portfolios from single sources. Tier-one motor manufacturers are unbundling specification authority from legacy national purchasing organizations, centralizing global commodity management functions in Stuttgart and Munich. The behavioral shift is most visible in Germany's premium EV platform supply chains, where direct mill relationships are displacing multi-tier distribution.
Europe Copper Magnetic Wire Market Segmentation
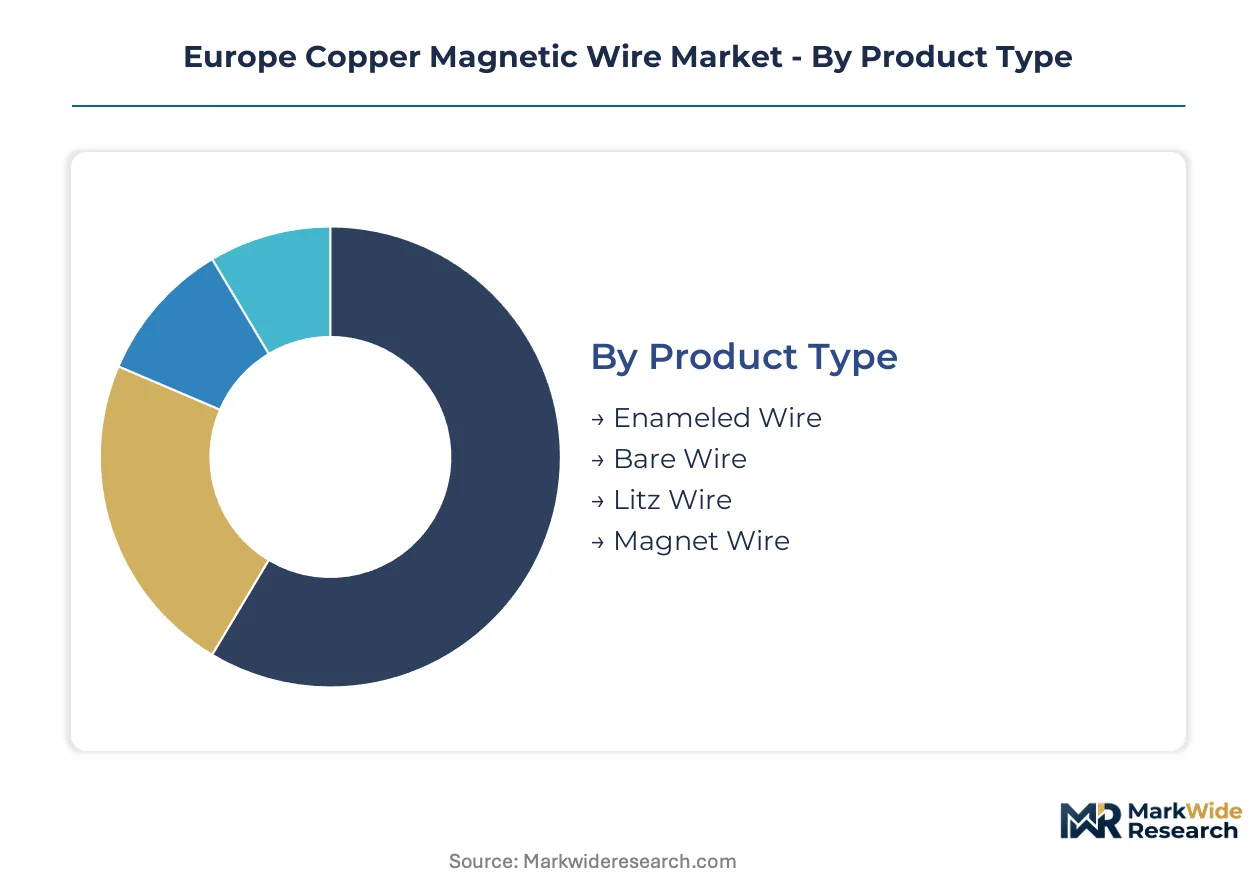
Copper magnetic wire buyers select specifications based on thermal endurance, slot-fill efficiency, and regulatory compliance rather than commodity pricing. Segmentation reveals how insulation chemistry and conductor geometry separate premium automotive contracts from cost-optimized appliance supply. Understanding these divides exposes where margin pools concentrate and where substitution threats emerge.
Product Type:
Buyers prioritize thermal class ratings and winding efficiency when selecting conductor formats for electromagnetic applications.
- Enameled Wire:Synthetic resin coatings ranging from 105°C to 240°C thermal index enable high-slot-fill designs in rotating machinery. German EV traction motor manufacturers specify thermal class 200+ formulations from Schwering & Hasse Elektrodraht to meet under-hood durability requirements under EU Green Deal mandates.
- Litz Wire:Stranded conductor architectures with individually insulated strands suppress skin effect losses at switching frequencies above 20 kHz. Silicon carbide inverter adoption across France's battery gigafactory cluster around Dunkirk and Douai is accelerating demand for precision-wound Litz configurations in automotive power electronics.
- Bare Wire:Uninsulated high-conductivity conductors serve grounding applications and intermediate processing stages before enamel coating.
- Magnet Wire:General-purpose electromagnetic winding conductors span transformer and motor applications with standardized IEC 60317 dimensional tolerances.
Enameled wire leads on scale; Litz wire leads on momentum.
Insulation Type:
REACH compliance and F-Gas Regulation constraints are reshaping resin formulation preferences across coating chemistry decisions.
- Polyesterimide:Hybrid resin systems combining polyester backbone with imide functionality deliver 180°C thermal index with improved solvent resistance. Italian wire manufacturers accelerated polyesterimide alternatives to maintain CE marking continuity as ECHA sunset dates approached for legacy phthalate-based plasticizers.
- Polyester:Cost-effective base enamels with 155°C thermal ratings dominate appliance motor and standard industrial applications where thermal margins permit.
- Polyamide:Overcoat layers provide mechanical protection and improved windability for precision winding operations in sub-millimeter fine wire gauges.
- Glass:Inorganic fiber insulation serves high-temperature generator applications and specialty furnace-wound coils exceeding organic resin thermal limits.
Polyesterimide gains share fastest in automotive specifications; polyester retains volume leadership in appliance supply.
Application:
Power density requirements and operating frequency profiles determine conductor geometry and insulation build specifications.
- Electric Motors:Rotating machinery from fractional horsepower to multi-megawatt traction systems demands rectangular profile wire with optimized corner radius for maximum slot-fill. EV power density compression across Germany's automotive manufacturing corridor is displacing round conductors in premium platform stator designs.
- Transformers:Static electromagnetic apparatus requires heavy-gauge rectangular strip with uniform insulation build for grid infrastructure and power distribution applications.
- Inductors:Energy storage components in battery management systems and power electronics specify fine-wire precision winding with tight dimensional tolerances.
- Generators:Prime mover-driven alternators for industrial and renewable applications combine heavy conductors with high thermal class insulation for continuous duty cycles.
Electric motors lead on scale; inductors lead on momentum.
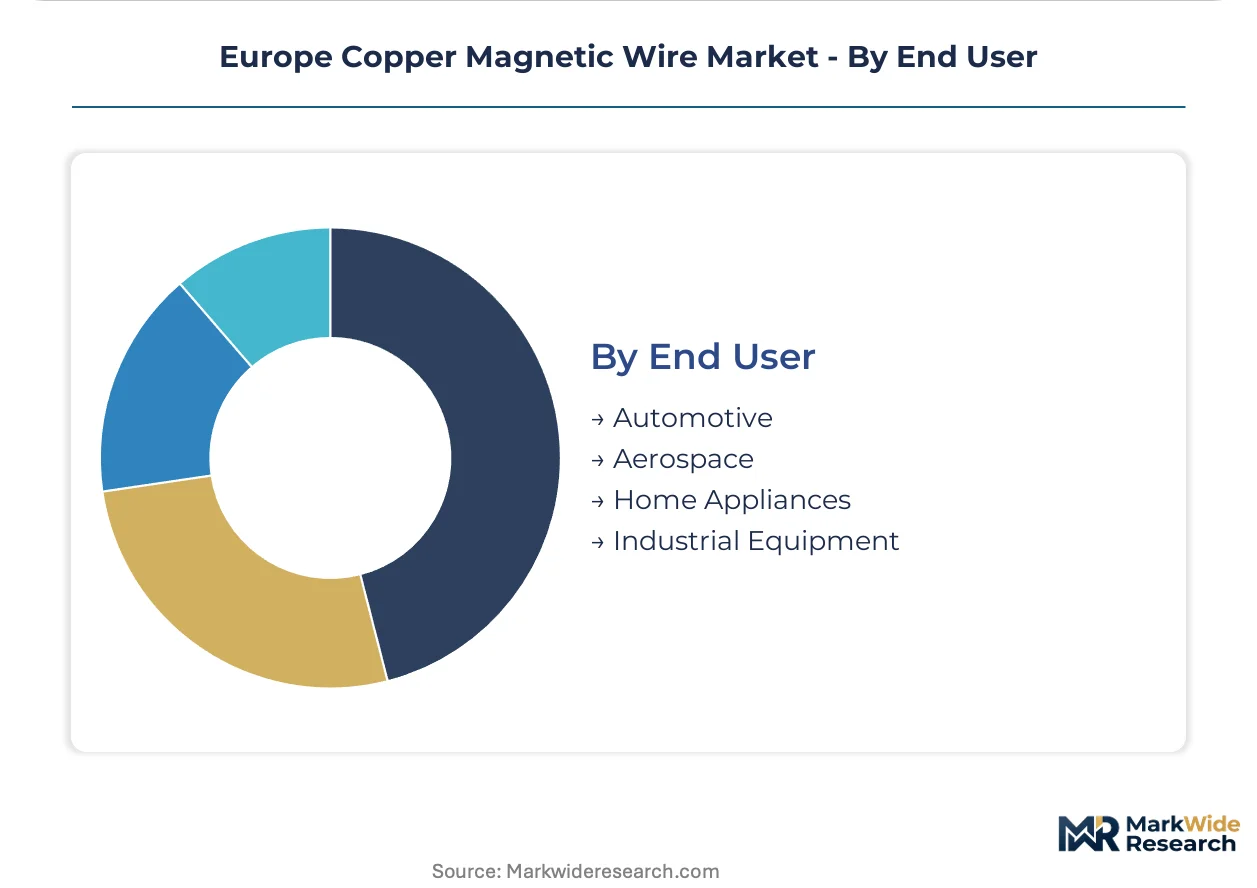
End User:
Specification authority and procurement centralization patterns vary sharply across customer categories.
- Automotive:Consolidated procurement desks at European OEMs demand integrated copper-enameled wire-Litz wire portfolios from single qualified sources. Tier-one motor manufacturers unbundled specification authority from legacy national purchasing organizations, centralizing global commodity management in Stuttgart and Munich.
- Industrial Equipment:Diverse machinery builders from compressed air systems to material handling specify standardized thermal class 155-180 constructions with price-sensitive procurement.
- Aerospace:Mass-sensitive applications adopt aluminum conductor substitution for auxiliary motors and actuators where winding weight reduction outweighs conductivity penalties.
- Home Appliances:White goods manufacturers in Poland and Turkey source cost-optimized polyester-insulated wire through distributor networks with limited direct mill relationships.
Automotive leads on scale and margin; aerospace presents selective substitution risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized enamel chemists and precision winding engineers concentrate in Germany's industrial belt, anchoring the region's technical workforce density for high-thermal-class wire development.
Germany
EV traction motor contracts from Stuttgart and Munich OEMs pull thermal class 200+ specifications into mass production. The EU Green Deal binds transport electrification targets that harden insulation durability requirements. The automotive manufacturing corridor spanning Baden-Württemberg and Bavaria hosts concentrated stator winding operations for premium EV platforms.
France
Battery gigafactory construction around Dunkirk and Douai generates localized demand for precision winding wire in battery management system inductors. The F-Gas Regulation constrains insulation resin formulations used in high-voltage automotive applications. The Hauts-de-France region clusters cell manufacturing expansion that consumes specialized Litz wire for silicon carbide inverters.
Italy
Appliance motor manufacturers accelerate polyesterimide alternatives to maintain CE marking continuity as ECHA sunset dates approach for legacy plasticizers. REACH Annex XIV authorization timelines compress supplier transition windows for flexible insulation systems. The Emilia-Romagna industrial district concentrates mid-tier wire suppliers serving white goods export markets.
Poland
Underdeveloped local enamel coating capacity creates import substitution potential for wire suppliers establishing regional slitting and insulating operations. National regulators enforce IEC 60317 dimensional standards governing cross-border component interoperability. The emerging motor manufacturing corridor around Wrocław and Poznań attracts tier-two stator winders seeking proximity to German OEM supply chains.
Switzerland
Medical device motor manufacturers specify self-bonding enamel formulations for miniature actuator assemblies in precision laboratory equipment. Swissmedic oversight shapes product liability exposure for wire supplied into safety-critical healthcare applications. The Zurich-Basel corridor concentrates R&D-intensive winding operations for sub-50W motor categories.
Europe Copper Magnetic Wire Market Competitive Landscape
Top-tier vendors anchor premium thermal class supply, while mid-tier specialists occupy cost-optimized appliance segments. The vendor base organizes around three strategic archetypes: vertically integrated enamel coaters with captive chemistry operations, extreme fine-wire specialists serving precision winding niches, and geographic proximity players leveraging Southern European motor manufacturing density. Competitive moves concentrate on backward integration into resin precursor supply and direct mill relationships that disintermediate traditional distributor networks.
Within the vertically integrated tier, Schwering & Hasse Elektrodraht GmbH represents the archetype of enamel chemistry control, while Elektrisola Dr. Gerd Schildbach GmbH & Co. KG exemplifies fine-wire specialization for precision applications. IRCE S.p.A. occupies a position among geographic proximity players serving Southern European motor manufacturers. These three anchors illustrate how competitive positioning separates premium automotive contracts from cost-sensitive appliance supply through differential control over coating chemistry, conductor geometry, and regional logistics.
| Leading Market Players |
|---|
| Schwering & Hasse Elektrodraht GmbH |
| HPW Metallwerk GmbH |
| Elektrisola Dr. Gerd Schildbach GmbH & Co. KG |
| IRCE S.p.A. |
| Dahrén Group |
| Altana AG |
| Superior Essex Inc. |
| TE Connectivity |
| SYNFL eX Elektro GmbH |
| Others |
Pricing and Supply Chain Analysis
Consolidated procurement desks at Stuttgart and Munich OEMs demanding integrated copper-enameled wire-Litz wire portfolios from single qualified sources are compressing supplier margins and forcing wire mills to absorb coating chemistry investments that were previously distributor-marked-up.
Pricing Analysis
Bundled direct-mill relationships versus unbundled distributor-mediated supply separates premium automotive contracts from cost-optimized appliance tiers. Pricing stratifies across thermal class 200+ automotive specifications, mid-tier polyesterimide industrial grades, and commodity polyester appliance supply. Cost compression in thermal class 220+ formulations is intensifying because specialty polyimide precursor manufacturing clusters in Germany's chemical belt create single-source vulnerability. White goods manufacturers in Poland and Turkey exhibit highest price sensitivity, while German EV platform procurement teams prioritize qualification speed over unit cost.
Supply Chain Analysis
Copper cathode supply rests on smelter arrangements concentrated in Germany, Poland, and Belgium for European wire drawers. Specialty polyimide precursors, bio-based polyester resins, and rectangular conductor slitting capacity constitute critical input dependencies. Single-source vulnerability for thermal class 220+ insulation resin formulations creates structural supply risk. Distribution runs through direct-to-tiers B2B marketplaces disintermediating traditional national distributor networks in Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Copper Magnetic Wire Market functions as a stable compounder anchored by EU Green Deal decarbonization mandates that pull high-thermal-class specifications into mass-market EV traction motor contracts with decade-long visibility.
For Market Incumbents: Acquire enamel coating chemistry expertise to secure backward integration into resin precursor supply. German wire manufacturers should expand rectangular profile wire slitting capacity in Poland's emerging motor manufacturing corridor to capture import substitution demand. Aluminum conductor substitution in aviation auxiliary motors and REACH Annex XIV sunset date compression for phthalate-based plasticizers threaten legacy revenue streams. For New Entrants and Emerging Players: The price-point gap between Schwering & Hasse Elektrodraht's premium thermal class 200+ positioning and mid-tier Italian polyesterimide suppliers creates entry space for precision Litz wire specialists. France's battery gigafactory cluster around Dunkirk and Douai offers the most penetrable geography for silicon carbide inverter-grade Litz configurations. A direct-to-tiers B2B marketplace go-to-market angle bypasses entrenched national distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated enamel coaters with captive chemistry operations and established IEC 60317 certification portfolios. The five-to-ten year viability window favors targets with thermal index requalification capabilities and blockchain-verified copper sourcing documentation ready for EU AI Act digital product passport mandates. Watch for silicon carbide inverter adoption rates above 20 kHz switching frequencies as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Precursor Supply | Captive polyimide chemistry control insulates margin from ECHA authorization timeline compression. |
| Regional Slitting and Insulating Operations in Poland | Proximity to Wrocław-Poznań motor manufacturing corridor reduces logistics exposure for German OEM supply. |
| Digital Product Passport Implementation | Blockchain-verified copper sourcing documentation satisfies EU AI Act traceability mandates before enforcement. |
| Bio-Based Polyester Formulation Development | REACH-compliant resin chemistry maintains CE marking continuity as ECHA sunset dates approach. |
| Direct-to-Tiers B2B Marketplace Launch | Disintermediation of Southern European distributor networks captures margin from tier-two stator winders. |
Research Methodology
Coverage spans Germany, France, Italy, Poland, and Switzerland, with primary inputs from each market cluster combining interviews with procurement directors at Tier 1 motor manufacturers, enamel coating R&D leads, and stator winding operations managers with secondary validation from ECHA REACH registration databases, EU F-Gas Regulation implementation filings, and IEC 60317 certification records. Bottom-up volume modeling triangulates against top-down OEM production forecasts.
Granularity-level modeling disaggregates demand across product type, insulation chemistry, conductor geometry, application, and end-user procurement centralization patterns. Value projections incorporate thermal class tier pricing differentials and Litz wire premium structures across the projection horizon. CAGRs derive from EV platform production schedules, silicon carbide inverter penetration curves, and battery gigafactory construction timelines.
Caveats apply where LME copper price volatility exceeding historical bands, ECHA sunset date acceleration for additional plasticizer categories, or aluminum conductor substitution breakthroughs in mass-sensitive automotive applications could materially shift the outlook. A small set of triggers—EU AI Act digital passport enforcement timing, silicon carbide switching frequency adoption curves, and Poland's motor manufacturing corridor development pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Europe Ferrite Magnet Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
Magnet Buffer Market
Magnetic Materials
Neodymium [Nd-Fe-B] Magnet Market
Magnetic Materials
High Purity Carbonyl Iron Powder (CIP) Market
Magnetic Materials
Magnetic Material Magnetization and Testing Equipment Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
Ferroboron Market
Magnetic Materials
Copper Magnet Wire Market
Magnetic Materials
Rare Earth Magnet Market
Magnetic Materials
Flux Field Directional Material Market
Magnetic Materials
North America Magnet Wire Market
Magnetic Materials
Global Iron Powder Market
Magnetic Materials
Magnetic Carbon Nanofoam Market
Magnetic Materials
Magnet Market