
 Global Non-Oriented Electrical Steel Market | 2026-2036
Global Non-Oriented Electrical Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Oriented Electrical Steel Market Foresight
The EU Green Deal is repositioning non-oriented electrical steel toward premium grades for high-efficiency motors. ArcelorMittal leverages its integrated European mills to supply automotive-grade laminations. NIPPON STEEL CORPORATION anchors Asian supply through advanced continuous annealing lines. POSCO dominates South Korean output with specialized silicon steel for inverter-duty motors.
Non-oriented electrical steel is a low-carbon silicon-alloyed flat-rolled product manufactured via continuous casting, hot rolling, and annealing to achieve isotropic magnetic properties with core losses typically below 2.5 W/kg at 1.5 T. Cold rolled grades command the widest application scope across fractional-horsepower to megawatt-class machines. Electric motors represent the deepest margin pool, while magnetic sensors constitute the fastest-growing application segment driven by precision motion control in robotics.
REACH in Europe, the EPA's energy efficiency mandates in the United States, and China's GB standards enforced by SAMR collectively dictate coating chemistries, core loss ceilings, and scrap-recycling protocols. These frameworks compel mills to certify every heat against tiered efficiency bands before market release. Stakeholders must track how regulatory tightening in major economies will split the supplier base between premium-certification leaders and commodity-grade challengers.
Market Dynamics
The EU Ecodesign Directive is compressing the efficiency threshold for industrial motors, forcing mills to recertify entire product portfolios against stricter core loss ceilings before market release.
Growth Catalysts
- EU Ecodesign Directive:Mandates IE4 efficiency classes for motors above 0.75 kW, pulling premium-grade silicon steel demand across German and Italian manufacturing bases.
- Electric vehicle traction motors:Automakers in China and Germany are specifying thinner-gauge laminations to reduce eddy current losses in high-speed inverter drives.
- Silicon content optimization:Advanced continuous annealing lines in Japan and South Korea now deliver 6.5% silicon grades with sub-2.0 W/kg core losses at competitive gauge thickness.
Market Restraints
- Silicon and electricity input volatility:Ferrosilicon prices fluctuate with Chinese smelter output curbs, while European mills face natural gas cost spikes from Norwegian and Algerian supply uncertainty.
- Supply concentration in East Asian annealing capacity:Over 60% of global high-grade continuous annealing lines sit in China, Japan, and South Korea, creating single-source exposure for automotive laminations.
- Grain-oriented steel substitution in large transformers:Utilities in India and Brazil specify domain-refined grain-oriented grades for distribution transformers above 10 MVA, capping non-oriented penetration.
Strategic Opportunities
- India's PLI scheme for high-efficiency motors:Domestic content requirements under the Production Linked Incentive program create captive demand for locally annealed non-oriented grades.
- Magnetic sensor integration in robotics:Precision motion control systems in German and Japanese automation clusters specify ultra-thin 0.10 mm laminations for resolver and encoder cores.
- Dual carbon goals in China:Provincial energy intensity targets in Jiangsu and Shandong reward mills deploying hydrogen-annealing retrofits with preferential grid access and carbon credit allocations.
Industry Challenges
- Magnetic property certification timelines:Third-party testing for IEC 60404-8-4 compliance requires 8-12 week lead times, delaying new heat releases during demand spikes.
- Legacy coating chemistry conversion:Mills in the United States and Europe must reformulate C6 chrome-free insulations to meet REACH Annex XVII restrictions while maintaining punchability and interlaminar resistance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Oriented Electrical Steel Market |
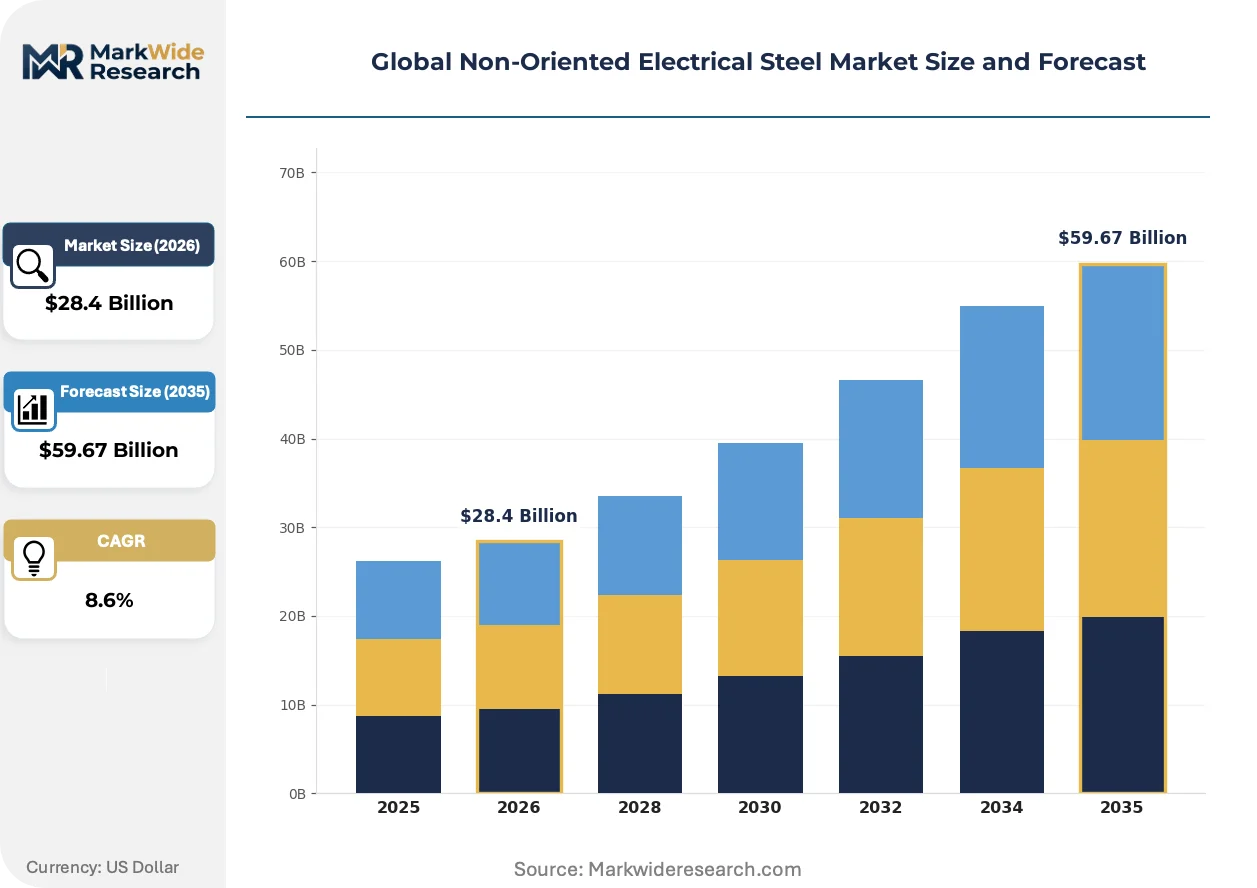
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $59.67 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
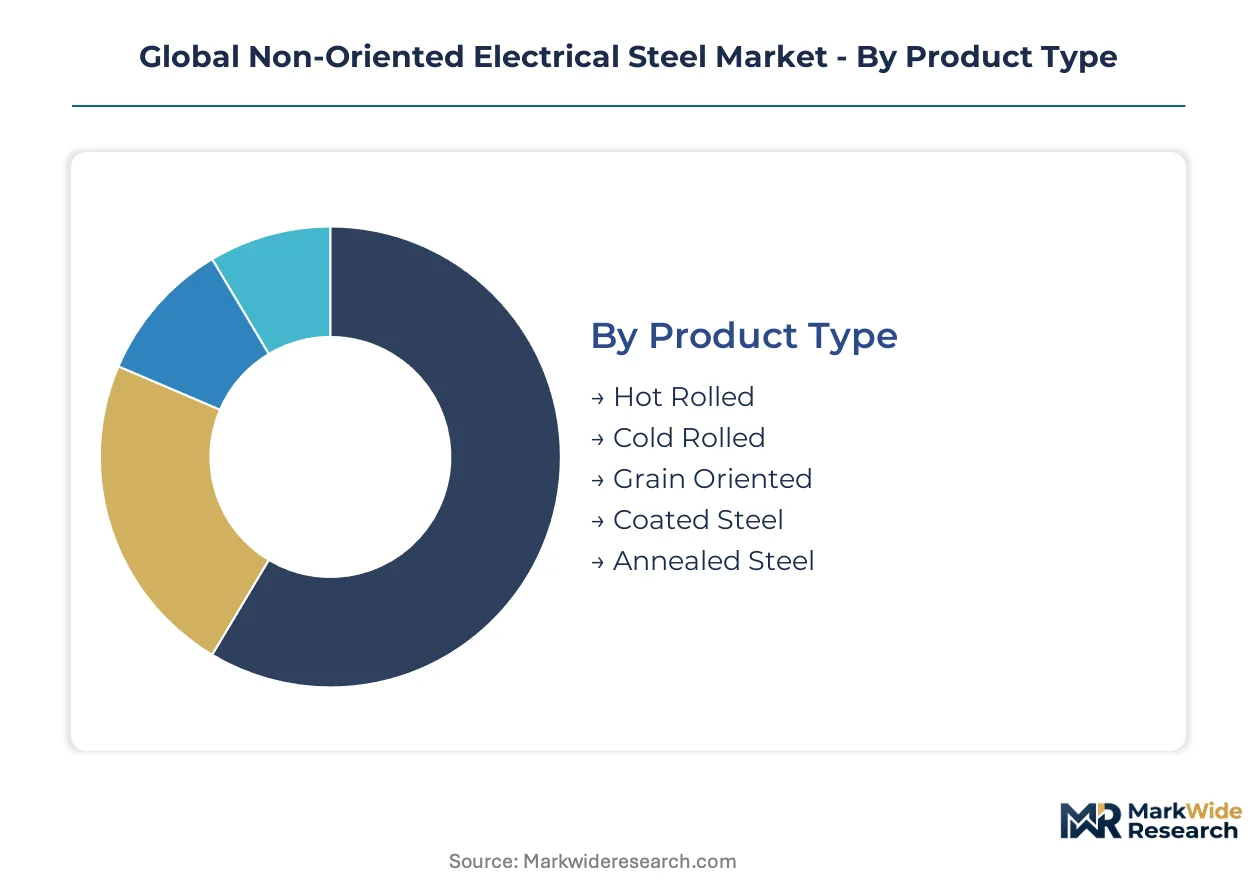
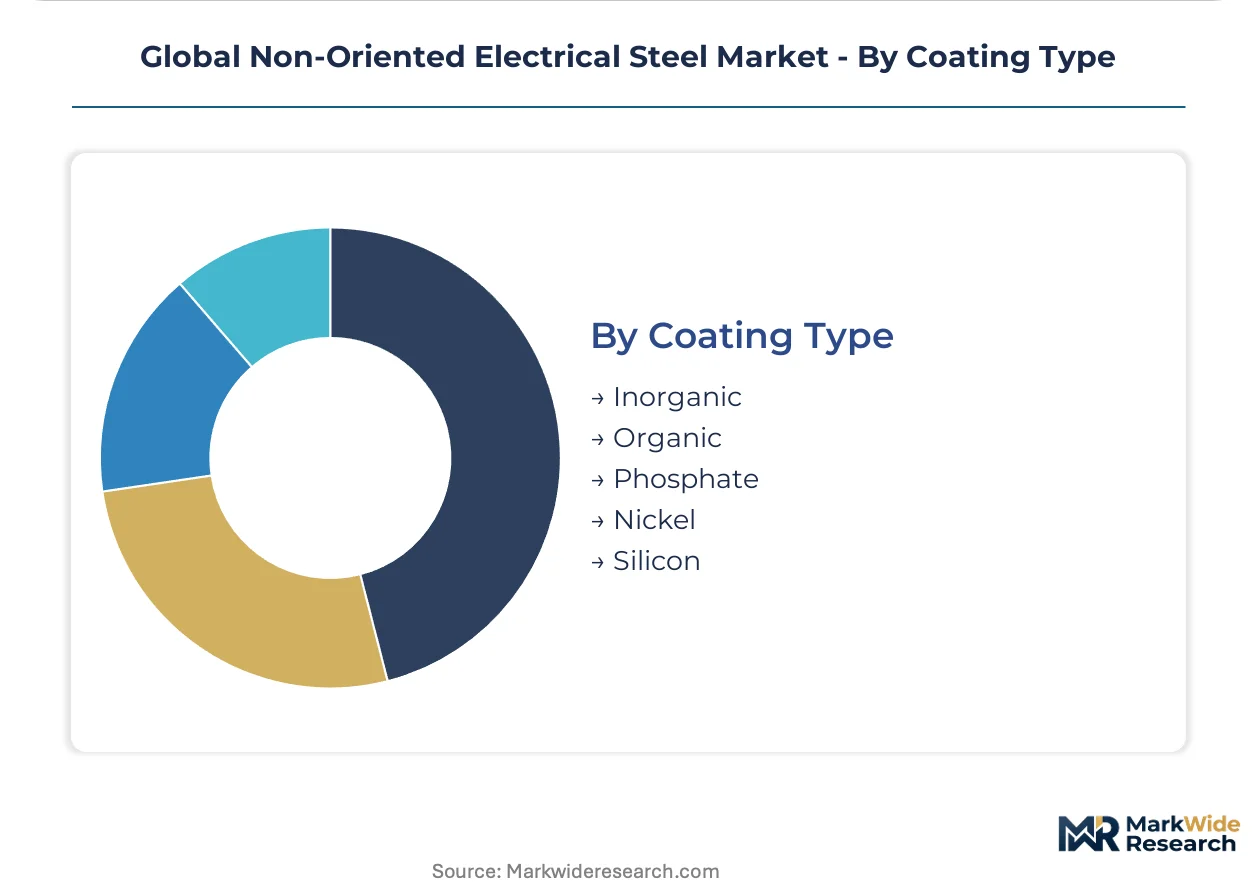
| Segmentation | Product Type: Hot Rolled, Cold Rolled, Grain Oriented, Coated Steel, Annealed Steel Application: Electric Motors, Generators, Transformers, Magnetic Sensors, Inverters End User Industry: Renewable Energy, Heavy Machinery, Consumer Electronics, Rail Transport, Aerospace Coating Type: Inorganic, Organic, Phosphate, Nickel, Silicon |
| Companies Covered | ArcelorMittal, Nucor Corporation, NIPPON STEEL CORPORATION, POSCO, Baosteel Group Corporation, JFE Steel Corporation, thyssenkrupp, Cleveland-Cliffs Inc., Tata Steel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Oriented Electrical Steel Market Shifts & Advancements
Digital twin modeling of annealing furnaces is compressing development cycles for new magnetic grades. Material informatics platforms now predict core loss from alloy composition before physical trials.
Ultra-thin 0.15 mm and 0.20 mm cold-rolled non-oriented grades is rewriting the performance ceiling for high-frequency inverter motors. Tier 1 automotive suppliers in Germany and Japan specify these gauges for 800V electric vehicle platforms operating above 10,000 RPM. The shift is compressing demand for legacy 0.50 mm construction grades in passenger vehicle applications.
REACH Annex XVII restrictions on hexavalent chromium are forcing coating chemistry transitions across European mill networks. C6 chrome-free organic varnishes now dominate new product development, though punch tool wear rates and welding compatibility remain unresolved. Japanese mills lead in hybrid inorganic-organic systems that balance environmental compliance with manufacturing throughput.
Buyer consolidation among electric vehicle drivetrain integrators is concentrating procurement leverage with fewer laminations suppliers. Direct mill relationships are displacing traditional steel service centers for automotive-grade volumes. The shift is most visible in China's Yangtze River Delta, where CATL and BYD subsidiaries negotiate long-term offtake agreements with dedicated annealing line capacity.
Global Non-Oriented Electrical Steel Market Segmentation
Non-oriented electrical steel procurement hinges on magnetic performance specifications that vary sharply across motor classes, frequency regimes, and environmental compliance tiers. Buyers segment supply by gauge thickness, silicon content, and coating chemistry before negotiating volume commitments.
Product Type:
Cost tier determines sourcing strategy, with cold-rolled grades commanding premium positioning against commodity hot-rolled alternatives.
- Cold Rolled:Thinner gauges deliver sub-2.0 W/kg core losses through precise thickness control and optimized silicon distribution. German and Japanese automotive suppliers specify 0.20-0.35 mm cold-rolled laminations for 800V traction motors in high-speed inverter drives.
- Hot Rolled:Thicker sections serve heavy industrial motors where efficiency standards permit higher losses. Chinese mills in Hebei and Shandong dominate volume output for construction equipment and pump manufacturers seeking lower unit costs.
- Grain Oriented:Domain-refined structures optimize magnetic flux alignment for transformer cores above 10 MVA capacity. Indian utilities specify these grades for distribution infrastructure expansion.
- Coated Steel:Organic and inorganic insulations prevent interlaminar eddy currents in stacked cores. REACH Annex XVII compliance now mandates chrome-free formulations across European mill networks.
- Annealed Steel:Continuous annealing lines in Japan and South Korea deliver isotropic magnetic properties through precise temperature-atmosphere control. Hydrogen-annealing retrofits attract preferential grid access under China's dual carbon goals.
Volume sits with Cold Rolled; growth tilts toward Annealed Steel.
Application:
End-use performance requirements split procurement between efficiency-critical automotive traction and cost-sensitive industrial drives.
- Electric Motors:IE4 efficiency mandates under the EU Ecodesign Directive pull premium-grade silicon steel across German and Italian manufacturing bases. Thinner laminations reduce eddy current losses in variable-speed applications.
- Magnetic Sensors:Ultra-thin 0.10 mm grades enable precision motion control in German and Japanese robotics clusters. Resolver and encoder cores demand tight dimensional tolerances and consistent magnetic permeability.
- Generators:Wind turbine OEMs in Denmark and Spain specify high-silicon grades for direct-drive permanent magnet machines. Offshore installations prioritize corrosion-resistant coatings.
- Transformers:Distribution utilities in India and Brazil balance non-oriented penetration against grain-oriented substitution in units above 10 MVA. Core loss certification drives material selection.
- Inverters:Power electronics manufacturers source specialized laminations for filtering chokes and inductor cores. High-frequency operation above 10 kHz favors amorphous metal competition.
Electric Motors capture the deepest margin pool; Magnetic Sensors are expanding most quickly.
End User Industry:
Customer type dictates volume scale and certification burden, with automotive and renewable energy buyers enforcing the strictest material traceability.
- Renewable Energy:Wind and solar inverter manufacturers in China and Germany negotiate long-term offtake agreements for certified high-efficiency grades. Domestic content requirements under India's PLI scheme redirect procurement toward locally anneled output.
- Heavy Machinery:Construction and mining equipment OEMs prioritize punchability and tool life over marginal efficiency gains. Mills in the US Midwest serve this segment with legacy coating chemistries.
- Consumer Electronics:Small motor manufacturers in China's Pearl River Delta specify standard-grade laminations for appliances and power tools. Price sensitivity limits silicon content to 1-2% ranges.
- Rail Transport:Traction motor rebuilders in France and Japan require proven fatigue resistance under mechanical vibration. Historical supplier relationships dominate procurement.
- Aerospace:Auxiliary power units and fuel pumps demand extreme reliability with minimal weight penalty. Qualification timelines extend 18-24 months for new heat approvals.
Heavy Machinery anchors volume demand; Renewable Energy shows the steepest expansion trajectory.
Coating Type:
Regulatory compliance timelines differentiate coating selection, with environmental mandates forcing chemistry transitions ahead of performance optimization.
- Organic:C6 chrome-free varnishes now dominate European new product development under REACH Annex XVII. Punch tool wear rates and welding compatibility remain unresolved technical barriers.
- Inorganic:Phosphate-based systems offer thermal stability for high-temperature motor applications. Japanese mills lead in hybrid inorganic-organic formulations balancing compliance with manufacturing throughput.
- Phosphate:Traditional conversion coatings retain cost advantage for industrial motor segments with less stringent insulation requirements. Chinese mills supply phosphate-coated grades across Southeast Asian manufacturing corridors.
- Nickel:Electrodeposited layers provide superior corrosion resistance for marine and offshore wind applications. Higher material costs limit penetration to premium segments.
- Silicon:Vapor-deposited silicon dioxide enables ultra-thin insulation for high-frequency magnetic components. Specialized annealing lines in South Korea commercialize these grades for robotics sensor cores.
Phosphate coatings retain volume leadership; Organic formulations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor global non-oriented electrical steel manufacturing, hosting over 60% of high-grade continuous annealing capacity and feeding automotive laminations to CATL and BYD subsidiaries across the Yangtze River Delta.
China
Provincial energy intensity targets in Jiangsu and Shandong reward mills deploying hydrogen-annealing retrofits with preferential grid access and carbon credit allocations under dual carbon goals. SAMR enforces GB standards certifying every heat against tiered efficiency bands. The Yangtze River Delta concentrates dedicated annealing line capacity serving long-term offtake agreements with electric vehicle drivetrain integrators.
Germany
IE4 efficiency mandates under the EU Ecodesign Directive pull premium-grade silicon steel across German and Italian manufacturing bases for industrial motors above 0.75 kW. ECHA's REACH Annex XVII restricts hexavalent chromium in coating chemistries, forcing C6 chrome-free varnish transitions. The Ruhr industrial corridor hosts integrated mills supplying automotive-grade laminations to domestic traction motor manufacturers.
Japan
Advanced continuous annealing lines in Nagoya and Kansai regions deliver 6.5% silicon grades with sub-2.0 W/kg core losses at competitive gauge thickness. METI oversees JIS standards alignment with IEC 60404-8-4 certification protocols. Precision motion control clusters in Osaka and Nagoya specify ultra-thin 0.10 mm laminations for robotics resolver and encoder cores.
United States
EPA energy efficiency mandates dictate core loss ceilings for industrial motor imports and domestic production. Mills in the Midwest serve heavy machinery OEMs prioritizing punchability and tool life over marginal efficiency gains. Legacy coating chemistry conversion lags European timelines due to fragmented regulatory pressure across state jurisdictions.
India
Domestic content requirements under the Production Linked Incentive scheme create captive demand for locally annealed non-oriented grades in high-efficiency motor manufacturing. BIS certification aligns with IEC efficiency banding for export market access. Gujarat and Maharashtra industrial corridors attract annealing line investments to serve wind turbine OEMs and automotive laminations suppliers.
Global Non-Oriented Electrical Steel Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and coating chemistry compliance. The supplier base concentrates around integrated steel mills with captive silicon supply and continuous annealing assets, while smaller electric furnace operators serve construction-grade segments. Three archetypes dominate: automotive-certification leaders with dedicated EV laminations lines, industrial-grade volume producers serving pump and compressor OEMs, and specialty annealers targeting robotics sensor cores. Competitive moves center on hydrogen-annealing retrofits for carbon credit access and direct mill relationships displacing steel service centers.
Among integrated European mills, ArcelorMittal and thyssenkrupp occupy positions spanning automotive-grade certification and industrial volume tiers. East Asian producers exemplify the technology-leading archetype, with NIPPON STEEL CORPORATION and POSCO anchoring advanced continuous annealing output for high-frequency inverter motor applications. These named entities represent the geographic and capability clustering that defines competitive positioning rather than discrete strategic actions.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nucor Corporation |
| NIPPON STEEL CORPORATION |
| POSCO |
| Baosteel Group Corporation |
| JFE Steel Corporation |
| thyssenkrupp |
| Cleveland-Cliffs Inc. |
| Tata Steel |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between IEC 60404-8-4 premium tiers and uncertified commodity grades manifests in both pricing premiums and supply chain routing, with automotive laminations commanding dedicated annealing line access while industrial motors flow through spot-market channels.
Pricing Analysis
Value-based pricing anchored to core loss performance and motor efficiency outcomes dominates contract negotiations, with sub-2.0 W/kg grades securing long-term offtake premiums. Price differentiation separates automotive-certification leaders from industrial-grade volume producers through silicon content and coating chemistry compliance. Cost compression in commodity hot-rolled segments is intensifying because Chinese mills in Hebei and Shandong are expanding output. Heavy machinery OEMs in the US Midwest exhibit highest price sensitivity, while German automotive suppliers prioritize magnetic performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with East Asian annealing capacity concentration, where over 60% of high-grade continuous annealing lines operate in China, Japan, and South Korea. Raw material dependencies draw from ferrosilicon smelters in Chinese provinces, Norwegian natural gas for European hydrogen-annealing retrofits, and specialized coating chemistries from Japanese chemical suppliers. Supply chain risk centers on tariff exposure for automotive laminations crossing Pacific trade routes. Distribution runs through direct mill relationships displacing traditional steel service centers, particularly in China's Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase where hydrogen-annealing retrofits and ultra-thin gauge capabilities are displacing legacy natural gas-fired batch annealing and standard 0.50 mm construction grades.
For Market Incumbents: Anchor market position through backward integration into ferrosilicon supply and dedicated annealing line capacity additions in Jiangsu and Zhejiang provinces. Defend against emerging specialty annealers targeting robotics sensor cores by accelerating IEC 60404-8-4 certification timelines and locking automotive OEMs into multi-year laminations agreements. For New Entrants and Emerging Players: The price-point gap between premium automotive-grade and economy industrial-grade creates entry space for mid-tier certification players. Target India's PLI scheme beneficiaries in Gujarat and Maharashtra industrial corridors, where domestic content requirements redirect procurement from imports. Pursue toll-annealing partnerships with underutilized Chinese mill capacity as the go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with hydrogen-annealing retrofit leaders given China's dual carbon goals allocating preferential grid access and carbon credits. Long-term viability favors integrated mills with captive silicon supply and continuous annealing assets over electric furnace operators. Watch provincial energy intensity target enforcement in Jiangsu and Shandong as the inflection signal for capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Annealing Retrofit Deployment | China's SAMR ties preferential grid access to carbon intensity reductions in Jiangsu and Shandong mills. |
| Direct Mill Relationship Formation | CATL and BYD subsidiaries in the Yangtze River Delta bypass service centers for automotive laminations volume. |
| C6 Chrome-Free Coating Conversion | ECHA's REACH Annex XVII mandates chemistry transitions across European mill networks before market release. |
| Ultra-Thin Gauge Capacity Addition | German and Japanese Tier 1 suppliers specify 0.15-0.20 mm grades for 800V electric vehicle platforms. |
| Domestic Annealing Investment | India's PLI scheme for high-efficiency motors creates captive demand in Gujarat and Maharashtra corridors. |
Research Methodology
Independent corroboration across continuous annealing line operators, automotive laminations procurement executives, and industrial motor OEMs underwrites the qualitative findings. Primary interviews with plant managers at integrated steel mills, procurement leads at German and Japanese Tier 1 suppliers, and technical R&D directors at coating chemistry specialists combined with secondary validation from SEC filings, customs and trade data, and IEC certification registries. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across product grades and end-use applications.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, with segmentation dimensions spanning gauge thickness tiers, silicon content bands, coating chemistry compliance levels, and end-use industry clusters. CAGRs derive from rolling average momentum in electric vehicle motor procurement and efficiency mandate implementation timelines. Core loss certification lead times and ferrosilicon price volatility curves feed uncertainty bands into the modeling framework.
Inputs from annealing line operators and automotive procurement executives were available through the study window; gaps in real-time coating chemistry conversion cost data introduce uncertainty bands around margin projections. Forecasts reflect assumptions on regulatory tightening trajectories under the EU Ecodesign Directive and China's dual carbon goals, with substitution risk from grain-oriented grades in large transformers representing a material revision factor. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Rare Earth Magnet Market
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Global Soft Magnetic Alloys Market
Magnetic Materials
Asia-Pacific Magnet Wire Market
Magnetic Materials
High Purity Carbonyl Iron Powder (CIP) Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
Europe Copper Magnetic Wire Market
Magnetic Materials
Magnetic Filter Market
Magnetic Materials
High Performance Permanent Magnet Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
Sintered Soft Magnetic Material Market
Magnetic Materials
Flux Field Directional Material Market