
 Thermal Spray Materials Market | 2026-2036
Thermal Spray Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Spray Materials Market Outlook
REACH is rebalancing the cost-of-entry calculus for European thermal spray feedstock suppliers, forcing reformulation of legacy powder chemistries to eliminate restricted substances. Höganäs AB leverages its integrated atomization capabilities to control purity from ore to finished powder. Kennametal Inc. anchors North American supply through captive tungsten carbide production and specialized HVOF-grade formulations. OC Oerlikon Management AG competes across the full technology stack, from wire arc to plasma spray systems and consumables.
Thermal spray materials encompass engineered powders, wires, and rods deposited as molten or semi-molten particles onto substrates to create protective coatings with thicknesses typically ranging from 50 microns to several millimeters. These materials—formulated from ceramics such as yttria-stabilized zirconia, metals including nickel and cobalt, alloys, and composites—primarily serve to impart wear resistance, thermal insulation, corrosion protection, and dimensional restoration to industrial components. Ceramics dominate aerospace turbine applications where thermal barrier coatings must withstand gas-path temperatures exceeding 1,200°C, while HVOF-deposited tungsten carbide-cobalt composites command premium positioning in oil & gas downhole tooling for extreme abrasion resistance. Cold spray technology, though still emerging in commercial scale, is attracting R&D investment for temperature-sensitive substrates in medical implant coatings.
The EPA enforces stringent occupational exposure limits for hexavalent chromium and cobalt particulates during thermal spray operations, directly shaping shop-floor ventilation investments and PPE protocols across US repair facilities. EMA medical device regulations and EU AI Act supply-chain traceability requirements are converging to demand batch-level documentation for implant-grade coatings, tightening compliance burdens for European service providers. Stakeholders must monitor how evolving F-Gas Regulation phase-down schedules affect plasma spray process gas availability and pricing, as this will determine technology migration timelines and capital allocation between atmospheric and controlled-environment deposition systems.
Market Dynamics
Aerospace engine OEMs are extending thermal barrier coating programs to compress maintenance intervals, forcing feedstock suppliers to certify new powder chemistries under tightening emissions and purity mandates across multiple jurisdictions.
Growth Catalysts
- REACH compliance deadlines:European powder formulators are reformulating legacy chemistries to eliminate restricted substances, creating certified-supplier premiums for compliant feedstock.
- Turbine repair clusters:Germany's industrial heartland concentrates demand from both power generation and aviation MRO facilities, anchoring regional consumption of yttria-stabilized zirconia.
- HVOF-grade tungsten carbide:Oil and gas downhole tooling specifications are hardening toward extreme abrasion resistance, pulling specialized composite formulations through the supply chain.
Market Restraints
- Tungsten supply concentration:Captive production of carbide feedstock concentrates among limited North American and Chinese suppliers, exposing buyers to geopolitical disruption.
- Hexavalent chromium exposure limits:EPA occupational standards mandate costly ventilation upgrades and PPE protocols across US repair facilities, elevating operational overhead.
- Plasma spray gas dependency:F-Gas Regulation phase-down schedules threaten argon and helium availability, compressing process economics for atmospheric deposition systems.
Strategic Opportunities
- Medical implant coatings:Cold spray technology is attracting R&D investment for temperature-sensitive substrates, opening orthopedic and dental applications previously closed to thermal methods.
- EU AI Act traceability:Batch-level documentation mandates for implant-grade coatings create compliance-service revenue streams for European providers with integrated quality systems.
- Automotive cylinder bore repair:Thermal spray alternatives to cast iron liners are penetrating high-performance engine rebuild channels, displacing traditional sleeving.
Industry Challenges
- Plasma spray technician certification:Compressed training pipelines struggle to replace retiring specialists proficient in parameter optimization for aerospace-grade deposition.
- Multi-standard quality systems:Simultaneous ISO, NADCAP, and customer-specific audits elongate qualification timelines for new feedstock entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Spray Materials Market |
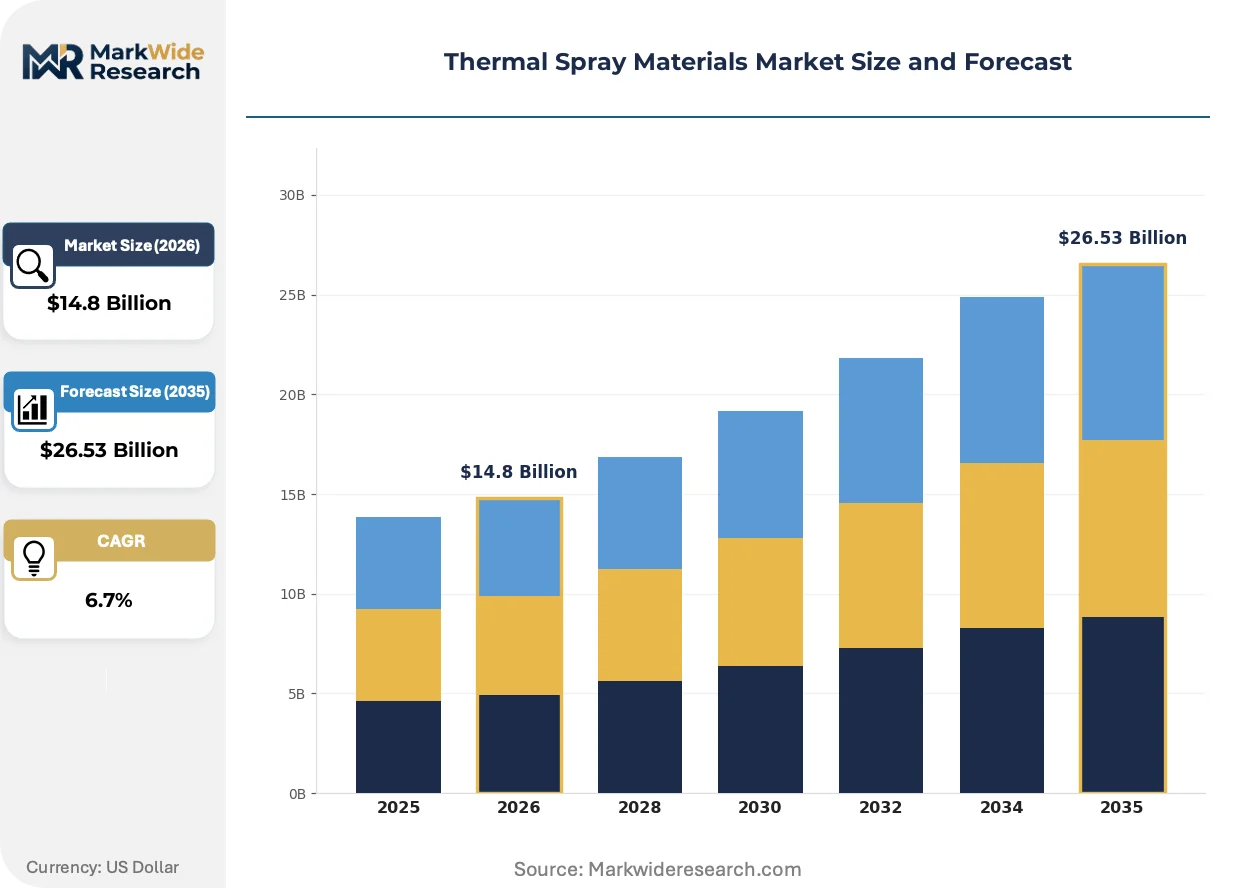
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Ceramics, Metals, Alloys, Composites Application: Aerospace, Automotive, Oil & Gas, Medical Technology: Flame Spray, Plasma Spray, HVOF, Cold Spray End User: Manufacturers, Repair Shops, OEMs, Service Providers |
| Companies Covered | Höganäs AB, OC Oerlikon Management AG, Kennametal Inc., Sandvik AB, Linde PLC, H.C. Starck GmbH, Praxair Surface Technologies, Bodycote, Chromalloy Gas Turbine LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Spray Materials Market Strategic Shifts
Process gas economics and substrate temperature sensitivity are bifurcating equipment investment strategies, with cold spray systems absorbing capital previously allocated to traditional thermal platforms.
Cold spray technology is absorbing R&D attention for depositing metals and alloys without melting, preserving substrate microstructure critical for medical implants and electronics. Orthopedic device manufacturers in Switzerland and Germany are piloting titanium and copper deposition for antimicrobial surfaces. The technology is absorbing market share from low-temperature HVOF applications where heat-affected zones previously restricted adoption.
EPA enforcement of hexavalent chromium and cobalt particulate limits is reshaping shop-floor infrastructure across US repair networks. Facilities must install engineered ventilation and real-time monitoring to maintain OSHA compliance during spray operations. Aviation MRO providers in Georgia, Ohio, and California are consolidating deposition activities into purpose-built cells to contain exposure risks.
Buyer consolidation among tier-one aerospace OEMs is compressing supplier qualification cycles and unbundling after-sales powder supply from equipment contracts. Engine manufacturers now specify feedstock chemistry and morphology independent of original system vendors, opening second-source opportunities for specialized atomizers. This pattern is most visible in the US Southeast and Germany, where turbine assembly and overhaul activities concentrate.
Thermal Spray Materials Market Segmentation
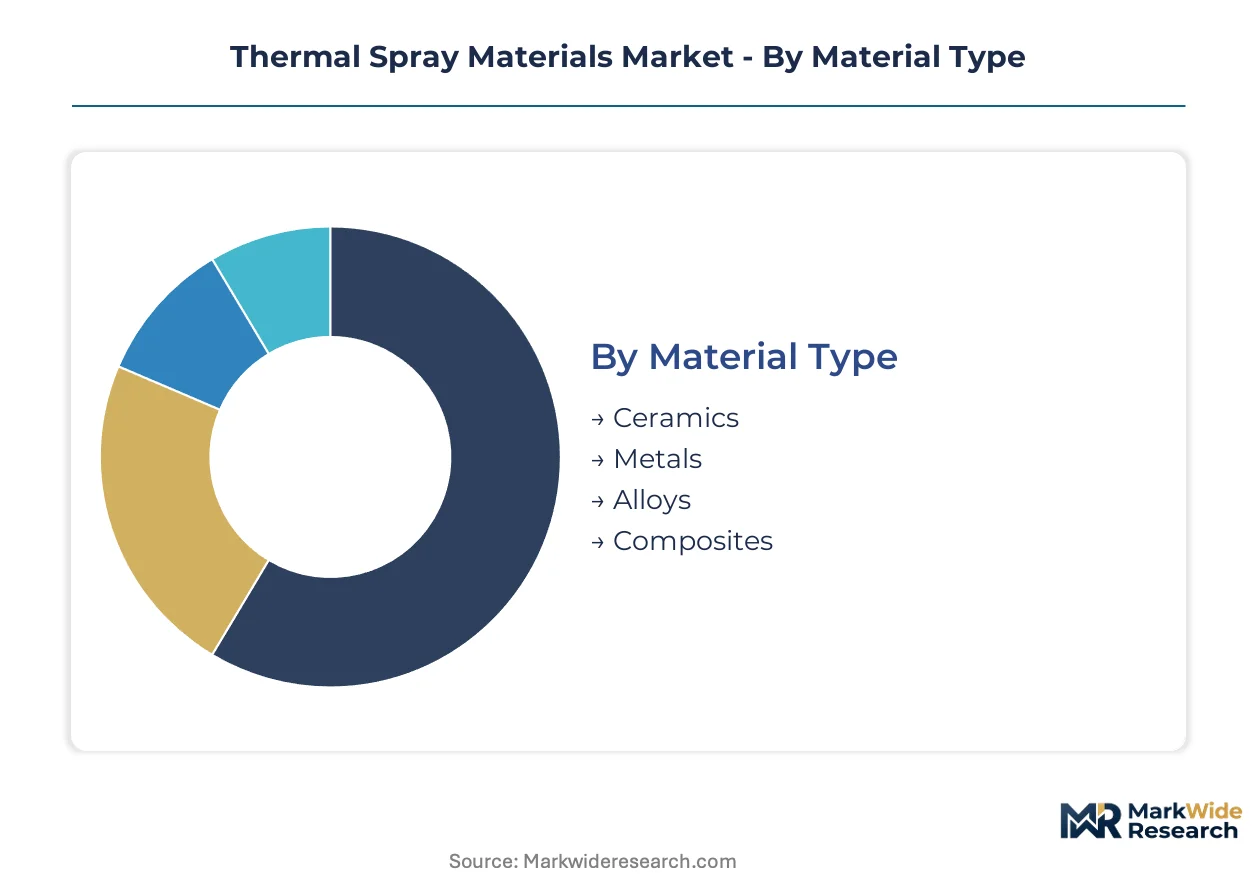
Feedstock chemistry and deposition technology dictate capital allocation patterns across the thermal spray value chain. Powder atomization equipment, plasma spray systems, and regulatory compliance infrastructure each impose distinct upfront burdens that reshape competitive positioning by segment.
Material Type:
Ceramic powder production demands the heaviest capital commitment, with spray-drying towers and controlled-atmosphere sintering furnaces requiring eight-figure investments per production line.
- Ceramics:Yttria-stabilized zirconia formulations dominate aerospace thermal barrier applications, with gas turbine OEMs in Germany and the US Southeast specifying exacting phase purity standards. REACH-mandated reformulation of stabilizer chemistries is compressing qualified supplier lists and elevating certified-feedstock premiums.
- Metals:Pure nickel, cobalt, and aluminum wires serve as bond coats and sacrificial corrosion barriers across marine and chemical processing infrastructure. Wire-arc spray systems in US Gulf Coast repair facilities consume tonnage volumes for offshore platform maintenance cycles.
- Alloys:Nickel-chromium and cobalt-chromium formulations balance oxidation resistance with mechanical toughness for land-based turbine hot-section components.
- Composites:Tungsten carbide-cobalt cermets command specialized HVOF-grade atomization protocols for oil and gas downhole tooling.
Most installed capacity flows through Ceramics. Expansion is steepest in Composites.
Application:
Volume concentration and margin structure diverge sharply across end-use sectors, with aerospace qualification timelines stretching 18-36 months versus automotive repair cycles measured in weeks.
- Aerospace:Engine OEMs and tier-one MRO providers specify thermal barrier coatings for high-pressure turbine blades and combustor liners, with NADCAP-accredited facilities in Georgia, Ohio, and Bavaria anchoring regional demand clusters. EPA hexavalent chromium exposure limits are forcing ventilation upgrades across US repair networks.
- Automotive:Cylinder bore thermal spray alternatives to cast iron liners are penetrating high-performance engine rebuild channels, with German and Japanese motorsport specialists driving formulation refinement for aluminum substrate compatibility.
- Oil & Gas:Downhole drilling and completion tools require extreme abrasion resistance from HVOF-deposited carbide composites, with specifications hardening toward longer service intervals in unconventional shale plays.
- Medical:Cold spray titanium and copper deposition for antimicrobial orthopedic implants is attracting Swiss and German device manufacturer pilot programs, with EU AI Act batch-traceability mandates tightening documentation burdens.
Aerospace commands the dominant revenue share. Medical applications are climbing the fastest.
Technology:
Process gas economics and substrate temperature sensitivity are bifurcating equipment investment strategies, with cold spray systems absorbing capital previously allocated to traditional thermal platforms.
- Flame Spray:Combustion-driven wire and powder deposition remains the lowest-cost entry point for general corrosion protection, with manual torch operations dominating field repair scenarios where portability outweighs precision requirements.
- Plasma Spray:Arc-generated plasma jets achieve temperatures exceeding 15,000°C for ceramic deposition, though F-Gas Regulation phase-down schedules threaten argon and helium availability across European facilities.
- HVOF:Kerosene-oxygen combustion produces dense, low-oxide metallic and cermet coatings for wear-critical components, with captive tungsten carbide supply chains concentrating among North American and Chinese feedstock producers.
- Cold Spray:Supersonic particle impact deposits metals without melting, preserving substrate microstructure for temperature-sensitive medical implants and electronics substrates.
HVOF retains the largest installed base. Cold spray is gaining share fastest.
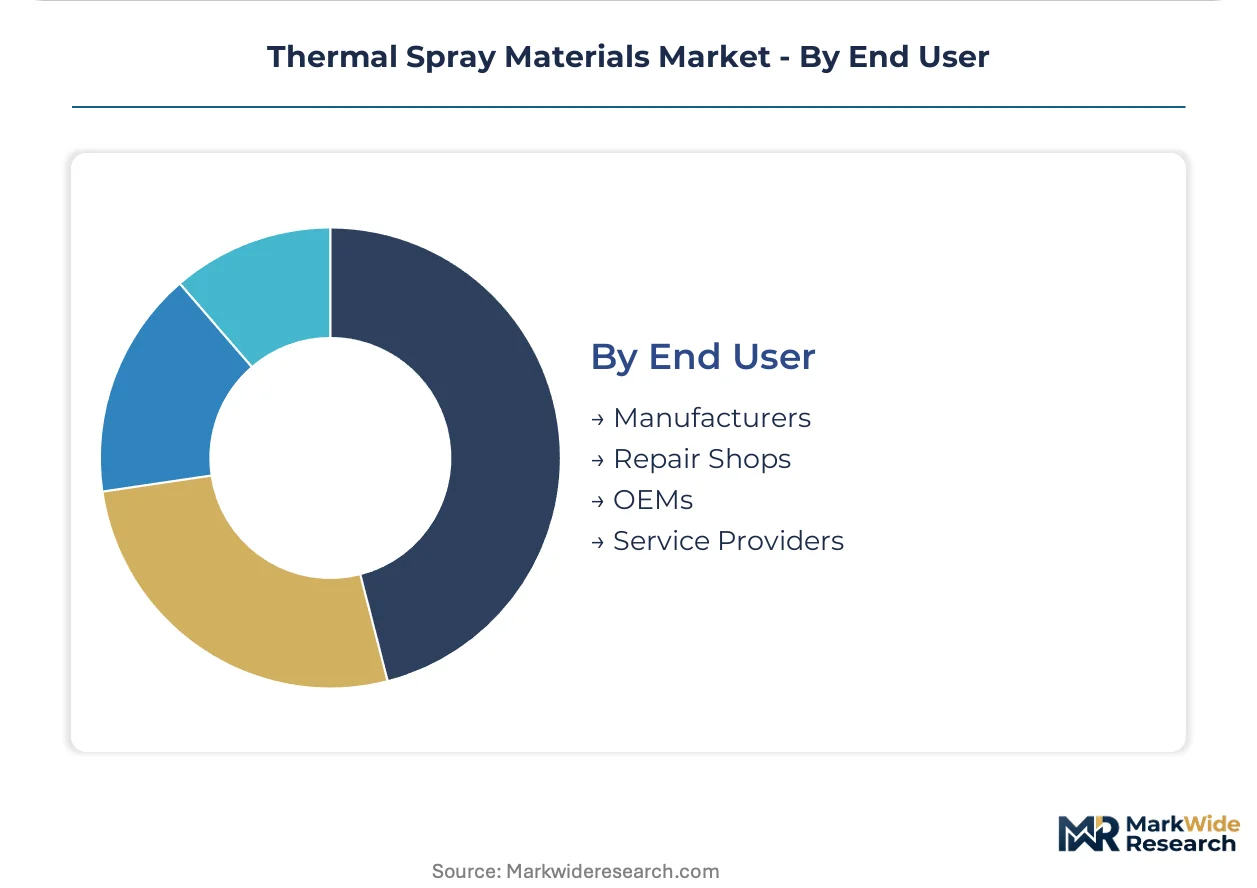
End User:
Procurement authority and technical specification control vary dramatically across customer types, with OEMs increasingly unbundling feedstock supply from original equipment contracts.
- Manufacturers:Original component producers specify coatings during new-build cycles, with aerospace engine makers in the US Southeast and Germany now mandating powder chemistry independent of system vendors.
- Repair Shops:Independent MRO facilities face compressed qualification timelines as tier-one OEMs consolidate approved supplier lists, with multi-standard audits elongating certification for new feedstock entrants.
- OEMs:Equipment manufacturers compete across integrated system-and-consumables offerings, though buyer consolidation is forcing unbundling of after-sales powder supply.
- Service Providers:Specialized coating houses with integrated quality systems are capturing compliance-service revenue streams from EU AI Act traceability mandates for implant-grade deposition.
Manufacturers direct the largest volume flows. Service providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermal spray technology originated in Switzerland during the early 20th century with Schoop's metal spraying patents, then scaled through German industrial adoption for turbine repair. The industry's geographic footprint now reflects concentrated aerospace, automotive, and energy clusters across five key countries.
United States
Georgia, Ohio, and California anchor aviation MRO demand for thermal barrier coatings on high-pressure turbine blades. EPA hexavalent chromium exposure limits are forcing ventilation upgrades across repair networks. The US Southeast concentrates engine assembly and overhaul activities, with NADCAP-accredited facilities driving yttria-stabilized zirconia consumption.
Germany
Bavaria and North Rhine-Westphalia host turbine repair clusters serving both power generation and aviation MRO. REACH compliance deadlines are compressing qualified supplier lists for reformulated powder chemistries. The country's industrial heartland anchors regional consumption of aerospace-grade feedstock.
China
Captive tungsten carbide production concentrates among domestic suppliers serving oil and gas downhole tooling specifications. The national environmental regulator is tightening occupational exposure standards for spray operations. Yangtze River Delta manufacturing hubs are absorbing HVOF-grade composite formulations for wear-critical components.
Switzerland
Orthopedic device manufacturers in Basel and Zurich are piloting cold spray titanium deposition for temperature-sensitive implants. Swissmedic and EU AI Act batch-traceability mandates are tightening documentation burdens for implant-grade coatings. The country's precision engineering heritage supports R&D investment in supersonic particle impact systems.
Japan
METI industrial technology programs are accelerating adoption of thermal spray alternatives to cast iron cylinder liners in high-performance automotive rebuilds. Nagoya and Osaka automotive clusters are driving formulation refinement for aluminum substrate compatibility. Domestic OEMs now specify feedstock chemistry independent of original system vendors.
Thermal Spray Materials Market Competitive Environment
The competitive structure tilts toward integrated powder atomizers with captive ore-to-finished capabilities. Three tiers have crystallized: multinational materials conglomerates with integrated atomization, specialized carbide producers with captive tungsten supply, and regional coating service houses with compliance-service revenue streams. Consolidation pressure is intensifying through OEM unbundling of after-sales powder supply from equipment contracts and multi-standard audit elongation for new feedstock entrants.
Among Swedish-integrated powder specialists, Höganäs AB exemplifies the ore-to-finished archetype with controlled-atmosphere atomization capabilities. OC Oerlikon Management AG, a Swiss conglomerate, occupies a position spanning wire arc through plasma spray systems and consumables. Kennametal Inc., a US-based manufacturer, anchors the captive carbide tier through in-house tungsten production and specialized HVOF-grade formulations.
| Leading Market Players |
|---|
| Höganäs AB |
| OC Oerlikon Management AG |
| Kennametal Inc. |
| Sandvik AB |
| Linde PLC |
| H.C. Starck GmbH |
| Praxair Surface Technologies |
| Bodycote |
| Chromalloy Gas Turbine LLC |
| Others |
Value Chain & Pricing Dynamics
REACH compliance deadlines in Europe gate qualified supply and premium-tier pricing access, forcing powder formulators to absorb reformulation costs while certified suppliers capture feedstock premiums from aerospace OEMs with unbargainable purity specifications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment. NADCAP-accredited feedstock commands substantial premiums from aviation MRO providers, while automotive repair shops negotiate standard-tier ceramics for cylinder bore applications. Cost compression in economy-grade wire products is intensifying because Chinese tungsten carbide producers are expanding HVOF-grade capacity. Tier-one aerospace OEMs exhibit the lowest price sensitivity, whereas independent coating service providers face margin pressure from multi-standard audit costs.
Supply Chain Analysis
Freight costs for argon and helium shipments from Middle Eastern and North African sources are elevating plasma spray operational economics across European facilities. Captive powder atomization concentrates in Sweden, Germany, and the United States, with tungsten carbide feedstock anchored in North American and Chinese supplier networks. Supply chains rest on ore-grade tungsten, yttria stabilizers, and cobalt binder metals. Single-source vulnerability concentrates in Chinese tungsten carbide production for oil and gas specifications. Distribution runs through direct OEM contracts, specialized distributor networks, and integrated coating service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal spray materials function as a stable compounder, with aerospace engine lifecycle extension programs delivering steady feedstock demand regardless of macroeconomic volatility.
For Market Incumbents: Deepen captive atomization capabilities to defend against OEM unbundling of powder supply from equipment contracts. Expand NADCAP-accredited capacity in Georgia and Bavaria to capture thermal barrier coating demand from concentrated turbine MRO clusters. Prioritize REACH-compliant reformulation pipelines to maintain qualified-supplier status as European purity mandates tighten. For New Entrants and Emerging Players: The price-point gap between premium NADCAP-certified feedstock and economy-grade wire products opens white-space in automotive cylinder bore repair channels. Target German and Japanese motorsport specialists with aluminum-compatible ceramic formulations for high-performance engine rebuilds. Enter through cold spray technology partnerships with Swiss orthopedic device manufacturers piloting antimicrobial titanium deposition. For Investors and Strategic Acquirers: Valuations sit cheapest among regional coating service houses with integrated quality systems and EU AI Act traceability infrastructure. The five-to-ten year viability thesis rests on medical implant coating expansion and automotive thermal spray penetration. Watch cold spray equipment adoption rates as the inflection signal for technology migration away from traditional thermal platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ore-Grade Tungsten | Kennametal and Chinese suppliers control captive carbide feedstock, insulating margins from commodity volatility. |
| REACH-Compliant Powder Reformulation | Höganäs AB leverages controlled-atmosphere atomization to eliminate restricted substances before certification deadlines. |
| Cold Spray Technology Licensing | Swiss device manufacturers pilot supersonic particle impact systems for temperature-sensitive orthopedic implants. |
| NADCAP Accreditation Expansion | Georgia and Ohio aviation MRO facilities consolidate deposition cells to meet EPA hexavalent chromium exposure limits. |
| EU AI Act Traceability Infrastructure | German service providers capture compliance-service revenue from batch-level documentation mandates for implant-grade coatings. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with powder metallurgy executives, thermal spray equipment engineers, aviation MRO procurement managers, and orthopedic device regulatory affairs leads. Secondary validation draws from SEC 10-K filings of listed materials companies, ECHA REACH registration databases, NADCAP accreditation directories, and customs trade data for tungsten carbide imports. Bottom-up feedstock volume estimates triangulate against top-down aerospace and automotive coating consumption models.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include material chemistry, deposition technology, application sector, and end-user procurement authority. CAGRs derive from fitted growth curves incorporating OEM thermal barrier coating program extensions, F-Gas Regulation phase-down impacts on plasma spray economics, and cold spray technology adoption rates in medical applications. Industry-specific inputs capture REACH compliance cost pass-through and tungsten supply concentration risk premiums.
Caveats apply where F-Gas Regulation enforcement intensity or Chinese environmental regulator action on spray operations could materially shift the outlook. Forecasts reflect assumptions about aerospace build rates and automotive thermal spray penetration that remain sensitive to OEM platform decisions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Europe Advanced Building Materials Market
Advanced Materials
Silver Nanowires Market
Advanced Materials
Advanced Carbon Materials Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
Curable Materials Market
Advanced Materials
Lab-Grown Rough Diamond Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
Transparent Wood Market
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
Cathode Active Material Market
Advanced Materials
Si-C Anode Material Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
Cubic Boron Nitrates Market
Advanced Materials
Natural Single Crystal Diamond Market
Advanced Materials
Global Advanced Materials Market
Advanced Materials
2D Materials Market