
 Aluminum Welding Wires Market | 2026-2036
Aluminum Welding Wires Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Welding Wires Market Analysis
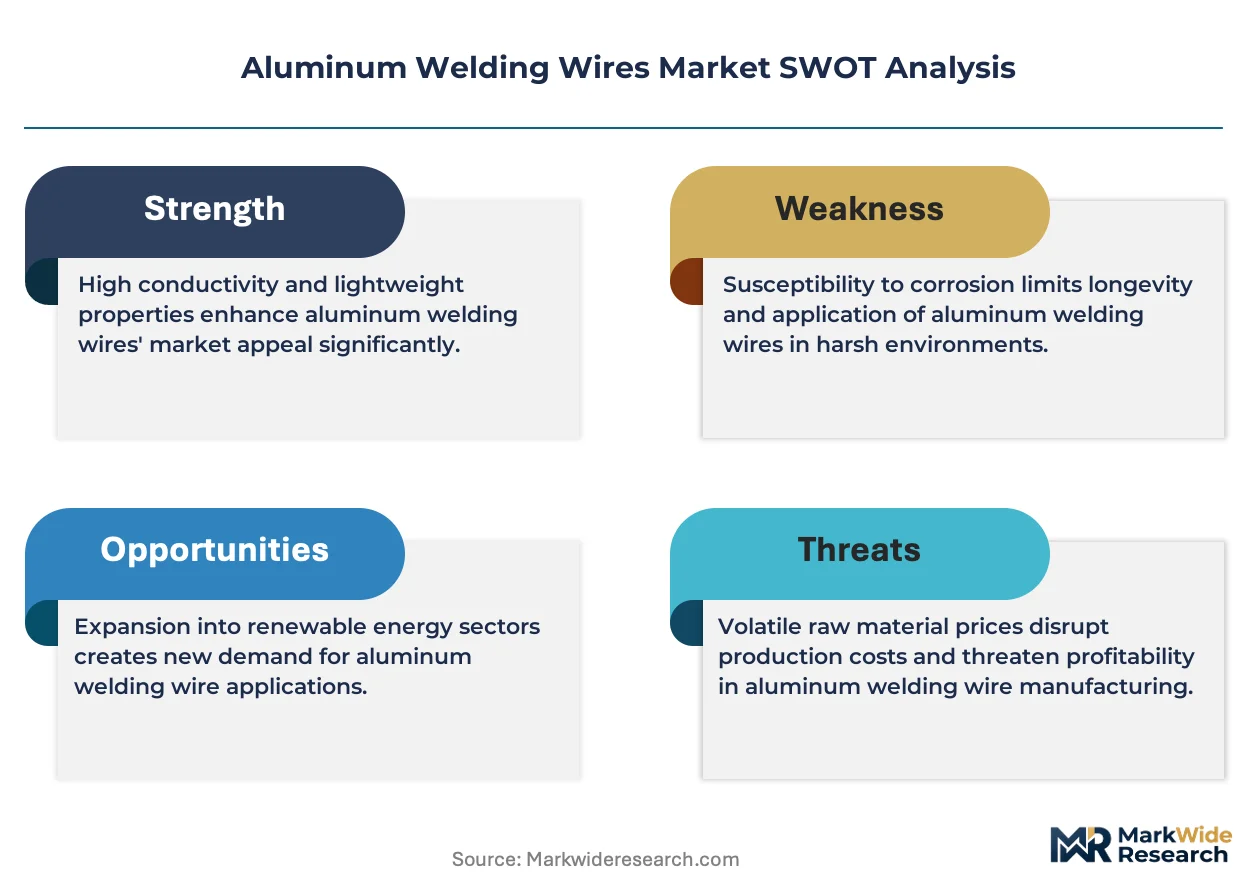
The divergence between premium and commodity tiers in aluminum welding wires is hardening as automotive OEMs impose stricter porosity and crack-resistance specifications on ER5356 and ER4047 grades while construction contractors prioritize cost-per-kilogram metrics on standard alloys. ESAB leverages its captive R&D pipeline in solid-wire chemistry to sustain specification leadership for aerospace MIG applications. Lincoln Electric anchors North American distribution through integrated welding equipment bundling, while ITW competes via consumables-to-systems compatibility across automotive production lines.
Aluminum welding wires are filler metals composed primarily of aluminum or aluminum alloys, typically supplied in diameters from 0.8 mm to 1.6 mm for automated and semi-automated fusion welding processes, designed to match or exceed the mechanical properties of base metals in structural joints. The ER5356 product type leads volume due to its magnesium content and superior corrosion resistance in marine environments, while ER4047 dominates margin pools through its silicon-rich formulation favored in brazing and thin-sheet automotive repair. MIG technology occupies the largest application share given throughput advantages in high-volume manufacturing, though laser welding is gaining traction in battery tray fabrication where heat input precision reduces distortion on 6xxx series extrusions.
China's SAMR enforces GB standards on wire chemistry and surface cleanliness that effectively restrict market access for uncertified imports, while the EU's REACH and F-Gas Regulation indirectly shape demand by accelerating aluminum substitution for copper in HVAC heat exchangers requiring compatible welding consumables. The US EPA and OSHA maintain exposure limits on welding fume constituents that push fabricators toward low-fume wire formulations and enhanced ventilation systems. Stakeholders must monitor how evolving dual carbon targets across Chinese provinces and European carbon border adjustments recalibrate sourcing economics for primary aluminum feedstock.
Market Dynamics
Automotive lightweighting mandates are compressing specification tolerances for aluminum welding wires, forcing consumables suppliers to recalibrate chemistry control and surface preparation protocols to meet OEM porosity thresholds on 6xxx series extrusions.
Growth Catalysts
- EU F-Gas Regulation:HVAC manufacturers accelerate aluminum heat exchanger deployment to replace copper coils, expanding demand for silicon-rich ER4047 wires in brazing applications across German and Italian production facilities.
- Battery tray fabrication:Electric vehicle platforms require laser-MIG hybrid welding of 6xxx series aluminum extrusions, pulling precision wire formulations into gigafactory supply chains near Shanghai and Austin industrial clusters.
- Marine hull construction:Shipbuilders in South Korea and Japan specify ER5356 grades for magnesium-alloy corrosion resistance in saltwater environments, sustaining volume pull through Hyundai Heavy Industries and Imabari Shipbuilding procurement programs.
Market Restraints
- Primary aluminum feedstock volatility:LME price swings for alumina and smelter-grade metal transmit directly into wire manufacturing cost structures, compressing margin buffers for non-integrated producers.
- GB standards enforcement:China's SAMR certification requirements for surface cleanliness and chemistry traceability create non-tariff barriers for uncertified import streams, fragmenting supply access.
- Copper-aluminum hybrid joints:Dissimilar metal welding limitations in electrical busbar applications preserve copper dominance in high-current transmission segments, capping aluminum wire penetration.
Strategic Opportunities
- Indian PLI scheme:Production-linked incentives for automotive and renewable energy manufacturing are attracting wire producers to Gujarat and Tamil Nadu corridors to localize supply for Tata Motors and Reliance Industries fabrication networks.
- Robotic welding integration:Collaborative robot deployments in small-batch job shops create demand for precision-spooled wire formats with enhanced cast and helix control, opening mid-market segments previously served by manual GMAW.
- Carbon border adjustments:EU CBAM implementation on embedded emissions in aluminum products incentivizes low-carbon primary metal sourcing, rewarding wire suppliers with verified renewable energy smelter partnerships.
Industry Challenges
- Welding engineer scarcity:Qualified technicians capable of programming pulse-MIG parameters for thin-gauge aluminum autobody repair remain concentrated in OEM training centers, constraining independent service network expansion.
- Multi-certification timelines:Simultaneous pursuit of AWS, ISO, and GB approvals for new alloy formulations extends product launch cycles by 18-24 months, delaying revenue recognition on R&D investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Welding Wires Market |
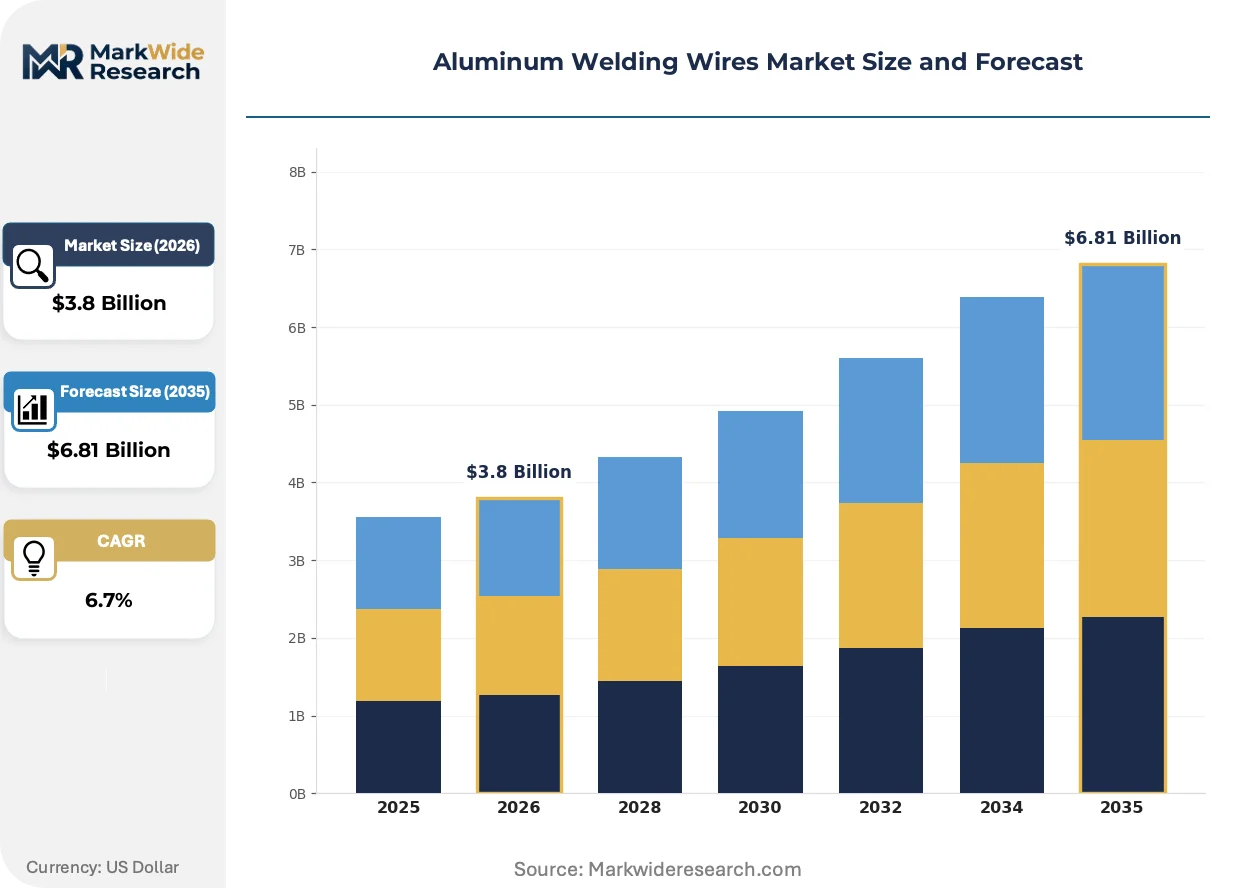
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ER4047, ER5356, ER4045, ER4043 Application: Aerospace, Automotive, Marine, Construction End User: Manufacturers, Fabricators, Repair Shops, Contractors Technology: MIG, TIG, Resistance, Laser |
| Companies Covered | ESAB (Colfax Corporation), Lincoln Electric, ITW, Sumitomo Electric Industries, Drahtwerk ELISENTAL W. Erdmann GmbH & Co., Novametal Group, Air Liquide Welding, EWM AG, Safra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Welding Wires Market Emerging Trajectories
Process automation and regulatory chemistry mandates are converging to redefine how aluminum welding wires are formulated, tested, and deployed across high-specification manufacturing environments.
Pulse-spray transfer variants with digitally controlled waveform modulation are rewriting throughput economics in automotive body-in-white applications. Tier-1 suppliers at BMW and Mercedes-Benz assembly plants have adopted these systems for 1.2 mm ER5183 wire deposition on closure panels. The technology is compressing cycle times while reducing spatter-induced post-weld grinding labor.
REACH authorization requirements on hexavalent chromium surface treatments are compelling wire producers to migrate to boron-based flux coatings and laser-cleaned feedstock. German fabricators serving rail vehicle construction must now document elimination of chrome-passivated wire surfaces to maintain CE marking compliance. The shift is elevating processing costs for commodity-grade producers while creating specification premiums for certified-clean supply.
Consolidated procurement through welding equipment OEMs is displacing independent distributor relationships in North American manufacturing. Lincoln Electric and ITW are bundling wire supply contracts with power source leases and preventive maintenance agreements, capturing multi-year spend commitments from Caterpillar and John Deere fabrication operations. The model is most visible in Midwest agricultural equipment production, where capital-constrained shops prioritize predictable operating expenditures over spot-market wire purchasing.
Aluminum Welding Wires Market Segmentation
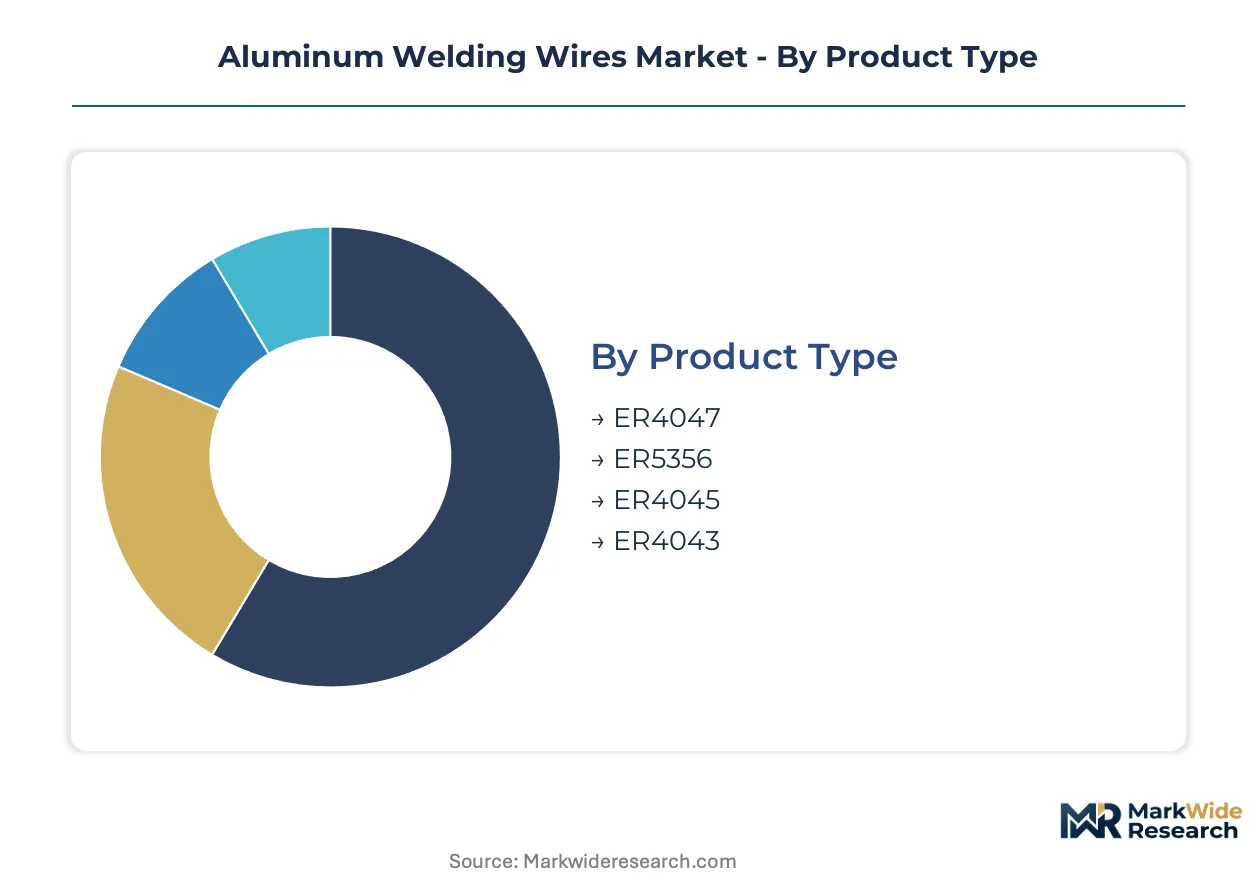
Aluminum welding wire demand fragments across chemistry grades, fabrication technologies, and end-user sophistication levels. Specification divergence between automotive OEMs and construction contractors drives tiered product positioning and channel strategies.
Product Type:
Volume concentrates in magnesium-bearing alloys while silicon-rich formulations command specification premiums.
- ER5356:Magnesium-alloyed wire delivering superior corrosion resistance and tensile strength in saltwater environments. Shipbuilders in South Korea and Japan specify this grade for hull fabrication, with procurement flowing through Hyundai Heavy Industries and Imabari Shipbuilding programs.
- ER4047:Silicon-rich formulation optimized for brazing applications and thin-sheet automotive repair. HVAC manufacturers deploy this grade for aluminum heat exchanger assembly, accelerated by EU F-Gas Regulation mandates phasing down copper coil systems.
- ER4045:Moderate silicon content bridging brazing and structural welding applications. General fabricators favor this grade for mixed-alloy repair work where chemistry matching is secondary to cost efficiency.
- ER4043:Standard silicon alloy serving general-purpose construction and maintenance welding. Contractors prioritize this grade for non-critical joints where cost-per-kilogram dominates selection criteria.
Mature deployment sits with ER5356 in marine and structural applications. Newer deployment is concentrated in ER4047 for thermal management and battery fabrication.
Application:
Specification stringency separates aerospace and automotive from construction and marine procurement.
- Automotive:Body-in-white and battery tray fabrication demand pulse-MIG compatibility with 6xxx series extrusions. BMW and Mercedes-Benz assembly plants specify ER5183 variants for closure panel welding with digitally controlled waveform modulation.
- Aerospace:Airframe structural joints require AWS D17.1 certification and lot-traceable chemistry. ESAB and Lincoln Electric dominate supply through captive R&D pipelines and integrated equipment bundling.
- Marine:Saltwater corrosion resistance drives ER5356 specification for hull and superstructure fabrication. Procurement concentrates around Shanghai and Guangzhou industrial clusters serving domestic shipbuilding.
- Construction:Infrastructure and architectural metalwork prioritize standard alloys with minimal surface preparation. Cost-per-kilogram metrics override chemistry precision in this segment.
Specification premiums cluster in aerospace and automotive. Volume scale concentrates in construction and marine procurement.
End User:
Technical capability and procurement sophistication determine product format and service requirements.
- Manufacturers:Tier-1 automotive and HVAC producers demand precision-spooled formats with cast and helix control for robotic welding cells. Multi-year supply contracts bundle wire with power source leases and preventive maintenance.
- Fabricators:Job shops serving mixed industries require flexible alloy availability and technical support for parameter optimization. Pulse-MIG programming assistance represents a key service differentiator.
- Repair Shops:Independent automotive service networks source smaller spool formats for thin-gauge autobody work. Welding engineer scarcity constrains expansion beyond OEM-certified training centers.
- Contractors:Construction-focused buyers prioritize distributor availability and price stability over chemistry specialization. Spot-market purchasing dominates this segment.
Integrated supply relationships dominate manufacturer procurement. Transactional purchasing persists among contractors and smaller repair operations.
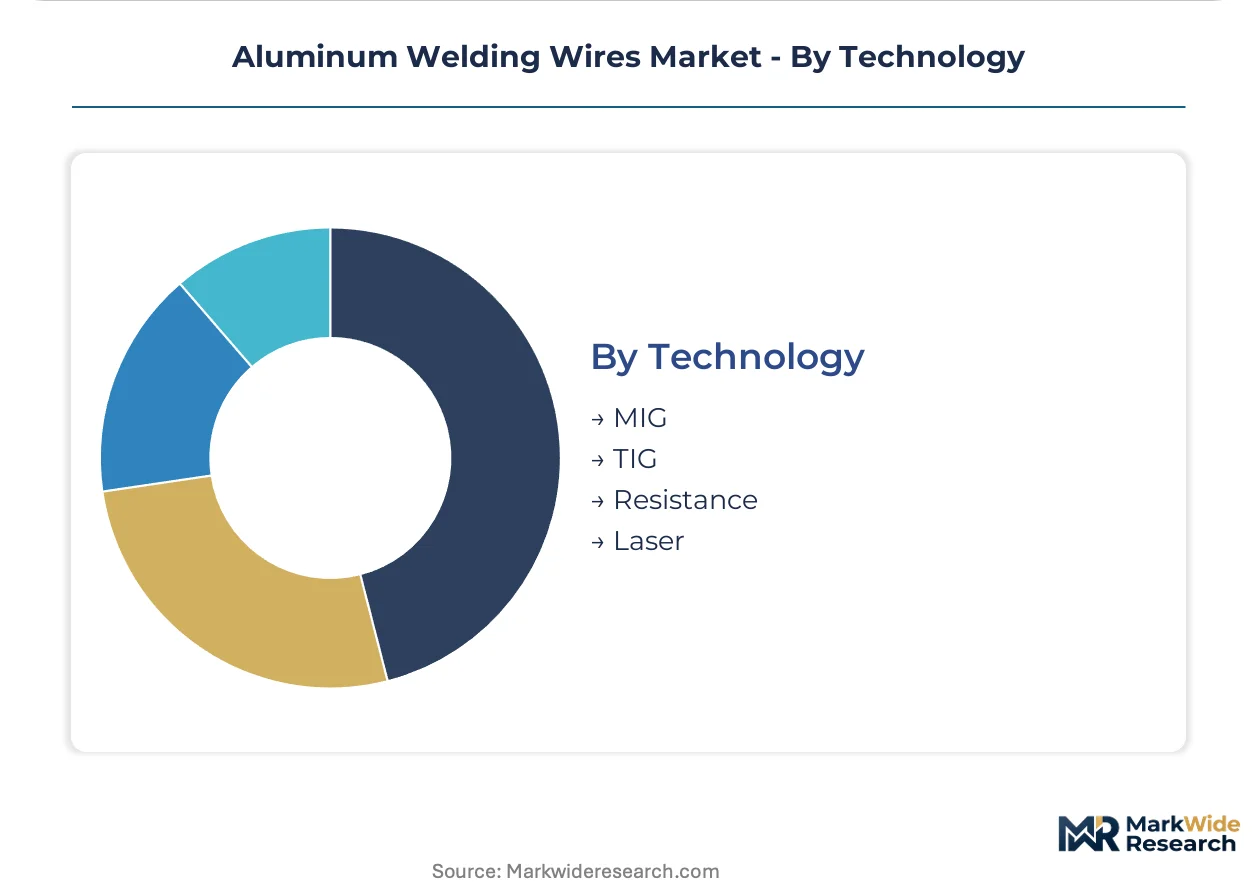
Technology:
Throughput economics and heat input precision drive technology selection across fabrication environments.
- MIG:Gas metal arc welding dominates high-volume manufacturing through deposition rate advantages. Automotive body-in-white applications favor 1.2 mm wire diameters with pulse-spray transfer variants.
- Laser:Battery tray fabrication for electric vehicles requires hybrid laser-MIG systems minimizing distortion on 6xxx series extrusions. Heat input precision justifies capital investment despite higher equipment costs.
- TIG:Tungsten inert gas welding serves aerospace and precision repair applications demanding aesthetic weld profiles. Manual skill requirements limit scalability.
- Resistance:Spot welding persists in sheet metal assembly where joint access permits electrode placement. Limited applicability for aluminum compared to steel fabrication.
Established throughput leadership sits with MIG in automotive mass production. Steepest expansion trajectory belongs to laser hybrid systems for battery platform welding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors global aluminum welding wire demand through its concentration of automotive gigafactories and shipbuilding yards. The Yangtze River Delta corridor processes the highest volume of ER5356 and ER4047 grades for export-oriented manufacturing. Industrial clusters in Guangzhou, Austin, and Stuttgart are pulling precision wire formulations into battery tray and body-in-white supply chains.
China
Automotive lightweighting mandates and marine hull construction drive consumption of magnesium-alloyed wires. SAMR enforces GB standards on surface cleanliness and chemistry traceability that restrict uncertified import access. The Guangzhou industrial cluster hosts fabrication networks supplying BYD and CATL battery platform welding programs.
United States
Electric vehicle battery tray fabrication and agricultural equipment manufacturing sustain demand for pulse-MIG compatible wires. OSHA maintains exposure limits on welding fume constituents that push fabricators toward low-fume formulations. The Austin metro area concentrates Tesla and Rivian gigafactory procurement of laser-MIG hybrid welding consumables.
Germany
HVAC heat exchanger assembly and rail vehicle construction dominate silicon-rich ER4047 consumption. REACH authorization requirements on hexavalent chromium surface treatments compel migration to boron-based flux coatings. The Stuttgart region anchors BMW and Mercedes-Benz body-in-white welding wire specification programs.
Japan
Shipbuilders at Imabari and Mitsubishi Heavy Industries specify ER5356 grades for saltwater corrosion resistance. METI oversees JIS standards alignment with international certification protocols for export markets. The Nagoya industrial corridor concentrates precision aerospace wire demand through Toyota and Subaru supply chains.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries procurement programs sustain marine-grade wire volumes. MFDS and KOSHA regulate welding fume exposure in shipyard environments. The Busan-Ulsan corridor processes the majority of domestic ER5356 consumption for export vessel construction.
Aluminum Welding Wires Market Vendor Landscape
Premium-margin players sit above commodity-margin players across specification stringency and certification depth. The market structures around chemistry control capabilities and captive equipment bundling relationships. Three archetypes dominate: integrated welding equipment OEMs with consumables-to-systems compatibility, standalone wire specialists with alloy formulation expertise, and regional fabricators serving cost-sensitive construction segments. Consolidation pressure operates through multi-year supply contract capture and backward integration into primary aluminum sourcing.
Within the integrated equipment tier, ESAB and Lincoln Electric exemplify specification leadership through captive R&D pipelines and distribution bundling. Novametal Group and Safra occupy positions among European specialists emphasizing alloy chemistry precision. Sumitomo Electric Industries anchors Asian manufacturing scale for automotive and marine procurement programs.
| Leading Market Players |
|---|
| ESAB (Colfax Corporation) |
| Lincoln Electric |
| ITW |
| Sumitomo Electric Industries |
| Drahtwerk ELISENTAL W. Erdmann GmbH & Co. |
| Novametal Group |
| Air Liquide Welding |
| EWM AG |
| Safra |
| Others |
Supply Flow & Price Mechanics
Premium-commodity bifurcation between AWS-certified aerospace wire and standard construction-grade alloys manifests in parallel supply chain configurations: automotive OEMs pay specification premiums for lot-traceable ER5183 with digitally controlled cast and helix, while contractors source ER4043 through spot-market distributors optimizing for freight cost per kilogram. This divergence concentrates procurement power among integrated welding equipment OEMs bundling multi-year supply contracts with power source leases, while fragmenting purchasing across independent job shops.
Pricing Analysis
Throughput-based pricing anchors value capture for precision-spooled formats serving robotic welding cells at BMW and Mercedes-Benz assembly plants, where wire feed consistency directly determines cycle time economics. Price differentiation rests on AWS D17.1 certification tier and surface cleanliness documentation rather than base metal content alone. Cost compression in commodity ER4043 runs through LME-linked alumina volatility and Chinese spot-market oversupply. Tier-1 automotive manufacturers exhibit lowest price sensitivity given qualification lock-in, while independent repair shops face acute margin pressure from welding engineer scarcity and training center concentration.
Supply Chain Analysis
Single-source vulnerability sits with Chinese primary aluminum smelters supplying GB-certified feedstock to Shanghai and Guangzhou industrial clusters, where SAMR traceability requirements effectively exclude uncertified import streams. Raw material dependencies draw from Australian bauxite, Guinean alumina, and domestic Chinese smelter capacity. Tariff exposure on unwrought aluminum shapes from Section 232 and EU CBAM implementation threatens margin buffers for non-integrated wire producers. Distribution runs through welding equipment OEM captive networks in North America and specialist alloy distributors serving European fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aluminum welding wire market sits in a technology-transition phase as laser-MIG hybrid systems displace conventional pulse-MIG in battery tray fabrication, recalibrating specification requirements and equipment bundling economics.
For Market Incumbents: Cement specification leadership by deepening backward integration into low-carbon primary aluminum partnerships ahead of EU CBAM enforcement, while locking in multi-year supply contracts with Tesla and Rivian gigafactory procurement teams. Laser-MIG hybrid qualification requirements threaten traditional MIG wire margins; defend by accelerating R&D in precision-spooled formats with enhanced cast and helix control for collaborative robot deployments. For New Entrants and Emerging Players: Enter via Gujarat and Tamil Nadu corridors under India's PLI scheme, where localized supply for Tata Motors and Reliance Industries fabrication networks remains underdeveloped. Target robotic welding integration in mid-market job shops previously served by manual GMAW, offering pulse-MIG programming assistance as a bundled service differentiator against incumbent distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with European specialists emphasizing alloy chemistry precision given REACH authorization timelines on hexavalent chromium alternatives and boron-based flux coating migration. Long-term viability hinges on verified renewable energy smelter partnerships and GB certification access for Chinese market participation. Watch for SAMR enforcement intensity as the inflection indicator for import-access fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Primary Aluminum | EU CBAM implementation rewards wire suppliers with verified renewable energy smelter partnerships in Iceland and Norway. |
| Robotic Welding Cell Qualification Programs | BMW and Mercedes-Benz assembly plants demand precision-spooled formats with cast and helix control for collaborative robot deployments. |
| Multi-Certification Fast-Track Investment | Simultaneous AWS, ISO, and GB approval pursuit compresses 18-24 month launch cycles for new alloy formulations. |
| Regional Manufacturing Localization | Indian PLI scheme attracts wire producers to Gujarat corridors serving Tata Motors battery platform welding programs. |
| Low-Fume Formulation Development | OSHA exposure limits push fabricators toward enhanced ventilation-compatible wire chemistry and surface preparation protocols. |
Methodological Framework
Trade databases, SAMR certification registries, and SEC filings from welding equipment OEMs formed the secondary backbone, supplemented by customs records tracking ER5356 and ER4047 grade flows through Shanghai and Guangzhou ports. Primary interviews with Tier-1 automotive procurement managers, shipyard welding engineers at Hyundai Heavy Industries, HVAC fabrication technical directors, and distributor channel heads combined with secondary validation. Bottom-up and top-down triangulation cross-checked alloy-grade volume estimates against power source installation data and robotic welding cell deployment metrics.
Bottom-up modeling built from individual country production clusters, grade-level consumption patterns, and technology-specific adoption curves across the analysis window. Segmentation dimensions included chemistry grade, fabrication technology, end-user sophistication tier, and regional regulatory cluster. CAGRs derived from weighted average of historical trajectory and technology substitution elasticity, with laser-MIG hybrid penetration rates and automotive lightweighting mandate intensity as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under LME alumina price volatility extremes and SAMR enforcement discontinuities. Forecasts reflect documented assumptions on GB standard harmonization timelines and EU CBAM scope expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Titanium Sponge Market
Metals
Smelting Chemicals Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Ultrafine Tungsten Wire for Medical Applications Market
Metals
Silver Powder and Flakes Market
Metals
India Steel Market
Metals
Titanium Powder Market
Metals
United States Metal Casting Market
Metals
Medium Carbon Steel Market
Metals
Iron Casting Market
Metals
Copper Foil Market
Metals
North America and Europe Metal Powder Market
Metals
Silver Enamel Market
Metals
Zinc Dust Market
Metals
Transition Metals Market
Metals
Global Oxygen-Free Copper Market