
 Europe Magnet Wire Market | 2026-2036
Europe Magnet Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Magnet Wire Market Foresight
Specialty distributor networks across Central Europe is narrowing as direct OEM procurement gains ground. Elektrisola leverages its enamel-coating expertise to anchor premium supply contracts with German automotive tier ones. Schwering & Hasse Elektrodraht GmbH sustains long-standing relationships with industrial motor manufacturers through customized copper wire formulations. IRCE SpA competes from its Italian manufacturing base by specializing in niche thermal class specifications for renewable energy generators.
Magnet wire is an insulated electrical conductor, typically copper or aluminum, coated with a thin polymer or enamel layer ranging from 0.01 mm to several millimeters in diameter, designed to create electromagnetic fields when energized. Its primary purpose is winding coils in motors, transformers, and inductors where electrical energy converts to mechanical motion or electromagnetic force. Copper wire dominates volume across the Europe Magnet Wire Market due to its superior conductivity and established recycling infrastructure, while aluminum wire captures cost-sensitive applications in large transformers where weight reduction offsets efficiency trade-offs. Specialty alloys command premium positioning in aerospace and high-frequency inductor segments where thermal performance exceeds standard enamel capabilities.
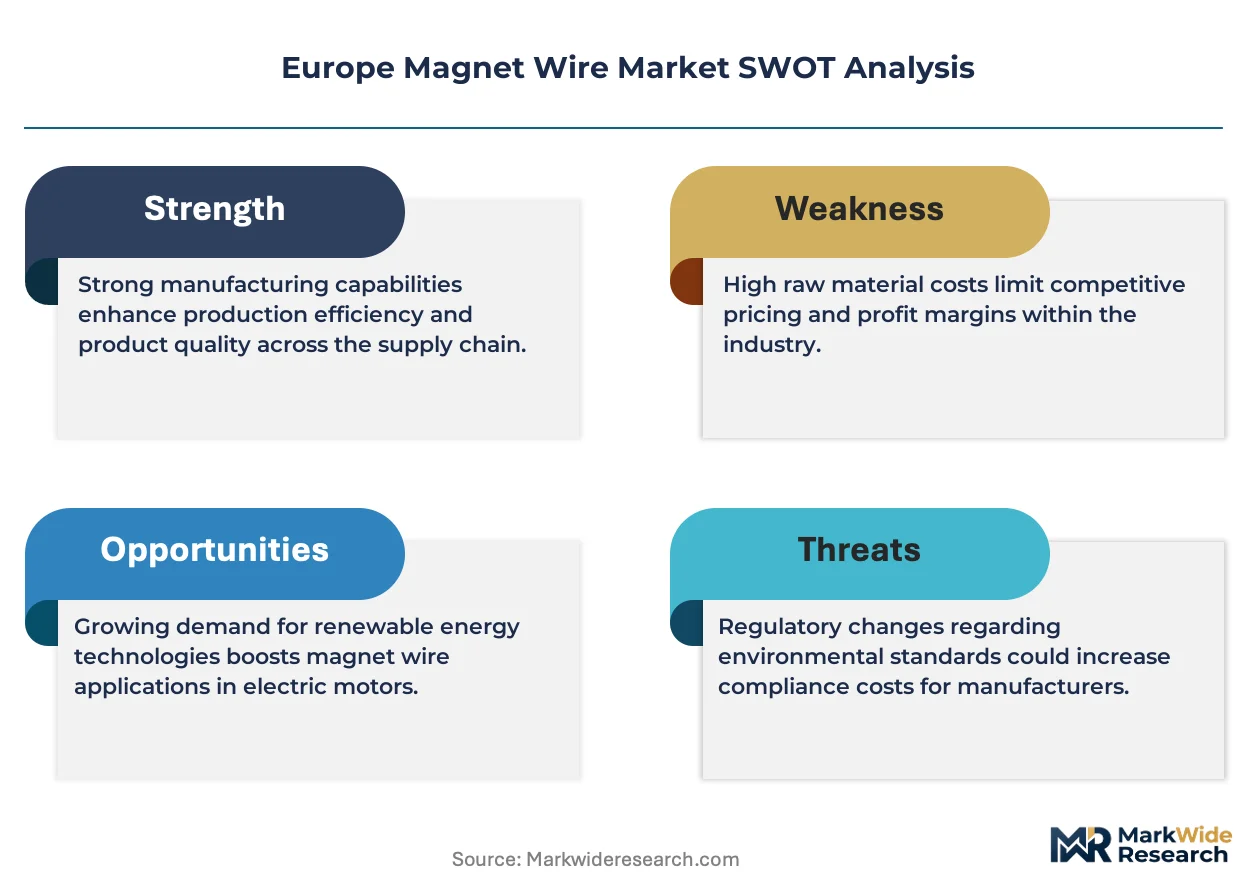
The EU Green Deal and Ecodesign for Sustainable Products Regulation are reshaping material sourcing requirements, with ECHA REACH compliance now mandatory for all insulation chemistries sold within the single market. CE marking under the Low Voltage Directive governs electrical safety certification, while Germany's KBA enforces automotive-specific reliability standards for traction motor windings. Stakeholders must track evolving F-Gas Regulation amendments affecting thermal management systems that determine insulation temperature ratings. The regulatory trajectory favors suppliers with verified circular-economy credentials and in-house polymer chemistry control.
Market Dynamics
Electric vehicle motor manufacturing in Germany is accelerating uptake of high-temperature insulation grades, while the EU Ecodesign for Sustainable Products Regulation tightens material disclosure requirements across the supply chain. This dual pressure from electrification demand and regulatory compliance is compressing supplier qualification timelines and reshaping procurement relationships.
Growth Catalysts
- EU Green Deal implementation:The EU Green Deal mandates circular-economy credentials for industrial components, pulling magnet wire with verified recycling content into premium supply tiers.
- France's electrification infrastructure:Grid modernization and renewable energy generator deployments in France are expanding demand for thermal class specifications above 180°C.
- Polyimide enamel chemistry:Advances in polyimide-based insulation systems enable continuous operating temperatures above 200°C, matching traction motor thermal loads.
Market Restraints
- Copper price volatility:LME copper pricing fluctuations compress margin visibility for wire manufacturers holding 60-90 day raw material inventories.
- Specialty chemical concentration:ECHA REACH compliance requires disclosure of enamel resin formulations, and polymer precursor supply concentrates among German and Belgian chemical producers.
- Aluminum substitution ceiling:Aluminum wire efficiency trade-offs limit penetration in automotive traction motors below 10% of conductor mass despite weight advantages.
Strategic Opportunities
- Poland's industrial corridor:Underpenetrated motor manufacturing capacity in Silesia offers white-space positioning for suppliers with EU-established logistics networks.
- CE marking convergence:The Low Voltage Directive's harmonized safety certification reduces country-by-country approval burdens for cross-border distribution.
- Direct OEM procurement channels:Automotive tier ones are consolidating supplier bases, creating entry points for magnet wire producers with in-house polymer chemistry control.
Industry Challenges
- Polymer chemistry talent scarcity:Formulation expertise for high-temperature enamel systems concentrates among retiring specialists in German industrial regions.
- Automotive qualification timelines:Germany's KBA reliability standards for traction motor windings require 18-24 month validation cycles, locking out new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Magnet Wire Market |
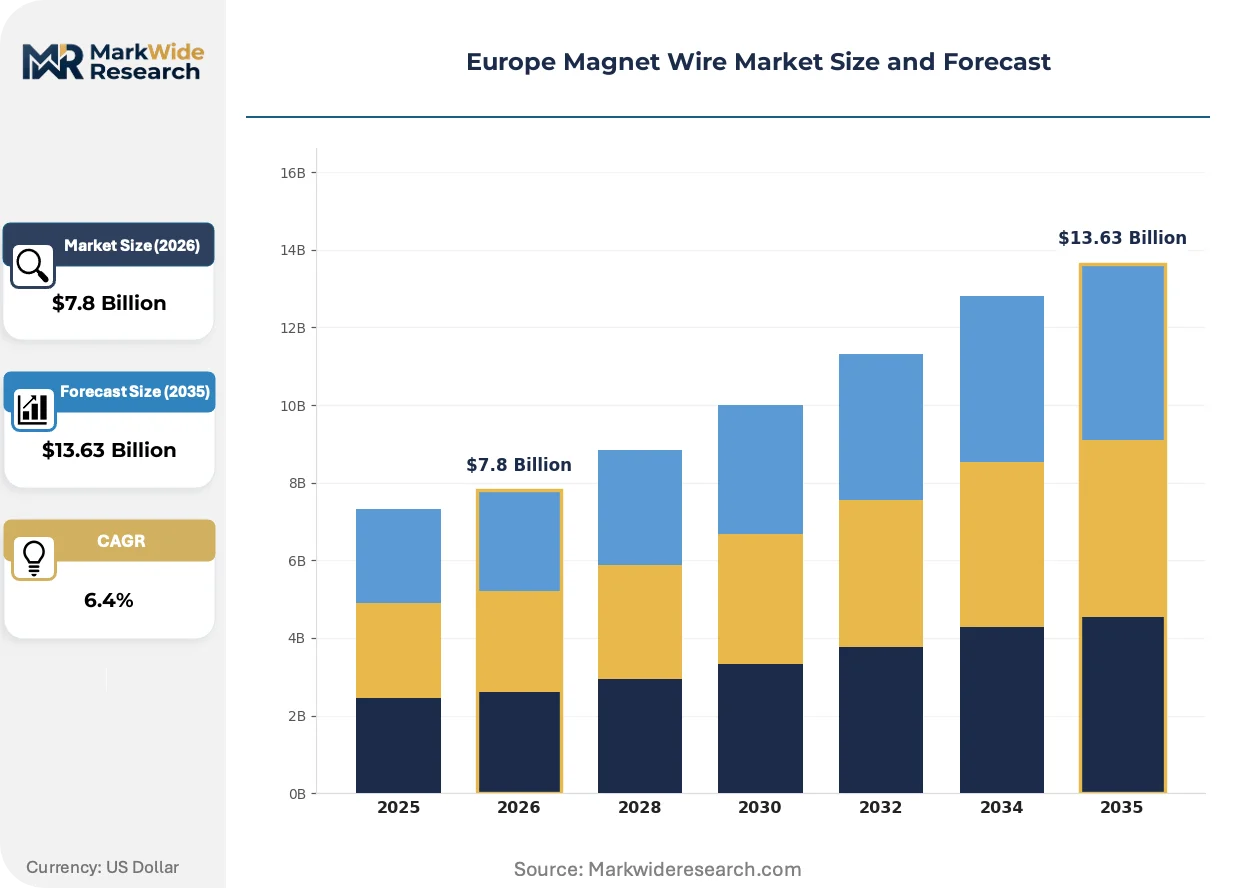
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Wire, Aluminum Wire, Specialty Alloys, Silver Wire Insulation Type: Polyester, Polyamide, Enamel, Thermoplastic, Others Application: Transformers, Electric Motors, Generators, Inductors End User: Automotive, Consumer Electronics, Industrial Equipment, Renewable Energy |
| Companies Covered | Synflex Elektro GmbH, LS Cable & System Ltd., Elektrisola, Furukawa Electric Co., Ltd., Sumitomo Electric Industries, Ltd., IRCE SpA, Von Roll, Superior Essex Inc., Schwering & Hasse Elektrodraht GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Magnet Wire Market Shifts & Advancements
Magnet wire insulation systems are undergoing material substitution as electrification thermal loads exceed legacy enamel capabilities. Three concurrent developments are compressing supplier R&D cycles and redefining competitive positioning.
Polyetherimide enamel formulations are migrating from aerospace niche applications into mainstream automotive traction motors. German OEMs are qualifying these materials for 800V inverter-fed machines operating above 180°C continuous. This migration from conventional polyesterimide systems is enabling smaller conductor cross-sections and higher slot fill factors in compact motor designs.
The F-Gas Regulation amendments are restricting hydrofluorocarbon-based thermal management fluids used in magnet wire manufacturing cooling systems. Industrial consequence includes forced retrofit of enamel curing ovens across Central European production facilities. Motor rewind shops in France and Italy face the steepest compliance costs due to distributed, small-batch equipment footprints.
Specialty distributor networks across Central Europe are narrowing as direct OEM procurement gains ground. German automotive tier ones now specify magnet wire at the platform architecture stage, bypassing traditional component distributors. This concentration is most visible in Stuttgart and Munich industrial corridors, where procurement teams embed supplier engineers into motor design workflows.
Europe Magnet Wire Market Segmentation
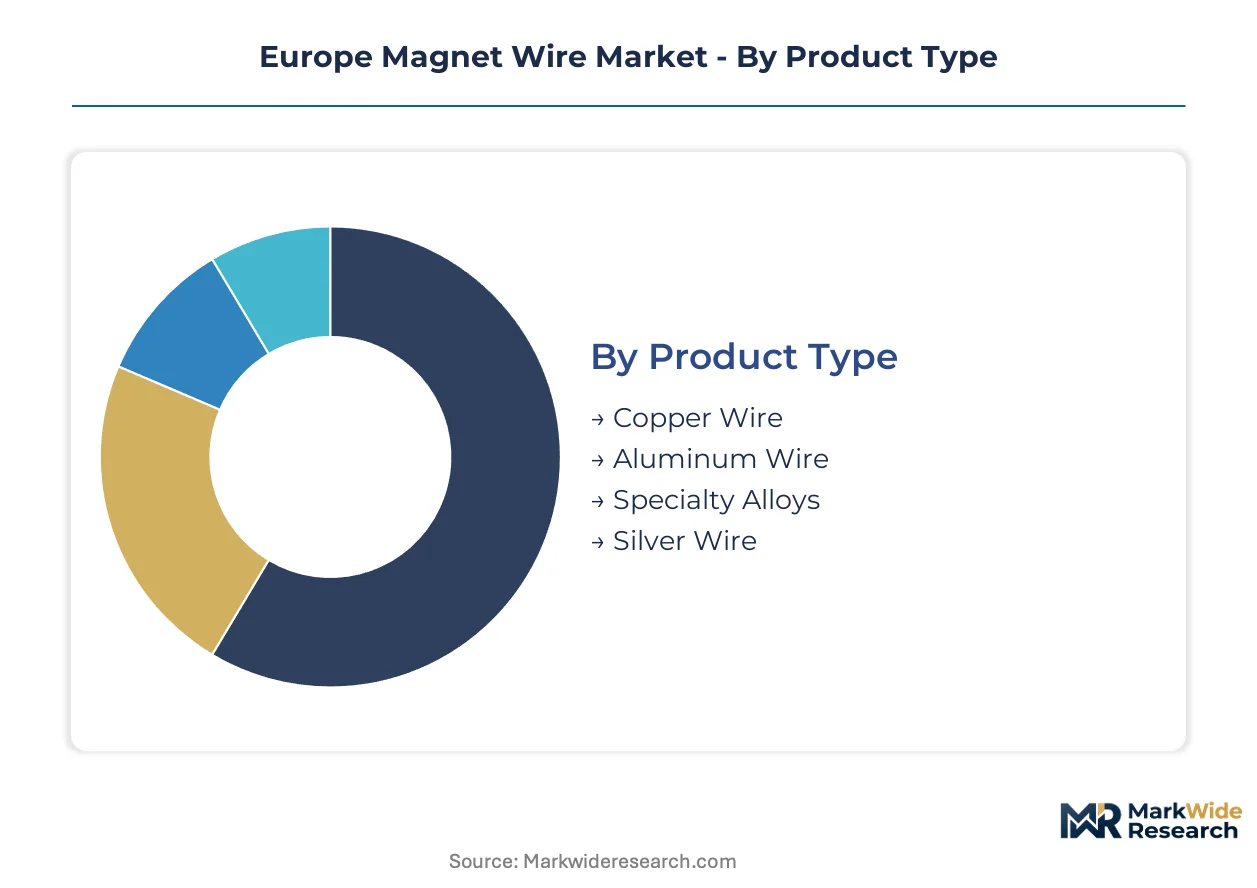
Magnet wire procurement in Europe fragments across conductor chemistry, thermal insulation systems, and end-use thermal loads. Each segmentation axis carries distinct qualification timelines, margin structures, and regulatory exposure that reshape supplier positioning.
Product Type:
After-sales-service intensity varies sharply by conductor base metal, with copper requiring technical support for recycling verification under EU Green Deal mandates while aluminum demands less intensive field engineering.
- Copper Wire:Electrolytic tough pitch copper dominates European volume due to conductivity advantages and established scrap recovery infrastructure. German automotive OEMs specify oxygen-free grades for traction motor windings where KBA reliability standards apply. Demand concentrates in Stuttgart and Munich industrial corridors where direct procurement relationships compress distributor margins.
- Aluminum Wire:Lightweight conductor captures large transformer applications where weight reduction offsets efficiency trade-offs. French grid modernization projects specify aluminum for distribution infrastructure. Polymer chemistry control determines insulation adhesion on aluminum substrates, creating supplier differentiation.
- Specialty Alloys:Copper-nickel and copper-silver formulations serve aerospace and high-frequency inductor segments where thermal performance exceeds standard enamel capabilities.
- Silver Wire:Highest conductivity metal commands niche positioning in cryogenic and medical imaging coil applications with extreme thermal cycling requirements.
Copper wire holds the largest share; momentum sits with specialty alloys as electrification thermal loads intensify.
Insulation Type:
Cost tier separation runs deepest in insulation chemistry, with polyimide-based systems commanding premium positioning against commodity polyester formulations.
- Polyester:Conventional enamel chemistry serves standard industrial motors and distribution transformers with 130°C-155°C thermal class ratings. Polish motor manufacturers in Silesia specify polyester for cost-sensitive applications. ECHA REACH compliance for base resin formulations is mandatory across all EU sales.
- Polyamide:Nylon overcoat systems provide mechanical abrasion resistance for winding operations in high-speed automated coil insertion. Italian generator producers specify dual-coated constructions for renewable energy machines.
- Enamel:Generic term covering modified polyester and polyesterimide base coats that balance cost and thermal performance in general-purpose industrial equipment.
- Thermoplastic:Extruded insulation systems serve specialty applications requiring thick build or specific dielectric properties not achievable with solvent-borne enamels.
- Others:Polyetherimide and polyimide-fluoropolymer hybrids emerging for 800V automotive traction motors operating above 180°C continuous.
Polyester maintains volume leadership; polyetherimide derivatives are climbing the fastest as German OEMs qualify 800V architectures.
Application:
Customer type segmentation separates specification authority between OEM platform teams and aftermarket rewind operations with divergent technical service requirements.
- Transformers:Power and distribution infrastructure applications specify thermal classes based on loading profiles and cooling system design. French RTE grid investments drive demand for 180°C+ insulation in substation equipment. Aluminum substitution ceiling remains highest here due to weight-driven installation economics.
- Electric Motors:Industrial and automotive traction applications impose the most severe thermal cycling and partial discharge exposure. German KBA reliability standards enforce 18-24 month qualification cycles that lock in incumbent suppliers.
- Generators:Wind turbine and hydroelectric machines require specialized formulations for variable frequency drive compatibility and environmental sealing.
- Inductors:High-frequency power electronics and filtering applications demand controlled permeability and minimal core losses from precise conductor geometry.
Electric motors command the greatest revenue concentration; generators are gaining share fastest on renewable energy deployment timelines.
End User:
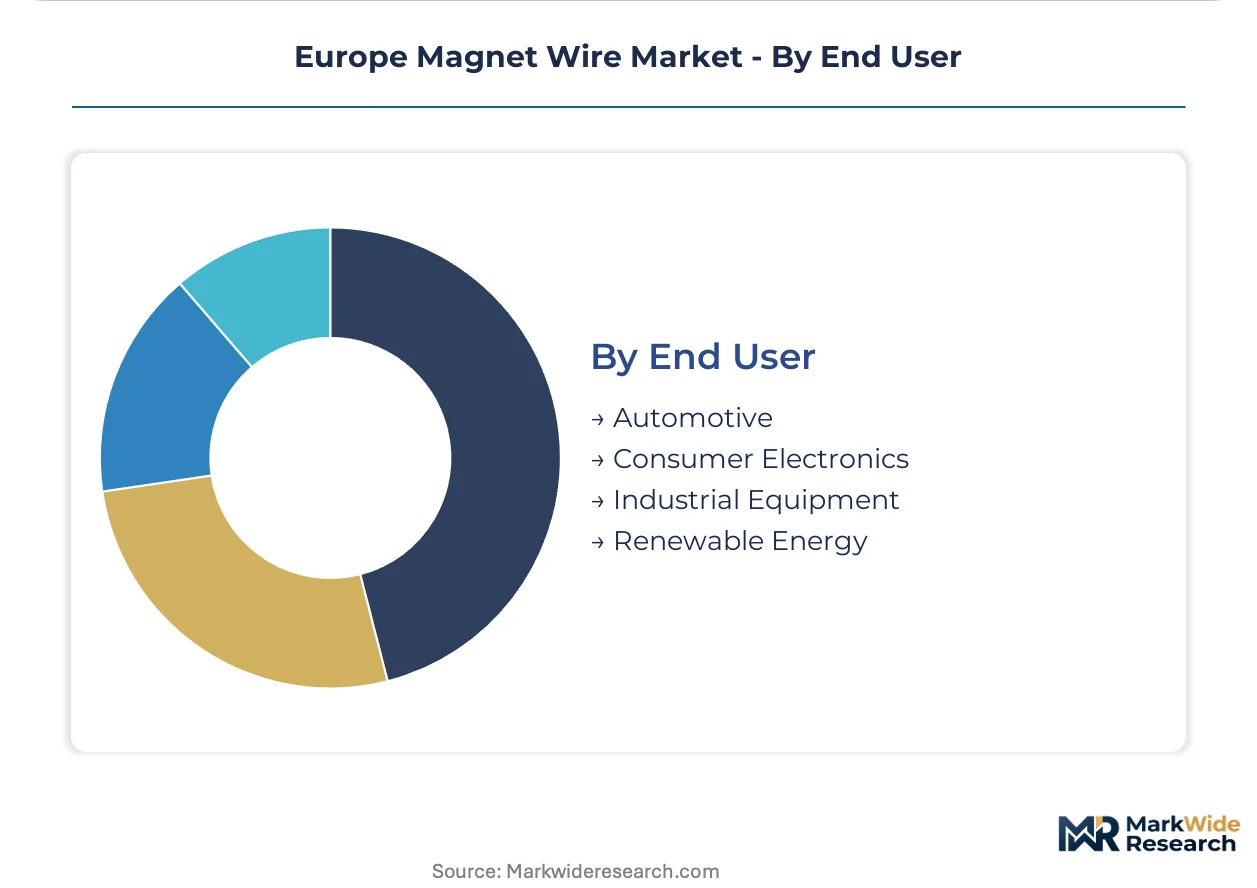
Supply concentration patterns diverge by end-use sector, with automotive procurement consolidating around platform-architecture specifications while industrial equipment retains fragmented distributor channels.
- Automotive:Traction motor manufacturing in Germany anchors premium demand for high-temperature insulation grades. Tier one suppliers embed magnet wire engineers into motor design workflows, bypassing traditional component distribution. F-Gas Regulation amendments force thermal management system redesigns affecting insulation temperature ratings.
- Consumer Electronics:Miniaturization trends drive ultra-fine wire demand with precision layer winding requirements for motors and inductors in portable devices.
- Industrial Equipment:Pump, compressor, and conveyor motor applications sustain broad demand across thermal classes with established rewind shop maintenance channels.
- Renewable Energy:Wind generator and solar inverter manufacturers specify thermal class 200°C+ systems for reliability in remote installations with limited maintenance access.
Automotive represents the largest end-use value pool; renewable energy shows the steepest expansion trajectory on EU Green Deal implementation timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight rail link underwrites Germany's industrial dominance in magnet wire demand, while France's nuclear grid interconnects and Poland's east-west logistics arteries shape sub-regional specialization across the continent.
Germany
Stuttgart and Munich industrial corridors concentrate automotive traction motor manufacturing for 800V architectures. KBA reliability standards enforce 18-24 month supplier qualification cycles that lock in incumbent relationships. Bavaria's motor design workflows now embed magnet wire engineers directly from raw material producers.
France
RTE grid modernization drives demand for 180°C+ thermal class insulation in substation transformers. The country's electrification infrastructure investments pull specialty wire formulations for renewable energy generators. Auvergne-Rhône-Alpes hosts concentrated winding equipment manufacturing serving pan-European distribution.
Italy
IRCE SpA anchors domestic supply from its manufacturing base specializing in niche thermal specifications. Wind turbine generator deployments in southern regions require thermal class 200°C+ systems for remote reliability. Emilia-Romagna's industrial motor sector sustains mid-tier polyester demand through established rewind channels.
Poland
Silesia's underpenetrated motor manufacturing capacity offers white-space positioning for EU-established logistics networks. Cost-sensitive applications specify conventional polyester enamel for industrial equipment. The country's central location enables just-in-time supply to German automotive tier ones.
United Kingdom
Offshore wind generator specifications drive demand for specialized formulations with variable frequency drive compatibility. Midlands industrial corridors retain fragmented distributor channels for pump and compressor motor applications. CE marking convergence under the Low Voltage Directive reduces cross-border approval burdens.
Europe Magnet Wire Market Competitive Landscape
On the supply side, the industry is consolidating around direct OEM procurement relationships that bypass traditional distribution tiers. German automotive tier ones now specify magnet wire at platform architecture stages, compressing qualification timelines and reshaping supplier access. Three archetypes dominate: enamel-coating specialists with polymer chemistry control, diversified cable producers with backward integration into conductor drawing, and regional wire drawers with customized alloy formulations. Capacity expansion and strategic partnerships represent the dominant competitive vectors as electrification thermal loads intensify R&D cycles.
Among Germany-based specialists, Elektrisola and Schwering & Hasse Elektrodraht GmbH exemplify the enamel-coating archetype with long-standing industrial relationships, while IRCE SpA represents Italian-based specialization in niche thermal segments. These three occupy positions spanning premium automotive supply tiers and industrial equipment maintenance channels, with geographic clustering reflecting distinct qualification ecosystems rather than scale-driven consolidation.
| Leading Market Players |
|---|
| Synflex Elektro GmbH |
| LS Cable & System Ltd. |
| Elektrisola |
| Furukawa Electric Co., Ltd. |
| Sumitomo Electric Industries, Ltd. |
| IRCE SpA |
| Von Roll |
| Superior Essex Inc. |
| Schwering & Hasse Elektrodraht GmbH |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine Corridor freight rail link carries enamel resin precursors from Belgian chemical producers to German coating facilities, its cost dynamics compressing margins for wire drawers without captive polymer supply while amplifying price differentiation between integrated and non-integrated suppliers.
Pricing Analysis
Volume-discount tiering structures separate automotive OEM direct contracts from distributor-served industrial accounts. KBA-certified insulation grades command premium positioning against CE-marked industrial equivalents. Cost compression in polyester enamel tiers intensifies as Polish motor manufacturers consolidate procurement. Aftermarket rewind shops exhibit highest price sensitivity; German tier one traction motor programs show lowest.
Supply Chain Analysis
Tariff exposure between EU member states and third-country copper concentrate suppliers dominates supply chain risk planning. Germany, Belgium, and Poland concentrate enamel coating capacity. Raw material flows draw from Chilean copper mines, German petrochemical complexes, and Italian specialty alloy foundries. Single-source vulnerability concentrates in polyimide precursor supply from two Belgian producers. Distribution runs through direct OEM procurement channels for automotive, fragmented distributor networks for industrial equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise for high-temperature enamel systems concentrates among retiring specialists in German industrial regions, constraining competitive replication and acquisition target availability.
For Market Incumbents: Pre-empt polymer chemistry talent scarcity by anchoring relationships with technical universities in Bavaria and Baden-Württemberg. Secure backward integration into polyimide precursor supply through long-term offtake agreements with Belgian chemical producers. Defend against aluminum substitution threats by embedding engineers into Stuttgart OEM platform teams. For New Entrants and Emerging Players: Silesia's underpenetrated motor manufacturing capacity offers white-space positioning for suppliers with EU-established logistics networks and polyester enamel cost structures. Target French RTE grid modernization programs for 180°C+ thermal class qualification. Pursue rewind shop distribution partnerships as entry path before automotive tier one engagement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enamel-coating specialists with in-house polymer chemistry control over diversified cable producers. Five-to-ten year viability hinges on 800V traction motor qualification timelines. Watch KBA certification completion rates as inflection indicator for supplier consolidation momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Chemistry | Captive polyimide precursor supply secures margin visibility against Belgian chemical producer concentration. |
| Direct OEM Procurement Channel Development | Bypassing distributor tiers captures specification authority at Stuttgart and Munich platform architecture stages. |
| High-Temperature Enamel R&D Investment | Polyetherimide formulation capabilities unlock 800V traction motor contracts under KBA reliability standards. |
| Poland Manufacturing Footprint Expansion | Silesia location enables just-in-time supply to German automotive tier ones with cost-competitive polyester production. |
| Circular-Economy Certification Program | EU Green Deal compliance pulls verified recycling content into premium supply tiers above commodity enamel. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with magnet wire procurement managers at German automotive tier ones, enamel coating plant managers in Bavaria, and industrial motor rewind shop operators across France and Italy; and secondary validation against ECHA REACH compliance databases, EU customs trade flows for copper wire and enamel resin categories, and KBA certification registries. Bottom-up segment sizing triangulated with top-down market envelope checks.
Forecast inputs considered thermal class migration rates, 800V traction motor adoption curves, and F-Gas Regulation amendment implementation timelines across the projection horizon. Segmentation dimensions modeled included conductor chemistry, insulation system thermal rating, end-use application, and procurement channel structure. CAGRs derived from volume trajectory analysis against value expansion patterns, with cross-reference to OEM platform production schedules and RTE grid investment disclosures.
Macroeconomic conditions sit as an overlay; deviation in LME copper pricing volatility, Rhine freight rates, or EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions on polymer precursor supply continuity and qualification timeline adherence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
Magnet Wire Market
Magnetic Materials
Global Soft Magnetic Alloys Market
Magnetic Materials
Europe Ferrite Magnet Market
Magnetic Materials
Nanocrystalline Soft Magnetic Material Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Global Iron Powder Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
North America Magnet Wire Market
Magnetic Materials
North America Magnet Market
Magnetic Materials
Magnetic Carbon Nanofoam Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
Ferrofluid Market
Magnetic Materials
Magnetic Filter Market