
 North America Magnet Wire Market | 2026-2036
North America Magnet Wire Market Size, Share, and Industry Trends Forecast 2026-2036
North America Magnet Wire Market Analytics
Aluminum magnet wire is expanding its addressable share in weight-sensitive applications across the North American automotive supply base. Essex Furukawa leverages integrated enameling and drawing operations to control coating consistency for high-frequency inverter-duty motors. Rea Magnet Wire sustains a dense manufacturing footprint across the Midwest and Southeast, anchoring just-in-time supply relationships with domestic OEMs. Superior Essex competes through vertical ownership of copper rod production, insulating its margin structure from LME volatility.
Magnet wire consists of solid or stranded conductor—typically copper or aluminum—overcoated with a thin polymeric insulation layer engineered to withstand thermal, electrical, and mechanical stress in electromagnetic coils. The insulation system, rated by temperature class per NEMA MW 1000, determines slot fill efficiency and operational lifespan in rotating machinery. Copper magnet wire retains dominance across transformer and motor applications where conductivity premium justifies material cost, while aluminum magnet wire captures share in automotive auxiliary systems where mass reduction offsets resistivity trade-offs. Renewable energy end-use represents the fastest-expanding demand pool, driven by generator rewinding cycles and new wind turbine buildouts requiring extended thermal endurance grades.
NHTSA corporate average fuel economy standards, EPA greenhouse gas emissions rules, and NEMA MW 1000 thermal classification protocols collectively dictate insulation chemistry migration and qualification timelines for North American suppliers. The US Inflation Reduction Act domestic content provisions are reshaping sourcing requirements for magnet wire consumed in federally subsidized clean energy and electric vehicle programs. Stakeholders must monitor regulatory alignment between federal procurement rules and state-level manufacturing incentives to secure qualified supplier status in emerging EV and wind energy supply chains.
Market Dynamics
Electric vehicle motor winding programs are concentrating demand among magnet wire producers capable of meeting NHTSA thermal performance mandates and EPA emissions standards. This demand compression is restructuring supplier relationships across the US Southeast automotive cluster.
Growth Catalysts
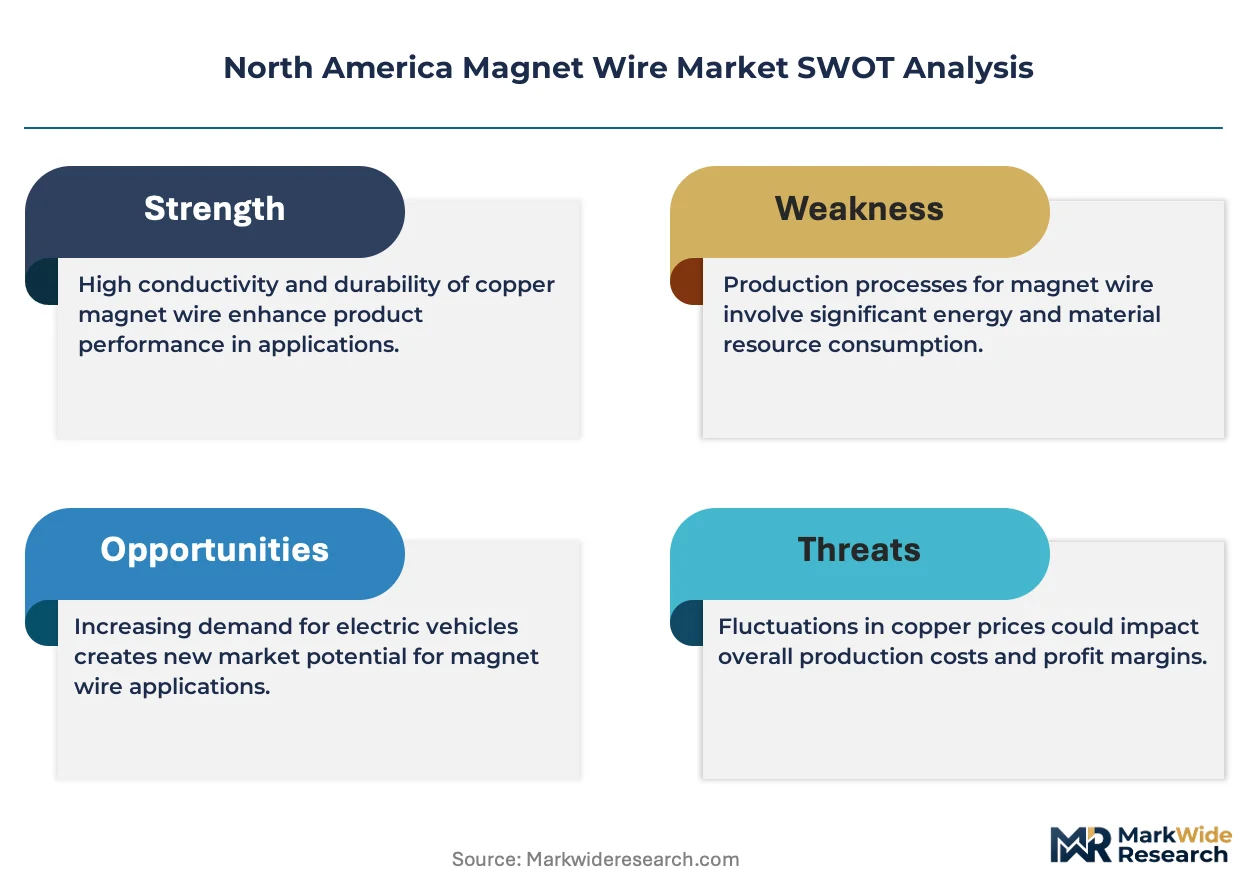
- EPA greenhouse gas emissions rules:Tightening standards force motor efficiency upgrades that require higher thermal class insulation systems, expanding qualified supplier volumes.
- Wind turbine generator rewinding:Extended thermal endurance grades for renewable energy applications pull new capacity from enameling operations across the Midwest.
- US Inflation Reduction Act domestic content provisions:Federal procurement rules for clean energy programs reshape sourcing requirements toward qualified North American suppliers.
Market Restraints
- LME copper price volatility:Raw material cost swings compress margin structures for non-integrated enameling operations without captive rod production.
- Supply concentration in Southeast automotive clusters:Geographic clustering of EV drivetrain facilities creates single-point vulnerability for just-in-time winding programs.
- Aluminum resistivity trade-offs:Conductivity limitations block penetration into high-efficiency transformer applications where copper retains performance premiums.
Strategic Opportunities
- NEMA MW 1000 thermal class migration:Higher temperature ratings enable slot fill efficiency gains that open aerospace and defense winding applications.
- High-frequency inverter-duty motor expansion:Coating consistency requirements for variable speed drives favor integrated drawing and enameling operations.
- State-level manufacturing incentives:Subnational clean energy programs create parallel qualification pathways beyond federal IRA provisions.
Industry Challenges
- Enamel chemist skill scarcity:Formulation expertise for polyimide and polyester-imide insulation systems concentrates among retiring specialists without pipeline replacement.
- Multi-year OEM qualification timelines:Motor manufacturer validation protocols delay revenue recognition for new thermal class introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Magnet Wire Market |
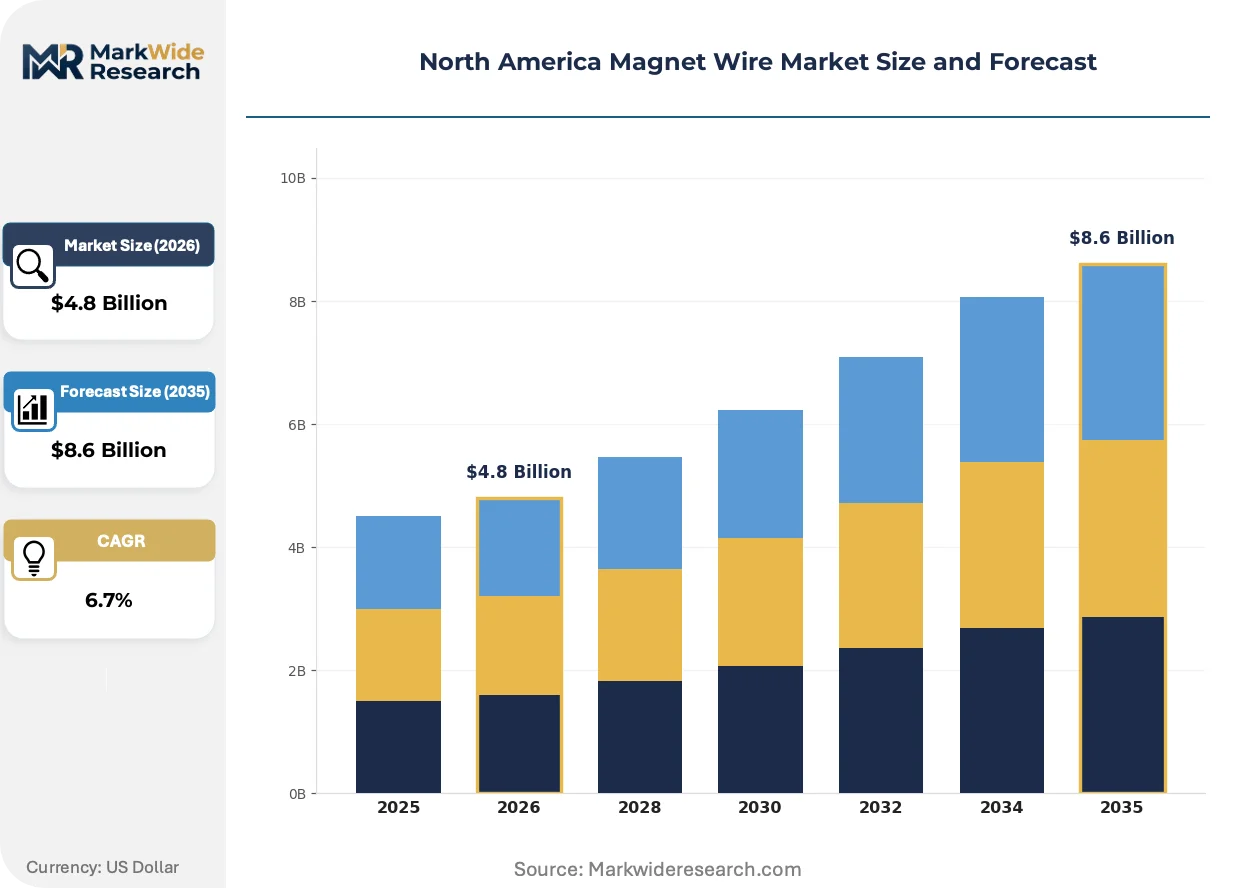
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Magnet Wire, Aluminum Magnet Wire, Enamelled Magnet Wire, Tinned Magnet Wire End User: Electrical Appliances, Automotive, Industrial Equipment, Renewable Energy Application: Transformers, Inductors, Motors, Generators Installation: Onshore, Offshore, Commercial, Residential |
| Companies Covered | Essex Furukawa, Rea Magnet Wire, Superior Essex, LS Cable & System Ltd., Elektrisola, IRCE SpA, Sam Dong, Sumitomo Electric Industries Ltd., MWS Wire Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Magnet Wire Market Evolving Landscape
Insulation chemistry migration and coating process control are converging to reshape competitive capability requirements across North American magnet wire supply chains. These shifts favor capital-intensive operations with integrated manufacturing footprints.
Automated optical inspection systems for enamel coating thickness uniformity are automating quality assurance protocols that previously required manual gauge verification. Tier 1 automotive suppliers are adopting these systems at pilot scale for EV motor winding programs. This automation is compressing defect escape rates and reducing qualification cycle times for high-frequency inverter-duty grades.
NHTSA corporate average fuel economy standards and EPA greenhouse gas emissions rules are mandating thermal performance upgrades that force insulation chemistry migration from polyester to polyimide-amide systems. Motor manufacturers face reformulation costs and retooling investments to maintain qualified supplier status. The US Southeast automotive cluster bears the highest compliance burden due to concentrated EV drivetrain production.
Buyer consolidation among automotive OEMs is compressing supplier negotiation leverage and extending payment terms for magnet wire deliveries. Tier 2 winding houses are responding by seeking direct relationships with enameling operations, bypassing traditional distribution channels. This channel disintermediation is most visible in Michigan and Tennessee, where just-in-time programs dominate EV motor supply chains.
North America Magnet Wire Market Segmentation
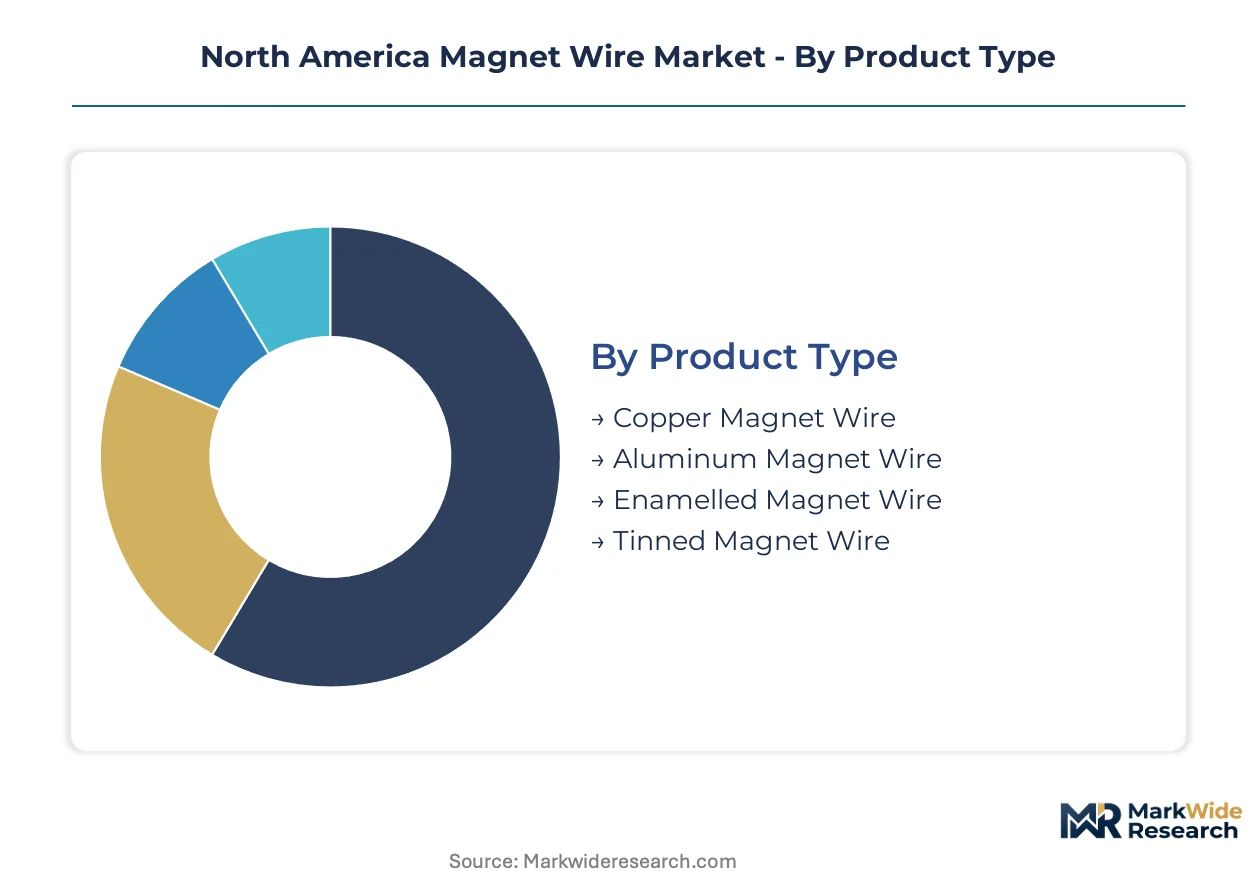
Magnet wire segmentation reveals how capital deployment, thermal performance requirements, and end-use specifications fragment supplier capabilities across North American manufacturing clusters. Understanding these divisions exposes where integrated enameling operations capture margin versus where commoditized grades face pricing pressure.
Product Type:
Capital intensity varies sharply across conductor and coating combinations, with integrated drawing-enameling operations demanding the heaviest upfront investment.
- Copper Magnet Wire:Solid or stranded copper conductor overcoated with polymeric insulation systems rated per NEMA MW 1000 thermal classes. Demand concentrates in transformer and high-efficiency motor applications across the US Midwest where conductivity premiums justify material costs against EPA emissions compliance mandates.
- Aluminum Magnet Wire:Lightweight conductor alternative with higher resistivity trade-offs, engineered with modified enamel chemistries to accommodate thermal expansion differentials. Automotive auxiliary systems in the US Southeast absorb volume where NHTSA fuel economy mandates drive mass reduction priorities.
- Enamelled Magnet Wire:Thin insulating film applied through continuous dip-and-bake processes, with coating thickness uniformity determining slot fill efficiency.
- Tinned Magnet Wire:Solderable surface coating for termination reliability in hand-wound and repair applications.
Copper magnet wire absorbs the bulk of installed capacity; aluminum magnet wire is expanding most quickly.
End User:
Customer concentration patterns separate long-cycle OEM qualification programs from shorter replacement demand cycles.
- Automotive:EV motor winding programs requiring high-frequency inverter-duty grades with coating consistency for variable speed drives. The US Southeast automotive cluster pulls the densest supplier footprint due to concentrated drivetrain facility investment.
- Renewable Energy:Wind turbine generator rewinding and new buildouts demanding extended thermal endurance grades. Midwest enameling operations are adding capacity to serve multi-megawatt generator requirements under IRA domestic content provisions.
- Industrial Equipment:Pump, compressor, and HVAC motor rewinding with established supply relationships through distributor channels.
- Electrical Appliances:Fractional horsepower motors for consumer goods with cost-sensitive specification thresholds.
Automotive end-use commands the highest qualification barriers; renewable energy is climbing the fastest.
Application:
Functional performance requirements dictate insulation chemistry selection and coating process control intensity.
- Motors:Rotating machinery windings spanning fractional to multi-megawatt ratings, where slot fill efficiency and thermal endurance determine operational lifespan. EV traction motors in Tennessee and Michigan facilities are forcing polyimide-amide chemistry migration under NHTSA thermal mandates.
- Transformers:Static electromagnetic devices requiring high dielectric strength and moisture resistance, with copper retaining dominance due to conductivity premiums in utility-scale applications.
- Generators:Synchronous and asynchronous machine windings for power generation, with wind turbine applications driving extended thermal class adoption.
- Inductors:Magnetic energy storage components with specialized high-frequency performance requirements in power electronics.
Motors absorb the bulk of installed capacity; generator applications are gaining share fastest.
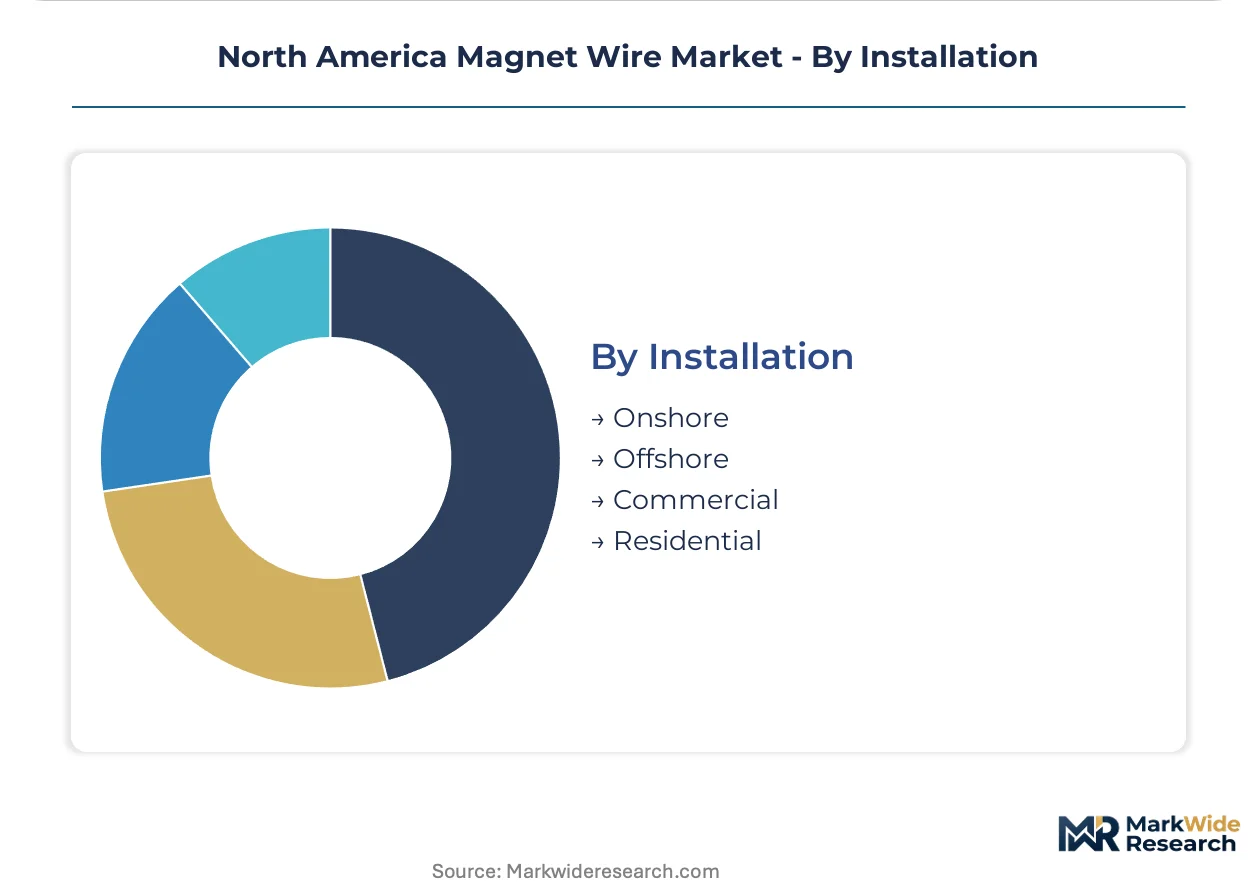
Installation:
Physical deployment context shapes environmental protection requirements and supply chain logistics.
- Onshore:Land-based wind turbine generators and utility transformers with accessible maintenance infrastructure. Texas and Iowa wind corridors are concentrating generator rewinding demand for onshore turbine fleets.
- Commercial:Building-scale HVAC and power distribution equipment with standardized NEMA specification compliance.
- Offshore:Marine-exposed wind turbine generators requiring enhanced moisture and salt spray resistance in insulating systems.
- Residential:Appliance and small motor applications with cost-optimized specification floors.
Onshore installation absorbs the bulk of installed capacity; offshore deployment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Magnet wire demand concentrates in the US Southeast where automotive OEMs have clustered EV drivetrain facilities, while the US Midwest and Canadian industrial corridors anchor transformer and industrial motor applications.
United States
EPA greenhouse gas emissions rules and NHTSA fuel economy mandates are forcing thermal class upgrades across motor winding programs. The US Inflation Reduction Act domestic content provisions are reshaping procurement requirements for clean energy applications. Tennessee and Michigan host the densest supplier footprints serving just-in-time EV motor supply chains.
Canada
Hydroelectric generator rewinding cycles and wind turbine buildouts in Ontario and Quebec are pulling extended thermal endurance grades from regional enameling operations. Health Canada's environmental regulations align with EPA standards on insulating chemistry migration timelines. The Prairie Provinces are seeing concentrated investment in utility-scale transformer applications.
Mexico
Automotive auxiliary system production for export markets is absorbing aluminum magnet wire volumes where mass reduction priorities offset resistivity trade-offs. Mexico's national energy regulator enforces efficiency standards that mirror NHTSA thermal performance thresholds. The Bajío Region and Northern Border States are concentrating new winding facility investments.
North America Magnet Wire Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers race to qualify for IRA-backed clean energy programs and EV motor contracts. The market structures around three tiers: integrated copper rod producers with captive enameling, specialized enameling operations serving automotive just-in-time programs, and regional distributors handling replacement demand. Strategic archetypes include backward-integrated material players, coating consistency specialists, and geographic proximity operators. M&A activity and multi-year OEM qualification timelines represent the dominant competitive moves reshaping supplier relationships.
Among North American-based suppliers, Essex Furukawa, Rea Magnet Wire, and Superior Essex exemplify the integrated manufacturing archetype. These companies occupy positions that span drawing, enameling, and direct OEM supply relationships. LS Cable & System Ltd. represents the Asia-Pacific multinational segment with regional manufacturing presence. Sumitomo Electric Industries Ltd. and Elektrisola sit within the specialty coating tier serving high-frequency and precision winding applications. The competitive map favors operations with in-house copper rod production and dense geographic clustering near automotive and renewable energy demand centers.
| Leading Market Players |
|---|
| Essex Furukawa |
| Rea Magnet Wire |
| Superior Essex |
| LS Cable & System Ltd. |
| Elektrisola |
| IRCE SpA |
| Sam Dong |
| Sumitomo Electric Industries Ltd. |
| MWS Wire Industries |
| Others |
Value Network & Pricing Analysis
Copper rod feedstock costs cascade through three pricing tiers before reaching EV motor winding programs, with LME volatility compressing margins at non-integrated enameling operations while integrated producers capture spread stability through captive rod production.
Pricing Analysis
Volume concentration in automotive just-in-time programs splits margin capture between commodity-grade transformer wire and premium inverter-duty grades. Price differentiation rests on NEMA MW 1000 thermal class certification and coating consistency for high-frequency applications. Pricing pressure stems from buyer consolidation among automotive OEMs extending payment terms for Tier 2 winding houses. Distributor-dependent replacement demand proves most price-sensitive; direct OEM supply relationships show lowest elasticity due to multi-year qualification lock-in.
Supply Chain Analysis
Enamel chemist workforce availability constrains capacity expansion in Tennessee and Michigan automotive clusters where EV drivetrain facilities concentrate demand. Raw material dependencies center on Chilean copper cathode, Saudi petrochemical feedstock for polyester-imide resins, and domestic rod production. Single-source vulnerability concentrates in Southeast automotive clusters where geographic clustering creates just-in-time delivery risk. Distribution runs through direct OEM supply relationships bypassing traditional channels, with regional distributors serving replacement demand in industrial motor rewind markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America magnet wire market operates as a vertical-integration race where backward control over copper rod production and enameling capacity determines margin capture against LME volatility and qualification timeline risk.
For Market Incumbents: Deepen captive rod production investments to insulate margin structures from raw material cost swings. Expand coating consistency capabilities for high-frequency inverter-duty grades before EPA thermal mandate deadlines tighten. Secure direct supply relationships with Tennessee and Michigan EV drivetrain facilities to bypass distributor channel compression.
For New Entrants and Emerging Players: Capture aluminum magnet wire share in automotive auxiliary systems where NHTSA mass reduction mandates offset resistivity trade-offs. Target wind turbine generator rewinding demand in Texas and Iowa corridors under IRA domestic content provisions. Lead with state-level manufacturing incentive qualification as a faster pathway than federal procurement rules.
For Investors and Strategic Acquirers: NEMA MW 1000 thermal class migration announcements from major automotive OEMs is the leading indicator that coating consistency specialists will command acquisition premiums. Mid-cap enameling operations with integrated drawing capabilities and dense Southeast geographic footprints represent the optimal target archetype over the coming decade. Monitor enamel chemist hiring velocity at qualified suppliers as the inflection signal for capacity constraint severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Rod Production | Captive rod supply insulates margin structures from LME volatility at Essex Furukawa and Superior Essex. |
| High-Frequency Inverter-Duty Grade Qualification | Coating consistency investments open EV motor winding contracts under NHTSA thermal performance mandates. |
| Aluminum Magnet Wire Capacity Expansion | Mass reduction priorities in automotive auxiliary systems offset conductivity trade-offs against copper dominance. |
| State-Level Manufacturing Incentive Alignment | Parallel qualification pathways beyond federal IRA provisions accelerate clean energy supplier status. |
| Automated Optical Inspection Deployment | Pilot-scale adoption at Tier 1 automotive suppliers compresses defect escape rates for enamel coating uniformity. |
Research Methodology
Independent corroboration across enameling operations, automotive OEM procurement teams, and wind turbine generator manufacturers underwrites the qualitative findings in this study. Primary interviews with plant managers at integrated magnet wire producers, Tier 1 supplier sourcing directors, and renewable energy EPC contractors combined with secondary validation from NEMA MW 1000 certification databases, EPA emissions rule filings, and US customs trade data. Bottom-up capacity assessments at individual enameling facilities triangulate against top-down demand modeling from vehicle production databases and wind turbine installation records.
Comparable-period anchoring to historical thermal class migration cycles and automotive qualification timelines shaped the projection horizon across the analysis window. Segmentation dimensions modeled include conductor material, thermal class rating, end-use industry, and regional manufacturing cluster. CAGRs derive from installed capacity utilization rates, OEM contract award velocity, and IRA domestic content provision implementation pace. Forecast inputs incorporate NHTSA fuel economy mandate compliance deadlines and EPA greenhouse gas rule phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to enamel chemist workforce availability and multi-year OEM qualification timeline extensions. Assumptions reflect current regulatory alignment between federal procurement rules and state-level incentives. LME copper price volatility, automotive buyer consolidation leverage, and offshore wind deployment acceleration represent the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Ferrofluid Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
Copper Magnet Wire Market
Magnetic Materials
North America Samarium Cobalt Magnets Market
Magnetic Materials
High Performance Magnet Market
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
Magnetic Filter Market
Magnetic Materials
Magnet Buffer Market
Magnetic Materials
Ferroboron Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
Samarium Cobalt Magnets Market
Magnetic Materials
Gadolinium Market