
 Magnetic Filter Market | 2026-2036
Magnetic Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Filter Market Insights
Neodymium-iron-boron is consolidating its position as the dominant magnetic core material in high-performance filtration systems, displacing older ferrite assemblies in applications requiring sub-10-micron particle capture. Eclipse Magnetics leverages proprietary magnetic circuit designs to sustain premium positioning in European food safety applications. Goudsmit Magnetics anchors its competitive stance through backward integration into rare-earth magnet sourcing. Eriez Manufacturing Co. dominates North American mineral processing installations with heavy-duty separator platforms.
A magnetic filter employs permanent or electromagnet arrays to extract ferrous and paramagnetic contaminants from liquid or slurry process streams, typically achieving capture thresholds of 0.5 to 50 microns depending on magnetic flux density and flow velocity design. Inline filter configurations lead unit volume due to their retrofit compatibility with existing pipeline infrastructure across water treatment and chemical processing plants. Crossflow filter architectures represent the fastest-growing product category as semiconductor-grade fluid cleanliness standards propagate into adjacent industrial sectors. Oil recovery applications concentrate margin pools through specification-intensive offshore platform deployments requiring corrosion-resistant alloy housings and redundant magnetic stages.
EPA effluent guidelines and OSHA process safety management requirements shape magnetic filter specification in US chemical and petrochemical facilities, mandating reliable particulate control to protect downstream catalyst beds and heat exchangers. The EU Machinery Directive and ATEX certification frameworks govern explosion-proof magnetic separator deployment in European solvent-handling environments. Stakeholders must monitor rare-earth supply chain origination requirements and evolving magnet recycling mandates as regulatory scrutiny intensifies on critical mineral provenance and end-of-life recovery obligations.
Market Dynamics
Neodymium supply concentration in China and the EU F-Gas Regulation are forcing magnetic filter manufacturers toward closed-loop designs and alternative magnet sourcing strategies. Equipment buyers now specify provenance documentation and end-of-life recovery protocols as standard procurement terms.
Growth Catalysts
- REACH compliance frameworks:European chemical processors must eliminate ferrous contamination from effluent streams, mandating inline magnetic filtration at catalyst bed inlets and heat exchanger stations.
- Semiconductor-grade fluid standards:Crossflow magnetic architectures capture sub-10-micron particles in photolithography coolant loops, expanding addressable market into electronics manufacturing.
- Germany's industrial corridor:Precision manufacturing clusters in Bavaria and North Rhine-Westphalia specify specification-grade magnetic filtration for machine tool coolant recovery systems.
Market Restraints
- Rare-earth supply concentration:Neodymium-iron-boron magnet production concentrates in Chinese processing facilities, exposing European and North American filter assemblers to export quota volatility and origination scrutiny.
- High-performance ferrite substitution ceiling:Ferrite magnetic cores cannot achieve the flux density required for sub-5-micron particle capture, limiting their deployment in semiconductor and pharmaceutical fluid handling.
- ATEX certification timelines:Explosion-proof magnetic separator approval for solvent-handling environments requires 18-24 month validation cycles, delaying revenue recognition on European chemical plant orders.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic production incentives attract multinational chemical processors to Gujarat and Maharashtra, creating installed base for specification filtration equipment.
- Hydrogen economy fluid handling:Electrolyzer coolant loops and fuel cell manufacturing require paramagnetic particle control in high-purity water systems, an application category with minimal incumbent penetration.
- Magnet recycling mandates:The EU Critical Raw Materials Act creates service-contract opportunities for filter OEMs to reclaim and reprocess rare-earth cores from decommissioned equipment.
Industry Challenges
- Magnetic circuit design specialization:Fewer than two dozen engineers globally possess expertise in high-gradient magnetic separation physics, constraining product development velocity at mid-tier manufacturers.
- Legacy pipeline retrofit complexity:Existing petrochemical and water treatment infrastructure features non-standard flange specifications and space-constrained installation envelopes, forcing custom engineering on 40% of inline filter deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Filter Market |
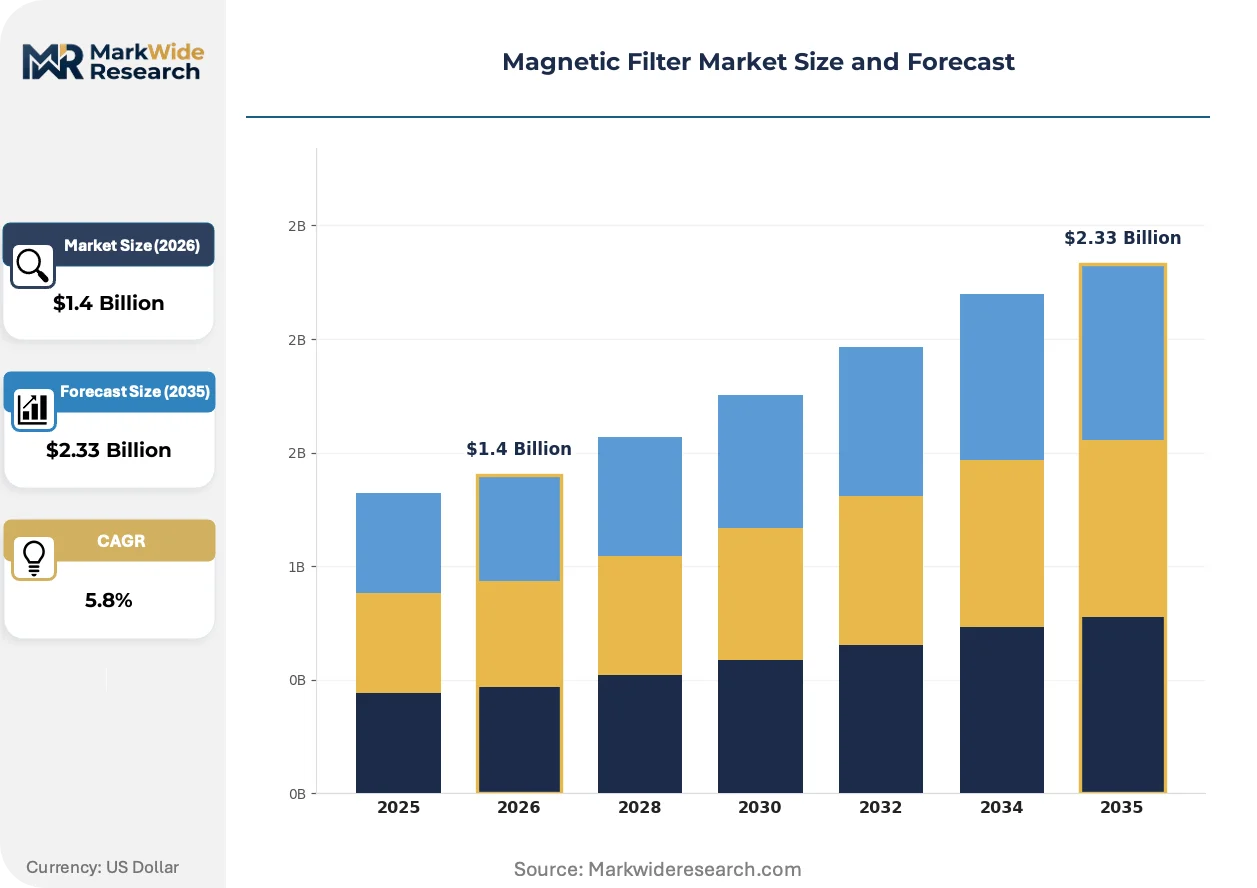
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Filters, Crossflow Filters, Batch Filters, Magnetic Separators End User: Water Treatment Facilities, Food Processing, Chemical Manufacturing, Petrochemical Industry Installation Type: Commercial Systems, Industrial Systems, Residential Systems, Portable Systems Application: Oil Recovery, Metal Recycling, Wastewater Treatment, Mineral Processing |
| Companies Covered | Eclipse Magnetics, Bunting, Goudsmit Magnetics, Permanent Magnets Ltd, Magnetix, Magnom, Eriez Manufacturing Co., Metso Outotec, Magnetic Filtration Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Filter Market Trends and Innovations
Magnetic filter architecture is converging with IoT-enabled condition monitoring and predictive maintenance platforms, transforming capital equipment into connected assets. This shift redefines aftermarket revenue models and competitive differentiation.
Neodymium-iron-boron permanent magnet arrays are integrating Hall-effect sensors and wireless telemetry modules for real-time flux density monitoring. Offshore oil platform operators in the North Sea deploy these smart separators to schedule magnet cleaning cycles based on actual particle loading rather than fixed intervals. The technology is integrating predictive analytics platforms that correlate filtration performance with downstream equipment failure rates.
The EU F-Gas Regulation and national implementations of the EU Green Deal are mandating closed-loop refrigerant and process fluid systems. Magnetic filtration enables refrigerant purity maintenance without disposable media, aligning with circular economy compliance targets. German chemical processors now specify magnet-based separation as the default technology in new solvent recovery plant engineering.
Asset-light service contracts are displacing traditional equipment purchase models in municipal water treatment. French and Italian utilities now procure magnetic filtration capacity through performance-based agreements where vendors retain ownership and responsibility for magnet regeneration. This model concentrates procurement authority with national water holding companies and compresses vendor selection cycles to technical capability demonstrations rather than capital tender processes.
Magnetic Filter Market Segmentation
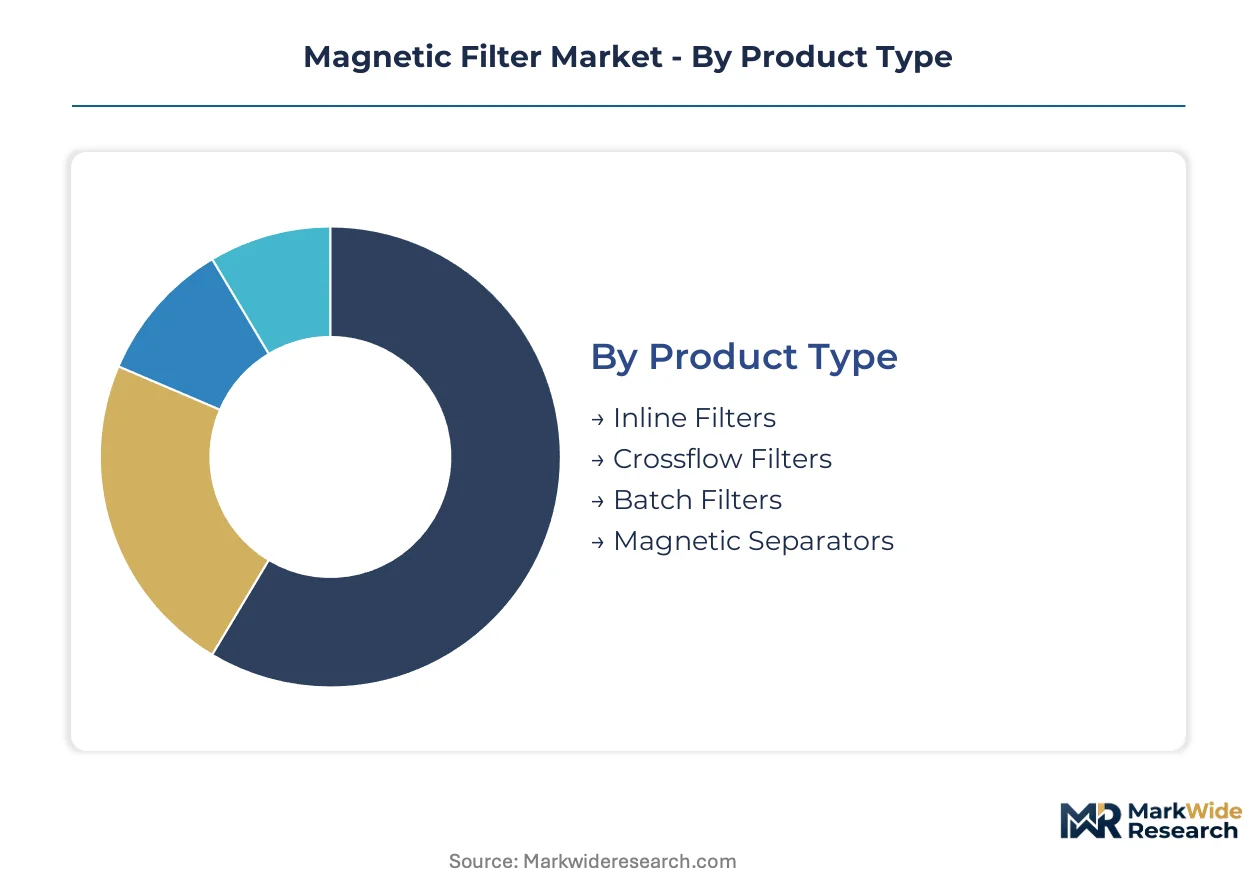
Magnetic filter procurement patterns diverge sharply across product architectures and installation contexts. Specification requirements for semiconductor-grade fluid handling bear little resemblance to heavy-duty mineral processing deployments, creating distinct competitive arenas with non-overlapping vendor bases.
Product Type:
Supply concentration in high-gradient magnetic circuit engineering favors manufacturers with captive magnet sourcing and proprietary flux density optimization.
- Inline Filters:These permanent-magnet arrays install directly into existing pipeline infrastructure, typically achieving 5-50 micron capture thresholds at flow velocities up to 3 meters per second. Water treatment facilities in Germany's industrial corridor specify inline configurations for retrofit compatibility with legacy flange standards, though custom engineering consumes 40% of deployment timelines due to non-standard installation envelopes.
- Crossflow Filters:Tangential flow architectures maintain fluid velocity across magnetized surfaces, enabling sub-10-micron particle capture without flow restriction. Semiconductor manufacturing clusters in Bavaria and North Rhine-Westphalia drive specification-grade procurement for photolithography coolant loops, where fluid cleanliness standards propagate from electronics into adjacent industrial sectors.
- Batch Filters:Intermittent-operation vessels suit low-volume, high-contaminant slurry processing with manual magnet cleaning cycles.
- Magnetic Separators:Heavy-duty drum and pulley configurations dominate mineral processing installations requiring continuous ferrous recovery from bulk material streams.
Today's leader: Inline Filters. Tomorrow's challenger: Crossflow Filters.
End User:
Regulatory stringency varies dramatically across end-use sectors, with EU REACH compliance mandating ferrous elimination that other geographies merely recommend.
- Water Treatment Facilities:Municipal utilities in France and Italy now procure magnetic filtration through performance-based service contracts rather than capital purchase, compressing vendor selection to technical capability demonstrations. Asset-light models concentrate procurement authority with national water holding companies.
- Petrochemical Industry:Refinery operators deploy specification-intensive magnetic filtration at catalyst bed inlets and heat exchanger stations to protect downstream equipment from ferrous contamination. EPA effluent guidelines and OSHA process safety management requirements shape procurement specifications in US facilities.
- Chemical Manufacturing:Solvent-handling environments require ATEX-certified explosion-proof separators with 18-24 month validation cycles.
- Food Processing:European food safety applications demand proprietary magnetic circuit designs with documented rare-earth provenance and end-of-life recovery protocols.
Petrochemical Industry commands current procurement volumes. Water Treatment Facilities are expanding most quickly through service-contract adoption.
Installation Type:
Margin structures stratify by system scale, with industrial deployments justifying redundant magnetic stages and corrosion-resistant alloy housings that residential applications cannot support.
- Industrial Systems:Multi-stage permanent-magnet arrays with automated cleaning mechanisms serve continuous-process manufacturing. Offshore oil platform operators in the North Sea deploy these configurations with IoT-enabled flux density monitoring to schedule maintenance based on actual particle loading.
- Commercial Systems:Mid-scale installations serve building-scale HVAC and process water loops with standardized magnet geometries.
- Portable Systems:Mobile filtration units address temporary construction dewatering and emergency response applications.
- Residential Systems:Single-magnet inline devices target point-of-entry water treatment with limited flux density and manual maintenance requirements.
Industrial Systems generate dominant revenue pools. Commercial Systems offer the steepest expansion trajectory as building codes tighten particulate discharge requirements.
Application:
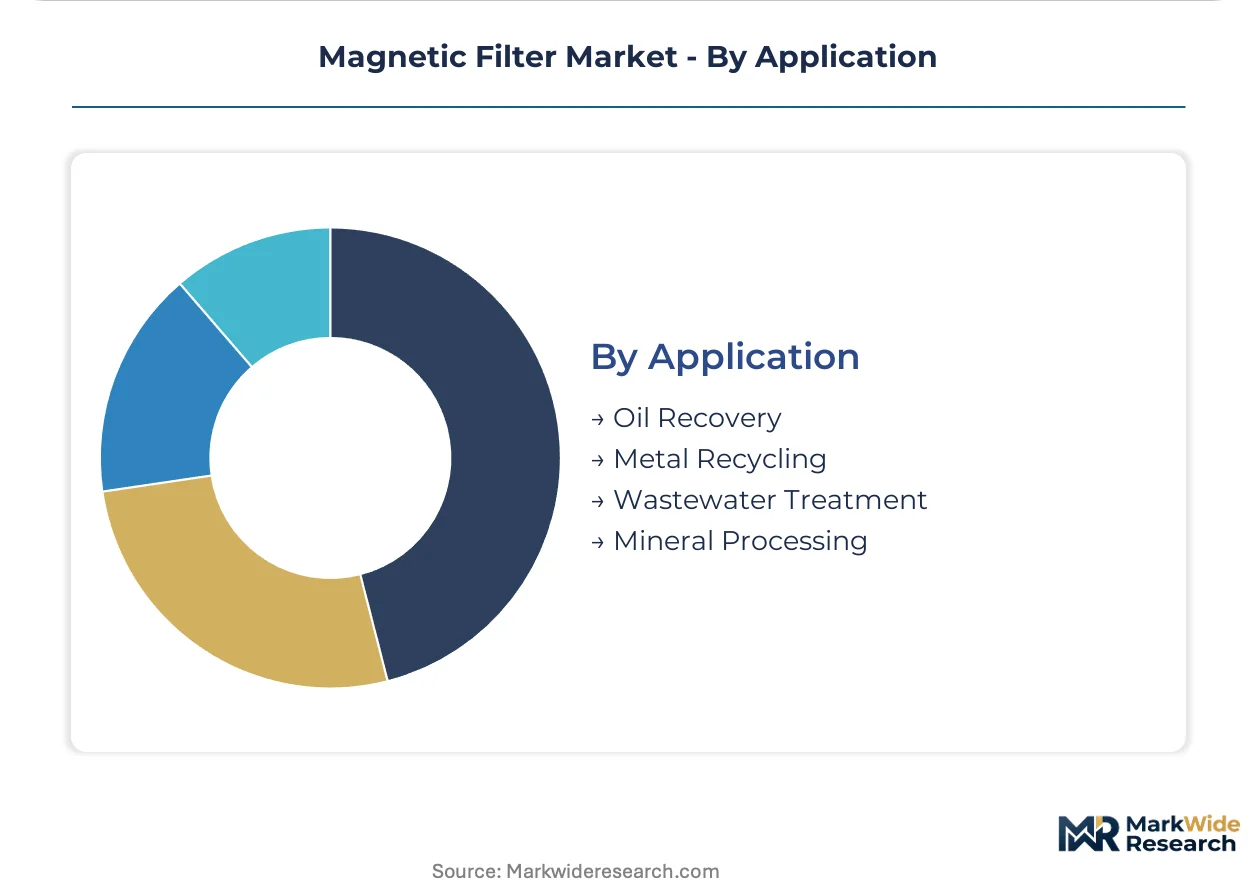
Specification intensity peaks in applications where fluid purity directly determines downstream process economics or regulatory compliance.
- Oil Recovery:Offshore platform deployments require corrosion-resistant superalloy housings and redundant magnetic stages to maintain crude stream integrity. These specification-intensive installations concentrate margin pools through extended service contracts and proprietary magnet regeneration services.
- Wastewater Treatment:Municipal and industrial effluent processing employs magnetic filtration for heavy metal and ferrous particle capture prior to discharge. The EU F-Gas Regulation and national Green Deal implementations mandate closed-loop refrigerant and process fluid systems where magnet-based separation eliminates disposable media.
- Mineral Processing:Bulk material handling operations recover ferrous contaminants from crushed ore streams to protect downstream grinding equipment.
- Metal Recycling:Shredder residue and scrap processing streams utilize magnetic separation for ferrous fraction recovery prior to non-ferrous sorting.
Oil Recovery commands premium pricing. Wastewater Treatment is gaining share fastest through regulatory mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor anchors procurement intensity for magnetic filtration systems, with precision manufacturing clusters driving specification-grade demand across Bavaria and North Rhine-Westphalia.
United States
Petrochemical refineries along the Gulf Coast deploy specification-intensive magnetic filtration at catalyst bed inlets to protect downstream equipment from ferrous contamination. EPA effluent guidelines and OSHA process safety management requirements shape procurement specifications in chemical processing facilities. Houston-area industrial complexes concentrate demand for heavy-duty separator platforms in mineral processing and oil recovery applications.
Germany
Precision manufacturing clusters in Bavaria and North Rhine-Westphalia specify specification-grade magnetic filtration for machine tool coolant recovery systems. The EU F-Gas Regulation and REACH compliance frameworks push processors toward closed-loop filtration systems without disposable media. Stuttgart and Munich industrial zones concentrate procurement authority for high-gradient magnetic separation equipment in automotive and electronics manufacturing.
China
Neodymium-iron-boron magnet production concentrates in Chinese processing facilities, exposing downstream filter assemblers to export quota volatility. The country's dual carbon goals and evolving magnet recycling mandates intensify regulatory scrutiny on critical mineral provenance. Yangtze River Delta manufacturing hubs drive domestic demand for inline filter configurations in water treatment and chemical processing plants.
India
Domestic production incentives under the PLI scheme for specialty chemicals attract multinational processors to Gujarat and Maharashtra, creating installed base for specification filtration equipment. BIS standards and state-level environmental clearances shape equipment certification requirements. Mumbai-Pune industrial corridor clusters concentrate demand for crossflow architectures in pharmaceutical and fine chemical manufacturing.
France
Municipal utilities procure magnetic filtration capacity through performance-based service agreements where vendors retain ownership and responsibility for magnet regeneration. The EU Green Deal national implementations mandate closed-loop process fluid systems in chemical manufacturing. Lyon and Marseille industrial zones concentrate specification procurement for ATEX-certified explosion-proof separators in solvent-handling environments.
Magnetic Filter Market Competitive Landscape
Global majors compete with regional champions across magnetic circuit design expertise and rare-earth magnet sourcing capabilities. The vendor base stratifies into three tiers: integrated manufacturers with captive magnet production, specialized filter assemblers sourcing third-party magnetic cores, and regional fabricators serving retrofit installation markets. Strategic archetypes include backward-integrated rare-earth processors, proprietary flux-density optimizers, and asset-light service contract providers. Competitive moves concentrate on magnet recycling service expansion and IoT-enabled condition monitoring platform deployment.
Among UK-based magnetic specialists, Eclipse Magnetics and Magnetic Filtration Ltd. occupy positions within the premium-tier segment emphasizing proprietary circuit designs. Goudsmit Magnetics anchors the Netherlands-based contingent with upstream control over rare-earth magnet sourcing. Eriez Manufacturing Co. exemplifies the North American heavy-duty platform provider archetype in mineral processing installations.
| Leading Market Players |
|---|
| Eclipse Magnetics |
| Bunting |
| Goudsmit Magnetics |
| Permanent Magnets Ltd |
| Magnetix |
| Magnom |
| Eriez Manufacturing Co. |
| Metso Outotec |
| Magnetic Filtration Ltd. |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance gates qualified supply for closed-loop filtration systems and premium-tier pricing access for vendors with documented rare-earth provenance and magnet regeneration capabilities. Equipment buyers now mandate end-of-life recovery protocols as standard procurement terms, compressing margin structures for assemblers lacking backward integration.
Pricing Analysis
Input-cost pass-through from neodymium-iron-boron magnet sourcing dominates pricing structures across the three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ATEX certification grade and flux density optimization for sub-10-micron capture. Cost compression in standard-tier inline filters is intensifying because ferrite substitution ceilings limit performance claims. Municipal water utilities exhibit highest price sensitivity through performance-based service contracts, while offshore oil platform operators show lowest sensitivity due to specification-intensive redundant stage requirements.
Supply Chain Analysis
ATEX certification and REACH compliance documentation requirements gate supplier qualification before rare-earth magnet procurement can commence. Magnetic core sourcing draws from China, Germany, and Japan, with permanent-magnet arrays and corrosion-resistant alloy housings as critical component inputs. Single-source vulnerability concentrates in Chinese neodymium processing facilities exposed to export quota volatility. Distribution runs through authorized industrial equipment distributors and direct OEM relationships for specification-grade deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The magnetic filter market functions as a stable compounder anchored by regulatory mandates for ferrous contamination control that expand addressable applications across process industries.
For Market Incumbents: Anchor competitive position through captive rare-earth magnet sourcing and proprietary flux density optimization to defend against mid-tier assemblers with third-party core procurement. Invest in IoT-enabled condition monitoring platforms to transform capital equipment into recurring service revenue streams. Prioritize magnet recycling service expansion under EU Critical Raw Materials Act mandates. For New Entrants and Emerging Players: System integrators serving India's PLI scheme for specialty chemicals represent the most penetrable channel partner type for specification filtration equipment. Target Gujarat and Maharashtra chemical clusters with crossflow architectures for pharmaceutical-grade fluid handling. Pursue asset-light service contract positioning to bypass capital tender barriers in French and Italian municipal water markets. For Investors and Strategic Acquirers: Roll-up economics work for specialized magnetic circuit design firms because fewer than two dozen engineers globally possess high-gradient separation physics expertise, creating scarcity value. Five-to-ten year viability rests on hydrogen economy fluid handling penetration and semiconductor-grade standard propagation. Watch electrolyzer coolant loop procurement specifications as inflection indicator for paramagnetic control demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Sourcing | Goudsmit Magnetics demonstrates how upstream magnet control insulates margin from Chinese export quota volatility. |
| IoT-Enabled Condition Monitoring Deployment | North Sea offshore operators now schedule maintenance based on Hall-effect sensor flux density readings rather than fixed intervals. |
| Magnet Recycling Service Expansion | EU Critical Raw Materials Act creates performance-based contract opportunities for OEM reclamation of decommissioned rare-earth cores. |
| Crossflow Architecture Development | Bavarian semiconductor clusters drive specification-grade procurement for photolithography coolant loops with sub-10-micron capture thresholds. |
| Hydrogen Economy Fluid Handling Positioning | Electrolyzer coolant loops and fuel cell manufacturing require paramagnetic particle control with minimal incumbent penetration. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, secondary validation through customs filings and SEC disclosures, technical specification analysis — were reconciled to construct market estimates. Stakeholder consultations included maintenance directors at petrochemical refineries, aftermarket service heads at water treatment utilities, and technical R&D directors at magnetic component suppliers. Bottom-up unit economics triangulated against top-down sectoral spend analysis.
Data-stream reconciliation across product architecture, end-use sector, and installation type dimensions produced volume and value outputs over the projection horizon. CAGRs were derived from segment-level growth rate calibration against macro industrial production indices. Forecast inputs incorporated REACH compliance timeline acceleration and rare-earth supply quota volatility scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to neodymium supply concentration shifts and hydrogen economy infrastructure buildout pacing. A model refresh is warranted upon material change in EU Critical Raw Materials Act implementation schedules or Chinese rare-earth export policy adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
High Performance Magnet Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Global Electrical Steel Sheet Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Magnetic Materials Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Rare Earth Magnet Market
Magnetic Materials
Samarium Cobalt Magnets Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Reduced Iron Powder Market
Magnetic Materials
Nanocrystalline Soft Magnetic Material Market
Magnetic Materials
Magnetic Carbon Nanofoam Market
Magnetic Materials
Magnetorheological Fluid Market
Magnetic Materials
High Purity Carbonyl Iron Powder (CIP) Market
Magnetic Materials
Global Permanent Magnet Market