

High Performance Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Magnet Market Insights
Buyer concentration in electric vehicle powertrains is rebalancing as automotive OEMs consolidate supplier rosters while wind turbine developers fragment procurement across regional tiers. Proterial leverages integrated rare-earth processing from mine to magnet in Japan. Shin-Etsu Chemical sustains dominant capacity in sintered neodymium formulations. TDK Corporation anchors European medical imaging supply chains through VACUUMSCHMELZE subsidiary operations.
High performance magnets are permanent magnetic materials engineered with energy products exceeding 30 MGOe, primarily composed of rare-earth elements such as neodymium-iron-boron or samarium-cobalt alloys produced through powder metallurgy sintering or hot pressing, serving critical functions in torque generation, sensor actuation, and beam focusing across industrial and commercial systems. Neodymium products command the largest revenue pool due to their unmatched maximum energy density in commercial volumes. Sintered technology occupies the dominant manufacturing share though bonded processing competes in complex geometries where net-shape forming reduces machining waste. Wind turbine applications represent the fastest-growing demand segment as direct-drive generators displace gearbox architectures.
REACH in Europe mandates supply chain disclosure for heavy rare-earth sourcing while China's MEE enforces emission caps on smelting and separation facilities. The US IRA offers production tax credits for domestic magnet manufacturing but requires progressive North American content thresholds. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment sourcing strategies and reshape facility location decisions.
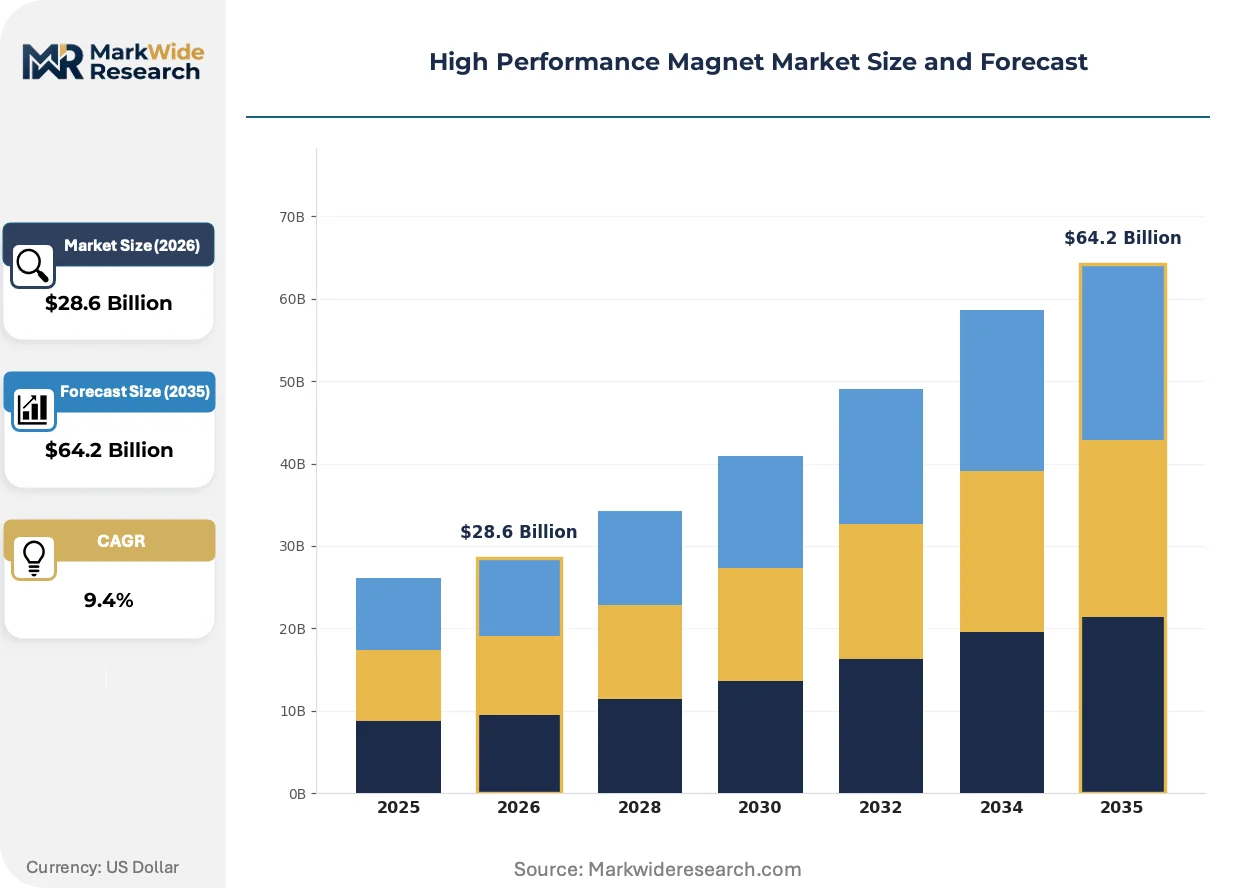
Market Dynamics
Direct-drive generator architectures in wind turbines are eliminating gearbox intermediaries, forcing magnet suppliers to engineer higher torque density formulations while automotive OEMs simultaneously consolidate rare-earth magnet supplier rosters to secure volume commitments.
Growth Catalysts
- EU Green Deal supply chain mandates:The framework requires documented heavy rare-earth provenance, compelling magnet manufacturers to invest in separation facility traceability systems.
- US IRA domestic content thresholds:Production tax credits escalate with progressive North American sourcing, redirecting capital toward magnet manufacturing facility construction.
- Electric vehicle powertrain torque density requirements:Sintered neodymium formulations deliver the specific power-to-weight ratios that axial-flux motor topologies demand.
Market Restraints
- Dysprosium and terbium price volatility:Heavy rare-earth inputs concentrate in Chinese separation facilities, exposing magnet producers to export quota fluctuations.
- Sintered process energy intensity:Hydrogen decrepitation and magnetic field alignment require sustained high-temperature furnace operations with limited renewable substitution pathways.
- REACH compliance documentation burdens:ECHA substance registration creates administrative fixed costs that disproportionately burden smaller magnet compounders.
Strategic Opportunities
- Japan's integrated mine-to-magnet corridors:Proterial and domestic processors control upstream rare-earth oxide refining, offering Western automotive OEMs supply diversification.
- Medical imaging gradient coil retrofits:Superconducting magnet replacement cycles in MRI systems create aftermarket demand for permanent magnet substitution.
- Bonded magnet net-shape forming:Injection molding of neodymium-iron-boron composites enables complex rotor geometries without machining waste, penetrating small-motor applications.
Industry Challenges
- Metallurgical engineering talent scarcity:Powder metallurgy sintering expertise concentrates in aging workforces across Japanese and German magnet producers.
- Magnetic property certification timelines:Demagnetization curve validation for automotive safety-critical applications requires extended thermal cycling protocols.
- Dual-use export control navigation:Defense-grade samarium-cobalt magnets trigger ITAR and national security review processes that delay commercial crossover.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Magnet Market Trends and Innovations
Hot-pressed nanocrystalline magnet processing is compressing grain structures below 300 nanometers, enabling thermal stability thresholds that sintered alternatives cannot match. This metallurgical pivot is redirecting R&D investment toward deformation routes that bypass traditional powder alignment limitations.
Grain boundary diffusion techniques are expanding into heavy rare-earth conservation strategies. Toyota and domestic suppliers deploy vapor-phase dysprosium infiltration to reduce critical element content by 50% while maintaining coercivity. The approach is expanding into cost structures previously reserved for bonded magnet applications, compressing the premium between high-performance and standard-grade formulations.
China's MEE emission caps on rare-earth smelting operations are forcing capacity consolidation in Jiangxi and Inner Mongolia separation facilities. Magnet producers must now qualify alternative oxide suppliers or absorb carbon intensity penalties in Scope 3 disclosures. European wind turbine developers are responding by accelerating qualification audits of Japanese and Australian upstream sources.
Automotive OEMs are unbundling magnet procurement from motor assembly contracts, establishing direct rare-earth magnet supply relationships that bypass tiered supplier hierarchies. BMW and Volkswagen now contract magnet compounders independently of their e-axle integrators. This disintermediation is most visible in Germany's automotive corridor, where powertrain engineering teams specify magnetic properties directly.
High Performance Magnet Market Segmentation
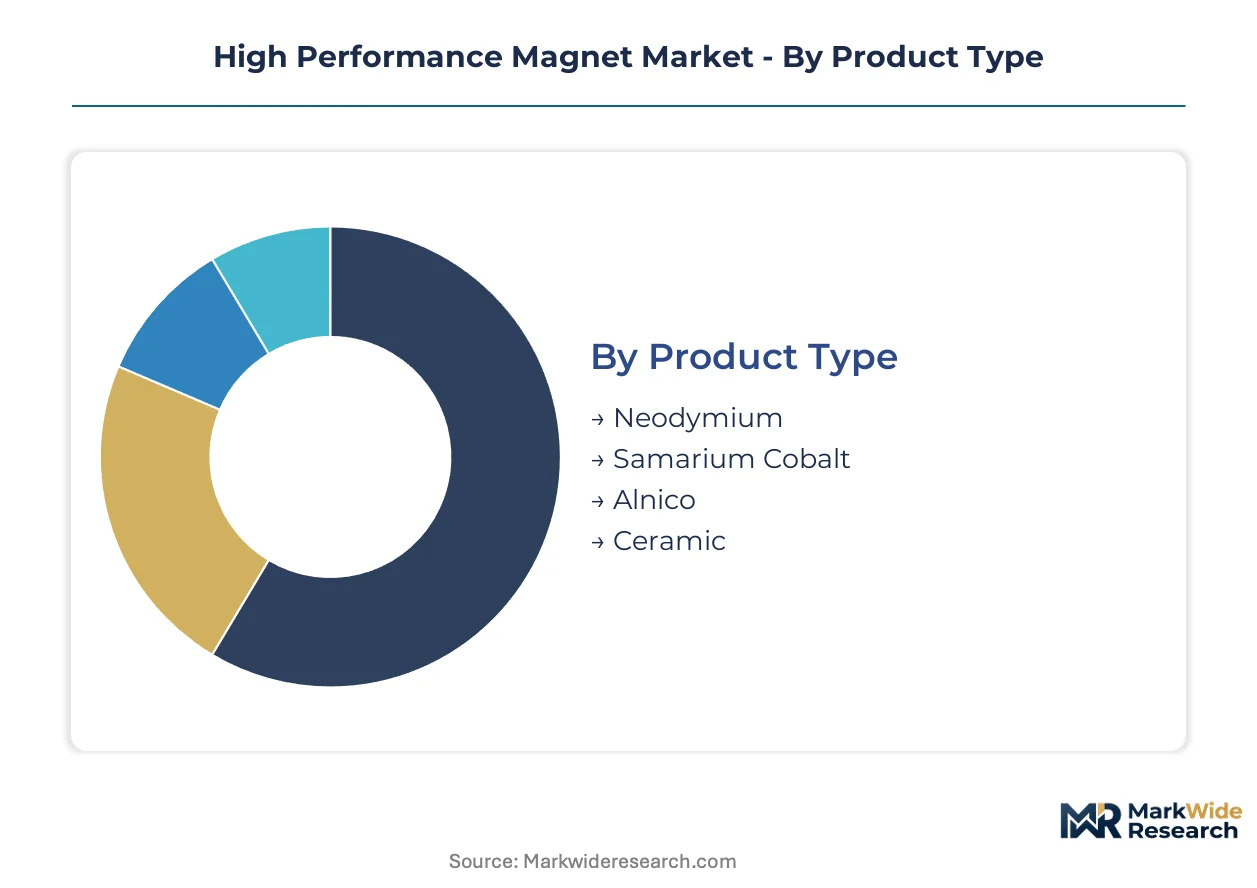
High performance magnet procurement splits between integrated system suppliers and standalone component distributors. Understanding these structural boundaries shapes facility location decisions and qualification timelines across automotive, medical, and energy verticals.
Product Type:
Integration depth varies sharply—neodymium and samarium cobalt embed directly into safety-critical torque systems, while alnico and ceramic serve standalone sensor and holding applications with looser supply chain coupling.
- Neodymium:Neodymium-iron-boron alloys achieve maximum energy products exceeding 50 MGOe through powder metallurgy sintering. Demand concentrates in Germany's automotive corridor where BMW and Volkswagen specify magnetic properties directly for axial-flux EV motors, constrained by dysprosium supply volatility from Chinese separation facilities.
- Samarium Cobalt:SmCo formulations retain magnetic performance above 300°C operating temperatures, enabling direct-drive wind turbine generators in Inner Mongolia and North Sea offshore arrays. High cobalt content exposes procurement to DRC mining traceability requirements under EU Green Deal mandates.
- Alnico:Aluminum-nickel-cobalt cast magnets serve temperature-stable sensor applications in industrial automation.
- Ceramic:Ferrite-based materials penetrate cost-sensitive consumer motor applications with limited rare-earth exposure.
Neodymium leads volumes today; samarium cobalt is gaining share fastest in high-temperature power generation.
Technology:
Cost tiers separate capital-intensive sintered operations from flexible bonded and molded alternatives serving prototype-to-production transitions.
- Sintered:Hydrogen decrepitation followed by magnetic field alignment and vacuum sintering produces anisotropic blocks requiring diamond grinding to final dimensions. German and Japanese producers dominate capacity, burdened by REACH energy intensity disclosures and limited renewable furnace fuel substitution pathways.
- Bonded:Compression bonding of NdFeB powder with epoxy binders enables near-net-shape arc segments for small motor rotors, penetrating Japanese robotics and German industrial automation supply chains without machining waste penalties.
- Injection Molded:Thermoplastic compound extrusion supports complex multipole geometries for automotive sensors and consumer device actuators.
- Hot Pressed:Nanocrystalline grain structures below 300 nanometers deliver thermal stability thresholds exceeding sintered alternatives, redirecting Toyota and domestic supplier R&D toward deformation processing routes.
Sintered technology commands margin leadership today; hot pressed is climbing the fastest as thermal stability specifications tighten.
Application:
Customer type stratification separates long-cycle infrastructure developers from high-velocity electronics manufacturers with diverging inventory and qualification protocols.
- Wind Turbines:Direct-drive generator architectures eliminate gearbox intermediaries, forcing magnet suppliers to engineer higher torque density formulations for 10+ MW offshore units. European developers fragment procurement across regional tiers to satisfy EU Green Deal heavy rare-earth provenance mandates.
- Medical Imaging:MRI gradient coil retrofits create aftermarket demand for permanent magnet substitution as superconducting systems age, with TDK's VACUUMSCHMELZE subsidiary anchoring European supply chains through specialized demagnetization curve validation protocols.
- Consumer Electronics:Miniaturization drives bonded magnet penetration in acoustic transducers and haptic actuators.
- Aerospace:ITAR-controlled samarium-cobalt specifications trigger dual-use export review processes that delay commercial crossover.
Wind turbines anchor volume scale today; medical imaging is expanding most quickly through replacement cycles.
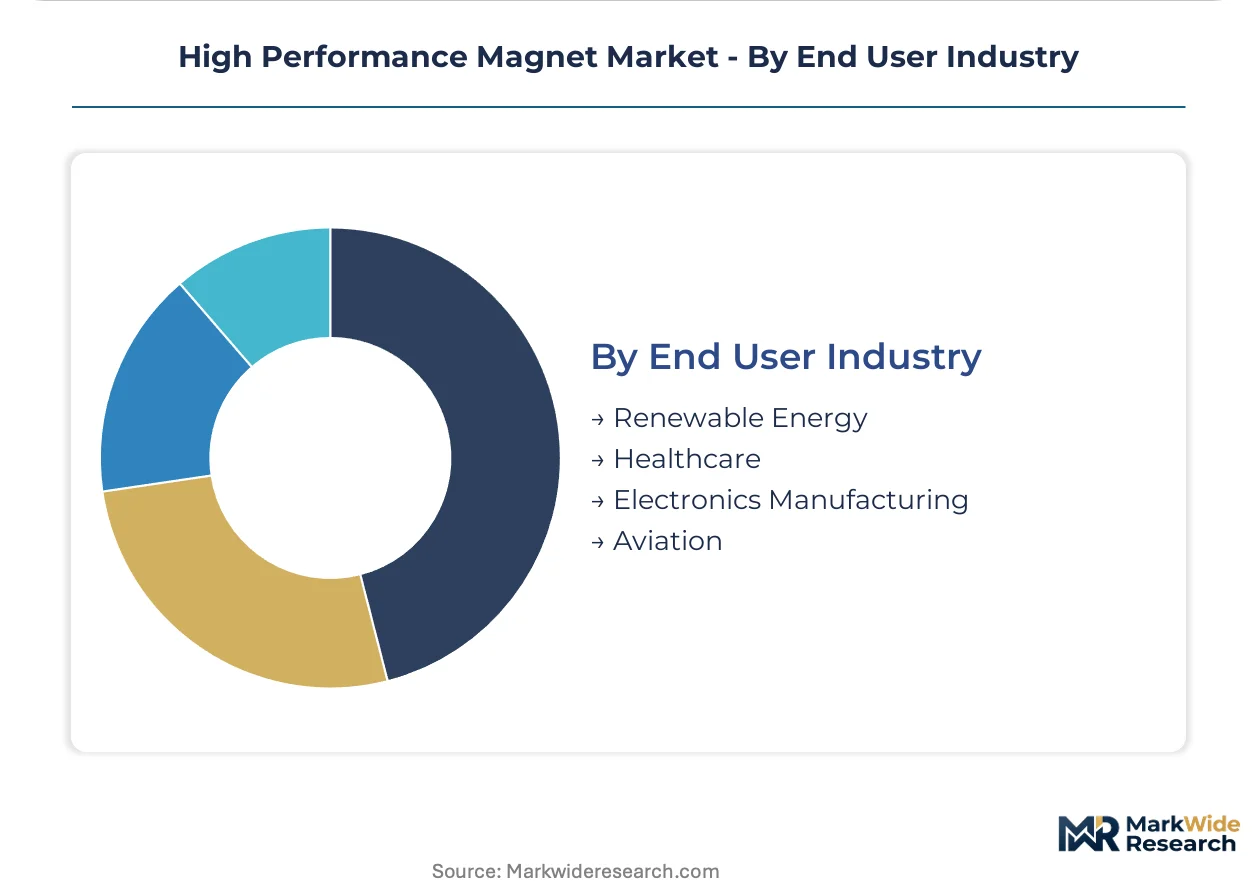
End User Industry:
Supply concentration aligns with geography—renewable energy clusters in Germany and Denmark, healthcare in Switzerland and Massachusetts, electronics in East Asian manufacturing corridors.
- Renewable Energy:Wind turbine OEMs and solar tracking system manufacturers consolidate rare-earth magnet supplier rosters to secure volume commitments, with China's MEE emission caps forcing qualification of Japanese and Australian upstream oxide sources.
- Healthcare:MRI system producers in Switzerland and Massachusetts specify magnetic homogeneity tolerances that bonded formulations cannot meet, sustaining sintered neodymium dominance despite grain boundary diffusion conservation efforts.
- Electronics Manufacturing:Consumer device assemblers in East Asian corridors prioritize bonded magnet flexibility for rapid product refresh cycles.
- Aviation:Defense-grade specifications concentrate samarium-cobalt procurement through national security review channels.
Renewable energy leads procurement volumes today; healthcare is gaining share fastest through imaging system upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metallurgical engineering talent concentrates in aging workforces across Japanese and German magnet producers, anchoring regional production capabilities. This workforce distribution shapes where sintering expertise and powder metallurgy R&D clusters persist.
China
MEE emission caps on rare-earth smelting operations in Jiangxi and Inner Mongolia separation facilities are forcing upstream consolidation. The country's dual carbon goals tighten supply chain due diligence for Western automotive OEMs. Magnet producers in Baotou and Ganzhou now face carbon intensity penalties in Scope 3 disclosures.
Germany
BMW and Volkswagen now contract magnet compounders independently of e-axle integrators for direct rare-earth magnet supply relationships. REACH mandates documented heavy rare-earth provenance through ECHA substance registration. The automotive corridor spanning Bavaria and Baden-Württemberg anchors axial-flux EV motor specification activity.
Japan
Proterial leverages integrated rare-earth processing from mine to magnet, offering Western automotive OEMs supply diversification. METI industrial policy supports domestic oxide refining capabilities. Toyota and domestic suppliers deploy grain boundary diffusion techniques in Nagoya-area R&D facilities.
United States
US IRA production tax credits escalate with progressive North American sourcing, redirecting capital toward magnet manufacturing facility construction. Defense-grade samarium-cobalt specifications trigger ITAR review processes that delay commercial crossover. The Department of Energy supports domestic separation facility traceability investments.
Australia
Upstream rare-earth oxide suppliers qualify as alternative sources to Chinese separation facilities under EU Green Deal mandates. The country's mining regulators enforce extraction standards that align with European heavy rare-earth provenance requirements. Western Australian rare-earth projects attract European wind turbine developer qualification audits.
High Performance Magnet Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across sintered neodymium and bonded magnet formulations. The market structure concentrates in Japanese and German producers with legacy powder metallurgy expertise. Three archetypes dominate: integrated mine-to-magnet operators, captive automotive suppliers, and specialty medical imaging compounders. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEMs consolidate supplier rosters.
Among Japanese producers, Proterial, Shin-Etsu Chemical, and TDK Corporation exemplify the integrated-to-specialist spectrum. Proterial occupies the upstream-integrated position with captive rare-earth oxide refining. Shin-Etsu Chemical sits within the volume-scale sintered formulation tier. TDK Corporation anchors European medical imaging supply chains through VACUUMSCHMELZE subsidiary operations, representing the geographic diversification archetype.
| Leading Market Players |
|---|
| Proterial |
| Shin-Etsu Chemical |
| TDK Corporation |
| Daido Steel |
| VACUUMSCHMELZE |
| Arnold Magnetic Technologies |
| Ningbo Yunsheng |
| Earth-Panda Advance Magnetic Material |
| Hangzhou Permanent Magnet Group |
| Others |
Pricing and Supply Chain Analysis
Hot-pressed nanocrystalline processing is compressing production timelines while simultaneously fragmenting cost structures across Japanese and German manufacturing corridors. This metallurgical pivot forces magnet compounders to recalibrate pricing power as thermal stability premiums compress against sintered alternatives, while China's MEE emission caps concentrate upstream oxide refining in fewer separation facilities.
Pricing Analysis
Magnet procurement unbundles from motor assembly contracts as automotive OEMs establish direct supplier relationships. Three-tier pricing structure across premium, standard, and economy levels separates grain boundary diffusion formulations from conventional sintered grades and bonded alternatives. Pricing pressure stems from dysprosium supply volatility in Chinese separation facilities, with volume-sensitive wind turbine developers exhibiting highest price sensitivity and medical imaging OEMs showing lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare-earth oxide refining, where Jiangxi and Inner Mongolia separation facilities control heavy rare-earth outputs. Raw material dependencies center on neodymium, dysprosium, and terbium oxides. Tariff exposure runs through EU Green Deal provenance mandates and US IRA domestic content thresholds. Distribution feeds from integrated mine-to-magnet operators in Japan through tiered qualification protocols to automotive and wind turbine OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high performance magnet market functions as a regulatory compounder, with EU Green Deal heavy rare-earth provenance mandates and US IRA domestic content thresholds accelerating demand fragmentation across qualified supply corridors.
For Market Incumbents: Deploy grain boundary diffusion R&D to reduce critical element content by half while maintaining coercivity. Defend against emerging hot-pressed nanocrystalline entrants by locking long-term offtake agreements with Australian oxide suppliers. Expand certification investments for REACH-compliant separation facility traceability systems to preempt regulatory disqualification. For New Entrants and Emerging Players: Capture bonded magnet retrofit opportunities in small motor robotics applications where net-shape forming eliminates machining waste. Target German industrial automation supply chains with injection-molded multipole geometries. Pursue direct qualification with automotive OEMs disintermediating tiered supplier hierarchies. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier sintered compounders lacking upstream oxide control. Long-term viability hinges on backward integration into rare-earth separation or captive offtake from Australian upstream projects. Watch Japanese METI industrial policy signals as inflection indicators for Western supply diversification momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Separation | Proterial's captive oxide refining in Japan insulates Western automotive OEMs from Chinese export quota volatility. |
| Grain Boundary Diffusion Scale-Up | Toyota's vapor-phase dysprosium infiltration reduces critical element dependence while preserving thermal stability thresholds. |
| Hot-Pressed Nanocrystalline Capacity Buildout | Deformation processing routes below 300 nanometers enable thermal performance that sintered alternatives cannot match. |
| EU Green Deal Qualification Audits | European wind turbine developers accelerate Japanese and Australian upstream sourcing to satisfy provenance mandates. |
| Direct OEM Supply Contracting | BMW and Volkswagen bypass e-axle integrators to specify magnetic properties and secure volume commitments independently. |
Research Methodology
Coverage spans Japan, Germany, China, and the United States, with primary inputs from each magnet manufacturing corridor. The research combines interviews with powder metallurgy sintering engineers, automotive OEM powertrain procurement leads, wind turbine generator sourcing managers, and rare-earth separation facility operators with secondary validation from SEC filings, METI industrial policy disclosures, ECHA substance registration databases, and customs trade flow records. Bottom-up capacity assessments triangulate against top-down demand modeling across end-use verticals.
Rate-of-change decomposition separates volume growth from price evolution and mix shifts across the projection horizon. Segmentation dimensions include magnet alloy composition, processing technology, application torque density requirements, and regional regulatory compliance tier. CAGRs derive from fitted growth curves applied to qualified capacity expansion announcements and OEM contract visibility. Industry-specific forecast inputs incorporate dysprosium spot price volatility bands and REACH compliance cost trajectories.
Export quota fluctuations, metallurgical engineering talent scarcity, and dual-use export control delays are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about separation facility consolidation timelines and automotive motor architecture transitions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.