
 Coordinate Measuring Machine Market | 2026-2036
Coordinate Measuring Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Coordinate Measuring Machine Market Intelligence
Software-defined inspection routines and predictive maintenance subscriptions is hardening into the core revenue model for CMM vendors. Hexagon AB leverages its PC-DMIS ecosystem to lock in recurring service revenue across aerospace and automotive accounts. ZEISS sustains premium positioning through proprietary sensor fusion and captive optics manufacturing. Mitutoyo Corporation anchors its competitive stance with dense distributor networks across Asian manufacturing corridors.
A coordinate measuring machine is a precision electromechanical system that probes or optically scans a workpiece to determine geometric dimensions and tolerances, typically achieving sub-micron repeatability through granite base structures and temperature-compensated scales. Its primary industrial purpose is to verify conformance to engineering specifications in high-value manufacturing environments. Bridge-type CMMs dominate installed base volume due to their cost-efficiency for medium-sized components, while optical and 3D vision technologies capture the fastest expansion as electronics miniaturization outpaces mechanical probe capabilities. Quality control applications absorb the largest share of end-user spending, though reverse engineering margins prove superior for vendors selling integrated scanning software bundles.
ISO 10360 calibration protocols govern dimensional traceability across EU and North American supply chains, compelling vendors to maintain accredited service infrastructure. The U.S. FDA and FAA impose stringent measurement documentation requirements on medical device and aerospace suppliers, respectively, which elevates demand for certified CMM platforms with audit-ready data logging. China's SAMR enforces GB standard alignment for imported metrology equipment, creating compliance barriers for non-domestic vendors. Stakeholders must weigh captive software ecosystems against open-architecture interoperability as the decisive procurement criterion.
Market Dynamics
Software-defined inspection routines and predictive maintenance subscriptions are hardening into the core revenue model for CMM vendors, compressing hardware margins while expanding recurring service attach rates across aerospace and automotive accounts.
Growth Catalysts
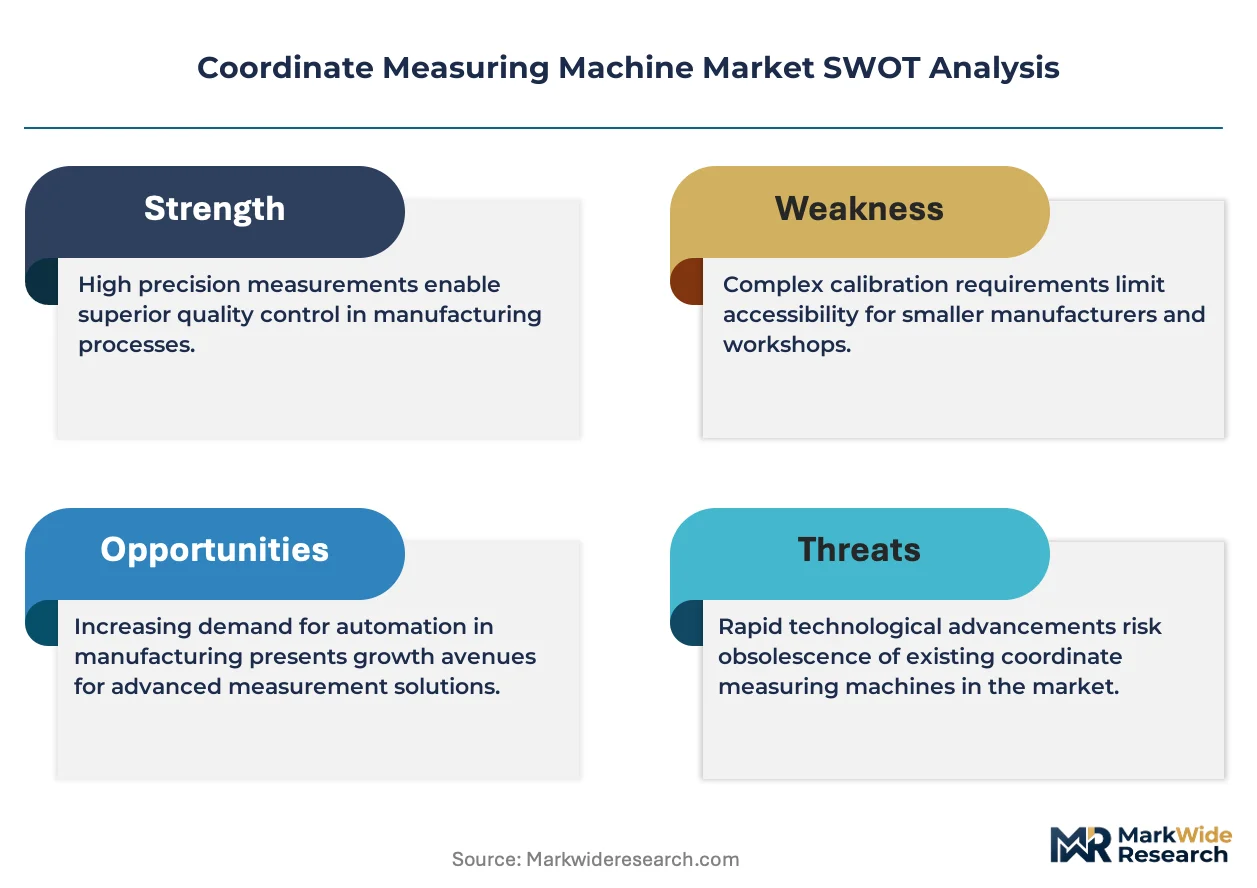
- ISO 10360 calibration protocols:Dimensional traceability mandates across EU and North American supply chains compel vendors to maintain accredited service infrastructure, locking in long-term service contracts.
- Electric vehicle powertrain validation:Automotive OEMs are expanding metrology adoption for EV motor housing and battery tray dimensional verification, creating sustained equipment refresh cycles.
- Granite base thermal stability:Sub-micron repeatability requirements in precision engineering clusters drive specification upgrades for temperature-compensated scale systems.
Market Restraints
- Optical sensor input cost volatility:Specialized CMOS arrays and laser interferometer components face supply concentration from Japanese and German component suppliers, compressing gross margins on entry-level systems.
- GB standard alignment friction:China's SAMR enforces domestic certification requirements for imported metrology equipment, creating compliance barriers and extended approval timelines for non-domestic vendors.
- 3D vision substitution threat:Structured light and photogrammetry systems are capturing dimensional verification applications below 50-micron tolerance thresholds, eroding bridge-type CMM addressable market in electronics assembly.
Strategic Opportunities
- India precision engineering corridors:BIS standard harmonization and PLI scheme incentives for advanced manufacturing are creating first-mover advantages for vendors establishing localized calibration laboratories.
- Medical device additive manufacturing:Orthopedic implant lattice structures require internal geometry validation that optical CMMs can penetrate, opening new application white space beyond surface probing.
- AI-driven defect prediction convergence:Machine learning models trained on CMM point clouds are converging with MES platforms, enabling real-time process correction and premium software bundling opportunities.
Industry Challenges
- Dimensional metrology technician scarcity:Specialized skills in probe calibration, thermal compensation modeling, and GD&T interpretation are concentrating in Germany and Japan, constraining service expansion.
- Legacy DCC controller integration complexity:Brownfield installations require protocol bridging between proprietary motion controllers and modern IoT data architectures, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coordinate Measuring Machine Market |
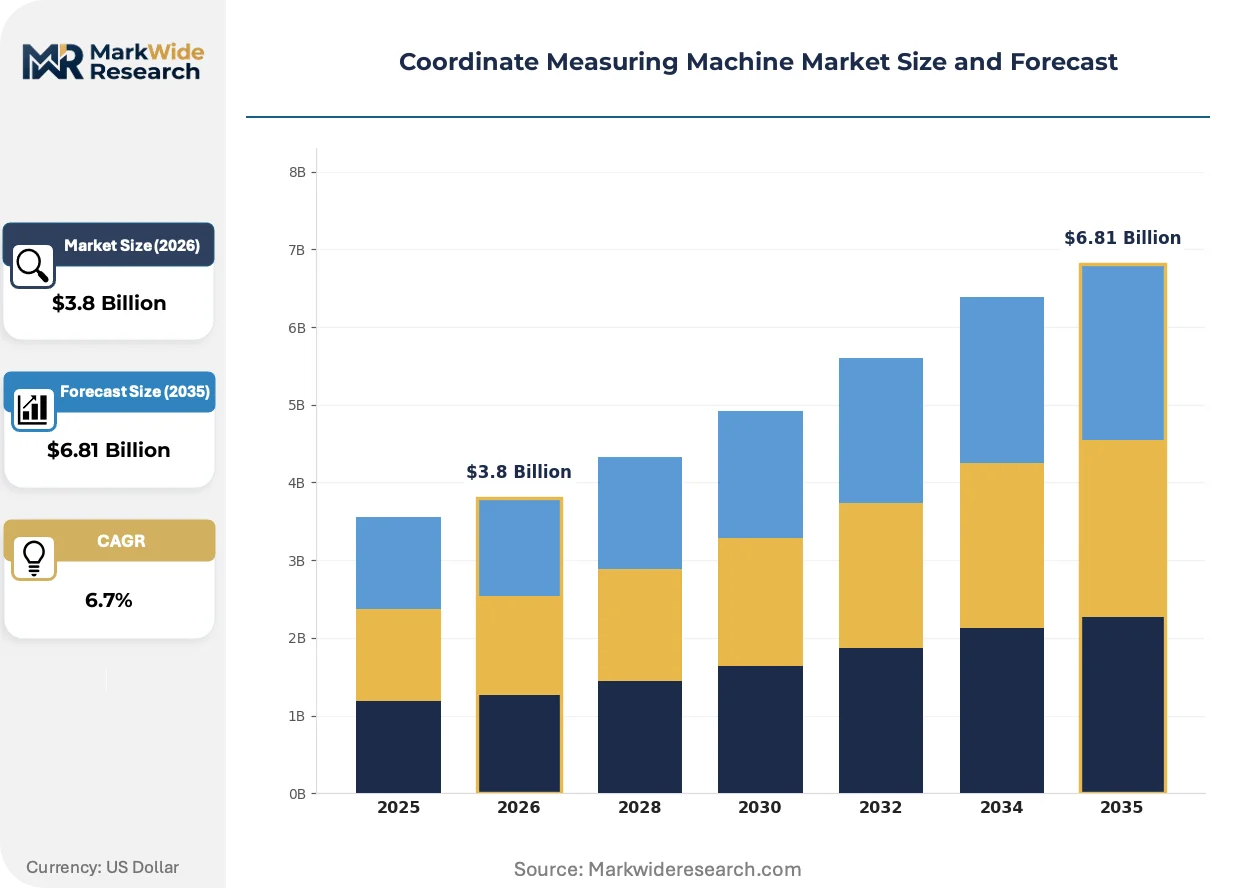
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Arm, Bridge, Gantry, Horizontal Arm Technology: Optical, Laser, Mechanical, 3D Vision End User: Aerospace, Automotive OEMs, Electronics Manufacturing, Industrial Machinery Application: Quality Control, Reverse Engineering, Assembly Verification, Prototyping |
| Companies Covered | Hexagon AB, ZEISS, Nikon Corporation, FARO Technologies, Keyence Corporation, Mitutoyo Corporation, Renishaw plc, Creaform, Wenzel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coordinate Measuring Machine Market Strategic Shifts & Innovations
Multi-sensor fusion architectures and cloud-native inspection programming are actively displacing standalone mechanical probing systems, while regulatory documentation requirements harden software ecosystems into competitive moats.
Optical and 3D vision technologies are converging with traditional mechanical CMM platforms to form hybrid inspection cells capable of simultaneous surface and internal geometry capture. Aerospace tier-one suppliers are adopting these configurations for turbine blade cooling channel validation. This convergence is compressing the addressable market for pure-play mechanical probe vendors while expanding premium system average selling prices.
EU MDR and FDA 21 CFR Part 11 documentation mandates are elevating audit-ready data logging from optional feature to procurement prerequisite. Medical device manufacturers now require immutable measurement records with electronic signatures. This regulatory pressure is forcing mid-tier vendors to either license compliant software stacks or exit certified segments entirely.
Buyer preference is rotating toward subscription-based predictive maintenance and remote diagnostic capabilities that unbundle traditional annual service contracts. Automotive supply chain accounts in Stuttgart and Nagoya corridors are piloting usage-based calibration scheduling. This behavioral shift is most visible among high-volume production environments where unplanned downtime costs exceed preventive service premiums.
Coordinate Measuring Machine Market Segmentation
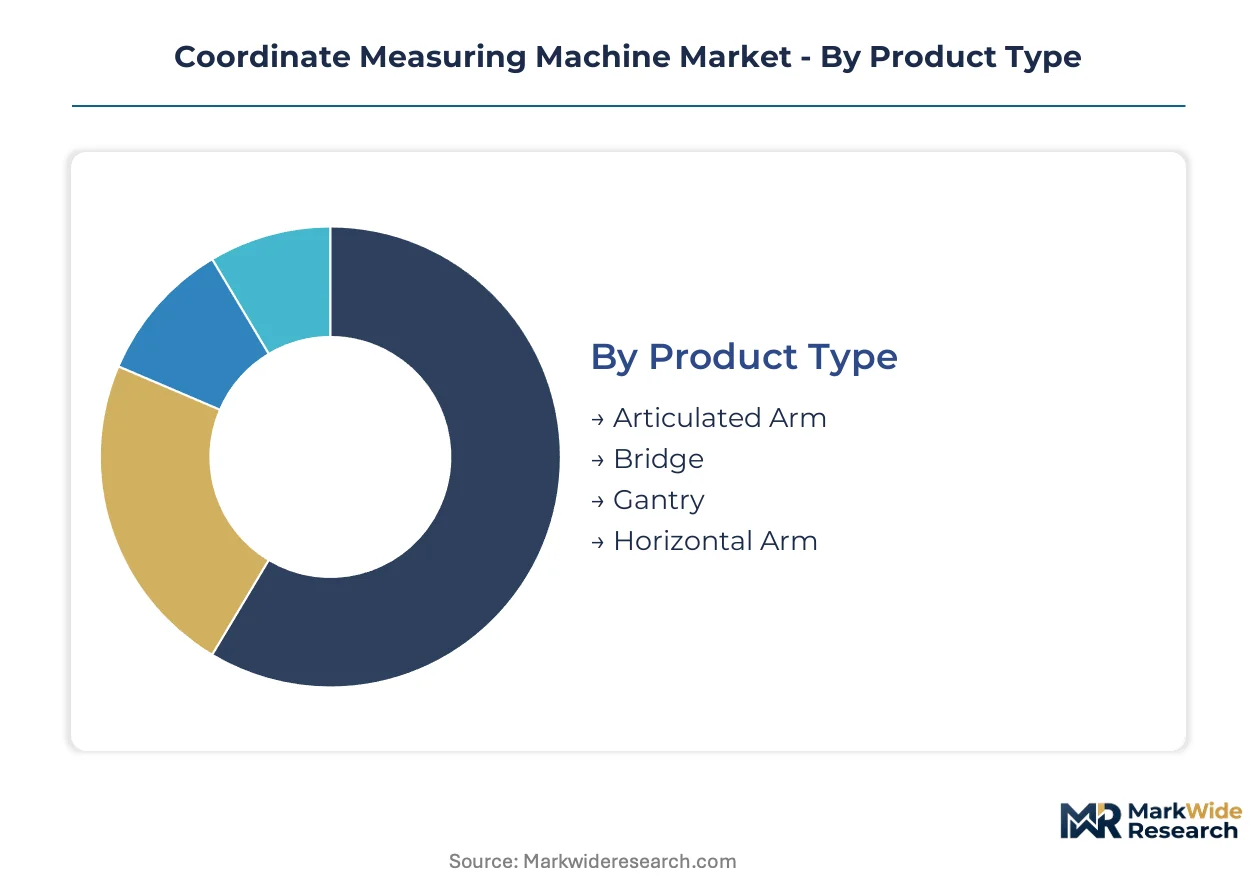
Segmentation in coordinate measuring machines reveals how buyer priorities diverge across precision thresholds, production volumes, and regulatory exposure. Equipment specifications, sensor modalities, and end-use compliance requirements create distinct procurement patterns that vendors must address through differentiated product architectures.
Product Type:
Cost tier separates buyers seeking entry-level dimensional verification from those demanding sub-micron stability for high-value components.
- Bridge:Granite base structures with temperature-compensated scales deliver sub-micron repeatability for medium-sized automotive and aerospace components. Demand concentrates in Germany's precision engineering clusters where ISO 10360 calibration mandates sustain equipment refresh cycles.
- Gantry:Oversized bridge configurations accommodate aircraft fuselage sections and wind turbine blades with multi-meter measuring volumes. Aerospace tier-one suppliers in Toulouse and Hamburg corridors specify these systems for assembly verification of large-format carbon fiber structures.
- Articulated Arm:Portable six-axis configurations enable shop-floor probing without part repositioning. Shop-floor metrology teams in industrial machinery plants favor these for in-process inspection of welded assemblies.
- Horizontal Arm:Cantilevered designs optimize access for vehicle body-in-white measurement. Automotive OEMs in Stuttgart and Nagoya deploy these for full-vehicle dimensional auditing.
Volume sits with Bridge configurations; growth tilts toward Gantry systems as aerospace component scales expand.
Technology:
Application tolerance thresholds determine sensor selection, with mechanical probing yielding to optical methods as electronics miniaturization accelerates.
- Mechanical:Touch-trigger probes remain the reference standard for ISO 10360 traceability in automotive powertrain validation. Germany's automotive supply chain maintains the densest installed base of probe-based systems for crankshaft and camshaft measurement.
- 3D Vision:Structured light and photogrammetry arrays capture free-form surfaces without contact risk to delicate electronics. Electronics manufacturing corridors in Shenzhen and Seoul are expanding these systems for smartphone housing dimensional verification.
- Optical:Vision-based edge detection serves high-throughput inspection of stamped metal components. Tier-two automotive suppliers specify these for brake disc and wheel rim geometric verification.
- Laser:Triangulation and interferometric methods enable non-contact scanning of reflective or soft surfaces. Medical device manufacturers deploy these for orthopedic implant surface characterization.
Mechanical systems retain the largest installed base; 3D Vision is climbing the fastest as semiconductor packaging tolerances tighten below 10 microns.
End User:
Regulatory documentation intensity varies sharply across end users, with aerospace and medical device manufacturers facing the most stringent audit requirements.
- Automotive OEMs:EV powertrain validation demands are expanding metrology adoption for motor housing and battery tray dimensional verification. Stuttgart, Wolfsburg, and Nagoya corridors are driving sustained equipment procurement for electric vehicle platforms.
- Aerospace:FAA and EASA documentation mandates require immutable measurement records with electronic signatures. Turbine blade manufacturers in Hartford and Derby specify multi-sensor CMMs for cooling channel internal geometry validation.
- Electronics Manufacturing:Miniaturization trends are displacing mechanical probes with optical systems for PCB and connector inspection. South Korean and Taiwanese semiconductor packaging facilities are leading sensor technology transitions.
- Industrial Machinery:Heavy equipment producers prioritize durability and shop-floor environmental tolerance over sub-micron precision. German and Japanese machine tool builders favor robust bridge configurations for large casting verification.
Automotive OEMs represent the largest equipment purchaser; aerospace commands the highest average selling prices through regulatory compliance bundling.
Application:
Margin structure diverges between high-volume quality control workflows and specialized reverse engineering services requiring integrated software bundles.
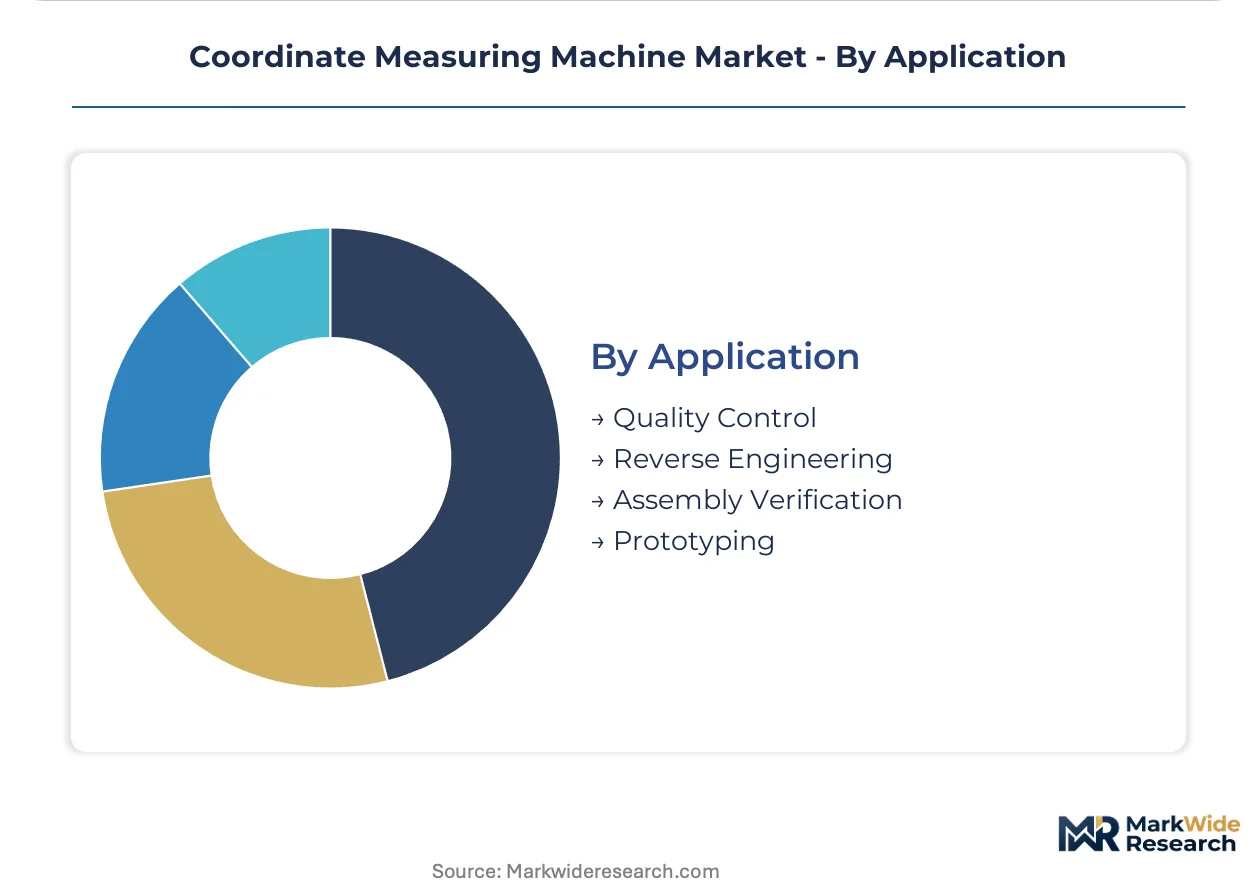
- Quality Control:Statistical process control integration drives specification of automated CMM cells with robotic part handling. Automotive stamping plants in Detroit and Shanghai corridors deploy these for 100% dimensional auditing of critical safety components.
- Reverse Engineering:Point cloud processing and CAD reconstruction software command premium pricing for legacy part replication. Aerospace MRO facilities in Singapore and Toulouse utilize these capabilities for obsolete turbine component reproduction.
- Assembly Verification:In-line CMM stations confirm fit-up tolerances before downstream welding or bonding operations. Wind turbine manufacturers specify these for blade root flange mating surface verification.
- Prototyping:Rapid iteration cycles demand flexible fixturing and program-free measurement routines. Formula 1 constructors and automotive design studios in Milton Keynes and Munich favor these for concept validation.
Quality Control absorbs the greatest equipment volume; reverse engineering generates the steepest expansion trajectory through software attach rate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and Japan where precision engineering heritage supports captive component supply, while consumption spreads across automotive and aerospace corridors in the United States, China, and South Korea where end-user validation demand drives equipment imports.
United States
FAA documentation mandates for aerospace suppliers and FDA 21 CFR Part 11 requirements for medical device manufacturers sustain premium CMM procurement. The country's national aviation regulator enforces immutable measurement records with electronic signatures. Hartford, Connecticut hosts dense turbine blade manufacturing clusters where multi-sensor systems validate cooling channel geometries.
Germany
Automotive OEM powertrain validation and ISO 10360 calibration protocol adherence anchor equipment refresh cycles. The country's national standards body maintains stringent dimensional traceability requirements across supply chains. Stuttgart and Wolfsburg corridors concentrate EV motor housing metrology adoption for electric vehicle platforms.
China
Electronics miniaturization and semiconductor packaging expansion accelerate optical CMM demand. SAMR enforces GB standard alignment for imported metrology equipment, creating compliance barriers for foreign vendors. Shenzhen and Shanghai manufacturing corridors deploy structured light systems for smartphone housing dimensional verification.
Japan
Automotive supply chain density and precision component export requirements sustain mechanical probe system demand. METI oversees industrial standards harmonization with international calibration protocols. Nagoya and Toyota City corridors maintain the densest installed base of bridge-type CMMs for crankshaft and camshaft measurement.
South Korea
Semiconductor packaging tolerance tightening below 10 microns displaces mechanical probing with 3D vision systems. The country's national semiconductor regulator coordinates advanced packaging roadmaps with metrology equipment specifications. Seoul and Suwon electronics manufacturing corridors lead sensor technology transitions for PCB and connector inspection.
Coordinate Measuring Machine Market Key Industry Players
Top-tier vendors anchor premium positioning through captive software ecosystems and proprietary sensor fusion, while mid-tier competitors compete on distributor density and regional service reach. The vendor base stratifies across three archetypes: integrated metrology conglomerates with multi-industry software platforms, precision optics specialists leveraging captive manufacturing, and regional fabricators with dense calibration laboratory networks. Consolidation pressure intensifies as recurring service revenue models displace hardware-centric business structures. M&A activity targets software-defined inspection capabilities, while strategic partnerships bridge legacy controller protocols with cloud-native architectures.
Within the integrated conglomerate tier, Hexagon AB and ZEISS exemplify divergent competitive vectors—one leveraging PC-DMIS ecosystem lock-in across aerospace accounts, the other sustaining premium positioning through proprietary optics manufacturing. Mitutoyo Corporation occupies a position among Asia-Pacific distributors with dense calibration infrastructure across manufacturing corridors. These three entities represent the archetype spectrum: software platform dominance, vertical manufacturing control, and service network density.
| Leading Market Players |
|---|
| Hexagon AB |
| ZEISS |
| Nikon Corporation |
| FARO Technologies |
| Keyence Corporation |
| Mitutoyo Corporation |
| Renishaw plc |
| Creaform |
| Wenzel Group |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists in Germany and Japan anchor component manufacturing for granite base structures and precision scales, translating captive production control into pricing discipline that resists commoditization pressure from Asian system integrators. Their ownership structure insulates long-term R&D cycles from quarterly margin scrutiny, sustaining premium positioning against private-equity-rolled competitors chasing service revenue multiples.
Pricing Analysis
Margin tightening in entry-level bridge configurations traces to 3D vision substitution for electronics assembly applications below 50-micron thresholds. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10360-certified systems with audit-ready data logging from uncertified shop-floor units. Cost-down pressure accelerates as Chinese domestic vendors achieve GB standard alignment and undercut import pricing. Automotive OEMs in Stuttgart and Nagoya corridors exhibit lowest price sensitivity due to unplanned downtime costs exceeding preventive service premiums, while tier-two electronics manufacturers in Shenzhen drive hardest bargain negotiations.
Supply Chain Analysis
Specialized metrology technician scarcity in Germany and Japan constrains calibration laboratory expansion and extends order fulfillment timelines for accredited service contracts. Granite quarrying draws from Bavarian and Tamil Nadu deposits for base structures, while temperature-compensated scale manufacturing rests on Japanese and German component suppliers. Single-source vulnerability concentrates in specialized CMOS arrays and laser interferometer inputs. Distribution runs through dense distributor networks across Asian manufacturing corridors, with Mitutoyo's channel density setting the competitive benchmark for regional service reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision metrology technician training pipeline limitations prop pricing power for vendors with captive certification infrastructure, creating supply-constrained conditions that favor incumbents with established service networks.
For Market Incumbents: Lock in recurring revenue through predictive maintenance subscriptions that unbundle traditional annual service contracts, defending against 3D vision substitution threats in electronics assembly by accelerating multi-sensor fusion R&D. Deepen backward integration into proprietary optics manufacturing to sustain margin differentiation from Asian competitors achieving GB standard compliance. Channel control through accredited calibration laboratory density remains the decisive lever for aerospace and medical device accounts facing FAA and FDA documentation mandates. For New Entrants and Emerging Players: India's PLI scheme incentives for advanced manufacturing and BIS standard harmonization open a window for establishing localized calibration laboratories ahead of first-mover infrastructure commitments from established vendors. Target medical device additive manufacturing applications requiring internal geometry validation that optical CMMs penetrate, where orthopedic implant lattice structures create application white space beyond surface probing capabilities. Go-to-market positioning should emphasize AI-driven defect prediction convergence with MES platforms for real-time process correction. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-defined inspection specialists with cloud-native architectures in North American aerospace corridors, where regulatory documentation requirements harden software ecosystems into durable competitive moats. Long-term viability hinges on recurring service attach rates displacing hardware-centric revenue structures. Watch for inflection signals in automotive EV powertrain validation procurement cycles, where motor housing and battery tray dimensional verification demands sustain equipment refresh trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Fusion R&D Investment | Hybrid inspection cells capture turbine blade cooling channel validation from pure-play mechanical probe vendors. |
| Cloud-Native Inspection Programming Platform | Subscription-based predictive maintenance unbundles annual service contracts for high-volume automotive accounts. |
| Accredited Calibration Laboratory Expansion | ISO 10360 compliance infrastructure locks in long-term service contracts across EU and North American supply chains. |
| AI-Driven Defect Prediction Integration | Machine learning models trained on CMM point clouds enable real-time process correction with MES platform convergence. |
| Regional Distributor Network Deepening | Dense Asian manufacturing corridor coverage sets competitive benchmark for localized service response capabilities. |
Research Approach
Independent corroboration across primary interviews with metrology equipment procurement managers, calibration laboratory directors, aerospace quality engineers, and automotive powertrain validation specialists underwrites the qualitative findings. Secondary validation draws from ISO 10360 accreditation databases, FDA 21 CFR Part 11 guidance documents, SAMR GB standard filings, and SEC 10-K disclosures from listed precision equipment manufacturers. Bottom-up segmentation modeling triangulates against top-down industry association estimates from VDMA and JMTBA.
Rate-of-change decomposition across the analysis window isolates volume drivers from value drivers, with CAGRs derived from segment-level growth trajectories weighted by end-user spending intensity. Segmentation dimensions span product architecture, sensor modality, end-use regulatory exposure, and geographic production cluster. Forecast inputs incorporate EV platform rollout schedules, semiconductor packaging tolerance roadmaps, and medical device additive manufacturing adoption curves without specific year anchoring.
The model assumes a particular technology adoption path; alternative pathways for 3D vision substitution would alter the outlook for bridge-type CMM addressable market. Forecasts reflect assumptions regarding ISO 10360 calibration protocol adherence, GB standard alignment timelines, and precision metrology technician training pipeline expansion. Material deviation in EV powertrain validation procurement intensity or FAA documentation mandate enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Handheld DC Torque Tools Market
Industrial Tools
Electric Tools Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Machine Tool Touch Probe Market
Industrial Tools
Tool Holder Market
Industrial Tools
Deburring Machine Market
Industrial Tools
Jigs and Other Tools Market
Industrial Tools
Air Screwdrivers Market
Industrial Tools
Global Tool Presetters Market
Industrial Tools
Dies, Jigs and Other Tools Market
Industrial Tools
Height Gauge Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
India Power Tool Market
Industrial Tools
Digital Tool Presetter Market