
 Dies, Jigs and Other Tools Market | 2026-2036
Dies, Jigs and Other Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Dies, Jigs and Other Tools Market Intelligence
A shift from in-house tool fabrication towards outsourced, specialized providers is realigning the competitive landscape for dies and jigs. This trend allows original equipment manufacturers to focus on core assembly operations. Kennametal, Inc. leverages its material science expertise to offer high-performance cutting tools. Schuler AG specializes in forming dies for the automotive sector, while MISUMI Group, Inc. provides a vast catalog of standardized components for jigs and fixtures.
Dies, jigs, and other tools are specialized devices used to cut, shape, or hold materials during manufacturing processes. These tools, often made from hardened tool steel or carbide, must maintain high-precision tolerances to ensure product consistency. Within product types, press dies for metal stamping applications in the automotive industry constitute a major segment. The consumer electronics end-user industry drives demand for intricate forming dies and jig fixtures used in electronics assembly.
Regulatory frameworks significantly influence tool design and operational safety. In the United States, OSHA standards mandate machine guarding, while CE marking in Europe certifies that jigs and fixtures meet health and safety requirements. Similarly, China's GB standards govern industrial equipment specifications. Stakeholders must now decide whether to invest in advanced automation and digital twinning for tool design verification to meet evolving production demands.
Market Dynamics
The structural shift from vertically integrated in-house tool rooms to outsourced specialist providers is fundamentally altering the market. This unbundling allows original equipment manufacturers to reduce capital intensity and focus on core competencies like product design and final assembly.
Growth Catalysts
- Additive Manufacturing:The proliferation of 3D printing enables the rapid production of complex, lightweight jigs and fixtures, particularly for the aerospace and medical device industries where customized, low-volume tools are essential for precision assembly.
- Automotive Sector Expansion:Sustained investment in new electric vehicle platforms in manufacturing centers like Germany and Japan drives significant demand for new press dies, stamping tools, and assembly jigs for high-volume production lines.
- Industrial Policy Support:Government initiatives, such as India's Production Linked Incentive (PLI) scheme, stimulate domestic manufacturing across various sectors, creating a direct downstream pull for a wide range of industrial tooling to equip new factories.
Market Restraints
- Raw Material Price Volatility:The market is highly sensitive to fluctuations in the cost of specialty materials like high-strength tool steel, tungsten carbide, and cobalt, which are critical for tool longevity and performance and subject to global supply chain disruptions.
- High Initial Investment:The substantial upfront capital and long lead times required to engineer, build, and test large, multi-stage progressive dies for applications like automotive body panels create a significant barrier to entry and limit supplier flexibility.
- Threat of Near-Net-Shape Processes:Alternative manufacturing methods such as precision casting and metal injection molding (MIM) can produce parts that require less secondary machining, thereby reducing the need for certain types of cutting and finishing tools.
Strategic Opportunities
- Digital Twin Integration:There is a significant opportunity for toolmakers to offer digital twinning services, creating virtual models of dies and jigs for simulation and process verification, which drastically cuts down physical trial-and-error cycles for manufacturers.
- Medical Device Tooling:The growing demand for miniaturized and biocompatible medical devices presents a high-margin opportunity for specialists in micro-molding, micro-stamping dies, and precision fixtures used in cleanroom assembly environments.
- Tool-as-a-Service (TaaS) Models:Shifting from outright tool sales to performance-based contracts, where customers pay per part produced, aligns tool provider incentives with OEM production efficiency and lowers the adoption barrier for advanced tooling.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of qualified tool and die makers, who possess the combined expertise of traditional craftsmanship and modern CAD/CAM programming, poses a significant operational bottleneck for tool shops globally.
- Legacy System Integration:Integrating modern, automated tooling systems equipped with sensors and IoT connectivity into older manufacturing plants with legacy control systems presents significant technical and interoperability challenges for plant engineers.
- Compliance Across Jurisdictions:Tool exporters face the complexity and cost of validating that their products meet divergent regional safety and design standards, such as CE marking in Europe, OSHA requirements in the US, and GB standards in China.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dies, Jigs and Other Tools Market |
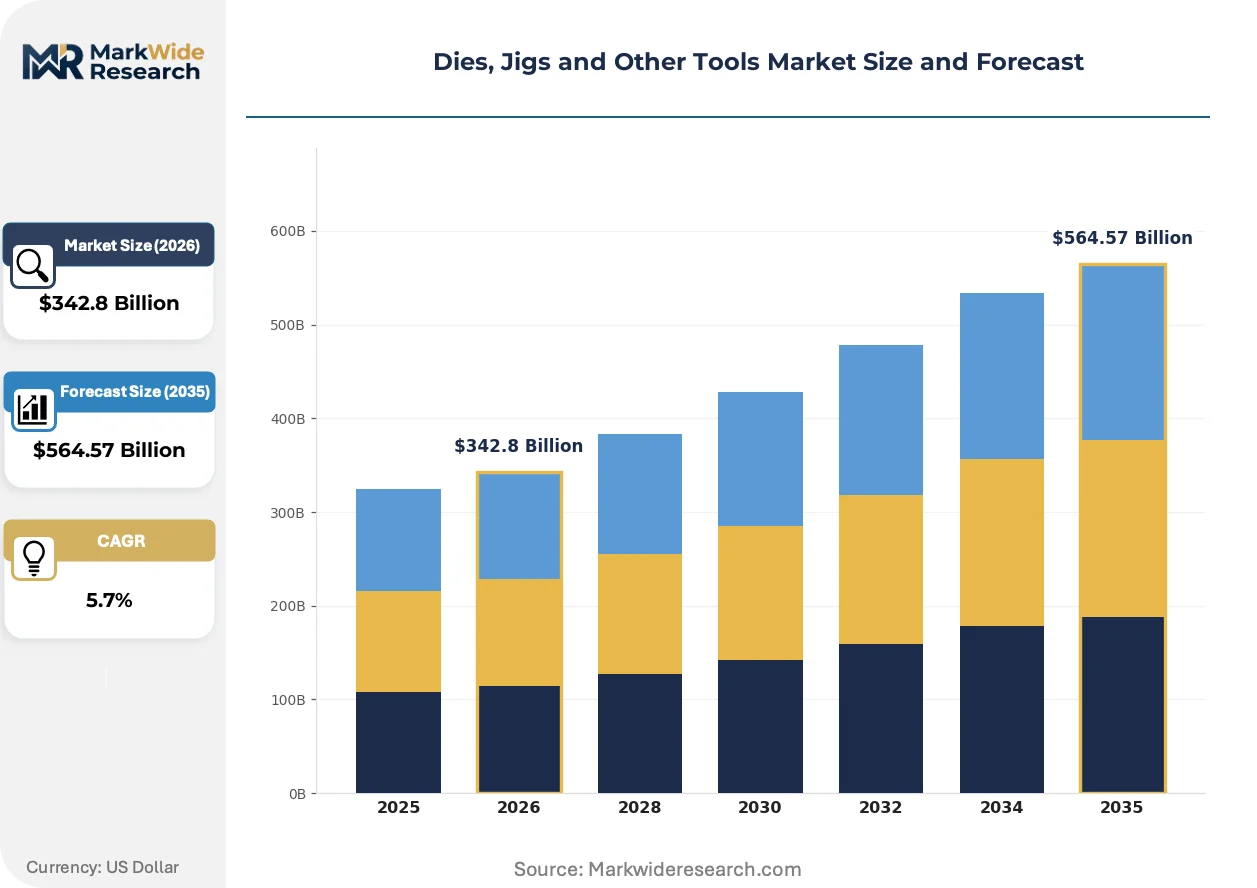
| Market Size in 2026 | $342.8 Billion |
| Market Size in 2035 | $564.57 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Press Dies, Cutting Tools, Forming Dies, Jig Fixtures, Tool Holders Technology: CNC Machining, EDM, 3D Printing, Laser Cutting, Wire Cutting Application: Metal Stamping, Plastic Molding, Woodworking, Textile Manufacturing, Electronics Assembly End User Industry: Consumer Electronics, Aerospace Manufacturers, Agricultural Equipment, Construction Machinery, Heavy Equipment Fabricators |
| Companies Covered | Kennametal, Inc., MISUMI Group, Inc., RotoMetrics, ALLMATIC-Jakob Spannsysteme GmbH, Midway Rotary Die Solutions, Dies Plus, Tipco Punch Inc., AWEBA Werkzeugbau GmbH, Schuler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dies, Jigs and Other Tools Market Strategic Shifts & Innovations
The convergence of material science and digital technology is transforming tooling from static, passive instruments into intelligent, performance-optimized assets. This evolution focuses on extending tool life, improving part quality, and integrating tooling data into broader manufacturing intelligence systems.
Additive manufacturing, particularly using metal powders, enables the creation of forming tools and jig fixtures with features impossible through traditional methods. Aerospace and automotive sectors are adopting this technology for creating prototypes and custom tools with conformal cooling channels that improve cycle times. For rapid, on-demand fixture creation, 3D printing is overtaking conventional CNC machining due to its speed and geometric freedom.
Workplace safety regulations are directly influencing tool and fixture design. In the United States, OSHA standards for machine guarding compel toolmakers to build safety features directly into die sets and jigs, rather than relying on secondary perimeter guarding. This affects tool design for automated press lines, where integrated light curtains and sensors within the tool itself are becoming standard practice.
A notable behavioral change involves OEMs transferring tooling asset management to third-party specialists. This model moves beyond simple fabrication outsourcing and includes responsibility for maintenance, repair, and inventory, effectively creating a service-based relationship. The practice is most advanced in the consumer electronics supply chain in Asia, where rapid product cycles make in-house tooling management impractical.
Dies, Jigs and Other Tools Market Segmentation
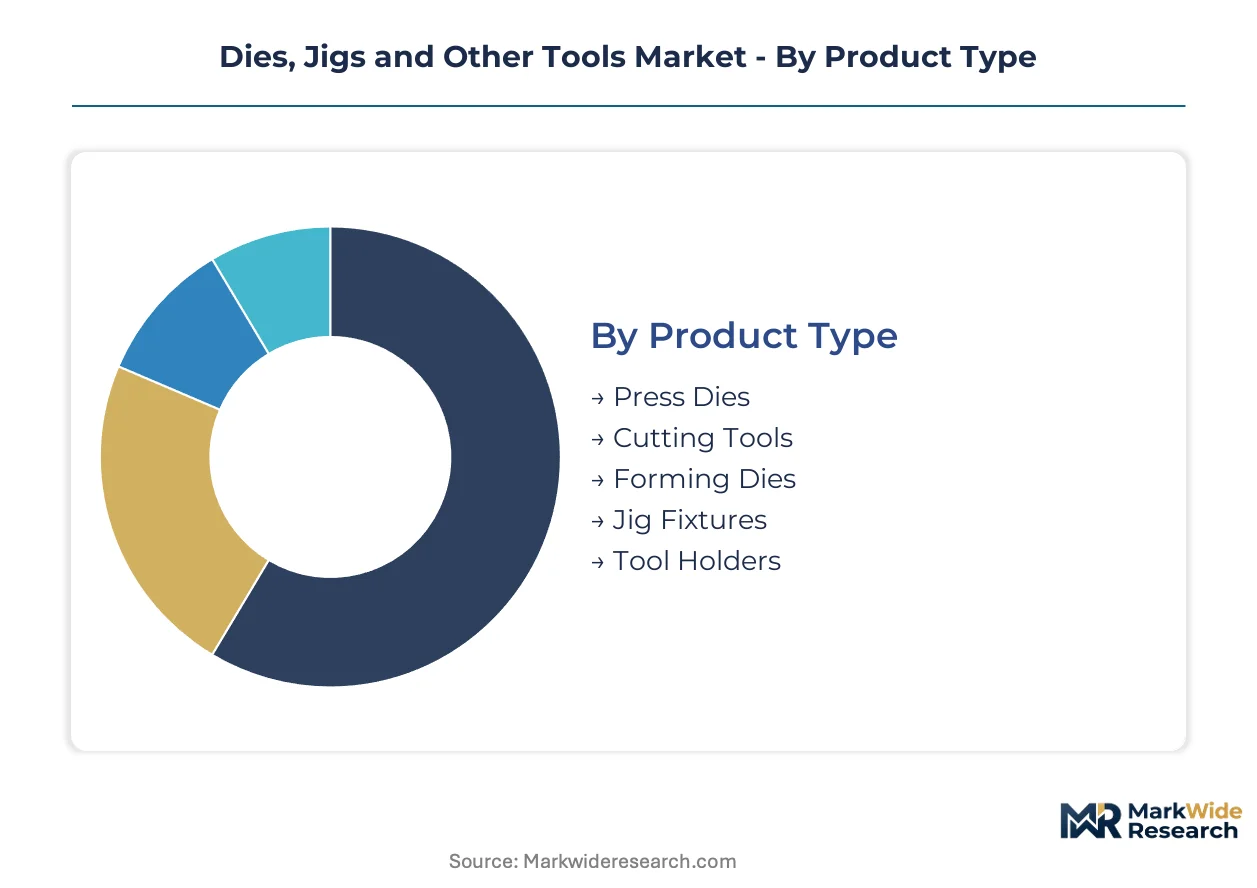
The Dies, Jigs and Other Tools Market is highly diversified, reflecting the specialized requirements of modern manufacturing processes. Analyzing market segments by product type, technology, application, and end-user industry reveals distinct growth opportunities and demand patterns for various tooling solutions. Understanding these segments helps stakeholders strategically align their offerings with specific industrial needs.
Product Type:
The market's product offerings are defined by their core operational specification and material interaction, ranging from material removal to precision holding. Each type serves a critical function in the production lifecycle, ensuring accuracy and repeatability in manufacturing.
- Press Dies:These robust tools are engineered for high-force metal stamping operations, shaping sheet metal into complex forms. Demand for press dies is particularly strong within automotive manufacturing centers like Germany and Japan for high-volume vehicle production.
- Forming Dies:Designed to shape materials without removing chips, these precision tools are crucial for creating intricate geometries. The consumer electronics industry drives significant demand for forming dies used in the assembly of miniaturized and complex device components.
- Cutting Tools:These tools remove material from workpieces, encompassing a wide range from drills to milling cutters. Manufacturers across general industrial sectors utilize cutting tools for various machining operations.
- Jig Fixtures:Devices used to hold workpieces securely and guide cutting tools, ensuring accuracy and interchangeability of parts. The aerospace industry relies on custom jig fixtures for precision assembly of complex airframe structures.
- Tool Holders:Components that secure cutting tools in a machine spindle, ensuring rigidity and precise positioning during machining.
Press Dies leads on scale; Jig Fixtures leads on momentum.
Technology:
Manufacturing processes employing dies and jigs leverage distinct technological approaches for precision and efficiency, influencing tool design and production methods. Advanced technologies enable the creation of more complex and performance-optimized tooling.
- 3D Printing:This additive manufacturing method builds complex, lightweight tools layer by layer, offering geometric freedom for intricate designs. Aerospace and medical device manufacturers adopt 3D printing for rapid prototyping and customized, low-volume tooling solutions.
- CNC Machining:Computer Numerical Control machining uses subtractive processes to produce high-precision tools from solid blocks of material. The automotive sector relies on CNC machining for creating durable, high-tolerance dies and molds for mass production.
- EDM:Electrical Discharge Machining creates intricate shapes and fine finishes using electrical sparks, particularly for hard materials. The mold and die making industry frequently employs EDM for precise cavity creation.
- Laser Cutting:This technology uses a focused laser beam to cut materials with high accuracy and minimal material distortion. It finds application in fabricating precise sheet metal components for jigs and fixtures.
- Wire Cutting:A specialized EDM process that uses a thin wire electrode to cut complex two-dimensional shapes in conductive materials.
Digital manufacturing methods are accelerating tool production speed and design complexity.
Application:
The utility of dies, jigs, and other tools spans diverse industrial applications, each requiring specialized tooling solutions to meet specific production needs. These applications dictate the design, material, and precision requirements for tooling.
- Metal Stamping:This application involves using press dies to cut and form sheet metal parts, a core process in high-volume manufacturing. The automotive industry extensively uses metal stamping for vehicle body panels and structural components.
- Electronics Assembly:Requires highly precise jigs and fixtures for positioning and joining small, delicate components in electronic devices. Consumer electronics manufacturers depend on these tools for accurate and efficient production of smartphones and other gadgets.
- Plastic Molding:Utilizes molds and dies to shape molten plastic into finished products through injection or blow molding. The packaging industry uses plastic molding for containers and various consumer goods.
- Woodworking:Employs specialized tools for cutting, shaping, and joining wood in furniture and construction. Custom cabinetry shops use woodworking tools for bespoke designs.
- Textile Manufacturing:Involves tools like cutting dies for fabric patterns and specialized jigs for sewing and assembly.
High-volume industrial processes dictate specific tooling requirements across manufacturing segments.
End User Industry:
Demand for specialized tooling originates from various end-user industries, each with unique production demands and regulatory environments. These industries drive innovation in tool materials, design, and manufacturing processes.
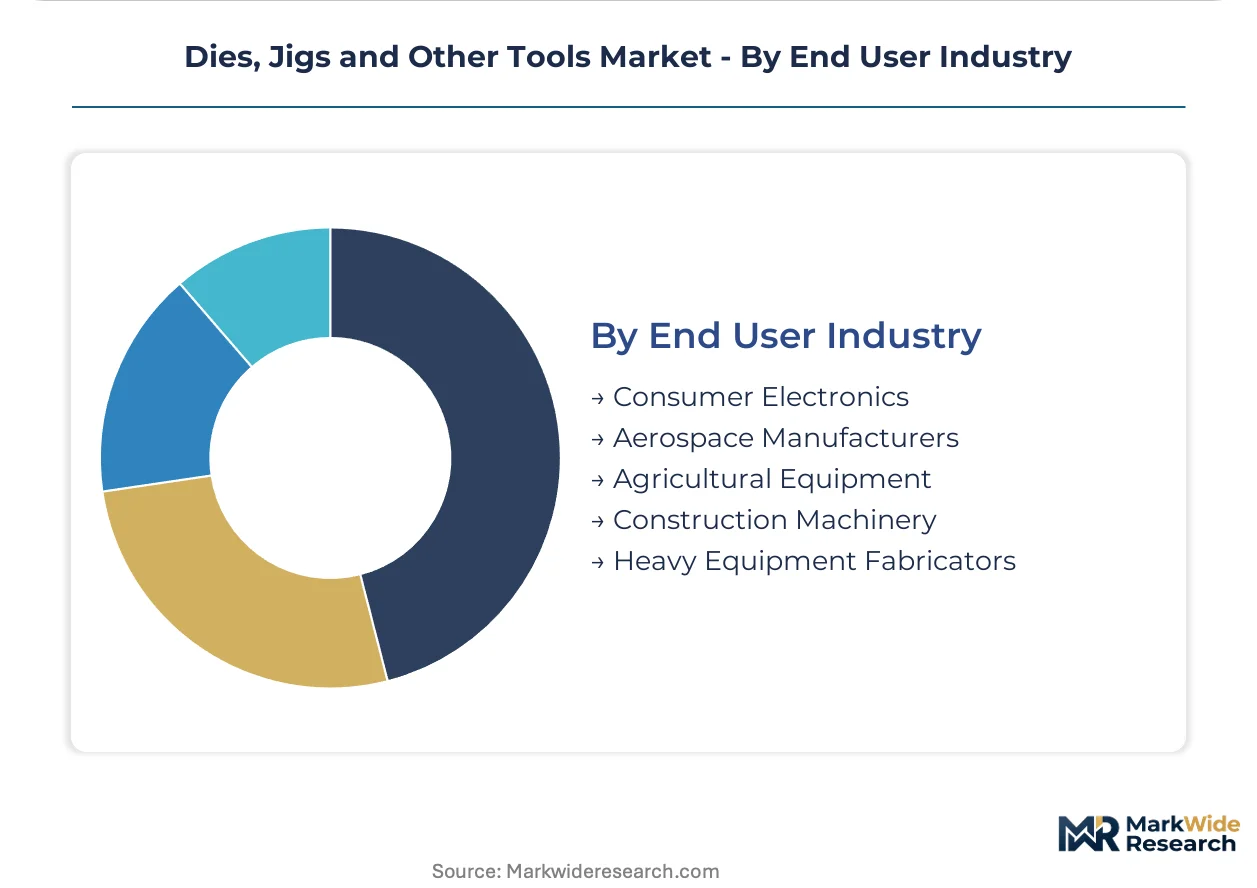
- Aerospace Manufacturers:This industry requires highly precise, lightweight, and custom tooling for complex airframe components and engine parts. The need for specialized jig fixtures for precision assembly is expanding for new aircraft programs.
- Consumer Electronics:Drives demand for intricate forming dies and jig fixtures used in the assembly of miniaturized and high-volume electronic devices. Rapid product cycles necessitate agile tooling solutions for smartphones and wearables.
- Agricultural Equipment:Utilizes robust dies and tools for fabricating heavy-duty components, including frames and engine parts. Manufacturers of tractors and harvesters require durable tooling for large-scale production.
- Construction Machinery:Employs heavy-duty tools for shaping and assembling large metal structures used in excavators and loaders. The sector demands resilient dies for thick material processing.
- Heavy Equipment Fabricators:Focuses on large-scale metal forming and cutting for industrial machinery and infrastructure projects.
The automotive sector sustains significant tooling investments, while aerospace manufacturers require highly specialized solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial heartland drives significant demand for dies, jigs, and other tools. This global market reflects diverse manufacturing needs and regional regulatory frameworks. Precision engineering and high-volume production define regional tooling requirements.
Germany
Automotive manufacturing and industrial machinery sectors sustain robust demand for press dies and high-precision cutting tools. CE marking ensures that tools meet stringent European health and safety requirements. The Stuttgart region, a major automotive hub, continuously invests in advanced forming dies for new vehicle platforms.
Japan
Japan's automotive and consumer electronics industries require advanced forming dies and intricate jig fixtures. JIS standards govern industrial equipment specifications, promoting quality and interchangeability. Manufacturing centers in Nagoya drive innovation in tool design for high-volume production lines.
United States
Aerospace manufacturers and general industrial sectors in the United States demand specialized tooling for complex components. OSHA standards mandate machine guarding, influencing tool design and operational safety. The Midwest manufacturing belt focuses on durable press dies for heavy equipment fabrication.
China
China's expanding consumer electronics and domestic manufacturing sectors generate substantial demand for intricate forming dies and jig fixtures. GB standards regulate industrial equipment specifications, impacting tool design and performance. The Yangtze River Delta region drives rapid prototyping and high-volume tool production.
India
India's Production Linked Incentive (PLI) scheme stimulates domestic manufacturing across various sectors, creating a direct pull for industrial tooling. This policy supports new factory setups requiring a wide range of dies, jigs, and other tools. The Pune region, an automotive and engineering hub, benefits from increased tooling investments.
Dies, Jigs and Other Tools Market Key Industry Players
Global majors compete with regional champions across technological sophistication and production scale within the dies, jigs, and other tools market. The landscape exhibits a tiered structure, with specialized providers focusing on niche applications and larger entities offering integrated solutions. Strategic archetypes include high-performance material science specialists, high-volume forming experts, and standardized component suppliers. Companies engage in portfolio diversification and technology licensing to maintain their market positions.
Specialists in material science and high-performance cutting tools, such as Kennametal, Inc., represent a premium segment focusing on tool longevity and precision. Schuler AG exemplifies expertise in large-scale forming dies, particularly for the automotive sector, where high-volume production demands robust solutions and consistent quality. MISUMI Group, Inc. occupies a position as a standardized component provider, serving diverse manufacturing needs with extensive catalogs of modular parts for jigs and fixtures. These entities collectively demonstrate the varied approaches to market engagement, from custom engineering to catalog-based supply, influencing procurement patterns across industries.
| Leading Market Players |
|---|
| Kennametal, Inc. |
| MISUMI Group, Inc. |
| RotoMetrics |
| ALLMATIC-Jakob Spannsysteme GmbH |
| Midway Rotary Die Solutions |
| Dies Plus |
| Tipco Punch Inc. |
| AWEBA Werkzeugbau GmbH |
| Schuler AG |
Cost & Logistics Intelligence
Raw material costs, particularly for specialty tool steels and carbides, directly influence the final price of dies and jigs supplied to automotive and aerospace manufacturers. These upstream material fluctuations propagate through the value chain, impacting toolmakers' margins.
Pricing Analysis
Input-cost pass-through remains a dominant factor, with tool steel and carbide prices directly influencing project-based pricing for custom dies and jigs. Price differentiation stems from the customization level required for intricate designs and certified quality grades for critical applications. Pricing softness reflects raw material price volatility, particularly for high-strength tool steel and cobalt. Aerospace and medical device manufacturers exhibit lower price sensitivity for precision tooling, while high-volume automotive production lines remain highly cost-conscious.
Supply Chain Analysis
Dual-sourcing requirements are common among large OEMs to mitigate risks associated with specialized tool suppliers. Supply concentrates heavily in manufacturing hubs like Germany, Japan, and China, reflecting their automotive and electronics production. The market draws from critical raw materials such as high-strength tool steel and tungsten carbide, creating vulnerability to global supply chain disruptions. Distribution runs through direct sales channels for custom dies and fixtures, complemented by catalog-based procurement for standardized components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dies, Jigs and Other Tools Market functions as a stable compounder, driven by continuous investment in advanced manufacturing technologies. This sustained innovation ensures steady demand for precision tooling across diverse industrial sectors.
For Market Incumbents: Hedge against the threat of near-net-shape processes by deepening vertical integration into advanced material science. Incumbents should invest in R&D for additive manufacturing, integrating conformal cooling channels into tool designs. Expanding digital twin integration for tool design verification reduces physical trial-and-error cycles. Pursuing certifications like CE marking and GB standards reinforces market position against regional competitors.
For New Entrants and Emerging Players: Begin with niche applications such as medical device tooling, targeting miniaturized and biocompatible components. The most penetrable segment involves customized, low-volume tools for precision assembly in cleanroom environments. New entrants can leverage additive manufacturing capabilities for rapid prototyping and complex jig fixtures. Offering Tool-as-a-Service (TaaS) models provides a differentiated go-to-market angle, lowering adoption barriers for OEMs.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized material science expertise meets digital integration capabilities within the tooling sector. The long-term viability of this market remains strong, anchored by the fundamental need for precision in advanced manufacturing. Investors should target specialized providers with proprietary digital twin technology or unique material science intellectual property. Increased M&A activity in tool asset management services or micro-molding specialists signals market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Addresses growing demand from electric vehicle platforms in Germany. |
| Digital Twin Integration | Reduces physical trial-and-error cycles for complex die designs. |
| Tool-as-a-Service (TaaS) Launch | Aligns tool provider incentives with OEM production efficiency goals. |
| Advanced Material R&D | Extends tool life and enhances performance for high-precision applications. |
| Global Regulatory Compliance | Facilitates market access and reduces export complexities across jurisdictions. |
Research Approach
Direct dialogue with tool and die makers, OEM procurement leads, and manufacturing engineers provided qualitative grounding for the analysis. This primary research was validated through extensive secondary data, including industry association reports, government manufacturing statistics from METI, and company annual filings. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and consistency.
A bottom-up approach aggregated market volumes across product types, technologies, and end-user industries, validated by top-down macroeconomic indicators over the projection horizon. The analysis modeled segmentation dimensions including product type, technology, application, end-user industry, and regional manufacturing output. Compound Annual Growth Rates were derived from historical growth trends and projected market dynamics. Key forecast inputs included automotive production forecasts and consumer electronics device shipments.
Several conditions sit outside the modeled scope, including unforeseen geopolitical conflicts or disruptive technological breakthroughs. Forecasts reflect assumptions concerning stable raw material supply and consistent industrial policy. Deviation in global trade policies or significant raw material supply shocks would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Die Grinders Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Centerless Grinding Market
Industrial Tools
India Power Tool Market
Industrial Tools
Height Gauge Market
Industrial Tools
Global Tool Presetters Market
Industrial Tools
Saudi Arabia Power Tools Market
Industrial Tools
Precision Components and Tooling Systems Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Handheld DC Torque Tools Market
Industrial Tools
Electric Tools Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Micro Welders Market
Industrial Tools
Deburring Machine Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
Insulated Screwdriver Market