
 Tool Wire Cutters Market | 2026-2036
Tool Wire Cutters Market Size, Share, and Industry Trends Forecast 2026-2036
Tool Wire Cutters Market Analytics
China is tilting toward higher-capacity forged-alloy production for professional-grade hand tools. Stanley Black & Decker leverages its multi-brand portfolio to control distribution across North American retail and industrial channels. Klein Tools specializes in electrically insulated cutter lines for utility and contractor trades. Robert Bosch anchors European demand through integrated battery-tool ecosystems that bundle cutters with cordless platforms.
Tool wire cutters are hardened-steel hand implements designed to sever, trim, or notch conductive and non-conductive wire with controlled mechanical advantage, typically achieving cutting edges hardened to 54-62 HRC for durability against tempered copper and steel cable. Flush cutters and diagonal cutters dominate volume in electronics assembly and electrical installation respectively, with the former commanding premium pricing on precision-ground edges for component-lead trimming. Alloy steel and high-speed steel formulations represent the fastest-expanding material tier as aerospace and automotive buyers specify cutters that withstand abrasive nickel-alloy and stainless harness wire without edge deformation.
OSHA mandates insulated-tool ratings for live electrical work in the United States, while REACH and RoHS frameworks in Europe restrict cadmium and hexavalent chromium in plating and alloy compositions. China's GB standards through SAMR enforce hardness and torque testing protocols that determine market access for domestic and imported brands. Stakeholders must monitor evolving dual carbon goals and material disclosure rules across these three regulatory zones to anticipate redesign cycles and sourcing shifts.
Market Dynamics
Tool wire cutter manufacturers face intensifying pressure from dual carbon mandates and REACH material restrictions that force alloy reformulation and plating process redesigns across European and Asian supply chains simultaneously.
Growth Catalysts
- OSHA insulated-tool mandates:Live-circuit work regulations in the United States drive specification of VDE-certified cutters among electrical contractors and utility maintenance crews.
- Aerospace harness wire specifications:Nickel-alloy and stainless steel cabling in aviation assembly lines demands cutters hardened beyond 58 HRC without edge chipping.
- Shenzhen-Dongguan manufacturing clusters:China's concentrated forging capacity enables rapid OEM turnaround for professional-grade hand tool brands serving export markets.
Market Restraints
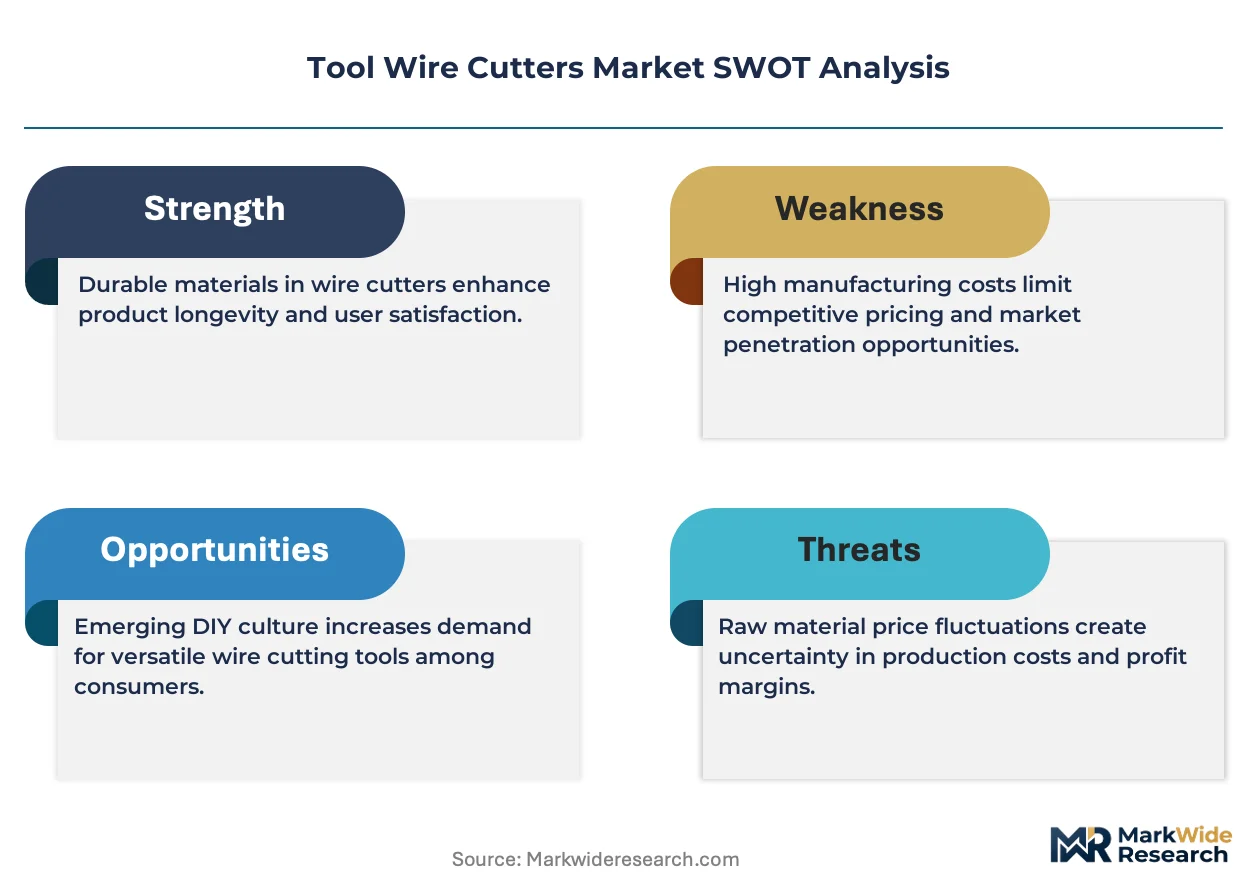
- Alloy steel input volatility:Molybdenum and vanadium price swings complicate margin planning for forged-alloy cutter producers.
- Single-source plating dependencies:Hexavalent chromium alternatives for corrosion resistance remain concentrated among German and Japanese chemical suppliers.
- Laser wire stripping substitution:Non-contact thermal methods displace mechanical cutters in high-volume electronics assembly for fine-gauge applications.
Strategic Opportunities
- India BIS certification pathways:Formal adoption of IS 60900 standards for insulated hand tools opens procurement channels for state electricity boards.
- Battery-tool ecosystem bundling:Cordless platform integration allows cutter placement alongside impact drivers and rotary tools in construction pro channels.
- Carbon accounting disclosure:EU CSRD scope 3 reporting requirements favor suppliers with verified low-emission forging and heat-treatment processes.
Industry Challenges
- Heat-treatment technician scarcity:Precision hardening to 54-62 HRC specifications requires experienced metallurgists increasingly concentrated at aging European and Japanese facilities.
- Dual certification timelines:Simultaneous VDE and UL listing for insulated cutters extends product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tool Wire Cutters Market |
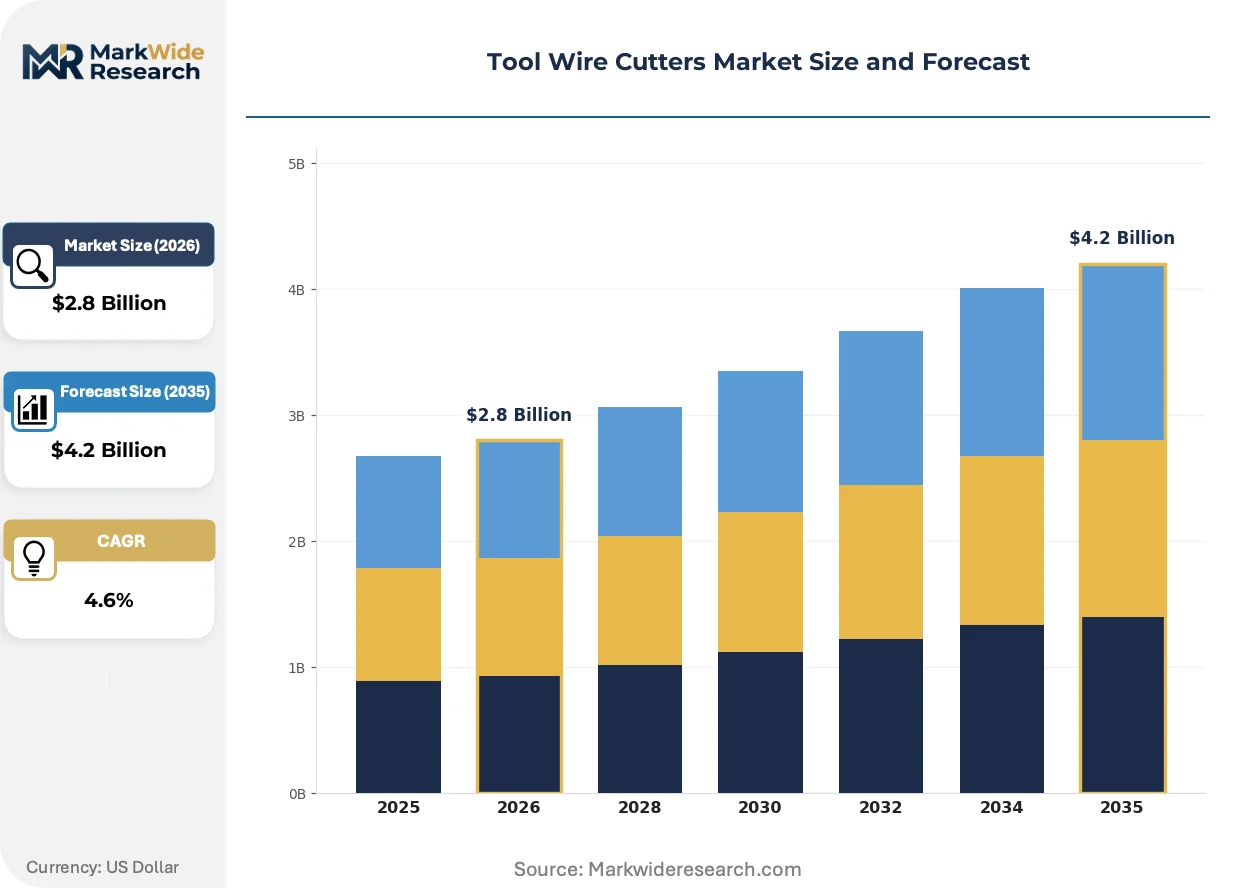
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flush Cutters, Diagonal Cutters, Needle Nose Cutters, End Cutters Material: Carbon Steel, Stainless Steel, Alloy Steel, High-Speed Steel Application: Electrical, Automotive, Aerospace, Construction Size: Mini, Standard, Heavy Duty, Professional |
| Companies Covered | Stanley Black & Decker, Apex Tool Group, Klein Tools, Snap-On Incorporated, Techtronic Industries, Robert Bosch, Makita Corporation, Hilti Corporation, Irwin Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tool Wire Cutters Market Evolving Landscape
Powder metallurgy and induction-hardening advances are compressing the performance gap between premium and mid-tier cutter lines, while regulatory chemistry restrictions force material science innovation in edge retention and corrosion protection.
Carbide-insert cutting edges are collapsing the traditional trade-off between hardness and toughness in precision flush cutters. Medical device assemblers and satellite electronics manufacturers now specify carbide-tipped units for Inconel and Kovar lead trimming where conventional HSS edges deform within weeks. The technology is collapsing replacement frequency and inventory carrying costs for high-mix, low-volume production environments.
REACH Annex XVII restrictions on cadmium and hexavalent chromium are forcing electroplating process migrations across European cutter suppliers. Surface treatment houses in Solingen and Sheffield report 18-month qualification periods for trivalent chromium and zinc-nickel alternatives that match legacy corrosion resistance. German industrial buyers now require full material disclosure documentation extending to subcontractor plating operations.
Certification-driven specification is consolidating procurement authority among tier-one electrical contractors and aerospace OEMs. Smaller installation firms previously sourcing through generic industrial distributors now face mandatory VDE or MIL-SPEC documentation from prime contractors. North American utility maintenance divisions have shifted volume toward pre-qualified supplier lists with audited forging and testing traceability.
Tool Wire Cutters Market Segmentation
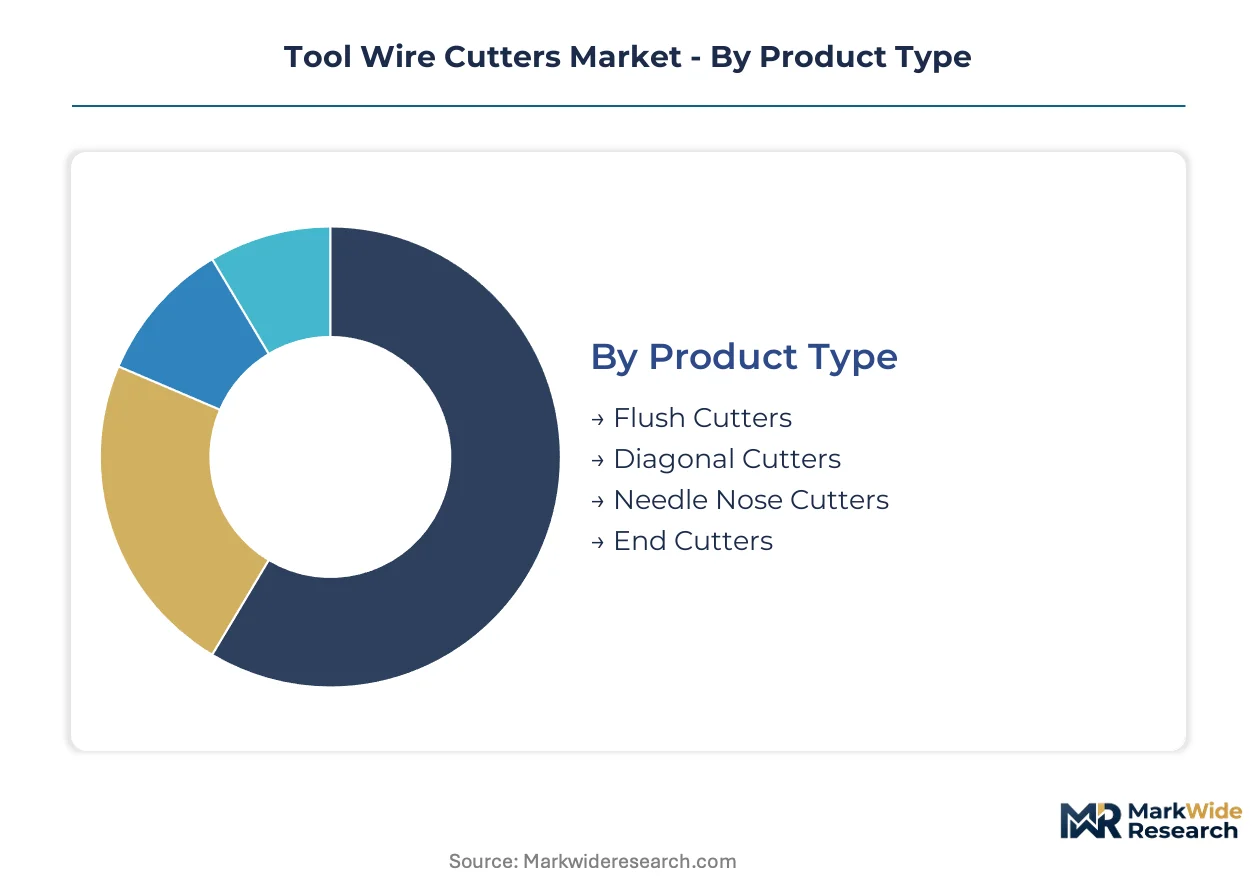
Tool wire cutter procurement patterns diverge sharply across technical specifications, with aerospace and medical buyers demanding carbide-tipped precision units while construction crews cycle through standard diagonal cutters on quarterly replacement schedules. Segmentation clarity enables suppliers to align forging capacity, inventory buffers, and certification investments with actual demand velocity.
Product Type:
Replacement cycles stretch from weeks in high-volume electronics assembly to years in aviation maintenance hangars, creating divergent inventory and service strategies across cutter formats.
- Flush Cutters:Precision-ground cutting edges with minimal lead protrusion suit component-lead trimming in PCB assembly and medical device manufacturing. Satellite electronics manufacturers in Germany and the United States now specify carbide-insert variants for Inconel and Kovar wire processing.
- Diagonal Cutters:Angled jaw geometry delivers mechanical advantage for copper and aluminum cable severing in electrical installation trades. OSHA-insulated models dominate procurement lists among United States utility contractors performing live-circuit maintenance.
- Needle Nose Cutters:Extended reach with integrated cutting jaws serves confined-space harness work in automotive and appliance assembly.
- End Cutters:Front-cutting action permits flush trimming against surfaces in finish carpentry and metal fabrication.
Diagonal cutters anchor the volume base while flush cutters gain share at the steepest rate.
Material:
Raw material selection determines forging complexity, heat-treatment protocols, and ultimate price positioning across professional and consumer tiers.
- Alloy Steel:Molybdenum and vanadium additions achieve 58-62 HRC hardness ratings for nickel-alloy wire processing without edge chipping. Aerospace harness assembly lines in France and the United States specify these formulations for stainless and Inconel cable.
- High-Speed Steel:Tungsten and cobalt content sustains cutting performance at elevated temperatures in high-duty-cycle industrial environments. Automotive wiring harness plants in Germany and Japan favor HSS cutters for abrasive multi-strand cable processing.
- Carbon Steel:Baseline hardness and lower cost serve occasional-use consumer and light industrial applications.
- Stainless Steel:Corrosion resistance suits food processing, marine, and chemical plant maintenance with frequent washdown requirements.
Carbon steel dominates unit shipments while alloy steel commands the steepest expansion trajectory in value terms.
Application:
End-use requirements dictate insulation ratings, hardness specifications, and documentation depth from initial forging through final delivery.
- Electrical:VDE and UL insulation certifications are mandatory for live-circuit work among contractors and utility maintenance divisions. United States electrical contractors now pre-qualify suppliers with audited testing traceability.
- Aerospace:MIL-SPEC documentation and 58+ HRC hardness ratings are required for nickel-alloy harness wire processing. Aviation OEMs in the United States and France mandate carbide-tipped units for satellite and medical electronics.
- Automotive:High-volume wiring harness production demands cutters with rapid replacement availability and consistent edge geometry.
- Construction:General-purpose diagonal cutters with basic insulation ratings serve rough-in electrical and structural steel work.
Electrical applications generate the highest unit volumes while aerospace commands premium pricing and documentation requirements.
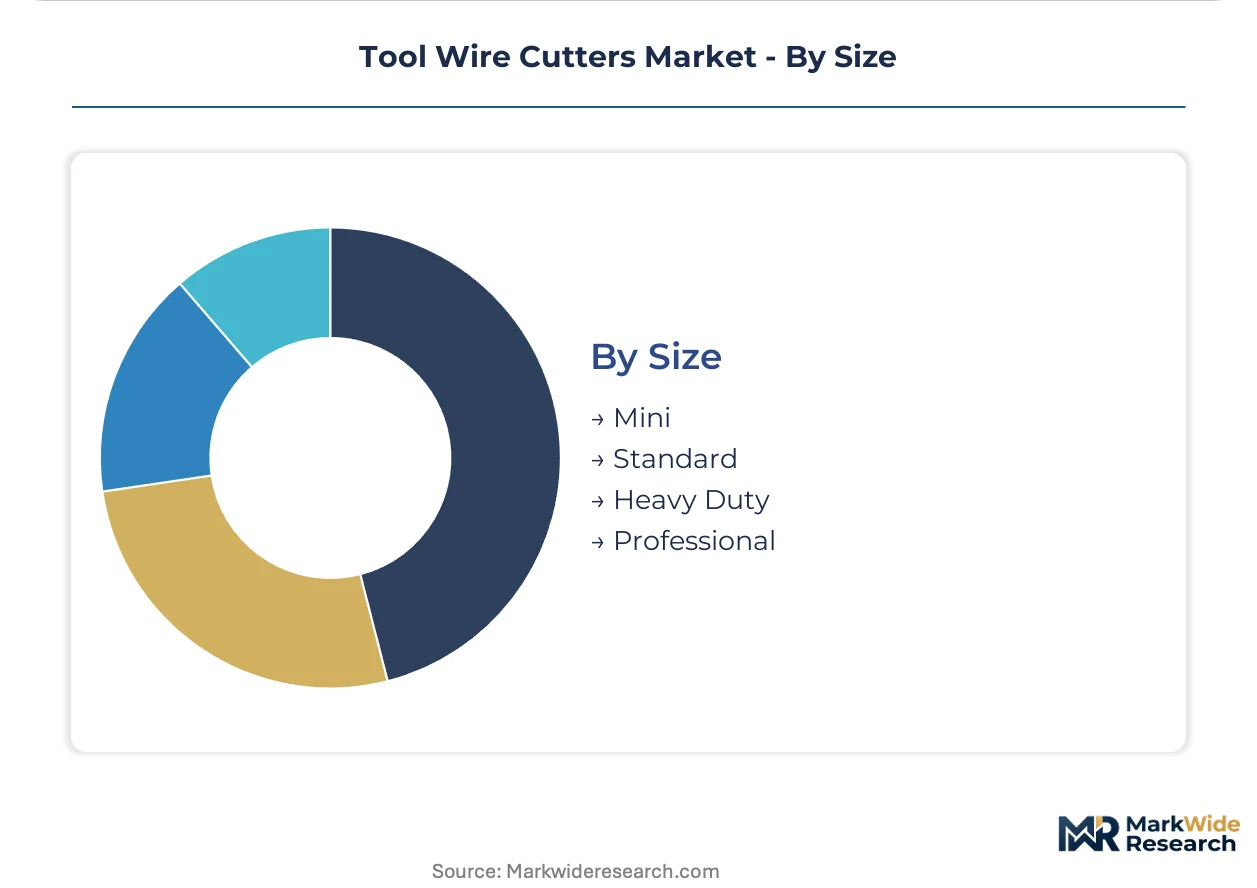
Size:
Physical dimensions correlate directly with leverage, portability, and the gauge range of wire that can be processed effectively.
- Professional:Optimized ergonomics and replaceable jaw inserts suit daily-use tradespeople with high-duty-cycle requirements. German and Japanese tool brands dominate this tier through forged-alloy construction and induction-hardening precision.
- Heavy Duty:Extended jaw length and compound leverage mechanisms address large-gauge cable and structural wire rope.
- Standard:General-purpose dimensions serve mixed-application maintenance and repair operations.
- Mini:Compact form factors enable access in dense electronics enclosures and precision instrument assembly.
Professional-grade units capture the highest margin pool while mini cutters expand most quickly in electronics manufacturing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA mandates for insulated hand tools anchor procurement patterns in the United States, while China's SAMR enforces GB standards that determine market access for domestic and imported cutter brands. Regulatory frameworks across Germany, Japan, and India are tightening certification requirements simultaneously.
United States
Electrical contractors and utility maintenance divisions drive specification of VDE-certified cutters for live-circuit work. OSHA 1910.335 mandates insulated-tool ratings for energized electrical systems. Manufacturing clusters in Illinois and Wisconsin supply forged-alloy cutters to North American industrial distribution channels.
Germany
REACH Annex XVII restrictions on cadmium and hexavalent chromium force plating process migrations across cutter suppliers. ECHA compliance documentation now extends to subcontractor surface treatment operations. Solingen's forging houses report 18-month qualification periods for trivalent chromium alternatives that match legacy corrosion resistance.
China
Shenzhen and Dongguan manufacturing clusters supply both domestic tool brands and export OEM contracts for professional-grade hand tools. SAMR enforces hardness and torque testing protocols through GB standards that determine market access. Dual carbon goals are pressuring alloy reformulation across Pearl River Delta forging facilities.
Japan
Automotive wiring harness plants in Aichi and Shizuoka prefectures favor high-speed steel cutters for abrasive multi-strand cable processing. METI oversees JIS standards that govern tool performance specifications. Aging heat-treatment facilities in Osaka and Nagoya face technician scarcity for precision hardening to 54-62 HRC.
India
State electricity boards are formalizing procurement channels through BIS adoption of IS 60900 standards for insulated hand tools. CEA regulations govern electrical safety equipment specifications for utility maintenance. Manufacturing activity concentrates in Maharashtra and Gujarat for domestic tool assembly and regional distribution.
Tool Wire Cutters Market Competitive Landscape
Multi-brand industrial conglomerates and specialized hand-tool manufacturers split the market into distinct competitive spheres. The vendor base organizes around three strategic archetypes: diversified power-tool platforms with cutter bundling capabilities, dedicated hand-tool specialists with deep trade-channel relationships, and regional forging houses serving OEM private-label contracts. Consolidation pressures are intensifying through battery-tool ecosystem expansion and pre-qualified supplier list consolidation among tier-one electrical contractors.
Within the diversified platform tier, Stanley Black & Decker and Robert Bosch exemplify archetypes that leverage multi-brand portfolios and integrated cordless ecosystems respectively. Klein Tools occupies a position representing specialized hand-tool manufacturers with focused trade-channel penetration. These three anchors illustrate how competitive positioning diverges between scale-driven bundling strategies and precision-specialist differentiation in professional-grade cutter procurement.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Apex Tool Group |
| Klein Tools |
| Snap-On Incorporated |
| Techtronic Industries |
| Robert Bosch |
| Makita Corporation |
| Hilti Corporation |
| Irwin Tools |
| Others |
Value Network & Pricing Analysis
The Shenzhen-Dongguan freight corridor's container rates directly compress margin pools for forged-alloy cutter exports while amplifying price spreads between premium VDE-certified units and economy-grade alternatives. Logistics cost volatility feeds into procurement decisions by United States electrical contractors and European aerospace OEMs, forcing tiered sourcing strategies that segment supply chains by certification grade and hardness specification.
Pricing Analysis
Geographic price spreads between German Solingen-forged cutters and Chinese OEM equivalents now exceed three-to-one for professional-grade diagonal cutters with identical HRC ratings. Pricing stratifies across premium, standard, and economy tiers where VDE insulation certification and carbide-insert edges command substantial premiums over baseline carbon steel units. Pricing pressure stems from molybdenum and vanadium input volatility complicating margin planning for alloy steel formulations. Electrical contractors in the United States exhibit the highest price sensitivity due to quarterly replacement cycles, while aerospace harness assemblers prioritize performance consistency over unit cost.
Supply Chain Analysis
Export-control regimes on tungsten carbide powder and cobalt concentrates constrain cutter manufacturers sourcing from restricted jurisdictions. Forged-alloy production concentrates in China, Germany, and Japan where heat-treatment expertise and precision grinding capacity anchor supply. Raw material flows draw from molybdenum mines in Chile, vanadium processing in South Africa, and high-grade chromium from Kazakhstan. Single-source vulnerability persists for hexavalent chromium alternatives in corrosion-resistant plating. Distribution runs through industrial distributors in North America, specialized trade channels in Europe, and direct OEM relationships in Asia-Pacific manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser wire stripping technology threatens mechanical cutter volumes in high-volume electronics assembly, forcing incumbents to defend substitution risk through precision differentiation and certification moats.
For Market Incumbents: Insulate market position by deepening captive forging capacity in Shenzhen-Dongguan clusters to control alloy reformulation costs under dual carbon mandates. Accelerate VDE and UL dual certification pipelines to extend product development timelines that deter mid-tier competitors from entering live-circuit procurement lists. For New Entrants and Emerging Players: India's state electricity boards present the most penetrable white-space target as BIS formalizes IS 60900 procurement channels for insulated hand tools. Target Maharashtra and Gujarat assembly operations with carbide-tipped precision units for medical device subcontracting clusters. Enter through audited supplier pre-qualification programs that tier-one electrical contractors now mandate. For Investors and Strategic Acquirers: Regional forging houses with established heat-treatment technician benches and existing VDE certification relationships represent the highest-conviction acquisition archetype. Monitor laser wire stripping adoption curves in German automotive harness plants as the critical inflection signal for mechanical cutter demand elasticity. Long-term viability hinges on carbon-accounting disclosure capabilities that satisfy EU CSRD scope 3 reporting requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Forging | Captive molybdenum-vanadium processing insulates margins from commodity volatility in Chinese supply chains. |
| Dual Certification Investment | Simultaneous VDE and UL listings unlock live-circuit procurement channels among United States utility contractors. |
| Carbide-Insert Technology Licensing | Medical device and satellite electronics manufacturers now specify tipped units for Inconel and Kovar processing. |
| Carbon Accounting Disclosure Program | Verified low-emission heat-treatment processes satisfy EU CSRD scope 3 reporting for European industrial buyers. |
| India Distribution Partnership | BIS-compliant insulated cutter placement captures state electricity board procurement formalization through CEA regulations. |
Research Methodology
Cross-validation between trade association filings and customs export data anchors the qualitative findings in observable shipment patterns. Primary interviews with forging plant managers, electrical contractor procurement leads, aerospace harness engineers, and industrial distributor category buyers combined with secondary validation from OSHA enforcement records, REACH Annex XVII substance restriction updates, SAMR GB standard bulletins, and SEC 10-K disclosures from listed tool manufacturers. Bottom-up segment sizing and top-down macroeconomic calibration ensure convergence across estimation approaches.
Calibration against historical alloy steel price elasticity and certification adoption curves informs the analytical framework across the projection horizon. Segmentation dimensions include cutter type, material formulation, application vertical, and regional regulatory cluster. CAGRs derive from fitted growth curves incorporating aerospace build rates, automotive wiring harness production indices, and electrical construction spending patterns. Industry-specific inputs encompass heat-treatment capacity utilization rates and dual certification timeline distributions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed forging conglomerates or rapid laser stripping adoption by German automotive OEMs would shift outcomes. Material shifts in REACH substance restriction timelines or OSHA insulated-tool mandate enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Micro Welders Market
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
Dies, Jigs and Other Tools Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Coordinate Measuring Machine Market
Industrial Tools
Tool Holder Collets Market
Industrial Tools
Digital Tool Presetter Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
Precision Components and Tooling Systems Market
Industrial Tools
Global Tool Presetters Market
Industrial Tools
Die Grinders Market
Industrial Tools
Centerless Grinding Market
Industrial Tools
Tool Holder Market
Industrial Tools
Handheld DC Torque Tools Market
Industrial Tools
Electric Tools Market