
 Robotic Flat Cable Market | 2026-2036
Robotic Flat Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Flat Cable Market Analytics
Market Context
CE marking under the EU Machinery Directive is rebalancing the cost-of-entry calculus for cable suppliers seeking European robot OEM contracts. TE Connectivity leverages its vertical integration into connector-cable assemblies to sustain pricing power across German automotive lines. Igus GmbH specializes in polymer-compound expertise that differentiates its drag chain cable portfolio. Sumitomo Electric Industries anchors its position through captive copper refining and Asian distribution density.
Technical Profile and Segment Structure
Robotic flat cable consists of parallel-conductor ribbon configurations engineered for repetitive flexing, typically incorporating stranded copper conductors with polyurethane or TPE jacketing rated for millions of bending cycles. These cables transmit power and control signals to articulated joints where round cable geometries would fail from torsional stress. High-flex cable commands the largest revenue pool due to universal deployment across six-axis industrial robots, while drag chain cable captures expanding share from automated guided vehicles operating in warehouse logistics. Polyurethane jackets lead material selection for oil-resistant factory floors, though TPE compounds gain traction where halogen-free fire safety specifications apply.
Regulatory Environment and Outlook
FDA device manufacturing regulations, EU Machinery Directive compliance frameworks, and China's GB standard certification collectively shape product qualification timelines and testing expenditures for robotic cable suppliers. ISO 10218 and IEC 60204-1 define insulation integrity and electromagnetic compatibility thresholds that determine market access for new entrants. Stakeholders must monitor evolving national robot safety codes and material substance restrictions to anticipate redesign obligations ahead of contract renewal cycles.
Market Dynamics
ISO 10218 safety mandates and EU Machinery Directive compliance timelines are compressing product development cycles for cable suppliers, forcing simultaneous redesigns of insulation compounds and flex-cycle architectures to maintain OEM qualification status.
Growth Catalysts
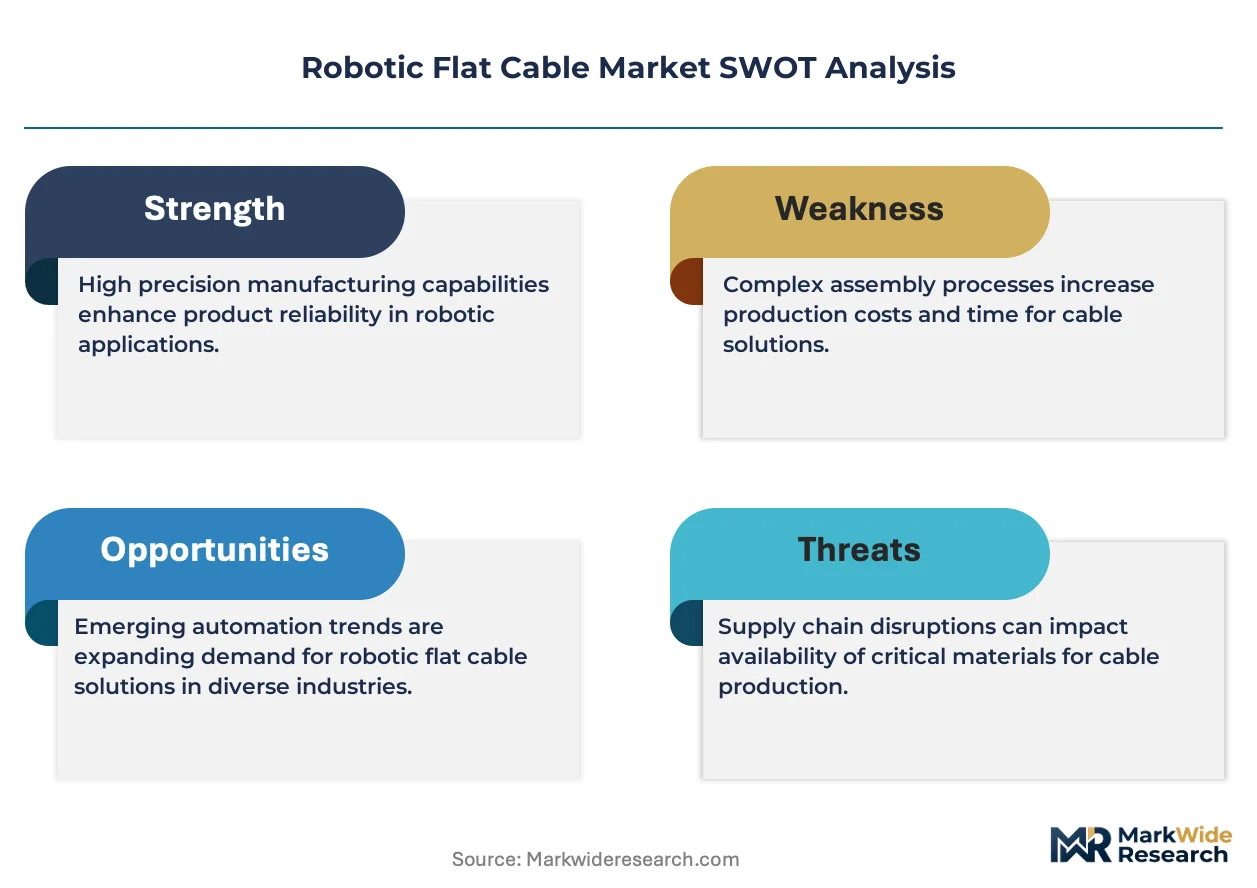
- EU Machinery Directive CE marking:Mandatory conformity assessment for robot motion systems is expanding addressable demand for certified high-flex cable assemblies among European automotive OEMs.
- Guangdong electronics manufacturing clusters:Dense robot fleet deployment across contract manufacturers is generating concentrated procurement volume for drag chain cable configurations.
- Polyurethane jacketing advances:Improved oil resistance and million-cycle flex ratings are enabling replacement of round cable geometries in articulated joint applications.
Market Restraints
- Copper price volatility:Stranded conductor raw material costs fluctuate with LME pricing, squeezing margin structures for non-vertically integrated cable assemblers.
- German supply concentration:Premium connector-cable assembly capability clusters around Stuttgart and Munich, creating single-source risk for tier-two robot builders.
- TPE compound technical ceiling:Halogen-free fire safety formulations currently achieve lower flex-cycle ratings than polyurethane alternatives, limiting deployment in high-duty six-axis joints.
Strategic Opportunities
- Automated guided vehicle logistics:Warehouse robotics in Jiangsu province is creating incremental demand for lightweight flat cable with integrated power-signal hybrid conductors.
- Japan METI carbon neutrality roadmap:Factory automation efficiency mandates are accelerating robot density targets, expanding cable replacement cycles in existing installed base.
- Digital twin integration:Convergence of cable health monitoring sensors with predictive maintenance platforms is opening premium-priced smart cable segments.
Industry Challenges
- Polymer compounding talent scarcity:Specialized formulation chemists capable of balancing flex-cycle performance with REACH substance restrictions command premium compensation, constraining R&D throughput.
- ISO 10218-1 certification timelines:Extended third-party testing for insulation integrity under repetitive bending stress delays new product launches by 8-14 months.
- Legacy round cable infrastructure:Existing robot designs with sealed cable glands require costly mechanical redesign to accommodate flat cable geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Flat Cable Market |
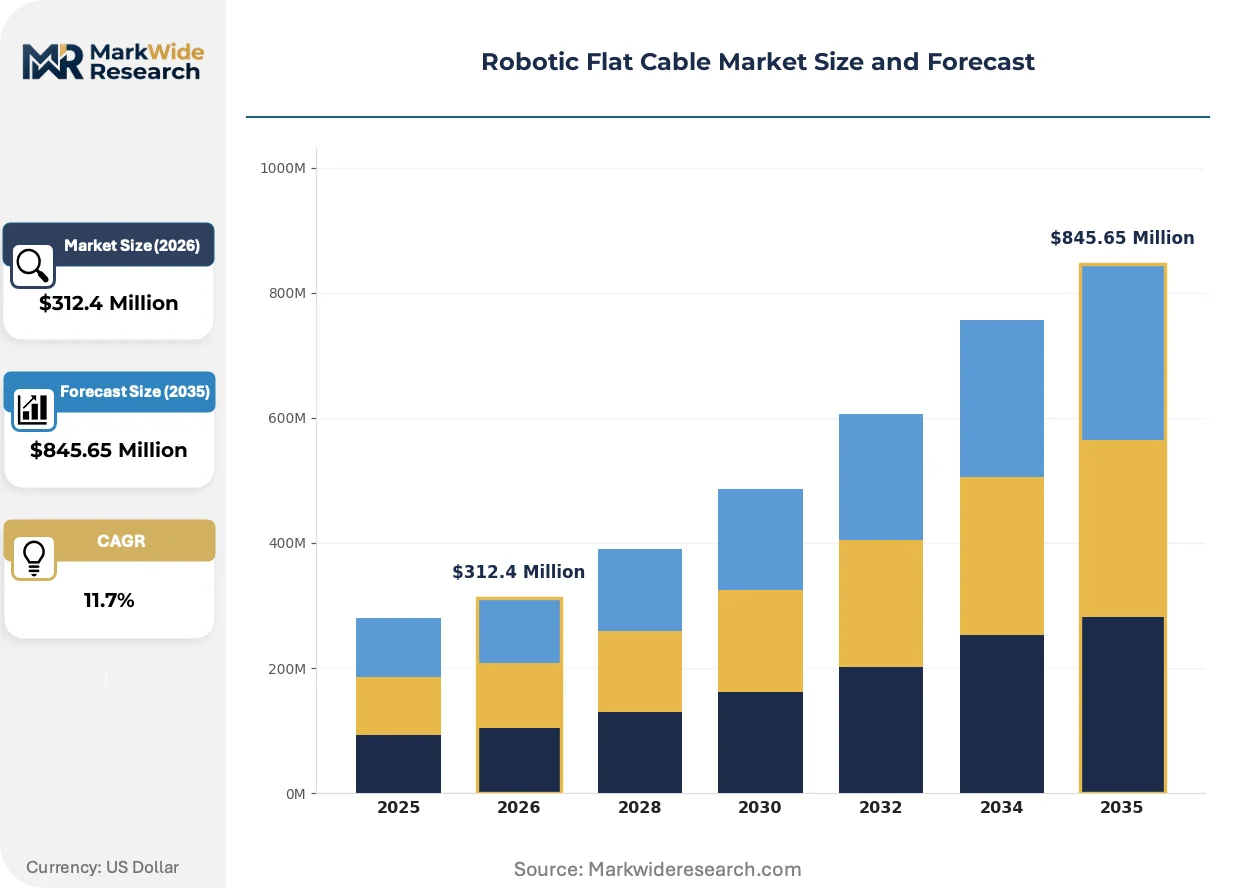
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cable, High-Flex Cable, Drag Chain Cable, Low-Friction Cable Application: Industrial Robots, Automated Guided Vehicles, 3D Printers, CNC Machines Material: Polyurethane, PVC, TPE, Nylon End User: Manufacturing, Automotive, Electronics, Healthcare |
| Companies Covered | HELUKABEL, Axon Cable, Sumitomo Electric Industries, LAPP Group, Luxshare-ICT, Igus GmbH, TE Connectivity, Molex, LEONI AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Flat Cable Market Evolving Landscape
Material science breakthroughs in thermoplastic elastomer compounding and embedded sensor integration are redefining performance benchmarks for motion system cabling, while regulatory pressure on halogen-free fire safety is redirecting R&D investment priorities.
Halogen-free TPE jacketing compounds are overtaking traditional polyurethane in European medical and food-handling robot installations. German automotive OEMs specify these materials for cleanroom-compatible production lines. The shift is compressing market share for oil-resistant but halogen-containing alternatives in safety-critical verticals.
EU REACH substance restrictions on persistent organic pollutants are tightening permissible additive chemistries in cable insulation. Compounders must reformulate flame retardant packages without legacy brominated compounds. High-flex cable suppliers serving pharmaceutical robot builders face the steepest compliance redesign obligations.
Robot OEMs now bundle cable health monitoring into extended service contracts rather than treating replacement as a discrete parts sale. Japanese automotive lines lead this transition, with predictive maintenance algorithms triggering preemptive cable swaps before flex-cycle failure. The model concentrates procurement authority with OEM service divisions rather than end-user maintenance departments.
Robotic Flat Cable Market Segmentation
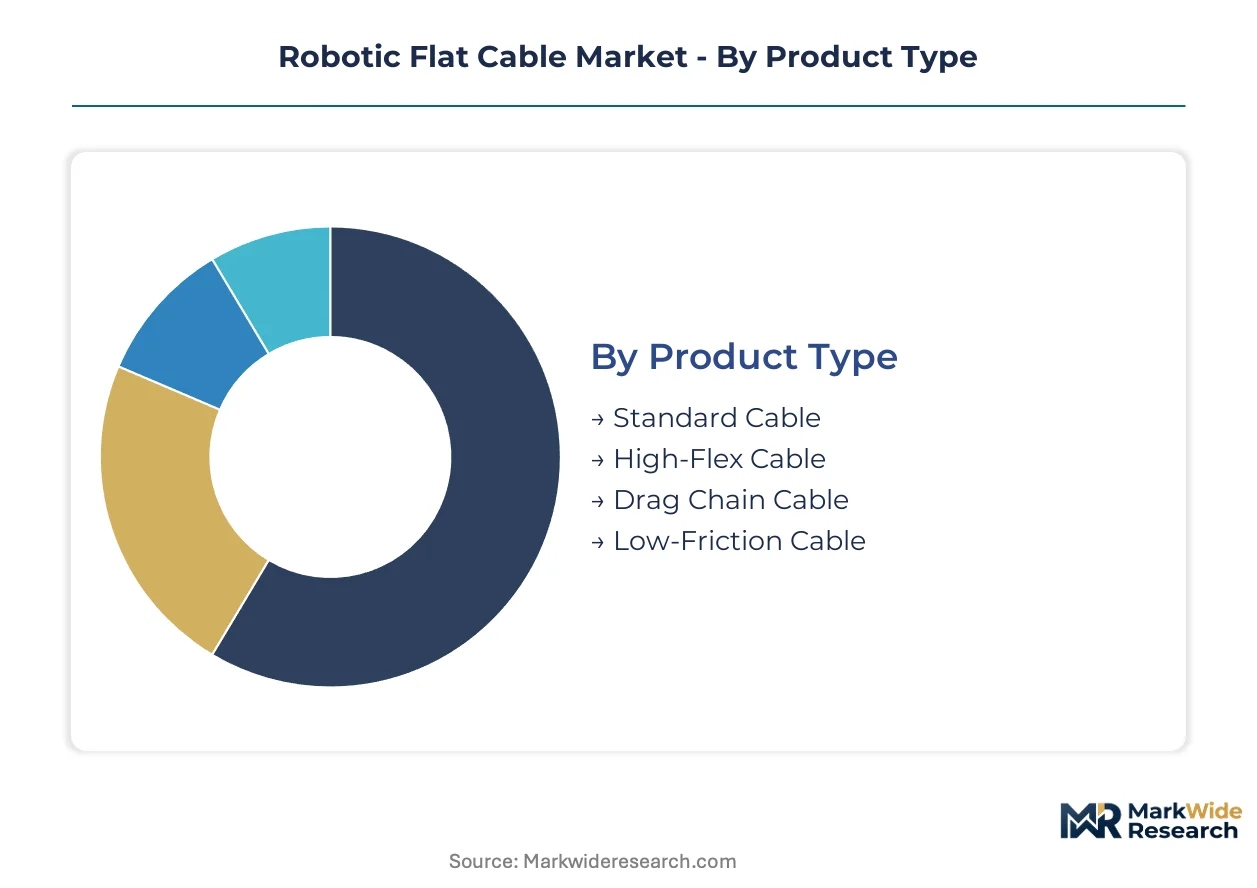
Segmentation in robotic flat cable markets reflects divergent technical requirements across motion system architectures. Product specifications, material chemistries, and end-use duty cycles create distinct procurement channels with limited substitutability between tiers.
Product Type:
Flex-cycle ratings and mechanical durability specifications define the technology axis for cable selection across robot motion systems.
- High-Flex Cable:Stranded copper conductors with engineered lay lengths and polyurethane jacketing withstand millions of bending cycles in six-axis industrial robot joints. German automotive lines specify these for welding and painting cells where round cables fail from torsional fatigue.
- Drag Chain Cable:Parallel-conductor ribbon configurations integrate tensile strength members for linear motion in automated guided vehicle fleet operations. Warehouse robotics in China's Jiangsu province is driving procurement volume for lightweight hybrid power-signal variants.
- Standard Cable:Basic polyurethane-jacketed flat configurations serve static or low-cycle installations in pick-and-place Cartesian robots.
- Low-Friction Cable:PTFE-impregnated jacketing compounds reduce drag in long-travel gantry systems where cable carriers operate at high velocities.
Mature deployment sits with High-Flex Cable in established automotive body shops. Newer deployment is concentrated in Drag Chain Cable for warehouse logistics expansion.
Application:
Motion system kinematics and environmental exposure dictate cable geometry and material selection across robot platforms.
- Industrial Robots:Six-axis articulated arms demand high-flex cable with million-cycle ratings for power and encoder signal transmission through rotating wrist joints. EU Machinery Directive CE marking mandates insulation integrity testing for these safety-critical motion systems.
- Automated Guided Vehicles:Linear travel in warehouse corridors favors flat cable with integrated hybrid conductors for battery power and CAN bus communication. Japan METI carbon neutrality targets are accelerating fleet density in existing manufacturing plants.
- 3D Printers:Gantry-based motion systems require low-friction jacketing for drag chain installations with rapid acceleration profiles.
- CNC Machines:Spindle power and axis control cables operate in oil-mist environments where polyurethane chemical resistance proves essential.
Volume concentration centers on Industrial Robots in German and Japanese OEM supply chains. Steepest expansion trajectory belongs to Automated Guided Vehicles in Chinese electronics contract manufacturing clusters.
Material:
Jacketing compound chemistry balances flex-cycle performance against regulatory substance restrictions and environmental exposure.
- Polyurethane:Oil-resistant thermoset formulations dominate factory floor installations where hydraulic fluid and metalworking coolant exposure is routine. REACH substance restrictions on isocyanate catalysts are forcing reformulation cycles among European compounders.
- TPE:Halogen-free thermoplastic elastomer compounds gain share in medical and food-handling robot installations where cleanroom compatibility and fire safety specifications converge. Flex-cycle ratings currently trail polyurethane alternatives.
- PVC:Cost-optimized jacketing serves price-sensitive applications with limited flex-cycle requirements and benign chemical environments.
- Nylon:Abrasion-resistant extrusions function as outer sheaths in high-wear drag chain applications where mechanical protection outweighs flex performance.
Polyurethane retains the largest installed base in heavy-duty industrial settings. TPE compounds are climbing fastest in regulated safety-critical verticals.
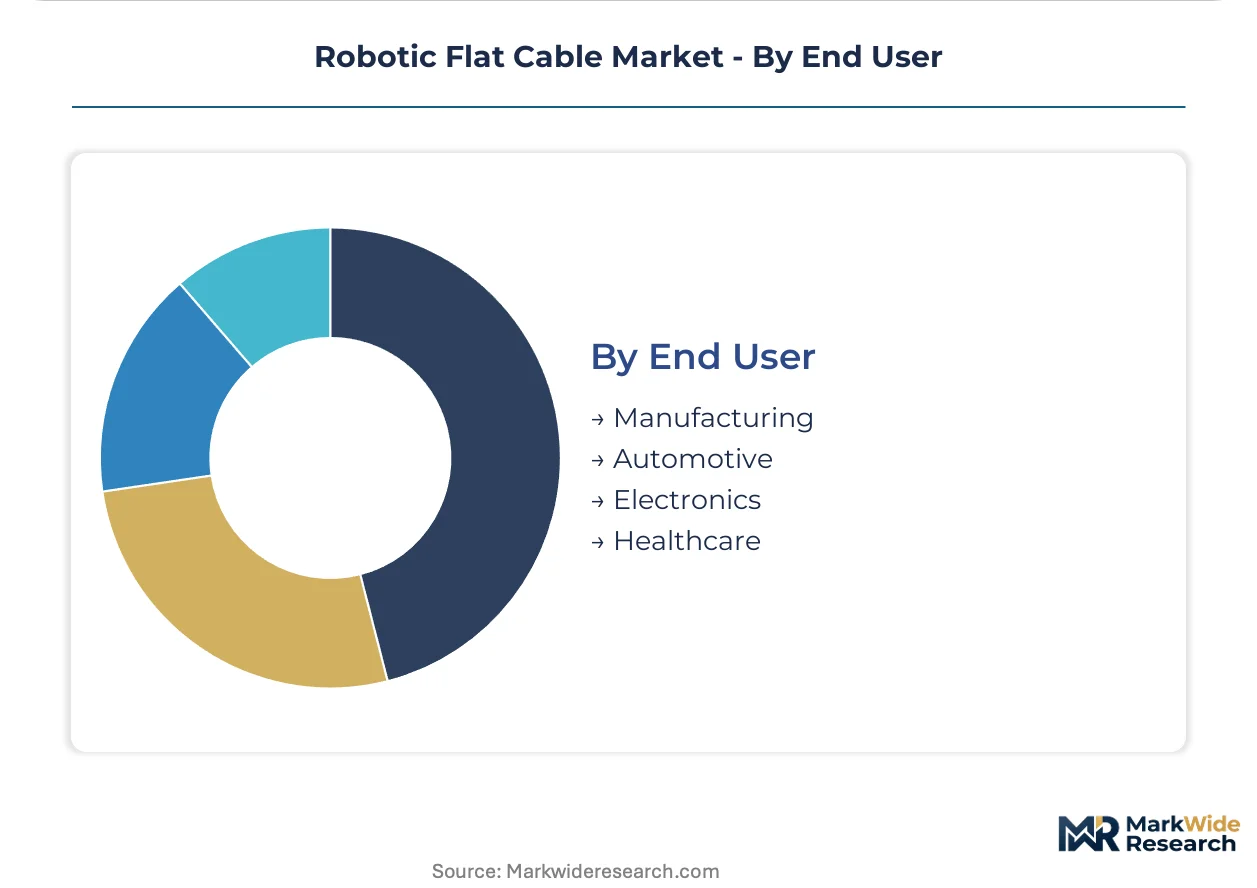
End User:
Procurement authority and specification authority diverge across end-use sectors with distinct qualification timelines and contract structures.
- Automotive:German OEMs specify certified cable assemblies through tier-one integrators with extended service contract provisions. Robot OEM service divisions now control replacement procurement through predictive maintenance platforms.
- Electronics:Contract manufacturers in Guangdong province operate dense robot fleets with concentrated cable consumption for surface-mount assembly and test handling operations.
- Manufacturing:General industrial automation spans diverse applications from packaging to metal fabrication with varying technical specifications and price sensitivity.
- Healthcare:Pharmaceutical and medical device manufacturing imposes FDA and EMA compliance requirements on cable materials with stringent substance documentation.
Automotive channels concentrate premium pricing power with OEM service divisions. Electronics manufacturing in China represents the highest volume procurement segment with compressed margin structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the densest concentration of robotic flat cable procurement, with electronics contract manufacturers in Guangdong and Jiangsu provinces operating robot fleets that dwarf other national markets. Germany and Japan anchor premium-tier demand through automotive OEM supply chains. The United States and South Korea round out the five-country demand matrix with distinct regulatory and industrial drivers.
China
Surface-mount assembly lines and semiconductor test handling operations in Shenzhen and Suzhou generate concentrated volume for drag chain cable configurations. GB standard certification and MIIT industrial automation directives shape product qualification requirements for domestic and export-bound suppliers. Guangdong province's Dongguan and Shenzhen clusters host the world's densest deployments of six-axis robots in electronics contract manufacturing.
Germany
Automotive body shops and powertrain assembly lines specify CE-marked high-flex cable assemblies with million-cycle ratings for welding and painting cells. EU Machinery Directive conformity assessment mandates insulation integrity testing that extends product development timelines. Stuttgart and Munich metropolitan areas concentrate tier-one robot integrator procurement authority for European OEM supply chains.
Japan
METI carbon neutrality roadmaps accelerate factory automation density targets, expanding replacement cycles in existing automotive and electronics installed bases. JIS standards and ISO 10218-1 certification requirements govern safety-critical motion system cabling. Nagoya's Chubu region and Osaka's Kansai manufacturing belt anchor domestic robot OEM supply chains with integrated cable-connector assembly specifications.
United States
FDA-regulated pharmaceutical manufacturing and food-handling automation drive demand for halogen-free TPE jacketing in cleanroom-compatible production environments. OSHA workplace safety standards and FCC electromagnetic compatibility requirements apply to robot motion system installations. Michigan's automotive corridor and California's medical device clusters represent distinct procurement channels with divergent technical specifications.
South Korea
Display panel manufacturing and battery cell assembly operations in Gyeonggi-do and Chungcheong provinces deploy high-flex cable in precision material handling robots. MFDS medical device regulations and KOSHA industrial safety standards influence material selection for pharmaceutical and electronics manufacturing applications. The Seoul Capital Area concentrates both robot OEM headquarters and tier-one component procurement decision-making.
Robotic Flat Cable Market Competitive Landscape
German producers anchor one tier; Japanese specialists hold another through captive copper refining and Asian distribution density. The vendor base structures around three to four dominant positions with long-term OEM qualification status, while mid-scale compounders and regional assemblers fill specification gaps. Two strategic archetypes predominate: vertically integrated connector-cable assembly houses and polymer-compound specialists with drag chain expertise. Competitive moves concentrate on backward integration into copper refining and strategic partnerships for predictive maintenance platform integration.
Within the integrated assembly tier, TE Connectivity and LEONI AG occupy positions that exemplify premium-tier pricing power through in-house production of connector-cable combinations. Igus GmbH represents the compound-specialist archetype, with its Cologne-based operations sitting within the polymer formulation expertise cluster that differentiates drag chain portfolios. Sumitomo Electric Industries anchors the Asian supply vector through its Osaka origins and captive control over conductor raw materials.
| Leading Market Players |
|---|
| HELUKABEL |
| Axon Cable |
| Sumitomo Electric Industries |
| LAPP Group |
| Luxshare-ICT |
| Igus GmbH |
| TE Connectivity |
| Molex |
| LEONI AG |
| Others |
Value Network & Pricing Analysis
Polymer compounding chemists in Germany's Cologne-Düsseldorf corridor command premium compensation packages that widen pricing spreads between CE-certified premium assemblies and standard-grade alternatives sourced from Asian contract manufacturers.
Pricing Analysis
Volume concentrates in drag chain cable for warehouse robotics while margins pool with high-flex assemblies for six-axis industrial robots. Pricing stratifies across premium CE-marked tiers, mid-grade ISO-certified lines, and economy-level unbranded alternatives. Cost compression in the electronics contract manufacturing segment stems from concentrated procurement authority among Guangdong-based fleet operators. Tier-one automotive OEMs exhibit lowest price sensitivity due to predictive maintenance bundling, while surface-mount assembly houses prioritize unit economics.
Supply Chain Analysis
Refurbishment flows for failed cable assemblies in existing robot installed bases are creating secondary material streams that compete with virgin compound demand. Copper conductor supply centers on Germany, Japan, and China with captive refining operations at Sumitomo Electric and LEONI AG. Jacketing compound formulation draws from specialized polymer labs in Cologne, Osaka, and Shanghai. Single-source vulnerability clusters around Stuttgart-area connector-cable assembly houses. Distribution runs through tier-one robot OEM service divisions rather than independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where backward control over copper refining and polymer compounding determines pricing power across European automotive supply chains.
For Market Incumbents: Extend qualification status with German automotive OEMs by accelerating ISO 10218-1 certification timelines for next-generation TPE compounds. Deepen backward integration into halogen-free flame retardant additive supply to offset REACH substance restriction redesign costs. Counter emerging Asian compounders by locking in exclusive service contracts with predictive maintenance platform providers.
For New Entrants and Emerging Players: Direct-to-manufacturer digital procurement platforms offer the lowest-friction route to bypass entrenched tier-one integrator relationships. Target warehouse logistics operators in Jiangsu province with lightweight hybrid conductor configurations for automated guided vehicle fleets. Lead with rapid GB standard certification turnaround to capture electronics manufacturing replacement cycles.
For Investors and Strategic Acquirers: Re-rating potential sits with polymer-compound specialists given EU REACH-driven reformulation cycles and OEM qualification scarcity. Long-term viability hinges on captive access to copper refining capacity and Asian distribution density. Monitor METI carbon neutrality roadmap implementation velocity as a demand inflection signal for Japanese replacement market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Refining | Captive conductor supply secures margin protection against LME price volatility for cable assemblers. |
| Halogen-Free TPE Compound Development | REACH-compliant formulations unlock European medical and food-handling robot procurement channels. |
| Predictive Maintenance Platform Partnership | OEM service contract bundling concentrates replacement authority away from end-user procurement. |
| GB Standard Certification Acceleration | MIIT compliance timelines determine market access speed for electronics manufacturing clusters. |
| Drag Chain Hybrid Conductor Launch | Integrated power-signal designs capture automated guided vehicle fleet expansion in Jiangsu. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with robot OEM procurement directors, polymer compounding R&D leads, tier-one automotive integrator supply chain managers, and electronics contract manufacturing fleet operators were cross-validated against ECHA REACH substance databases, EU Machinery Directive conformity assessment registries, and MIIT industrial automation directive publications. Bottom-up cable consumption estimates by robot density and application were reconciled with top-down market value triangulation.
Data-stream reconciliation across installation base tracking, replacement cycle modeling, and new robot deployment forecasts informed the projection framework. Segmentation dimensions included flex-cycle rating tier, jacketing compound chemistry, motion system architecture, and end-use sector qualification requirements. CAGRs were derived from compound annual trajectory fitting across the analysis window with sensitivity testing for copper price volatility and regulatory compliance timeline shifts. Factory automation density targets under Japan METI roadmaps and EU carbon neutrality mandates served as demand-side scenario inputs.
The model holds under stable REACH substance restriction timelines and OEM qualification continuity; deviation in ISO 10218-1 certification duration or copper supply disruption would shift replacement cycle assumptions. Practitioners should monitor ECHA additive chemistry restriction proposals and METI roadmap implementation velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Breadboards Market
Electronic Components
North America Miniature Ball Bearing Market
Electronic Components
Digital Isolator Market
Electronic Components
Fuel Pump Driver Module Market
Electronic Components
Frequency Control and Timing Devices Market
Electronic Components
Trackpad Market
Electronic Components
Digital Potentiometer Market
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
Audio Transistors Market
Electronic Components
Passive Attenuator Market
Electronic Components
Global Active Electronic Components Market
Electronic Components
Audio Power Amplifier Market
Electronic Components
Metal Composite Power Inductor Market
Electronic Components
Bonding Wires and Ribbons Market
Electronic Components
Lead Zirconate Titanate (PZT) Market
Electronic Components
Global Capacitor Market