
 Electric Tools Market | 2026-2036
Electric Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Tools Market Analytics
Residential construction is pivoting toward battery-powered equipment as builders prioritize mobility and noise reduction on job sites. Stanley Black & Decker leverages its broad brand portfolio to anchor North American retail channels. Robert Bosch GmbH sustains engineering leadership through advanced motor and battery integration. Makita Corporation dominates professional-grade cordless platforms across Asian and European trade channels.
Electric tools are motor-driven implements engineered to cut, drill, fasten, grind, or shape materials through rotational or reciprocating mechanical force, typically operating at voltages from 12V to 120V depending on power source and application. Cordless drills now represent the largest product category as battery chemistry improvements extend runtime and reduce charging intervals. Industrial users generate the highest-margin demand segment due to fleet replacement cycles and durability requirements. Battery-powered systems are displacing corded alternatives in construction and automotive applications where tethered operation limits workspace flexibility.
OSHA electrical safety standards and EPA energy efficiency guidelines shape product certification requirements and manufacturing compliance costs in the United States. REACH substance restrictions and CE marking obligations govern material composition and market access across European Union member states. China's GB standards and MIIT industrial policy directives influence domestic production specifications and export qualification protocols. Stakeholders must monitor evolving battery transportation regulations and circular economy mandates that will redefine supply chain accountability and end-of-life recovery obligations.
Market Dynamics
Lithium-ion battery energy density improvements are compressing replacement cycles and redefining workspace mobility requirements across construction and automotive verticals.
Growth Catalysts
- OSHA electrical safety frameworks:Updated grounding and insulation standards accelerate cordless platform certification, compelling fleet operators to retire corded inventories ahead of schedule.
- China's infrastructure investment:Manufacturing clusters in Guangdong and Zhejiang concentrate production capacity, shortening lead times for professional-grade battery packs and motor assemblies.
- Brushless motor technology:Permanent magnet designs reduce heat generation and extend operational lifespan, driving preference among industrial maintenance crews.
Market Restraints
- Lithium carbonate price volatility:Battery cell input costs fluctuate with South American and Australian mining output, compressing margin visibility for cordless platform manufacturers.
- REACH substance restrictions:ECHA limitations on cobalt and nickel compounds in battery electrodes force reformulation investments and extend qualification timelines for EU market access.
- Pneumatic tool substitution:Compressed-air systems retain cost advantages in heavy-duty metalworking and shipyard applications where tethered operation remains acceptable.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic battery manufacturing incentives reduce import dependency and create localized supply ecosystems for South Asian distribution.
- EU Green Deal circular economy mandates:Battery passport requirements and end-of-life recovery obligations favor modular designs with standardized cell formats.
- Smart tool connectivity:Integration of torque sensors and Bluetooth diagnostics with fleet management software creates subscription revenue streams for equipment lessors.
Industry Challenges
- Battery transportation certification:UN 38.3 testing protocols and IATA lithium shipping classifications add documentation burden and delay international fulfillment.
- Cross-platform compatibility gaps:Proprietary battery interfaces lock users into single-brand ecosystems, fragmenting aftermarket service networks and spare parts availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Tools Market |
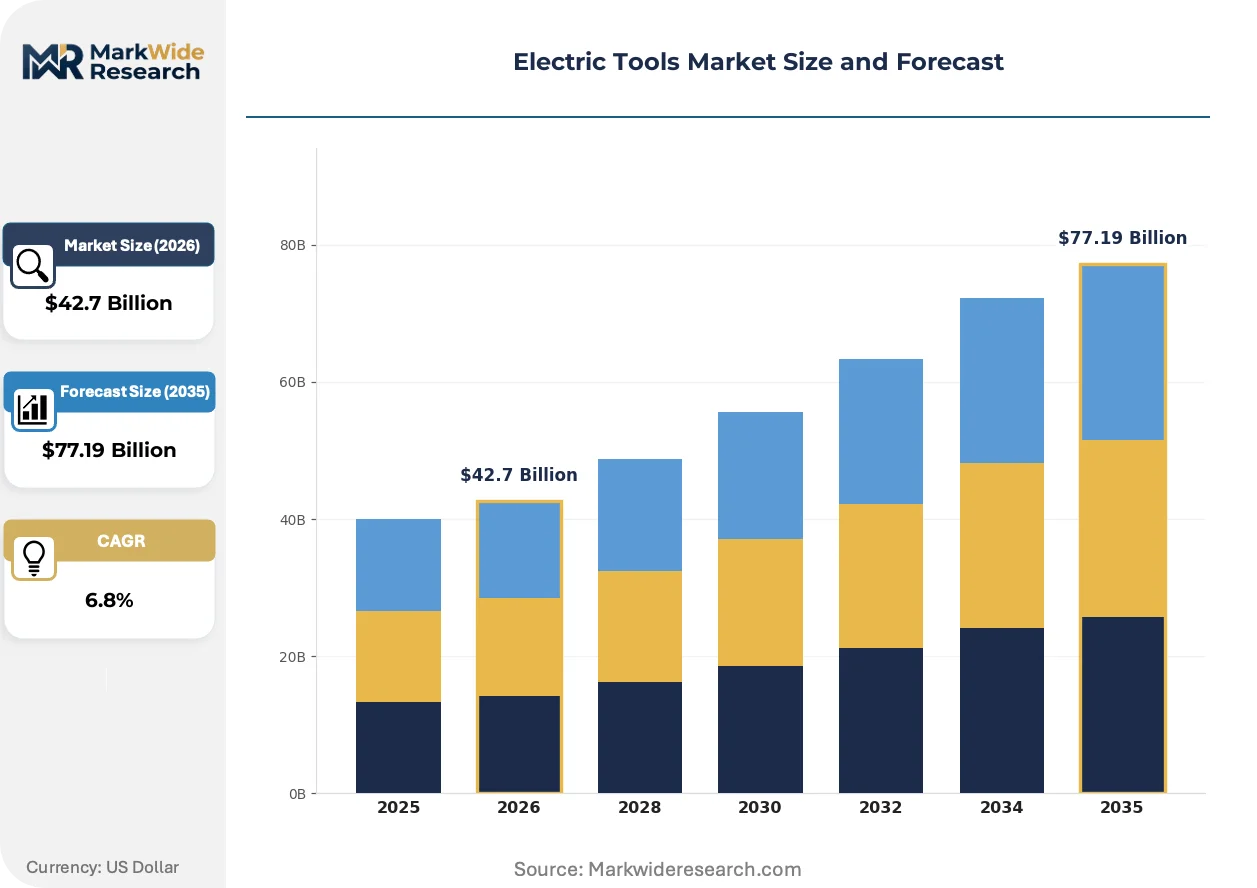
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $77.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cordless Drills, Angle Grinders, Saws, Sanders End User: Contractors, DIY Enthusiasts, Industrial Users, Maintenance Technicians Power Source: Corded, Battery-Powered, Hybrid, Pneumatic Application: Construction, Automotive, Home Improvement, Electrical Work |
| Companies Covered | Stanley Black & Decker, Robert Bosch GmbH, Techtronic Industries Co. Ltd., Makita Corporation, Hilti Corporation, Apex Tool Group, Atlas Copco AB, Ingersoll Rand, Snap-on Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Tools Market Evolving Landscape
Solid-state battery chemistry and intelligent motor control are compressing the performance gap between cordless and corded platforms while enabling predictive maintenance capabilities.
Silicon-anode lithium-ion cells are expanding into high-torque rotary hammer and angle grinder categories previously dominated by AC-powered equipment. Commercial contractors in Germany and Japan are standardizing on 21700-format battery packs that deliver sustained output above 1,000 watts. This platform consolidation is expanding into adjacent outdoor power equipment, blurring category boundaries and extending manufacturer service relationships.
EPA energy efficiency guidelines for battery charging systems now mandate standby power limits and power factor correction in commercial-grade equipment sold in the United States. California's Title 20 appliance standards extend these requirements to consumer channels, forcing adapter redesigns and semiconductor upgrades. Chinese exporters are responding by integrating active power factor correction circuits as standard rather than region-specific configurations.
Equipment-as-a-service contracts are displacing outright purchase models among multi-site construction conglomerates seeking to transfer obsolescence risk. Hilti and similar providers bundle tool replacement, battery refresh, and theft insurance into monthly per-user fees. This model concentrates most visibly in Nordic markets where labor costs amplify downtime penalties and where union frameworks favor predictable operational expenditures over capital allocations.
Electric Tools Market Segmentation
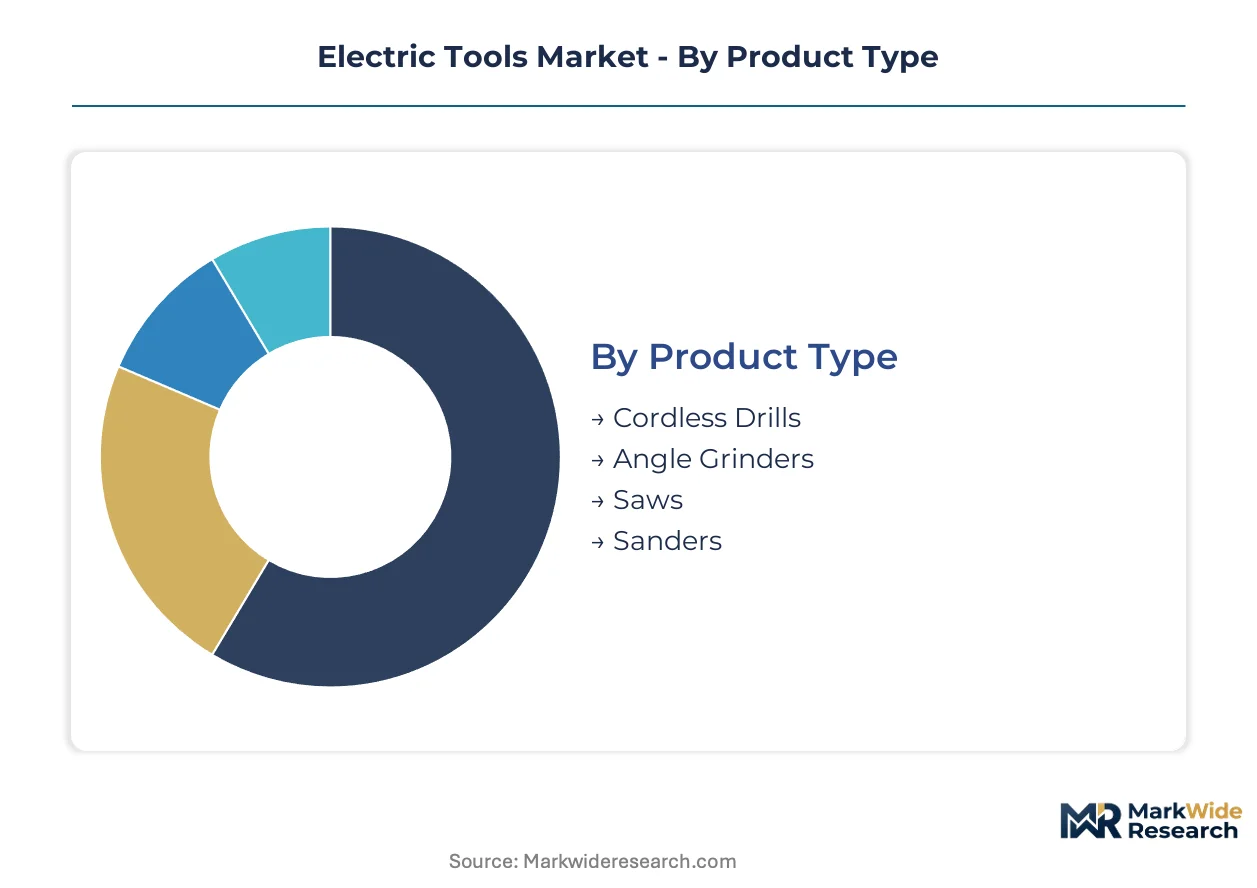
Segmentation in electric tools reveals how battery chemistry advances and motor control innovations are redrawing competitive boundaries across product categories and user profiles. Distinct specifications for professional versus consumer channels create divergent margin structures and replacement cycle dynamics.
Product Type:
Supply concentration for lithium-ion battery packs and brushless motor assemblies tilts manufacturing advantage toward platforms with the highest production volumes and standardized cell formats.
- Cordless Drills:Rotary percussion mechanisms deliver torque above 80 Nm through planetary gear reductions, with 18V and 20V platforms dominating professional job sites. Demand concentrates among residential construction crews in the United States where OSHA electrical safety frameworks accelerate corded-to-cordless fleet conversions.
- Angle Grinders:Disc speeds exceeding 10,000 RPM require thermal management systems and electronic motor protection circuits. German metalworking shops and Japanese shipyards drive specification requirements for sustained high-load operation.
- Saws:Reciprocating and circular blade configurations span wood, metal, and masonry cutting applications with specialized tooth geometries.
- Sanders:Orbital and belt-driven abrasion systems prioritize dust extraction integration for EPA-compliant workplace air quality standards.
Today's leader: Cordless Drills. Tomorrow's challenger: Angle Grinders.
End User:
Cost tier differentiation separates premium-grade durability specifications from economy-focused portability priorities across user categories.
- Contractors:Daily-use intensity demands IP54 ingress protection and drop-rated housings, with fleet management software integration becoming standard. Multi-site construction conglomerates in Nordic markets favor equipment-as-a-service contracts that bundle tool replacement and battery refresh.
- Industrial Users:Three-shift operational schedules require mean-time-between-failure metrics above 2,000 hours and rapid field-serviceability. Automotive assembly plants in Stuttgart and Toyota City specify vibration-dampened handles and torque-calibrated fastening systems.
- DIY Enthusiasts:Intermittent usage patterns prioritize lightweight ergonomics and single-battery platform compatibility across multiple tools.
- Maintenance Technicians:Confined-space access requirements drive compact head designs and right-angle drive configurations for facility infrastructure repair.
Industrial Users command premium pricing tiers. Contractors represent the steepest expansion trajectory as subscription models displace capital purchases.
Power Source:
Application environment dictates tethered versus mobile power architectures, with battery energy density improvements compressing the performance gap historically favoring corded systems.
- Battery-Powered:21700-format lithium-ion cells deliver sustained output above 1,000 watts through silicon-anode chemistry, enabling rotary hammer and large-angle grinder categories previously restricted to AC power. Commercial contractors in Germany and Japan are standardizing on this platform.
- Corded:Continuous high-torque applications in stationary metalworking retain cost advantages where workspace mobility is unnecessary.
- Hybrid:Dual-input systems accommodate battery operation for portability with AC adapter fallback for extended runtime.
- Pneumatic:Compressed-air systems retain dominance in heavy-duty shipyard and foundry applications where tethered operation remains acceptable and explosive atmosphere safety requires spark-free operation.
Battery-Powered platforms are gaining share fastest. Pneumatic retains defensive positions in hazardous environment niches.
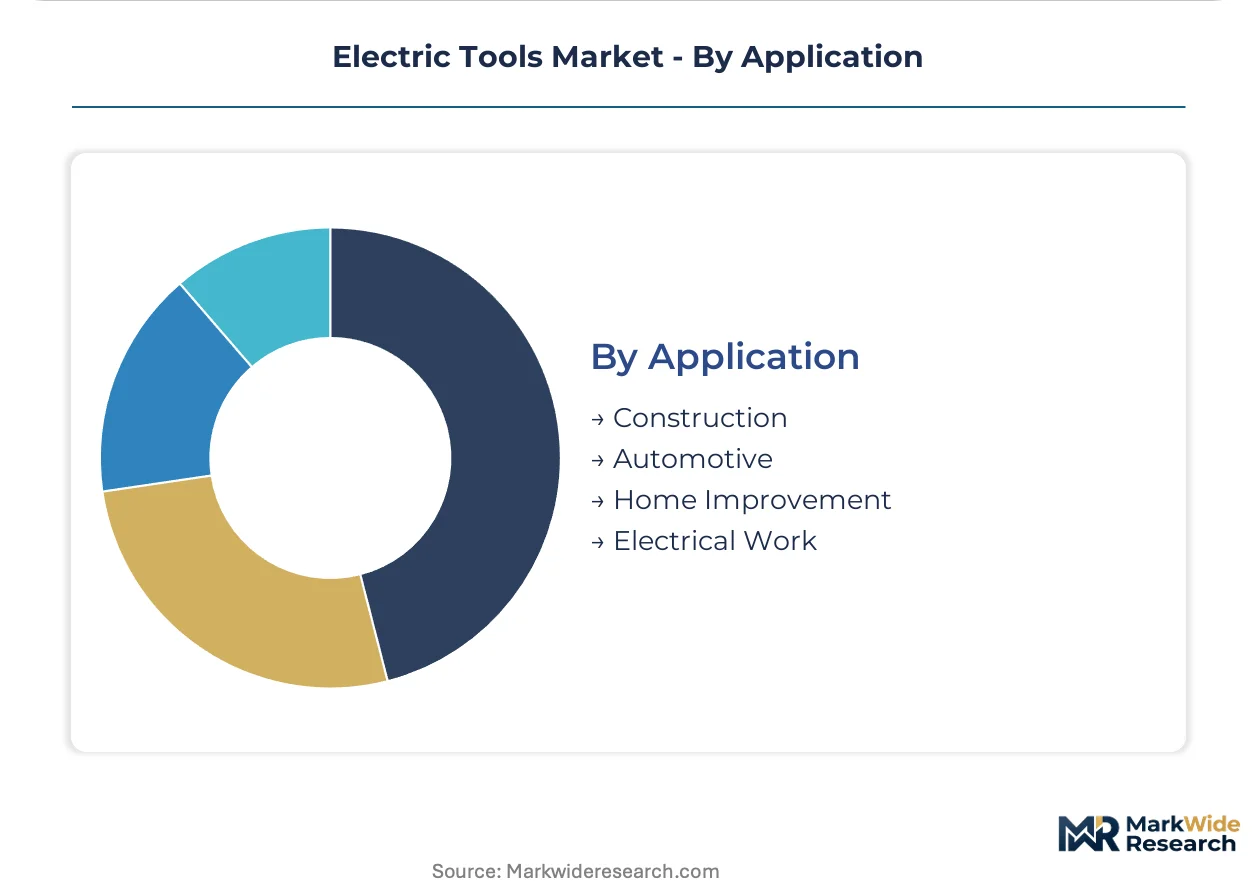
Application:
Customer type concentration varies by project scale, with professional channels demanding interoperability and consumer channels prioritizing single-platform simplicity.
- Construction:Framing, concrete anchoring, and finishing operations require tool ecosystems with cross-compatible batteries and rapid charger networks. China's infrastructure investment in Guangdong and Zhejiang manufacturing clusters shortens lead times for professional-grade battery packs.
- Automotive:Assembly line fastening protocols mandate torque precision within 3% variance and data logging for quality traceability.
- Home Improvement:Episodic project timelines favor compact storage footprints and multi-tool combo kits with shared battery platforms.
- Electrical Work:Insulated tool ratings and arc-flash protection compliance dominate specification requirements for live-circuit applications.
Construction anchors current volume. Automotive climbs fastest as electric vehicle assembly expands battery-powered fastening standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong and Zhejiang manufacturing clusters anchor global electric tool production capacity, with infrastructure investment cycles and regulatory compliance frameworks creating divergent demand patterns across major economies.
United States
Residential construction crews drive cordless platform adoption as OSHA electrical safety frameworks accelerate corded equipment retirement. EPA energy efficiency guidelines for battery charging systems mandate standby power limits and power factor correction in commercial-grade equipment. Manufacturing and distribution concentrate in the Midwest industrial corridor and Southeast logistics hubs serving retail and professional channels.
Germany
Commercial contractors standardize on 21700-format battery packs delivering sustained output above 1,000 watts for rotary hammer and angle grinder applications. REACH substance restrictions on cobalt and nickel compounds force electrode reformulation investments and extend EU qualification timelines. Stuttgart automotive assembly plants specify vibration-dampened handles and torque-calibrated fastening systems for three-shift operations.
China
Manufacturing clusters in Guangdong and Zhejiang concentrate professional-grade battery pack and motor assembly production, shortening lead times for export markets. MIIT industrial policy directives and GB standards influence domestic production specifications and export qualification protocols. Infrastructure investment in western provinces accelerates replacement cycles for construction equipment fleets.
Japan
Commercial contractors in Toyota City and Osaka industrial zones drive specification requirements for sustained high-load operation in metalworking applications. METI efficiency standards and JIS certification protocols shape product development priorities for domestic and export markets. Nagoya-area automotive assembly plants mandate torque precision within variance limits for quality traceability.
India
Domestic construction expansion and automotive assembly growth create demand for cordless fastening and cutting equipment. PLI scheme incentives for advanced chemistry cells reduce import dependency and build localized battery supply ecosystems. Manufacturing investment concentrates in Gujarat and Maharashtra industrial corridors serving South Asian distribution networks.
Electric Tools Market Competitive Landscape
Platform consolidation through proprietary battery ecosystem expansion dominates the current landscape, with manufacturers racing to lock users into single-brand equipment portfolios. The vendor base organizes around three tiers: diversified industrial conglomerates with broad brand portfolios, specialized professional-grade equipment manufacturers, and regional fabricators serving price-sensitive consumer channels. Two strategic archetypes define competitive positioning: ecosystem architects investing in cross-tool battery compatibility and modular design, and application specialists concentrating torque precision and durability specifications for industrial maintenance. M&A activity targets battery technology assets and connectivity software capabilities, while capacity expansion focuses on Southeast Asian and Indian manufacturing to mitigate tariff exposure and logistics costs.
Among diversified industrial conglomerates, Stanley Black & Decker and Robert Bosch GmbH exemplify ecosystem architects with broad retail and professional channel presence. Makita Corporation occupies a position within the specialized professional-grade tier, representing the archetype of trade-channel dominance through cordless platform standardization. These three companies anchor the competitive structure, with their strategic postures shaping battery format adoption and fleet management software integration trajectories across construction and automotive verticals.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Robert Bosch GmbH |
| Techtronic Industries Co. Ltd. |
| Makita Corporation |
| Hilti Corporation |
| Apex Tool Group |
| Atlas Copco AB |
| Ingersoll Rand |
| Snap-on Incorporated |
| Others |
Value Network & Pricing Analysis
Multi-site construction conglomerates in Nordic markets demanding equipment-as-a-service contracts with bundled battery refresh and theft insurance are forcing manufacturers to restructure cost accounting and supplier payment terms, compressing working capital cycles and amplifying margin sensitivity to lithium carbonate volatility.
Pricing Analysis
Lithium carbonate pass-through from South American and Australian mining operations creates margin compression that manufacturers address through three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates IP54-rated contractor-grade platforms with fleet software integration from DIY-focused lightweight ergonomics. Pricing pressure stems from REACH substance restrictions forcing cobalt and nickel electrode reformulation investments. Industrial users exhibit lowest price sensitivity due to three-shift operational schedules and mean-time-between-failure requirements above 2,000 hours.
Supply Chain Analysis
Dual-sourcing mandates from automotive assembly plants in Stuttgart and Toyota City require battery cell qualification across multiple suppliers, extending procurement timelines. Manufacturing concentrates in China, South Korea, and Japan for lithium-ion cells, brushless motor assemblies, and silicon-anode materials. Raw material dependencies span lithium carbonate, rare-earth permanent magnets, and copper windings. Single-source vulnerability in 21700-format cell production creates exposure. Distribution runs through Midwest industrial corridor and Southeast logistics hubs serving North American retail and professional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing cost arbitrage between China's Guangdong clusters and India's Gujarat corridor under PLI scheme incentives creates structural margin expansion for players relocating battery pack assembly.
For Market Incumbents: Acquire solid-state battery chemistry assets to defend against silicon-anode disruption from emerging chemistry specialists. Secure captive supply of rare-earth permanent magnets through backward integration into magnet alloy production. Expand 21700-format platform standardization to lock professional users into proprietary ecosystems and fragment aftermarket service networks. For New Entrants and Emerging Players: Capture India's domestic construction expansion by establishing localized battery pack assembly under PLI scheme incentives. Target maintenance technician segments with compact right-angle drive configurations for confined-space facility infrastructure repair. Deploy direct-to-contractor digital channels bypassing established retail and trade distribution. For Investors and Strategic Acquirers: Asymmetric upside sits with modular battery platform specialists enabling cross-brand compatibility and circular economy recovery obligations. Five-to-ten year viability favors companies with standardized cell formats aligned to EU Green Deal battery passport requirements. Watch India's advanced chemistry cell manufacturing scale-up as inflection indicator for South Asian supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Secures permanent magnet feedstock for brushless motor production against export restriction risks. |
| Equipment-as-a-Service Platform Launch | Transfers obsolescence risk to lessors while creating recurring revenue from Nordic construction conglomerates. |
| 21700-Format Battery Standardization | Enables sustained output above 1,000 watts for rotary hammer categories previously restricted to AC power. |
| Smart Tool Connectivity Integration | Bundles torque sensors and Bluetooth diagnostics with fleet management software for subscription revenue streams. |
| India PLI Scheme Manufacturing Investment | Reduces import dependency for advanced chemistry cells serving South Asian distribution networks. |
Research Methodology
Multiple input streams — OEM procurement team interviews, aftermarket distributor operational data, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged plant engineers, maintenance directors, construction fleet managers, and battery pack procurement leads across construction and automotive verticals. Secondary validation drew from OSHA electrical safety standard updates, EPA energy efficiency guideline revisions, ECHA REACH substance restriction notices, and MIIT industrial policy directives.
Data-stream reconciliation anchored volume and value outputs across product type, power source architecture, end-user intensity tier, and regional regulatory cluster segmentation. CAGRs were derived from replacement cycle compression rates and infrastructure investment trajectories. Forecast inputs incorporated lithium-ion energy density improvement curves, brushless motor adoption slopes, and equipment-as-a-service contract penetration rates.
Lithium carbonate price volatility, REACH substance restriction expansion, and India's PLI scheme implementation pace are the dominant revision risks to modeled outputs. Deviation in battery chemistry transition timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Die Grinders Market
Industrial Tools
Machine Tool Touch Probe Market
Industrial Tools
Global Tool Presetters Market
Industrial Tools
Height Gauge Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Coordinate Measuring Machine Market
Industrial Tools
Saudi Arabia Power Tools Market
Industrial Tools
Deburring Machine Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
Jigs and Other Tools Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Precision Components and Tooling Systems Market
Industrial Tools
India Power Tool Market
Industrial Tools
Dies, Jigs and Other Tools Market
Industrial Tools
Tool Holder Collets Market