
 Handheld DC Torque Tools Market | 2026-2036
Handheld DC Torque Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld DC Torque Tools Market Foresight
A shift from single-source pneumatic supply contracts to multi-source electric platform procurement is repositioning how tier-one manufacturers secure fastening capability. Atlas Copco leverages its cordless platform breadth to anchor premium contracts with European automotive OEMs. Stanley Black & Decker competes through retail-industrial hybrid distribution that extends its reach into mid-market maintenance shops. Robert Bosch GmbH dominates professional-grade brushless motor architectures with integrated torque-angle measurement.
Handheld DC torque tools are battery-powered, electronically controlled fastening instruments that deliver calibrated rotational force within ±1-5% accuracy tolerances, primarily used to prevent joint failure in critical assembly operations. Electric torque wrenches and torque screwdrivers lead product category revenue due to their compatibility with Industry 4.0 traceability systems, while digital technology segments capture expanding margin pools as manufacturers replace mechanical click-type tools with data-logging platforms. Assembly applications sustain the largest end-use volume, though maintenance and repair channels grow fastest as fleet operators internalize precision fastening capability.
FCC electromagnetic emissions standards in the United States, CE marking requirements under EU machinery directives, and REACH substance restrictions on battery chemistries collectively shape product design cycles and market access conditions for DC torque tool suppliers. ISO 5393 and ISO 6789 calibration protocols further dictate recertification intervals that sustain aftermarket service revenue streams. Stakeholders must monitor how emerging battery recycling mandates and right-to-repair legislation alter total cost-of-ownership calculations and channel economics.
Market Dynamics
Brushless motor architectures and integrated torque-angle measurement systems are compressing calibration cycles and forcing suppliers to rebuild service revenue models around predictive maintenance platforms rather than periodic recertification visits.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for traceable fastening data in automotive assembly are accelerating replacement of mechanical tools with digital logging platforms across German and Czech manufacturing plants.
- Semiconductor cleanroom specifications:South Korean fabrication facilities require oil-free electric fastening to eliminate pneumatic contamination risks in sub-10nm wafer production environments.
- Lithium-ion energy density improvements:Advanced cell chemistries are extending cordless tool runtime above 8 hours, enabling single-shift coverage without battery swap protocols in high-volume Chinese EV battery plants.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependency on Chinese refining capacity creates input cost volatility for brushless motor production.
- ISO 6789 recertification burden:Mandatory 12-month calibration intervals for precision-grade tools impose recurring compliance costs that deter small maintenance shops from upgrading from mechanical wrenches.
- Pneumatic legacy infrastructure:Existing compressed air distribution networks in mature US and Mexican automotive plants delay electric platform conversion despite superior torque accuracy.
Strategic Opportunities
- Indian PLI scheme for advanced manufacturing:Production-linked incentives for electronics and automotive component output are attracting torque tool suppliers to establish local calibration and service infrastructure.
- Right-to-repair legislative momentum:Proposed EU and US state-level mandates for battery replaceability and diagnostic access would unlock aftermarket parts revenue and extend tool lifecycle value.
- 5G-enabled predictive maintenance:Convergence of industrial IoT sensors and low-latency connectivity allows real-time joint quality monitoring, creating subscription-based torque assurance service models.
Industry Challenges
- Mechatronics technician scarcity:Maintenance departments lack personnel trained in both mechanical fastening physics and embedded electronics diagnostics, slowing Industry 4.0 tool deployment.
- Legacy MES integration complexity:Digital torque tools require custom middleware to communicate with decades-old manufacturing execution systems in brownfield European automotive facilities.
- REACH substance compliance timelines:Battery chemistry disclosure and recycling documentation obligations extend product development cycles by 6-9 months for EU market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld DC Torque Tools Market |
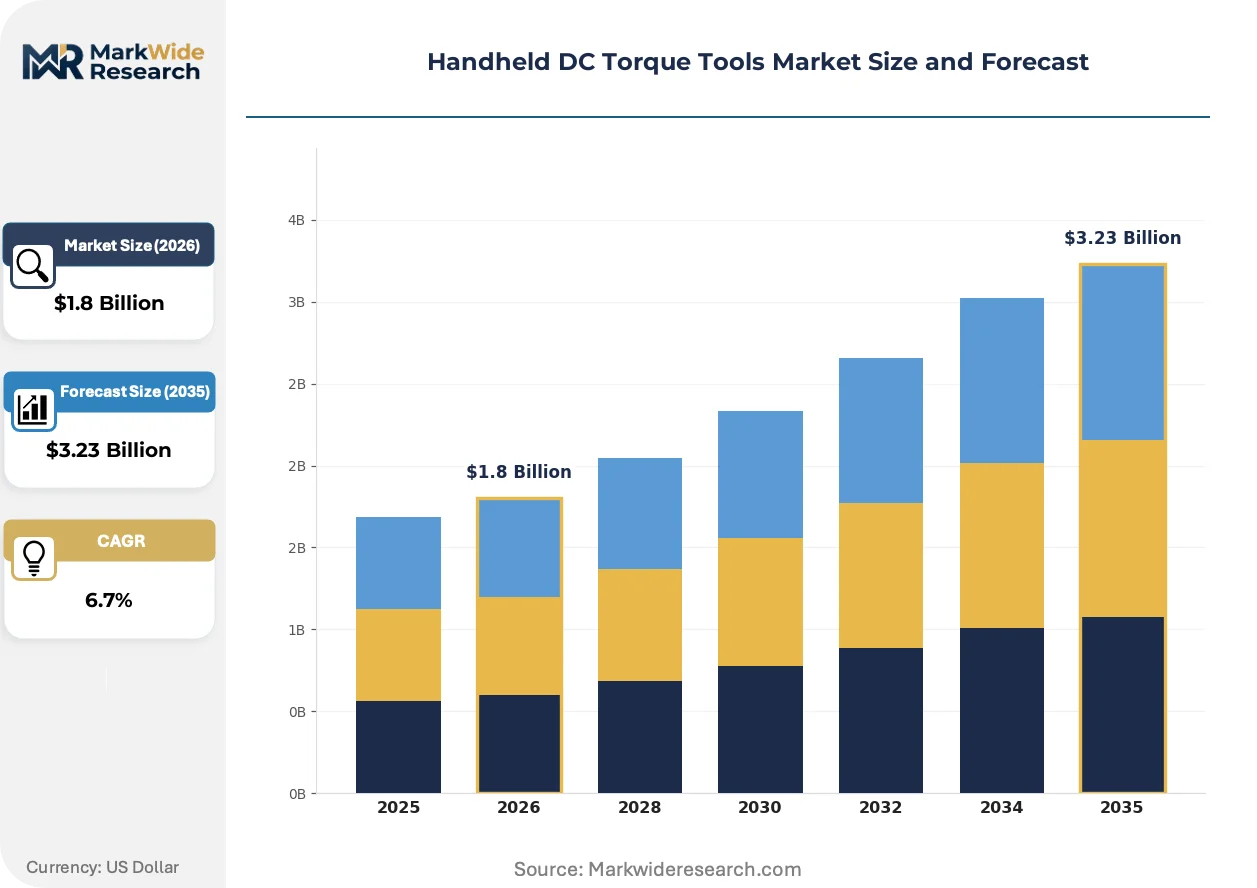
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Torque Wrenches, Torque Screwdrivers, Pneumatic Torque Tools, Multipliers End User: Automotive, Aerospace, Construction, Manufacturing Technology: Digital, Mechanical, Hydraulic, Electric Application: Assembly, Maintenance, Repair, Manufacturing Line |
| Companies Covered | Atlas Copco, Apex Tool Group, Stanley Black & Decker, Robert Bosch GmbH, Ingersoll Rand, Makita Corporation, Hilti, Snap-on, Desoutter Industrial Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld DC Torque Tools Market Shifts & Advancements
Real-time data capture and edge computing capabilities are transforming handheld torque tools from isolated mechanical instruments into networked quality control nodes that feed directly into statistical process control systems.
Multi-sensor torque-angle-speed measurement is integrating MEMS gyroscopes and strain-gauge arrays into compact pistol-grip housings, enabling joint friction analysis during the fastening cycle itself. German automotive OEMs specify these platforms for aluminum-intensive vehicle architectures where thread galling risks demand dynamic torque modulation. The technology is integrating process control directly into the tool rather than relying on external controllers, compressing the feedback loop from milliseconds to microseconds.
REACH substance restrictions on cobalt and nickel compounds in battery cathodes are forcing cell chemistry transitions toward lithium-iron-phosphate formulations that trade energy density for supply chain compliance. Tool manufacturers must redesign thermal management systems to accommodate these lower-voltage cells without sacrificing duty cycle performance. European professional-grade product lines are most affected, with suppliers accelerating modular battery platform architectures that isolate chemistry changes from tool electronics.
Buyer concentration among tier-one automotive and electronics contract manufacturers is compressing vendor qualification timelines and unbundling after-sales service from hardware procurement. Fleet operators in South Korean semiconductor and Chinese EV battery sectors now negotiate separate contracts for tool supply, calibration, and software licensing. This disintermediation is most visible in East Asian manufacturing clusters where consolidated purchasing power forces suppliers to disclose component-level cost structures.
Handheld DC Torque Tools Market Segmentation
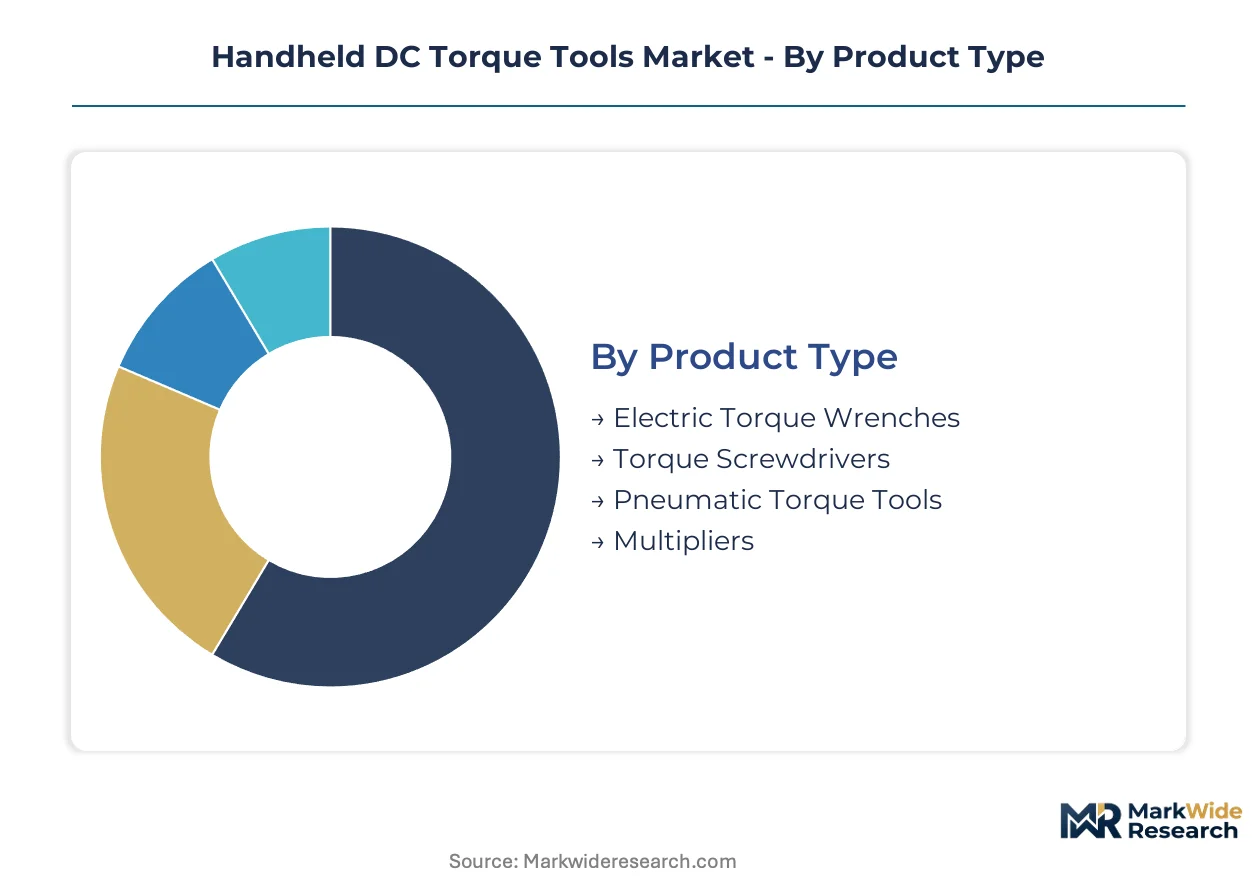
Segmentation in handheld DC torque tools reveals distinct upgrade cycles across product architectures and end-use environments. Procurement patterns diverge sharply between precision-critical assembly operations and general maintenance channels.
Product Type:
Replacement cycles accelerate where digital traceability requirements override mechanical tool longevity.
- Electric Torque Wrenches:Battery-powered pistol and inline configurations deliver calibrated torque with ±1-3% accuracy through brushless motor control. German automotive OEMs specify these platforms for aluminum-intensive vehicle architectures where thread galling risks demand dynamic torque modulation. Demand concentrates in Stuttgart and Munich assembly plants upgrading from pneumatic systems to meet EU Machinery Directive traceability mandates.
- Torque Screwdrivers:Compact DC-powered instruments target low-torque precision fastening in electronics assembly. South Korean semiconductor fabrication facilities require oil-free electric screwdrivers to eliminate pneumatic contamination risks in sub-10nm wafer production environments.
- Pneumatic Torque Tools:Legacy compressed-air systems retain installed base in mature Mexican and US automotive plants with existing air distribution infrastructure.
- Multipliers:Gear-assisted torque amplification attachments extend standard tool range for heavy-vehicle assembly applications.
Volume placements concentrate in electric torque wrenches; the faster expansion belongs to torque screwdrivers.
End User:
Cost tier differentiation separates specification-grade procurement from price-sensitive maintenance operations.
- Automotive:Tier-one suppliers and OEM assembly plants drive premium digital platform adoption. Battery-powered brushless tools displace pneumatic systems in German and Czech manufacturing facilities facing tighter fastening tolerances.
- Aerospace:FAA-certified calibration protocols and AS9100 traceability requirements sustain specialized service revenue streams. Precision-grade torque-angle measurement systems command 3-5x mechanical tool pricing.
- Construction:Field maintenance crews prioritize runtime and durability over measurement accuracy. Mid-market cordless platforms dominate bridge and infrastructure fastening applications.
- Manufacturing:Electronics contract manufacturers in Chinese EV battery plants and South Korean semiconductor clusters negotiate consolidated fleet contracts with unbundled software licensing.
Revenue concentrates in automotive; the steepest expansion trajectory appears in manufacturing.
Technology:
Application maturity determines whether digital platforms displace established mechanical or hydraulic alternatives.
- Digital:Integrated torque-angle-speed measurement with MEMS gyroscopes and strain-gauge arrays enables real-time joint friction analysis. Process control migrates directly into tool electronics, compressing feedback loops from milliseconds to microseconds.
- Mechanical:Click-type wrenches retain cost advantage in small maintenance shops deterred by ISO 6789 recertification burdens. Legacy mechanical tools persist where traceability requirements remain unenforced.
- Hydraulic:High-torque applications in heavy machinery assembly sustain niche demand for fluid-powered systems exceeding electric platform limits.
- Electric:Brushless motor architectures with integrated controllers bridge digital and mechanical categories, capturing mid-market transitions.
Installations concentrate in electric; the fastest share gains belong to digital.
Application:
Customer type fragmentation separates high-volume assembly procurement from sporadic maintenance purchasing patterns.
- Assembly:High-volume production lines in Chinese EV battery plants demand 8+ hour runtime from advanced lithium-ion cell chemistries. Single-shift coverage without battery swap protocols drives fleet standardization on specific cordless platforms.
- Maintenance:Fleet operators internalize precision fastening capability, creating fastest-growing channel for mid-tier digital tools. Indian PLI scheme incentives attract suppliers to establish local calibration infrastructure for electronics and automotive component maintenance.
- Repair:Aftermarket service operations prioritize interoperability across multiple OEM platforms. Right-to-repair legislative momentum in EU and US state jurisdictions would unlock battery replaceability and diagnostic access revenue.
- Manufacturing Line:Brownfield European automotive facilities face legacy MES integration complexity, delaying Industry 4.0 tool deployment despite specification requirements.
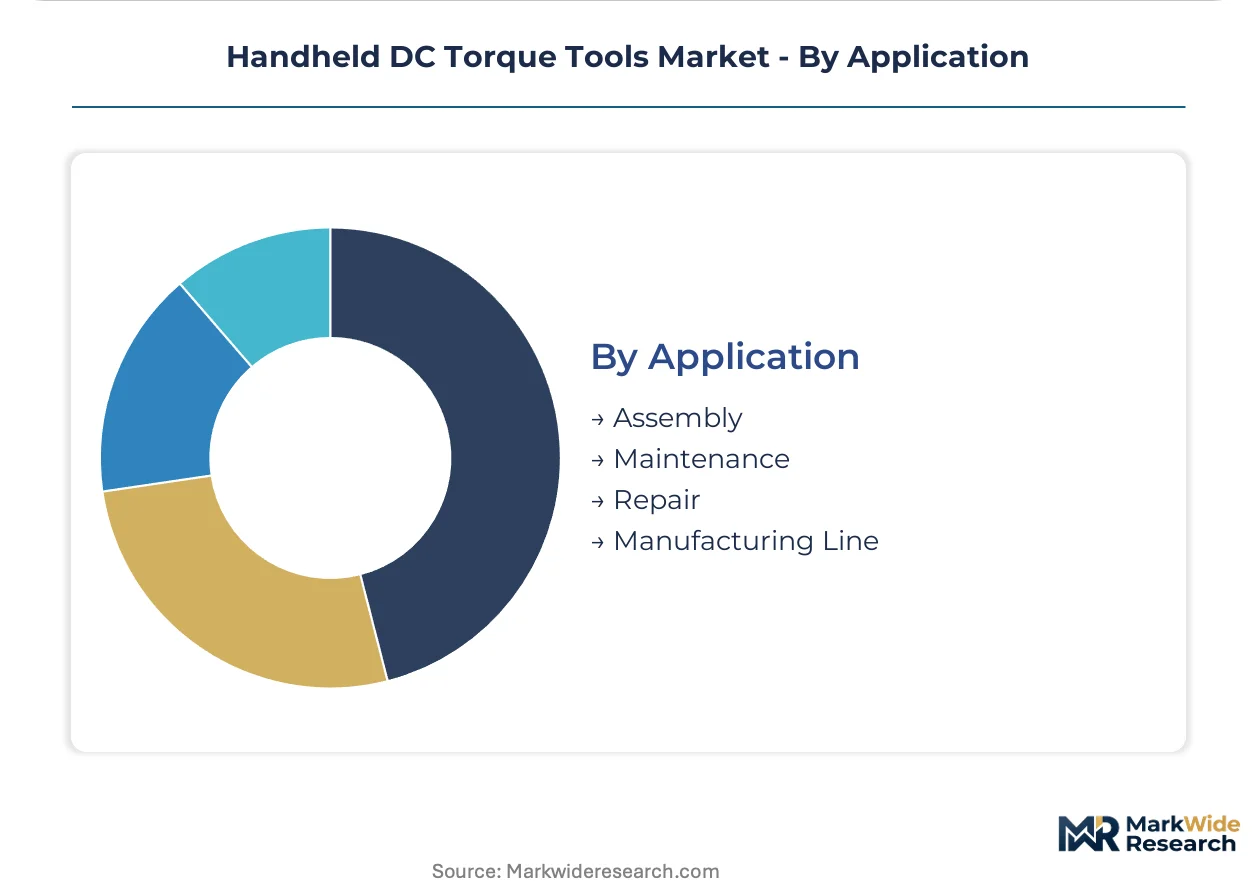
Unit volumes concentrate in assembly; the most rapid expansion occurs in maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium and dysprosium refining capacity in China anchors upstream supply chains for brushless motor production, while assembly demand clusters in German automotive corridors, South Korean semiconductor fabrication zones, and Chinese electric vehicle manufacturing belts.
China
Domestic rare earth magnet refining dominance secures captive input supply for brushless motor manufacturing. MIIT industrial equipment upgrade programs accelerate replacement of pneumatic systems with digital torque platforms in Yangtze River Delta electronics assembly plants. Shenzhen and Dongguan contract manufacturers negotiate consolidated fleet contracts with unbundled software licensing for EV battery production lines.
Germany
Stuttgart and Munich automotive OEMs specify torque-angle measurement systems for aluminum-intensive vehicle architectures. CE marking requirements under EU Machinery Directive mandate traceable fastening data, accelerating digital tool adoption across Baden-Württemberg assembly plants. KBA vehicle type approval protocols extend calibration compliance obligations to tier-one supplier networks.
South Korea
Semiconductor fabrication facilities in Pyeongtaek and Hwaseong require oil-free electric fastening to eliminate pneumatic contamination risks in sub-10nm wafer production. MFDS industrial equipment standards align with cleanroom specifications for electronics manufacturing. Busan-Ulsan machinery clusters host specialized calibration service infrastructure for precision-grade tool fleets.
United States
FCC electromagnetic emissions standards shape product design cycles for cordless platform entry. NHTSA tightening of fastener quality traceability in automotive assembly drives digital tool procurement in Michigan and Ohio manufacturing corridors. Mexican maquiladora plants with existing pneumatic infrastructure delay electric conversion despite specification advantages.
India
PLI scheme production-linked incentives for electronics and automotive component output attract torque tool suppliers to establish local calibration infrastructure. BIS certification requirements for industrial equipment create compliance barriers for imported platforms. Maharashtra and Tamil Nadu manufacturing clusters see fastest maintenance channel expansion as fleet operators internalize precision fastening capability.
Handheld DC Torque Tools Market Competitive Landscape
Global majors compete with regional champions across technology licensing and service infrastructure dimensions. The vendor base organizes into three tiers: integrated industrial conglomerates with cordless platform breadth, specialized fastening equipment houses with calibration service networks, and power tool manufacturers extending from consumer into professional-grade segments. Consolidation pressure intensifies as buyer concentration among tier-one automotive and electronics contract manufacturers compresses vendor qualification timelines. Dominant competitive moves include geographic expansion through local calibration joint ventures and portfolio diversification into predictive maintenance software subscriptions.
Among European industrial equipment houses, Atlas Copco and Robert Bosch GmbH occupy positions anchoring premium-tier procurement with integrated torque-angle measurement architectures. Apex Tool Group represents the transatlantic fabrication archetype bridging North American and Asian supply relationships. These three exemplify how scale-driven platform breadth competes against specialized fastening expertise in contract negotiations with consolidated fleet operators.
| Leading Market Players |
|---|
| Atlas Copco |
| Apex Tool Group |
| Stanley Black & Decker |
| Robert Bosch GmbH |
| Ingersoll Rand |
| Makita Corporation |
| Hilti |
| Snap-on |
| Desoutter Industrial Tools |
| Others |
Supply & Pricing Matrix
Battery chemistry transitions toward lithium-iron-phosphate formulations simultaneously compress gross margins on European professional-grade product lines and concentrate procurement leverage among tier-one automotive and electronics contract manufacturers with consolidated fleet purchasing power.
Pricing Analysis
Warranty and calibration service bundling separates premium-tier suppliers from mid-market competitors, with Atlas Copco and Robert Bosch GmbH commanding 40-60% price premiums through integrated predictive maintenance subscriptions. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 6789 certification grade and torque-angle measurement capability. Cost compression in the mid-tier is intensifying because unbundled software licensing allows Chinese EV battery plants to negotiate hardware and service contracts separately. Small maintenance shops in India and Mexico remain most price-sensitive due to mandatory 12-month recertification burdens.
Supply Chain Analysis
Neodymium and dysprosium magnet supply rests on Chinese refining capacity, with secondary processing concentration in Japan and Germany for high-grade motor laminations. Brushless motor production draws from rare earth permanent magnets, lithium-ion cell packs, and MEMS sensor arrays. Single-source vulnerability in Chinese rare earth processing creates input cost volatility that propagates through motor controller pricing. Distribution runs through authorized industrial distributors in automotive corridors and direct OEM contracts in semiconductor fabrication zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Machinery Directive traceability mandates and ISO 6789 recertification protocols erect barrier-to-entry moats for suppliers with established calibration infrastructure.
For Market Incumbents: To counter unbundled procurement pressure from consolidated fleet operators, anchor premium contracts through predictive maintenance platform subscriptions and deepen backward integration into brushless motor controller production to defend margin position against rare earth cost volatility. For New Entrants and Emerging Players: E-commerce calibration service portals offer the most penetrable route into Indian maintenance channels underserved by established European service networks, with PLI scheme incentives enabling local infrastructure buildout at lower capital intensity than automotive assembly plant qualification. For Investors and Strategic Acquirers: Re-rating potential sits with specialized fastening equipment houses possessing ISO 17025-accredited calibration networks given right-to-repair legislative momentum unlocking aftermarket parts revenue. Long-term viability favors targets with software-defined torque assurance capabilities. The signal to watch is 5G-enabled predictive maintenance subscription attach rates crossing threshold penetration in South Korean semiconductor fabs.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Atlas Copco leverages real-time joint quality monitoring to convert hardware margins into recurring SaaS revenue streams. |
| Backward Integration into Motor Controllers | Robert Bosch GmbH captures value from brushless motor architectures through in-house production of torque-angle measurement electronics. |
| Local Calibration Joint Venture | Apex Tool Group establishes ISO 17025-accredited service infrastructure in Maharashtra to serve Indian PLI scheme manufacturing clusters. |
| Battery Platform Modularization | Suppliers isolate REACH chemistry transitions from tool electronics through swappable lithium-iron-phosphate cell architectures. |
| 5G-Enabled Torque Assurance Service | Desoutter Industrial Tools deploys edge computing capabilities for microsecond-feedback process control in German aluminum-intensive vehicle assembly. |
Research Methodology
Document review covered ISO 5393 and ISO 6789 calibration protocol documentation, EU Machinery Directive compliance filings, and REACH substance restriction guidance, complemented by interviews with plant engineers at German automotive OEMs, maintenance directors at South Korean semiconductor fabrication facilities, procurement leads at Chinese EV battery contract manufacturers, and aftermarket service heads at Indian electronics component suppliers. Secondary validation drew from customs trade data for rare earth magnet flows, SEC 10-K filings for industrial equipment manufacturers, and MIIT industrial equipment upgrade program disclosures. Bottom-up demand modeling from end-user fleet sizes triangulated against top-down market sizing from supplier revenue disclosures.
Unit shipment and value estimates across the projection horizon reflect segmented modeling by product type, technology tier, end-use industry, and regional manufacturing cluster. CAGRs derive from regression analysis of replacement cycle acceleration patterns and technology penetration curves. Industry-specific forecast inputs include lithium-ion energy density improvement trajectories and semiconductor cleanroom specification evolution for oil-free fastening requirements.
The model holds under stable rare earth supply conditions and continued EU Machinery Directive enforcement; deviation in Chinese export restriction policies or right-to-repair legislative timelines would shift replacement cycle assumptions. Forecasts reflect documented assumptions regarding brushless motor cost curves and calibration service pricing elasticity. A small set of triggers—battery chemistry transition costs, 5G infrastructure deployment pace, and mechatronics technician training pipeline expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Drill Drivers Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Machine Tool Touch Probe Market
Industrial Tools
Tool Holder Market
Industrial Tools
India Power Tool Market
Industrial Tools
Air Screwdrivers Market
Industrial Tools
Digital Tool Presetter Market
Industrial Tools
Global Tool Presetters Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
Die Grinders Market
Industrial Tools
Height Gauge Market
Industrial Tools
Coordinate Measuring Machine Market
Industrial Tools
Dies, Jigs and Other Tools Market
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
Saudi Arabia Power Tools Market
Industrial Tools
Tool Holder Collets Market