
 Global Tool Presetters Market | 2026-2036
Global Tool Presetters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tool Presetters Market Outlook
Carbide-tipped measuring probes and contactless optical sensors are expanding the performance envelope of next-generation tool presetters, displacing legacy mechanical dial systems in high-throughput environments. Zoller leverages integrated software platforms that bridge presetting data directly into CAM workflows. HAIMER anchors its position through proprietary shrink-fit technology bundled with presetter sales. Renishaw differentiates via probe-based verification systems that extend tool measurement into in-process monitoring.
A tool presetter is a precision metrology device that measures cutting tool geometry, runout, and length offline before installation in a machine tool spindle, typically achieving repeatability within two micrometers. Its primary purpose is eliminating manual trial cuts, reducing machine downtime, and ensuring first-part accuracy in subtractive manufacturing. Automatic and CNC presetters command the widest installed base among product types due to throughput advantages in serial production, while digital technology segments capture expanding margin pools as shops replace analog readouts with networked data capture. Aerospace and medical device applications sustain premium pricing for higher-accuracy configurations.
FDA quality system regulations for medical device subcontractors in the United States mandate traceable tool measurement records, directly elevating demand for data-logging presetters. Japan's METI promotes smart factory standards that incentivize wireless-connected presetting systems, while ISO 13399 and ISO 8601 frameworks govern cutting tool data interoperability across European and Asian supply chains. Stakeholders must evaluate whether to standardize on single-vendor digital ecosystems or maintain interoperability across mixed toolroom fleets.
Market Dynamics
ISO 13399 standardization for cutting tool data exchange is compressing procurement cycles and forcing toolroom digitization across automotive and aerospace supply chains, eliminating analog measurement workflows that previously tolerated manual data re-entry.
Growth Catalysts
- Automotive precision mandates:German and Japanese OEMs now require CNC-based presetter verification for all high-volume cutting tools, eliminating trial-cut protocols that previously consumed spindle hours.
- FDA traceability requirements:Medical device subcontractors in the United States must maintain auditable tool measurement records, directly elevating demand for data-logging presetters with embedded database functionality.
- Carbide-tipped probe adoption:Contactless optical sensors paired with mechanical touch probes are expanding measurement envelopes to micro-tool geometries below three millimeters in diameter.
Market Restraints
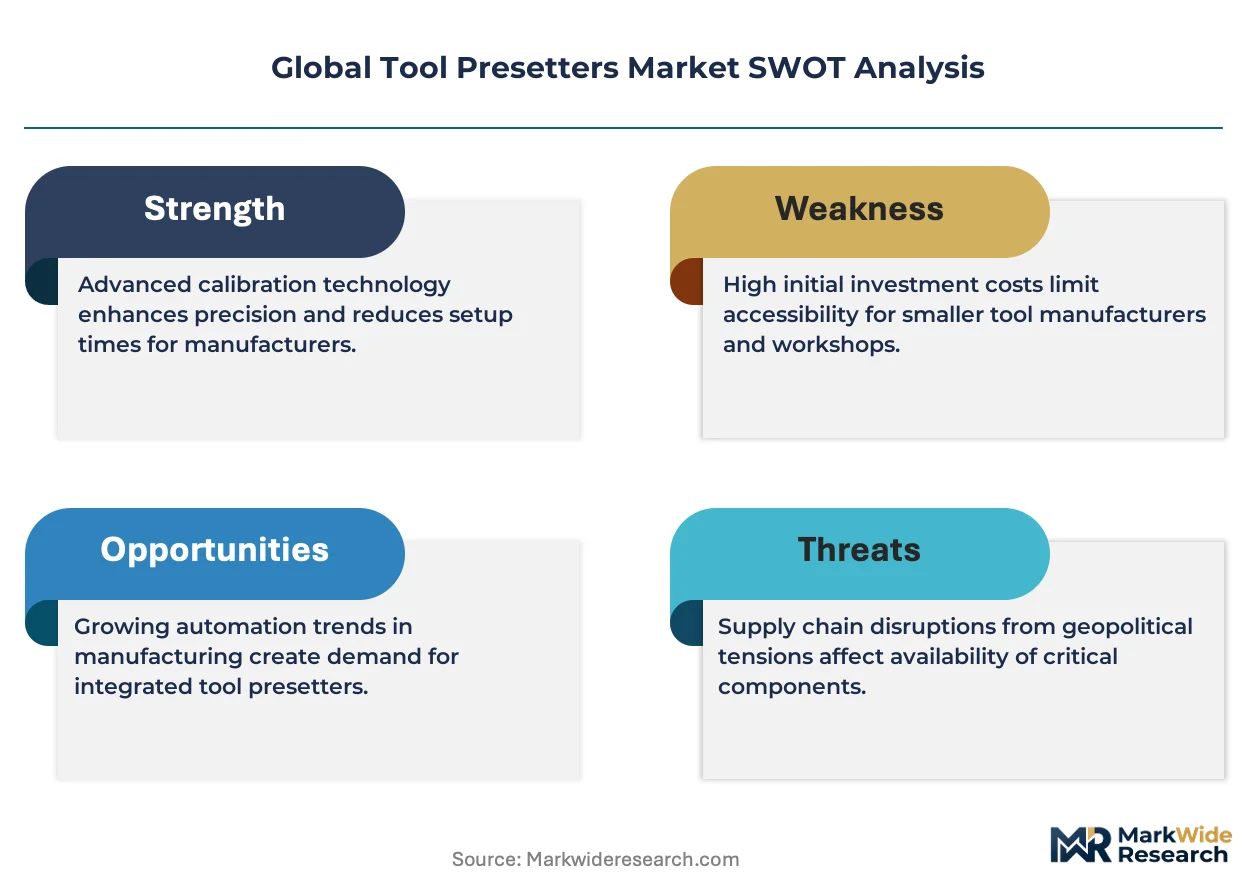
- High-precision granite substrate costs:Vibration-dampened base materials sourced from specialized quarries in Switzerland and Germany create input cost volatility that squeezes margins on mid-range presetter configurations.
- Concentrated spindle interface supply:HSK and Capto taper measurement adapters rely on a narrow supplier base concentrated in Baden-Württemberg, exposing buyers to extended lead times during capacity constraints.
- Limited retrofit compatibility:Legacy mechanical dial presetters lack standardized data ports, forcing complete replacement rather than upgrade paths for shops with depreciated equipment.
Strategic Opportunities
- Indian precision machining expansion:Aerospace component manufacturing in Bangalore and Hyderabad is accelerating, yet domestic presetter penetration remains below fifteen percent of toolroom capacity.
- Wireless data integration:METI smart factory incentives in Japan are subsidizing Bluetooth-enabled presetter-to-CAM connectivity, creating subsidized upgrade windows for domestic and export equipment.
- Additive-manufacturing hybrid workflows:Metal 3D-printed cutting tools with complex internal cooling channels require non-contact runout verification that traditional mechanical presetters cannot perform.
Industry Challenges
- Metrology technician scarcity:Shops in South Korea and Switzerland report acute shortages of operators trained in interferometric calibration procedures for optical presetter maintenance.
- Multi-vendor software integration:CAM workflows from disparate suppliers require custom middleware development to ingest presetter data streams, extending deployment timelines by four to eight weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tool Presetters Market |
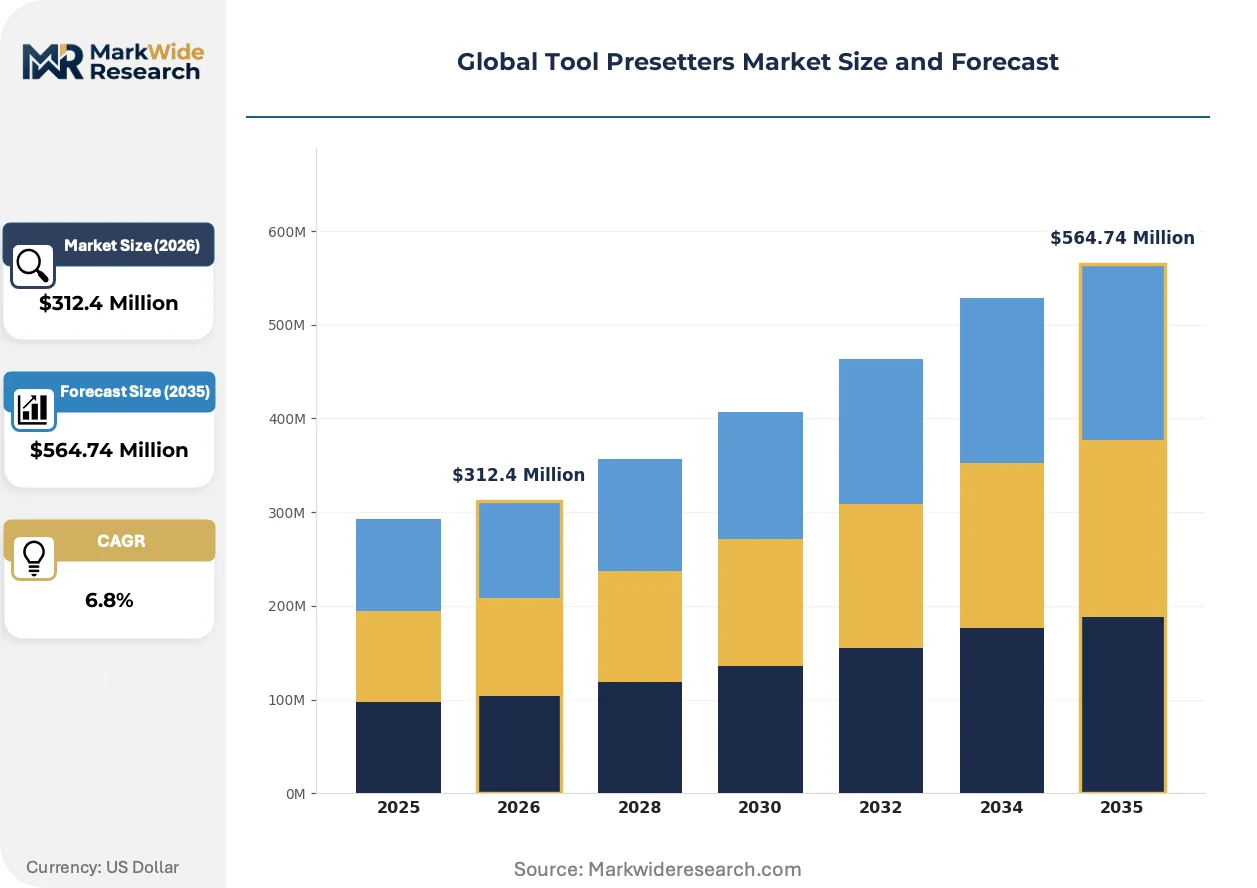
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Semi-Automatic, CNC Application: Aerospace, Automotive, Medical Devices, Industrial Manufacturing End User: OEMs, Maintenance Providers, Tooling Companies, Engineering Firms Technology: Digital, Analog, Hybrid, Wireless |
| Companies Covered | Zoller, HAIMER, Speroni, NIKKEN Kosakusho, BIG DAISHOWA, Kelch, Parlec, Renishaw, NT Tool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tool Presetters Market Strategic Shifts
Measurement hardware is converging with manufacturing execution software, collapsing the historical separation between tool preparation and production scheduling. This integration is compressing setup cycles and enabling predictive tool life management.
Contactless chromatic confocal sensors are rewriting surface finish and edge-radius measurement capabilities for micro-milling tools. Medical device manufacturers in Switzerland and orthopedics suppliers in Warsaw are adopting these systems at replacement rates exceeding thirty percent annually. The technology is compressing measurement uncertainty bands from five micrometers to sub-micron repeatability, enabling first-article approval without destructive test cuts.
Japan's METI smart factory standards now mandate wireless-connected presetter data streams as a condition for productivity subsidy eligibility. The regulation forces domestic machine shops to replace analog readouts with networked systems or forfeit equipment depreciation credits. Small and mid-tier subcontractors in Aichi and Osaka prefectures are responding with phased retrofit programs rather than full equipment replacement.
Buyers are unbundling after-sales calibration contracts from initial equipment purchases, treating metrology verification as a competitive procurement category separate from hardware. Distributor service divisions in Germany and the United States are losing captive maintenance revenue to independent ISO 17025 laboratories. The shift is most visible among tier-two automotive suppliers with centralized toolroom operations across multiple plant locations.
Global Tool Presetters Market Segmentation
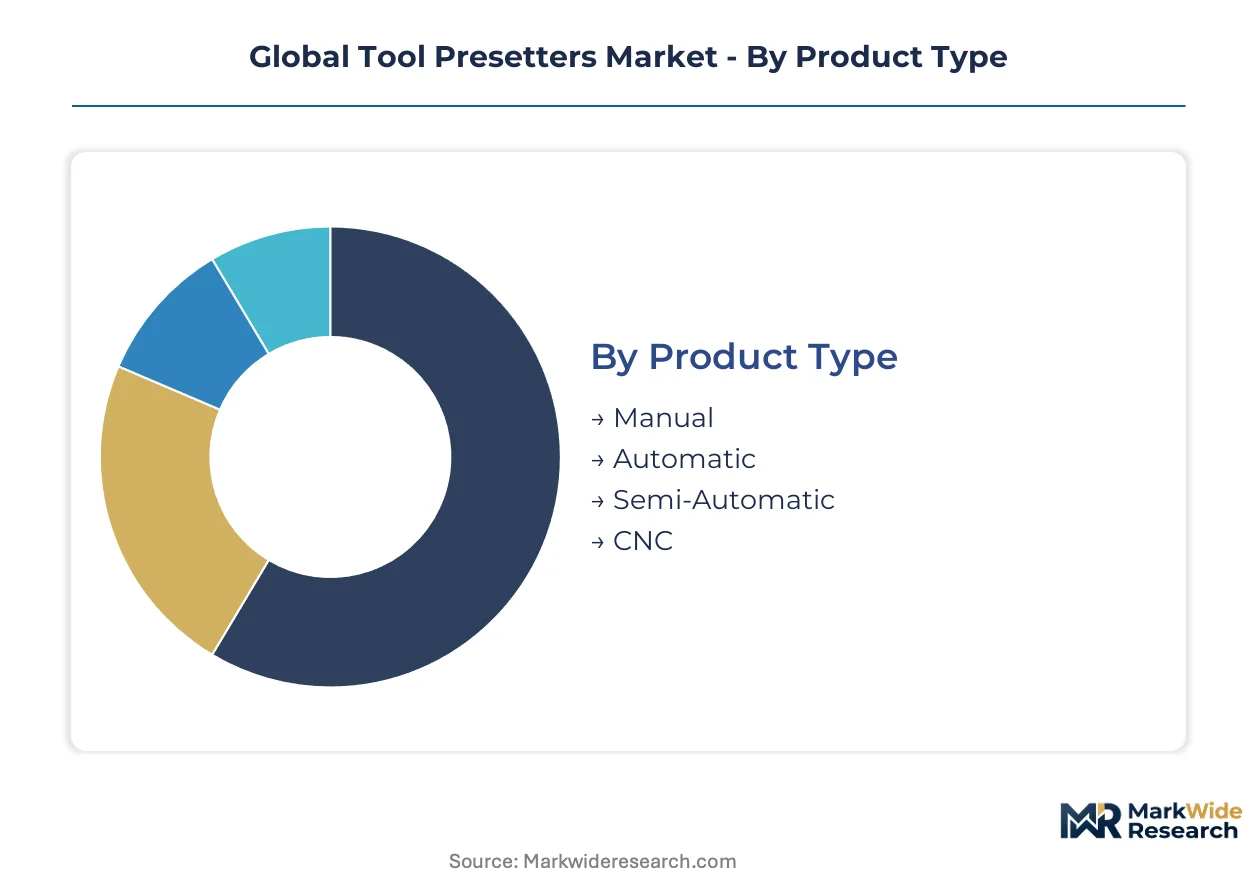
Tool presetter segmentation reflects divergent investment cycles across manufacturing tiers. Procurement patterns split between high-volume automotive serial production demanding automated throughput and precision medical device workshops prioritizing measurement traceability over speed.
Product Type:
Spindle interface complexity and measurement repeatability specifications define the technology hierarchy across manual through CNC configurations.
- Automatic:Motorized measuring cycles with pneumatic tool clamping achieve sub-two-micron repeatability without operator intervention. German and Japanese automotive OEMs mandate automatic presetters for all high-volume cutting tools, eliminating trial-cut protocols that previously consumed spindle hours.
- CNC:Programmable multi-axis positioning enables complex tool geometry measurement including ball-nose end mills and indexable insert bodies. Aerospace precision mandates in Switzerland and South Korea concentrate demand for CNC configurations with integrated probe calibration.
- Manual:Mechanical dial or digital readout systems requiring operator positioning of cutting edges against fixed references.
- Semi-Automatic:Hybrid configurations automating measurement cycles while retaining manual tool loading for mixed-batch toolrooms.
Automatic presetters lead on scale; CNC configurations lead on momentum.
Application:
Regulatory intensity and tolerance requirements create four distinct demand profiles with divergent margin structures.
- Automotive:Tier-one suppliers in Germany operate centralized toolrooms serving multiple stamping and powertrain plants with identical presetter protocols. ISO 13399 standardization compresses procurement cycles and forces toolroom digitization across automotive supply chains.
- Medical Devices:FDA quality system regulations for US-based subcontractors mandate traceable tool measurement records with embedded database functionality. Orthopedics suppliers in Warsaw and cardiovascular device manufacturers in Minnesota sustain premium pricing for higher-accuracy configurations.
- Aerospace:Titanium and Inconel machining applications demand thermal stability and vibration damping that constrain acceptable base material sourcing.
- Industrial Manufacturing:General machining job shops with heterogeneous tool portfolios and intermittent presetter utilization patterns.
Automotive commands the largest installed base; medical devices capture the steepest expansion trajectory.
End User:
Capital deployment authority and tool lifecycle responsibility determine procurement specifications across the value chain.
- Tooling Companies:Specialized cutting tool manufacturers in Baden-Württemberg and Osaka prefecture operate captive presetters for incoming quality verification and final inspection. These firms bundle shrink-fit technology and presetter sales into integrated offerings.
- OEMs:Original equipment manufacturers with centralized toolroom operations across multiple plant locations unbundle after-sales calibration contracts from initial equipment purchases.
- Maintenance Providers:Third-party repair and refurbishment specialists requiring portable or compact presetter configurations for on-site service.
- Engineering Firms:Prototype and low-volume production workshops with intermittent presetter utilization and sensitivity to capital expenditure thresholds.
Tooling companies dominate replacement demand; OEMs drive specifications for new installations.
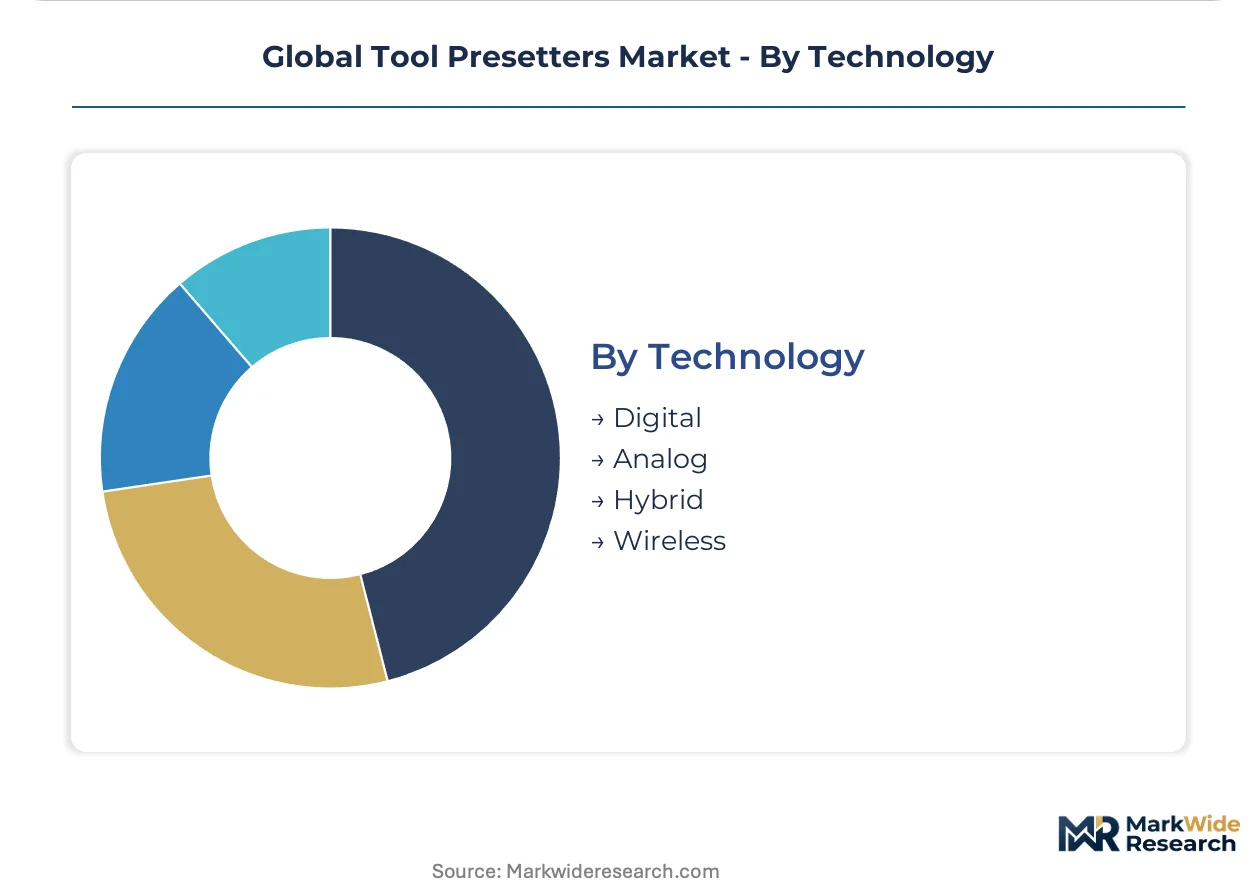
Technology:
Data capture architecture and connectivity protocols separate legacy analog installations from networked digital systems.
- Digital:Networked data capture with direct CAM workflow integration and embedded database functionality for audit trails. METI smart factory standards in Japan mandate wireless-connected presetter data streams as a condition for productivity subsidy eligibility.
- Wireless:Bluetooth-enabled presetter-to-CAM connectivity eliminating manual data re-entry and enabling real-time tool status monitoring across distributed toolrooms.
- Analog:Mechanical dial or basic digital readout systems lacking standardized data ports and forcing complete replacement rather than upgrade paths.
- Hybrid:Configurations combining optical sensors with mechanical touch probes for expanded measurement envelopes including micro-tool geometries below three millimeters.
Digital technology leads current revenue; wireless connectivity gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision machining corridor anchors presetter demand through captive tooling company operations and automotive supplier concentration. ISO 13399 standardization reshapes procurement protocols across German, Japanese, and Swiss manufacturing clusters. Regulatory mandates from METI and FDA accelerate digitization in East Asian and North American toolrooms.
Germany
Automotive tier-one suppliers in Stuttgart and Munich operate centralized toolrooms mandating CNC-based presetter verification for all high-volume cutting tools. KBA vehicle safety regulations indirectly elevate machining precision requirements across powertrain component supply chains. Baden-Württemberg's tooling manufacturers bundle shrink-fit technology with presetter sales into integrated offerings.
Japan
METI smart factory standards now mandate wireless-connected presetter data streams as a condition for productivity subsidy eligibility. Aichi and Osaka prefecture subcontractors face phased retrofit programs to maintain equipment depreciation credits. Nagoya's aerospace component manufacturers concentrate demand for thermal-stable granite-base configurations.
United States
FDA quality system regulations mandate traceable tool measurement records for medical device subcontractors in Minnesota and Massachusetts. Orthopedics suppliers sustain premium pricing for higher-accuracy presetter configurations with embedded database functionality. Greater Boston's cardiovascular device manufacturers drive replacement rates exceeding thirty percent annually for chromatic confocal sensor systems.
Switzerland
Medical device manufacturers in Geneva and Bern adopt contactless chromatic confocal sensors for micro-milling tool verification at sub-micron repeatability. Swissmedic device approval requirements elevate measurement traceability standards across orthopedic and dental implant supply chains. Jura-based precision machining clusters source vibration-dampened granite substrates from specialized domestic quarries.
South Korea
Aerospace precision mandates in Seoul and Busan concentrate demand for CNC configurations with integrated probe calibration. Acute shortages of metrology technicians trained in interferometric calibration procedures constrain optical presetter maintenance capacity. Daegu-Gyeongbuk's automotive component manufacturers accelerate automatic presetter adoption for serial production environments.
Global Tool Presetters Market Competitive Environment
Global majors compete with regional champions across software integration and spindle interface specialization. The vendor base separates into three tiers: integrated platform providers bundling presetter hardware with CAM connectivity, precision measurement specialists leveraging proprietary sensor architectures, and regional fabricators serving localized tooling company relationships. Consolidation pressure concentrates in mid-range configurations where granite substrate cost volatility squeezes margins. Dominant competitive moves include strategic partnerships for wireless data protocol standardization and selective backward integration into shrink-fit taper adapter production.
Within the integrated platform tier, Zoller and HAIMER represent contrasting geographic anchoring strategies. Zoller occupies a position bridging presetter data directly into manufacturing execution workflows through software-centric positioning. HAIMER exemplifies the precision measurement specialist archetype with proprietary mechanical technology bundled across hardware sales. Renishaw sits within the sensor technology vector, extending tool measurement architectures into in-process monitoring applications. These three anchors illustrate how competitive differentiation fragments across software integration, mechanical precision, and sensor innovation vectors rather than consolidating around uniform capability stacks.
| Leading Market Players |
|---|
| Zoller |
| HAIMER |
| Speroni |
| NIKKEN Kosakusho |
| BIG DAISHOWA |
| Kelch |
| Parlec |
| Renishaw |
| NT Tool |
| Others |
Value Chain & Pricing Dynamics
Tier-one automotive suppliers in Germany and Japan concentrate procurement authority for CNC-based presetters, anchoring a contract-based pricing model where multi-year service bundling determines effective unit economics. This buyer concentration grants volume purchasers leverage over mid-range configurations while premium medical-device tiers sustain price integrity through FDA-mandated database functionality.
Pricing Analysis
Granite substrate volatility from Swiss and German quarries passes through to mid-range presetter margins, compressing returns on non-automated configurations. Three-tier pricing structure across premium, standard, and economy levels separates medical-device chromatic confocal systems from automotive automatic units and legacy manual installations. Price erosion runs through semi-automatic and manual tiers as METI subsidy deadlines force Japanese shops toward wireless digital replacements. Job shops in industrial manufacturing exhibit highest price sensitivity, while orthopedics suppliers in Warsaw and cardiovascular device manufacturers in Minnesota accept premium positioning for sub-micron repeatability.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Minneapolis coordinate hub-and-spoke fulfillment for presetter hardware and calibration consumables. Manufacturing concentrates in Germany, Japan, and Switzerland, with vibration-dampened granite bases drawing from specialized quarries in the Jura region and Black Forest. HSK and Capto taper measurement adapters rest on a narrow supplier base in Baden-Württemberg, creating single-source vulnerability during capacity constraints. Distribution runs through captive tooling company channels in Baden-Württemberg and Osaka prefecture, alongside independent metrology distributors serving North American medical-device clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into durable demand, with ISO 13399 standardization eliminating analog measurement workflows and forcing replacement cycles across automotive and aerospace supply chains.
For Market Incumbents: Deepen proprietary shrink-fit taper adapter production to offset HSK/Capto supply concentration risks in Baden-Württemberg. Expand calibration service networks into independent ISO 17025 laboratories before distributor service divisions lose captive maintenance revenue. Software-centric positioning via direct CAM workflow integration defends against sensor-technology specialists extending into presetter hardware. For New Entrants and Emerging Players: Launch via wireless-enabled compact configurations targeting Indian aerospace subcontractors in Bangalore and Hyderabad, where domestic presetter penetration remains below fifteen percent of toolroom capacity. METI smart factory subsidies in Japan create a subsidized upgrade window for Bluetooth-enabled systems. Focus initial deployment on additive-manufacturing hybrid workflows requiring non-contact runout verification for metal 3D-printed cutting tools. For Investors and Strategic Acquirers: Precision measurement specialists with proprietary optical sensor architectures are the most active acquirer in this space, consolidating software integration capabilities to bridge presetter data into manufacturing execution workflows. Long-term viability hinges on regulatory ratchet effects from FDA traceability mandates and METI connectivity standards. Monitor replacement rates for chromatic confocal sensor systems in Swiss and Boston medical-device clusters as inflection indicators for premium-tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Shrink-Fit Taper Production | Captive supply of HSK/Capto adapters insulates margins from Baden-Württemberg supplier concentration. |
| Wireless Data Protocol Standardization Partnership | Bluetooth-enabled CAM connectivity secures METI subsidy eligibility for Japanese equipment deployments. |
| Chromatic Confocal Sensor Platform Launch | Sub-micron repeatability captures Swissmedic-driven replacement cycles in Geneva orthopedic implant toolrooms. |
| Independent Calibration Service Expansion | ISO 17025 laboratory accreditation captures unbundled maintenance procurement from tier-one automotive suppliers. |
| Indian Aerospace Component Manufacturing Joint Venture | Bangalore and Hyderabad precision machining clusters offer underpenetrated demand for automatic presetter verification. |
Study Parameters
Coverage spans Germany, Japan, the United States, Switzerland, and South Korea, with primary inputs from each precision machining cluster. Primary interviews with toolroom managers at automotive tier-one suppliers, metrology technicians in Swiss medical-device manufacturers, and aftermarket service heads at German tooling companies combined with secondary validation from ISO 13399 implementation documentation, METI smart factory subsidy records, and FDA quality system inspection data. Bottom-up presetter installation counts triangulated against top-down manufacturing value-added estimates across subtractive machining applications.
Granularity-level modeling disaggregated volume and value across the projection horizon by product type, application, end user, and technology segments. The analytical framework derived CAGRs from segment-level replacement rates, regulatory compliance deadlines, and capital expenditure patterns at centralized toolroom operations. Industry-specific forecast inputs included METI equipment depreciation credit phase-out schedules and Swissmedic device approval timelines affecting measurement traceability requirements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under acute metrology technician shortages in South Korea or extended granite quarry supply disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
India Power Tool Market
Industrial Tools
Precision Components and Tooling Systems Market
Industrial Tools
Coordinate Measuring Machine Market
Industrial Tools
Air Screwdrivers Market
Industrial Tools
Machine Tool Touch Probe Market
Industrial Tools
Tool Holder Market
Industrial Tools
Jigs and Other Tools Market
Industrial Tools
Digital Tool Presetter Market
Industrial Tools
Handheld DC Torque Tools Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
Height Gauge Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Plasma Arc Cutting Market
Industrial Tools
Electric Tools Market
Industrial Tools
Dies, Jigs and Other Tools Market
Industrial Tools
Centerless Grinding Market