
 Insulated Screwdriver Market | 2026-2036
Insulated Screwdriver Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Screwdriver Market Insights
Commercial electricians is collapsing the historical split with residential contractors as the dominant buyer archetype for insulated screwdriver procurement. Klein Tools leverages its channel depth in North American electrical supply houses to sustain contractor loyalty. Wiha Tools anchors European demand through precision manufacturing and VDE certification dominance. Stanley Black & Decker competes across price tiers with broad distribution scale.
An insulated screwdriver is a hand tool with a non-conductive handle and shaft coating, typically rated to 1,000 volts AC per IEC 60900, designed to protect technicians from electric shock during energized circuit work. The tool serves critical safety functions in electrical maintenance, telecommunications infrastructure, and industrial manufacturing where accidental contact with live conductors poses fatal risk. Phillips and slotted product types occupy the volume core, while Torx variants capture premium positioning in aerospace and precision assembly applications. Fiberglass and polypropylene materials lead the material mix, with rubber-overmolded handles commanding higher margins due to ergonomic certification requirements.
VDE certification in Germany, IEC 60900 international standards, and OSHA 1910.335 in the United States collectively define product compliance thresholds and market access conditions for insulated screwdriver manufacturers. These frameworks mandate periodic dielectric testing, traceable batch certification, and handle material flammability standards that directly shape R&D allocation and production cost structures. Stakeholders must monitor evolving national adoptions of IEC revisions and regional enforcement intensity to anticipate compliance-driven replacement cycles.
Market Dynamics
The insulated screwdriver market pivots on tightening electrical safety enforcement across industrial maintenance protocols, where live-work certification requirements are compressing replacement cycles and elevating dielectric testing standards as non-negotiable procurement criteria.
Growth Catalysts
- IEC 60900 Adoption:National implementations across utility sectors mandate 1,000V-rated hand tools for energized circuit maintenance, forcing fleet upgrades in power distribution networks.
- Commercial Electrician Procurement:Industrial facility managers specify VDE-certified toolkits for contracted maintenance crews, accelerating volume demand beyond residential replacement rates.
- Fiberglass Handle Technology:Advanced composite manufacturing reduces dielectric degradation under thermal cycling, extending certified tool lifespan in high-frequency use environments.
Market Restraints
- Raw Material Concentration:Specialized fiberglass rovings and high-grade polypropylene resins concentrate among Asian chemical suppliers, exposing manufacturers to input cost volatility.
- Certification Timeline Friction:VDE batch testing protocols in Germany create 12-16 week lead times for new product introductions, constraining rapid market response.
- Non-Insulated Substitute Persistence:Standard screwdrivers retain share in de-energized work environments where electricians bypass premium pricing for routine installation tasks.
Strategic Opportunities
- Telecommunications Infrastructure:5G fiber-to-the-antenna deployments require compact insulated precision drivers for cabinet work in partially energized equipment rooms.
- OSHA Enforcement Intensification:Enhanced 1910.335 inspection activity across US manufacturing plants creates compliance-driven replacement demand with documented audit trails.
- E-Commerce Direct Procurement:Specialized industrial distributors bypass traditional electrical supply house channels, capturing contractor mobile ordering preferences.
Industry Challenges
- Dielectric Testing Technician Scarcity:Certified laboratories capable of IEC 60900 periodic verification remain concentrated in Germany and the United States, creating geographic bottlenecks for tool recertification services.
- Legacy Inventory Obsolescence:Pre-2018 insulated tool stocks lacking traceable batch documentation face write-downs as industrial procurement departments enforce certificate-of-conformity requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Screwdriver Market |
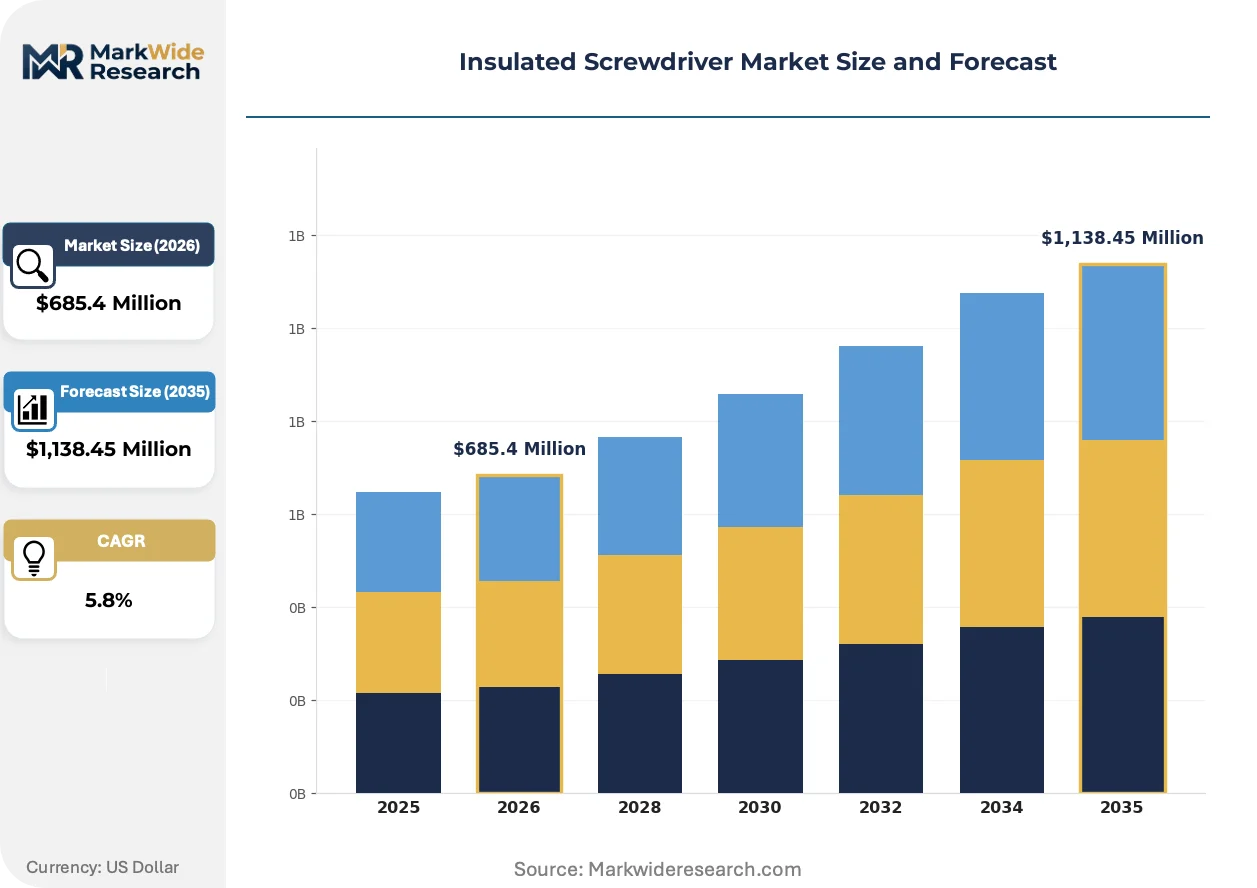
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slotted, Phillips, Torx, Hex, Pozidriv Material: Fiberglass, Plastic, Rubber, Polypropylene, PVC Application: Electrical Maintenance, Telecommunications, Aerospace, Marine, Manufacturing End User: Electricians, Industrial Technicians, Mechanical Assemblers, HVAC Specialists, Electronics Engineers |
| Companies Covered | Wiha Tools, Klein Tools, Wera Tools, Greenlee, IDEAL Industries, Stanley Black & Decker, Emerson Electric, Honeywell International, Fluke Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Screwdriver Market Trends and Innovations
Material science advances and regulatory digitization are restructuring how insulated hand tools achieve certification, distribute through channels, and embed traceability into maintenance workflows.
Dual-layer injection molding with fiberglass-reinforced polypropylene cores is supplanting single-material handles in premium product tiers. Aerospace maintenance divisions and automotive electrical teams specify these constructions for enhanced thermal stability under repeated sterilization and solvent exposure. The technology compresses warranty claim rates while extending recertification intervals.
EU F-Gas Regulation enforcement is tightening supply chain documentation requirements for handle polymers with blowing-agent residuals. Manufacturers must now submit third-party chemical composition attestations alongside dielectric test reports to maintain CE marking validity. German industrial buyers are the first to reject shipments lacking expanded material disclosure.
Certification-driven preference shifts now dominate contractor toolkit specifications. Facility safety managers in US manufacturing plants require serialized tool tracking with digital certificate repositories, displacing paper-based VDE documentation. This behavior concentrates most visibly in automotive and chemical processing verticals where audit preparedness determines vendor selection.
Insulated Screwdriver Market Segmentation
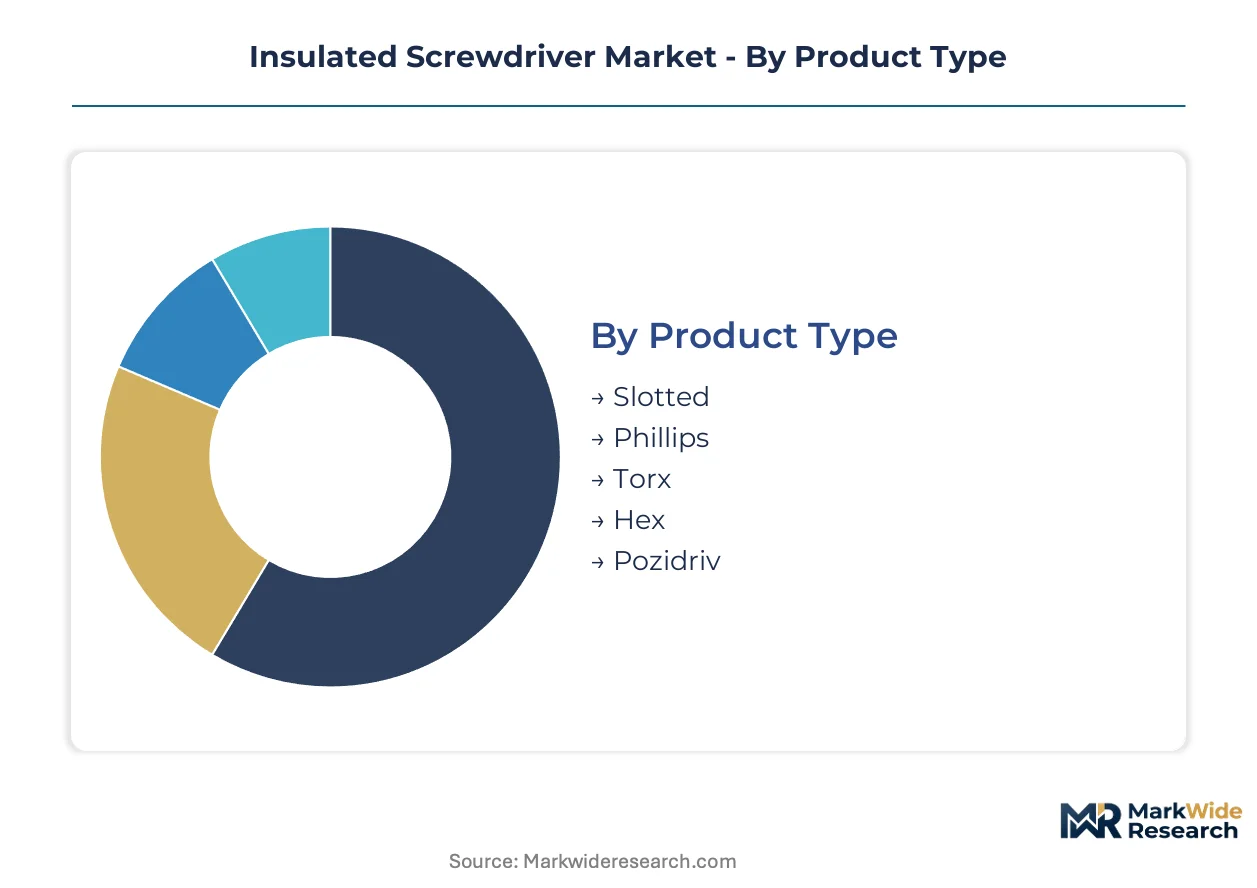
Insulated screwdriver procurement decisions split across technical specifications, safety certifications, and end-use environments. Each segmentation dimension reveals distinct substitution pressures and margin structures that reshape vendor positioning.
Product Type:
Slotted and Phillips variants face persistent substitution from standard non-insulated drivers in de-energized residential work, while specialized tip geometries command protected niches.
- Slotted:Flat-blade design rated to 1,000V AC per IEC 60900 remains the default specification for legacy electrical panels and industrial switchgear. Demand concentrates in German industrial maintenance protocols where VDE certification mandates traceable batch documentation for every tool in energized work kits.
- Phillips:Cross-recess tip geometry dominates North American electrical supply house inventories. Commercial electricians in US manufacturing plants specify these for OSHA 1910.335 compliance during live-circuit breaker servicing, driving faster replacement cycles than residential channels.
- Torx:Six-lobe star pattern captures aerospace maintenance divisions requiring tamper-resistant precision.
- Hex:Six-sided recess serves mechanical assemblers in automotive electrical systems.
- Pozidriv:Supplemented cross design reduces cam-out in European telecommunications cabinet installations.
Slotted anchors the volume base while Torx gains share at the steepest rate.
Material:
Cost tier stratification separates premium composite constructions from commodity polymer handles, with thermal cycling performance determining recertification economics.
- Fiberglass:Reinforced roving cores with polypropylene overmolding deliver superior dielectric stability under repeated thermal stress. Aerospace and chemical processing verticals specify these for extended recertification intervals, justifying 40-60% handle cost premiums over single-material alternatives.
- Polypropylene:Injection-molded homopolymer balances electrical insulation with solvent resistance for industrial technicians. German automotive electrical teams favor this grade for sterilization compatibility in cleanroom maintenance environments.
- Plastic:General-purpose thermoplastics serve price-sensitive residential contractors.
- Rubber:Overmolded grip layers command ergonomic certification premiums.
- PVC:Legacy compound faces EU F-Gas Regulation documentation scrutiny for blowing-agent residuals.
Polypropylene captures the highest shipment volumes while fiberglass expands most quickly in premium tiers.
Application:
Electrical maintenance absorbs the majority of insulated tool procurement, though telecommunications infrastructure is accelerating fastest as 5G fiber-to-the-antenna deployments multiply energized cabinet work sites.
- Electrical Maintenance:Utility sector specifications mandate 1,000V-rated hand tools for power distribution network energized circuit work. IEC 60900 national implementations across European grid operators force fleet-wide upgrades, compressing replacement cycles to 24-36 months in high-frequency use environments.
- Telecommunications:Compact precision drivers for partially energized equipment rooms serve 5G infrastructure rollout. US tower technicians and European fiber installers specify slim-profile insulated sets for dense cabinet configurations where accidental live contact poses fatal risk.
- Aerospace:MRO divisions require serialized tool tracking with digital certificate repositories.
- Marine:Salt-air corrosion resistance specifications add material complexity.
- Manufacturing:OSHA enforcement intensification across US plants drives compliance-driven replacement demand.
Electrical maintenance dominates absolute demand while telecommunications infrastructure shows the steepest expansion trajectory.
End User:
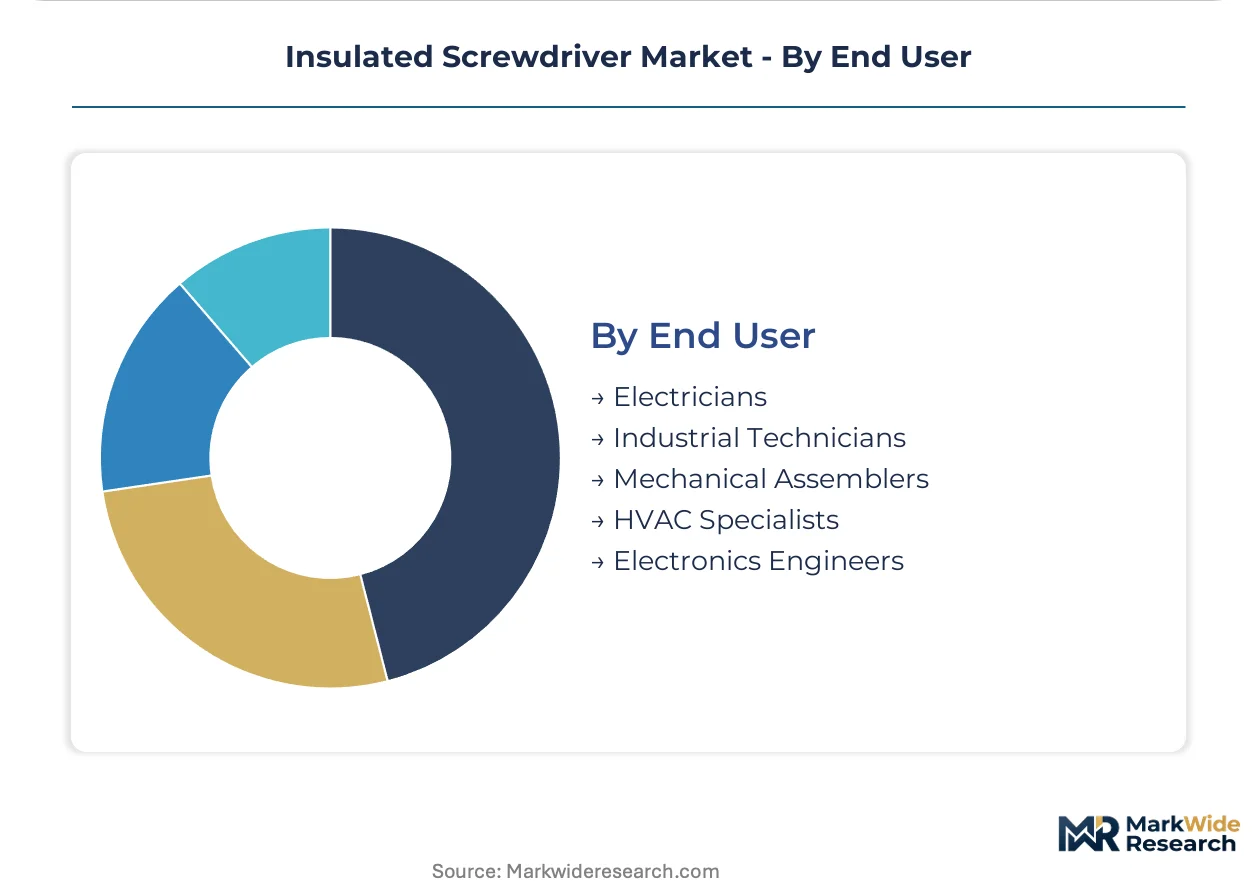
Electricians and industrial technicians split procurement authority, with facility safety managers increasingly specifying certified toolkits for contracted maintenance crews rather than individual purchase decisions.
- Electricians:Commercial contractors now outpace residential specialists in insulated screwdriver procurement velocity. German facility managers require VDE-certified complete toolkits for external maintenance crews, shifting purchase authority from individual tradespeople to procurement departments with documented audit trail requirements.
- Industrial Technicians:Manufacturing plant maintenance teams operate under tightening OSHA 1910.335 inspection activity. US automotive and chemical processing verticals enforce serialized tracking with digital certificate repositories, displacing paper-based VDE documentation.
- Mechanical Assemblers:Automotive electrical system integration requires precision insulated drivers.
- HVAC Specialists:Refrigeration circuit work drives demand for compact insulated sets.
- Electronics Engineers:Laboratory and test bench applications favor precision tip geometries.
Electricians retain the largest installed base while industrial technicians drive the fastest procurement growth rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor sustains Central European industrial maintenance density, while the Texas-to-California transmission superhighway underwrites North American electrical contractor mobility.
Germany
VDE-certified toolkits dominate procurement for industrial facility maintenance crews across Bavaria and North Rhine-Westphalia. The country's Federal Network Agency enforces IEC 60900 compliance timelines for utility sector contractors. Stuttgart's automotive electrical cluster drives premium fiberglass handle specifications for extended recertification intervals.
United States
OSHA 1910.335 inspection intensification across manufacturing plants compresses replacement cycles for commercial electricians. The Department of Labor's enhanced enforcement protocols mandate documented audit trails for live-work tool certification. Houston's petrochemical corridor and Detroit's automotive belt concentrate demand for serialized tracking systems.
China
State Grid Corporation's 1,000V-rated tool mandates for distribution network maintenance accelerate fleet upgrades. The State Administration for Market Regulation aligns national GB standards with IEC 60900 dielectric testing protocols. Yangtze River Delta manufacturing clusters supply specialized fiberglass rovings for handle core production.
Japan
METI's electrical safety guidelines for telecommunications infrastructure drive compact precision driver demand. The Ministry of Economy, Trade and Industry coordinates JIS standard harmonization with international certification frameworks. Osaka-Kansai electronics maintenance hubs specify slim-profile insulated sets for dense cabinet configurations.
India
Bureau of Indian Standards adoption of IEC 60900 for utility sector procurement creates compliance-driven replacement demand. The Central Electricity Authority mandates periodic dielectric testing for state distribution company contractors. Maharashtra's Mumbai-Pune industrial corridor and Gujarat's chemical processing belt concentrate facility safety manager procurement authority.
Insulated Screwdriver Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and channel density. The insulated screwdriver market structures around three tiers: heritage electrical tool brands with supply house dominance, precision manufacturing specialists with VDE certification authority, and diversified industrial conglomerates with broad distribution scale. Strategic moves concentrate on certification digitization partnerships and dielectric testing laboratory capacity expansion.
Among heritage electrical specialists, Klein Tools and Wiha Tools exemplify divergent geographic anchoring strategies, while Stanley Black & Decker occupies a position spanning price tier diversification. Wera Tools and Greenlee sit within the precision-specialist archetype emphasizing tip geometry engineering. IDEAL Industries and Fluke Corporation represent the instrumentation-integrated toolkit approach where insulated hand tools complement electrical testing equipment portfolios.
| Leading Market Players |
|---|
| Wiha Tools |
| Klein Tools |
| Wera Tools |
| Greenlee |
| IDEAL Industries |
| Stanley Black & Decker |
| Emerson Electric |
| Honeywell International |
| Fluke Corporation |
| Others |
Pricing and Supply Chain Analysis
Batch-scale dielectric testing capacity in Germany anchors cost floors for VDE-certified toolkits, compressing margin flexibility for manufacturers serving price-sensitive residential channels while elevating premiums for traceable documentation tiers. This concentration of certification infrastructure simultaneously enforces supply-side discipline and stratifies pricing power across commercial and industrial buyer archetypes.
Pricing Analysis
Volume-discount tiering structures separate individual contractor purchases from fleet procurement contracts issued by facility safety managers at automotive and chemical processing plants. Pricing stratifies across premium, standard, and economy tiers based on certification depth and ergonomic certification status. Cost compression in economy-grade polypropylene handles intensifies as Asian compounders expand generic resin capacity. Residential electricians exhibit highest price sensitivity, while industrial procurement departments prioritize documented audit trails over unit cost.
Supply Chain Analysis
China and Germany anchor specialized fiberglass roving production for dielectric handle cores, with Yangtze River Delta chemical clusters feeding roving supply and Bavarian compounders finishing high-grade polypropylene overmolding. The supply chain draws from concentrated Asian resin suppliers and German certification laboratories. Single-source vulnerability concentrates in VDE batch testing capacity, where twelve-to-sixteen-week lead times constrain rapid product introduction. Distribution runs through electrical supply houses in North America and industrial distributors in Europe, with direct e-commerce channels capturing mobile contractor ordering preferences.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulated screwdriver market sits in early-cycle recovery as utility sector fleet upgrades accelerate under IEC 60900 national implementations across European grid operators and State Grid Corporation mandates in China.
For Market Incumbents: Shield certification-derived pricing power by deepening laboratory partnerships in Germany to secure dielectric testing priority slots against emerging competitors. Expand serialized digital certificate repositories to capture automotive and chemical processing verticals where audit preparedness determines vendor selection. Defend against non-insulated substitute erosion by bundling recertification services with original toolkit sales. For New Entrants and Emerging Players: Aftermarket recertification services represent the most penetrable white-space target, as incumbent manufacturers under-serve dielectric testing demand outside Germany and the United States. Target telecommunications infrastructure contractors with compact precision driver sets optimized for dense 5G cabinet configurations. Pursue direct e-commerce procurement partnerships to bypass entrenched electrical supply house channel control. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among certification laboratories and digital tool-tracking platform providers serving automotive and chemical processing verticals with serialized audit requirements. Long-term viability centers on compliance-driven replacement cycles rather than discretionary equipment purchases. Monitor OSHA 1910.335 enforcement intensity across US manufacturing plants as the primary inflection indicator for compliance-driven demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dielectric Testing Laboratory Expansion | Capacity additions in Germany and the United States reduce certification bottlenecks and compress new product introduction timelines. |
| Digital Certificate Repository Development | Serialized tracking platforms capture automotive and chemical processing procurement specifications requiring documented audit trails. |
| Fiberglass Handle Composite R&D | Advanced thermal cycling performance extends recertification intervals and justifies premium pricing in aerospace maintenance divisions. |
| Direct E-Commerce Channel Investment | Mobile ordering platforms capture contractor preferences bypassing traditional electrical supply house intermediaries. |
| Telecommunications Precision Driver Launch | Compact slim-profile sets address 5G fiber-to-the-antenna deployment requirements in partially energized equipment rooms. |
Research Methodology
A standing panel of facility safety managers, commercial electrical contractors, dielectric testing laboratory technicians, and industrial procurement directors provided ongoing calibration across primary interview rounds. Secondary validation drew from IEC 60900 standard documentation, OSHA enforcement records, VDE certification registries, and utility sector procurement specifications. Bottom-up shipment estimates triangulated against top-down market sizing derived from electrical supply house inventory data and industrial distributor sell-through reports.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for fiberglass roving imports, resin producer capacity disclosures, and certification laboratory throughput metrics. The analytical framework modeled demand across product type, material grade, application environment, and end-user procurement authority throughout the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory implementation timelines. Industry-specific forecast inputs incorporated utility sector fleet replacement cycles and telecommunications infrastructure deployment schedules.
Material uncertainties — regulatory enforcement intensity variations, raw material cost volatility in Asian resin markets, and certification standard revision timelines — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained IEC 60900 adoption momentum and OSHA inspection protocol continuity. Recalibration cycles align with material shifts in national electrical safety regulation adoptions and dielectric testing capacity expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Centerless Grinding Market
Industrial Tools
Machine Tool Touch Probe Market
Industrial Tools
Global Tool Presetters Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Plasma Arc Cutting Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
India Power Tool Market
Industrial Tools
Height Gauge Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Tool Holder Collets Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Deburring Machine Market
Industrial Tools
Die Grinders Market
Industrial Tools
Precision Components and Tooling Systems Market
Industrial Tools
Jigs and Other Tools Market
Industrial Tools
Dies, Jigs and Other Tools Market