
 Portable Lamps Market | 2026-2036
Portable Lamps Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Lamps Market Analytics
Outdoor activities procurement is broadening as a share of total portable lamps demand, pulling ahead of traditional household replacement cycles. SureFire dominates tactical and professional-grade segments through military and first-responder contracts. Nitecore specializes in high-output rechargeable designs for alpine and backcountry users. Fenix extends its position across Asia-Pacific through regional distribution partnerships and localized charging standards.
Portable lamps are self-contained illumination devices incorporating LED emitters, lithium-ion or solid-state battery packs, and reflector or diffuser optics in housings rated for IPX4 water resistance or higher; they deliver task or area lighting independent of fixed electrical infrastructure. Rechargeable lamps now command the strongest margin pools as USB-C power delivery and GaN charging circuits reduce cycle-time anxiety. Solar lamps represent the fastest-expanding product type in sub-Saharan Africa and South Asian rural electrification corridors, though absolute volumes trail rechargeable segments. LED lanterns retain maturity in North American retail channels where seasonal camping surges sustain predictable replenishment rhythms.
The EU Ecodesign Directive and REACH constrain hazardous substance thresholds in batteries and enclosures, while the FDA regulates photobiological safety for lamps marketed with medical or therapeutic claims in the United States. China's GB standards and NMPA oversight shape export certification requirements for manufacturers sourcing cells domestically. Stakeholders must monitor solid-state battery commercialization timelines and evolving right-to-repair mandates that could alter product architecture and aftermarket service economics.
Market Dynamics
Solid-state battery chemistry and the EU Ecodesign Directive are compressing product refresh cycles while elevating performance thresholds across rechargeable and solar-powered portable lamp portfolios.
Growth Catalysts
- REACH substance restrictions:The EU's hazardous substance thresholds are accelerating R&D investment in safer electrolyte formulations and enclosure materials, pulling forward next-generation product launches.
- Off-grid housing installations:German residential construction outside municipal grid coverage is generating sustained procurement of high-capacity rechargeable lanterns with USB-C power delivery.
- GaN charging circuits:Gallium nitride semiconductor adoption is cutting recharge times by half, reducing cycle-time anxiety among alpine and backcountry users who depend on rapid power restoration.
Market Restraints
- Lithium cell supply concentration:Cathode and anode material sourcing clusters in China's Jiangsu and Fujian provinces create vulnerability to export licensing shifts under NMPA oversight.
- Solid-state manufacturing yield rates:Current ceramic electrolyte production suffers from defect rates above twenty percent, constraining volume scalability before 2028.
- Photobiological safety compliance:FDA regulatory friction for lamps marketed with therapeutic claims adds six to nine months to US certification timelines.
Strategic Opportunities
- Rural electrification corridors:Sub-Saharan Africa's off-grid population represents underpenetrated demand for solar-integrated lanterns with pay-as-you-go financing.
- Right-to-repair mandates:Emerging EU legislation on product serviceability is creating first-mover advantage for modular battery architectures with swappable cell packs.
- Dual carbon goals alignment:China's MEE efficiency standards are opening procurement channels for solar-rechargeable hybrids in provincial disaster preparedness programs.
Industry Challenges
- Optical engineering talent scarcity:LED emitter thermal management and reflector design expertise concentrates in Shenzhen and Seoul, forcing Western brands into costly relocation or retention packages.
- IP fragmentation around solid-state electrolytes:Patent thickets held by Toyota, QuantumScape, and Samsung SDI complicate licensing negotiations for mid-tier manufacturers.
- GB standards harmonization delays:Divergent Chinese national standards versus IEC protocols force dual certification runs, stretching capex across parallel testing tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Lamps Market |
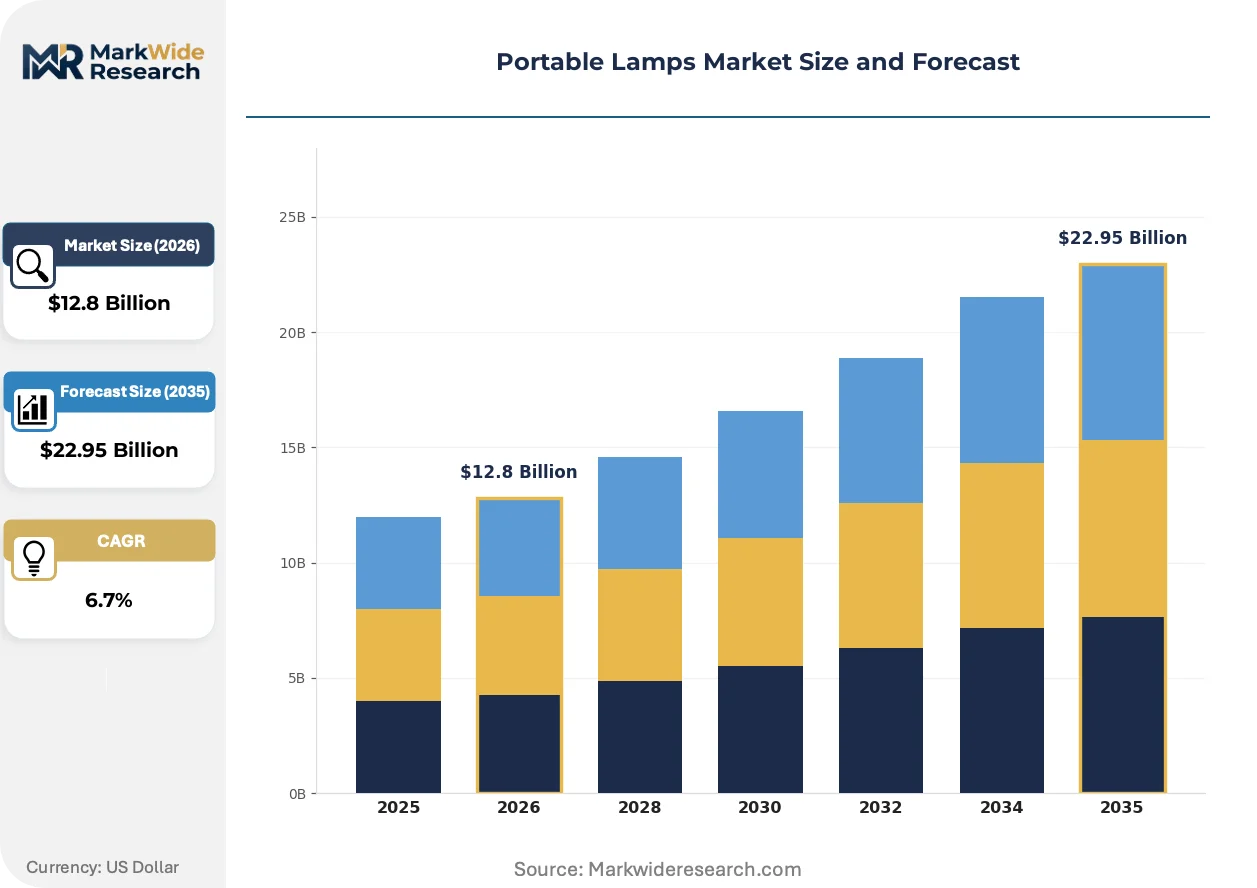
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rechargeable Lamps, Solar Lamps, LED Lanterns, Table Lamps Application: Campsites, Emergency Lighting, Home Use, Outdoor Activities Power Source: Batteries, Solar Power, AC Power, Hybrid End User: Households, Outdoor Enthusiasts, Commercial Users, Retailers |
| Companies Covered | SureFire, Nitecore, Maglite, Fenix, Olight, Energizer, Pooky, Streamlight, Ledlenser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Lamps Market Evolving Landscape
USB-C power delivery standardization and solid-state battery prototyping are compressing form factors while extending operational runtime. These shifts are reshaping procurement criteria across outdoor recreation and emergency response verticals.
GaN charging circuits are expanding into portable lamp architectures as the dominant power management technology. Alpine rescue teams and backcountry expedition operators are specifying GaN-equipped units for fifty-percent faster recharge cycles. This semiconductor shift is expanding into premium product tiers while pressuring legacy silicon-based designs into discount channels.
REACH substance thresholds are tightening enforcement across EU member states, with ECHA audits now targeting phthalate content in flexible housing materials. Manufacturers are reformulating TPU and silicone compounds to eliminate restricted plasticizers, passing certification costs through to retail pricing. The outdoor recreation segment is absorbing these adjustments fastest, as German and Austrian retailers demand full material disclosure.
Seasonal replenishment rhythms in North American camping retail are compressing further, with big-box buyers now placing firm orders eight months ahead of spring shelf resets. This inventory pre-positioning is displacing the traditional twelve-week replenishment window, forcing Asian contract manufacturers to carry finished goods risk through winter lulls. The pattern is most visible in LED lantern categories, where REI and Dick's Sporting Goods have consolidated supplier rosters to three preferred vendors.
Portable Lamps Market Segmentation
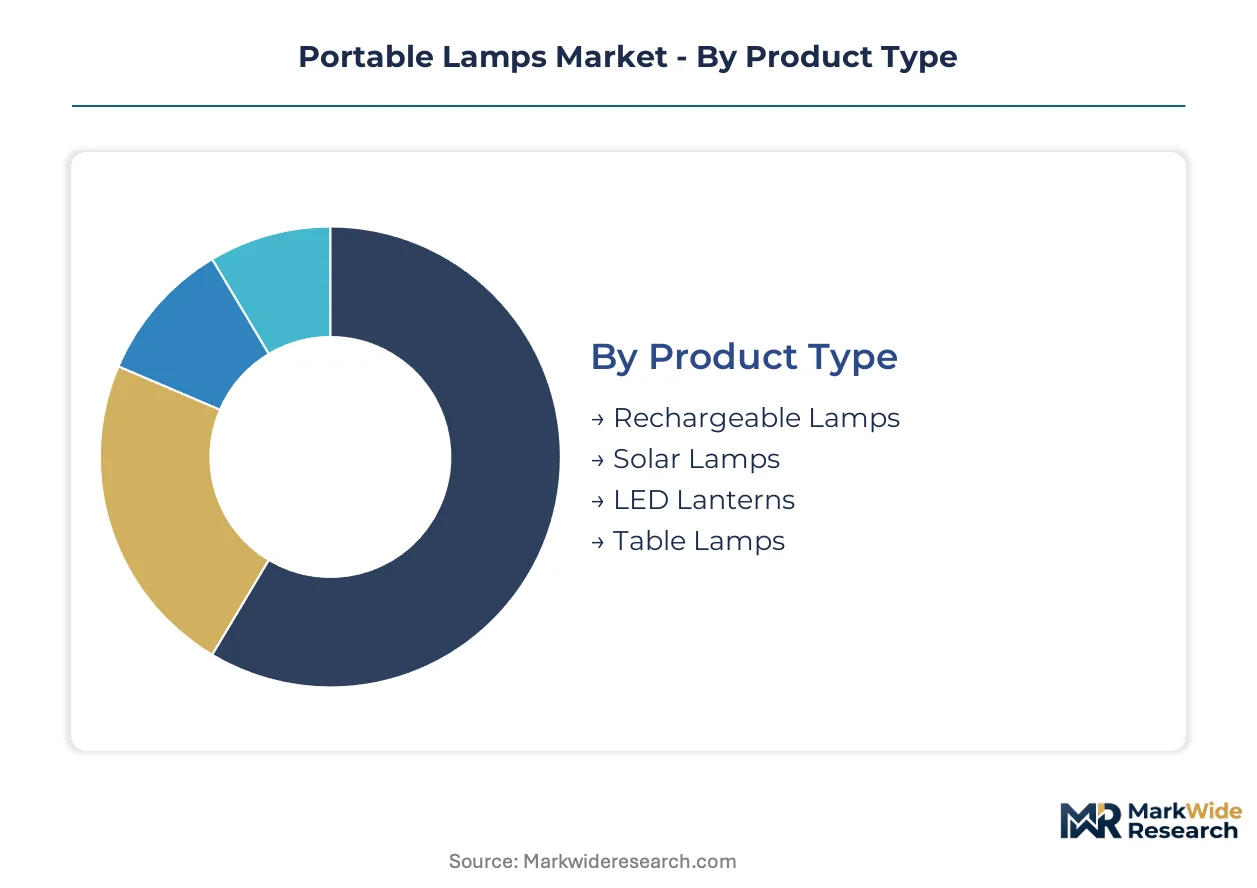
Portable lamps demand fragments across usage intensity, infrastructure access, and mobility requirements. Manufacturers configure battery chemistry, ingress protection, and optical output to match distinct procurement profiles rather than pursuing universal designs.
Product Type:
Customization intensity spans from standardized commodity lanterns to precision-engineered rechargeable systems with GaN charging circuits.
- Rechargeable Lamps:Lithium-ion or solid-state battery packs with USB-C power delivery dominate alpine and backcountry specifications. German off-grid housing installations and North American emergency preparedness agencies are specifying units with fifty-percent faster recharge cycles to reduce cycle-time anxiety.
- Solar Lamps:Photovoltaic panels integrated into weather-resistant housings serve sub-Saharan Africa and South Asian rural electrification corridors. Pay-as-you-go financing models are unlocking procurement among households outside municipal grid coverage where absolute volumes trail rechargeable segments.
- LED Lanterns:Mature designs with predictable seasonal replenishment rhythms anchor North American retail channels.
- Table Lamps:Decorative and task-oriented housings prioritize aesthetic integration over extreme durability.
Leading the category by volume: LED Lanterns. Growing fastest: Solar Lamps.
Application:
Cost tiers separate professional-grade emergency specifications from discretionary recreational purchases.
- Campsites:Area lighting with IPX4 water resistance or higher addresses seasonal outdoor recreation surges. REI and Dick's Sporting Goods have consolidated supplier rosters to three preferred vendors, compressing inventory pre-positioning to eight months ahead of spring shelf resets.
- Emergency Lighting:Sustained output specifications for first-responder and disaster preparedness agencies require military-grade durability. FDA photobiological safety compliance adds six to nine months to US certification timelines for therapeutic claim variants.
- Home Use:Residential replacement cycles concentrate in established markets with existing electrical infrastructure.
- Outdoor Activities:Alpine rescue teams and expedition operators specify rapid-recharge capabilities for mission-critical illumination.
Emergency Lighting commands premium pricing. Outdoor Activities shows steepest expansion trajectory among discretionary segments.
Power Source:
Supply concentration around lithium cell manufacturing in China's Jiangsu and Fujian provinces shapes sourcing strategies.
- Batteries:Lithium-ion cells with solid-state chemistry prototyping dominate rechargeable architectures. NMPA oversight of cathode and anode material export licensing creates vulnerability to supply disruption.
- Solar Power:Integrated photovoltaic generation targets off-grid populations with minimal infrastructure investment. China's MEE efficiency standards are opening provincial disaster preparedness procurement channels for solar-rechargeable hybrids.
- AC Power:Tethered operation limits mobility to fixed installation contexts.
- Hybrid:Dual-source flexibility commands design complexity premiums for specialized applications.
Batteries lead absolute shipments. Solar Power gains share fastest in emerging market electrification.
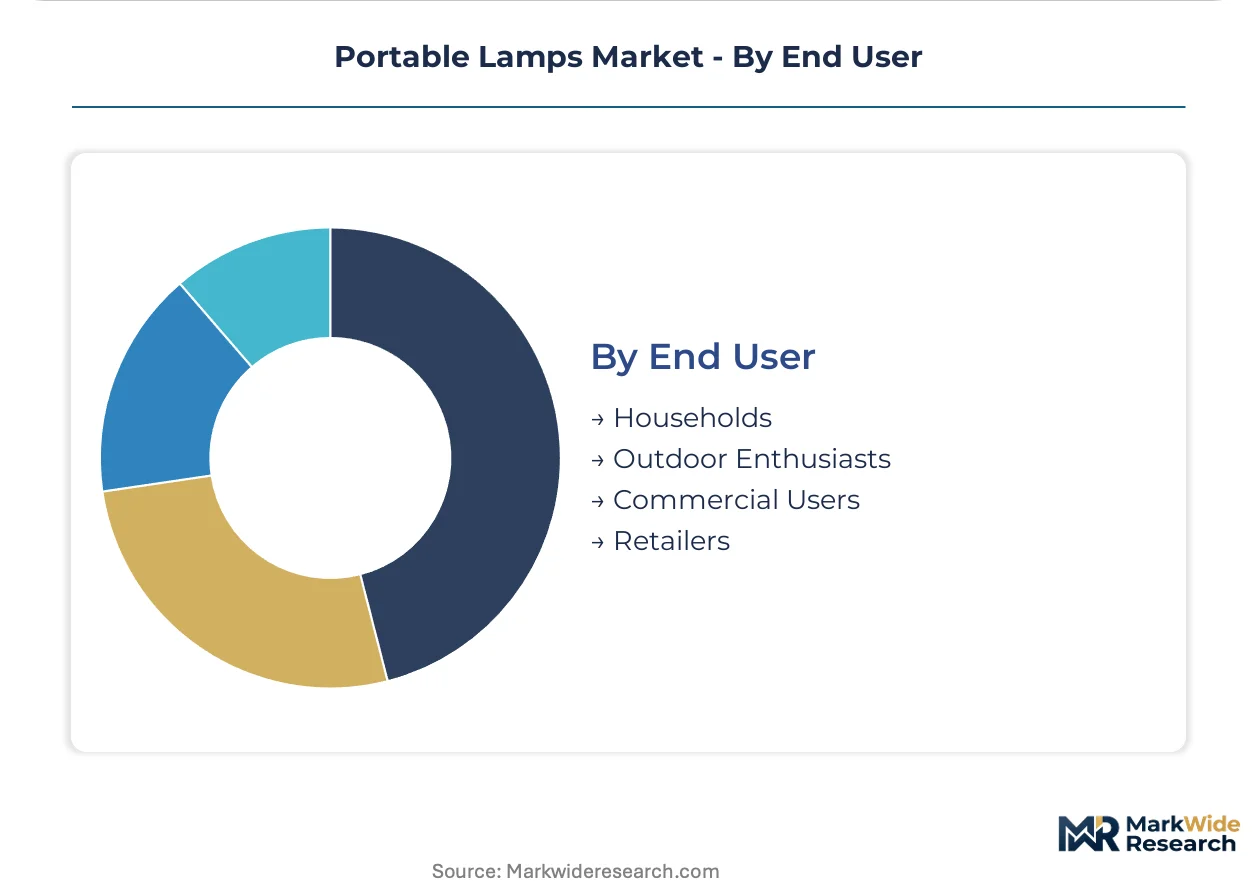
End User:
Customer type determines distribution channel configuration and serviceability requirements.
- Households:Mass-market procurement through retail and e-commerce channels emphasizes price accessibility. EU right-to-repair mandates are creating first-mover advantage for modular battery architectures with swappable cell packs.
- Outdoor Enthusiasts:Technical specifications for weight, runtime, and recharge speed drive premium willingness-to-pay. German and Austrian retailers now demand full material disclosure under tightening REACH enforcement.
- Commercial Users:Volume procurement with standardized performance metrics favors established supplier relationships.
- Retailers:Channel intermediaries consolidate vendor rosters to manage inventory risk through seasonal demand fluctuations.
Households generate largest absolute demand. Outdoor Enthusiasts deliver highest margin contribution per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's special economic zone status concentrates contract manufacturing for portable illumination, drawing component suppliers and optical engineering talent into southern China's Pearl River Delta corridor.
United States
Outdoor recreation procurement from REI and Dick's Sporting Goods drives seasonal demand concentration, with firm orders placed eight months ahead of spring shelf resets. FDA photobiological safety compliance adds six to nine months to certification timelines for therapeutic claim variants. Manufacturing specification work concentrates in California's Bay Area, where GaN semiconductor design firms partner with lamp assemblers.
Germany
Off-grid housing installations outside municipal grid coverage sustain demand for high-capacity rechargeable lanterns with USB-C power delivery. ECHA audits under REACH enforcement now target phthalate content in flexible housing materials, forcing TPU and silicone reformulation. Bavaria's camping equipment distributors demand full material disclosure ahead of Austrian and Swiss retail placement.
China
Domestic procurement channels for solar-rechargeable hybrids are opening under MEE efficiency standards in provincial disaster preparedness programs. NMPA oversight of cathode and anode material export licensing from Jiangsu and Fujian provinces creates supply vulnerability. Shenzhen and Seoul retain concentrated LED emitter thermal management expertise, forcing Western brands into costly retention packages.
Japan
Alpine rescue teams and expedition operators specify rapid-recharge capabilities for mission-critical illumination in backcountry contexts. METI efficiency standards shape domestic product specifications and influence export certification requirements for regional markets. Nagoya's precision optics cluster supplies reflector components to premium-tier portable lamp manufacturers.
India
Rural electrification corridors represent underpenetrated demand for solar-integrated lanterns with pay-as-you-go financing models among off-grid households. BIS certification requirements for lithium-ion cell integration create compliance barriers for imported assemblies. Tamil Nadu's electronics manufacturing zone hosts contract assemblers serving sub-Saharan African export markets.
Portable Lamps Market Competitive Landscape
Top-tier vendors anchor military and first-responder contracts, while mid-tier specialists pursue alpine and backcountry positioning. The market structure fragments across three strategic tiers: tactical-grade suppliers with defense relationships, outdoor recreation specialists with technical distribution, and mass-market brands with retail consolidation. Two dominant competitive moves are emerging: strategic partnerships with GaN semiconductor designers for charging circuit integration, and portfolio diversification into solar-rechargeable hybrids for emerging market electrification.
Within the tactical-grade tier, SureFire and Streamlight occupy positions anchored by military and first-responder procurement relationships. Nitecore exemplifies the outdoor recreation specialist archetype, sitting within technical distribution channels serving alpine and backcountry users. Fenix represents the Asia-Pacific expansion vector through regional distribution partnerships.
| Leading Market Players |
|---|
| SureFire |
| Nitecore |
| Maglite |
| Fenix |
| Olight |
| Energizer |
| Pooky |
| Streamlight |
| Ledlenser |
| Others |
Value Network & Pricing Analysis
Captive integration into Shenzhen-based contract manufacturing anchors both component sourcing leverage and pricing power for Western brands, compressing margin pools for non-integrated competitors while elevating procurement costs for those dependent on third-party assembly.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with REI and Dick's Sporting Goods paying elevated rates for eight-month pre-positioned inventory versus spot-market procurement. Three-tier pricing structure across premium, standard, and economy levels separates GaN-equipped rapid-recharge units from legacy silicon designs and commodity solar lanterns. Cost compression in economy tiers is intensifying because Chinese contract manufacturers absorb finished goods risk through winter lulls. Emergency preparedness agencies show least price sensitivity, while mass-market households drive hardest bargain.
Supply Chain Analysis
Returns and refurbishment flows remain underdeveloped, with defective solid-state ceramic electrolyte cells exceeding twenty percent yield loss and lacking established reclamation pathways. Component sourcing draws from China's Jiangsu and Fujian provinces for cathode materials, South Korea for separator films, and Japan for precision optics. Single-source vulnerability concentrates in NMPA-licensed anode material export approvals. Distribution runs through technical outdoor retailers in Germany and Austria, big-box sporting goods in the United States, and pay-as-you-go financiers in sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance thresholds and ECHA audit enforcement erect a cost-of-compliance barrier that favors incumbents with reformulated TPU and silicone compounds, screening out undercapitalized entrants lacking material science capabilities.
For Market Incumbents: Anchor military and first-responder contract relationships through FDA photobiological safety certification investment, insulating against emerging solar-rechargeable hybrid entrants. Deepen backward integration into GaN semiconductor design partnerships to defend rapid-recharge specification advantages.
For New Entrants and Emerging Players: Begin with pay-as-you-go financing models in sub-Saharan African rural electrification corridors, the most penetrable white-space where absolute volumes trail rechargeable segments. Pursue modular battery architectures with swappable cell packs to exploit emerging EU right-to-repair mandates.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by outdoor recreation conglomerates seeking technical distribution channels. Five-to-ten year viability hinges on solid-state battery commercialization timelines. Monitor ceramic electrolyte manufacturing yield improvements as inflection indicator for volume scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Charging Circuit Integration | Partnerships with semiconductor designers halve recharge cycles for alpine rescue specifications. |
| Solar-Rechargeable Hybrid Development | China's MEE efficiency standards open provincial disaster preparedness procurement channels. |
| Modular Battery Architecture Launch | Swappable cell packs align with EU right-to-repair mandates creating first-mover advantage. |
| REACH Compliance Certification | ECHA audit readiness screens competitors lacking reformulated housing material capabilities. |
| Pay-as-you-go Financing Platform | Rural electrification corridors in sub-Saharan Africa unlock underpenetrated household demand. |
Research Methodology
Independent corroboration across primary interviews with outdoor equipment procurement officers, GaN semiconductor design engineers, and ECHA regulatory compliance specialists underwrites the qualitative findings, supplemented by secondary validation through customs records, REI supplier disclosure filings, and NMPA export licensing databases. Bottom-up segment sizing triangulates against top-down market reconstruction.
Rate-of-change decomposition separates volume growth from pricing trajectory across the projection horizon, modeling product type, application intensity, power source architecture, and end-user procurement behavior dimensions. CAGRs derive from segment-level run-rate extrapolation tempered by solid-state battery yield improvement curves and seasonal replenishment rhythm compression.
Underlying measurement precision varies by segment; rechargeable lamp specifications carry tighter precision than solar lantern rural electrification estimates. Forecasts incorporate assumptions around NMPA licensing continuity and REACH enforcement intensity. Practitioners should monitor ceramic electrolyte defect rate announcements and EU right-to-repair legislative passage for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Architectural Lighting Market
Lighting
Indicator Lights Market
Lighting
Display Light Control Film Market
Lighting
Human Centric Lighting Market
Lighting
Vintage Bulb Market
Lighting
Photography Light Box Market
Lighting
Battery Operated Lights Market
Lighting
Smart Industrial Illumination Market
Lighting
Gesture Control Light Market
Lighting
Ultraviolet Lamps Market
Lighting
Global Lamps Market
Lighting
Global Commercial Lighting Market
Lighting
Residential Lighting Fixtures Market
Lighting
Lighting Control Components Market
Lighting
Intelligent Lighting Market
Lighting
High-End Lighting Market