
 India Power Tool Market | 2026-2036
India Power Tool Market Size, Share, and Industry Trends Forecast 2026-2036
India Power Tool Market Outlook
Tool-as-a-service maintenance contracts is recalibrating how commercial buyers evaluate total cost of ownership in the India power tool sector. Bosch Limited leverages its captive service network across industrial corridors to lock in fleet-management accounts. Stanley Black & Decker India Pvt. Ltd. sustains brand pull among mid-tier contractors through localized spare-parts availability. Makita Power Tools India Pvt. Ltd. anchors cordless platform loyalty with battery interoperability across its professional-grade lineup.
Power tools encompass motorized handheld and stationary devices engineered to deliver rotational or percussive force for cutting, drilling, grinding, or fastening operations, typically rated between 12V and 36V for cordless variants and up to 2,400W for corded industrial units. Their primary commercial purpose is to compress task completion time and reduce manual labor intensity across fabrication and assembly workflows. Cordless power source configurations now command the fastest expansion trajectory as lithium-ion energy density improvements extend runtime per charge cycle. Construction end users represent the deepest margin pool, though DIY segments through online distribution channels are narrowing the volume gap as e-commerce penetration deepens in Tier-2 and Tier-3 cities.
BIS electrical safety standards, CDSCO device-quality frameworks for medical-adjacent tooling, and state-level factory licensing under the CEA shape product compliance burdens and channel access for imported and domestically manufactured equipment alike. The PLI scheme for advanced manufacturing is inducing capacity relocation decisions among multinational suppliers evaluating local assembly versus fully-built-unit imports. Stakeholders must monitor how BIS certification timelines and state EV infrastructure buildouts alter cordless platform deployment economics in industrial hubs.
Market Dynamics
Brushless motor technology is compressing replacement cycles across industrial corridors as contractors in Maharashtra and Gujarat recalibrate equipment procurement around runtime efficiency rather than upfront cost. The shift from brushed to brushless architectures redefines supplier relationships and service contract structures.
Growth Catalysts
- PLI scheme for advanced manufacturing:The production-linked incentive scheme is inducing multinational suppliers to relocate assembly capacity from fully-built-unit imports to domestic manufacturing, reducing landed cost structures for professional-grade equipment.
- Automotive manufacturing clusters:Dense OEM and tier-1 supplier concentrations in Tamil Nadu and Karnataka generate concentrated demand for precision fastening and material removal tools, anchoring replacement revenue pools.
- Lithium-ion energy density improvements:Extended runtime per charge cycle is enabling cordless platforms to displace pneumatic and corded alternatives in high-torque applications previously resistant to battery power.
Market Restraints
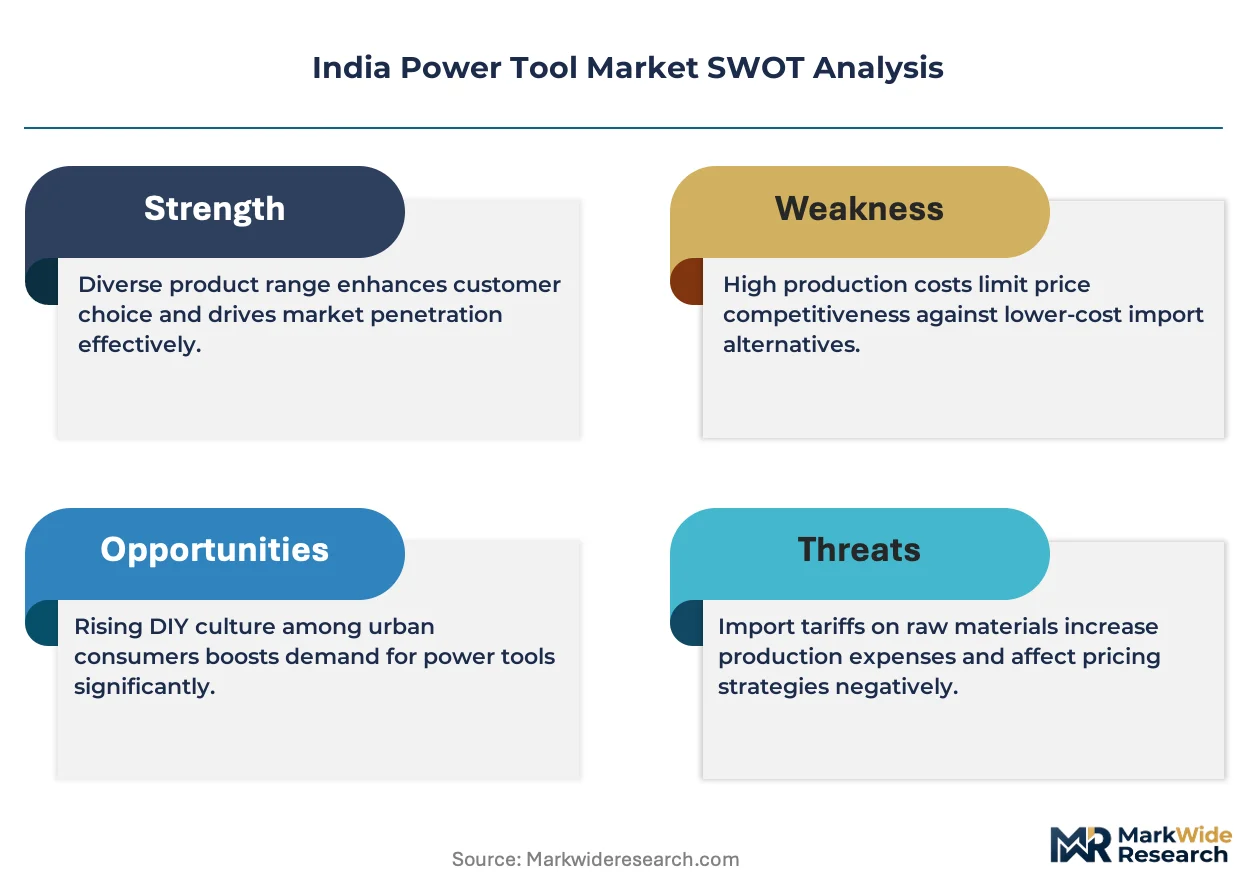
- BIS certification timelines:Electrical safety testing protocols under the Bureau of Indian Standards create 4-6 month approval windows that delay new product introductions and compress selling seasons for seasonal contractors.
- Import concentration for battery cells:Domestic lithium-ion cell manufacturing remains nascent, leaving assemblers exposed to East Asian supply concentration and currency volatility in raw material procurement.
- Pneumatic tool installed base:Legacy compressed-air infrastructure in established fabrication shops creates switching friction that slows cordless adoption despite total-cost advantages.
Strategic Opportunities
- Tier-2 and Tier-3 city e-commerce penetration:DIY segments through online distribution channels are narrowing the volume gap with professional users as last-mile logistics deepen reach beyond metropolitan hubs.
- Tool-as-a-service contracts:Fleet-management maintenance agreements recalibrate commercial buyer evaluation criteria from capital expenditure to uptime guarantees, locking in multi-year supplier relationships.
- CEA state-level factory licensing harmonization:Streamlined electrical installation approvals under the Central Electricity Authority reduce site commissioning friction for industrial cordless charging infrastructure.
Industry Challenges
- Brushless motor repair technician scarcity:Electronic speed control diagnostics and Hall sensor replacement require skill sets concentrated in authorized service centers, extending downtime for independent contractors outside metro corridors.
- Battery platform interoperability:Proprietary cell formats and communication protocols across supplier ecosystems fragment fleet standardization, complicating procurement for multi-brand toolrooms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Power Tool Market |
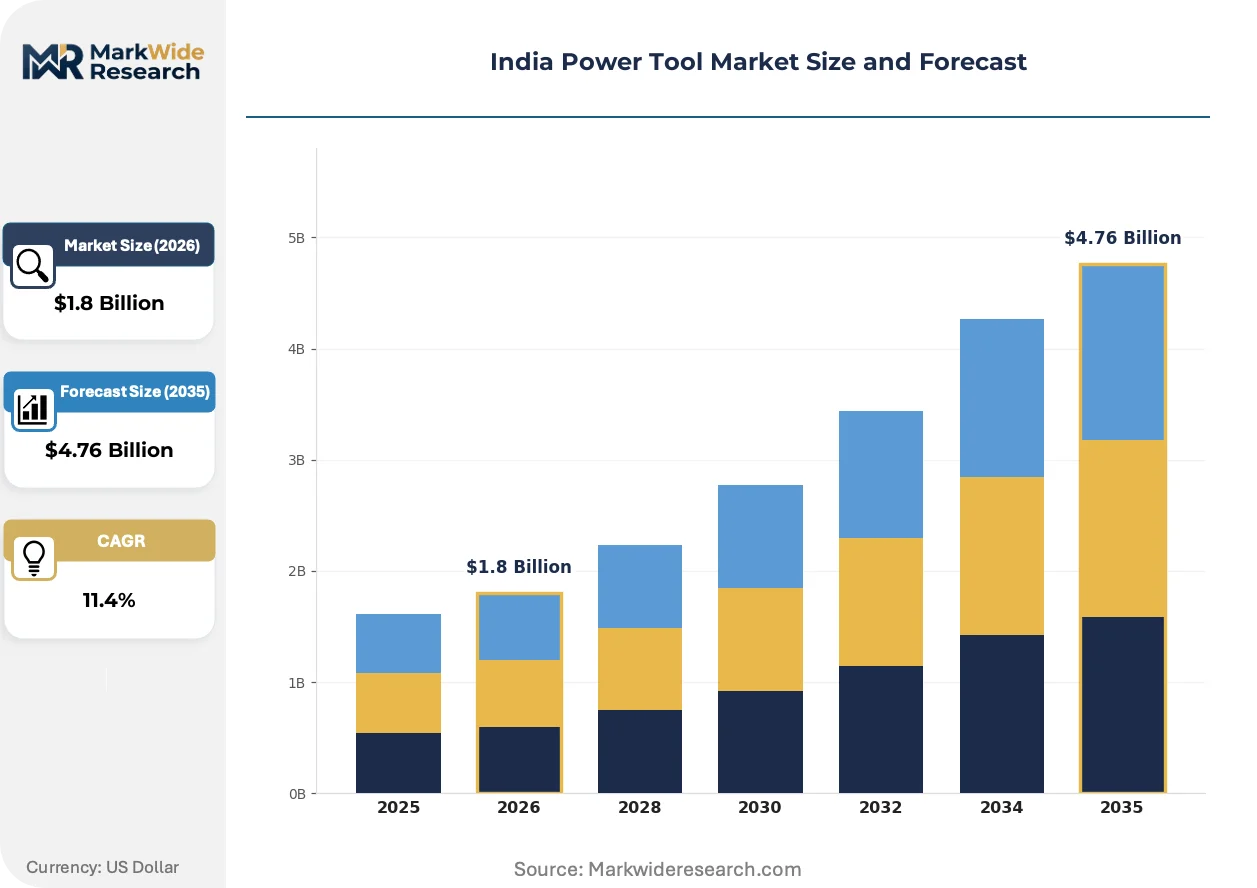
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tool Type: Drills, Saws, Grinders, Sanders Power Source: Corded, Cordless, Pneumatic, Hydraulic End User: Construction, Automotive, Manufacturing, DIY Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Bosch Limited, Stanley Black & Decker India Pvt. Ltd., Makita Power Tools India Pvt. Ltd., Hilti India Pvt. Ltd., Hitachi Koki India Pvt. Ltd., Atlas Copco (India) Ltd., FEIN Power Tools India Pvt. Ltd., Kulkarni Power Tools Ltd. (KPT), Eastman Cast & Forge Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Power Tool Market Strategic Shifts
Connected tool ecosystems and predictive maintenance algorithms are redefining how commercial buyers evaluate equipment lifecycle value. The convergence of hardware digitization with service unbundling creates new monetization architectures.
Brushless motor technology is converging with integrated torque sensors and Bluetooth-enabled performance logging. Automotive assembly plants in Chennai and Pune are adopting these platforms for traceable fastening operations. The technology is converging with quality assurance protocols, compressing the gap between power tool output and Industry 4.0 data requirements.
BIS electrical safety standards and CDSCO device-quality frameworks for medical-adjacent tooling are tightening compliance documentation requirements. Importers now face batch testing obligations that extend lead times for new model introductions. Professional-grade cordless platforms with higher voltage ratings encounter the most scrutiny, pushing suppliers toward preemptive certification investments.
Commercial procurement is consolidating around fleet-management contracts that unbundle hardware ownership from maintenance responsibility. Mid-tier contractors in Gujarat are shifting from spot purchases to multi-year service agreements with guaranteed uptime clauses. This pattern is most visible in western India, where infrastructure project density supports predictable utilization rates that justify subscription economics.
India Power Tool Market Segmentation
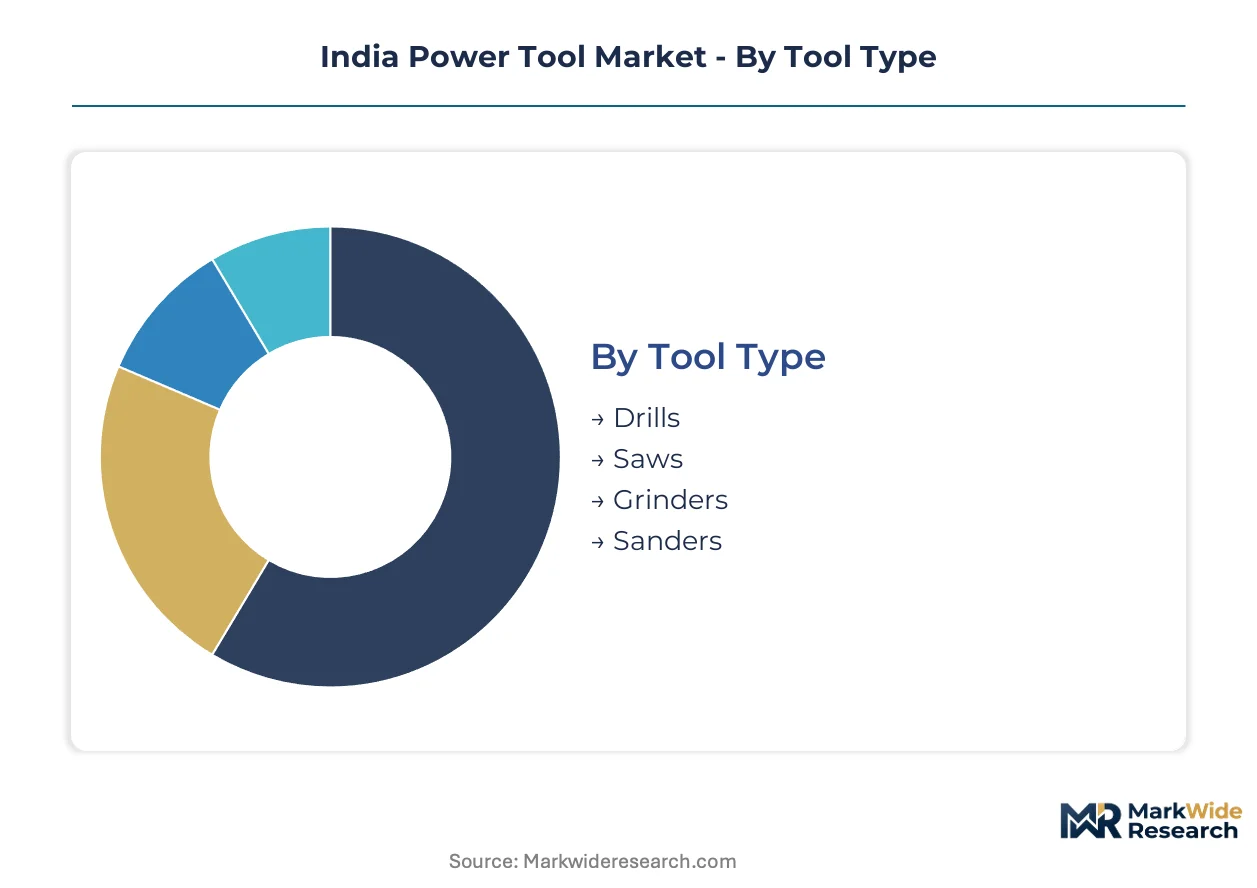
Equipment procurement patterns in India diverge sharply across contractor tiers and state-level infrastructure cycles. Segmentation reveals how brushless motor adoption and cordless platform economics reshape replacement priorities in Maharashtra and Gujarat industrial corridors.
Tool Type:
Upgrade cycles accelerate where runtime efficiency gains justify premature replacement of functional equipment.
- Drills:Rotary and percussive variants rated 12V to 36V dominate residential and light commercial fastening. Demand concentrates in Pune and Ahmedabad construction clusters where multi-speed brushless models displace brushed legacy units for concrete and masonry work.
- Saws:Circular, reciprocating, and miter configurations span corded 1,800W units and cordless 18V-54V platforms. Automotive trim shops in Chennai and Gurgaon drive thin-kerf blade adoption for aluminum and composite cutting with chip extraction integration.
- Grinders:Angle and die grinder formats serve metal fabrication and weld preparation.
- Sanders:Orbital, belt, and detail variants target surface finishing operations.
Drills sit at the top of the volume ranking, with saws climbing the fastest as cordless blade speed and battery capacity close the performance gap with corded alternatives.
Power Source:
Total cost of ownership calculations now weight charging infrastructure availability against pneumatic compressor maintenance.
- Corded:Continuous-duty units rated 800W to 2,400W sustain high-torque grinding and cutting in fixed fabrication stations. Tamil Nadu and Karnataka automotive plants retain corded platforms for spindle consistency in precision material removal.
- Cordless:Lithium-ion platforms at 12V, 18V, and 36V ratings enable site mobility without generator dependency. Maharashtra residential contractors prioritize these for high-rise electrical and plumbing rough-in work where outlet access is intermittent.
- Pneumatic:Compressed-air systems persist in legacy shipbuilding and heavy equipment repair yards.
- Hydraulic:Underwater and explosion-rated applications in offshore and mining sectors.
Cordless platforms command the steepest expansion trajectory, while corded units retain revenue density in established manufacturing installations.
End User:
Margin structures separate fleet-scale procurement from spot purchasing across contractor tiers.
- Construction:General and specialty contractors drive professional-grade volume through multi-tool platform standardization. Gujarat infrastructure project density supports tool-as-a-service contracts with uptime guarantees replacing capital expenditure models.
- Automotive:OEM and tier-1 supplier toolrooms demand traceable torque output and Bluetooth-enabled quality logging. Pune and Chennai assembly plants specify brushless fastening platforms for ISO-compliant audit trails.
- Manufacturing:Metal fabrication and industrial maintenance operations.
- DIY:Home improvement enthusiasts through e-commerce channels in Tier-2 and Tier-3 cities.
Construction anchors absolute volume, with DIY gaining share fastest as last-mile logistics penetrate beyond metropolitan hubs.
Distribution Channel:
Channel selection correlates with buyer technical sophistication and post-sale service requirements.
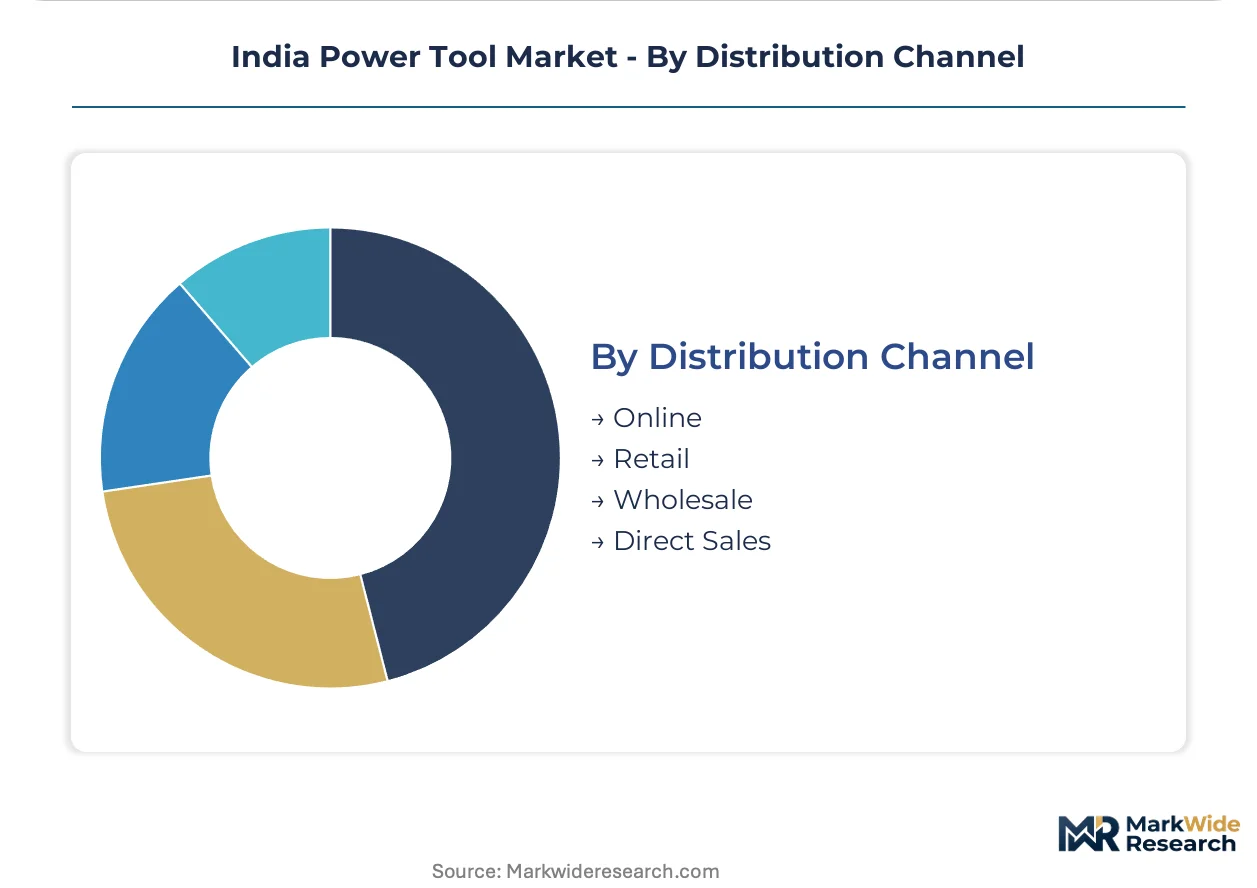
- Online:E-commerce platforms capture DIY and small contractor segments through price transparency and battery platform comparison tools. Tier-2 city penetration deepens as regional warehousing cuts delivery windows.
- Retail:Authorized dealer networks provide hands-on evaluation and immediate spare parts availability. Maharashtra and Gujarat industrial corridors sustain these for mid-tier contractors prioritizing localized service.
- Wholesale:Bulk procurement for large fleet operators and rental companies.
- Direct Sales:Factory-level agreements for automotive OEM toolroom specifications.
Retail maintains the deepest penetration in western India, with online channels expanding most quickly into southern and central state secondary cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western India generates deeper equipment procurement volumes than southern corridors, though both regions anchor distinct demand profiles shaped by infrastructure investment cycles and industrial cluster density.
Maharashtra
Residential contractors in Mumbai and Pune drive cordless platform adoption for high-rise electrical rough-in work where generator access is restricted. The state electrical inspectorate enforces CEA licensing standards for industrial charging infrastructure deployment. Nashik and Aurangabad automotive toolrooms specify brushless fastening systems for ISO-compliant assembly traceability.
Gujarat
Infrastructure project density in Ahmedabad and Surat supports tool-as-a-service contract proliferation with uptime guarantee clauses replacing spot purchasing. DGFT import documentation requirements shape landed cost structures for battery cell procurement. Vadodara fabrication clusters retain corded grinder installations for continuous-duty weld preparation in metalworking operations.
Tamil Nadu
Chennai automotive OEM and tier-1 supplier concentrations generate concentrated demand for precision torque tools with Bluetooth-enabled quality logging. BIS electrical safety certification timelines compress selling seasons for seasonal contractors in Coimbatore industrial zones. Hosur precision engineering parks specify thin-kerf saw platforms for aluminum and composite material processing.
Karnataka
Bengaluru aerospace and electronics manufacturing clusters drive demand for compact cordless platforms in cleanroom-adjacent assembly environments. The state factory licensing framework under CEA guidelines streamlines electrical installation approvals for charging infrastructure. Mysuru and Tumkur metal fabrication yards balance pneumatic legacy systems with cordless adoption for site mobility.
Haryana
Gurgaon and Faridabad automotive trim shops anchor thin-kerf blade demand for aluminum cutting with integrated chip extraction. CDSCO device-quality frameworks apply to medical-adjacent tooling procurement in Delhi-NCR satellite manufacturing. Manesar supplier parks specify traceable fastening platforms for export-oriented assembly compliance.
India Power Tool Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with multinational assemblers commanding premium-tier procurement through captive service networks while domestic fabricators capture mid-market volume through price-competitive cordless platforms. The supplier base arranges into three strategic archetypes: integrated multinationals with India-specific assembly operations, licensed distributors of foreign-origin equipment, and indigenous manufacturers with regional spare-parts networks. Capacity relocation decisions under the PLI scheme and battery platform standardization efforts constitute the dominant competitive vectors reshaping procurement relationships.
Among multinational assemblers with India-specific operations, Bosch Limited, Stanley Black & Decker India Pvt. Ltd., and Makita Power Tools India Pvt. Ltd. occupy positions exemplifying distinct service-network strategies. Bosch Limited anchors fleet-management accounts through industrial corridor service density. Stanley Black & Decker India Pvt. Ltd. sits within the mid-tier contractor segment where localized spare-parts availability drives repeat procurement. Makita Power Tools India Pvt. Ltd. represents battery interoperability approaches that lock in platform loyalty across professional-grade lineups.
| Leading Market Players |
|---|
| Bosch Limited |
| Stanley Black & Decker India Pvt. Ltd. |
| Makita Power Tools India Pvt. Ltd. |
| Hilti India Pvt. Ltd. |
| Hitachi Koki India Pvt. Ltd. |
| Atlas Copco (India) Ltd. |
| FEIN Power Tools India Pvt. Ltd. |
| Kulkarni Power Tools Ltd. (KPT) |
| Eastman Cast & Forge Ltd. |
| Others |
Value Chain & Pricing Dynamics
Lithium-ion battery cell imports from China, South Korea, and Japan flow through DGFT documentation checkpoints into landed cost calculations that stratify cordless platform pricing across premium brushless and economy brushed tiers. Maharashtra and Gujarat contractors absorb these upstream cost structures through multi-year fleet contracts that amortize hardware premiums against runtime efficiency gains.
Pricing Analysis
Capacity additions in Tamil Nadu and Karnataka automotive corridors are reshaping price floors for precision fastening platforms as domestic assembly under PLI incentives compresses import duty burdens. Three-tier pricing structure across premium brushless, standard brushed, and economy contractor-grade levels separates ISO-certified automotive specifications from residential construction spot purchases. Cost compression in mid-tier cordless drills is intensifying because battery platform interoperability wars force supplier discounting. Small contractors in Tier-2 cities exhibit highest price sensitivity; automotive OEM toolrooms show lowest.
Supply Chain Analysis
Domestic-content mandates under the PLI scheme for advanced manufacturing are reshaping sourcing decisions as multinational assemblers relocate final assembly from fully-built-unit imports to India-based operations. East Asian lithium-ion cell manufacturing in China, South Korea, and Japan remains the dominant upstream anchor, with brushless motor controllers and precision bearings drawing from Taiwan and Germany. Single-source vulnerability in battery cell procurement exposes assemblers to currency volatility and logistics chokepoints at Nhava Sheva and Chennai ports. Distribution runs through authorized dealer networks in western industrial corridors, with e-commerce platforms penetrating southern Tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India power tool market functions as a regulatory compounder where BIS electrical safety certification timelines and CEA factory licensing standards accelerate replacement cycles among compliance-focused automotive and infrastructure buyers.
For Market Incumbents: Extend captive service network density across Maharashtra and Gujarat industrial corridors to lock in fleet-management accounts before battery platform standardization consolidates procurement relationships. Invest in preemptive BIS certification for higher-voltage cordless platforms to compress approval windows and capture seasonal contractor demand. Vertical integration into brushless motor controller assembly mitigates import dependency risks from East Asian semiconductor supply concentration. For New Entrants and Emerging Players: Enter via DIY e-commerce channels in Tier-2 and Tier-3 southern cities where last-mile logistics gaps and price transparency tools enable platform comparison without established dealer relationships. Target Karnataka aerospace and electronics manufacturing clusters with compact cordless platforms designed for cleanroom-adjacent assembly environments. Anchor go-to-market strategy around battery interoperability claims that reduce fleet standardization friction for multi-brand toolrooms. For Investors and Strategic Acquirers: Consolidation pressure builds where brushless motor repair technician scarcity concentrates service capability in authorized networks, creating acquisition value for regional spare-parts distributors with trained technical workforces. Long-term viability hinges on suppliers' ability to convert capital expenditure procurement to tool-as-a-service recurring revenue models. Watch CEA state-level licensing harmonization progress as inflection indicator for industrial cordless charging infrastructure deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Relocation | PLI scheme incentives compress landed costs for professional-grade cordless platforms in Tamil Nadu automotive corridors. |
| Battery Platform Standardization | Interoperability investments lock in contractor loyalty and reduce multi-brand fleet procurement friction. |
| Tool-as-a-Service Contracts | Uptime guarantee clauses replace spot purchasing among Gujarat infrastructure contractors with predictable utilization. |
| Preemptive BIS Certification | Early electrical safety testing investments compress approval timelines for seasonal selling windows. |
| Regional Service Network Expansion | Authorized technician density in Maharashtra and Gujarat anchors fleet-management account retention. |
Study Parameters
Bottom-up contractor and automotive OEM modeling reconciled against top-down lithium-ion battery import tracking forms the analytical core of this study. Primary interviews with maintenance directors at Pune and Chennai assembly plants, procurement leads at Gujarat infrastructure contractors, aftermarket service heads at Bosch and Stanley Black & Decker India, and channel partners in Maharashtra industrial corridors combined with secondary validation from BIS certification databases, DGFT import records, CEA licensing filings, and PLI scheme beneficiary disclosures. Triangulation between demand-side utilization patterns and supply-side capacity investments anchors volume and value estimates.
Historical trendline analysis of brushless motor adoption rates and cordless platform displacement patterns calibrated against infrastructure investment cycles and automotive production trajectories. Segmentation dimensions modeled include tool type, power source configuration, end-user industry, and distribution channel, with regional regulatory cluster variations across Maharashtra, Gujarat, Tamil Nadu, and Karnataka. CAGRs derived from equipment replacement cycle compression and lithium-ion energy density improvement curves. Forecast inputs incorporate BIS certification timeline distributions and CEA electrical installation approval velocity.
The model holds under stable PLI scheme incentive structures and continued lithium-ion cell import access; deviation in BIS testing protocol changes or East Asian supply disruptions would shift replacement cycle assumptions. Forecasts reflect documented assumptions about contractor procurement behavior standardization and automotive traceability requirement adoption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Dies, Jigs and Other Tools Market
Industrial Tools
Handheld DC Torque Tools Market
Industrial Tools
Tool Holder Collets Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Die Grinders Market
Industrial Tools
Height Gauge Market
Industrial Tools
Air Screwdrivers Market
Industrial Tools
Micro Welders Market
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Jigs and Other Tools Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Machine Tool Touch Probe Market
Industrial Tools
Deburring Machine Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
Precision Components and Tooling Systems Market