
 Height Gauge Market | 2026-2036
Height Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
Height Gauge Market Analytics
EU Green Deal manufacturing efficiency standards is hardening requirements for dimensional accuracy in machined components. Mitutoyo leverages its digital product portfolio to serve automotive calibration labs across East Asia. Starrett anchors its position through mechanical gauge dominance in North American education and research institutions. Hexagon Manufacturing Intelligence competes on software-integrated inspection workflows that merge height measurement with broader quality ecosystems.
A height gauge is a precision vertical measuring instrument equipped with a finely ground base, a vertical column, and a sliding carriage holding a scriber or probe, typically resolving to 0.01 mm or finer for layout and inspection tasks. Digital variants employ capacitive or inductive linear encoders to eliminate parallax error and enable direct data logging into statistical process control systems. The digital product type segment leads value generation due to higher unit prices and integration with Bluetooth-enabled data collection systems. Quality control applications sustain the largest volume share as automotive and aerospace suppliers mandate 100% dimensional verification on critical features. Manual technology remains entrenched in education budgets where capital constraints limit electronic system procurement.
ISO calibration traceability requirements enforced by national metrology institutes shape procurement specifications and replacement cycles across industrial end users. The US FDA and FAA both reference dimensional measurement protocols in device manufacturing and airframe assembly standards, while REACH compliance in Europe affects surface coating materials on gauge columns and bases. Stakeholders must monitor how NIST and equivalent national bodies revise uncertainty budgets for electronic height measurement systems.
Market Dynamics
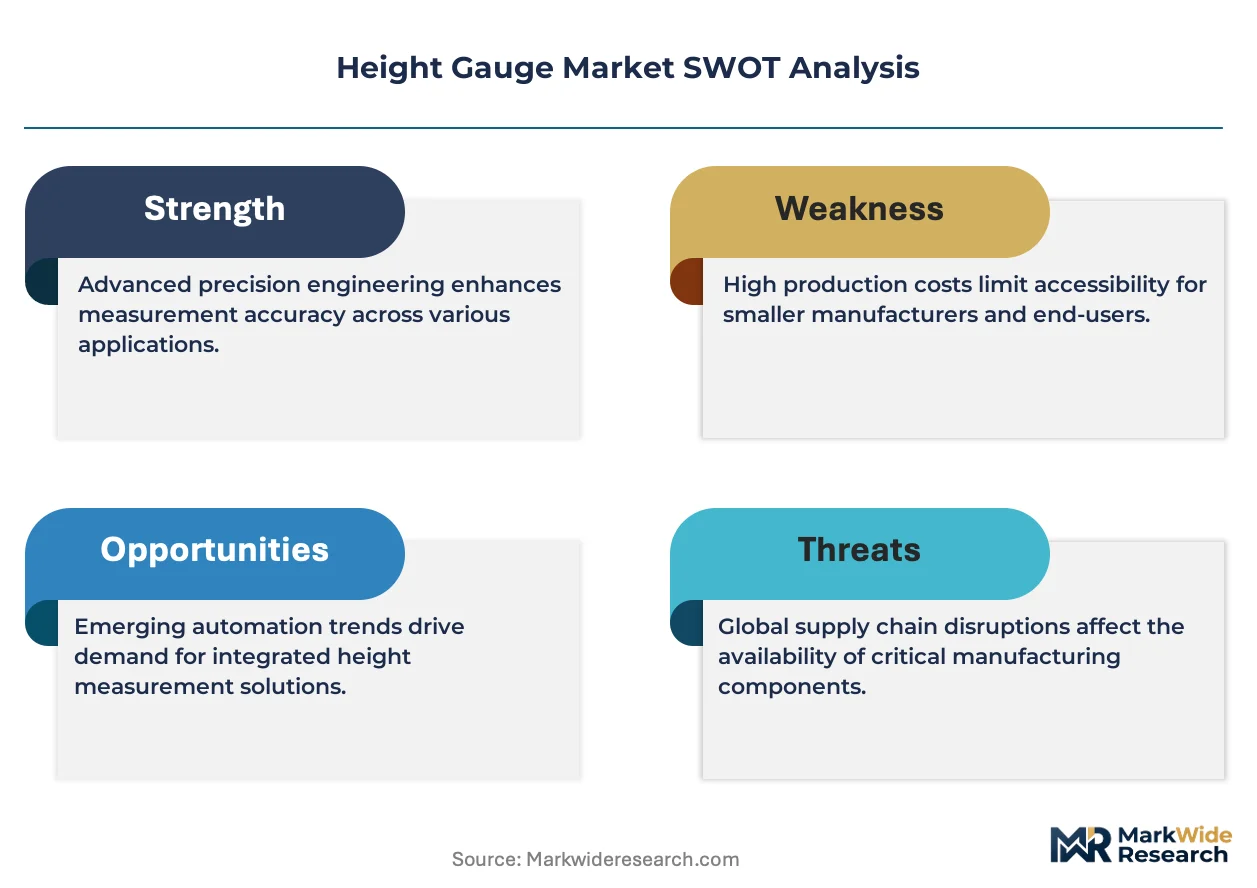
ISO 9001 quality mandates are compressing replacement cycles for precision metrology equipment as aerospace and automotive suppliers face mandatory dimensional verification protocols. This regulatory tightening is forcing capital redeployment toward digital height measurement systems with direct SPC integration.
Growth Catalysts
- EU Green Deal manufacturing standards:Hardening dimensional accuracy requirements for machined components are forcing automotive suppliers to upgrade inspection equipment. German automotive networks are expanding metrology budgets to meet these efficiency mandates.
- East Asian production clusters:Concentrated aerospace and electronics manufacturing in Japan and South Korea is driving demand for high-resolution digital height gauges with Bluetooth data logging capabilities.
- Inductive linear encoder technology:Elimination of parallax error through capacitive and inductive sensing is accelerating replacement of mechanical dial gauges in quality control laboratories.
Market Restraints
- Calibration infrastructure concentration:NIST-traceable calibration services concentrate in Germany, Japan, and the United States, creating service access barriers for secondary manufacturing regions.
- Raw material coating compliance:REACH restrictions on surface coating materials for gauge columns and bases are increasing production costs and limiting supplier flexibility across European supply chains.
- Mechanical gauge substitution persistence:Capital-constrained education budgets continue procuring manual height gauges, fragmenting demand and compressing average selling prices for digital variants in institutional channels.
Strategic Opportunities
- Indian precision manufacturing expansion:BIS quality certification requirements and PLI scheme incentives for aerospace components are creating first-time demand for ISO-calibrated height measurement systems in emerging supplier networks.
- Software-integrated inspection workflows:Convergence of height measurement data with broader quality ecosystems and statistical process control platforms is opening premium pricing tiers for connected gauge systems.
- Aftermarket calibration services:Mandatory recertification intervals enforced by national metrology institutes are generating recurring revenue streams independent of new equipment sales.
Industry Challenges
- Metrology technician scarcity:Specialized skills for operating electronic height gauges with encoder-based systems are concentrated in aging workforces across Japanese and German precision manufacturing hubs.
- Legacy system integration friction:Digital height gauges with Bluetooth connectivity face protocol incompatibility with existing shop-floor data collection infrastructure in mid-tier automotive supplier facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Height Gauge Market |
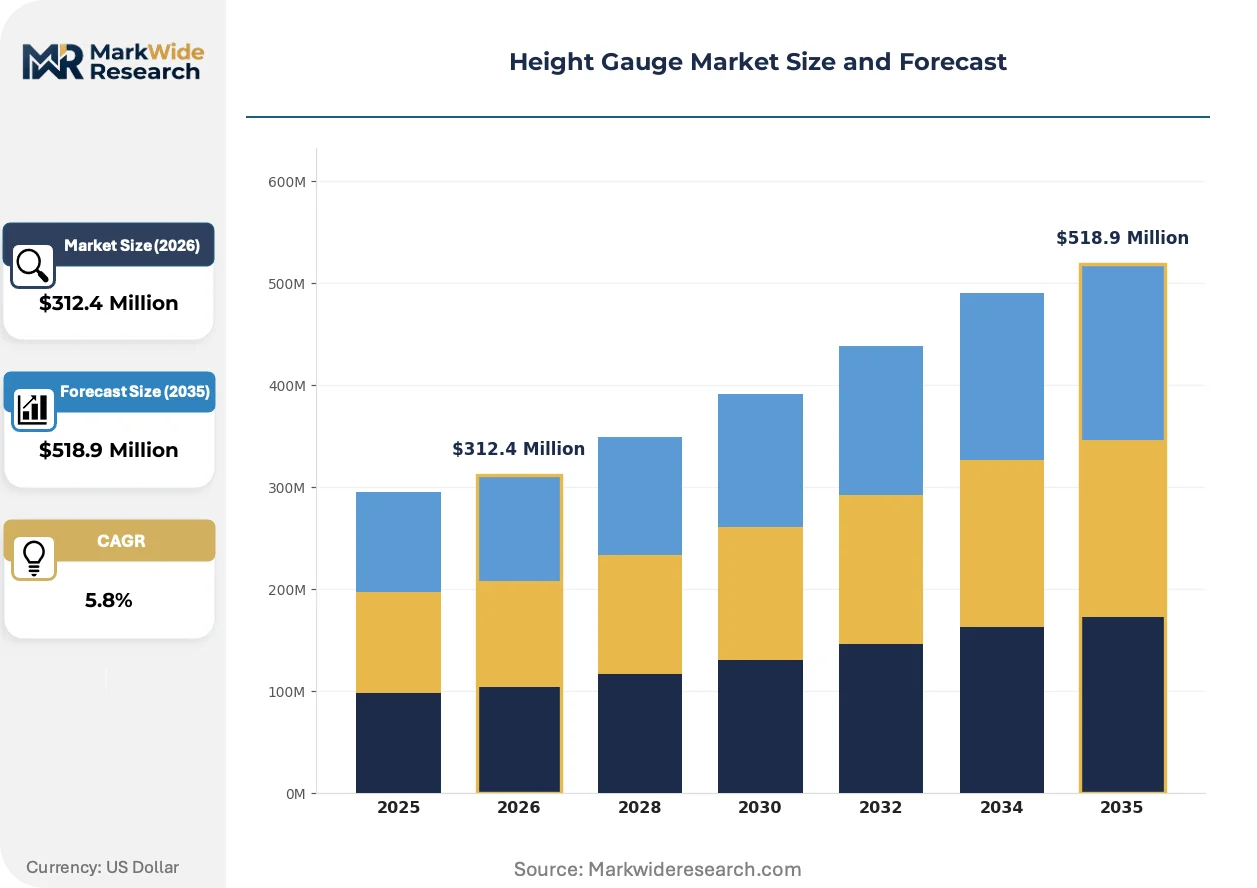
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Digital, Electronic, Bluetooth End User: Manufacturing, Automotive, Aerospace, Education Technology: Laser, Ultrasonic, Optical, Manual Application: Quality Control, Research, Calibration, Inspection |
| Companies Covered | Mitutoyo, Starrett, Brown & Sharpe, Mahr, Hexagon Manufacturing Intelligence, Renishaw, Sony Manufacturing Systems, Trimos, Wyler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Height Gauge Market Evolving Landscape
Digital measurement architectures are absorbing functionality from adjacent quality systems, compressing the boundary between standalone gauges and integrated inspection platforms. This convergence is reshaping how dimensional data flows into manufacturing execution systems.
Capacitive linear encoder technology is absorbing the position-sensing function previously handled by mechanical rack-and-pinion assemblies. Automotive calibration laboratories in Stuttgart and Toyota City are adopting these systems at replacement-cycle pace. The technology is absorbing error sources associated with operator parallax, compressing measurement uncertainty budgets for critical aerospace features.
REACH compliance enforcement by ECHA is hardening material specifications for gauge column surface treatments. Industrial consequence includes restricted supplier pools for coating chemistries and extended qualification timelines for new gauge introductions. German automotive supplier networks are responding by consolidating procurement around pre-qualified coating vendors with established SVHC documentation.
Buyer concentration among tier-one automotive and aerospace suppliers is compressing negotiation leverage for gauge manufacturers. Direct procurement relationships are displacing distributor intermediaries in high-volume calibration equipment purchasing. This pattern is most visible in Bavaria and Aichi Prefecture, where supplier consolidation has produced dedicated metrology procurement functions with technical specification authority.
Height Gauge Market Segmentation
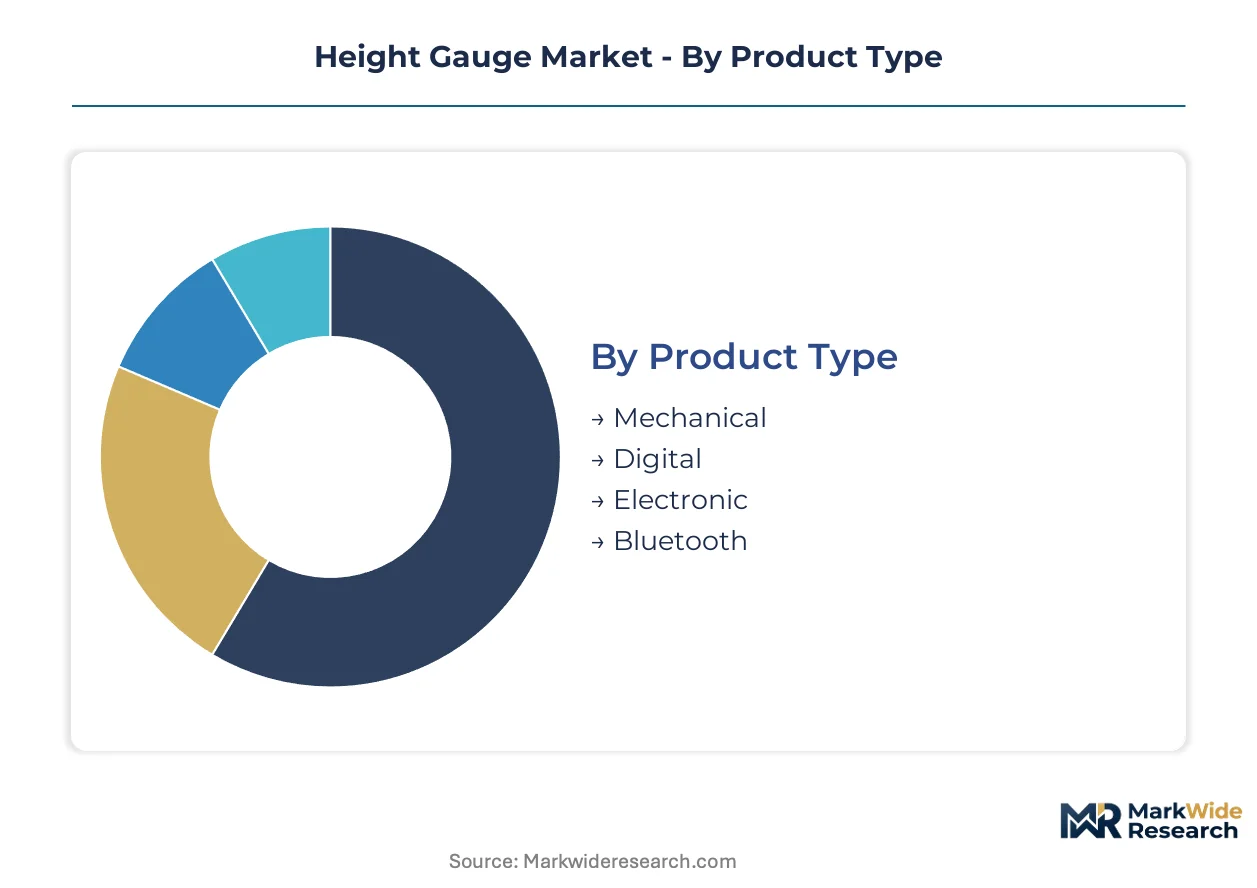
Height gauge segmentation reveals how precision measurement technology stratifies across calibration requirements, connectivity demands, and operator skill levels. Procurement patterns diverge sharply between automated quality ecosystems and capital-constrained institutional budgets.
Product Type:
Resolution specifications and data connectivity define the technology hierarchy in vertical measurement instrumentation.
- Mechanical:Rack-and-pinion assemblies with vernier or dial indicators deliver 0.02 mm resolution without power dependency. Education budgets in North American technical institutes sustain demand despite SPC incompatibility.
- Digital:Capacitive linear encoders eliminate parallax error while enabling direct RS-232 or USB data export. Automotive calibration laboratories in Stuttgart and Toyota City are replacing mechanical inventories at standard replacement cycles.
- Electronic:Microprocessor-controlled systems with temperature compensation algorithms maintain stability across shop-floor thermal variation. Aerospace suppliers in Germany specify these for airframe assembly verification protocols.
- Bluetooth:Wireless data streaming integrates with mobile SPC platforms and cloud-based quality dashboards. East Asian electronics manufacturers are specifying these for cleanroom environments where cable routing creates contamination risk.
Digital leads on scale; Bluetooth leads on momentum.
End User:
Capital deployment intensity varies fourfold across buyer categories, from production-line integration to classroom instruction.
- Manufacturing:General machining operations deploy height gauges for first-article inspection and periodic tool verification. Tier-two suppliers in India are procuring ISO-calibrated systems for BIS certification compliance.
- Automotive:Powertrain and chassis component suppliers mandate 100% dimensional verification on critical features. German automotive networks are expanding metrology budgets to meet EU Green Deal efficiency mandates.
- Aerospace:Airframe assembly and engine component manufacturing require NIST-traceable uncertainty budgets below 5 micrometers. Japanese precision manufacturers in Aichi Prefecture operate dedicated procurement functions with technical specification authority.
- Education:Vocational training programs and university engineering departments prioritize mechanical durability over electronic functionality. Capital constraints limit electronic system procurement in North American community college budgets.
Automotive commands procurement volume; aerospace commands specification stringency.
Technology:
Measurement physics determines environmental tolerance, operator skill requirements, and integration complexity with existing quality infrastructure.
- Laser:Triangulation-based non-contact systems measure soft or reflective surfaces without probe deformation risk. Research institutions in Japan deploy these for MEMS component characterization.
- Ultrasonic:Time-of-flight measurement through coupling media enables thickness-integrated height verification. Limited adoption outside specialized composite manufacturing applications.
- Optical:Vision-based edge detection automates scriber alignment for repetitive inspection sequences. Quality control laboratories in South Korea are integrating these with robotic part handling systems.
- Manual:Human-operator visual alignment with mechanical reference surfaces remains standard in apprentice training environments. REACH compliance costs for column coatings are extending replacement timelines in European education budgets.
Manual retains installed base dominance; optical gains share fastest in automated inspection cells.
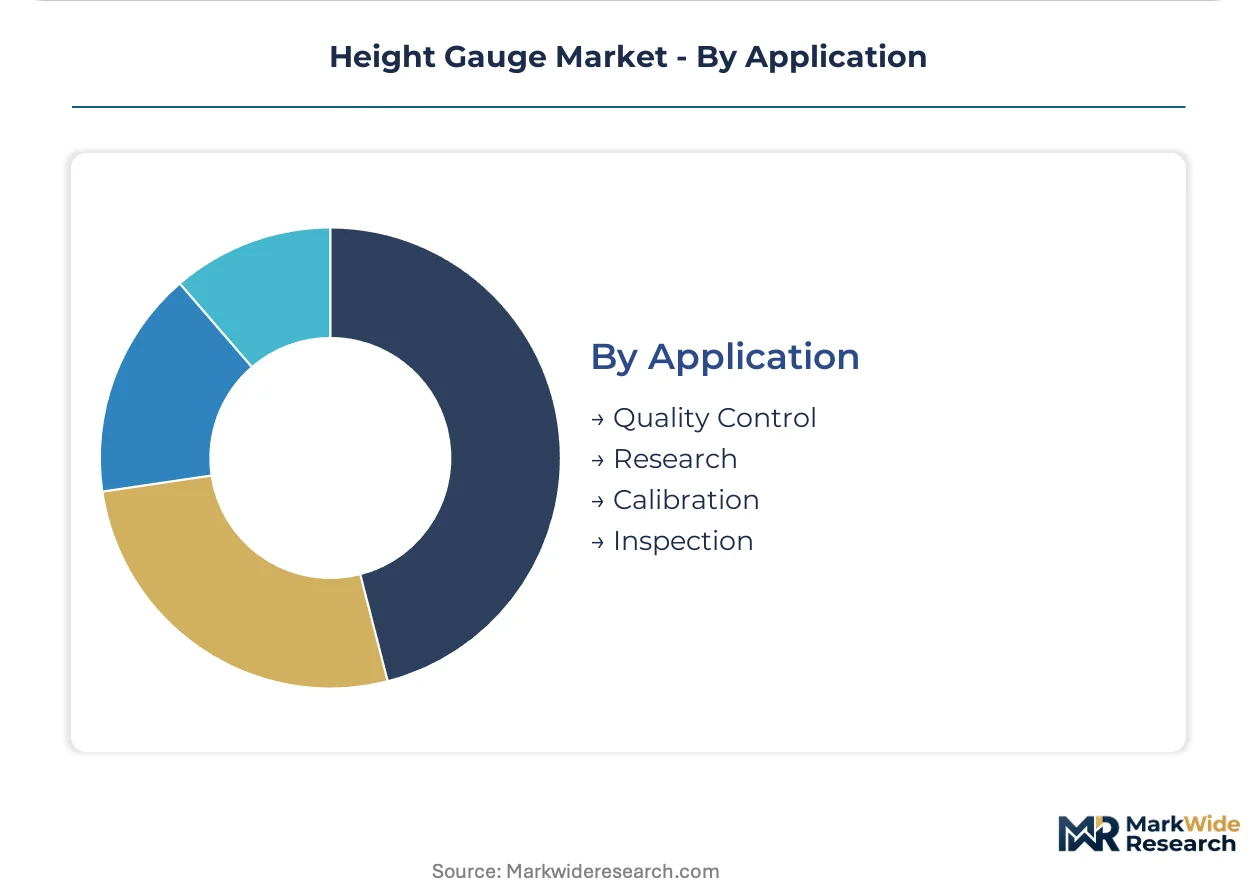
Application:
Workflow integration depth separates transactional measurement from embedded quality system architecture.
- Quality Control:Production-floor dimensional verification against engineering tolerances sustains the largest equipment volume. ISO 9001 mandates are compressing replacement cycles for digital systems with direct SPC integration.
- Research:Materials science and metrology laboratories pursue sub-micrometer uncertainty for publication-grade measurement. National metrology institutes in Germany and Japan specify inductive encoder systems for inter-laboratory comparison studies.
- Calibration:Gauge block and reference standard verification requires environmental isolation and thermal stabilization. Mandatory recertification intervals are generating recurring service revenue independent of new equipment sales.
- Inspection:Incoming material verification and final audit sampling balance throughput speed against statistical confidence. Mid-tier automotive suppliers face protocol incompatibility when integrating Bluetooth gauges with legacy shop-floor data infrastructure.
Quality Control anchors equipment volume; Calibration generates the highest service attachment rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metrology technician pools in Stuttgart, Aichi Prefecture, and Boston anchor precision measurement demand across three continents. These workforce concentrations sustain calibration laboratory networks and drive specification authority for dimensional verification equipment.
Germany
Automotive supplier networks in Bavaria and Baden-Württemberg are expanding metrology budgets to meet EU Green Deal manufacturing efficiency standards. REACH compliance enforced by ECHA restricts surface coating chemistries for gauge columns, consolidating procurement around pre-qualified vendors. Stuttgart operates dedicated metrology procurement functions with technical specification authority for tier-one powertrain suppliers.
Japan
Aerospace manufacturers in Aichi Prefecture and electronics clusters in Kansai are driving demand for high-resolution digital height gauges. METI quality certification requirements shape procurement specifications for precision manufacturing equipment. Toyota City calibration laboratories are replacing mechanical gauge inventories with encoder-based systems at standard replacement cycles.
United States
FAA-mandated dimensional verification protocols for airframe assembly are compressing replacement cycles among aerospace suppliers. NIST traceability requirements enforced by national metrology institutes shape uncertainty budgets for electronic measurement systems. Greater Boston research institutions sustain demand for sub-micrometer resolution systems in materials science applications.
India
BIS quality certification requirements and PLI scheme incentives for aerospace components are creating first-time demand for ISO-calibrated systems. The country's national metrology institute enforces mandatory recertification intervals that generate recurring service revenue. Maharashtra and Karnataka precision manufacturing clusters are procuring calibrated height measurement systems for emerging supplier networks.
South Korea
Electronics manufacturers in Gyeonggi Province are specifying Bluetooth-enabled height gauges for cleanroom environments where cable routing creates contamination risk. The national standards body enforces calibration traceability requirements that shape procurement specifications. Quality control laboratories in Seoul are integrating optical edge detection systems with robotic part handling infrastructure.
Height Gauge Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the precision metrology value chain. The vendor base stratifies between integrated measurement platform builders and standalone gauge specialists. Three archetypes dominate: Japanese precision instrument conglomerates with encoder technology depth, German metrology specialists with automotive calibration relationships, and software-integrated inspection workflow providers. Competitive dynamics center on strategic partnerships with SPC platform vendors and geographic expansion through distributor network consolidation.
Within the Japanese precision tier, Mitutoyo and Sony Manufacturing Systems exemplify encoder technology leadership. German metrology heritage is represented by Mahr and Wyler AG, both occupying positions anchored in European automotive supplier relationships. Hexagon Manufacturing Intelligence represents the software-integrated workflow archetype, bridging height measurement data with broader quality ecosystem platforms. These three groupings capture distinct procurement channels: production-line integration, calibration laboratory service, and automated inspection cell architecture.
| Leading Market Players |
|---|
| Mitutoyo |
| Starrett |
| Brown & Sharpe |
| Mahr |
| Hexagon Manufacturing Intelligence |
| Renishaw |
| Sony Manufacturing Systems |
| Trimos |
| Wyler AG |
| Others |
Value Network & Pricing Analysis
EU Green Deal manufacturing efficiency standards gate qualified supply for precision metrology equipment, restricting coating chemistry vendors to pre-qualified pools with established SVHC documentation and compressing premium-tier pricing access for buyers demanding REACH-compliant gauge columns.
Pricing Analysis
The bundled-vs-unbundled service split separates equipment-only transactions from calibration-inclusive packages. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and encoder technology tier. Cost compression in economy mechanical gauges intensifies because education budgets remain capital-constrained. Automotive calibration laboratories exhibit lowest price sensitivity due to ISO 9001 mandate compliance requirements.
Supply Chain Analysis
Dual-sourcing requirements from tier-one automotive and aerospace buyers mandate multi-supplier qualification for gauge column coatings and encoder sensor modules. Manufacturing concentrates in Germany, Japan, and the United States. Raw material dependencies include precision-ground granite bases, inductive encoder strips, and REACH-compliant surface treatments. Single-source vulnerability persists for NIST-traceable calibration reference standards. Distribution runs through authorized metrology distributors with technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: calibration infrastructure scarcity in India versus concentrated technician pools in Germany creates margin expansion opportunities for service-forward entrants.
For Market Incumbents: Anchor defensive positioning through captive calibration service networks and backward integration into encoder sensor production. Threat from software-integrated inspection workflow providers demands counter-investment in Bluetooth-enabled data streaming capabilities. Certification investment in BIS-compliant systems for Indian aerospace supplier networks represents priority capacity deployment. For New Entrants and Emerging Players: Enter via aftermarket calibration services in Maharashtra and Karnataka precision manufacturing clusters, where mandatory recertification intervals generate recurring revenue independent of equipment sales. White-space targets include Bluetooth-enabled gauges for South Korean electronics cleanrooms and optical edge detection systems for automated inspection cells. Go-to-market angle: SPC platform partnerships with existing quality software vendors. For Investors and Strategic Acquirers: Roll-up economics work for regional calibration service providers because mandatory recertification intervals generate predictable revenue streams with low customer churn. Long-term viability centers on technician workforce scarcity and regulatory tightening across precision manufacturing hubs. Acquisition target archetype: German automotive-calibration specialists with established tier-one supplier relationships. Signal to watch: NIST uncertainty budget revisions for electronic height measurement systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Encoder Technology | Captive supply of inductive linear encoders insulates margins from sensor module price volatility. |
| Calibration Service Network Expansion | Mandatory recertification intervals in India and South Korea generate recurring revenue attachment. |
| SPC Platform Partnership | Bluetooth data streaming integration with Hexagon quality ecosystems opens premium pricing tiers. |
| REACH-Compliant Coating Qualification | Pre-qualified vendor status with ECHA documentation accelerates German automotive procurement cycles. |
| Optical Edge Detection Development | Vision-based automation aligns with South Korean robotic inspection cell deployment patterns. |
Research Methodology
Multiple input streams — primary interviews with metrology laboratory directors, OEM procurement managers, and calibration service technicians; secondary validation through NIST technical publications, ECHA SVHC databases, and BIS certification records; plus customs trade data for precision instrument imports — were reconciled through bottom-up equipment deployment estimates and top-down manufacturing value-added calculations.
Data-stream reconciliation across product type, end-user industry, application workflow, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs derived from replacement-cycle compression rates and digital system penetration curves. Industry-specific forecast inputs include ISO 9001 audit frequency data and REACH compliance cost trajectories for surface treatment materials.
Inputs from national metrology institutes and automotive supplier association procurement surveys were available through the study window; gaps in mid-tier supplier capital expenditure plans introduce uncertainty bands around digital system adoption timelines. Deviation in EU Green Deal enforcement intensity or NIST uncertainty budget revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Global Tool Presetters Market
Industrial Tools
Tool Holder Collets Market
Industrial Tools
Digital Tool Presetter Market
Industrial Tools
Air Screwdrivers Market
Industrial Tools
Die Grinders Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Electric Tools Market
Industrial Tools
Micro Welders Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Precision Components and Tooling Systems Market
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
Plasma Arc Cutting Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Coordinate Measuring Machine Market
Industrial Tools
Machine Tool Touch Probe Market
Industrial Tools
Deburring Machine Market