
 Digital Tool Presetter Market | 2026-2036
Digital Tool Presetter Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Tool Presetter Market Analysis
Market Context
Carbide cutting tool substrates is rebalancing cost-performance tradeoffs across digital presetting workflows as coated carbide inserts displace high-speed steel in demanding applications. Zoller GmbH leverages vertical integration into software-driven measurement cycles to sustain premium positioning in European automotive supply chains. Haimer GmbH anchors its competitive stance through R&D intensity in thermal-stable spindle interfaces. Renishaw PLC differentiates via non-contact laser technology leadership that extends into aerospace qualification protocols.
Technical Definition and Segment Structure
A digital tool presetter is a precision measurement device that captures tool geometry, length, diameter, and runout parameters offline before spindle insertion, typically achieving repeatability below two microns through granite base frames and air-bearing spindles. Its primary commercial purpose is eliminating machine downtime from manual tool setting while preventing spindle crashes from incorrect offset data. Automatic presetters capture the dominant margin pool as manufacturers prioritize unmanned presetting cells integrated with tool management systems, while laser measurement technology represents the fastest-expanding segment as optical systems displace contact probes for micro-tool applications below three millimeters. Metalworking applications occupy the mature volume base, though aerospace demand accelerates as five-axis machining complexes require multi-vector tool verification.
Regulatory Environment
ISO 230 standards and VDI/VDE 3441 guidelines in Germany establish accuracy verification protocols that shape product certification requirements for presetter manufacturers seeking European market access. The US FAA and NHTSA indirectly drive demand through aerospace and automotive subsystem traceability mandates that cascade to tool measurement documentation. Stakeholders must monitor how evolving ISO standards for smart manufacturing data interfaces reshape interoperability requirements between presetters and machine tool controllers.
Market Dynamics
ISO 230 accuracy verification protocols are tightening measurement traceability requirements across European automotive supply chains, forcing presetter manufacturers to recertify granite base frame thermal stability specifications and air-bearing spindle repeatability claims.
Growth Catalysts
- VDI/VDE 3441 Guidelines:German precision machining clusters now mandate documented tool verification workflows, compelling Tier-1 suppliers to deploy automatic presetting cells with integrated tool management systems.
- Five-Axis Aerospace Machining:Multi-vector tool verification requirements at Boeing and Airbus subcontractors are accelerating demand for laser measurement systems capable of capturing complex cutting geometries offline.
- Coated Carbide Insert Displacement:High-speed steel tool retirement in Swiss watchmaking and medical device manufacturing is expanding addressable volume for micro-tool presetters below three millimeters.
Market Restraints
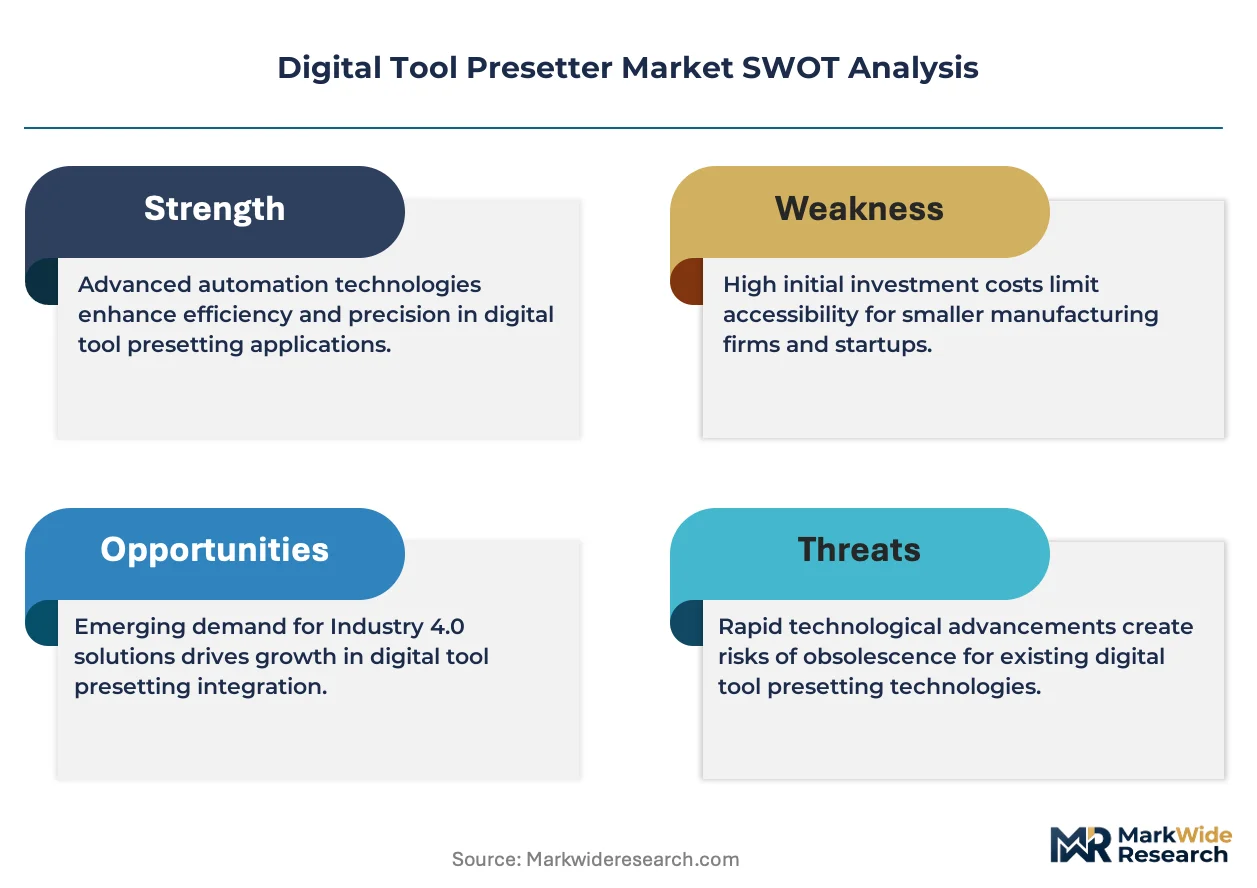
- Granite Base Frame Supply Concentration:Premium-grade black granite quarrying concentrates in southern India and Brazil, exposing presetter manufacturers to raw material shipping volatility and customs processing delays.
- Air-Bearing Spindle Technical Ceiling:Current hydrostatic bearing designs face thermal drift limitations above 10,000 RPM, constraining measurement repeatability for high-speed cutting tool applications.
- CE Marking Certification Friction:Evolving EU machinery directive interpretations are extending type-examination timelines for laser-equipped presetters by six to nine months.
Strategic Opportunities
- South Korean Smart Manufacturing:Government-funded K-Smart Factory initiatives are subsidizing presetter-tool management system integration for mid-tier metalworking suppliers previously priced out of automatic measurement cells.
- Additive Manufacturing Hybrid Workflows:Convergence of laser scanning technology with traditional touch-probe architectures enables single-platform verification of both subtractive cutting tools and additively manufactured fixtures.
- US Midwest Aerospace Corridor:Boeing's supply chain localization mandates are creating first-mover advantage for presetter vendors establishing service depots in Wichita and St. Louis machining clusters.
Industry Challenges
- Metrology Technician Scarcity:Sub-micron tool setting accuracy requirements demand specialized training in thermal compensation algorithms and interferometry calibration, skills concentrated among aging German and Japanese workforces.
- Legacy CNC Controller Integration:Proprietary data formats from Fanuc, Siemens, and Heidenhain machine tool controllers complicate seamless offset transmission from presetter software to shop-floor equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Tool Presetter Market |
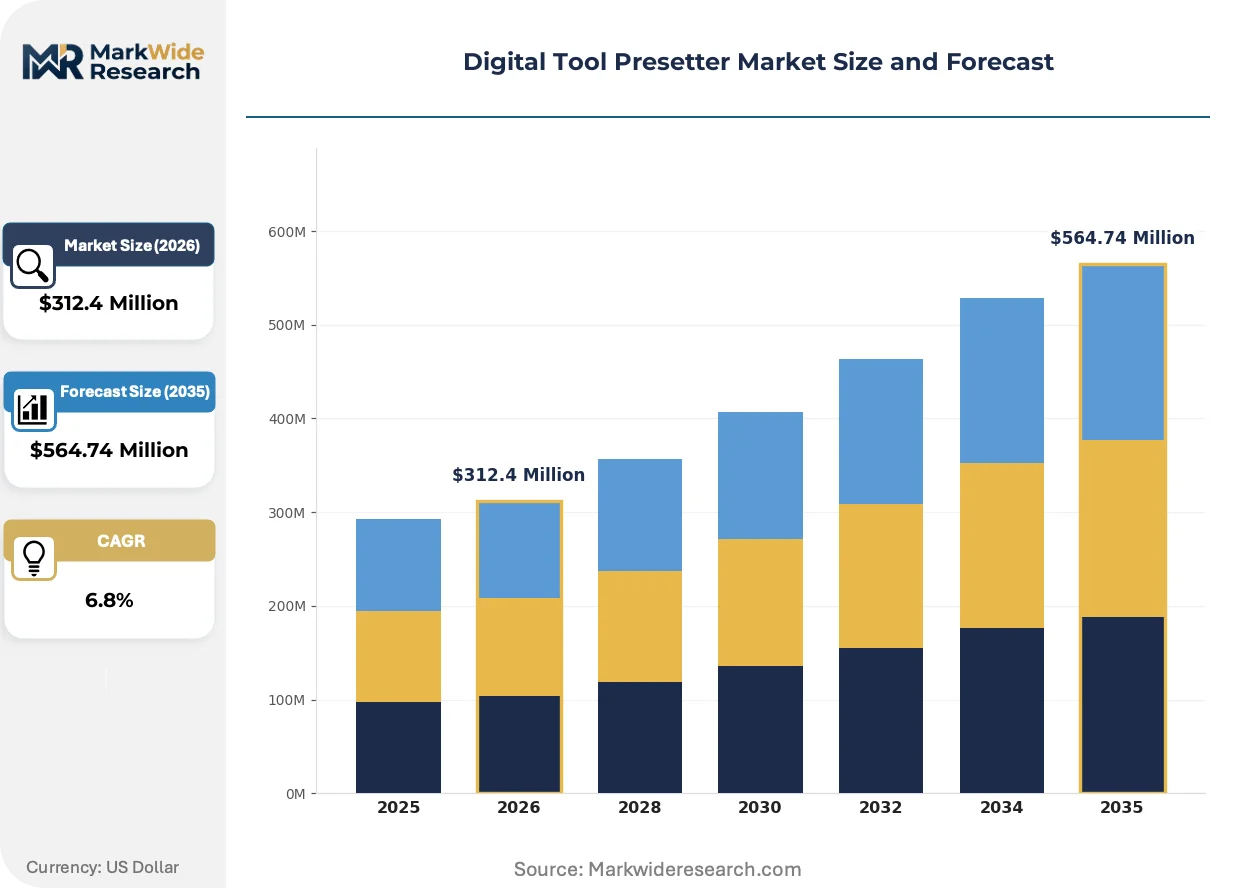
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Presetters, Automatic Presetters, Digital Presetters, CNC Presetters Application: Metalworking, Woodworking, Aerospace, Automotive End User: Manufacturers, Workshops, OEMs, Tool Distributors Technology: Contact Measurement, Non-Contact Measurement, Optical Measurement, Laser Measurement |
| Companies Covered | Zoller GmbH, Haimer GmbH, Renishaw PLC, BIG DAISHOWA, Speroni, Nikken Kosakusho, Kelch, Parlec, DMG MORI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Tool Presetter Market Emerging Trajectories
Non-contact optical measurement architectures are displacing mechanical touch probes across micro-tool applications, while regulatory traceability mandates reshape software functionality and service bundling models.
Laser triangulation systems with sub-micron resolution are integrating thermal drift compensation algorithms directly into measurement cycles. Aerospace suppliers in Toulouse and Hamburg are deploying these systems for unmanned overnight tool verification. This integration is compressing qualification timelines for five-axis machining centers from weeks to days.
REACH substance restrictions on hexavalent chromium coatings are forcing presetter spindle manufacturers to qualify ceramic-based alternatives for corrosion protection. The industrial consequence is extended validation cycles for spindle interface components. German automotive suppliers are responding by pre-qualifying presetter vendors with documented RoHS-compliant supply chains.
Tool-as-a-service contracting is displacing capital purchase models among US job shops with volatile order books. Distributor-managed presetter cells with per-measurement pricing are capturing mid-market volume previously lost to manual setting methods. This pattern concentrates in Chicago and Detroit metalworking corridors where capacity utilization swings exceed thirty percent seasonally.
Digital Tool Presetter Market Segmentation
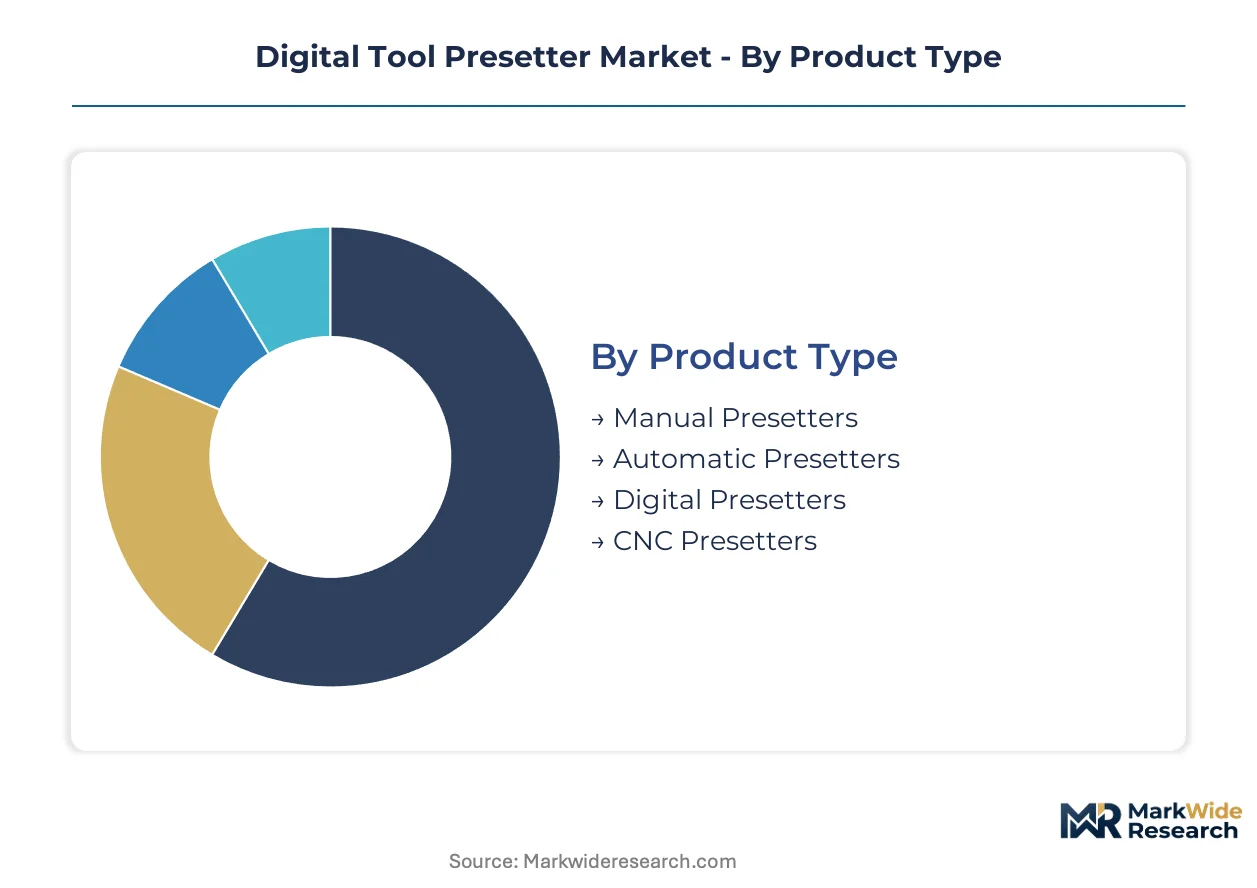
Digital tool presetter segmentation reveals distinct upgrade cycles across automation tiers and measurement technologies. Replacement timelines vary from five-year manual equipment refresh to eighteen-month automatic presetter recalibration intervals in aerospace-qualified facilities.
Product Type:
Equipment replacement cycles accelerate as automotive suppliers migrate from manual to automatic presetting cells to satisfy VDI/VDE 3441 documentation mandates.
- Automatic Presetters:Unmanned measurement cells integrate with tool management software to eliminate spindle downtime. German Tier-1 suppliers in Stuttgart and Munich clusters deploy these systems for overnight batch verification of coated carbide inserts.
- Manual Presetters:Mechanical dial-indicator systems persist in low-volume Swiss watchmaking subcontractors where operator skill substitutes for automation capital. Retirements concentrate among aging machinists without digital literacy.
- Digital Presetters:Electronic display units with basic data output serve mid-tier US Midwest job shops transitioning from mechanical gauges.
- CNC Presetters:Direct machine controller communication enables automated offset transmission to Fanuc and Siemens systems.
Volume placements concentrate in Automatic Presetters; the faster expansion belongs to CNC Presetters.
Application:
End-use diversification follows machining complexity gradients across subtractive manufacturing sectors.
- Metalworking:Mature demand base spans general machining with carbide insert verification. South Korean government subsidies through K-Smart Factory initiatives are accelerating presetter adoption among previously underserved mid-tier suppliers.
- Aerospace:Boeing and Airbus subcontractors require multi-vector tool verification for five-axis titanium machining. Toulouse and Hamburg suppliers deploy laser-equipped systems for unmanned overnight qualification cycles.
- Automotive:ISO 230 tightening drives recertification of granite base frame thermal stability specifications across German and Japanese production networks.
- Woodworking:Precision routing applications in Italian furniture manufacturing adopt entry-level digital presetters for profile cutter verification.
Metalworking retains the installed base; Aerospace claims the steepest expansion trajectory.
End User:
Procurement authority patterns separate capital-intensive manufacturers from service-oriented intermediaries.
- Manufacturers:In-house machining departments at automotive OEMs specify automatic presetting cells with integrated tool management. Toyota and Volkswagen captive suppliers mandate documented verification workflows.
- OEMs:Machine tool builders bundle presetter packages with five-axis machining center sales to aerospace customers.
- Workshops:Independent job shops in Chicago and Detroit corridors adopt per-measurement service contracts to avoid capital commitment.
- Tool Distributors:Resharpening service providers invest in compact laser presetters to verify reground cutting tools before customer delivery.
Manufacturers dominate capital deployment; Tool Distributors are gaining share fastest through service bundling.
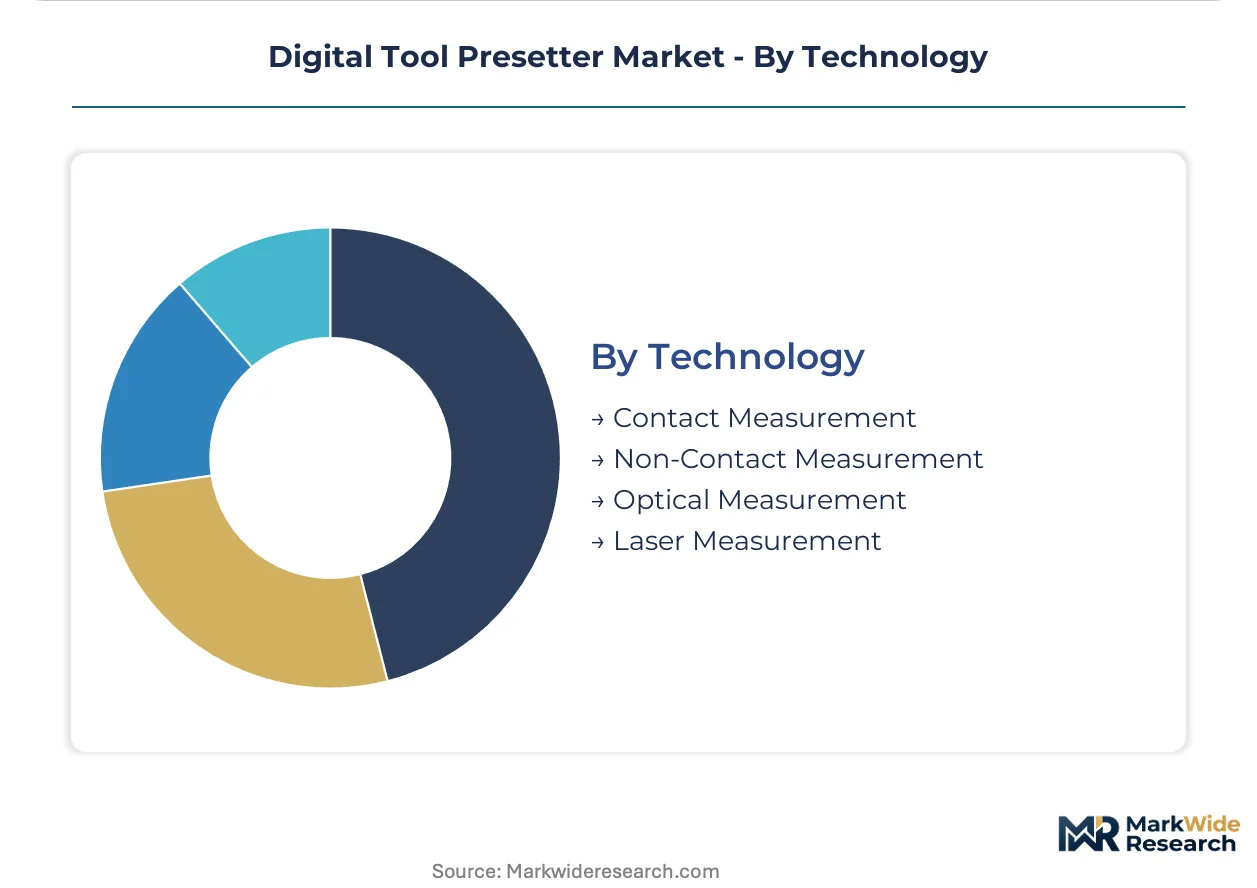
Technology:
Measurement modality selection hinges on tool geometry complexity and required repeatability thresholds.
- Laser Measurement:Non-contact triangulation systems achieve sub-micron resolution for micro-tools below three millimeters. Swiss medical device manufacturers and Japanese electronics subcontractors drive qualification of thermal-drift-compensated optical architectures.
- Non-Contact Measurement:Vision systems with edge-detection algorithms displace touch probes for complex cutting geometries in five-axis aerospace applications.
- Contact Measurement:Mechanical touch probes with granite base frames retain cost advantage for standard insert verification above six millimeters.
- Optical Measurement:Structured light systems bridge price-performance gaps for mid-tier metalworking suppliers.
Contact Measurement holds volume leadership; Laser Measurement is climbing the fastest as optical systems displace mechanical probes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in South Korea and precision manufacturing clusters in Switzerland concentrate demand for sub-micron measurement systems. Government-backed smart factory programs and aerospace supply chain mandates reshape regional deployment patterns.
Germany
VDI/VDE 3441 guidelines mandate documented tool verification workflows across Stuttgart and Munich automotive clusters. The KBA enforces traceability standards that cascade to Tier-1 suppliers. BMW and Volkswagen captive machining networks deploy automatic presetting cells for overnight batch verification of coated carbide inserts.
United States
FAA aerospace qualification protocols drive multi-vector tool verification demand at Boeing subcontractors. Wichita and St. Louis machining corridors localize presetter service depots under supply chain reshoring mandates. Chicago and Detroit job shops adopt per-measurement service contracts to avoid capital commitment amid volatile order books.
Japan
METI-funded productivity initiatives accelerate laser measurement adoption among electronics subcontractors. JIS standards govern thermal stability specifications for granite base frames. Toyota production networks in Aichi Prefecture mandate integrated tool management systems for documented offset verification.
Switzerland
Swissmedic traceability requirements extend to medical device manufacturing tooling. Watchmaking subcontractors in the Jura Arc retain manual presetters where operator skill substitutes for automation capital. Precision machining clusters in Geneva and Basel deploy micro-tool presetters below three millimeters for coated carbide insert verification.
South Korea
K-Smart Factory initiatives subsidize presetter-tool management system integration for mid-tier metalworking suppliers. The MFDS influences medical device manufacturing quality protocols that cascade to tooling verification. Busan-Ulsan machining clusters represent the fastest-expanding adoption corridor for automatic presetting cells.
Digital Tool Presetter Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with precision measurement specialists commanding premium positioning in aerospace-qualified facilities while diversified machine tool builders capture bundled sales. The vendor base organizes around three archetypes: granite-base-frame specialists with captive quarry relationships, laser-triangulation technology licensors, and machine tool OEMs integrating presetters into five-axis machining center packages. Consolidation pressure concentrates among mid-tier European fabricators facing REACH compliance costs and extended CE marking timelines. Strategic moves emphasize backward integration into software-driven measurement cycles and geographic proximity to aerospace supply chain clusters.
Among German GmbH-structured specialists, Zoller GmbH and Haimer GmbH exemplify the premium-tier archetype anchored in European automotive supply chain relationships. Renishaw PLC represents the technology-licensing vector with British public limited company structure. These three occupy positions that span the measurement modality spectrum from contact-probe granite systems to non-contact laser architectures, with each firm sitting within distinct regulatory compliance frameworks shaped by ISO 230 and VDI/VDE certification requirements.
| Leading Market Players |
|---|
| Zoller GmbH |
| Haimer GmbH |
| Renishaw PLC |
| BIG DAISHOWA |
| Speroni |
| Nikken Kosakusho |
| Kelch |
| Parlec |
| DMG MORI |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between aerospace-qualified and general metalworking presetters manifests in both pricing premiums and supply chain sourcing strategies. VDI/VDE 3441 compliance and ISO 230 thermal stability documentation command 40-60% price premiums while tethering procurement to German and Japanese granite-base specialists with captive metrology-grade quarry relationships.
Pricing Analysis
Volume placements cluster in standard-grade contact measurement systems for general metalworking, while margin concentration sits with laser-equipped automatic presetters qualified for aerospace subcontracts. Price differentiation separates CE-marked automatic cells with integrated tool management from entry-level digital units serving mid-tier job shops. Cost compression in manual presetter tiers is intensifying as coated carbide insert displacement accelerates equipment refresh cycles. Tier-1 automotive suppliers in Germany exhibit lowest price sensitivity due to mandated documentation workflows, whereas Chicago and Detroit job shops prioritize per-measurement service contracts to avoid capital commitment.
Supply Chain Analysis
Single-source vulnerability sits with premium-grade black granite quarrying concentrated in southern India and Brazil, exposing presetter manufacturers to raw material shipping volatility and customs processing delays. Manufacturing capacity draws from Germany, Japan, and Switzerland for precision spindle assemblies and thermal-stable base frames. Air-bearing spindle component supply hinges on specialized ceramic coating suppliers adapting to REACH hexavalent chromium restrictions. Distribution runs through machine tool OEM bundling agreements and authorized distributor networks with regional service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Granite base frame quarry access functions as the binding capacity constraint, propping pricing power for incumbents with captive mineral sourcing while marginalizing fabricators dependent on spot-market stone procurement.
For Market Incumbents: Acquire premium-grade granite quarry relationships or long-term offtake agreements to secure thermal stability certification capacity. Haimer GmbH and Zoller GmbH should deepen backward integration into ceramic spindle coating supply chains before REACH compliance costs escalate. Defensive positioning requires preemptive laser-triangulation R&D investment as optical architectures displace contact probes below three millimeter applications. For New Entrants and Emerging Players: Capture K-Smart Factory subsidized demand in South Korea's Busan-Ulsan corridor where mid-tier metalworking suppliers remain underserved by automatic presetter tooling. White-space concentration sits with additive manufacturing hybrid workflow verification platforms combining laser scanning with traditional touch-probe architectures. Go-to-market execution should emphasize per-measurement service contracting to bypass capital-intensive equipment sales cycles. For Investors and Strategic Acquirers: Re-rating potential sits with laser-triangulation technology licensors given aerospace multi-vector verification mandates and five-axis machining proliferation. Long-term viability favors specialists with documented ISO 230 recertification capabilities and software-driven measurement cycle integration. Monitor CE marking timeline extensions for laser-equipped systems as the inflection signal for regulatory compliance moat widening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Granite Sourcing | Captive quarry access secures thermal stability certification capacity for VDI/VDE 3441 compliance. |
| Laser-Triangulation R&D Expansion | Non-contact optical architectures displace mechanical probes in Swiss medical device manufacturing. |
| Service Depot Localization | Wichita and St. Louis proximity captures Boeing supply chain reshoring mandate volume. |
| Software-Driven Measurement Cycles | Zoller GmbH leverages integrated tool management systems for overnight batch verification. |
| Per-Measurement Contracting Model | Chicago and Detroit job shops adopt usage-based pricing amid volatile capacity utilization. |
Methodological Framework
Trade association filings, customs and import-export databases, and machine tool OEM technical documentation formed the secondary backbone for this analysis. Primary fieldwork encompassed structured interviews with metrology equipment procurement managers at German Tier-1 automotive suppliers, maintenance directors at US Midwest aerospace subcontractors, and aftermarket service heads at Japanese electronics manufacturing networks. Bottom-up volume estimates derived from presetter shipment records triangulated against top-down spending patterns from national productivity initiatives.
Historical trendline analysis of replacement cycle intervals and technology upgrade patterns informed the projection framework across the analysis window. Segmentation modeling incorporated automation tier, measurement modality, end-use application complexity, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves calibrated to ISO 230 recertification mandates and K-Smart Factory subsidy disbursement trajectories. Forecast inputs included air-bearing spindle technical ceiling constraints and REACH substance restriction implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CE marking interpretation shifts and granite quarry supply disruptions. Aerospace qualification protocol evolution and additive manufacturing hybrid workflow adoption represent primary revision triggers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Precision Components and Tooling Systems Market
Industrial Tools
Deburring Machine Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Jigs and Other Tools Market
Industrial Tools
Electric Tools Market
Industrial Tools
Tool Holder Market
Industrial Tools
Micro Welders Market
Industrial Tools
Air Screwdrivers Market
Industrial Tools
Tool Holder Collets Market
Industrial Tools
Machine Tool Touch Probe Market
Industrial Tools
Global Tool Presetters Market
Industrial Tools
Centerless Grinding Market
Industrial Tools
India Power Tool Market
Industrial Tools
Plasma Arc Cutting Market