
 Soldering Iron Pen Market | 2026-2036
Soldering Iron Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Soldering Iron Pen Market Analytics
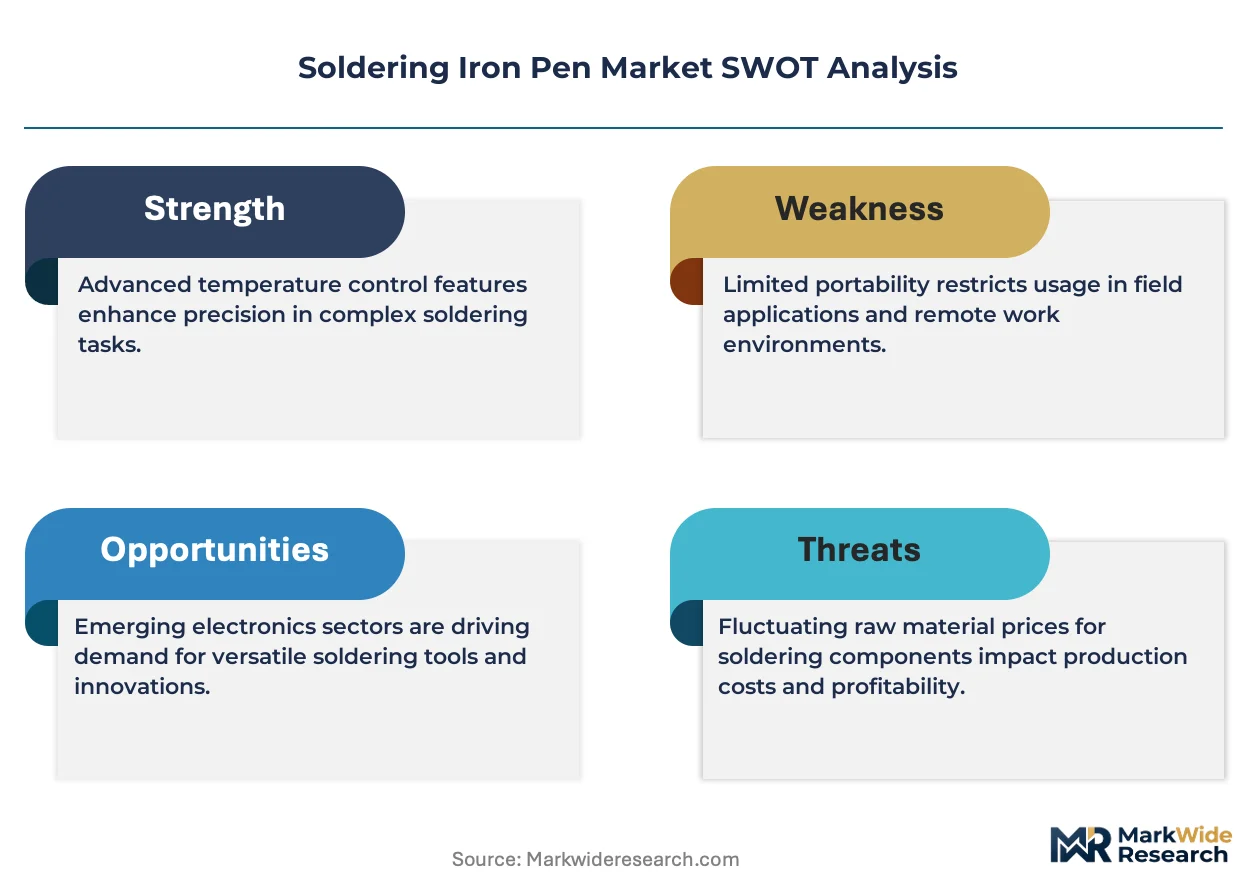
Modular kit configurations pairing interchangeable tips with adjustable wattage bases is hardening as the dominant product architecture. Weller Tools GmbH leverages its German engineering heritage to sustain premium positioning in professional channels. Ersa GmbH anchors European industrial demand through specialized high-wattage stations for automotive electronics assembly. Apollo Seiko Europe BV competes in precision automation, differentiating through robotic soldering integration rather than handheld units alone.
A soldering iron pen is a handheld thermal tool comprising a resistive heating element, temperature-controlled tip, and ergonomic grip, designed to melt solder alloy for electrical and mechanical joint formation on printed circuit boards and component leads. Electric variants dominate volume shipments due to consistent thermal stability, while battery-powered units are gaining traction in field repair and portable applications where mains access is limited. The hobbyist segment occupies the entry-price tier with high unit volumes but thinner margins, whereas professionals and educational institutions sustain margin pools through replacement tip consumption and calibration service attach rates.
RoHS and REACH frameworks in the European Union restrict lead and cadmium content in tip plating, compelling suppliers to certify alternative metallurgies. The EPA and OSHA in the United States govern fume extraction and workplace exposure limits, shaping ventilation accessory bundling and industrial channel compliance documentation. ISO 9001 quality management and IEC 60335 safety standards further gate market access for cross-border suppliers. Stakeholders must monitor evolving tip material certifications and regional service infrastructure requirements as warranty terms and calibration networks become decisive in procurement decisions.
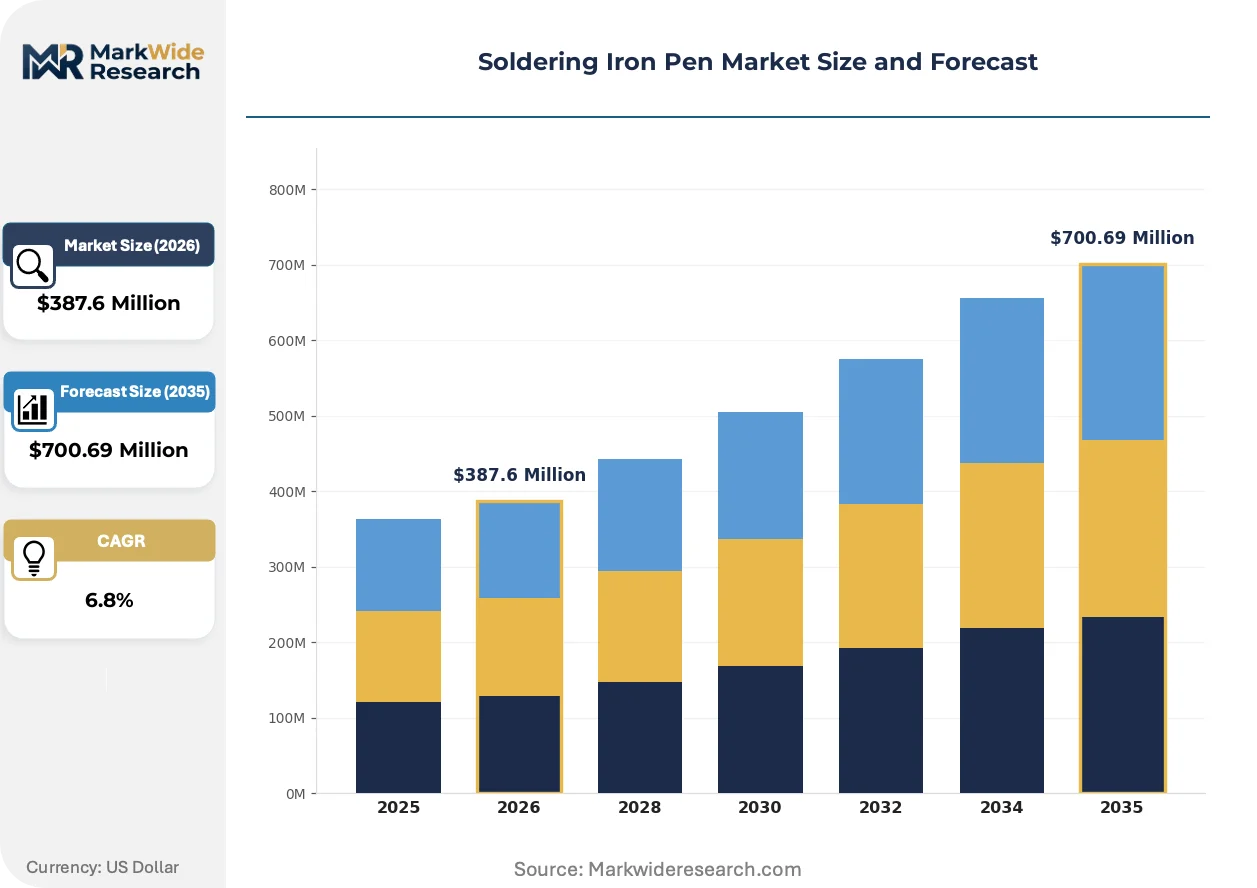
Market Dynamics
Miniaturization pressure from consumer electronics and automotive PCB assembly is compressing tip geometries while demanding tighter thermal control tolerances. This structural force cascades through material science, heating element design, and calibration service requirements.
Growth Catalysts
- REACH compliance deadlines:European Union tip plating restrictions are accelerating R&D into nickel-boron and iron-chromium alternatives that eliminate cadmium leaching risks.
- Shenzhen electronics cluster:Contract manufacturers in China's Pearl River Delta are standardizing professional-grade stations for high-mix, low-volume prototyping workflows.
- Induction heating cores:Faster thermal recovery times are displacing traditional ceramic elements in precision rework applications where joint quality variance must stay below three percent.
Market Restraints
- Copper price volatility:Tip substrate costs swing with London Metal Exchange pricing, compressing margin on replacement consumables.
- Single-source ceramic suppliers:Alumina heating element production concentrates in Japanese prefectures, exposing buyers to earthquake-related supply interruptions.
- Lead-free solder compatibility:Higher melting point alloys accelerate tip erosion, forcing more frequent replacement cycles that strain maintenance budgets.
Strategic Opportunities
- Field repair mobility:Battery-powered units with USB-C charging are penetrating telecommunications infrastructure maintenance in India and Southeast Asian markets.
- EU Green Deal procurement rules:Public sector educational institutions must favor repairable, modular designs over sealed disposable units.
- Robotic integration:Handheld pen form factors with position-feedback encoders are converging with collaborative robot arms for semi-automated rework stations.
Industry Challenges
- Micro-soldering certification scarcity:IPC J-STD-001 qualified technicians remain concentrated in aerospace and medical device hubs, limiting contract manufacturer expansion.
- Calibration traceability infrastructure:ISO 17025 accredited labs for tip temperature verification are sparse outside Germany, Japan, and the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soldering Iron Pen Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Battery-Powered, Manual, Gas End User: Hobbyists, Professionals, Educational Institutions, Repair Shops Wattage: 15W, 30W, 40W, 60W Tip Type: Conical, Chisel, Blade, Fine |
| Companies Covered | Weller Tools GmbH, Adolf Würth GmbH & Co. KG, Ersa GmbH, JBC, Aoyue, Hakka, Apollo Seiko Europe BV, DEN-ON INSTRUMENTS Co., Ltd, P. F. Freund & Cie. GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soldering Iron Pen Market Evolving Landscape
Thermal management architectures and compliance documentation requirements are rewiring competitive advantage away from raw wattage specifications toward precision control and service attach rates.
Active tip temperature sensing using platinum resistance elements is expanding into high-reliability automotive electronics assembly. Tier-1 suppliers in Stuttgart and Wolfsburg are mandating closed-loop feedback systems that log thermal profiles for traceability. This capability is compressing the addressable market for open-loop resistive designs in premium industrial channels.
EPA workplace exposure limits for rosin flux particulates are forcing fume extraction bundling in North American distribution. Industrial distributors now package activated carbon filtration arms with station purchases to preempt OSHA inspection failures. Educational institutions and small contract shops face the steepest compliance cost increases as they retrofit legacy benches.
Direct-to-manufacturer purchasing through configurators is fragmenting traditional distributor hold on replacement tip volumes. Professional users in South Korea and Taiwan are bypassing channel intermediaries to order certified consumables via supplier portals with subscription replenishment. This behavior compresses distributor margin pools while shifting warranty liability to factory-direct service networks.
Soldering Iron Pen Market Segmentation
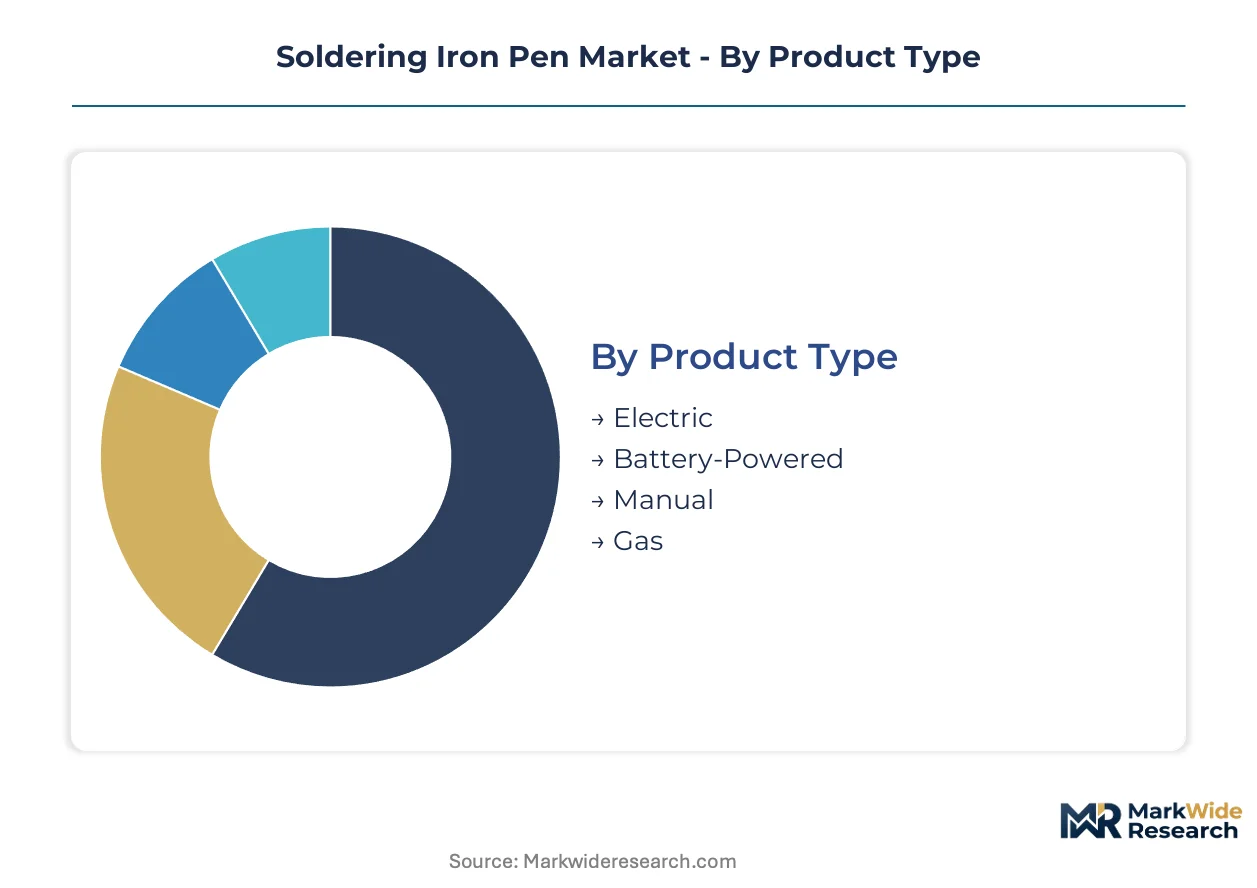
Soldering iron pen procurement patterns diverge sharply across user sophistication levels and thermal precision requirements. Segment boundaries harden around calibration service attach rates, tip replacement economics, and compliance documentation burdens.
Product Type:
Capital intensity escalates with temperature control sophistication and power delivery architecture.
- Electric:Resistive heating elements with closed-loop thermocouple feedback dominate professional workflows. Demand concentrates in Shenzhen contract manufacturers where ISO 9001 traceability requirements mandate consistent thermal profiles for automotive PCB assembly.
- Battery-Powered:Lithium-ion cell packs with USB-C charging circuits enable field mobility. Expansion accelerates in Indian telecommunications infrastructure maintenance where mains access remains intermittent at rural tower sites.
- Manual:Butane-fueled units with catalytic combustion tips serve emergency repair scenarios. Fire safety regulations in German industrial facilities restrict deployment.
- Gas:Propane-oxygen hybrid torches for heavy-gauge soldering occupy niche plumbing and HVAC applications. EPA fume exposure limits constrain North American educational procurement.
Most installed capacity flows through Electric. Expansion is steepest in Battery-Powered.
End User:
Margin pools stratify by replacement consumable velocity and certification service requirements.
- Professionals:IPC J-STD-001 certified technicians demand calibrated stations with logged thermal profiles. Stuttgart automotive electronics clusters mandate closed-loop feedback systems for traceability compliance.
- Educational Institutions:EU Green Deal procurement rules favor modular, repairable designs over sealed disposable units. RoHS tip plating certifications gate supplier selection.
- Hobbyists:Entry-price tier with high unit volumes but minimal service attach rates. Shenzhen e-commerce channels dominate distribution.
- Repair Shops:Mixed-skill environments prioritize tip interchangeability across wattage bases. OSHA ventilation requirements in US markets force fume extraction bundling.
Replacement tip revenue concentrates in Professionals. Volume expansion is fastest in Educational Institutions.
Wattage:
Heating element material selection and thermal recovery specifications scale with power rating.
- 60W:High-mass ceramic cores with induction heating architectures serve automotive wire harness assembly. Ersa GmbH anchors European industrial demand through specialized stations.
- 40W:Balanced thermal capacity for general-purpose PCB rework. Shenzhen prototyping workflows standardize this rating for high-mix, low-volume production.
- 30W:Precision applications in consumer electronics miniaturization. Lead-free solder compatibility accelerates tip erosion, compressing replacement cycles.
- 15W:Micro-soldering for medical device and aerospace componentry. IPC certification scarcity limits addressable market expansion.
Industrial procurement gravitates toward 60W. Steepest climb occurs in 40W.
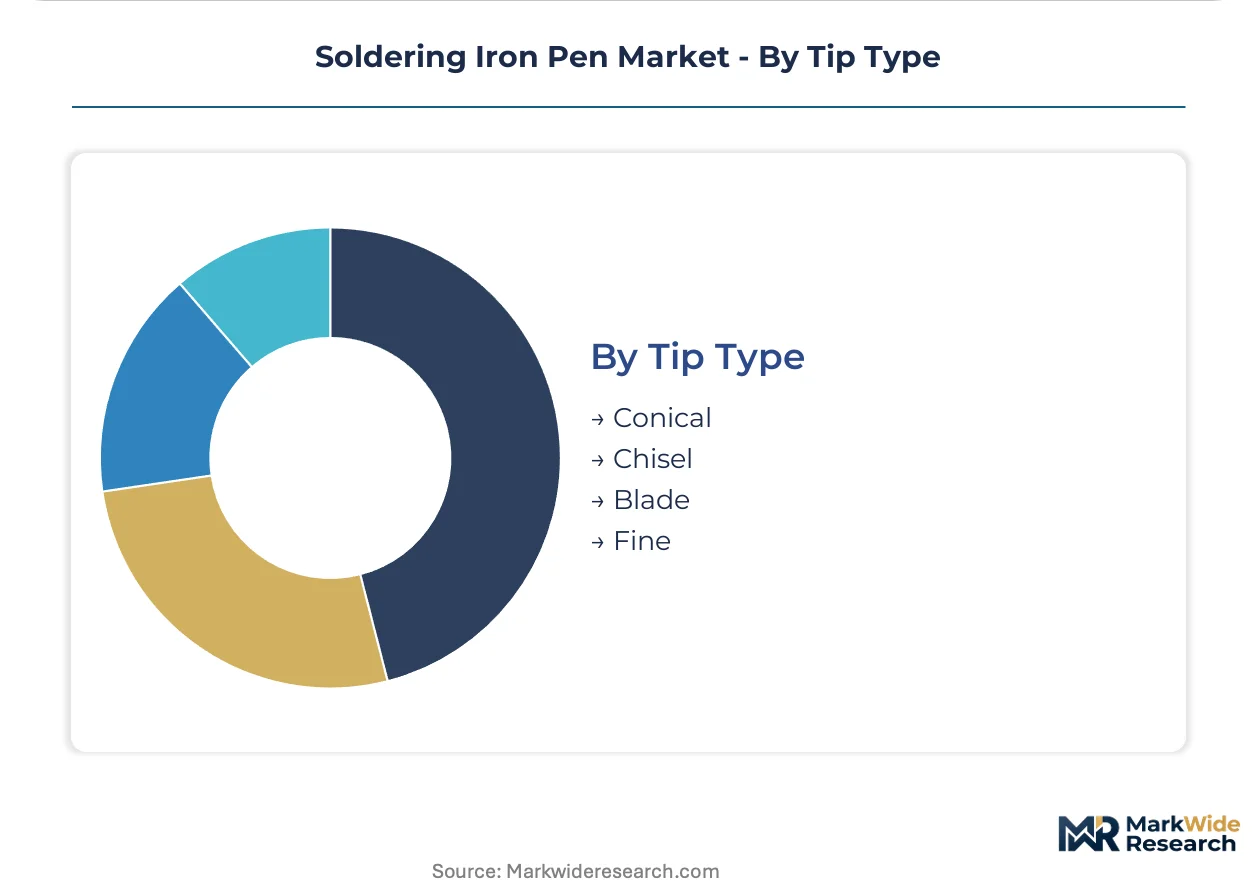
Tip Type:
Geometry selection determines joint accessibility and thermal transfer efficiency in specific component footprints.
- Chisel:Flat blade profile maximizes surface contact for through-hole component soldering. German automotive electronics assembly lines specify nickel-boron plating alternatives to satisfy REACH cadmium restrictions.
- Conical:Tapered point geometry enables precision work in dense SMD layouts. South Korean contract manufacturers drive volume through direct-to-manufacturer portal purchasing.
- Blade:Extended reach configurations for heat sink and connector applications. Copper price volatility swings replacement consumable costs.
- Fine:Sub-millimeter tips for 0201 and smaller passive components. Alumina heating element supply concentration in Japanese prefectures exposes buyers to interruption risk.
Chisel geometry carries the largest installed base. Fine tips are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering traditions established the foundation for professional-grade thermal tools in the early twentieth century. Contemporary demand distributes across electronics manufacturing clusters where miniaturization pressures and regulatory compliance intersect.
Germany
Automotive electronics assembly in Stuttgart and Wolfsburg drives procurement of closed-loop feedback soldering stations. REACH enforcement through ECHA mandates cadmium-free tip plating alternatives. Bavarian industrial distributors bundle fume extraction systems to satisfy workplace exposure regulations.
China
Shenzhen's contract manufacturers standardize professional-grade equipment for high-mix prototyping workflows. MIIT certification requirements govern product safety documentation for domestic sales. The Pearl River Delta cluster consumes volume shipments of precision rework stations for consumer electronics miniaturization.
United States
EPA workplace exposure limits for rosin flux particulates shape fume extraction bundling in industrial distribution. OSHA inspection protocols force ventilation accessory compliance documentation. Midwestern contract manufacturers serving automotive tier-1 suppliers demand logged thermal profiles for traceability.
Japan
Alumina heating element production concentrates in prefectures vulnerable to seismic interruption risk. METI industrial standards govern tip temperature calibration protocols. Nagoya-area automotive electronics suppliers mandate induction heating architectures for wire harness assembly.
South Korea
Direct-to-manufacturer portal purchasing compresses traditional distributor margins on replacement consumables. MFDS-equivalent industrial safety frameworks regulate workplace thermal tool deployment. Seoul Capital Area contract manufacturers drive volume through subscription-based tip replenishment models.
Soldering Iron Pen Market Competitive Landscape
Premium-margin players sit above commodity-margin players across calibration service attach rates and tip replacement economics. The vendor base stratifies between German-engineered precision specialists, Asian volume manufacturers, and automation-integrated solution providers. Three archetypes dominate: heritage engineering houses with certification infrastructure, scale-driven fabricators serving hobbyist channels, and robotic integration specialists. Competitive moves concentrate on backward integration into heating element supply and geographic expansion through distributor network acquisition.
Within the heritage engineering tier, Weller Tools GmbH and Ersa GmbH exemplify premium positioning through German manufacturing lineage and calibration service infrastructure. Apollo Seiko Europe BV occupies a distinct automation-integrated position. Chinese volume manufacturers including Aoyue and Hakka represent scale-driven competitors in entry-price segments. Japanese specialists such as JBC and DEN-ON INSTRUMENTS Co., Ltd anchor precision rework applications in automotive and medical device channels.
| Leading Market Players |
|---|
| Weller Tools GmbH |
| Adolf Würth GmbH & Co. KG |
| Ersa GmbH |
| JBC |
| Aoyue |
| Hakka |
| Apollo Seiko Europe BV |
| DEN-ON INSTRUMENTS Co., Ltd |
| P. F. Freund & Cie. GmbH |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between IPC J-STD-001 compliant stations and uncertified hobbyist units manifests in both pricing architecture and supply chain sourcing strategies. Premium German-engineered products command calibration service attach rates that commodity Shenzhen manufacturers cannot replicate, while raw material dependencies in Japanese ceramic production constrain cost flexibility across all tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement decisions, with ISO 17025 calibration certification and REACH-compliant tip plating as primary differentiation drivers. Cost compression in the economy tier intensifies because Shenzhen volume manufacturers compete on replacement consumable velocity rather than thermal precision. Hobbyist segments exhibit highest price sensitivity, while Stuttgart automotive electronics clusters accept premium positioning for closed-loop feedback systems with logged thermal profiles.
Supply Chain Analysis
Alumina heating element supply rests on Japanese prefecture production, while copper tip substrates draw from Chilean mining operations and nickel-boron plating chemistry sources from German specialty metallurgy houses. Single-source ceramic vulnerability exposes buyers to seismic interruption risk in the Tokai region. Distribution runs through Bavarian industrial distributors in European professional channels and direct-to-manufacturer portals in South Korean contract manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soldering iron pen market functions as a stable compounder, with electronics miniaturization mandates from automotive and medical device sectors ensuring steady replacement cycle demand across the analysis window.
For Market Incumbents: Acquire calibration service infrastructure in underserved geographies to preempt emerging competitors from capturing ISO 17025-accredited lab scarcity in India and Southeast Asia. Backward integration into nickel-boron plating chemistry reduces REACH compliance cost exposure. Defend against direct-to-manufacturer portal disintermediation by embedding subscription replenishment capabilities in existing distributor relationships. For New Entrants and Emerging Players: The 40W precision tier gap between professional closed-loop systems and hobbyist open-loop designs offers white-space entry for mid-market contract manufacturers in Shenzhen and Taipei. Battery-powered field repair units for Indian telecommunications infrastructure represent the most penetrable application expansion. Pursue USB-C charging standardization as a go-to-market angle to bypass proprietary ecosystem lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where calibration traceability infrastructure concentrates in Germany, Japan, and the United States while demand fragments across emerging manufacturing clusters. Long-term viability favors targets with captive heating element supply or established ECHA compliance documentation. Watch induction heating architecture adoption rates in Stuttgart automotive electronics as an inflection signal for ceramic element displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Captive alumina ceramic supply mitigates Japanese prefecture seismic risk exposure. |
| Calibration Service Network Expansion | ISO 17025 accredited labs in India capture emerging contract manufacturer demand. |
| REACH-Compliant Tip Plating R&D | Nickel-boron alternatives satisfy ECHA cadmium restrictions for European automotive. |
| Direct-to-Manufacturer Portal Launch | Subscription replenishment models bypass distributor margin compression in South Korea. |
| Battery-Powered Product Line Extension | USB-C charging enables rural telecommunications infrastructure maintenance in India. |
Research Methodology
Coverage spans Germany, China, the United States, Japan, and South Korea, with primary inputs from each market cluster combined with secondary validation. Interviews with IPC-certified technician training directors, automotive electronics procurement managers at Stuttgart Tier-1 suppliers, Shenzhen contract manufacturing operations heads, Bavarian industrial distributor category managers, and South Korean direct-portal purchasing specialists informed demand-side assumptions. Secondary sources include ECHA REACH compliance databases, MIIT product safety filings, EPA workplace exposure documentation, METI industrial standards, and MFDS-equivalent regulatory frameworks. Bottom-up unit economics triangulate against top-down electronics manufacturing output projections.
Rate-of-change decomposition separates volume growth from value mix shift across the projection horizon. Segmentation dimensions modeled include product type, end user sophistication tier, wattage rating, tip geometry, and regional regulatory compliance cluster. CAGRs derive from installed base replacement cycle analysis and new equipment procurement intensity in high-mix prototyping workflows. Induction heating architecture penetration rates and lead-free solder compatibility erosion patterns serve as industry-specific forecast inputs.
Caveats apply where copper price volatility, Japanese seismic events, or REACH enforcement intensity could materially shift the outlook. Forecasts reflect assumptions about technician certification expansion rates and calibration infrastructure buildout timing. A small set of named triggers—alumina supply interruption, ECHA plating restriction expansion, and automotive electronics miniaturization acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Coordinate Measuring Machine Market
Industrial Tools
Tool Holder Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Air Screwdrivers Market
Industrial Tools
India Power Tool Market
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
Centerless Grinding Market
Industrial Tools
Precision Components and Tooling Systems Market
Industrial Tools
Die Grinders Market
Industrial Tools
Deburring Machine Market
Industrial Tools
Tool Holder Collets Market
Industrial Tools
Handheld DC Torque Tools Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Dies, Jigs and Other Tools Market
Industrial Tools
Saudi Arabia Power Tools Market