
 Machine Tool Touch Probe Market | 2026-2036
Machine Tool Touch Probe Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Tool Touch Probe Market Analysis
Aerospace engineering is decoupling from automotive manufacturing as the dominant demand vertical for machine tool touch probes. Renishaw plc leverages its probe-to-software ecosystem to anchor high-value contracts with tier-one aerospace suppliers. Hexagon AB competes through its metrology-to-manufacturing software bridge, while Blum-Novotest GmbH specializes in compact radio-wave probes for five-axis machining centers.
A machine tool touch probe is a precision sensor device mounted on CNC machines or coordinate measuring equipment to detect workpiece position, tool length, and surface geometry during automated cycles, typically achieving repeatability below one micron. Its primary industrial purpose is to eliminate manual setup time, reduce scrap rates, and enable closed-loop process correction in unmanned machining operations. Contact probes dominate installed bases across mature manufacturing economies due to proven reliability in harsh coolant environments, while wireless technology segments capture expanding share as machine builders retrofit older CNC architectures with cable-free measurement systems. Optical probes command premium positioning in semiconductor and medical device machining where non-contact surface preservation matters.
FDA device manufacturing regulations, EU Machinery Directive safety frameworks, and ISO 230 machine tool test codes collectively shape probe calibration protocols and supplier qualification requirements across end-user sectors. Japan's METI industrial standards and Germany's KBA automotive certification pathways further segment product compliance roadmaps by destination market. Stakeholders must monitor how infrared technology integration and digital signal processing architectures redefine competitive differentiation before next-generation platform decisions lock in.
Market Dynamics
Wireless radio-wave probe architectures are displacing cable-dependent systems across five-axis machining centers, forcing incumbent suppliers to reengineer signal transmission protocols for coolant-immersed environments.
Growth Catalysts
- EU Machinery Directive compliance mandates:Tightened safety frameworks for in-process measurement systems compel European manufacturers to replace legacy probe fleets with certified next-generation units.
- Aerospace precision requirements:Titanium airframe component machining demands sub-micron repeatability that manual setup cannot achieve, accelerating automated probe integration.
- Japan's METI industrial standards:Updated JIS calibration protocols for unmanned machining operations drive probe replacement cycles in precision manufacturing clusters.
Market Restraints
- Signal interference in harsh environments:Coolant immersion and metal chip density degrade wireless transmission reliability, limiting radio-wave probe deployment in heavy roughing applications.
- Supplier concentration in precision sensor components:Germany and Japan control critical piezoelectric element supply, creating vulnerability for probe manufacturers outside these geographies.
- ISO 230 test code complexity:Multi-axis calibration verification requirements extend qualification timelines and inflate engineering overhead for new product introductions.
Strategic Opportunities
- India's PLI scheme for precision manufacturing:Production-linked incentives for advanced machine tools create localized demand for cost-optimized probe systems.
- Optical probe convergence with semiconductor fabrication:Non-contact surface preservation requirements in wafer machining open premium positioning for laser-triangulation sensors.
- Digital twin integration:Real-time probe data feeds into virtual machining simulations, enabling predictive tool wear models that command software-recurring revenue streams.
Industry Challenges
- Multi-axis kinematics expertise scarcity:Five-axis probe calibration requires specialized metrology engineers that machine shops struggle to recruit and retain.
- Legacy CNC architecture integration:Retrofitting 1990s-era machine tools with wireless probe systems demands custom interface development that fragments engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Tool Touch Probe Market |
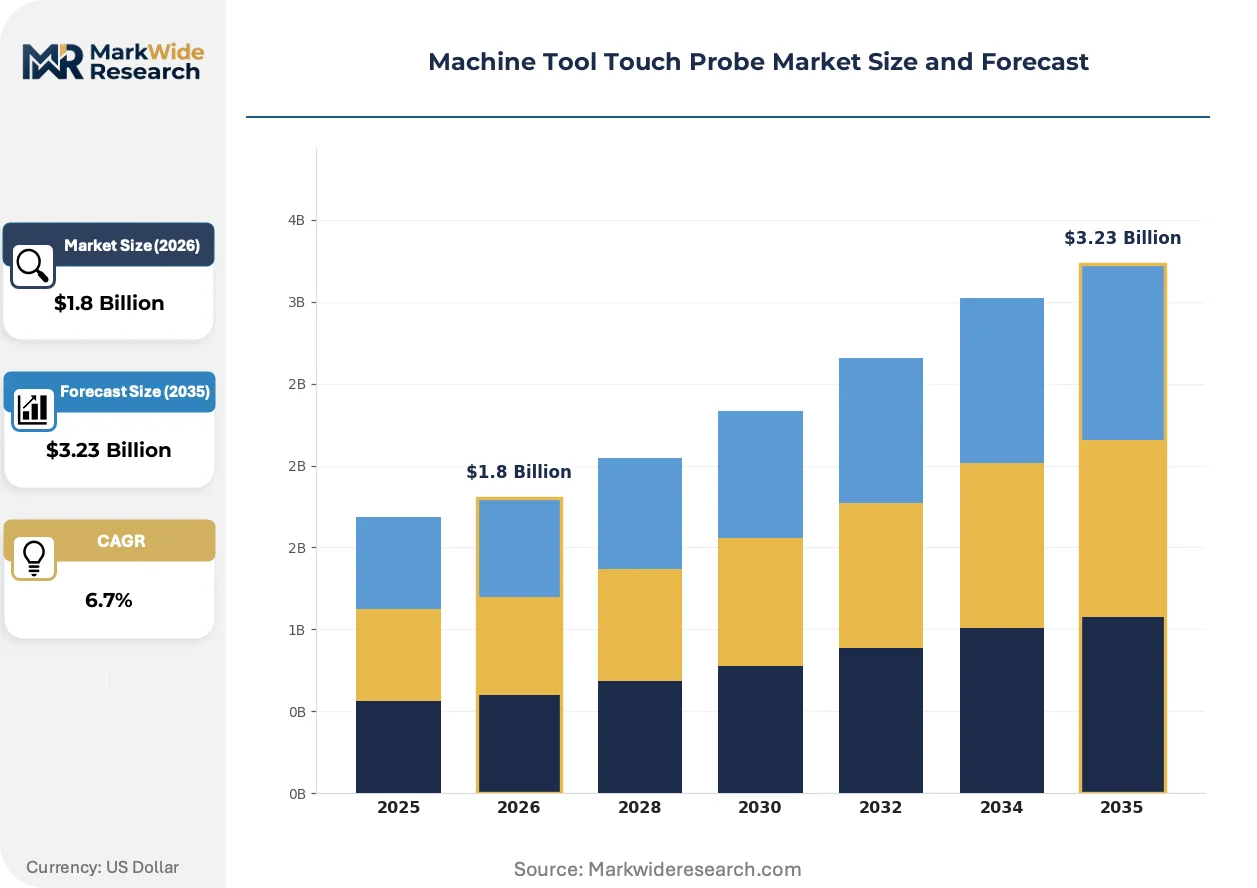
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: CMM, CNC Machining, Automotive Manufacturing, Aerospace Engineering Type: Contact Probes, Optical Probes, Magnetic Probes, Laser Probes Technology: Analog Technology, Digital Technology, Wireless Technology, Infrared Technology End User: Manufacturers, Machine Shops, OEMs, Research Institutions |
| Companies Covered | Renishaw plc, Hexagon AB, Blum-Novotest GmbH, Marposs S.p.A., Heidenhain Corporation, Carl Zeiss Industrial Metrology, Mitutoyo Corporation, Keyence Corporation, Qidu Metrology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Tool Touch Probe Market Emerging Trajectories
Digital signal processing architectures are compressing measurement cycle times while expanding the data bandwidth available for in-process quality feedback loops.
Radio-frequency identification coupling with touch probe systems is electrifying tool-data management in unmanned machining cells. Aerospace tier-one suppliers are deploying these combined units at accelerating rates to eliminate manual tool presetting. This convergence is electrifying competitive differentiation around data interoperability rather than raw measurement precision alone.
The EU AI Act's risk classification framework for automated manufacturing systems is reshaping probe software validation requirements. Industrial consequence includes mandatory algorithmic transparency documentation for machine-learning-enhanced measurement routines. Medical device machining facilities in Ireland and Switzerland are responding by segregating AI-assisted probes into dedicated quality assurance protocols.
After-sales service unbundling is fragmenting traditional probe supplier relationships. Machine builders now procure measurement hardware separately from calibration contracts and software subscriptions. This shift is most visible in Germany's automotive supplier ecosystem, where captive metrology departments negotiate component-level pricing rather than turnkey system packages.
Machine Tool Touch Probe Market Segmentation
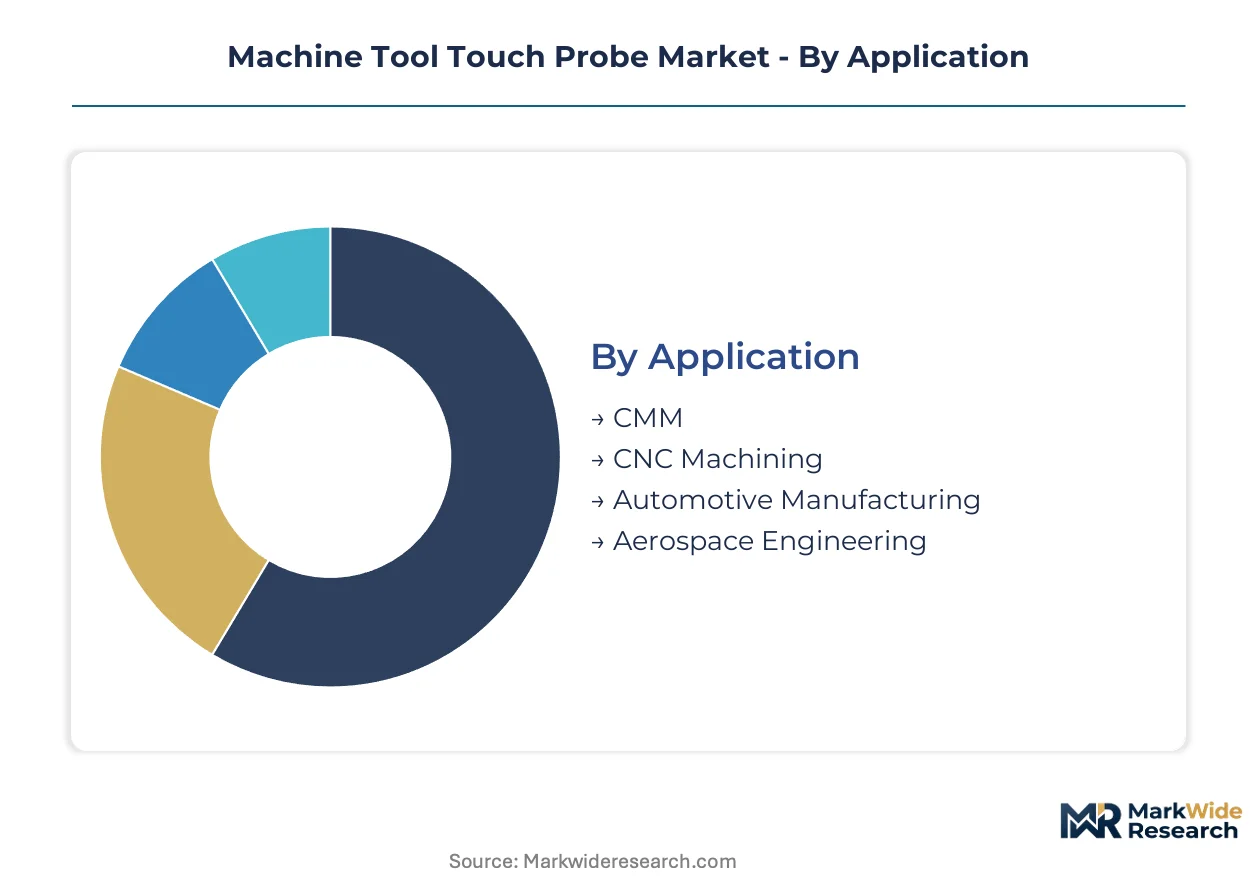
Probe specification varies sharply by machining environment and measurement precision requirements. Aerospace engineering demands sub-micron repeatability that optical systems deliver, while automotive manufacturing prioritizes coolant-resistant contact probes for high-volume production. Understanding segment boundaries clarifies where suppliers must engineer for performance versus cost optimization.
Application:
Standardized probe architectures dominate high-volume automotive lines, whereas aerospace and CMM applications demand customized calibration protocols and specialized stylus configurations.
- CMM:Coordinate measuring machines deploy touch probes as primary sensing elements for offline quality verification, with stylus changers enabling multi-tip inspection routines. Demand concentrates in Germany's automotive supplier ecosystem, where KBA certification mandates drive replacement of manual gauging systems with automated CMM integration.
- CNC Machining:In-process touch probes mounted directly on machine spindles eliminate workpiece repositioning between machining and measurement stations. Japan's METI unmanned machining standards accelerate deployment across precision manufacturing clusters in Aichi and Osaka prefectures.
- Automotive Manufacturing:High-volume powertrain machining relies on robust contact probes with hardened styli for cast iron and aluminum roughing operations.
- Aerospace Engineering:Titanium and Inconel airframe component machining demands thermally stable probe designs for five-axis contouring applications.
Most installed capacity flows through CNC Machining. Expansion is steepest in Aerospace Engineering.
Type:
Cost tiering separates premium non-contact systems from commodity contact probes, with price multiples exceeding 4x between optical and magnetic categories.
- Contact Probes:Mechanical touch-trigger mechanisms with ruby-ball styli achieve repeatability below one micron in coolant-immersed environments. Germany's precision manufacturing clusters sustain dominant demand, where ISO 230 calibration protocols maintain strict qualification requirements for in-process measurement.
- Optical Probes:Laser-triangulation and chromatic confocal sensors preserve delicate surfaces in semiconductor wafer machining and medical device fabrication. FDA device manufacturing regulations in the United States and Swissmedic requirements in Switzerland drive premium positioning for non-contact systems in implantable component production.
- Magnetic Probes:Inductive sensing elements suit ferrous workpiece inspection in heavy equipment manufacturing.
- Laser Probes:Line-laser and point-laser configurations enable high-speed surface scanning for die and mold verification.
Contact Probes retain the largest installed base. Optical Probes are climbing the fastest on semiconductor fabrication demand.
Technology:
Technology maturity curves diverge sharply, with analog systems approaching end-of-life replacement cycles while wireless architectures capture retrofit opportunities.
- Analog Technology:Voltage-based signal transmission through shielded cables remains prevalent in legacy CNC architectures from the 1990s. Japan's machine tool installed base sustains residual demand, though METI industrial standards increasingly favor digital interfaces for new unmanned machining installations.
- Digital Technology:DSP-based signal processing compresses measurement cycle times while expanding data bandwidth for real-time quality feedback. Germany's automotive suppliers lead adoption, integrating digital probes with MES systems for closed-loop process correction.
- Wireless Technology:Radio-wave transmission eliminates cable fatigue and spindle interference in five-axis machining centers.
- Infrared Technology:Optical data links suit cleanroom environments where radio-frequency emissions must be minimized.
Digital Technology carries the majority of new installations. Wireless Technology shows the steepest expansion trajectory as machine builders retrofit older architectures.
End User:
Customer type determines procurement complexity, with OEMs demanding system-level integration while machine shops prioritize standalone probe reliability.
- Manufacturers:Tier-one aerospace and automotive producers specify probe-to-software ecosystems with predictive maintenance capabilities. The United States concentrates demand among Boeing and Lockheed Martin suppliers, where FAA quality system requirements mandate traceable measurement data chains.
- Machine Shops:Independent job shops prioritize probe durability and rapid stylus replacement over advanced data analytics. India's emerging precision manufacturing sector under PLI scheme incentives drives cost-optimized demand for compact radio-wave systems.
- OEMs:Machine tool builders integrate probes as standard equipment on premium machining centers.
- Research Institutions:National laboratories and university manufacturing centers deploy specialized probes for process development and materials characterization.
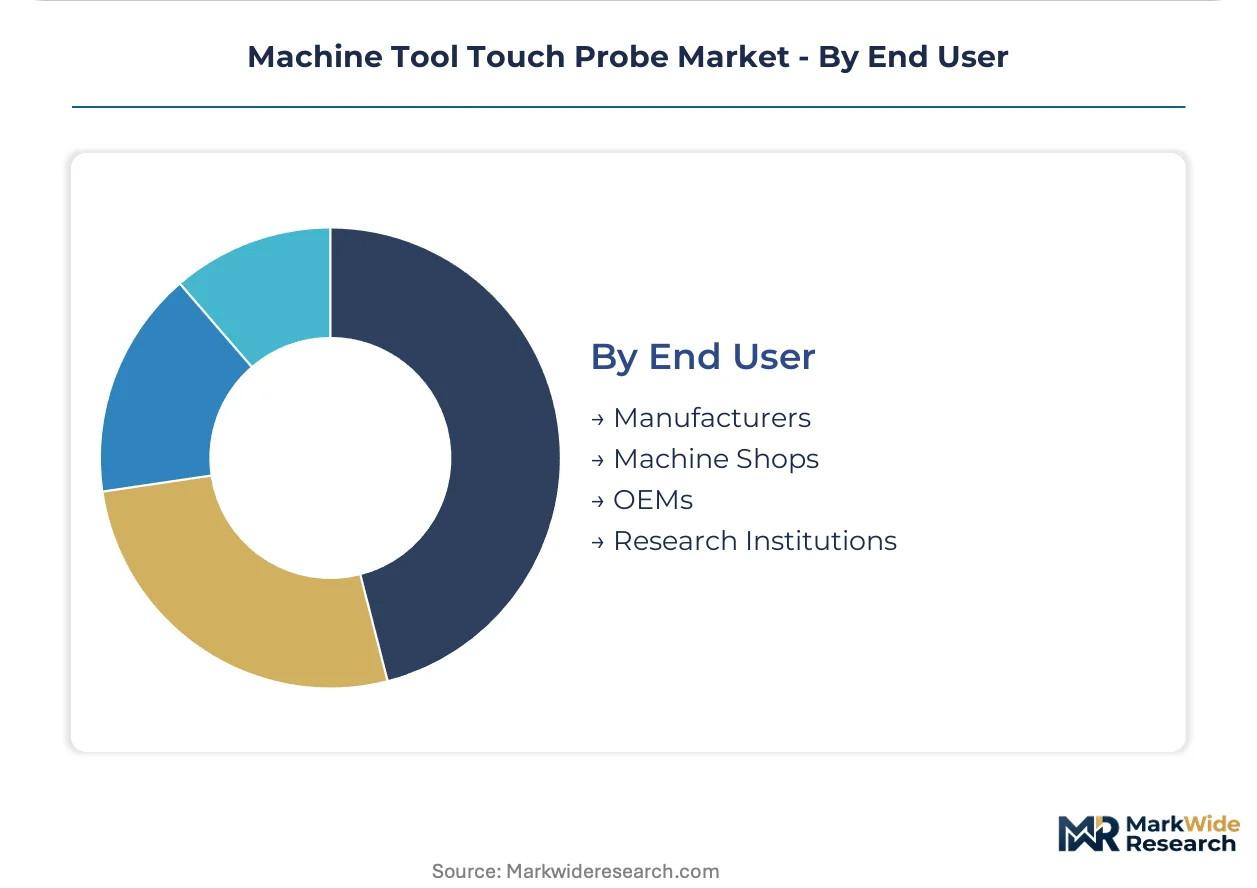
Manufacturers account for the largest procurement volume. Machine Shops are expanding most quickly in Asia-Pacific emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting probe procurement toward jurisdictions with calibrated compliance costs. Manufacturers are relocating precision machining capacity to exploit gaps between EU Machinery Directive stringency and emerging-market incentive structures.
Germany
KBA automotive certification and ISO 230 test code enforcement sustain replacement demand for certified probe systems. The EU Machinery Directive mandates in-process measurement safety upgrades across Baden-Württemberg precision clusters. Stuttgart's machine tool builders integrate wireless probe architectures as standard equipment on five-axis machining centers.
United States
FAA quality system requirements and FDA device manufacturing regulations drive traceable measurement data chains for Boeing and Lockheed Martin suppliers. Tier-one aerospace contractors in Seattle and Wichita deploy probe-to-software ecosystems with predictive maintenance capabilities. The Pacific Northwest concentrates unmanned machining cell deployment for titanium airframe components.
Japan
METI industrial standards and updated JIS calibration protocols accelerate probe replacement in unmanned machining operations. Aichi and Osaka prefectures host precision manufacturing clusters where digital signal processing architectures dominate new installations. Nagoya's automotive suppliers integrate digital probes with MES systems for closed-loop process correction.
India
PLI scheme production-linked incentives for advanced machine tools generate localized demand for cost-optimized probe systems. BIS standards alignment with ISO frameworks shapes supplier qualification requirements for precision manufacturing entrants. Gujarat and Maharashtra industrial corridors attract machine tool builders retrofitting older CNC architectures with wireless measurement systems.
China
GB standards and MIIT industrial policies segment probe compliance roadmaps by destination market for export-oriented manufacturers. Yangtze River Delta precision clusters sustain dominant demand for coolant-resistant contact probes in high-volume automotive lines. Shanghai's semiconductor fabrication facilities command premium positioning for non-contact optical probe systems.
Machine Tool Touch Probe Market Vendor Landscape
Technology licensing dominates the current landscape as incumbent suppliers reengineer signal transmission protocols for coolant-immersed environments. The vendor base concentrates around precision sensor specialists with captive piezoelectric element supply relationships. Two strategic archetypes define competitive positioning: integrated metrology-to-manufacturing software bridges, and compact hardware specialists for five-axis machining centers. M&A activity and portfolio diversification into digital twin integration represent the dominant competitive moves reshaping supplier relationships.
Among UK-based precision sensor specialists, Renishaw plc exemplifies the probe-to-software ecosystem archetype anchoring high-value aerospace contracts. Hexagon AB, a Swedish corporation, occupies a position within the metrology-to-manufacturing software bridge tier. Blum-Novotest GmbH represents the compact radio-wave probe specialization for five-axis machining centers, with its German GmbH structure signaling engineering-intensive product development.
| Leading Market Players |
|---|
| Renishaw plc |
| Hexagon AB |
| Blum-Novotest GmbH |
| Marposs S.p.A. |
| Heidenhain Corporation |
| Carl Zeiss Industrial Metrology |
| Mitutoyo Corporation |
| Keyence Corporation |
| Qidu Metrology |
| Others |
Supply Flow & Price Mechanics
Captive piezoelectric element production anchors competitive positioning for probe manufacturers in Germany and Japan, creating tiered pricing power that radiates from sensor component control through finished system assembly. This integration pattern compresses supplier margins for non-captive competitors while enabling premium positioning for ecosystem bundling in aerospace and medical device verticals.
Pricing Analysis
Distributor margins compress as machine builders unbundle after-sales service from hardware procurement, forcing probe suppliers to defend position through direct OEM relationships. Pricing stratifies across premium optical systems for semiconductor fabrication, standard digital probes for automotive lines, and economy contact units for emerging market machine shops. Cost compression in the economy tier stems from India's PLI scheme incentivizing localized production. Machine shops in Asia-Pacific emerging markets exhibit highest price sensitivity, while tier-one aerospace contractors prioritize traceability and predictive maintenance capabilities over unit cost.
Supply Chain Analysis
Piezoelectric crystal supply rests on Japanese specialty ceramic producers and German precision engineering clusters, creating input dependency for probe manufacturers outside these geographies. Critical components include ruby-ball styli, radio-frequency transmission modules, and digital signal processing chipsets. Single-source vulnerability concentrates in ceramic sensing elements subject to export control reviews. Distribution runs through machine tool OEM captive channels in mature markets and independent distributors in emerging precision manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The machine tool touch probe market functions as a stable compounder where regulatory-mandated replacement cycles in aerospace and automotive certification frameworks generate predictable demand visibility.
For Market Incumbents: Lock in aerospace tier-one contracts through probe-to-software ecosystem bundling that embeds predictive maintenance capabilities. Deepen backward integration into piezoelectric element supply to neutralize emerging Asian competitors. Defend against optical probe substitution in semiconductor verticals by accelerating infrared technology roadmaps. For New Entrants and Emerging Players: The gap between premium aerospace-grade systems and economy machine-shop units creates white-space opportunity in cost-optimized wireless probes for India's PLI scheme beneficiaries. Target Gujarat and Maharashtra industrial corridors with compact radio-wave architectures retrofittable to legacy CNC platforms. Pursue channel partnerships with German machine tool distributors seeking secondary sourcing options. For Investors and Strategic Acquirers: Roll-up economics work for compact hardware specialists with five-axis machining center expertise because calibration protocol fragmentation prevents rapid organic scaling. Five-to-ten year viability hinges on digital twin integration capabilities. Monitor probe data feed standardization efforts as inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Real-time probe data feeds into virtual machining simulations enable predictive tool wear revenue streams. |
| Wireless Architecture Retrofit | Radio-wave probe deployment on legacy CNC platforms captures replacement demand in Japan's precision clusters. |
| Optical Probe Convergence | Laser-triangulation sensors penetrate semiconductor fabrication where FDA and Swissmedic regulations mandate surface preservation. |
| Calibration Service Unbundling | Separate hardware and software subscription pricing fragments traditional supplier relationships in Germany's automotive ecosystem. |
| Piezoelectric Supply Security | Captive ceramic element production insulates margins from export control volatility affecting Japanese and German sources. |
Methodological Framework
Coverage spans Germany, Japan, the United States, India, and China, with primary inputs from each precision manufacturing cluster. The analysis combines interviews with CNC machining center procurement managers, aerospace quality system directors, machine tool OEM product planners, and metrology service technicians with secondary validation from METI industrial standards documentation, EU Machinery Directive compliance filings, FDA device manufacturing regulations, and ISO 230 test code publications. Bottom-up probe shipment data triangulates against top-down machine tool production statistics.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation dimensions modeled include application type, probe technology, end-user category, and regional regulatory framework. CAGRs derive from installed base replacement cycle analysis and new machine tool penetration assumptions. Industry-specific forecast inputs incorporate JIS calibration protocol updates and PLI scheme incentive trajectories.
Caveats apply where METI standards acceleration or EU AI Act algorithmic transparency mandates could materially shift the outlook. Forecasts reflect assumptions about wireless signal reliability in coolant-immersed environments and piezoelectric supply continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Jigs and Other Tools Market
Industrial Tools
Handheld DC Torque Tools Market
Industrial Tools
Die Grinders Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
Dies, Jigs and Other Tools Market
Industrial Tools
India Power Tool Market
Industrial Tools
Precision Components and Tooling Systems Market
Industrial Tools
Electric Tools Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Tool Holder Collets Market
Industrial Tools
Deburring Machine Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Digital Tool Presetter Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Global Tool Presetters Market
Industrial Tools
Coordinate Measuring Machine Market