
 Industrial Wire Stripping Machine Market | 2026-2036
Industrial Wire Stripping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Wire Stripping Machine Market Insights
Automation in wire processing is fragmenting legacy mechanical systems into modular, software-configurable platforms. Schleuniger leverages its Swiss engineering heritage to dominate high-precision medical and aerospace stripping applications. Komax sustains volume leadership through integrated harness production lines that extend from cutting to terminal crimping. Eraser competes in the North American maintenance and repair segment with benchtop units that occupy a defensible niche against larger system vendors.
An industrial wire stripping machine removes insulation from conductive cores with blade tolerances typically between 0.01 mm and 0.1 mm, depending on conductor gauge and insulation material, serving the essential preparatory step in electrical harness and cable assembly. Automatic machines lead the product type category in revenue terms, while portable units represent the fastest-growing configuration for field service and MRO operations. Electric technology dominates new equipment sales, though pneumatic systems retain share in heavy-gauge industrial environments where hydraulic force would damage sensitive conductors.
CE marking under the EU Machinery Directive governs equipment safety and electromagnetic compatibility for machines sold across Europe, while OSHA electrical safety standards shape workplace deployment requirements in the United States. China's SAMR enforces GB standards on mechanical equipment that constrain import specifications for foreign-built stripping systems. Stakeholders must monitor how evolving EV battery pack wiring standards in multiple jurisdictions will redefine acceptable strip length precision and conductor surface integrity thresholds.
Market Dynamics
EV powertrain assembly standards are forcing wire harness manufacturers to upgrade from mechanical stripping systems to precision-controlled platforms capable of maintaining 0.01 mm blade tolerances on high-voltage conductors.
Growth Catalysts
- EU RoHS Directive:Hazardous substance limits on wire insulation materials are compelling manufacturers to invest in stripping equipment compatible with halogen-free and bio-based compounds.
- EV Battery Pack Wiring:Electric vehicle OEMs in Germany, the United States, and China require strip length precision below 0.5 mm variance for high-current busbar connections.
- Medical Device Manufacturing:Miniaturized catheter and implantable device production in Switzerland and Massachusetts demands laser-guided stripping systems for micro-gauge conductors.
Market Restraints
- Specialized Carbide Blade Supply:Japanese and German suppliers dominate precision blade manufacturing, creating input cost volatility when yen-euro exchange rates fluctuate.
- GB Standards Compliance:China's SAMR mechanical equipment regulations impose testing and documentation burdens that extend import approval timelines for European and North American equipment vendors.
- Manual Benchtop Substitution:Low-volume job shops in maintenance and repair segments continue favoring hand-operated strippers for gauge-flexible operations, capping automatic system penetration.
Strategic Opportunities
- Field Service Robotics:Portable stripping units integrated with collaborative robot arms address MRO operations in offshore wind turbine nacelles and mining equipment.
- India PLI Scheme:Production-linked incentives for automotive component manufacturing are drawing wire harness suppliers to Chennai and Pune, creating demand for mid-range automatic strippers.
- CE-MDR Convergence:Medical device regulation harmonization with machinery safety standards enables single-certification equipment platforms serving both industrial and healthcare segments.
Industry Challenges
- Mechatronics Technician Scarcity:Maintenance of servo-driven stripping heads requires cross-trained personnel fluent in both mechanical calibration and PLC programming, a combination rarely found in traditional electrical trades.
- Legacy System Integration:Brownfield automotive plants running 1990s-era harness lines face control protocol mismatches when retrofitting Industry 4.0-capable stripping modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Wire Stripping Machine Market |
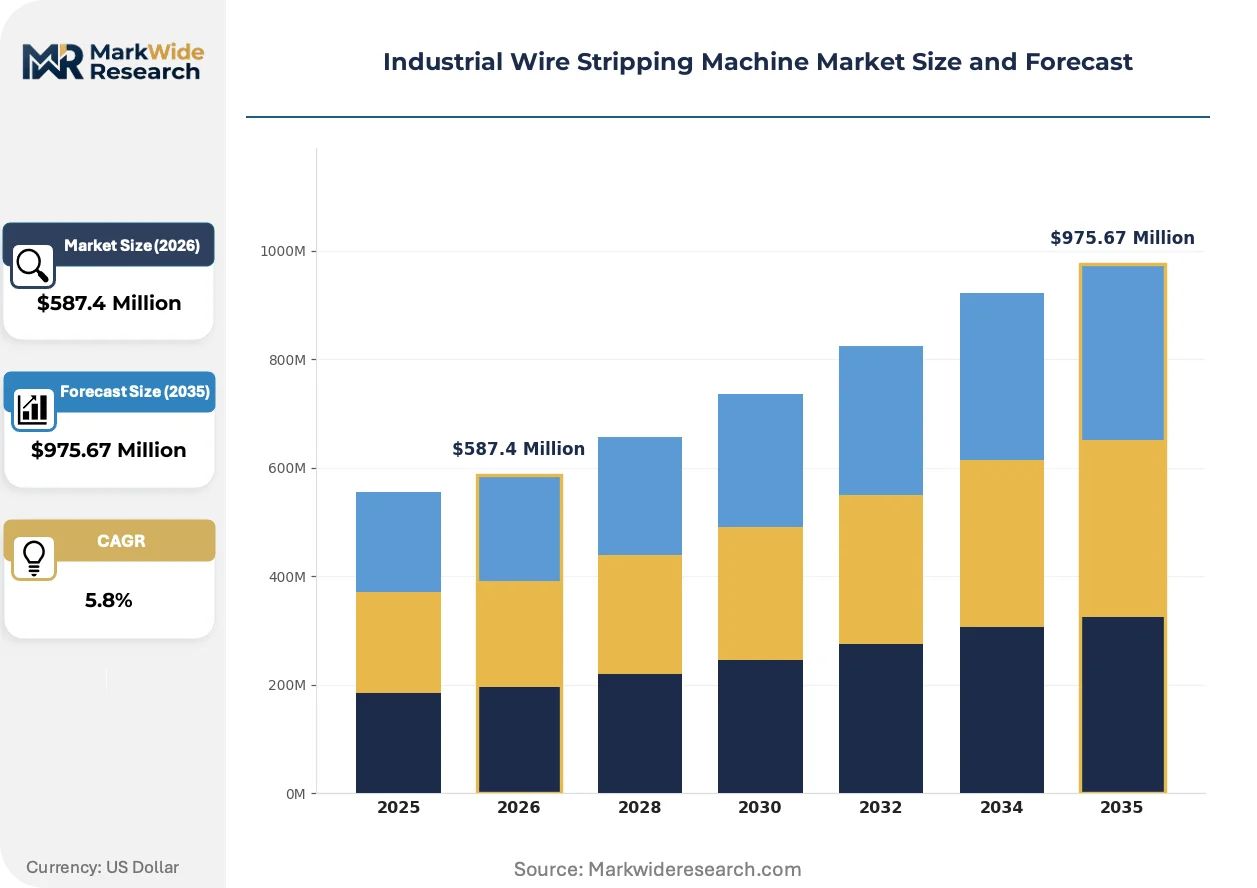
| Market Size in 2026 | $587.4 Million |
| Market Size in 2035 | $975.67 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Portable Technology: Pneumatic, Hydraulic, Electric, Mechanical Application: Telecommunications, Automotive Manufacturing, Electrical Distribution, Aerospace End User: Manufacturers, Contractors, Repair Shops, Wholesalers |
| Companies Covered | Schleuniger, Komax, Eraser, Kodera, MK Electronics, Artos Engineering, Carpenter Manufacturing Company, Machine Makers R.S., Metzner Maschinenbau, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Wire Stripping Machine Market Trends and Innovations
Laser and ultrasonic stripping technologies are collapsing the boundary between insulation removal and conductor surface preparation, eliminating secondary cleaning steps in high-reliability applications.
Vision-guided laser stripping is collapsing mechanical blade wear as a process variable. Aerospace harness manufacturers in France and California adopt these systems for PTFE-insulated silver-plated copper. The technology is collapsing rework rates on critical flight control cabling from percentages to single-digit basis points.
REACH substance restrictions on perfluorinated compounds are accelerating fluoropolymer insulation phase-outs in European medical device supply chains. Wire processors in Ireland and Germany retrofit thermal strippers for alternative high-temperature polymers. Equipment vendors respond with modular heating elements swappable between material chemistries.
Contract manufacturers now bundle stripping services with terminal crimping and 100% electrical testing under single-source agreements. Tier-2 automotive suppliers in Mexico and Eastern Europe prefer this consolidated procurement model over capital ownership. The shift compresses equipment sales cycles while expanding recurring revenue streams for integrated production line vendors.
Industrial Wire Stripping Machine Market Segmentation
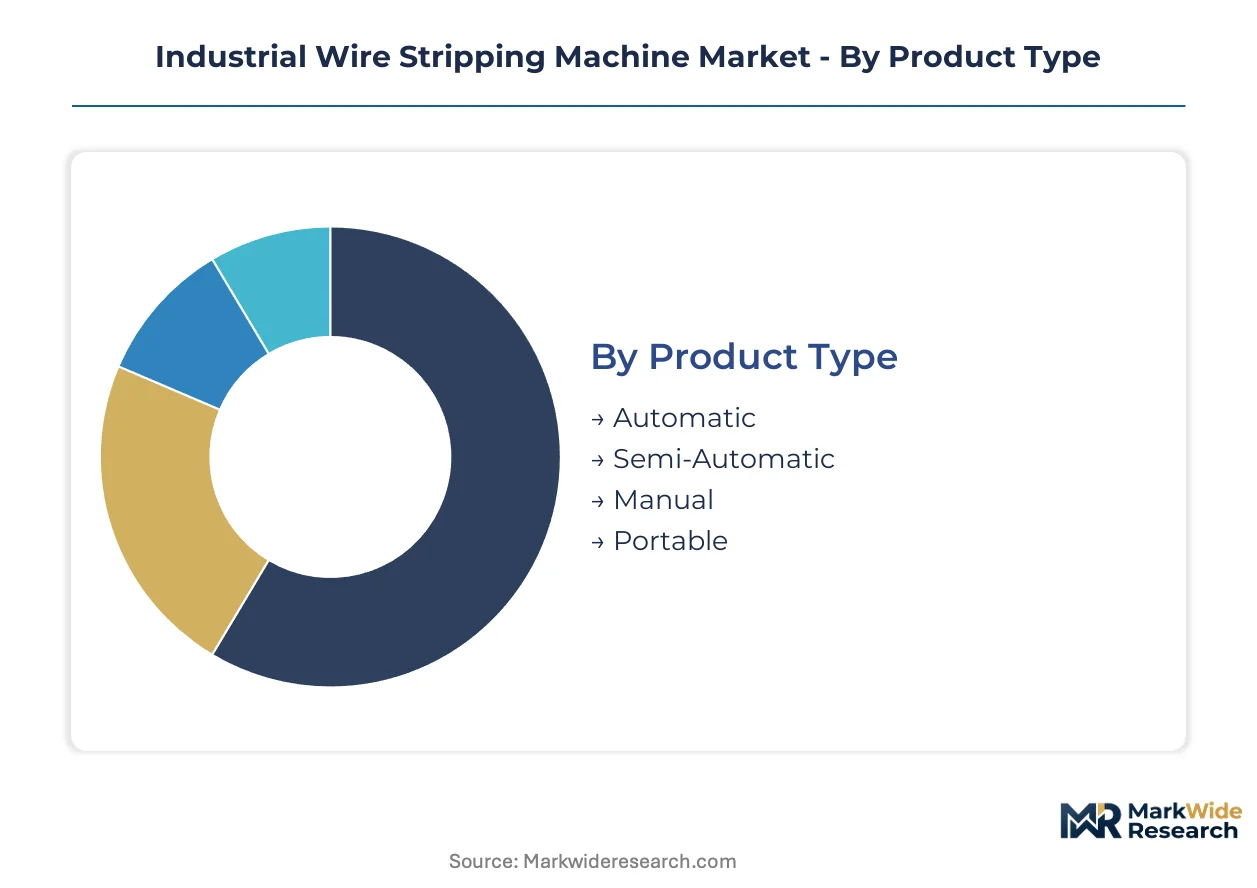
Wire stripping equipment segments by product type, technology, application, and end user reveal distinct replacement cycles and margin profiles. Procurement patterns diverge sharply between high-volume automotive lines requiring sub-0.5 mm precision and field service operations prioritizing portability over absolute accuracy.
Product Type:
Automatic machines turn over slowest with 7-10 year depreciation schedules, while portable units cycle fastest as battery and motor technology advances.
- Automatic:Servo-driven blade positioning systems maintain 0.01 mm tolerances across high-volume production shifts. Automotive harness manufacturers in Germany and the United States anchor demand as EV battery pack wiring standards tighten strip length variance requirements.
- Semi-Automatic:Operator-assisted feeding combines mechanical precision with gauge flexibility for mid-volume contract manufacturers. Mexico's tier-2 automotive suppliers favor these units for mixed-model production lines where lot sizes fluctuate.
- Manual:Hand-cranked benchtop units serve maintenance operations where capital constraints outweigh throughput needs. Repair shops in Eastern Europe and Southeast Asia sustain this segment despite automatic system price erosion.
- Portable:Battery-powered field units with interchangeable blade cartridges address wind turbine nacelle maintenance and mining equipment repair. Collaborative robot arm integration is expanding deployment into hazardous access environments.
Automatic machines dominate installed base. Portable units are where expansion concentrates.
Technology:
Cost tiers separate legacy mechanical systems from precision electric platforms, with pneumatic systems occupying a mid-market position for heavy-gauge applications.
- Electric:Brushless servo motors with closed-loop position feedback deliver programmable blade force curves for delicate conductor materials. Medical device manufacturers in Switzerland and Massachusetts specify these systems for micro-gauge catheter production.
- Pneumatic:Compressed air actuation generates high instantaneous force for armored cable and industrial power conductors without hydraulic fluid contamination risk. Heavy equipment OEMs in China retain these systems for construction machinery harness assembly.
- Hydraulic:Fluid power systems process extra-high-tension transmission cables where mechanical advantage exceeds electric motor torque density. Utility infrastructure contractors in the United States deploy these for grid modernization projects.
- Mechanical:Cam-driven blade mechanisms with fixed stroke lengths serve lowest-cost benchtop applications. Price-sensitive procurement in India's emerging automotive supplier belt sustains residual demand.
Electric technology commands premium pricing. Pneumatic systems retain defensive share in heavy-gauge niches.
Application:
Volume concentration varies dramatically, with automotive manufacturing absorbing multiple units per production line while aerospace accepts single-unit qualification cycles lasting 18-24 months.
- Automotive Manufacturing:Integrated harness production lines demand stripping-to-crimping modules with 100% electrical testing verification. EV powertrain assembly standards in Germany, the United States, and China are forcing upgrades from mechanical to precision-controlled platforms.
- Telecommunications:Fiber optic and copper data cable processing requires specialized jacket slitting without conductor nicking. 5G infrastructure deployment in South Korea and Japan is driving demand for mid-range automatic units.
- Aerospace:PTFE-insulated silver-plated copper conductors mandate laser or thermal stripping to preserve surface integrity. French and California harness manufacturers adopt vision-guided systems to collapse rework rates.
- Electrical Distribution:Utility-grade cable processing spans residential wiring to high-voltage transmission conductors. Grid interconnection projects in Texas and Australia's renewable zones sustain regional equipment demand.
Automotive Manufacturing dominates installed base. Aerospace is climbing the fastest.
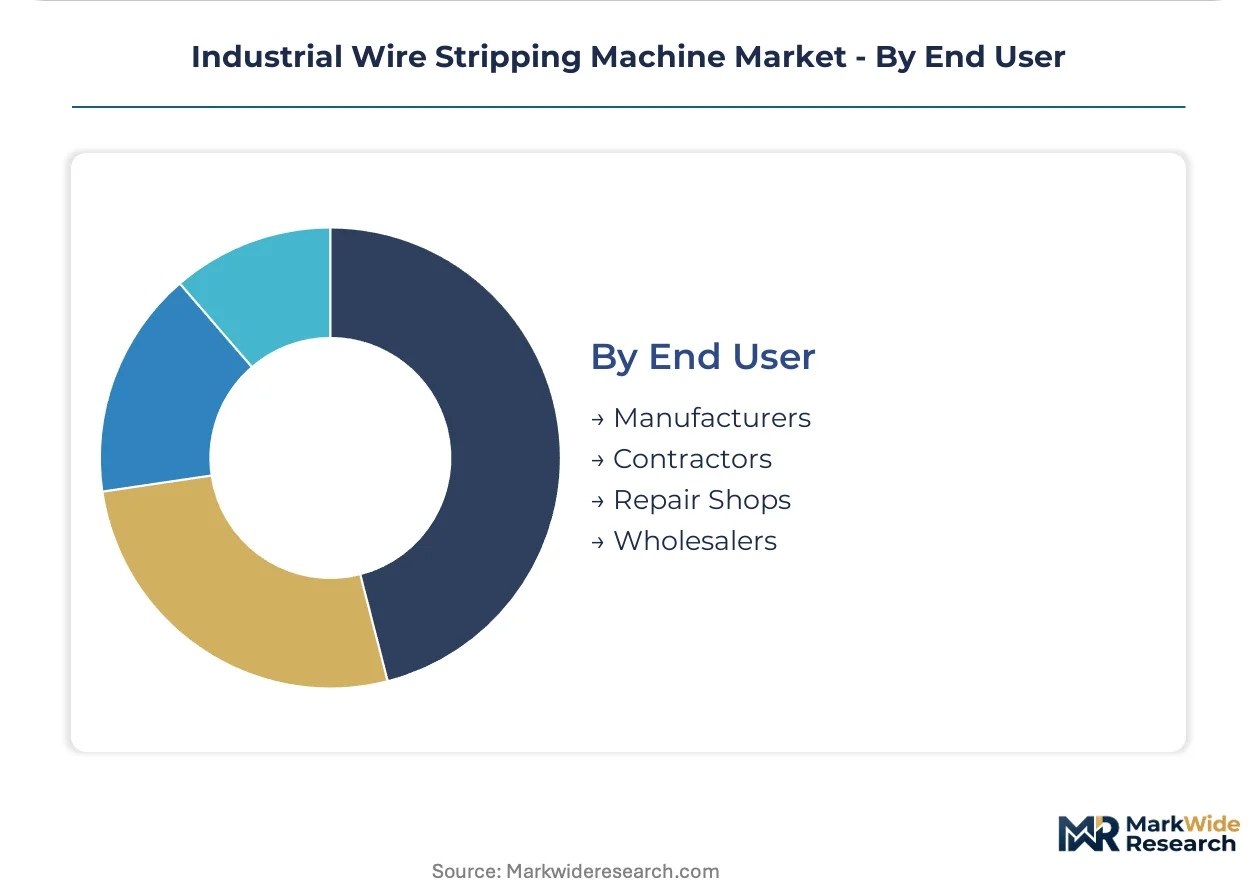
End User:
Customer type determines procurement modality, with manufacturers favoring capital ownership and contractors increasingly preferring service bundling.
- Manufacturers:OEM and tier-1 harness producers operate captive stripping capacity with dedicated maintenance teams. Schleuniger and Komax anchor integrated production line sales to this segment.
- Contractors:Electrical installation and infrastructure firms source stripping services through equipment-as-a-subscription models. Mexico and Eastern European contract manufacturers prefer consolidated procurement over capital ownership.
- Repair Shops:Independent maintenance operations prioritize gauge-flexible benchtop units for intermittent use. Eraser competes in this North American segment with defensible niche positioning.
- Wholesalers:Distributor networks stock portable and manual units for same-day fulfillment to construction and industrial maintenance accounts. Inventory turns fastest in this channel.
Manufacturers dominate installed base. Contractors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision wire processing equipment to automotive assembly plants across the United States and China, sustaining trade corridors that shape regional demand patterns for stripping machinery.
United States
EV battery pack wiring standards from NHTSA and OEM procurement specifications drive demand for 0.01 mm tolerance systems. OSHA electrical safety standards govern workplace deployment requirements for automated harness lines. Michigan and South Carolina automotive supplier belts anchor production clusters where tier-1 harness manufacturers retrofit legacy mechanical systems.
Germany
Continental OEMs in Bavaria and Baden-Württemberg mandate RoHS-compliant halogen-free insulation processing for powertrain assemblies. CE marking under the EU Machinery Directive constrains equipment import specifications from non-European vendors. The automotive supplier belt around Stuttgart and Munich concentrates Schleuniger and Komax manufacturing clusters serving continental EV production lines.
China
Domestic EV OEMs in Shanghai and Shenzhen enforce GB standards on high-voltage conductor surface integrity that exceed legacy mechanical stripping capabilities. SAMR mechanical equipment regulations impose extended testing timelines on European and North American equipment imports. The Yangtze River Delta wire harness manufacturing corridor absorbs mid-range automatic strippers under localization mandates.
Switzerland
Medical device manufacturers in the Zurich-Basel corridor demand laser-guided stripping systems for micro-gauge catheter production. Swissmedic harmonization with EU MDR enables single-certification equipment platforms serving both industrial and healthcare segments. Precision engineering clusters around Solothurn anchor high-margin stripping system development for aerospace and implantable device applications.
India
PLI scheme incentives for automotive component manufacturing draw wire harness suppliers to Chennai and Pune manufacturing corridors. BIS mechanical equipment standards create compliance thresholds for imported European stripping systems. Tamil Nadu and Maharashtra supplier parks generate demand for mid-range automatic strippers as tier-2 producers scale EV-compatible harness capacity.
Industrial Wire Stripping Machine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates around integrated production line vendors and precision component suppliers. The vendor base organizes into three tiers: Swiss-German precision engineering houses, Japanese specialist manufacturers, and North American maintenance-focused suppliers. Dominant competitive moves include strategic partnerships between equipment vendors and automotive tier-1 suppliers, plus geographic expansion through localized assembly operations in Mexico and Eastern Europe.
Among Swiss-German precision engineering houses, Schleuniger AG and Komax Holding AG exemplify the integrated production line archetype, while Eraser Company anchors the North American maintenance and repair segment. Kodera Electric Co., Ltd. occupies a position within the Japanese specialist tier focused on high-volume automotive applications. These three named entities represent distinct strategic postures: precision-dominated medical-aerospace positioning, volume-leadership through harness line integration, and defensible niche defense in field service portability.
| Leading Market Players |
|---|
| Schleuniger |
| Komax |
| Eraser |
| Kodera |
| MK Electronics |
| Artos Engineering |
| Carpenter Manufacturing Company |
| Machine Makers R.S. |
| Metzner Maschinenbau |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's mid-range automatic stripper segment is compressing margins for European equipment vendors while forcing Japanese and German suppliers toward premium positioning. Utilization rates below 70% in Yangtze River Delta assembly plants trigger aggressive pricing on standardized units, whereas Swiss precision manufacturers maintain pricing power through medical-grade certification tiers.
Pricing Analysis
Current-generation electric servo systems command 40-60% premiums over prior-generation pneumatic platforms, while next-generation laser stripping systems occupy a separate pricing tier entirely. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified medical-grade equipment from industrial automatic units and Chinese-manufactured mechanical benchtop systems. Cost compression in the standard tier is intensifying because of localized assembly in Mexico and Eastern Europe eroding European import premiums. Contract manufacturers in Mexico exhibit the highest price sensitivity, while Swiss medical device OEMs demonstrate the lowest due to regulatory compliance requirements.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement relationships between automotive tier-1 suppliers and equipment vendors, straining working capital for mid-tier manufacturers. Precision carbide blade manufacturing concentrates in Japan and Germany, while servo motor and control system assembly draws from China and Taiwan. Specialized ceramic blade coatings hinge on single-source suppliers in the Nagoya industrial corridor, creating tariff exposure from yen-denominated input contracts. Distribution runs through authorized dealer networks in mature markets and direct OEM relationships in emerging automotive supplier belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortages of mechatronics technicians capable of maintaining servo-driven stripping heads constrain equipment utilization rates across automotive harness lines. This capability gap creates asymmetric returns for vendors investing in predictive maintenance software and remote diagnostics platforms.
For Market Incumbents: Pre-empt commoditization in mid-range automatic strippers by embedding Industry 4.0 connectivity as standard rather than optional, forcing smaller competitors into unsustainable R&D cost structures. Backward integration into precision blade manufacturing through partnerships with Japanese carbide suppliers defends margin position against yen volatility. CE-MDR convergence certification investment creates switching costs for medical device customers evaluating multi-application equipment platforms. For New Entrants and Emerging Players: Portable stripping units for offshore wind turbine maintenance represent the most penetrable entry point, as incumbent vendors underinvest in battery-powered field configurations. India's PLI scheme corridors around Chennai and Pune offer second-mover advantages for mid-range automatic strippers with localized assembly partnerships. Go-to-market execution should target electrical contractors through equipment-as-a-subscription models rather than capital sales, mirroring Mexican and Eastern European procurement preferences. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable and collaborative robot-integrated stripping segments as battery and sensor costs decline. Long-term viability favors vendors with software-defined control architectures capable of remote material recipe updates. Acquisition targets should display captive blade supply relationships or proprietary vision-guidance IP. The signal to watch is EV OEM strip length tolerance specification tightening below 0.3 mm variance, which would obsolete mechanical systems faster than replacement cycles suggest.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Stripping Technology Adoption | Aerospace harness manufacturers in France and California collapse rework rates on PTFE-insulated conductors. |
| Backward Integration into Blade Manufacturing | Swiss-German precision houses secure supply against yen-euro exchange volatility and Japanese supplier concentration. |
| CE-MDR Convergence Certification | Single-certification equipment platforms capture medical device demand in Switzerland and Massachusetts clusters. |
| Collaborative Robot Arm Integration | Portable units penetrate hazardous access environments in offshore wind turbine nacelles and mining equipment. |
| Localized Assembly in Mexico | Mid-range automatic strippers serve tier-2 automotive suppliers under consolidated procurement agreements. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with industry stakeholders and secondary validation across regulatory and trade databases. Plant engineers at German and US automotive harness manufacturers, procurement leads at Swiss medical device OEMs, aftermarket service heads at North American maintenance operations, and OEM platform engineers at Chinese EV producers provided operational perspective. Secondary sources included EU Machinery Directive compliance filings, SAMR GB standard registration databases, USITC trade flow records, and SEC 10-K equipment vendor disclosures. Bottom-up equipment unit economics triangulated against top-down end-use industry demand estimates.
Forecast inputs considered technology substitution curves, regulatory compliance timeline acceleration, and regional automotive production cluster expansion across the analysis window. Segmentation dimensions modeled include product type, actuation technology, end-use application, and customer procurement modality. CAGRs derived from equipment replacement cycle analysis and EV powertrain wiring standard evolution. Industry-specific inputs encompassed EV battery pack wiring tolerance specification trajectories and REACH substance restriction phase-out schedules affecting insulation material compatibility.
Practitioners should monitor EV OEM strip length precision requirements, REACH fluoropolymer restriction enforcement, and mechatronics technician training pipeline capacity for early signals of forecast deviation. Macroeconomic contraction in automotive capital expenditure, regulatory delay in CE-MDR harmonization, or breakthrough in solid-state battery architecture eliminating high-voltage harness complexity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
Dies, Jigs and Other Tools Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Height Gauge Market
Industrial Tools
Centerless Grinding Market
Industrial Tools
Die Grinders Market
Industrial Tools
Jigs and Other Tools Market
Industrial Tools
Deburring Machine Market
Industrial Tools
Saudi Arabia Power Tools Market
Industrial Tools
India Power Tool Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
Micro Welders Market
Industrial Tools
Machine Tool Touch Probe Market
Industrial Tools
Coordinate Measuring Machine Market
Industrial Tools
Tool Holder Collets Market
Industrial Tools
Digital Tool Presetter Market