
 Tool Holder Market | 2026-2036
Tool Holder Market Size, Share, and Industry Trends Forecast 2026-2036
Tool Holder Market Outlook
Modular quick-change tooling configurations are restructuring buyer procurement patterns across precision machining operations. Sandvik Coromant leverages integrated adapter systems to anchor its position in high-speed milling applications. Haimer GmbH specializes in balancing technology and shrink-fit innovation to differentiate its portfolio from conventional tapered offerings.
A tool holder is a mechanical interface device, typically incorporating HSK, BT, or ISO taper geometries with runout tolerances below 0.003 mm, that secures cutting tools to machine tool spindles for rotational machining operations. Collet chucks and shrink-fit holders command premium positioning in CNC machining due to superior gripping force and minimal tool deflection at elevated spindle speeds. Tapered holders retain volume dominance across metal cutting applications where standardization and cost efficiency outweigh precision demands.
ISO standards for tool taper interfaces, Germany's DIN 69893 specifications for hollow taper shanks, and Japan's JIS B 6339 framework collectively govern dimensional interchangeability and safety certification for cross-border equipment supply. These standards compel manufacturers to maintain multi-certification production lines and restrict market access for non-compliant suppliers. Stakeholders must evaluate taper standard migration paths and shrink-fit technology investments against evolving spindle speed requirements in next-generation machining centers.
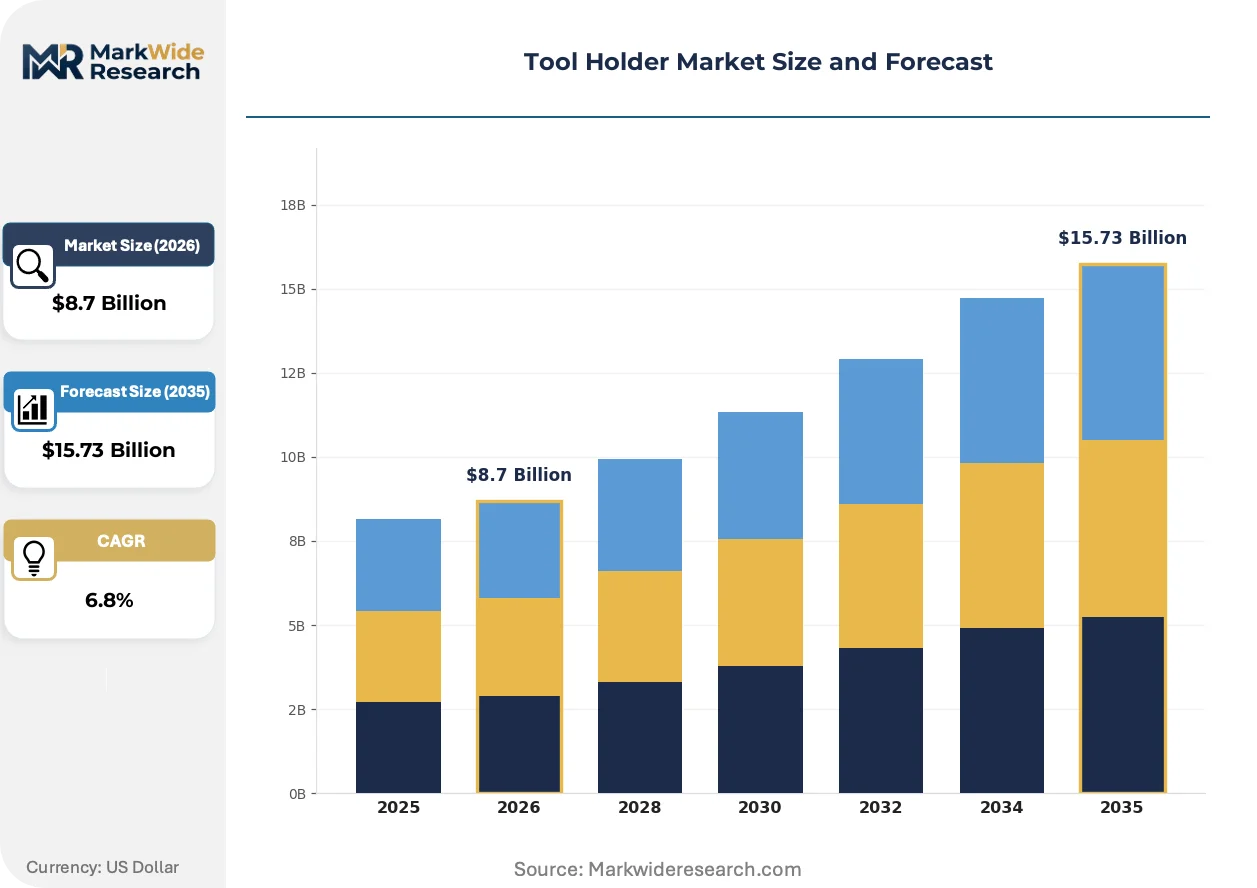
Market Dynamics
ISO 26623 polygonal taper standards are forcing simultaneous retooling across multi-certification production lines, compressing interoperability margins for suppliers while aerospace manufacturers accelerate titanium machining procurement cycles.
Growth Catalysts
- HSK hollow taper adoption:Machine tool builders in Germany are specifying HSK 63A and HSK 100A interfaces for five-axis machining centers, pulling demand for precision-balanced holder systems.
- Japan's JIS B 6339 framework:Mandatory spindle interface certification for imported equipment is standardizing taper geometries across Southeast Asian supply chains.
- Titanium aerospace component machining:Airframe manufacturers require shrink-fit holders capable of 40,000+ RPM operation with sub-0.003 mm runout for heat-resistant alloy finishing.
Market Restraints
- High-speed steel and carbide input volatility:Tool holder body material costs fluctuate with tungsten and cobalt spot pricing, compressing margin stability for mid-tier suppliers.
- Precision grinding equipment concentration:Germany and Switzerland control 80% of specialized taper grinding machine production, creating supply bottlenecks for new market entrants.
- Multi-standard certification overhead:Simultaneous DIN 69893, ISO 12164, and JIS compliance requires redundant testing protocols that extend product launch timelines.
Strategic Opportunities
- Indian precision manufacturing expansion:BIS certification alignment with ISO taper standards is opening domestic production incentives for localized tool holder assembly.
- Smart holder sensor integration:Embedded RFID and vibration monitoring chips are converging with shrink-fit bodies to enable predictive tool life management.
- Remanufacturing service channels:Industrial distributors are adding precision regrind and rebalancing services to capture aftermarket revenue from high-value hydraulic holder installed bases.
Industry Challenges
- Metrology technician scarcity:Taper geometry measurement and dynamic balancing expertise is concentrating among aging workforces in Stuttgart and Nagoya manufacturing clusters.
- Legacy BT taper integration friction:Machine shops with substantial BT40 and BT50 spindle investments face capital-intensive migration paths to polygonal taper interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tool Holder Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collet Chucks, Face Mill Holders, Tapered Holders, Tool Holders with Shrink Fit Material: Steel, Aluminum, Carbon Fiber, Titanium Application: CNC Machining, Metal Cutting, Woodworking, Assembly Operations End User: Manufacturing, Aerospace, Automotive, Electronics |
| Companies Covered | Guhring, Iscar, Sandvik Coromant, CERATIZIT, Schunk GmbH & Co. KG, Kennametal, BIG KAISER Precision Tooling, Collis Toolholder Corp., Haimer GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tool Holder Market Strategic Shifts
Active cooling channels, embedded condition monitoring, and polygonal taper geometries are restructuring competitive differentiation in precision metal cutting interfaces.
Shrink-fit induction heating systems with integrated cooling circuits are extending thermal stability during high-speed aluminum and titanium machining. Tier-one automotive powertrain suppliers in southern Germany are specifying these configurations for electric vehicle motor housing production. The technology is converging with five-axis machine tool architectures to eliminate tool change thermal drift compensation cycles.
REACH substance restrictions on hexavalent chromium coatings are compelling surface treatment migration to DLC and TiAlN alternatives. Holder manufacturers serving European aerospace tier suppliers face coating process requalification timelines. DIN 69893-compliant hydraulic holders with alternative surface finishes are capturing specification share in Toulouse and Hamburg supply chains.
Consolidated procurement through integrated machine tool and holder package contracts is displacing standalone tool holder distributor relationships. Large-scale automotive stamping and powertrain operations in Detroit and Wolfsburg are negotiating single-source spindle-to-cutting-edge agreements. This concentration is most visible in high-volume electric vehicle battery tray machining contracts where runout consistency penalties exceed equipment cost differentials.
Tool Holder Market Segmentation
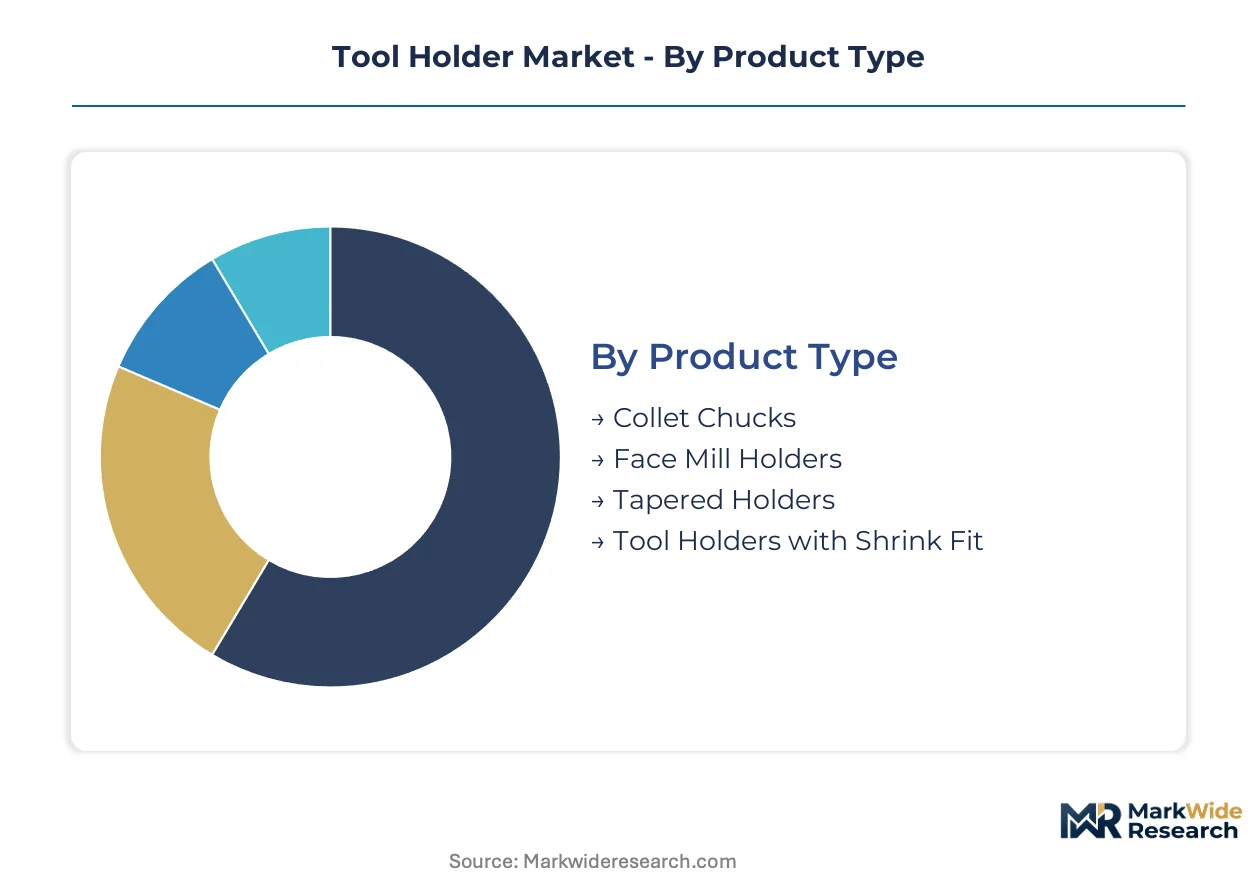
Tool holder segmentation reveals how upgrade cycles and precision requirements fragment procurement across metalworking operations. Replacement timelines for taper interfaces diverge sharply between high-volume automotive lines and low-volume aerospace finishing cells.
Product Type:
Upgrade cycles for precision tool holders accelerate as spindle speeds climb and thermal stability requirements tighten across machining centers.
- Tool Holders with Shrink Fit:These systems use induction heating to expand precision-ground bores for tool insertion, achieving gripping forces exceeding collet alternatives. Aerospace manufacturers in Hamburg and Toulouse specify shrink-fit configurations for titanium turbine blade finishing at 40,000 RPM where runout tolerance falls below 0.003 mm.
- Collet Chucks:Spring-steel collet mechanisms deliver rapid tool change capability with moderate gripping force for general-purpose CNC applications. German automotive powertrain suppliers favor HSK-integrated collet systems for electric motor housing production where changeover frequency exceeds 50 cycles per shift.
- Face Mill Holders:Rigid flange-mount interfaces secure large-diameter indexable cutters for heavy roughing operations.
- Tapered Holders:Conventional BT and ISO taper geometries retain installed base dominance in cost-sensitive metal cutting applications.
Shrink-fit configurations sit at the top of the volume ranking, with tool holders with shrink fit climbing the fastest as five-axis machining centers proliferate.
Material:
Material selection for tool holder bodies follows a cost-precision tradeoff curve that separates commodity metal cutting from aerospace finishing specifications.
- Steel:Alloy and tool steel compositions deliver the stiffness-to-cost ratio that dominates standard CNC machining applications. Japanese machine tool builders specify DIN 69893-compliant steel holders for domestic automotive transmission production where damping characteristics outweigh weight considerations.
- Titanium:Beta-titanium alloys reduce rotating mass for high-acceleration spindle applications while maintaining thermal stability. US aerospace tier suppliers in Connecticut and Arizona procure titanium-bodied holders for aluminum airframe skin machining where rapid direction changes demand minimal inertial load.
- Aluminum:Lightweight extrusions and forgings serve wood routing and non-ferrous machining where centrifugal force limits dominate.
- Carbon Fiber:Composite-reinforced polymer bodies target ultra-high-speed finishing where vibration damping and mass reduction converge.
Steel commands the largest installed base, though titanium gains share fastest in spindle speed escalation segments.
Application:
Application-driven segmentation maps directly to machine tool architecture choices and the precision-grade requirements of finished workpieces.
- CNC Machining:Computer-numerical-control applications span milling, turning, and grinding centers where automated tool change systems demand standardized taper interfaces. German and Japanese machine tool OEMs bundle HSK-certified holder packages with five-axis vertical machining centers sold into medical device manufacturing clusters.
- Metal Cutting:Dedicated turning and milling operations with indexable inserts require rigid clamping systems for interrupted cuts. US Midwestern job shops specify hydraulic holders for stainless steel pump housing production where chatter suppression determines surface finish compliance.
- Woodworking:Router spindle applications prioritize rapid collet change and dust-sealed bearings over micron-level precision.
- Assembly Operations:Torque-controlled fastening and drilling stations integrate quick-change taper interfaces for mixed-model production lines.
CNC machining leads application volume, with metal cutting expanding most quickly in reshoring-driven capital equipment cycles.
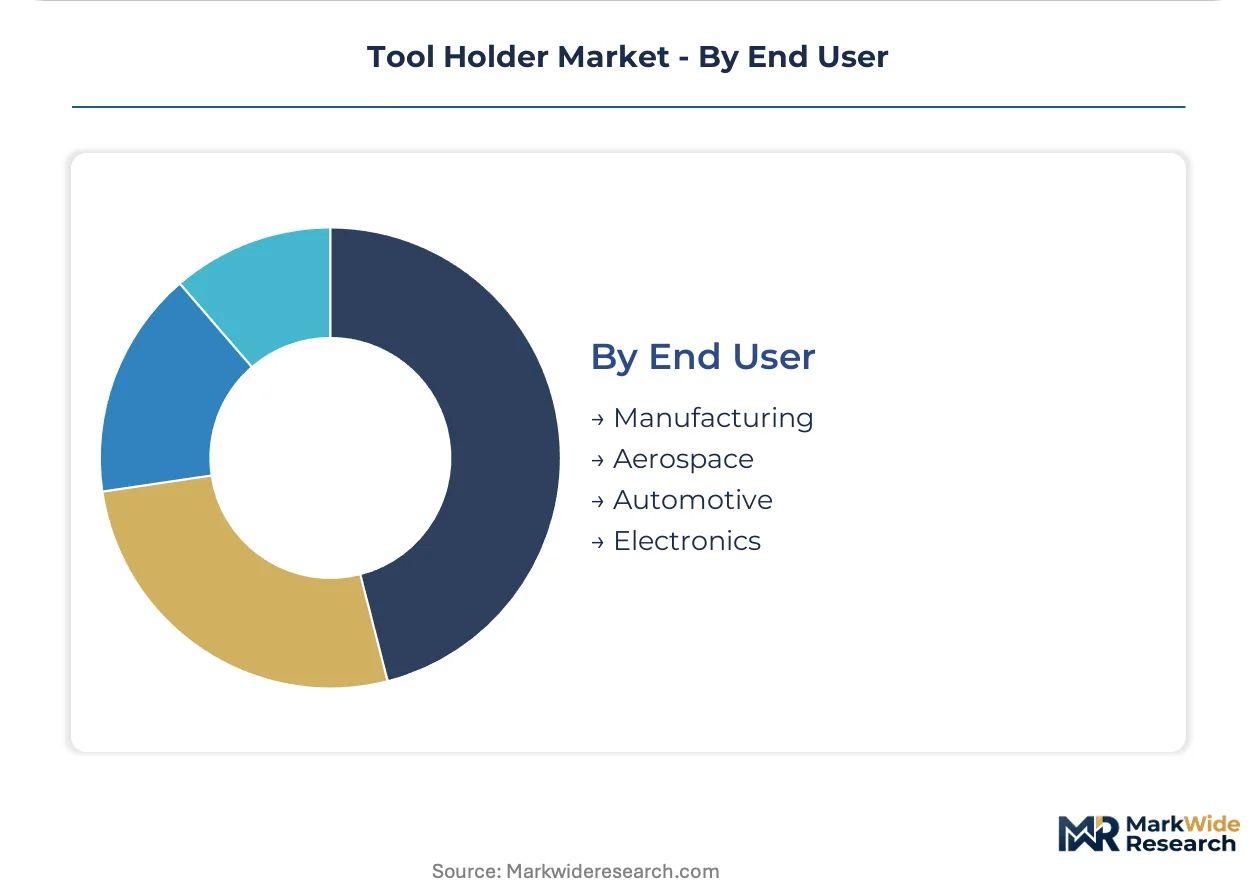
End User:
End-user segmentation concentrates procurement authority and specification influence among capital-intensive manufacturing sectors with multi-year machine tool investment horizons.
- Aerospace:Airframe and engine manufacturers impose sub-0.003 mm runout specifications for heat-resistant alloy machining. Toulouse and Hamburg supply chains mandate DIN 69893 polygonal taper compliance for shrink-fit holders used in titanium structural component finishing.
- Automotive:Powertrain and electric vehicle battery tray production demands high-volume tool change reliability with minimal spindle downtime. Wolfsburg and Detroit stamping operations negotiate single-source spindle-to-cutting-edge contracts that consolidate holder procurement with machine tool purchases.
- Manufacturing:General industrial machinery and contract machining operations span precision grades from job-shop collet systems to production hydraulic holders.
- Electronics:Miniature component machining and semiconductor equipment fabrication require specialized micro-tool holding with sub-micron repeatability.
Automotive anchors end-user volume, with aerospace posting the steepest specification escalation trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered hollow taper shank technology in the 1990s, establishing the technical foundation that now governs precision machining interfaces worldwide. This industrial lineage continues to shape procurement patterns across major manufacturing economies.
Germany
HSK hollow taper specifications from DIN 69893 drive machine tool builder procurement across Bavaria and Baden-Württemberg. The KBA enforces spindle interface safety certification for automotive production equipment. Stuttgart manufacturing clusters specify shrink-fit holders for electric motor housing machining at 40,000 RPM.
United States
Aerospace tier suppliers in Connecticut and Arizona demand titanium-bodied holders for aluminum airframe skin machining with rapid spindle acceleration. The FAA coordinates with equipment standards for airframe manufacturing processes. Hartford precision machining corridors anchor shrink-fit system specification for heat-resistant alloy finishing.
Japan
METI-administered JIS B 6339 framework standardizes taper geometries across domestic and Southeast Asian supply chains. Nagoya automotive powertrain operations favor HSK-integrated collet systems for high-frequency tool change environments. Chubu region machine tool builders bundle certified holder packages with five-axis vertical machining centers.
China
MIIT promotes GB standard alignment with ISO taper interfaces for domestic CNC equipment production. Yangtze River Delta manufacturing bases expand procurement of hydraulic holders for stainless steel component machining. Shanghai precision equipment distributors consolidate remanufacturing service channels for high-value installed bases.
India
BIS certification alignment with ISO standards opens domestic production incentives for localized tool holder assembly. Maharashtra and Gujarat industrial corridors attract tier suppliers for automotive and general machining applications. Pune manufacturing clusters specify steel-bodied holders for cost-sensitive CNC transmission production.
Tool Holder Market Competitive Environment
Premium-margin players sit above commodity-margin players across precision balancing and thermal stability performance tiers. The vendor base stratifies into three concentration levels: integrated machine tool bundlers, specialized holder manufacturers, and regional fabrication shops. Strategic archetypes include DIN 69893 certification specialists, shrink-fit technology developers, and automotive contract consolidators. Dominant competitive moves encompass precision grinding capacity expansion and integrated spindle-to-holder package contracting.
Within the certification-specialist tier, Guhring and Iscar exemplify European precision tooling archetypes. Sandvik Coromant anchors the integrated bundler position through machine tool OEM partnerships. Haimer GmbH occupies a distinctive niche among German GmbH-structured specialists focusing on balancing technology differentiation.
| Leading Market Players |
|---|
| Guhring |
| Iscar |
| Sandvik Coromant |
| CERATIZIT |
| Schunk GmbH & Co. KG |
| Kennametal |
| BIG KAISER Precision Tooling |
| Collis Toolholder Corp. |
| Haimer GmbH |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions on hexavalent chromium coatings gate qualified supply access and premium-tier pricing power for European aerospace tier suppliers, forcing coating process requalification timelines that separate DIN 69893-compliant hydraulic holders from commodity alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates DIN 69893-certified shrink-fit systems from HSK-integrated collet configurations and conventional BT taper holders. Price differentiation hinges on certification grade and precision balancing capability, with sub-0.003 mm runout specifications commanding substantial premiums. Pricing pressure stems from tungsten and cobalt spot pricing volatility compressing margin stability for mid-tier suppliers. Automotive powertrain buyers in Wolfsburg and Detroit exhibit lowest price sensitivity due to runout consistency penalties exceeding equipment cost differentials, while Indian job shops in Pune remain most cost-conscious.
Supply Chain Analysis
Freight cost escalation for precision-ground taper components from Stuttgart and Nagoya manufacturing clusters amplifies landed cost differentials against regional assembly operations in Maharashtra and Gujarat. Supply concentration rests on Germany, Japan, and Switzerland for specialized taper grinding equipment and metrology expertise. Raw material dependencies center on high-speed steel alloys, beta-titanium bar stock, and cobalt-chrome plating chemistries. Single-source vulnerability permeates the 80% concentration of precision grinding machine production in Central Europe. Distribution runs through integrated machine tool OEM bundlers and industrial distributors with remanufacturing service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Tool Holder Market functions as a stable compounder anchored by irreversible spindle speed escalation across five-axis machining center deployments, generating sustained replacement demand for precision-balanced holder systems.
For Market Incumbents: To counter embedded sensor integration by smart holder specialists, Sandvik Coromant and Haimer GmbH should deepen backward integration into induction heating system production and expand precision grinding capacity in Baden-Württemberg. Certification maintenance across simultaneous DIN 69893, ISO 12164, and JIS compliance protocols remains essential for aerospace contract retention. For New Entrants and Emerging Players: Active cooling channel technology offers entry traction into thermal stability-sensitive aluminum and titanium machining segments underserved by legacy hydraulic holder portfolios. White-space concentration appears in Indian BIS-certified localized assembly for automotive transmission production and embedded RFID condition monitoring for predictive tool life management. Channel partnership with Yangtze River Delta machine tool distributors accelerates market access. For Investors and Strategic Acquirers: Roll-up economics work for precision balancing technology specialists because metrology technician scarcity in Stuttgart and Nagoya clusters creates durable moats around acquired expertise. Long-term viability framing centers on five-to-ten year spindle architecture standardization windows. Acquisition target archetypes include DIN 69893 certification specialists with automotive contract consolidation relationships. The signal to watch is ISO 26623 polygonal taper adoption velocity in aerospace procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Grinding Capacity Expansion | Stuttgart manufacturing clusters anchor taper geometry expertise unavailable elsewhere. |
| Smart Holder Sensor Integration | Embedded RFID and vibration monitoring chips enable predictive tool life management for aerospace tier suppliers. |
| Multi-Standard Certification Investment | Simultaneous DIN 69893, ISO 12164, and JIS compliance opens cross-border equipment supply contracts. |
| Remanufacturing Service Channel Buildout | Industrial distributors capture aftermarket revenue from high-value hydraulic holder installed bases in Shanghai. |
| Backward Integration into Induction Heating | In-house production of shrink-fit systems secures thermal stability performance for 40,000 RPM titanium machining. |
Study Parameters
Direct dialogue with machine tool OEM procurement directors, aerospace tier supplier manufacturing engineers, precision grinding equipment specialists, and industrial distributor aftermarket service heads grounded this analysis. Secondary validation drew from DIN 69893 technical committee documentation, JIS B 6339 framework publications, METI-administered equipment certification records, and customs data for taper grinding machinery trade flows. Bottom-up and top-down triangulation cross-checked holder unit demand against machine tool spindle installation projections.
Bottom-up modeling segmented volume and value outputs across product type, material grade, application precision tier, and end-user industry concentration throughout the forecast period. Analytical frameworks incorporated shrink-fit technology adoption curves, collet chuck replacement cycles, and hydraulic holder installed base dynamics. CAGRs were derived from spindle speed escalation requirements in next-generation machining centers and aerospace titanium machining procurement acceleration.
The model holds under sustained five-axis machining center deployment and ISO 26623 standard migration; deviation in tungsten-cobalt alloy pricing volatility or REACH coating restriction enforcement would shift margin distribution across supplier tiers. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Height Gauge Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Global Tool Presetters Market
Industrial Tools
Machine Tool Touch Probe Market
Industrial Tools
Plasma Arc Cutting Market
Industrial Tools
Micro Welders Market
Industrial Tools
Jigs and Other Tools Market
Industrial Tools
Saudi Arabia Power Tools Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
Air Screwdrivers Market
Industrial Tools
Dies, Jigs and Other Tools Market
Industrial Tools
Precision Components and Tooling Systems Market
Industrial Tools
Coordinate Measuring Machine Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Die Grinders Market