
 Hybrid Microcircuits Market | 2026-2036
Hybrid Microcircuits Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Microcircuits Market Foresight
The hybrid microcircuits market is rebalancing as premium hermetic packages for defense and aerospace applications command widening margin premiums over commodity consumer-grade modules. Samsung Electronics Co Ltd leverages its semiconductor packaging scale to anchor high-volume production of multi-chip modules for telecommunications infrastructure. Panasonic Corporation specializes in thick-film hybrid circuits for industrial power electronics, sustaining a defensible position through proprietary ceramic substrate formulations. DuPont de Nemours dominates advanced metallization paste supply, controlling critical material inputs that differentiate performance in harsh-environment applications.
Hybrid microcircuits combine passive components, active semiconductor devices, and interconnect substrates into single functional assemblies, typically fabricated on ceramic or alumina bases using thick-film or thin-film deposition processes with firing temperatures between 850°C and 1600°C depending on conductor systems. These assemblies serve primarily where monolithic integration fails due to mixed-signal requirements, high-voltage isolation, or extreme thermal cycling. System in Package configurations lead value creation by integrating disparate die technologies while preserving signal integrity, whereas thick-film technology retains cost advantages in high-reliability industrial and defense programs where volume runs remain modest. Medical device applications represent the fastest-growing demand pool as wearable diagnostic equipment miniaturization drives chip-scale hybrid adoption.
FDA device regulations in the United States, ECHA REACH substance restrictions across Europe, and China's GB standards for electronic component reliability collectively shape material selection, qualification protocols, and market access requirements for hybrid microcircuit suppliers. The EU Green Deal's expanding scope on critical raw materials sourcing is forcing substrate manufacturers to document supply chain provenance for tantalum capacitors and noble metal conductors. Stakeholders must monitor how export control expansions on advanced packaging equipment affect manufacturing geography decisions and qualification timelines for defense-qualified suppliers.
Market Dynamics
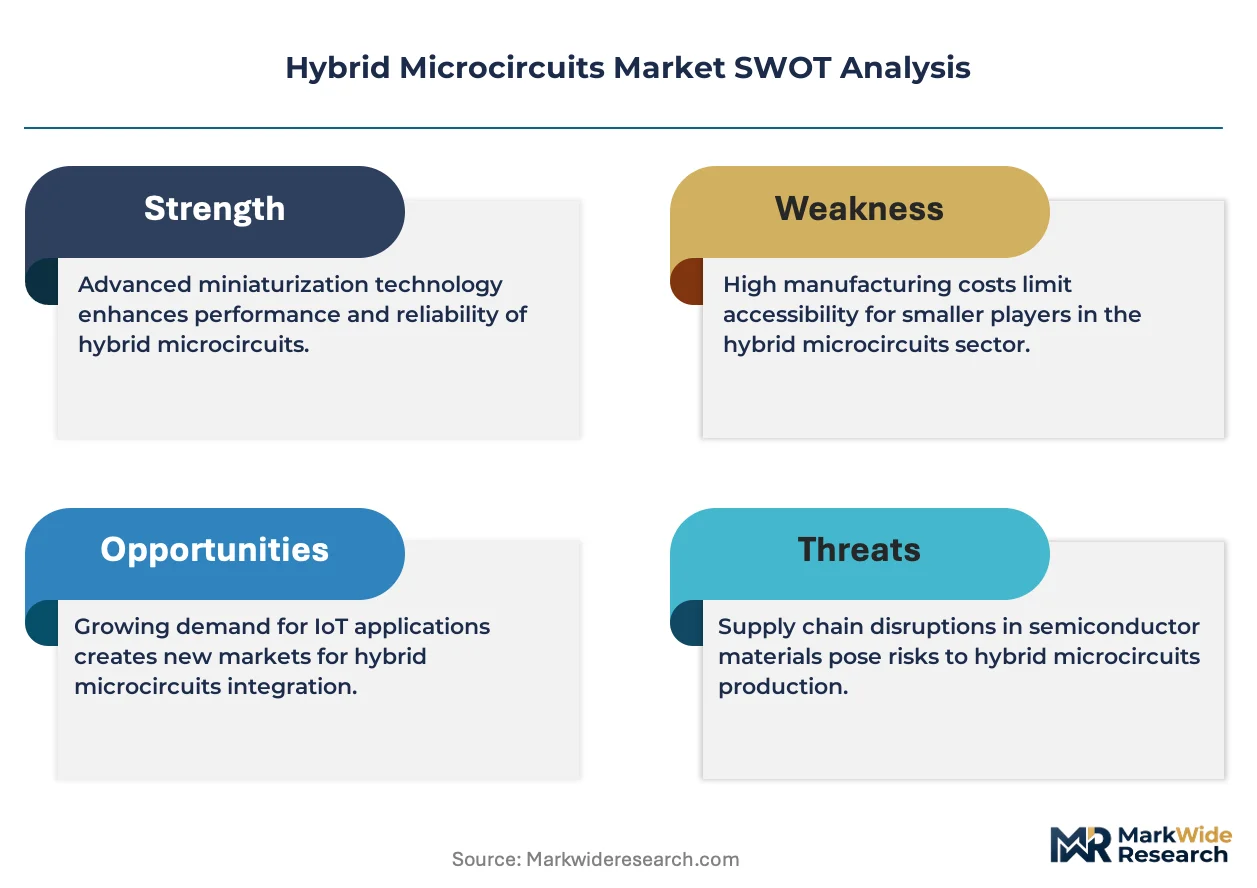
Defense procurement cycles and REACH substance restrictions are forcing substrate metallization suppliers to requalify entire product lines while aerospace contractors absorb extended lead times for hermetically sealed packages.
Growth Catalysts
- REACH substance restrictions:European ECHA mandates on lead-free metallization are accelerating process innovation in thick-film conductor systems, creating first-mover advantages for compliant suppliers.
- Medical device miniaturization:Wearable diagnostic equipment manufacturers are specifying chip-scale hybrid assemblies for mixed-signal isolation in implantable monitors.
- East Asian packaging clusters:Advanced foundry concentration in South Korea and Taiwan is compressing qualification timelines for multi-chip module production.
Market Restraints
- Noble metal cost volatility:Palladium and silver paste pricing swings directly compress margins for thick-film substrate manufacturers serving industrial power electronics.
- Hermetic package supply concentration:Qualified ceramic package suppliers for aerospace programs remain concentrated among three domestic vendors, creating single-source vulnerabilities.
- Monolithic integration substitution:Silicon carbide power modules are displacing discrete hybrid assemblies in traction inverter applications above 650V.
Strategic Opportunities
- EU Green Deal critical raw materials documentation:Substrate manufacturers who map tantalum capacitor provenance can access premium pricing from defense contractors facing supply chain audit mandates.
- System-in-Package convergence:Integration of photonic interconnect with traditional hybrid substrates opens medical imaging and quantum sensing applications.
- Telecommunications infrastructure buildouts:5G base station deployments in India are creating demand for high-isolation filter modules that monolithic processes cannot fabricate.
Industry Challenges
- Fireable thick-film engineering talent:Experienced ceramic substrate process engineers are retiring faster than vocational programs can replenish specialized metallization expertise.
- ITAR/EAR requalification timelines:Export control expansions on wire bonding equipment are forcing defense-qualified suppliers to restart facility certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Microcircuits Market |
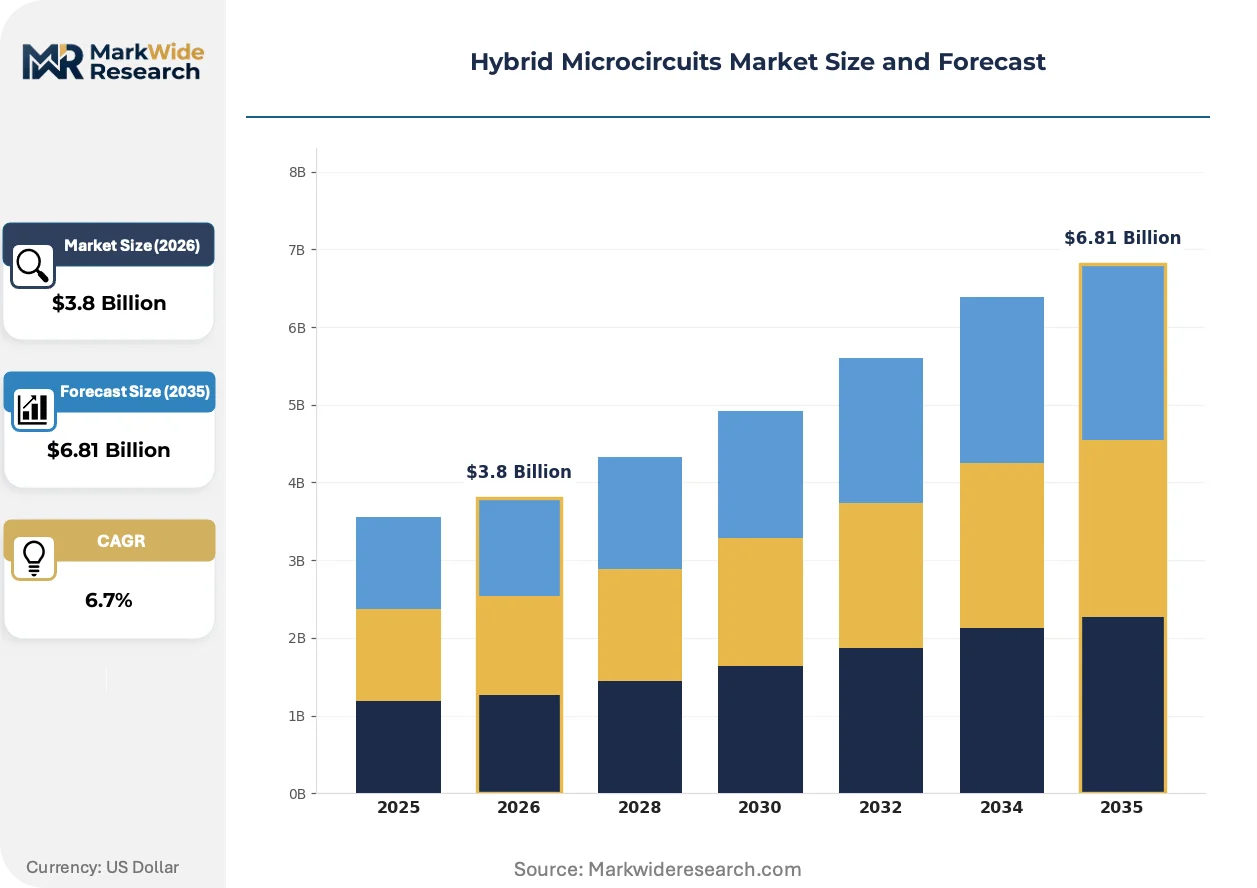
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Integrated Circuits, Multi-Chip Modules, System in Package, Chip-on-Board Technology: Thick Film, Thin Film, Monolithic, Chip Scale Application: Aerospace, Medical Devices, Telecommunications, Consumer Electronics End User: Defense, Automotive, Industrial, Healthcare |
| Companies Covered | American Semiconductor Inc., Samsung Electronics Co Ltd, Jabil Inc., AT&S, DuPont de Nemours, Flex Ltd., Panasonic Corporation, Zhen Ding Technology, TTM Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Microcircuits Market Shifts & Advancements
Advanced packaging architectures are fragmenting traditional hybrid categories as substrate suppliers integrate photonic and RF functions that previously required separate assemblies.
Photonic-electronic hybrid integration is modularizing signal routing in aerospace sensor arrays. Defense contractors are specifying co-packaged laser diodes with control electronics for LiDAR targeting systems. This convergence is compressing subsystem supplier counts while elevating substrate-level optical alignment requirements.
EU F-Gas Regulation phase-down schedules are accelerating hermetic sealing process changes. Manufacturers are transitioning from seam welding to laser sealing for aluminum oxide packages to eliminate perfluorinated compounds. Medical device suppliers serving European markets are absorbing requalification costs ahead of 2027 enforcement deadlines.
Defense procurement offices are consolidating vendor lists around qualified suppliers with captive ceramic substrate production. Prime contractors are awarding multi-year sole-source agreements to hybrid manufacturers with demonstrated ITAR compliance. This concentration is most visible in satellite payload programs where radiation-hardened packaging mandates eliminate commercial alternatives.
Hybrid Microcircuits Market Segmentation
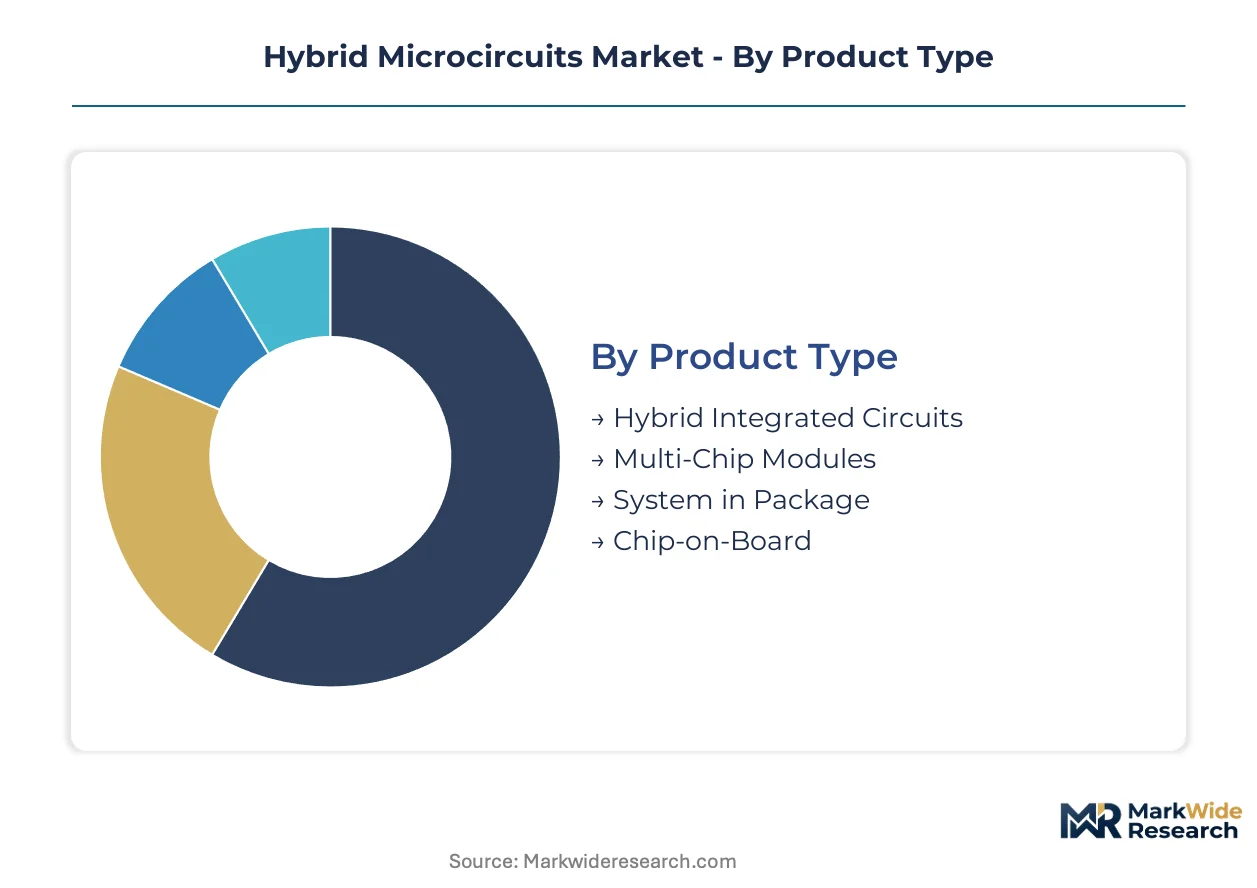
Hybrid microcircuits fragment across four distinct axes that determine procurement priorities. Product architecture dictates whether buyers prioritize hermetic sealing or cost-optimized surface-mount assembly. Technology selection separates defense contractors requiring 1600°C co-fired ceramics from medical device makers seeking chip-scale miniaturization.
Product Type:
Defense contractors and telecommunications infrastructure buyers diverge sharply on package architecture priorities. Hermetic sealing requirements versus volume cost targets create distinct sourcing channels.
- Hybrid Integrated Circuits:Discrete passive components and active devices mount on ceramic substrates with thick-film or thin-film interconnects. Aerospace programs in the United States specify these for satellite payload electronics where radiation tolerance exceeds monolithic capabilities. Procurement concentrates among ITAR-qualified suppliers with captive ceramic fabrication.
- Multi-Chip Modules:Multiple bare die attach to a common substrate with wire bond or flip-chip interconnect, enabling mixed-technology integration. South Korean telecommunications foundries drive demand for 5G base station filter modules requiring high-isolation performance that monolithic processes cannot achieve. REACH compliance on lead-free metallization is forcing substrate requalification across European supply chains.
- System in Package:Heterogeneous die integration with through-silicon vias or substrate-level routing preserves signal integrity across analog-digital boundaries. Medical device manufacturers specify these for implantable diagnostic monitors where miniaturization and biocompatibility converge.
- Chip-on-Board:Bare die attach directly to printed circuit boards with encapsulant protection rather than hermetic packages. Industrial power electronics in Japan favor these for motor drive applications where cost sensitivity outweighs environmental sealing requirements.
Volume sits with Hybrid Integrated Circuits; growth tilts toward System in Package.
Technology:
Process temperature and conductor metallurgy separate premium defense-grade supply from commercial medical and consumer channels.
- Thick Film:Screen-printed conductor and resistor pastes fire at 850°C on alumina substrates, enabling rapid prototyping and modest-volume production. Industrial power electronics in Germany specify these for traction inverter applications below 650V where silicon carbide modules have not yet displaced hybrid assemblies. Palladium and silver paste cost volatility compresses margins for substrate manufacturers.
- Thin Film:Sputtered or evaporated metals achieve finer line resolution and tighter tolerances through photolithographic patterning. Aerospace contractors in France demand these for precision resistor networks in satellite attitude control systems where temperature coefficient stability is critical. EU F-Gas Regulation phase-down is accelerating laser sealing adoption for aluminum oxide packages.
- Monolithic:Single-crystal silicon integration of all circuit functions eliminates interconnect parasitics. Consumer electronics in Taiwan leverage these for cost-sensitive portable devices where mixed-signal requirements do not justify hybrid complexity.
- Chip Scale:Wafer-level packaging approaches minimize footprint for wearable and implantable medical devices. FDA device regulations in the United States shape qualification protocols for diagnostic equipment miniaturization.
Thick Film dominates unit shipments; Chip Scale expands most quickly.
Application:
Environmental exposure severity and regulatory burden determine technology selection and supplier qualification depth.
- Aerospace:Hermetically sealed ceramic packages withstand thermal cycling, radiation, and vacuum exposure. United States defense procurement offices consolidate vendor lists around qualified suppliers with demonstrated ITAR compliance for satellite payload programs.
- Medical Devices:Biocompatible encapsulants and miniaturized form factors enable implantable and wearable diagnostics. Wearable diagnostic equipment manufacturers specify chip-scale hybrid assemblies for mixed-signal isolation in implantable monitors.
- Telecommunications:High-isolation filter modules and power amplifiers serve base station infrastructure. Indian 5G deployments create demand that monolithic processes cannot fabricate.
- Consumer Electronics:Cost-optimized surface-mount modules support portable devices and peripheral accessories. South Korean manufacturing clusters compress qualification timelines for high-volume production.
Aerospace commands premium pricing; Medical Devices gain share fastest.
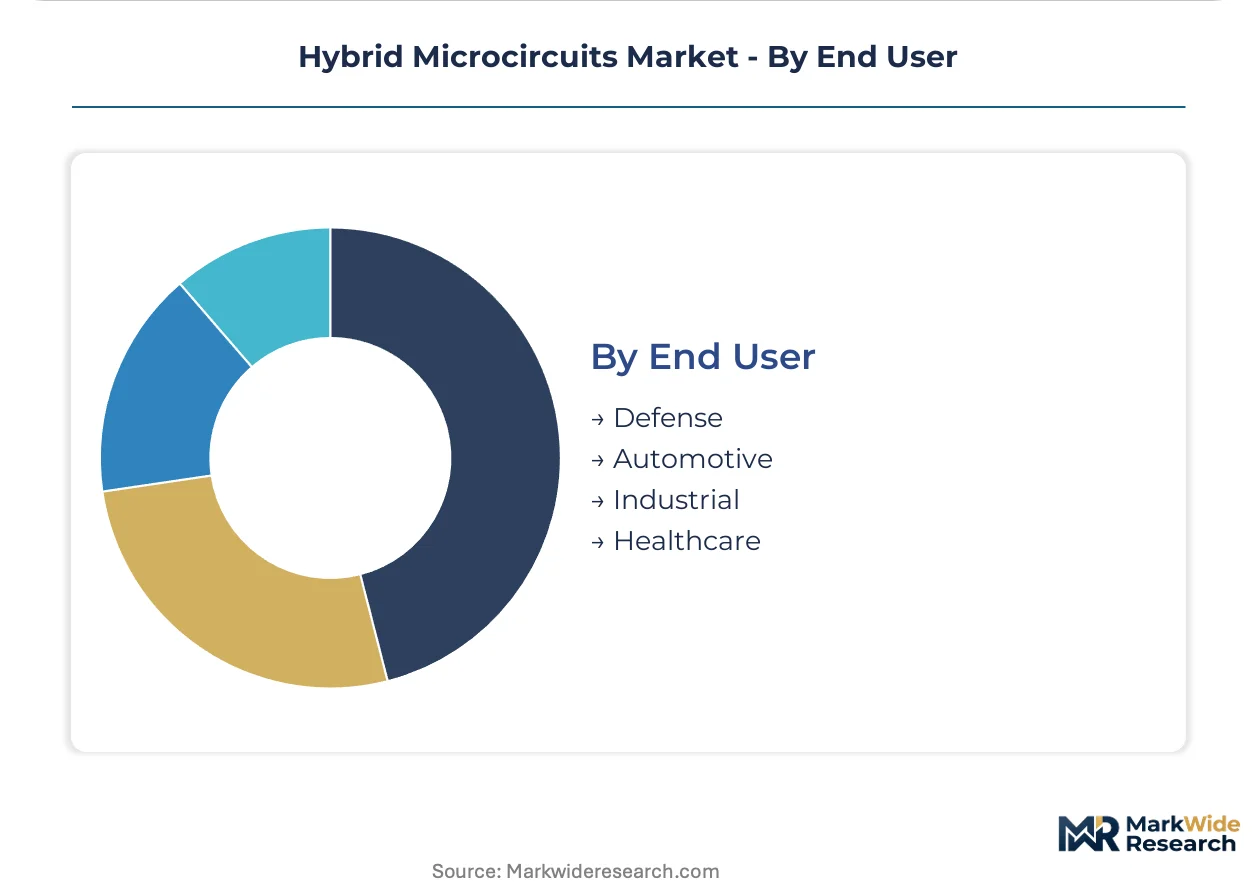
End User:
Procurement sophistication and compliance burden separate defense and healthcare buyers from industrial and automotive channels.
- Defense:ITAR and EAR export controls mandate domestic or allied-nation manufacturing with audited supply chains. Prime contractors award multi-year sole-source agreements to hybrid manufacturers with captive ceramic substrate production.
- Automotive:AEC-Q100 qualification and ISO 26262 functional safety shape supplier selection. Traction inverter applications above 650V see silicon carbide power modules displacing discrete hybrid assemblies.
- Industrial:Long product lifecycles and harsh operating environments favor thick-film reliability. Experienced ceramic substrate process engineers are retiring faster than vocational programs can replenish specialized metallization expertise.
- Healthcare:FDA and EMA device regulations enforce biocompatibility and traceability requirements. EU Green Deal critical raw materials documentation forces substrate manufacturers to map tantalum capacitor provenance.
Defense anchors revenue concentration; Healthcare shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors the most concentrated advanced packaging cluster for hybrid microcircuits, with Samsung Electronics Co Ltd operating foundries that compress qualification timelines for telecommunications infrastructure. South Korean manufacturing scale shapes regional supply patterns across East Asia.
United States
Defense procurement offices in the United States consolidate vendor lists around ITAR-qualified suppliers with captive ceramic substrate production for satellite payload programs. FAA and FDA regulations respectively govern aerospace component airworthiness and medical device biocompatibility requirements. California's aerospace corridor concentrates prime contractor activity around radiation-hardened packaging mandates.
Germany
Industrial power electronics manufacturers in Germany specify thick-film hybrid circuits for traction inverter applications below 650V where silicon carbide modules have not yet displaced assemblies. KBA automotive safety standards and ECHA REACH substance restrictions shape lead-free metallization process adoption. Bavaria's industrial belt hosts substrate manufacturers absorbing palladium paste cost volatility.
South Korea
Telecommunications foundries in South Korea drive demand for 5G base station filter modules requiring high-isolation performance that monolithic processes cannot achieve. MFDS medical device regulations and national semiconductor investment programs accelerate chip-scale packaging adoption. Seoul Capital Area manufacturing clusters anchor high-volume multi-chip module production.
Japan
Industrial motor drive applications in Japan favor chip-on-board configurations where cost sensitivity outweighs environmental sealing requirements. METI industrial standards and JIS reliability specifications govern supplier qualification protocols. Nagoya's automotive electronics corridor concentrates thick-film engineering expertise for power electronics.
Taiwan
Advanced packaging foundries in Taiwan operate at scale for consumer electronics and telecommunications infrastructure modules. National semiconductor development initiatives and GB standards alignment for cross-strait supply chains shape manufacturing geography decisions. Hsinchu Science Park concentrates substrate-level process engineering talent.
Hybrid Microcircuits Market Competitive Landscape
Premium-margin players sit above commodity-margin players across hermetic sealing certification and defense qualification depth. The vendor base stratifies into three tiers: ITAR-compliant defense specialists with captive ceramic production, East Asian scale operators serving telecommunications infrastructure, and regional substrate suppliers absorbing noble metal cost volatility. Two dominant competitive moves are reshaping positioning: defense contractors awarding multi-year sole-source agreements to qualified suppliers, and substrate manufacturers integrating backward into metallization paste formulation to control critical material inputs.
Among East Asian scale fabricators, Samsung Electronics Co Ltd and Zhen Ding Technology occupy positions within the telecommunications infrastructure supply tier, while DuPont de Nemours anchors the critical materials vector through metallization paste supply. Panasonic Corporation represents the industrial power electronics specialist archetype with proprietary ceramic substrate capabilities. American Semiconductor Inc. exemplifies the defense-qualified supplier model with ITAR-compliant manufacturing infrastructure.
| Leading Market Players |
|---|
| American Semiconductor Inc. |
| Samsung Electronics Co Ltd |
| Jabil Inc. |
| AT&S |
| DuPont de Nemours |
| Flex Ltd. |
| Panasonic Corporation |
| Zhen Ding Technology |
| TTM Technologies |
| Others |
Supply & Pricing Matrix
Palladium and silver paste pricing volatility cascades through thick-film substrate manufacturing tiers, compressing margins for industrial power electronics suppliers while hermetic package vendors in the United States command certification-linked premiums. REACH-mandated lead-free metallization requalification costs concentrate in European supply chains, forcing substrate manufacturers to absorb process conversion expenses or exit defense-qualified tiers entirely.
Pricing Analysis
Radiation tolerance certification anchors value-based pricing for satellite payload electronics, with ITAR-compliant suppliers capturing sustained premiums over commercial-grade alternatives. Three-tier pricing structure across defense-qualified, industrial-grade, and consumer-tier segments reflects hermetic sealing depth and qualification audit intensity. Cost compression in industrial thick-film modules is intensifying because silicon carbide power modules are displacing hybrid assemblies above 650V. Defense contractors show least price sensitivity due to sole-source dependency, while Japanese motor drive manufacturers prioritize unit economics over environmental sealing.
Supply Chain Analysis
Single-source vulnerability sits with qualified ceramic package suppliers for aerospace programs concentrated among three domestic United States vendors. Manufacturing gravity centers on South Korea, Taiwan, and Japan for advanced packaging foundries, while noble metal paste formulation rests on DuPont de Nemours and specialized European chemical suppliers. Tariff exposure runs through wire bonding equipment subject to expanded EAR export controls. Distribution runs through prime contractor vendor lists with multi-year sole-source agreements rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance restrictions and ITAR compliance requirements have erected a cost-of-compliance barrier that favors incumbents with captive qualification infrastructure and documented supply chain provenance systems.
For Market Incumbents: Acquire specialized metallization paste formulation capabilities to secure critical material inputs against noble metal cost volatility. Consolidate around multi-year sole-source agreements with defense prime contractors before requalification timelines compress vendor lists further. Silicon carbide power module substitution in traction inverters above 650V threatens industrial thick-film revenue pools. For New Entrants and Emerging Players: Enter via chip-scale hybrid assembly for wearable diagnostic equipment, where FDA device regulations and miniaturization requirements outpace established supplier adaptation. Indian 5G telecommunications infrastructure presents the most penetrable geography, with high-isolation filter module demand exceeding domestic packaging capacity. Partner with South Korean foundries for qualification timeline compression rather than building captive ceramic fabrication. For Investors and Strategic Acquirers: Defense procurement office vendor list consolidation announcements are the leading indicator that ITAR-compliant manufacturing assets are approaching scarcity premium pricing. Long-term viability favors vertically integrated substrate suppliers with captive ceramic production and demonstrated ECHA REACH compliance documentation. Monitor EU Green Deal critical raw materials audit mandate enforcement as the inflection signal for provenance-tracking technology valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallization Paste | DuPont de Nemours dominance in conductor formulations creates supply security for qualified substrate manufacturers. |
| Hermetic Package Laser Sealing Conversion | EU F-Gas Regulation phase-down forces process transition ahead of 2027 enforcement deadlines. |
| Multi-Chip Module Foundry Scale-Up | South Korean telecommunications infrastructure demand compresses qualification timelines for 5G filter production. |
| ITAR Compliance Infrastructure Investment | Defense procurement consolidation around audited supply chains elevates captive ceramic fabrication value. |
| Chip-Scale Packaging for Medical Devices | FDA biocompatibility requirements and wearable diagnostic miniaturization converge on hybrid assembly specifications. |
Research Methodology
Multi-period observation of defense procurement cycle timing, REACH requalification cost absorption patterns, and noble metal paste pricing volatility anchored the trend analysis, supplemented by interviews with ceramic substrate process engineers, aerospace component procurement managers, medical device regulatory affairs leads, and thick-film metallization specialists. Secondary validation drew from ECHA substance restriction filings, FDA device registration databases, SEC supplier disclosure filings, and customs trade data for hybrid microcircuit imports. Bottom-up build of application-specific demand segments triangulated against top-down semiconductor packaging market allocation models.
Segment-weighting across product architecture, technology type, application severity, and end-user compliance burden shaped the analytical framework. Product-level forecasts incorporated hermetic sealing certification depth, process temperature requirements, and radiation tolerance specifications throughout the projection horizon. CAGRs derived from historical procurement cycle analysis and substitution elasticity estimates for silicon carbide displacement in power electronics. Industry-specific inputs included defense budget authorization trajectories, medical device PMA submission rates, and telecommunications infrastructure deployment schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control expansion scenarios or accelerated silicon carbide cost reduction curves. Forecasts reflect assumptions about regulatory enforcement consistency, qualified engineering talent replenishment rates, and critical raw materials supply continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Ram BOP Market
Semiconductor Devices
Americas Semiconductor Device Market
Semiconductor Devices
Middle East and Africa Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Asia-Pacific Semiconductor Diode Market
Semiconductor Devices
5G Modems Market
Semiconductor Devices
APAC Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Programmable Logic Device (PLD) Market
Semiconductor Devices
Americas Microcontroller (MCU) Market
Semiconductor Devices
Laneth-16 Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
China Semiconductor Device Market
Semiconductor Devices
Global Gan Semiconductor Device Market
Semiconductor Devices
Global Diodes Market
Semiconductor Devices
N-Topcon Solar Cells Market